
 Europe Direct Methanol Fuel Cell Market | 2026-2036
Europe Direct Methanol Fuel Cell Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Direct Methanol Fuel Cell Market Insights
The capability gap between membrane-electrode assembly in-house producers and pure system integrators is reorganizing competitive tiers across the European DMFC landscape. SFC Energy AG leverages its German manufacturing base to dominate military and off-grid portable applications. Blue World Technologies ApS anchors its position through methanol reformer integration and maritime fuel-cell packaging. Johnson Matthey sustains catalyst supply relationships that extend its reach across multiple downstream OEM channels.
A direct methanol fuel cell electrochemically converts liquid methanol and oxygen into electricity through a proton exchange membrane, typically operating at 60–130°C with energy densities of 0.5 kWh/kg for the fuel itself, serving applications where hydrogen logistics prove impractical. Portable cells command the largest current shipment volumes due to soldier power and remote instrumentation demand, while hybrid systems integrating batteries with DMFC stacks represent the fastest-expanding configuration as runtime requirements lengthen. Stationary cells for telecommunications backup occupy a mature margin pool with predictable replacement cycles across European tower networks.
The EU Green Deal, F-Gas Regulation, and CE marking under the EU AI Act collectively restrict conventional generator deployments while certifying fuel-cell alternatives for critical infrastructure use. ECHA REACH compliance shapes membrane and catalyst material selections, particularly affecting fluorinated polymer content in proton exchange layers. Stakeholders must monitor national hydrogen and e-fuel strategies for methanol pathway eligibility, as this classification determines subsidy access and carbon accounting methodologies across member state procurement frameworks.
Market Dynamics
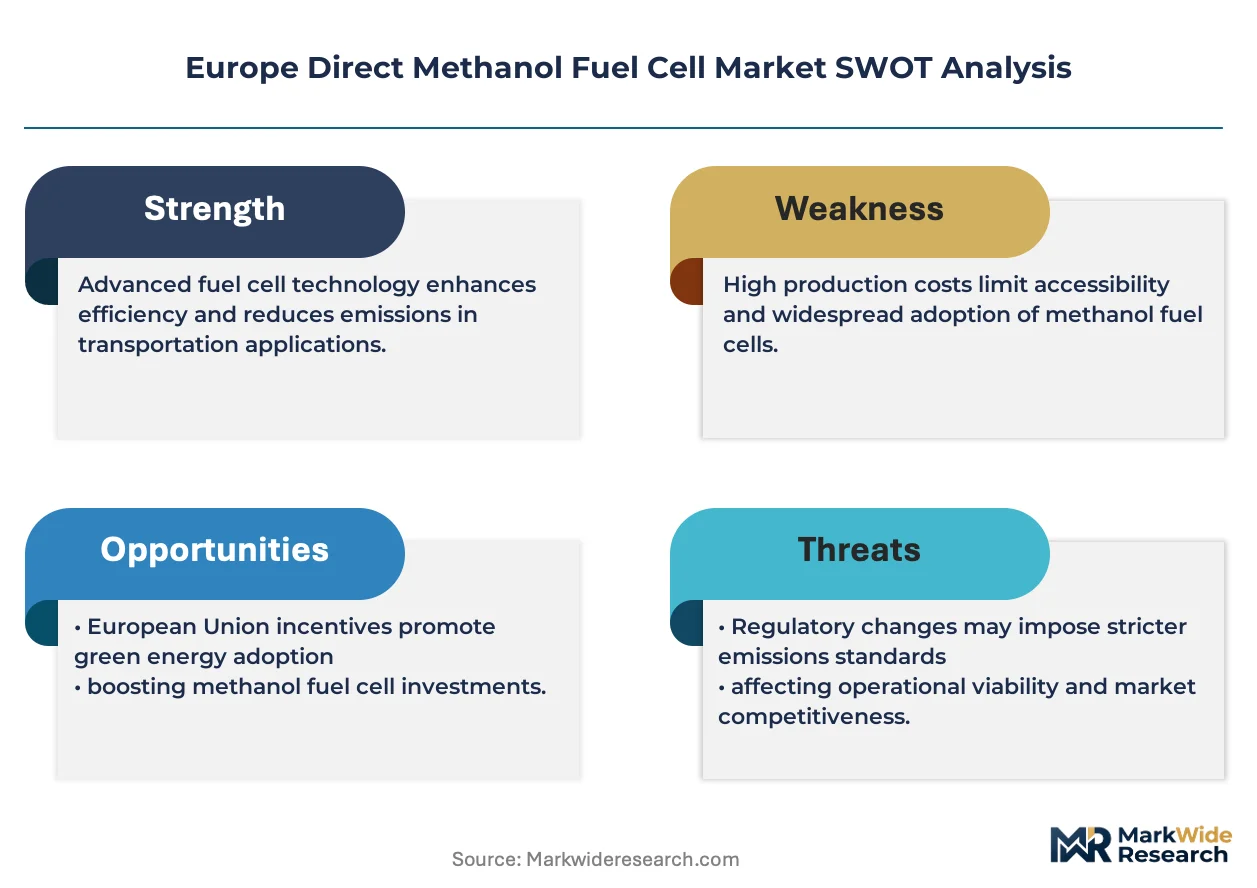
The EU F-Gas Regulation is systematically decommissioning diesel backup generators across European telecommunications and defense infrastructure, redirecting capital toward methanol-based electrochemical alternatives. This regulatory compression is restructuring procurement specifications from runtime hours to carbon intensity metrics.
Growth Catalysts
- EU Green Deal carbon accounting rules:Defense ministries in Germany and Denmark now mandate renewable fuel compatibility for forward-deployed power systems, eliminating conventional generator options from tender eligibility.
- Maritime electrification corridors:The Netherlands and Scandinavian port authorities are piloting methanol bunkering infrastructure that positions DMFC systems as auxiliary power alternatives for vessel cold-ironing.
- Remote instrumentation networks:Alpine and Nordic environmental monitoring stations are specifying liquid-fuel cells for year-round autonomous operation where battery swaps prove logistically prohibitive.
Market Restraints
- Platinum-group metal cost volatility:Catalyst layers remain exposed to ruthenium and platinum price swings that compress stack manufacturing margins during commodity spikes.
- Fluorinated polymer supply concentration:Proton exchange membrane production concentrates among a limited set of chemical suppliers, creating single-source vulnerability for European stack assemblers.
- Methanol purity standards:Fuel-grade methanol specifications under ECHA REACH compliance add handling complexity that diesel alternatives bypass entirely.
Strategic Opportunities
- Eastern European grid resilience programs:Polish and Romanian critical infrastructure operators are evaluating DMFC backup for substations and rail signaling vulnerable to weather-induced outages.
- Hybrid battery-fuel cell architectures:Integration with lithium-ion buffers allows smaller stack sizing for peak shaving, opening cost-competitive positioning against larger pure-fuel-cell configurations.
- EU Defense Fund procurement windows:Collaborative European defense equipment acquisition is creating pooled demand for standardized soldier power and field command modules.
Industry Challenges
- Electrochemist talent scarcity:Membrane-electrode assembly engineering expertise concentrates among a limited pool of specialists, constraining stack manufacturing scale-up timelines.
- CE marking pathway complexity:Novel fuel cell categories lack harmonized conformity assessment procedures under the EU AI Act and Machinery Directive, extending certification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Direct Methanol Fuel Cell Market |
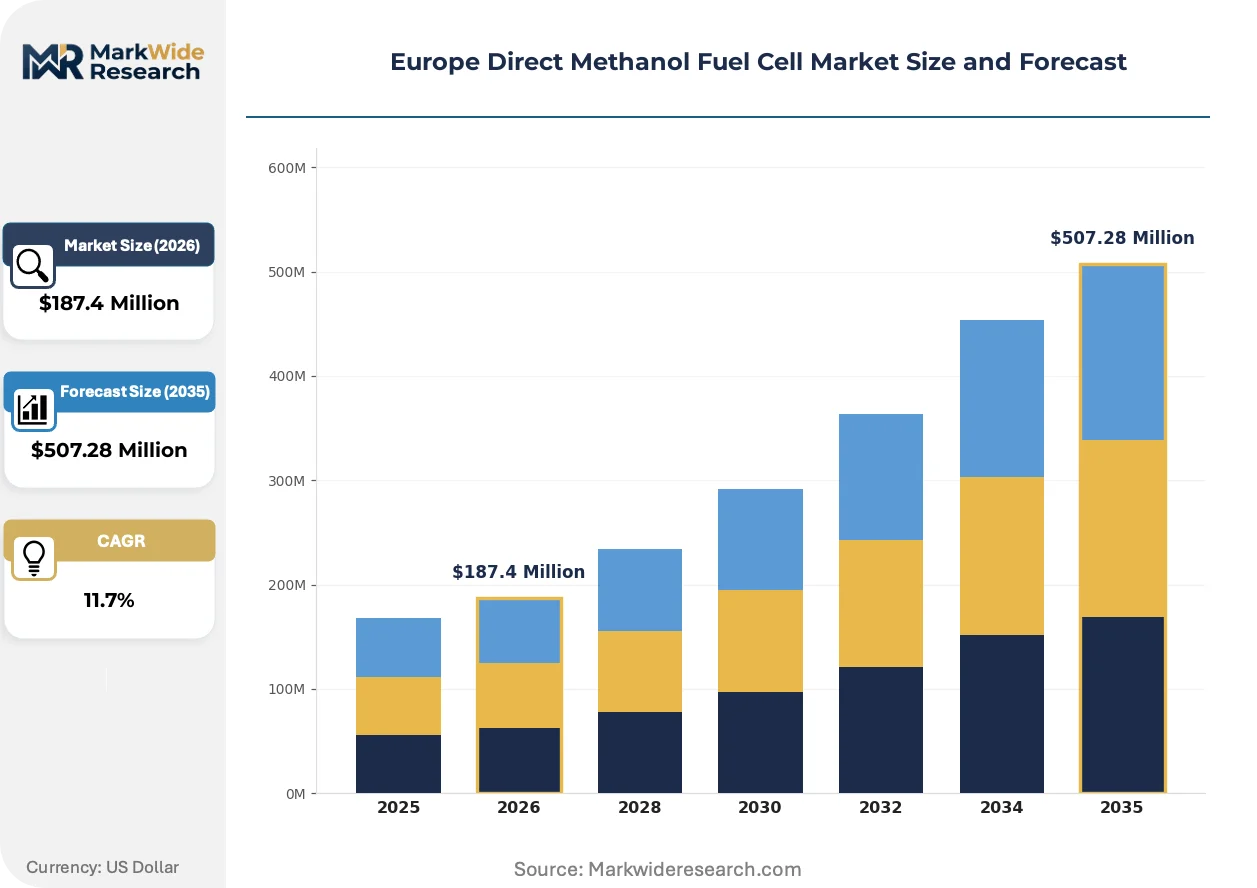
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Cells, Stationary Cells, Hybrid Systems, Backup Power Solutions Application: Automotive, Marine, Telecommunications, Emergency Services End User: Government, Commercial, Industrial, Residential Technology: Proton Exchange Membrane, Direct Methanol, Reforming, Fuel Processing |
| Companies Covered | Ballard Power Systems Inc., Roland Gumpert, SFC Energy AG, MeOH Power, Inc., Advent Technologies, Blue World Technologies ApS, Viaspace Inc., Oorja Protonics Inc., Johnson Matthey, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Direct Methanol Fuel Cell Market Trends and Innovations
Reformer-integrated system architectures are compressing the footprint and thermal management burden of methanol power units, enabling deployment scenarios previously reserved for battery-only solutions. These engineering advances are redrawing competitive boundaries between pure fuel cell and hybrid system suppliers.
Membrane-electrode assemblies utilizing hydrocarbon-based proton exchange layers are supplanting perfluorinated sulfonic acid alternatives in European stack designs. German and Danish system integrators are adopting these materials for defense and maritime contracts where fluorinated content faces regulatory scrutiny. The shift is enabling simplified ECHA REACH compliance documentation while maintaining comparable ionic conductivity performance.
The EU F-Gas Regulation's phase-down schedule for hydrofluorocarbons is eliminating refrigerant-based thermal management from auxiliary power units. Equipment manufacturers are responding with passive cooling architectures and liquid-loop heat rejection systems that comply with amended ecological design requirements. Telecommunications backup applications in Germany and the Netherlands are experiencing the most acute specification changes.
Defense procurement offices are consolidating soldier power and field infrastructure requirements into multi-year framework agreements. This concentration is displacing spot purchasing for individual battery and generator replacements, favoring suppliers capable of integrated logistics support and training provision. The trend is most pronounced in Nordic and German military modernization programs.
Europe Direct Methanol Fuel Cell Market Segmentation
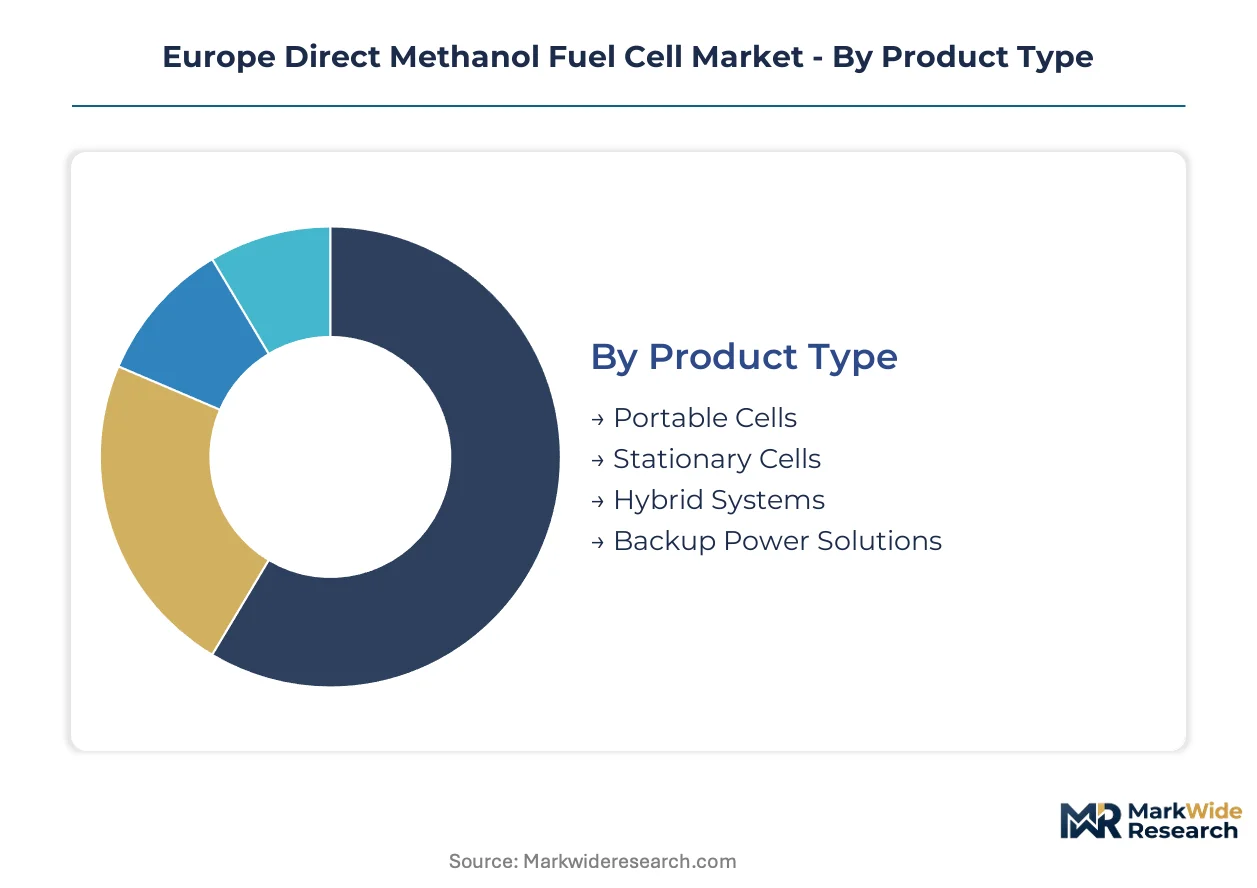
Segmentation reveals how DMFC demand fragments across incompatible performance requirements and procurement regimes. Each dimension exposes distinct margin structures and regulatory exposure profiles that reshape supplier positioning.
Product Type:
German and Danish demand concentrates in portable and hybrid configurations for defense export programs, while stationary installations serve domestic telecommunications resilience.
- Portable Cells:Compact stacks rated 25–100W power soldier-worn electronics and environmental monitoring equipment. German defense procurement channels absorb the majority of European volume through multi-year framework agreements for forward-deployed power.
- Hybrid Systems:DMFC-lithium-ion architectures optimize fuel consumption against peak load demands. Scandinavian alpine monitoring networks and Netherlands maritime auxiliary power pilots are expanding specifications fastest as runtime requirements lengthen beyond pure battery feasibility.
- Stationary Cells:Rack-mounted units provide backup for telecommunications infrastructure across German and Dutch tower networks. Replacement cycles align with F-Gas Regulation decommissioning schedules for diesel generators.
- Backup Power Solutions:Containerized systems serve grid-substitution roles in Polish and Romanian critical infrastructure vulnerability assessments.
Stationary cells hold the largest share; momentum sits with hybrid systems.
Application:
Cost tiers separate military-grade specifications from commercial telecommunication deployments, with marine applications commanding premium thermal management requirements.
- Telecommunications:Base station backup and remote tower power dominate current installed base across German, Dutch, and Nordic networks. EU F-Gas Regulation compliance deadlines are compressing procurement timelines for diesel replacement.
- Marine:Auxiliary power for vessel cold-ironing and harbor maneuvering attracts Netherlands and Scandinavian port authority pilot programs. Methanol bunkering infrastructure investments position DMFC against shore-power alternatives.
- Automotive:Range-extender applications for light commercial vehicles remain experimental, constrained by platinum-group metal cost structures and ECHA REACH catalyst documentation requirements.
- Emergency Services:Mobile command centers and field hospitals specify liquid-fuel independence for disaster response scenarios, with German and Danish civil defense agencies leading tender activity.
Telecommunications commands current revenue concentration; marine applications are climbing the fastest.
End User:
Government procurement frameworks concentrate volume through defense and critical infrastructure mandates, while commercial adoption follows total-cost-of-ownership thresholds.
- Government:Defense ministries and civil defense agencies in Germany, Denmark, and the Netherlands specify standardized soldier power and field infrastructure modules through EU Defense Fund collaborative acquisition windows.
- Commercial:Telecommunications operators and environmental monitoring consortia evaluate DMFC against battery-swap logistics across Alpine and Nordic remote installations.
- Industrial:Manufacturing facilities with process-critical power requirements pilot methanol backup for production continuity, particularly in chemical processing clusters with existing fuel handling infrastructure.
- Residential:Off-grid cabins and remote dwellings represent minimal current penetration, constrained by fuel distribution economics and CE marking complexity for consumer equipment categories.
Government segments anchor procurement volume; commercial installations are gaining share fastest.
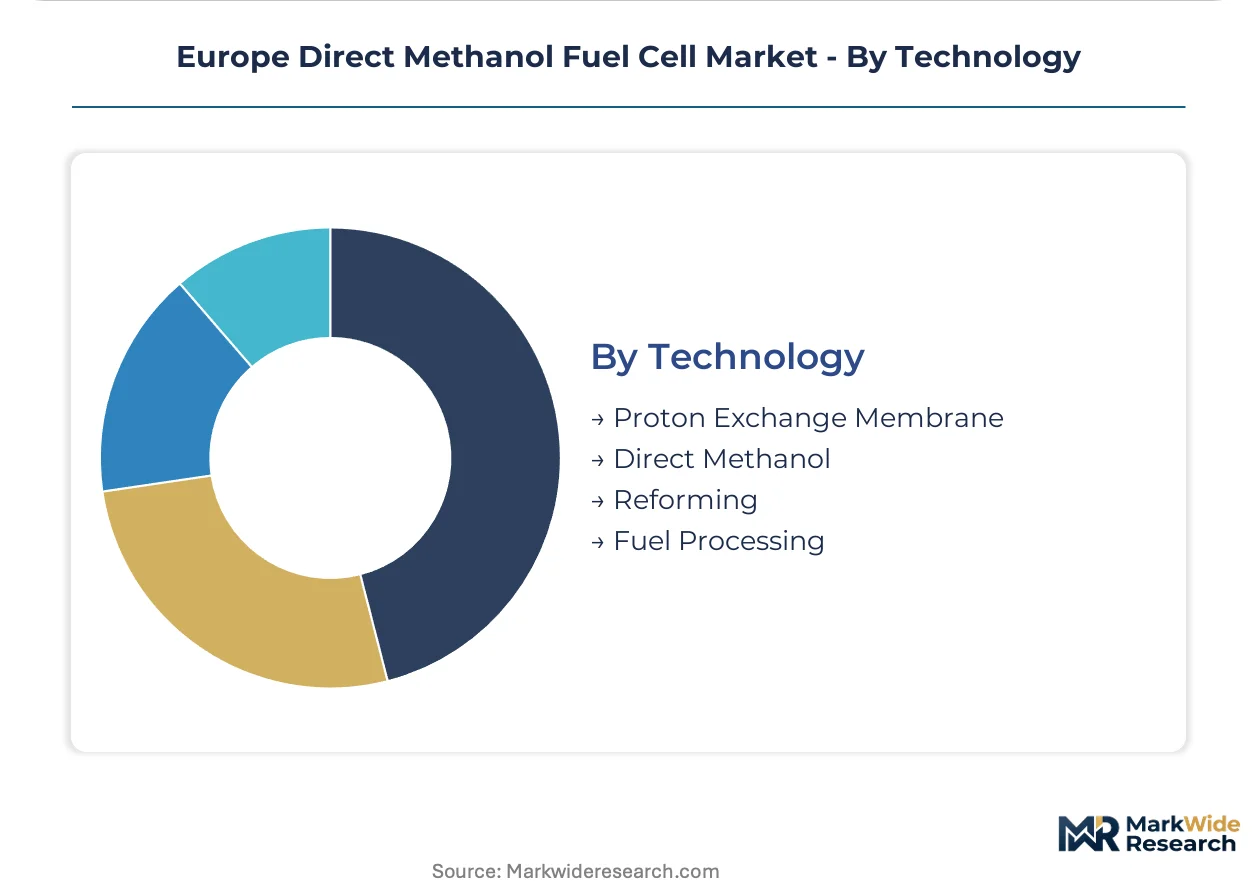
Technology:
Membrane chemistry choices determine regulatory compliance pathways and supply concentration exposure for European stack assemblers.
- Proton Exchange Membrane:Fluorinated and hydrocarbon-based polymer electrolytes dominate stack designs. German and Danish integrators are shifting toward hydrocarbon alternatives to simplify ECHA REACH documentation and reduce fluorinated content regulatory scrutiny.
- Direct Methanol:Passive and active fuel feed architectures differentiate system complexity and cold-start performance. Military specifications favor active systems with broader temperature tolerance.
- Reforming:Onboard methanol-to-hydrogen conversion enables higher-temperature operation and reduced platinum loading. Blue World Technologies anchors European capability in maritime-integrated reformer packaging.
- Fuel Processing:Impurity tolerance and water management subsystems determine field reliability. Telecommunications backup applications prioritize maintenance intervals exceeding five years.
Proton exchange membrane stacks hold the largest share; reforming-integrated systems show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German defense procurement commands premium pricing for field-deployable power systems, while Polish grid operators negotiate cost-sensitive backup configurations for substation resilience programs.
Germany
Bundeswehr modernization and alpine environmental monitoring drive portable DMFC absorption. The EU F-Gas Regulation decommissions diesel backup generators across telecommunications infrastructure. Munich and Stuttgart host defense contractor clusters where soldier power specifications concentrate manufacturing capability.
Denmark
Maritime auxiliary power pilots and civil defense field hospital requirements expand hybrid system specifications. National hydrogen strategy frameworks classify methanol pathways for carbon accounting eligibility. Copenhagen and Aalborg anchor Blue World Technologies' reformer-integrated packaging operations for Scandinavian port authorities.
Netherlands
Rotterdam methanol bunkering infrastructure positions DMFC systems against shore-power alternatives for vessel cold-ironing. Port authority procurement mandates renewable fuel compatibility for harbor maneuvering applications. Eindhoven's high-tech manufacturing corridor supplies membrane-electrode assembly components to maritime system integrators.
Poland
Grid resilience programs evaluate containerized backup for rail signaling and electrical substations vulnerable to weather-induced outages. EU Green Deal carbon accounting rules determine subsidy access for critical infrastructure operators. Warsaw and Krakow industrial zones pilot methanol fuel handling for process-critical manufacturing continuity.
Sweden
Nordic environmental monitoring networks specify liquid-fuel cells for year-round autonomous operation in subarctic conditions. ECHA REACH compliance shapes fluorinated polymer selections for proton exchange layers. Stockholm and Gothenburg research consortia develop hydrocarbon-based membrane alternatives for defense export programs.
Europe Direct Methanol Fuel Cell Market Competitive Landscape
Concentration sits with German and Danish system integrators who control military and maritime procurement channels. The vendor base stratifies across membrane-electrode assembly producers, pure stack assemblers, and full-system packagers. Three archetypes dominate: defense-focused portable power specialists, maritime-integrated reformer packagers, and catalyst suppliers extending across multiple OEM relationships. Competitive moves center on backward integration into membrane production and multi-year framework agreements with defense procurement offices.
Among German-based fabricators, SFC Energy AG and Johnson Matthey occupy positions at opposite ends of the value chain. SFC Energy exemplifies the defense-anchored system integrator archetype through its Bavarian manufacturing concentration. Johnson Matthey represents the catalyst-supplier tier that reaches across downstream stack assembly relationships. Blue World Technologies ApS anchors the Danish maritime-specialist segment with reformer-integrated packaging capability.
| Leading Market Players |
|---|
| Ballard Power Systems Inc. |
| Roland Gumpert |
| SFC Energy AG |
| MeOH Power, Inc. |
| Advent Technologies |
| Blue World Technologies ApS |
| Viaspace Inc. |
| Oorja Protonics Inc. |
| Johnson Matthey |
| Others |
Pricing and Supply Chain Analysis
CE marking under the EU AI Act gates both supplier qualification and price differentiation, forcing membrane-electrode assembly producers to absorb certification costs that standard system integrators bypass entirely. This regulatory overlay stratifies pricing power between in-house stack manufacturers and pure packagers.
Pricing Analysis
Configured-to-order pricing for defense-grade portable units commands spreads of 40-60 percent above standard telecommunications backup configurations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and runtime specification differentiation. Cost compression in the standard tier intensifies as Polish and Romanian grid operators prioritize substation resilience budgets over performance margins. Government defense procurement shows least price sensitivity due to multi-year framework agreements, while commercial telecommunications operators negotiate aggressively against battery-swap alternatives.
Supply Chain Analysis
Rotterdam port congestion and container availability constraints on Asia-Europe trade lanes inflate inbound logistics costs for platinum-group metal catalyst precursors. German and Danish stack assemblers draw from Japanese and South Korean membrane polymer suppliers, with fluorinated ionomer production concentrating among three chemical conglomerates. Single-source vulnerability in proton exchange membrane feedstock creates procurement risk exposure that stack manufacturers hedge through dual-qualification programs. Distribution runs through defense contractor primes for military applications and direct OEM relationships for telecommunications infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane-electrode assembly engineering expertise concentrates among fewer than two hundred specialists across Europe, constraining manufacturing scale-up regardless of capital availability. This capability bottleneck rewards early movers who lock talent pools through university partnership pipelines.
For Market Incumbents: Compound defensive positioning through backward integration into hydrocarbon-based membrane production and captive catalyst recycling facilities. Lock in multi-year framework agreements with Bundeswehr and Danish Defense procurement offices before EU Defense Fund standardization windows close. Prioritize certification investment for CE marking under amended Machinery Directive procedures to extend compliance moats against emerging Asian competitors. For New Entrants and Emerging Players: CE marking fast-track through notified body pre-submission for hybrid battery-fuel cell architectures opens white-space penetration in Scandinavian alpine monitoring networks. Target Polish and Romanian grid resilience pilots where incumbent presence remains thin and procurement specifications emphasize cost over brand heritage. Lead with liquid-loop thermal management as a differentiated reliability feature against passive-cooled incumbent offerings. For Investors and Strategic Acquirers: EU F-Gas Regulation phase-down completion reshapes the acquisition landscape toward reformer-integrated system packagers with maritime certification. Long-term viability hinges on methanol pathway eligibility under national hydrogen strategies determining subsidy access. Monitor German and Danish defense export program award announcements as inflection signals for volume concentration shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Production | German system integrators reduce ECHA REACH compliance exposure through captive hydrocarbon polymer supply. |
| Reformer-Integrated System Packaging | Danish maritime specialists capture Netherlands port authority cold-ironing procurement specifications. |
| Multi-Year Defense Framework Agreements | Bavarian manufacturers secure volume visibility through Bundeswehr soldier power modernization programs. |
| Hybrid Architecture Development | Scandinavian environmental monitoring networks specify lithium-ion buffer integration for extended runtime. |
| Catalyst Recycling Infrastructure | Platinum-group metal recovery programs insulate margins against ruthenium price volatility spikes. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with electrochemistry R&D directors, defense procurement officers, telecommunications infrastructure planners, and membrane production engineers; and secondary validation against ECHA REACH substance registrations, EU Defense Fund tender databases, F-Gas Regulation implementation reports, and customs trade data for platinum-group metal imports. Bottom-up stack shipment estimates triangulated against top-down procurement budget allocations across member state defense ministries.
Across the analysis window, the forecasting framework modeled demand trajectories by product configuration, application sector, end-user procurement regime, and membrane chemistry technology pathway. CAGRs derived from segment-level volume build-ups incorporating replacement cycle timing for diesel generator decommissioning. Industry-specific inputs included methanol bunkering infrastructure deployment schedules and national hydrogen strategy methanol pathway classifications.
Underlying assumptions cover EU Green Deal carbon accounting rule stability and ECHA REACH fluorinated polymer restriction timelines, with deviation risk concentrated in platinum-group metal price volatility and CE marking harmonization delays. Forecasts reflect these documented conditions; outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuel Cell Technology
Hydrogen Fuel Cell Stack and Membrane Recycling for EU Mobility Market
Fuel Cell Technology
Fuel Cells for CHP Application Market
Fuel Cell Technology
Hydrogen Fueling Nozzle Market
Fuel Cell Technology
North America Microbial Fuel Cell Market
Fuel Cell Technology
Asia-Pacific Direct Methanol Fuel Cell Market
Fuel Cell Technology
Fuel Cells for Marine Vessels Market
Fuel Cell Technology
Hydrogen Fuel Cell Vehicle Market
Fuel Cell Technology
China Fuel Cell Market
Fuel Cell Technology
Hydrogen Fuel Cells Market
Fuel Cell Technology
Europe Fuel Cell Market
Fuel Cell Technology
Hydrogen Fuel Cell Drone Market
Fuel Cell Technology
Fuel Vending Machines Market
Fuel Cell Technology
France Fuel Cell Market
Fuel Cell Technology
Hydrogen Recirculation Blower for Fuel Cell Market
Fuel Cell Technology
Global Planar Solid Oxide Fuel Cell Market
Fuel Cell Technology
Helium Recovery Systems Market