
 PEM Electrolyzer Market | 2026-2036
PEM Electrolyzer Market Size, Share, and Industry Trends Forecast 2026-2036
PEM Electrolyzer Market Insights
Long-term service contracts for membrane replacement and stack refurbishment are realigning how PEM electrolyzer vendors capture lifetime value. Nel ASA leverages its Nordic manufacturing base to sustain cost discipline across high-volume orders. Siemens Energy anchors its position through captive proton exchange membrane R&D and utility-scale project execution. Plug Power competes by dominating North American hydrogen logistics infrastructure and forklift-to-stationary power adjacencies.
A proton exchange membrane electrolyzer deploys a solid polymer electrolyte, typically perfluorosulfonic acid, to conduct protons between anode and cathode while separating hydrogen and oxygen gases at operating pressures up to 30 bar and temperatures near 80°C. Its primary commercial purpose is producing high-purity hydrogen for industrial feedstock, energy storage, and mobility applications where rapid response to renewable power variability matters. The Proton Exchange Membrane product category leads installed capacity because stack power density and dynamic load tolerance suit variable renewable integration. Within end user segmentation, Transportation and Chemical applications attract the fastest capacity additions as fleet operators and ammonia producers seek dedicated green hydrogen supply.
The EU Green Deal and delegated acts on renewable hydrogen define the regulatory perimeter for European deployment, while the US IRA production tax credits shape North American project economics through direct cost offsets. Japan's METI hydrogen roadmap and subsidy windows for import infrastructure create a third demand jurisdiction with distinct certification requirements. Stakeholders must monitor how diverging national hydrogen standards affect stack interoperability and offtake contract structuring across jurisdictions.
Market Dynamics
The PEM electrolyzer market is being restructured by the EU Green Deal's tightening certification thresholds, which force stack manufacturers to prove renewable hydrogen provenance through hourly matching requirements and additionality criteria.
Growth Catalysts
- Industrial ammonia decarbonization:Fertilizer producers in the Rhine-Ruhr region are signing long-term offtake agreements for green hydrogen feedstock, creating anchor demand for megawatt-scale installations.
- US IRA production tax credits:Direct cost offsets through the Inflation Reduction Act are compressing project payback periods for utility-scale deployments.
- Perfluorosulfonic acid membrane advancement:Improved proton conductivity and durability are extending stack operational lifespans while reducing maintenance intervals.
Market Restraints
- Iridium supply concentration:Over 80% of iridium mining occurs in South Africa and Russia, creating geopolitical exposure for catalyst-dependent anode production.
- Platinum group metal cost volatility:Price swings in platinum and iridium directly inflate stack manufacturing costs, squeezing margin structures for system integrators.
- Alkaline electrolyzer substitution:Lower capital cost per kilowatt in alkaline systems threatens PEM adoption in baseload industrial applications where dynamic response is less critical.
Strategic Opportunities
- Japan METI hydrogen import infrastructure:Subsidy windows for ammonia carrier terminals and power-to-gas facilities are opening dedicated procurement channels for European and North American stack suppliers.
- Transportation fueling networks:Heavy-duty fleet operators are contracting dedicated hydrogen supply for depot-based refueling, bypassing merchant gas markets.
- Membrane electrode assembly convergence:Integration of catalyst-coated membranes with bipolar plate manufacturing is enabling modular, containerized system architectures.
Industry Challenges
- Electrolyzer stack engineering talent scarcity:Shortages in electrochemistry and high-pressure sealing expertise are delaying commissioning timelines for first-of-a-kind installations.
- Renewable hydrogen certification complexity:Divergent national standards between EU delegated acts, US Treasury guidance, and Japan's METI requirements are forcing redundant testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PEM Electrolyzer Market |
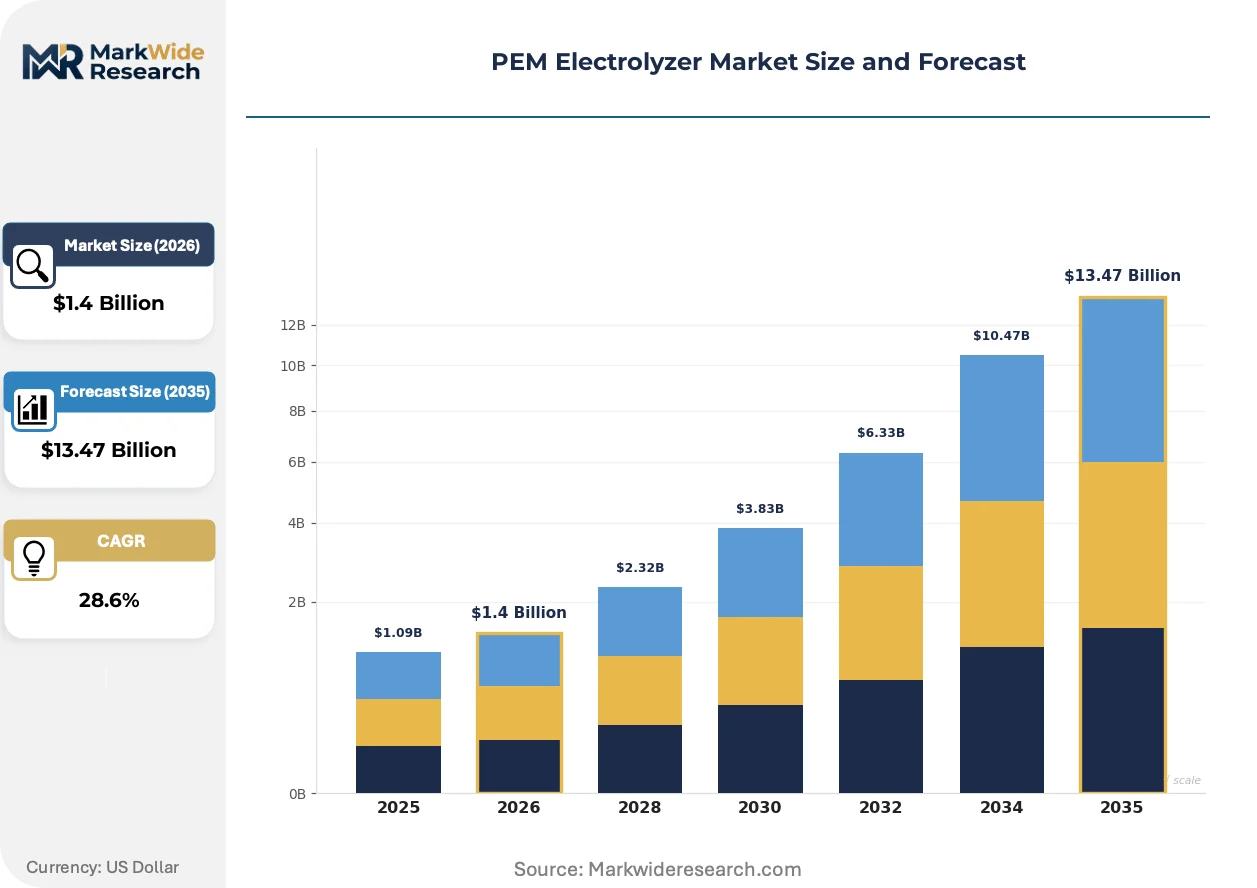
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $13.47 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alkaline, Proton Exchange Membrane, Solid Oxide, Polymer Electrolyte End User: Power Generation, Industrial, Transportation, Chemical Technology: Electrolytic Water Splitting, High-Temperature Operation, Low-Temperature Operation, Renewable Integration Installation: On-site, Off-site, Mobile, Stationary |
| Companies Covered | Linde plc, Air Products and Chemicals, Inc., Nel ASA, Cummins Inc., Plug Power Inc., ITM Power, Air Liquide S.A., Photofabrication Engineering, Inc., Siemens Energy AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PEM Electrolyzer Market Trends and Innovations
Stack architecture is converging with power electronics and thermal management systems, compressing the traditional boundaries between hydrogen production and renewable asset control. This integration is forcing vendors to develop software competencies alongside electrochemical expertise.
Anion exchange membrane technology is electrifying the competitive landscape by promising platinum-group-metal-free catalyst configurations. Ammonia producers in Germany are piloting these stacks for continuous operation scenarios. The technology is electrifying cost structures by eliminating iridium dependency while maintaining comparable current densities to conventional proton exchange systems.
The EU Green Deal's delegated acts on renewable hydrogen are mandating hourly temporal correlation between renewable generation and electrolyzer operation. Industrial offtakers in the Netherlands and Denmark are restructuring power purchase agreements to comply. Chemical clusters are responding by co-locating electrolyzers directly behind offshore wind substations.
Fleet operators are consolidating hydrogen procurement through long-term take-or-pay contracts rather than spot market purchases. Heavy-duty logistics companies in California and Germany are bypassing merchant hydrogen distributors entirely. This concentration is visible most acutely in port-based drayage operations where fuel cost predictability outweighs capital commitment flexibility.
PEM Electrolyzer Market Segmentation
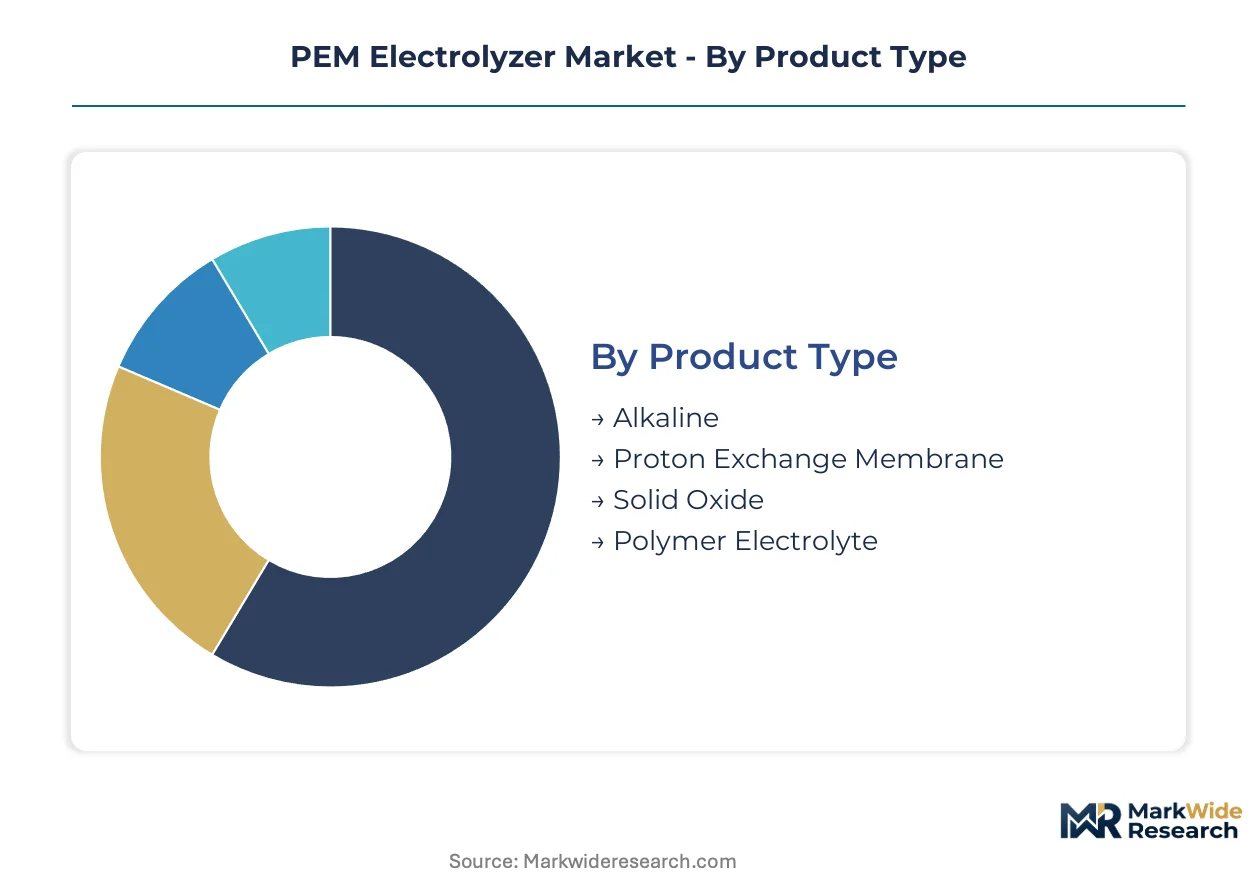
PEM electrolyzer procurement decisions pivot on operational pressure requirements, renewable power integration needs, and hydrogen purity specifications. Understanding how demand fragments across product architectures and deployment contexts reveals where margin concentrates and which technology trajectories warrant capacity investment.
Product Type:
Buyers select stack chemistry based on dynamic load tolerance, capital cost sensitivity, and target hydrogen purity thresholds.
- Proton Exchange Membrane:Solid polymer electrolyte architecture conducts protons between electrodes at pressures up to 30 bar and temperatures near 80°C. Rhine-Ruhr chemical clusters in Germany anchor offtake agreements for megawatt-scale installations where rapid response to wind variability matters.
- Alkaline:Liquid potassium hydroxide electrolyte operates without platinum-group-metal catalysts, achieving lower capital cost per kilowatt at the expense of dynamic response speed. Baseload industrial applications in China and India favor this chemistry where renewable power fluctuation is minimal.
- Solid Oxide:Ceramic electrolyte conducts oxygen ions at 700-800°C, enabling high electrical efficiency and co-production of heat for industrial processes. Pilot deployments in Japan's METI-subsidized demonstration projects test integration with ammonia synthesis loops.
- Polymer Electrolyte:Variant proton-conducting membranes optimized for specific catalyst loadings and durability profiles. Niche applications in laboratory and small-scale industrial settings where membrane replacement intervals drive total cost of ownership calculations.
Volume sits with Alkaline systems in cost-sensitive markets; growth tilts toward Proton Exchange Membrane where renewable integration mandates dominate procurement criteria.
End User:
Application-specific hydrogen purity, pressure, and volume requirements dictate system sizing and stack configuration choices.
- Chemical:Ammonia producers and methanol synthesis operations require continuous high-purity hydrogen feedstock at elevated pressures. Fertilizer manufacturers in Germany's industrial corridors are signing long-term offtake agreements that specify hourly renewable power matching under EU Green Deal delegated acts.
- Transportation:Heavy-duty fleet operators and depot-based refueling networks demand rapid-fill hydrogen at 350-700 bar. California port drayage operations and German logistics hubs are contracting dedicated supply bypassing merchant gas markets entirely.
- Industrial:Steel decarbonization and semiconductor manufacturing use hydrogen as reduction agent and process gas. Steelmakers in Sweden and the Netherlands pilot electrolyzer integration with direct reduction iron facilities.
- Power Generation:Grid-scale energy storage and power-to-gas applications buffer renewable intermittency through hydrogen intermediate storage. Danish and Dutch offshore wind developers co-locate electrolyzers behind substations to comply with temporal correlation requirements.
Contract value concentrates in Chemical offtake; capacity expansion accelerates fastest in Transportation as fleet electrification timelines compress.
Technology:
Operational temperature regime and power source coupling determine stack materials, system balance-of-plant, and maintenance protocols.
- Renewable Integration:Direct coupling with variable wind and solar output demands rapid ramp rates and partial load efficiency maintenance. German and Danish project developers optimize stack sizing against hourly production profiles from specific offshore wind arrays.
- Electrolytic Water Splitting:Fundamental electrochemical process dissociates water molecules using electrical current. All commercial PEM systems deploy this mechanism with efficiency improvements tracked through cell voltage and current density metrics.
- Low-Temperature Operation:Maintains stack temperature below 100°C through active thermal management, preserving membrane integrity and catalyst stability. Standard configuration for commercial PEM deployments where membrane longevity drives economics.
- High-Temperature Operation:Elevated thermal regimes reduce electrical energy requirements per kilogram of hydrogen produced. Research-stage hybrid systems explore membrane materials tolerant to intermittent thermal cycling.
Deployment scale favors Low-Temperature Operation for proven reliability; technology investment flows toward Renewable Integration as grid compliance rules tighten.
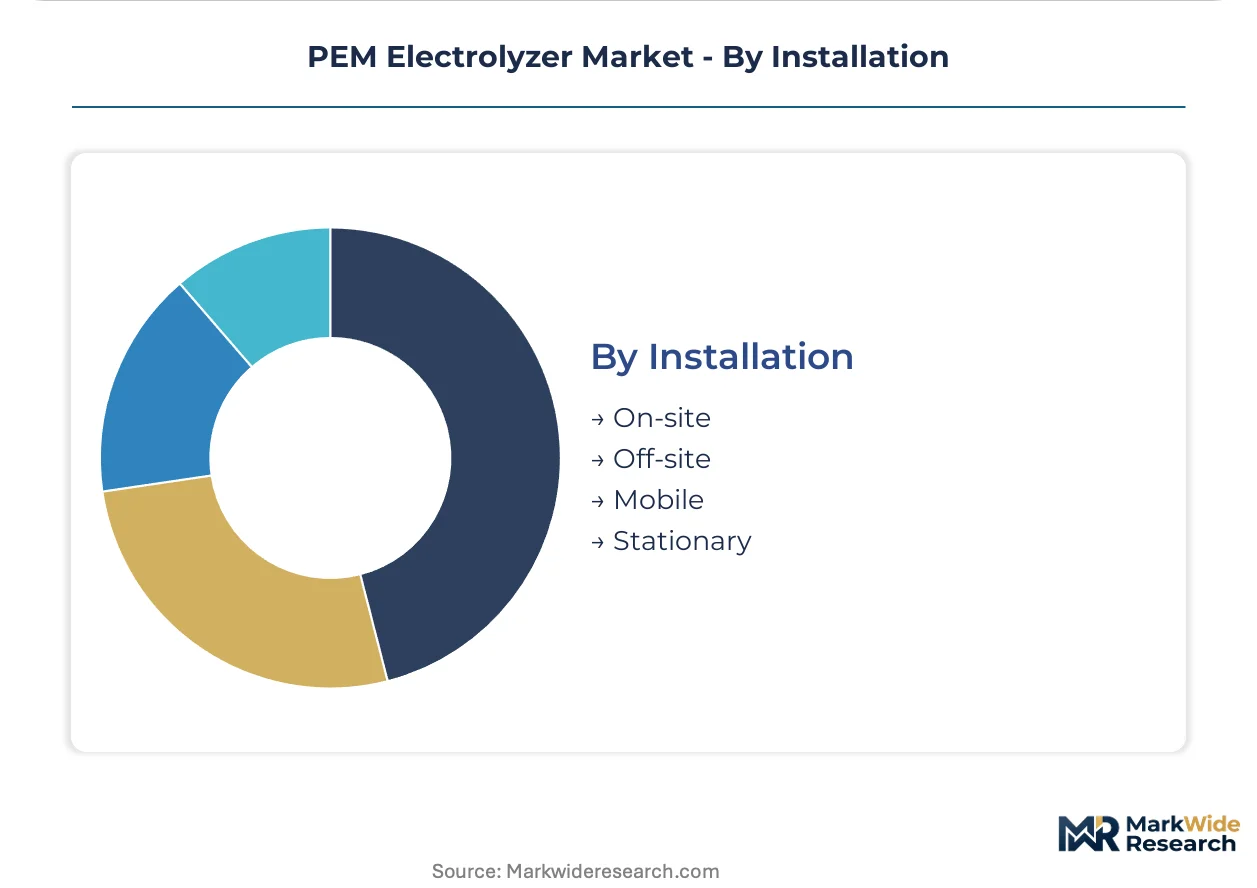
Installation:
Physical deployment model shapes permitting pathways, power interconnection costs, and operational flexibility trade-offs.
- Stationary:Fixed-site installations with dedicated civil infrastructure, grid connection, and hydrogen distribution piping. Industrial clusters in Germany's chemical corridors standardize on this model for multi-decade asset lifetimes.
- On-site:Co-located hydrogen production at point of consumption eliminates distribution logistics. Ammonia plants and steel mills in the Netherlands and Sweden prefer this configuration to secure supply chain control.
- Mobile:Containerized or skid-mounted systems relocatable between temporary power sources or demand centers. Mining operations in remote geographies and construction sites deploy these for project-duration hydrogen supply.
- Off-site:Centralized production facilities with pipeline or tube-trailer delivery to dispersed consumers. Emerging hub-and-spoke models in California and Germany's hydrogen core network test this architecture for cost aggregation.
Capacity installation concentrates in Stationary configurations; project pipeline momentum builds fastest in On-site deployments as industrial self-supply motives strengthen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr chemical corridor anchors European PEM electrolyzer deployment, with industrial clusters in Duisburg and Leverkusen driving megawatt-scale offtake agreements for green ammonia feedstock.
Germany
Fertilizer manufacturers in the Rhine-Ruhr region and steelmakers in the Hamburg industrial zone are contracting dedicated hydrogen supply under EU Green Deal delegated acts. The country's national hydrogen regulator enforces hourly temporal correlation requirements for renewable hydrogen certification. Chemical clusters in Leverkusen and Duisburg are co-locating electrolyzers behind offshore wind substations to comply with additionality criteria.
United States
California port drayage operators and Texas petrochemical complexes are procuring PEM systems for fleet decarbonization and process heat applications. The IRA production tax credits administered by the Treasury are compressing project payback periods for utility-scale deployments. Heavy-duty logistics hubs in Long Beach and Houston are signing long-term take-or-pay contracts bypassing merchant hydrogen markets entirely.
Japan
Ammonia synthesis pilot projects and power-to-gas demonstrations are testing stack integration with import terminal infrastructure. METI subsidy windows for hydrogen carrier facilities are opening procurement channels for European and North American equipment suppliers. Demonstration sites in Yokohama and Kobe are validating electrolyzer performance under the country's distinct certification protocols.
Netherlands
Offshore wind developers and steel decarbonization consortia are restructuring power purchase agreements to meet EU hourly matching requirements. The country's environmental regulator enforces delegated act compliance for renewable hydrogen offtake. Rotterdam port authorities and IJmuiden steelworks are anchoring demand for grid-connected electrolyzer installations.
China
Industrial parks in the Yangtze River Delta and Pearl River Delta are piloting PEM systems alongside dominant alkaline electrolyzer fleets. The Ministry of Industry and Information Technology sets efficiency benchmarks for electrolyzer manufacturing under dual carbon goals. Demonstration projects in Shanghai and Shenzhen are testing stack interoperability with variable renewable power profiles.
PEM Electrolyzer Market Competitive Landscape
Capital-heavy producers compete with asset-light designers for project development margins in the PEM electrolyzer market. Integrated industrial gas conglomerates and specialized electrochemical equipment firms occupy distinct competitive tiers. Three archetypes dominate: diversified energy majors with captive hydrogen distribution infrastructure, pure-play electrolyzer specialists with modular system architectures, and power engineering conglomerates with utility-scale project execution capabilities. Strategic moves concentrate on membrane electrode assembly integration and long-term service contract capture for stack refurbishment.
Among Nordic-based specialists, Nel ASA exemplifies the pure-play archetype with manufacturing discipline across high-volume orders. Siemens Energy AG occupies a position within the power engineering tier through captive proton exchange membrane research and utility-scale deployment capabilities. Plug Power Inc. represents the infrastructure-integrated model by anchoring North American hydrogen logistics networks and forklift-to-stationary power adjacencies.
| Leading Market Players |
|---|
| Linde plc |
| Air Products and Chemicals, Inc. |
| Nel ASA |
| Cummins Inc. |
| Plug Power Inc. |
| ITM Power |
| Air Liquide S.A. |
| Photofabrication Engineering, Inc. |
| Siemens Energy AG |
| Others |
Pricing and Supply Chain Analysis
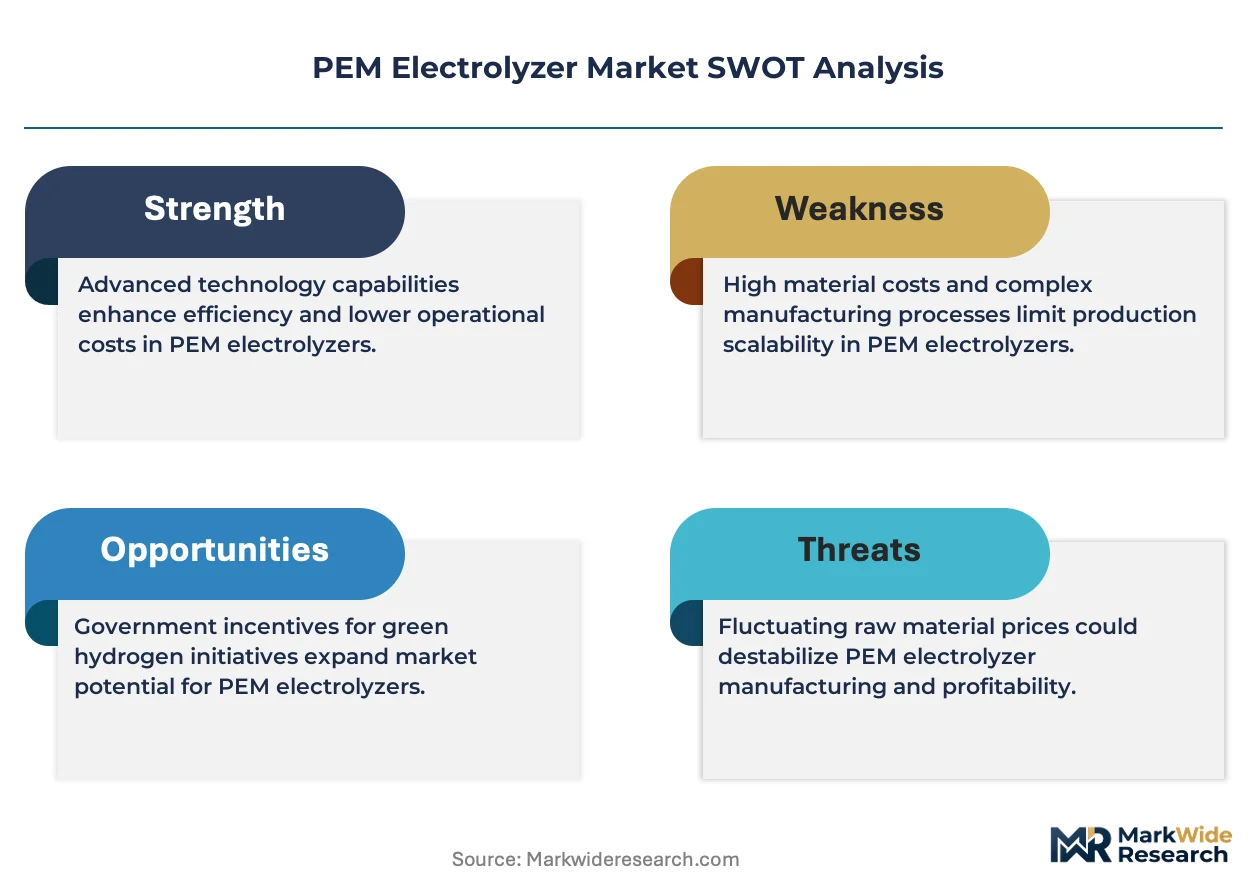
Membrane electrode assembly convergence toward integrated catalyst-coated membrane architectures is simultaneously compressing stack manufacturing costs and concentrating procurement leverage among Nordic and German production hubs. This technical transition rewards vendors with captive proton exchange membrane R&D capabilities while squeezing margin structures for asset-light system integrators dependent on third-party membrane supply.
Pricing Analysis
Long-term hydrogen output guarantees anchor value-based pricing frameworks where buyers pay per kilogram of certified renewable hydrogen delivered rather than capital equipment acquisition. Pricing stratifies across premium, standard, and economy tiers based on renewable certification stringency and membrane replacement bundling. Cost compression in standard-tier systems is intensifying because alkaline electrolyzer substitution threatens PEM adoption in baseload applications. Chemical offtakers in Germany's Rhine-Ruhr corridor exhibit lowest price sensitivity due to EU Green Deal compliance mandates, while remote industrial users in mining and construction segments drive hardest bargain negotiations.
Supply Chain Analysis
Direct-to-chemical-cluster channels handle megawatt-scale procurement from German and Danish project developers, while distributor-mediated sales serve smaller transportation fueling deployments. Iridium and platinum group metal supply concentrates in South African mining operations and Russian extraction facilities, creating geopolitical exposure for catalyst-dependent anode production. Stack manufacturing draws from perfluorosulfonic acid membrane supply anchored in United States and Japanese chemical production. Single-source vulnerability in iridium refining presents the dominant structural risk, with over four-fifths of global output originating from two jurisdictions facing diverging trade policy trajectories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PEM electrolyzer supply remains constrained by iridium catalyst scarcity and electrochemical engineering talent shortages, conditions that prop pricing power for integrated manufacturers with captive materials science capabilities.
For Market Incumbents: Lock in membrane electrode assembly supply through backward integration into catalyst-coated membrane manufacturing or exclusive tolling agreements with Nordic chemical producers. Secure long-term iridium offtake contracts with South African refiners before trade policy fragmentation hardens. Anion exchange membrane substitution represents the named threat requiring defensive patent positioning in platinum-group-metal-free catalyst configurations. For New Entrants and Emerging Players: Solid oxide electrolyzer hybrid architectures offer a technology-first wedge into high-temperature industrial process integration where PEM systems face efficiency disadvantages. Target Japan's METI-subsidized ammonia import infrastructure as the most penetrable geography, where distinct certification protocols disadvantage established European vendors. Pursue containerized system architectures as the specific go-to-market angle, enabling rapid deployment without permanent civil infrastructure. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated industrial gas conglomerates seeking captive hydrogen production capabilities. Long-term viability favors vendors with demonstrated utility-scale project execution and software competencies for renewable power coupling. Monitor hourly temporal correlation enforcement intensity under EU delegated acts as the specific signal indicating certification premium capture potential.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Electrode Assembly Integration | Captive catalyst-coated membrane production secures supply continuity against iridium price volatility. |
| Long-term Service Contract Capture | Stack refurbishment agreements with Rhine-Ruhr chemical clusters generate recurring revenue streams. |
| Power Purchase Agreement Structuring | Hourly matching compliance with EU Green Deal delegated acts commands certification premiums. |
| Containerized System Architecture | Modular deployment enables rapid relocation between offshore wind substations and demand centers. |
| Anion Exchange Membrane R&D Investment | Platinum-group-metal-free catalyst development eliminates iridium dependency while maintaining current density. |
Research Methodology
Document review covered EIA project databases, IEA hydrogen technology reports, EU delegated act regulatory filings, and SEC equipment manufacturer disclosures, complemented by interviews with utility planning officers, IPP project developers, EPC contractors, and fuel supply specialists. Primary fieldwork with electrolyzer stack engineering teams and chemical procurement leads validated capacity installation timelines and offtake contract structures. Bottom-up stack shipment tallies were cross-referenced against top-down hydrogen demand projections from ammonia and transportation fueling applications.
Historical deployment trajectories were cross-referenced against expert panel assessments of regulatory enforcement intensity and materials science breakthrough timelines. Segmentation modeling incorporated product type, end user industry, renewable integration technology, and installation configuration dimensions across the analysis window. CAGRs were derived from fitted growth curves calibrated to policy subsidy window durations and industrial offtake contract commencement patterns. Forecast inputs included offshore wind capacity expansion schedules in the North Sea and Baltic regions, plus IRA production tax credit utilization rates from Treasury guidance implementation.
Several conditions sit outside the modeled scope, including unilateral iridium export restrictions, abrupt alkaline electrolyzer cost breakthroughs, and suspension of EU Green Deal delegated act enforcement. Forecasts reflect assumptions regarding continued platinum group metal price volatility and stable renewable power purchase agreement availability. Practitioners should monitor South African mining labor actions and METI subsidy window renewal announcements for early signals of supply constraint intensification.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuel Cell Technology
Global Planar Solid Oxide Fuel Cell Market
Fuel Cell Technology
Europe Direct Methanol Fuel Cell Market
Fuel Cell Technology
Japan Fuel Cell Market
Fuel Cell Technology
Asia-Pacific Fuel Cell Market
Fuel Cell Technology
Global Fuel Cell Balance of Plant (BOP) Market
Fuel Cell Technology
Microbial Fuel Cell Market
Fuel Cell Technology
Phosphoric Acid Fuel Cell Market
Fuel Cell Technology
Hydrogen Fuel Cells Market
Fuel Cell Technology
Alkaline Fuel Cell Market
Fuel Cell Technology
China Fuel Cell Market
Fuel Cell Technology
Fuel Cells for CHP Application Market
Fuel Cell Technology
Fuel Cell for Stationary Power Market
Fuel Cell Technology
Solid Oxide Fuel Cell Market
Fuel Cell Technology
Europe Fuel Cell Market
Fuel Cell Technology
Fuel Cell Technology Market
Fuel Cell Technology
Fuel Cells for Marine Vessels Market