
 Hydrogen Fuel Cell Stack and Membrane Recycling for EU Mobility Market | 2026-2036
Hydrogen Fuel Cell Stack and Membrane Recycling for EU Mobility Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Fuel Cell Stack and Membrane Recycling for EU Mobility Market Insights
The divergence between premium catalyst recovery and commodity stack dismantling is realigning competitive tiers in EU hydrogen recycling. Johnson Matthey leverages its precious metal refining heritage to command high-value platinum and iridium streams from spent membrane electrode assemblies. Heraeus Precious Metals anchors German industrial clusters with closed-loop hydrometallurgical capacity. Umicore competes through integrated battery and fuel cell recycling infrastructure spanning Belgium and Poland.
Hydrogen fuel cell stack and membrane recycling encompasses the disassembly, sorting, and material recovery of proton exchange membrane fuel cell components, where membrane electrode assemblies contain 0.3-0.5 grams of platinum per kilowatt of rated power and require acid leaching or pyrometallurgical extraction to achieve 95%+ metal purity. The primary purpose is to recapture scarce platinum group metals and reuse bipolar plate substrates for remanufactured stacks serving EU mobility decarbonization targets. Membrane electrode assembly recycling leads value capture due to concentrated precious metal content, while hydrometallurgical recovery processes represent the fastest-expanding technology segment as operators seek lower-emission alternatives to pyrolysis. Fleet operators constitute the most concentrated end user channel, generating predictable high-volume feedstock from standardized public transport vehicle retirements.
The EU Green Deal, REACH, and F-Gas Regulation collectively mandate end-of-life accountability for hydrogen mobility components while restricting fluorinated membrane disposal pathways. ECHA chemical registration requirements shape leaching agent selection and waste classification for cross-border material shipments. Stakeholders must monitor how the EU AI Act's emerging transparency rules affect automated sorting line deployments and whether the CSRD extends circularity reporting obligations to fleet operators' recycling contracts.
Market Dynamics
The EU Green Deal's end-of-life accountability mandates are forcing rapid buildout of hydrometallurgical recovery infrastructure across member states, compressing the timeline for commercializing closed-loop platinum group metal flows.
Growth Catalysts
- EU Green Deal Decarbonization Mandates:Public transport fleet operators in Germany and the Netherlands face binding hydrogen bus deployment targets that generate predictable membrane electrode assembly retirement volumes.
- Membrane Electrode Assembly Precious Metal Concentration:Platinum loadings of 0.3-0.5 grams per kilowatt create concentrated recovery value streams that justify dedicated recycling facility investments.
- Cross-Border Feedstock Flows:Specialized hydrometallurgical facilities in the Netherlands attract spent fuel cell components from Belgium, Germany, and France under harmonized ECHA waste classification frameworks.
Market Restraints
- Platinum Price Volatility:Input cost uncertainty for recovered metal offtake contracts complicates long-term recycling facility financing and offtake agreement structuring.
- Fluorinated Membrane Disposal Restrictions:The EU F-Gas Regulation and REACH constraints on perfluorinated compound handling limit landfill and thermal destruction pathways for spent proton exchange membranes.
- Feedstock Concentration Risk:Early-stage hydrogen bus fleets in Germany and the Netherlands dominate available membrane electrode assembly volumes, creating geographic supply concentration.
Strategic Opportunities
- Poland's Emerging Industrial Cluster:Integrated battery and fuel cell recycling infrastructure investments position the country as a lower-cost alternative to Benelux processing capacity.
- CSRD Circularity Reporting Extension:The Corporate Sustainability Reporting Directive's evolving scope may mandate fleet operators to disclose recycling contract performance, creating audit-driven service demand.
- Automated Sorting and EU AI Act Convergence:Machine vision systems for bipolar plate grading and membrane classification align with emerging transparency requirements for automated industrial equipment.
Industry Challenges
- Hydrometallurgical Process Engineering Talent Scarcity:Acid leaching optimization and solvent extraction design expertise concentrates in legacy precious metals refiners, limiting new entrant technical staffing.
- CE Marking and Waste Shipment Compliance Timelines:Cross-border material movements require ECHA-registered leaching agent documentation and multi-jurisdictional waste code harmonization that extends project commissioning.
- Membrane Electrode Assembly Disassembly Standardization Delays:Absence of unified stack dismantling protocols forces facility-specific process development, raising capital intensity for each new recycling line.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Fuel Cell Stack and Membrane Recycling for EU Mobility Market |
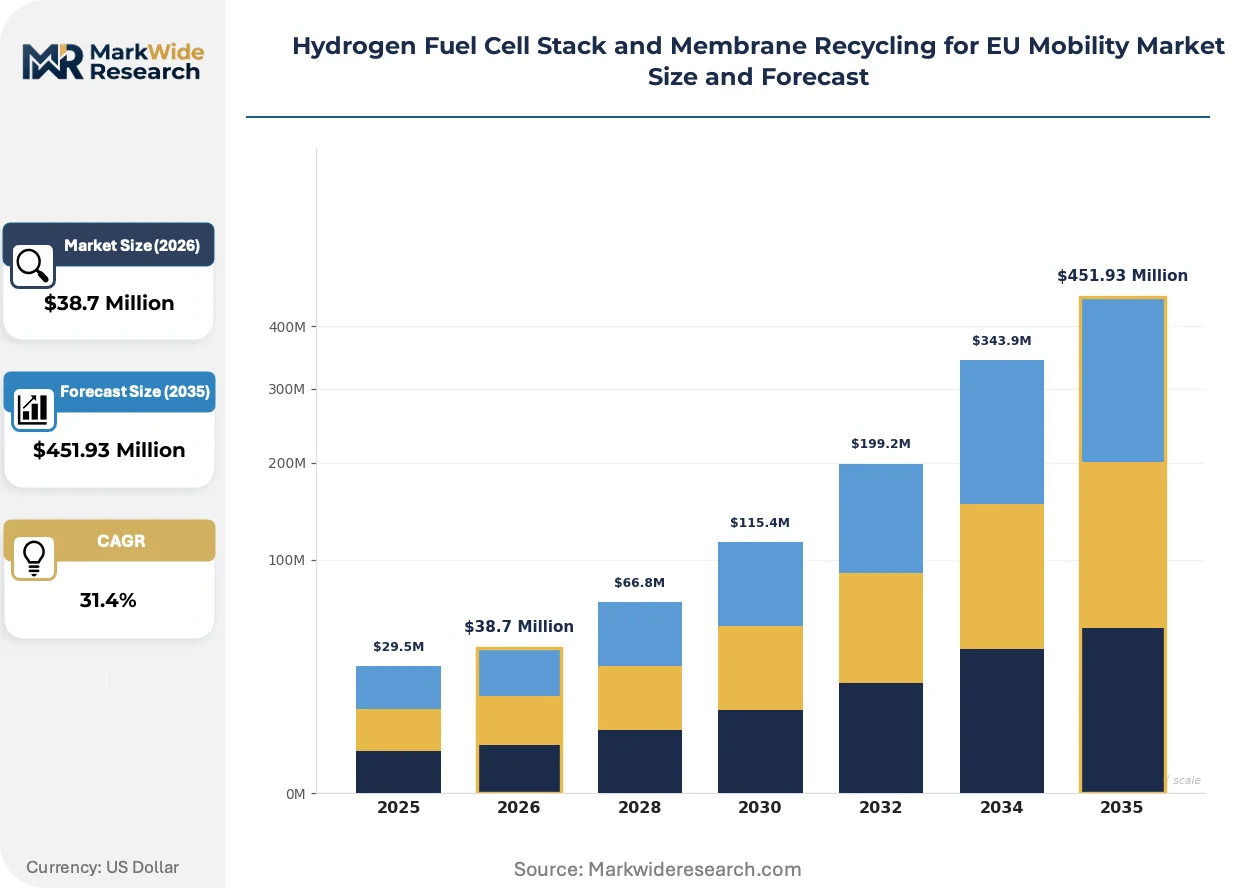
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $451.93 Million |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Membrane Electrode Assembly, Bipolar Plates, Gaskets, Catalyst Layers Application: Light Commercial Vehicles, Public Transport Vehicles, Forklifts, Delivery Trucks End User Type: Fleet Operators, Vehicle Refurbishment Centers, Recycling Facilities, Energy Providers Process Technology: Mechanical Crushing, Chemical Leaching, Pyrolysis, Hydrometallurgical Recovery |
| Companies Covered | Johnson Matthey, Hensel Recycling, Mastermelt, BASF Environmental Catalyst and Metal Solutions, Heraeus Precious Metals, Umicore, Syensqo, EKPO Fuel Cell Technologies, ZSW, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Fuel Cell Stack and Membrane Recycling for EU Mobility Market Trends and Innovations
Hydrometallurgical recovery processes are actively displacing pyrometallurgical alternatives as operators seek to reduce carbon intensity and capture higher-purity platinum group metal streams. Three interconnected developments are compressing technology adoption cycles.
Acid leaching with selective solvent extraction is overtaking pyrolysis-based recovery as the dominant membrane electrode assembly processing route. German industrial clusters are adopting closed-loop hydrometallurgical circuits to meet Scope 3 emissions targets. This technology shift is enabling 95%+ platinum purity at lower energy intensity, compressing payback periods for new facility investments.
The EU AI Act's transparency requirements for automated industrial systems are reshaping sorting line deployment economics. Fleet operators and recyclers must document algorithmic decision-making in membrane classification and bipolar plate grading equipment. German public transport authorities are most affected, requiring vendor compliance documentation before contract award.
Service unbundling is fragmenting traditional integrated recycling contracts. Fleet operators in the Netherlands now separately procure collection logistics, dismantling services, and precious metal refining, pressuring full-service providers to defend margin position through performance guarantees. This pattern is most visible in Rotterdam-Amsterdam corridor hydrogen bus deployments where municipal procurement rules favor multi-vendor structures.
Hydrogen Fuel Cell Stack and Membrane Recycling for EU Mobility Market Segmentation
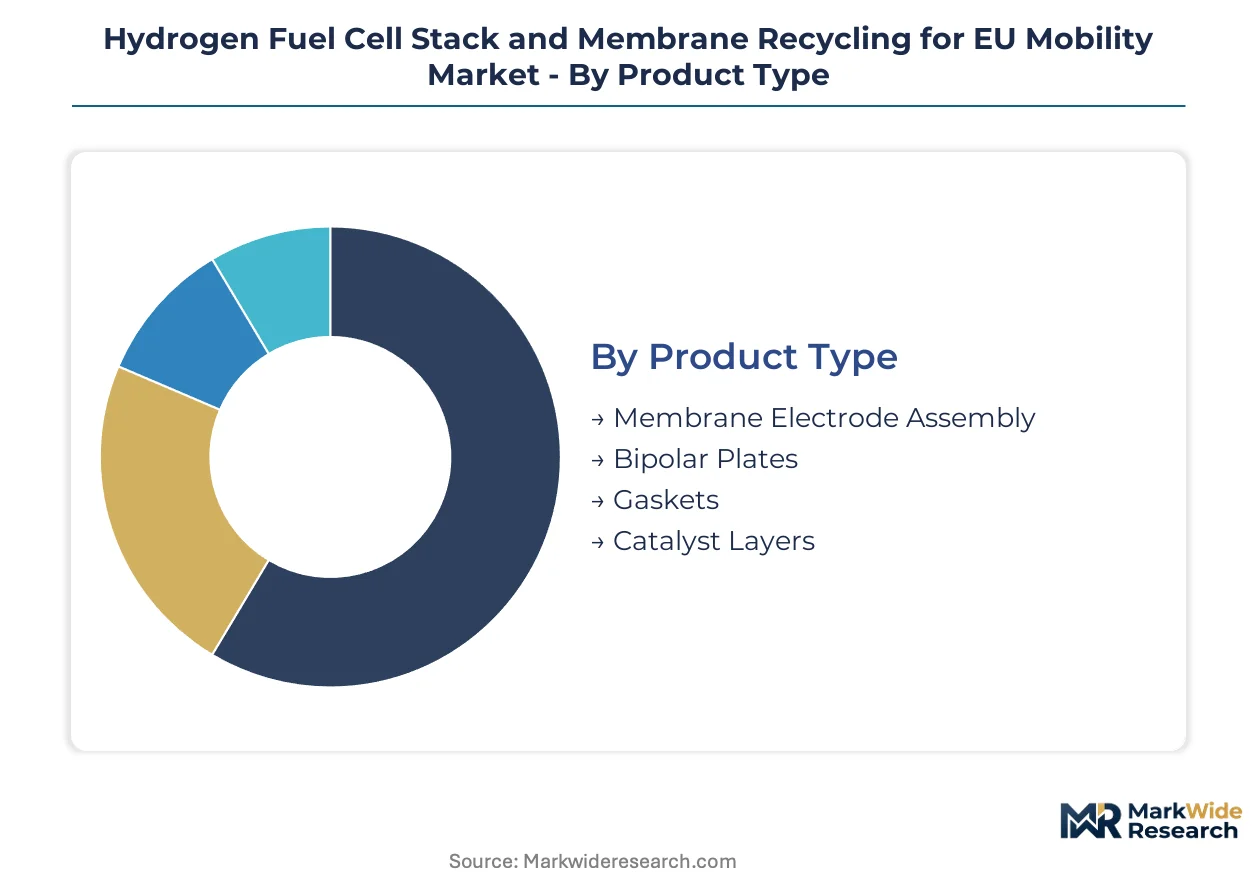
Segmentation in hydrogen fuel cell recycling reveals how regulatory complexity concentrates value capture. Certification requirements for precious metal recovery and fluorinated material handling create tiered compliance burdens that reshape competitive positioning across product categories and process technologies.
Product Type:
CE marking obligations and REACH registration requirements vary sharply by component precious metal content and fluoropolymer composition.
- Membrane Electrode Assembly:Contains 0.3-0.5 grams of platinum per kilowatt of rated power within catalyst layers bonded to proton exchange membranes. German public transport fleet retirements in Berlin and Hamburg generate concentrated feedstock volumes that justify dedicated acid leaching facility investments. ECHA chemical registration requirements govern solvent extraction agent selection for cross-border material movements.
- Bipolar Plates:Graphite-polymer or metal substrate structures that channel reactant gases and electrical current, recoverable for remanufactured stack assembly. Netherlands-based hydrometallurgical facilities prioritize plate substrate sorting to supply Belgian remanufacturing clusters under harmonized waste codes. F-Gas Regulation constraints on fluorinated coatings limit thermal recovery pathways.
- Gaskets:Elastomeric sealing components with lower precious metal contamination, processed through mechanical separation rather than chemical extraction.
- Catalyst Layers:Thin electrochemically active coatings applied to membrane surfaces, requiring specialized dissolution protocols distinct from bulk membrane handling.
Membrane Electrode Assembly sits at the top of the volume ranking, with Bipolar Plates climbing the fastest as remanufacturing demand outpaces virgin substrate supply.
Application:
End-use vehicle categories determine retirement predictability and feedstock standardization, with municipal procurement rules shaping collection logistics structures.
- Public Transport Vehicles:Hydrogen bus fleets operate under EU Green Deal binding deployment targets that create scheduled retirement calendars. German federal-state transit authorities in Bavaria and North Rhine-Westphalia coordinate standardized 12-year vehicle lifecycles, enabling long-term recycling contract structures.
- Light Commercial Vehicles:Smaller fuel cell powertrains in urban delivery vans generate dispersed retirement patterns across multiple logistics operators.
- Delivery Trucks:Medium-duty hydrogen trucks for last-mile distribution present emerging feedstock volumes as pilot fleets scale in Rotterdam and Amsterdam corridors.
- Forklifts:Indoor material handling equipment with smaller stack configurations, concentrated in Netherlands distribution center deployments.
Public Transport Vehicles dominate current feedstock availability, while Delivery Trucks gain share fastest as municipal logistics electrification accelerates.
End User Type:
Customer procurement sophistication varies by in-house technical capability and regulatory reporting obligations under evolving CSRD circularity disclosure requirements.
- Fleet Operators:Public and private vehicle owners responsible for end-of-life accountability under EU Green Deal extended producer responsibility frameworks. German municipal transport companies now unbundle recycling contracts into separate logistics, dismantling, and refining procurement lots to satisfy audit-driven procurement rules.
- Vehicle Refurbishment Centers:Regional remanufacturing facilities that recover bipolar plates and gaskets for stack rebuild programs serving secondary markets.
- Recycling Facilities:Licensed waste processors operating under ECHA-registered leaching agent protocols and multi-jurisdictional waste shipment authorizations.
- Energy Providers:Utility-affiliated hydrogen infrastructure operators with captive fleet retirement obligations.
Fleet Operators anchor current contract volumes, with Recycling Facilities expanding most quickly as specialized hydrometallurgical capacity multiplies across Benelux and Poland.
Process Technology:
Technology selection determines carbon intensity, metal purity achievement, and capital intensity thresholds that filter market entry.
- Hydrometallurgical Recovery:Acid leaching combined with selective solvent extraction achieves 95%+ platinum purity at lower energy intensity than thermal alternatives. German industrial clusters adopt closed-loop circuits to meet Scope 3 emissions targets, with Netherlands facilities attracting cross-border feedstock from Belgium and France.
- Chemical Leaching:Batch acid dissolution processes for smaller-scale operators without continuous flow infrastructure.
- Mechanical Crushing:Size reduction and magnetic separation for bipolar plate substrate recovery, bypassing fluorinated membrane handling constraints.
- Pyrolysis:High-temperature thermal decomposition with higher carbon footprint, losing share to hydrometallurgical alternatives under tightening emissions regulations.
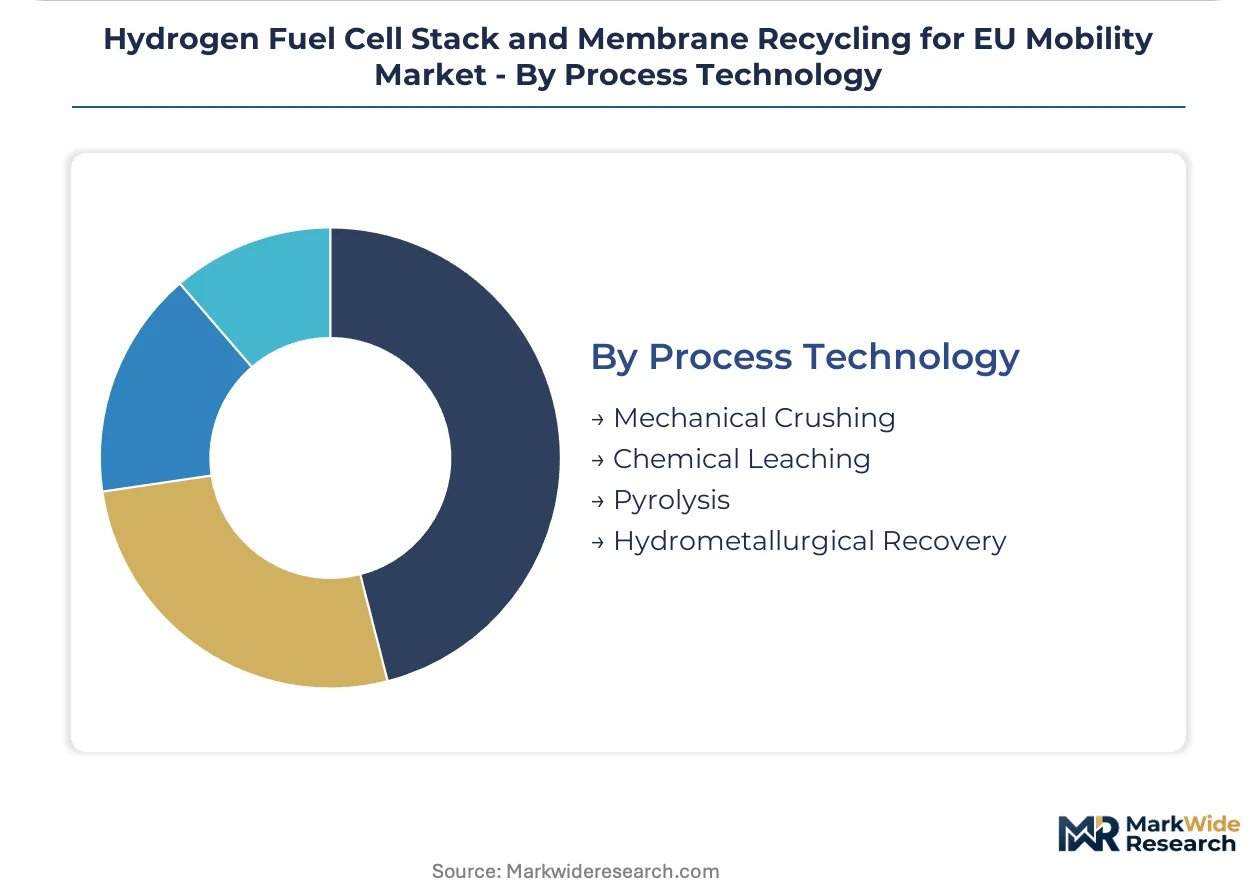
Hydrometallurgical Recovery leads on value capture, with Mechanical Crushing gaining traction fastest for non-precious metal component streams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized hydrometallurgical engineers and precious metals chemists concentrate in the Netherlands and Germany, anchoring EU hydrogen recycling capacity. This talent distribution shapes where acid leaching facilities achieve commercial scale first. Cross-border feedstock flows follow these technical clusters.
Germany
Berlin and Hamburg public transport authorities operate scheduled hydrogen bus retirement programs under federal-state transit agreements. The EU Green Deal's binding decarbonization targets for municipal fleets create predictable membrane electrode assembly volumes. Heraeus Precious Metals anchors industrial hydrometallurgical capacity in Hanau, serving Bavarian and North Rhine-Westphalia fleet operators through closed-loop refining circuits.
Netherlands
Rotterdam-Amsterdam corridor municipalities unbundle recycling contracts into separate logistics, dismantling, and refining procurement lots. ECHA-registered leaching agent protocols enable cross-border waste shipments from Belgium and France under harmonized classifications. Specialized facilities in the Randstad attract spent fuel cell components from German and French fleet operators seeking lower-emission recovery alternatives to pyrolysis.
Belgium
Umicore's integrated battery and fuel cell recycling infrastructure spans Antwerp and Hoboken, positioning the country as a hub for precious metal refining. REACH registration requirements for solvent extraction agents shape leaching chemistry selection for membrane electrode assembly processing. The Flanders region hosts remanufacturing clusters that recover bipolar plate substrates for stack rebuild programs serving secondary mobility markets.
Poland
Lower-cost processing capacity investments near Katowice target integrated battery and fuel cell recycling infrastructure. The country's industrial clusters attract German and Benelux feedstock flows seeking alternatives to higher-cost western EU hydrometallurgical capacity. EU cohesion fund support for circular economy projects accelerates facility commissioning timelines for acid leaching circuits.
France
Île-de-France transport authorities pilot hydrogen bus deployments under regional climate plans, generating early membrane electrode assembly retirement volumes. ANSM chemical safety oversight intersects with ECHA registration requirements for cross-border material movements to Belgian and Dutch processors. The Auvergne-Rhône-Alpes region hosts research partnerships between stack manufacturers and recyclers developing standardized dismantling protocols.
Hydrogen Fuel Cell Stack and Membrane Recycling for EU Mobility Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across hydrogen fuel cell recycling, though both require ECHA-registered chemical handling licenses to operate. The vendor base concentrates around precious metals refiners extending into fuel cell streams and specialized hydrometallurgical operators serving cross-border EU feedstock flows. Three archetypes dominate: legacy platinum group metal refiners with closed-loop heritage, integrated materials companies spanning battery and fuel cell recovery, and regional specialists concentrating single-process excellence. Capacity expansion and strategic partnerships represent the dominant competitive moves as operators seek to secure long-term offtake agreements with fleet operators.
Among legacy precious metals refiners, Johnson Matthey and Heraeus Precious Metals exemplify archetypes leveraging multi-decade platinum recovery expertise into membrane electrode assembly streams. BASF Environmental Catalyst and Metal Solutions occupies a position bridging chemical catalyst heritage with fuel cell component recycling. These three represent how technical staffing concentration in acid leaching and solvent extraction creates defensive moats against new entrants lacking comparable process engineering depth.
| Leading Market Players |
|---|
| Johnson Matthey |
| Hensel Recycling |
| Mastermelt |
| BASF Environmental Catalyst and Metal Solutions |
| Heraeus Precious Metals |
| Umicore |
| Syensqo |
| EKPO Fuel Cell Technologies |
| ZSW |
| Others |
Pricing and Supply Chain Analysis
Platinum group metal spot prices cascade through membrane electrode assembly recovery contracts, compressing margins for hydrometallurgical operators serving German fleet operators while rewarding Dutch facilities with cross-border feedstock arbitrage. Acid leaching chemical costs and ECHA-registered solvent extraction agent procurement dominate variable cost structures, creating pricing power concentration among legacy precious metals refiners with captive chemical supply chains.
Pricing Analysis
Service unbundling splits integrated recycling contracts into separate logistics, dismantling, and refining procurement lots. Price differentiation rests on precious metal recovery purity tiers and CSRD audit documentation depth, with Rotterdam-Amsterdam corridor municipalities demanding transparent chain-of-custody reporting. Cost compression in commodity stack dismantling intensifies as Polish operators undercut Benelux hydrometallurgical rates. Fleet operators exhibit highest price sensitivity for collection logistics, while refining services command premium tolerance due to platinum purity guarantees.
Supply Chain Analysis
Regional distribution centers in the Netherlands and Germany anchor hub-and-spoke collection networks feeding specialized acid leaching facilities. Feedstock draws from hydrogen bus retirements in Germany, the Netherlands, and Belgium, with membrane electrode assemblies and bipolar plates constituting the critical component streams. Single-source vulnerability concentrates in ECHA-registered leaching agent suppliers, where REACH compliance documentation creates switching friction. Distribution runs through municipal fleet operator contracts to licensed dismantling facilities, then onward to precious metals refiners under long-term offtake structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hydrogen fuel cell recycling offers margin expansion through hydrometallurgical process efficiency gains and premium-tier service unbundling, with platinum purity achievement and CSRD compliance documentation driving value capture differentiation.
For Market Incumbents: Deploy closed-loop hydrometallurgical capacity expansion to defend against Polish cost competition threatening Benelux processing margins. Johnson Matthey and Heraeus Precious Metals should deepen acid leaching talent retention while securing exclusive offtake agreements with German federal-state transit authorities facing binding fleet retirement schedules. ECHA chemical registration portfolios create regulatory moats against emerging entrants lacking comparable compliance infrastructure. For New Entrants and Emerging Players: Automated membrane classification systems using machine vision offer technology-first entry points where EU AI Act transparency requirements reshape procurement criteria. Poland's emerging Katowice industrial cluster presents the most penetrable geography, with EU cohesion fund support compressing facility commissioning timelines. Target service unbundling opportunities in Rotterdam-Amsterdam corridor logistics contracts, where municipal procurement rules favor multi-vendor structures over integrated incumbents. For Investors and Strategic Acquirers: Consolidation pressure builds where hydrometallurgical process engineering talent scarcity limits new entrant technical staffing. Long-term viability favors acquiring mid-cap specialists with ECHA-registered chemical handling licenses and established cross-border waste shipment authorizations. Watch for inflection where CSRD circularity reporting mandates extend to fleet operator recycling contract disclosure obligations, triggering audit-driven service demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Leaching Agent Supply | ECHA-registered chemical captive production secures REACH compliance continuity for Dutch and German facilities. |
| Cross-Border Waste Shipment Authorization Expansion | Harmonized multi-jurisdictional permits enable Netherlands facilities to capture Belgian and French feedstock flows. |
| Automated Sorting Line Deployment | Machine vision systems for bipolar plate grading align with EU AI Act transparency mandates affecting German procurement. |
| CSRD Compliance Documentation Services | Audit-ready chain-of-custody reporting creates premium service tier for Rotterdam-Amsterdam municipal contracts. |
| Poland Industrial Cluster Capacity Buildout | Lower-cost acid leaching circuits near Katowice attract German and Benelux feedstock seeking margin relief. |
Research Methodology
Coverage spans Germany, the Netherlands, Belgium, Poland, and France, with primary inputs from each market cluster. The analysis combines structured interviews with fleet procurement directors, hydrometallurgical plant managers, ECHA regulatory affairs specialists, and precious metals refining operations leads with secondary validation from EU Green Deal implementation reports, ECHA chemical registration databases, CSRD disclosure frameworks, and national transport authority fleet retirement schedules. Bottom-up feedstock volume modeling triangulates against top-down EU mobility decarbonization target allocations.
Granularity-level modeling captures membrane electrode assembly, bipolar plate, gasket, and catalyst layer product segments alongside public transport vehicle, light commercial vehicle, delivery truck, and forklift application categories. Hydrometallurgical recovery, chemical leaching, mechanical crushing, and pyrolysis process technologies were dimensioned separately. CAGRs derive from compounding annual feedstock availability projections tied to scheduled hydrogen bus fleet retirements across the analysis window, with platinum price volatility scenarios stress-testing recovery facility revenue models.
The model holds under sustained EU Green Deal enforcement and ECHA waste classification harmonization; deviation in F-Gas Regulation membrane disposal pathway restrictions or platinum spot price collapse would shift facility economics. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuel Cell Technology
Hydrogen Fuel Cell Stack Durability and Performance Test Equipment Market
Fuel Cell Technology
North America Fuel Cell Technology Market
Fuel Cell Technology
Portable Fuel Cells Market
Fuel Cell Technology
Proton Exchange Membrane Fuel Cell (PEMFC) Market
Fuel Cell Technology
Asia-Pacific Direct Methanol Fuel Cell Market
Fuel Cell Technology
Europe Direct Methanol Fuel Cell Market
Fuel Cell Technology
Alkaline Fuel Cell Market
Fuel Cell Technology
Fuel Cells for Marine Vessels Market
Fuel Cell Technology
Helium Recovery Systems Market
Fuel Cell Technology
Solid Oxide Fuel Cell Market
Fuel Cell Technology
Global Planar Solid Oxide Fuel Cell Market
Fuel Cell Technology
Protonic Ceramic Fuel Cell (PCFC) Market
Fuel Cell Technology
Hydrogen Fuel Cells Market
Fuel Cell Technology
Europe Fuel Cell Market
Fuel Cell Technology
Hydrogen Fuel Cell Drone Market
Fuel Cell Technology
Aircraft Fuel Cell Market