
 Fuel Cell Market | 2026-2036
Fuel Cell Market Size, Share, and Industry Trends Forecast 2026-2036
Fuel Cell Market Analysis
Platinum is restructuring fuel cell stack economics as manufacturers reduce loadings through advanced catalyst layer engineering and alloy formulations. Ballard Power Systems anchors heavy-duty transportation deployments with specialized membrane electrode assembly production in North America and Europe. Plug Power Inc. extends its position through captive green hydrogen supply and integrated fueling infrastructure for material handling and logistics customers. Ceres Power Holdings PLC differentiates via steel-supported solid oxide technology that operates at lower temperatures than conventional ceramic designs.
A fuel cell converts chemical energy from hydrogen or hydrogen-rich fuels directly into electrical power through electrochemical reactions, typically achieving electrical efficiencies of 40-60% and generating water as the primary byproduct. Proton exchange membrane systems dominate automotive and portable applications due to rapid cold-start capability and power density above 1.0 kW per liter. Solid oxide fuel cells command stationary power and industrial cogeneration segments where exhaust heat recovery pushes combined efficiencies toward 90%. Transportation applications across heavy trucking, maritime, and rail represent the fastest-expanding end-use category as battery weight penalties exclude these modes from full electrification.
The US EPA and Department of Energy coordinate zero-emission vehicle mandates with hydrogen hub funding under the IRA framework, while the EU F-Gas Regulation and ETS carbon pricing mechanisms elevate fuel cell competitiveness against diesel alternatives. Japan's METI maintains hydrogen and fuel cell technology roadmaps that direct public-private investment toward residential cogeneration and industrial decarbonization. Stakeholders must track electrolyzer cost curves and green hydrogen offtake contract structures, as these upstream variables determine fuel cell operating economics more directly than stack manufacturing scale.
Market Dynamics
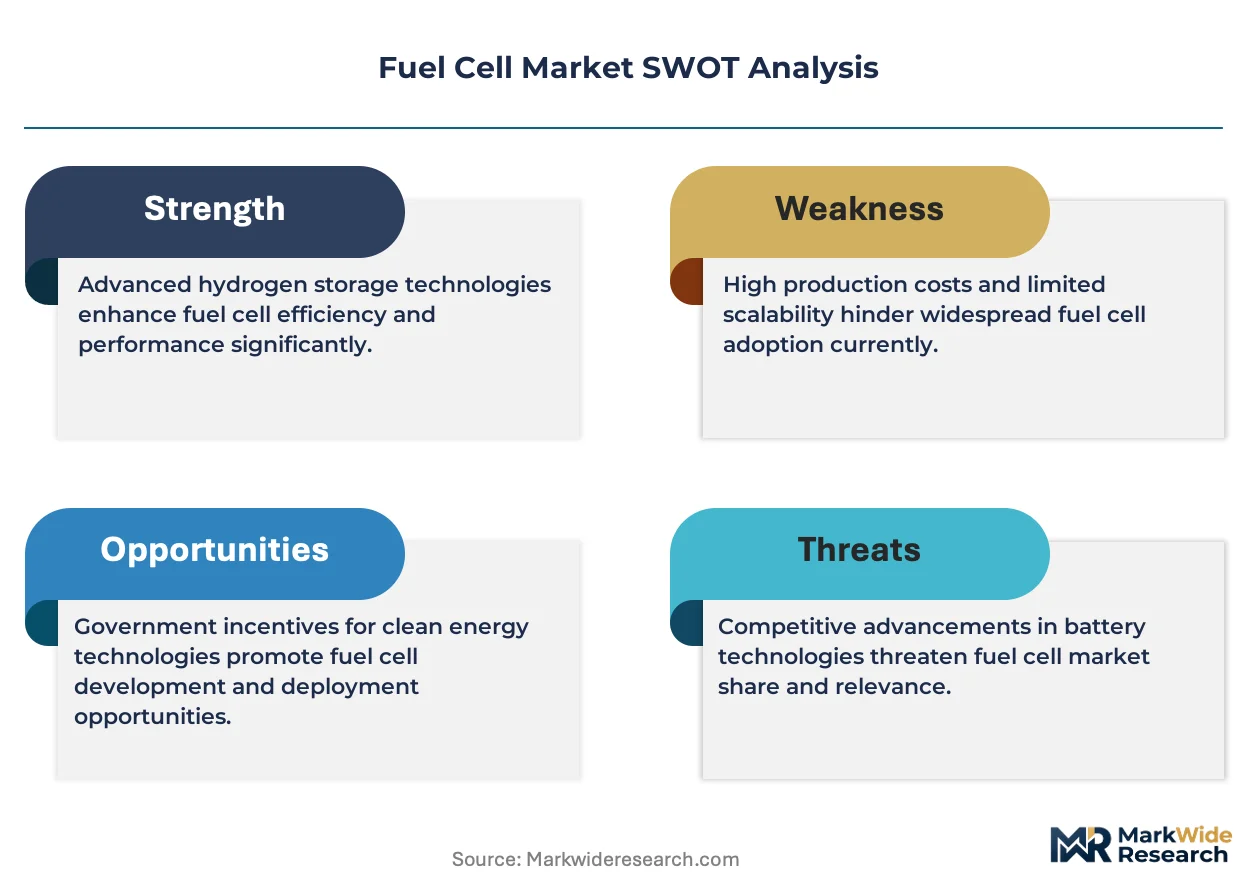
Platinum loading reduction is compressing fuel cell stack costs faster than manufacturing scale alone, as advanced catalyst layer engineering and alloy formulations cut precious metal content without sacrificing power density or durability.
Growth Catalysts
- US Inflation Reduction Act hydrogen production tax credits:These credits subsidize electrolyzer capacity expansion, lowering green hydrogen delivered costs and improving fuel cell operating economics for fleet operators in California and Texas.
- Heavy-duty trucking payload constraints:Battery weight penalties exclude long-haul freight from full electrification, pulling fleet procurement toward proton exchange membrane systems for routes exceeding 500 miles.
- German national hydrogen roadmap:Public procurement mandates for fuel cell buses and regional trains create guaranteed offtake volumes that de-risk manufacturing investments by stack suppliers.
Market Restraints
- Platinum supply concentration:South African and Russian mining operations control over 70% of primary platinum output, exposing catalyst cost curves to geopolitical disruption and export restriction risk.
- Electrolyzer capital intensity:Alkaline and proton exchange membrane electrolyzer systems require $800-1,200 per kilowatt installed capacity, slowing green hydrogen production scale-up and keeping fuel cell feedstock costs elevated.
- Compressed natural gas substitution:CNG infrastructure maturity and lower vehicle conversion costs delay fuel cell adoption in municipal bus fleets where range requirements are modest.
Strategic Opportunities
- Maritime auxiliary power units:International Maritime Organization emission targets for port operations create demand for solid oxide fuel cells in container ship cold-ironing and hotel load applications.
- EU Green Deal renewable hydrogen targets:The 10 million ton domestic production mandate by 2030 requires electrolyzer-fuel cell integration across industrial clusters in the Netherlands and Spain.
- Steel-supported solid oxide technology:Lower operating temperatures than ceramic designs enable faster thermal cycling and modular packaging for distributed generation in data center backup power.
Industry Challenges
- Membrane electrode assembly technician scarcity:Precision coating and catalyst deposition skills concentrate at Ballard Power Systems and Plug Power facilities, constraining second-source supplier qualification timelines.
- Hydrogen fueling station certification:NFPA 2 and SAE J2601 compliance testing extends deployment schedules for retail infrastructure, limiting consumer vehicle market development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fuel Cell Market |
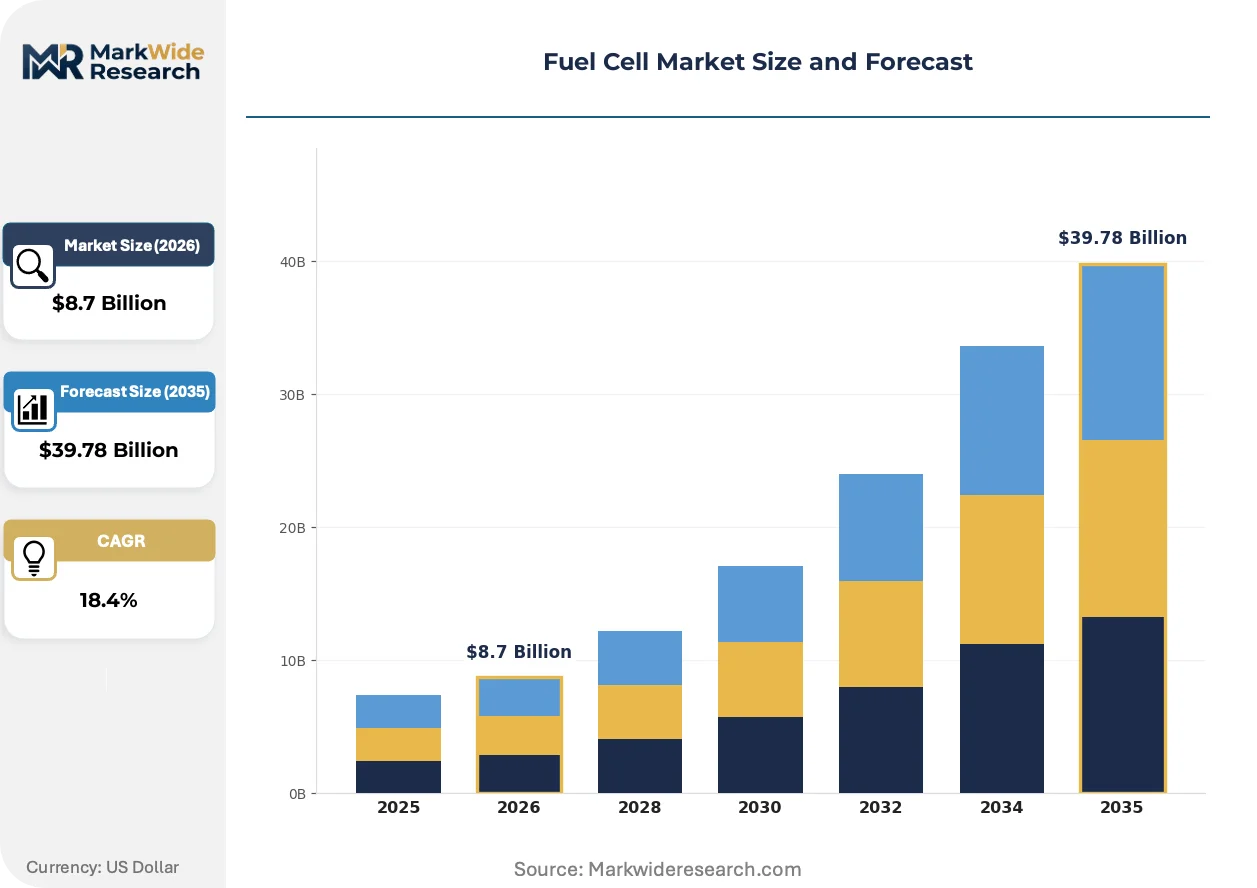
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Proton Exchange Membrane, Solid Oxide, Alkaline, Direct Methanol End User: Automotive, Aerospace, Industrial, Stationary Power Application: Backup Power, Transportation, Portable Power, Energy Storage Technology: Hydrogen Fuel, Methanol Fuel, Biofuel, Hybrid Systems |
| Companies Covered | Plug Power Inc., Ballard Power Systems, Bloom Energy, FuelCell Energy Inc., SFC Energy AG, AISIN Corporation, Doosan Fuel Cell, Ceres Power Holdings PLC, Hydrogenics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fuel Cell Market Emerging Trajectories
Electrochemical system architectures are fragmenting across temperature regimes and fuel flexibility, as stationary and mobility applications diverge in their thermal management and hydrogen purity requirements.
Anion exchange membrane technology is rewriting the cost structure of low-temperature fuel cells by eliminating platinum group metals entirely while maintaining the rapid cold-start capability that proton exchange membrane systems provide. Material handling fleet operators at Amazon and Walmart distribution centers are piloting these stacks for forklift replacements. The technology is compressing the historical trade-off between catalyst cost and power density that has constrained fuel cell penetration in price-sensitive logistics segments.
EU F-Gas Regulation phase-down schedules for fluorinated greenhouse gases are forcing membrane manufacturers to reformulate proton exchange materials using shorter-chain perfluorinated compounds or hydrocarbon alternatives. Industrial consequence includes accelerated qualification timelines for new membrane chemistries at electrolyzer and fuel cell producers. The stationary power segment in Germany and Denmark is most affected, as solid oxide systems with ceramic electrolytes face renewed competitive pressure from reformulated low-temperature alternatives.
Fleet procurement contracts are consolidating hydrogen supply and fueling infrastructure into single-source agreements that bundle electrolyzer output, compression, and dispensing with stack maintenance and performance guarantees. Logistics operators in California's Central Valley are displacing fragmented fuel procurement through these integrated service models. The pattern is most visible in heavy trucking, where Total Cost of Ownership comparisons against diesel favor operational simplicity over capital ownership.
Fuel Cell Market Segmentation
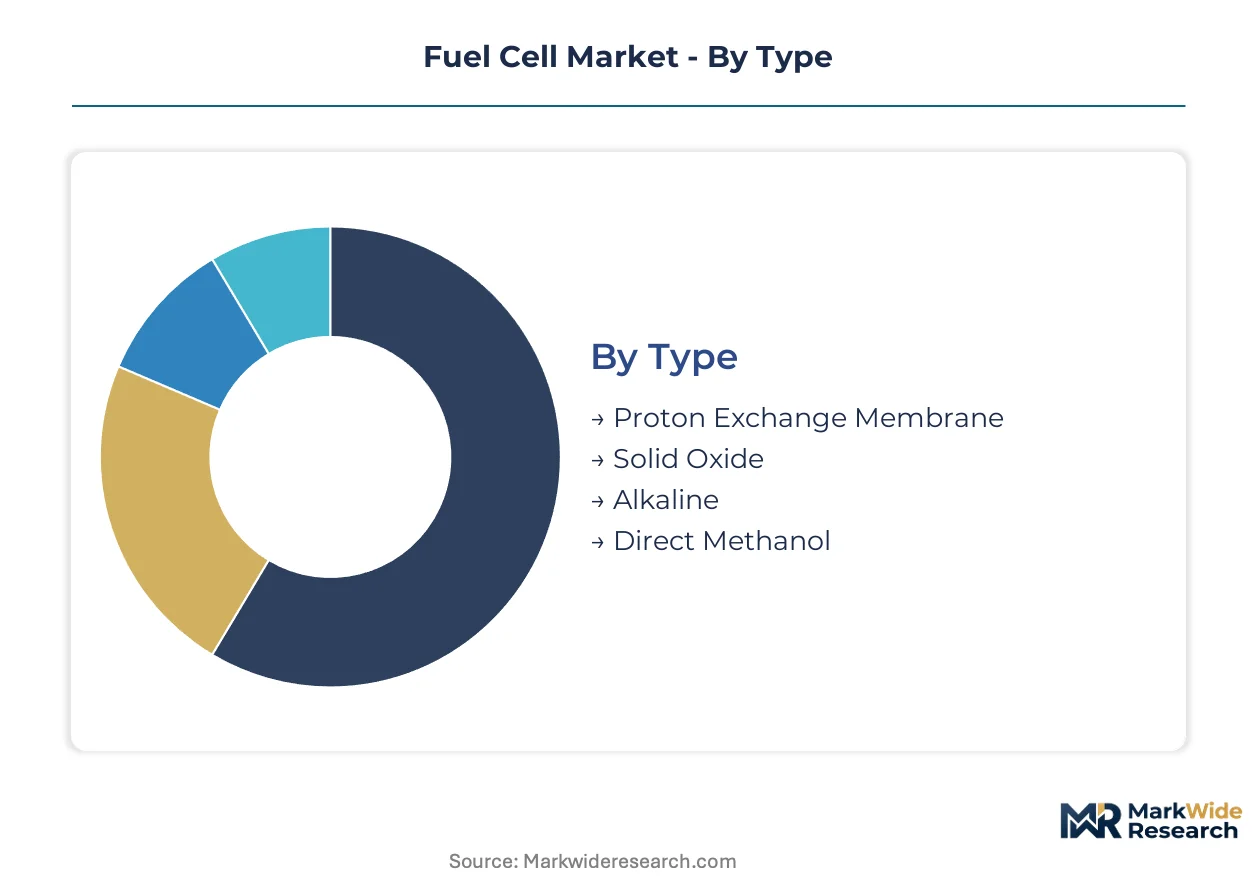
Fuel cell segmentation tracks electrochemical system architectures across temperature regimes and fuel flexibility requirements. Technology choices cascade through manufacturing scale, precious metal loading, and hydrogen purity specifications that define competitive positioning in each vertical.
Type:
Upgrade cycles in heavy-duty transportation and stationary power are pulling fleet operators and utilities toward next-generation stack designs with reduced catalyst loadings and extended service intervals.
- Proton Exchange Membrane:Polymer electrolyte membranes conduct protons at 60-80°C with power density above 1.0 kW per liter, enabling rapid cold-start for Class 8 trucking routes exceeding 500 miles where battery weight penalties exclude electrification. California's Central Valley freight corridors concentrate procurement volumes as hydrogen hub infrastructure matures.
- Solid Oxide:Ceramic or steel-supported electrolytes operate at 600-850°C with combined heat and power efficiencies approaching 90%, serving industrial cogeneration and data center backup applications. Germany's Ruhr industrial cluster anchors demand for grid-scale stationary installations with exhaust heat recovery.
- Alkaline:Liquid potassium hydroxide electrolyte systems achieve 60% electrical efficiency without platinum group metals, finding niche deployment in cost-sensitive stationary power.
- Direct Methanol:Dilute methanol fuel eliminates hydrogen storage infrastructure, supporting portable electronics and remote sensor networks with lower energy density trade-offs.
Proton Exchange Membrane sits at the top of the volume ranking, with Solid Oxide climbing the fastest as steel-supported designs compress thermal cycling limitations.
End User:
Customer procurement patterns diverge sharply between mobility operators seeking single-source hydrogen service agreements and industrial facilities optimizing around captive heat recovery.
- Automotive:Passenger vehicle deployments concentrate in Japan and South Korea where METI hydrogen roadmaps direct retail infrastructure investment. South Korea's Ulsan industrial complex anchors domestic fuel cell vehicle manufacturing with dedicated hydrogen supply.
- Aerospace:Auxiliary power units for ground operations and emerging propulsion concepts drive solid oxide system development for emission-controlled airport environments.
- Industrial:Steel, ammonia, and refinery operations in the Netherlands and Spain integrate electrolyzer-fuel cell systems under EU Green Deal renewable hydrogen mandates for process heat and power.
- Stationary Power:Commercial buildings and critical facilities in Denmark deploy combined heat and power configurations with district heating integration, leveraging high electrical efficiency and exhaust thermal capture.
Industrial procurement dominates current revenue concentration, with Automotive expanding most quickly as heavy-duty trucking fleets displace diesel on long-haul corridors.
Application:
Application selection hinges on duty cycle predictability and hydrogen accessibility, with continuous baseload operations commanding premium stack durability specifications.
- Backup Power:Telecommunications and data center operators in Germany specify solid oxide systems with 99.999% availability targets, displacing diesel generators under EU F-Gas Regulation emission constraints.
- Transportation:Material handling fleets at Amazon and Walmart distribution centers convert forklift operations to proton exchange membrane systems, bundling hydrogen supply into performance-based service contracts.
- Portable Power:Military and emergency response units deploy direct methanol and reformate-capable systems for off-grid electricity in remote terrain.
- Energy Storage:Grid-scale installations in Texas and California pair electrolyzer-fuel cell combinations with renewable curtailment, converting excess solar and wind into dispatchable hydrogen power.
Backup Power commands the highest margin tier, with Energy Storage gaining share fastest as grid interconnection queues extend and renewable penetration climbs.
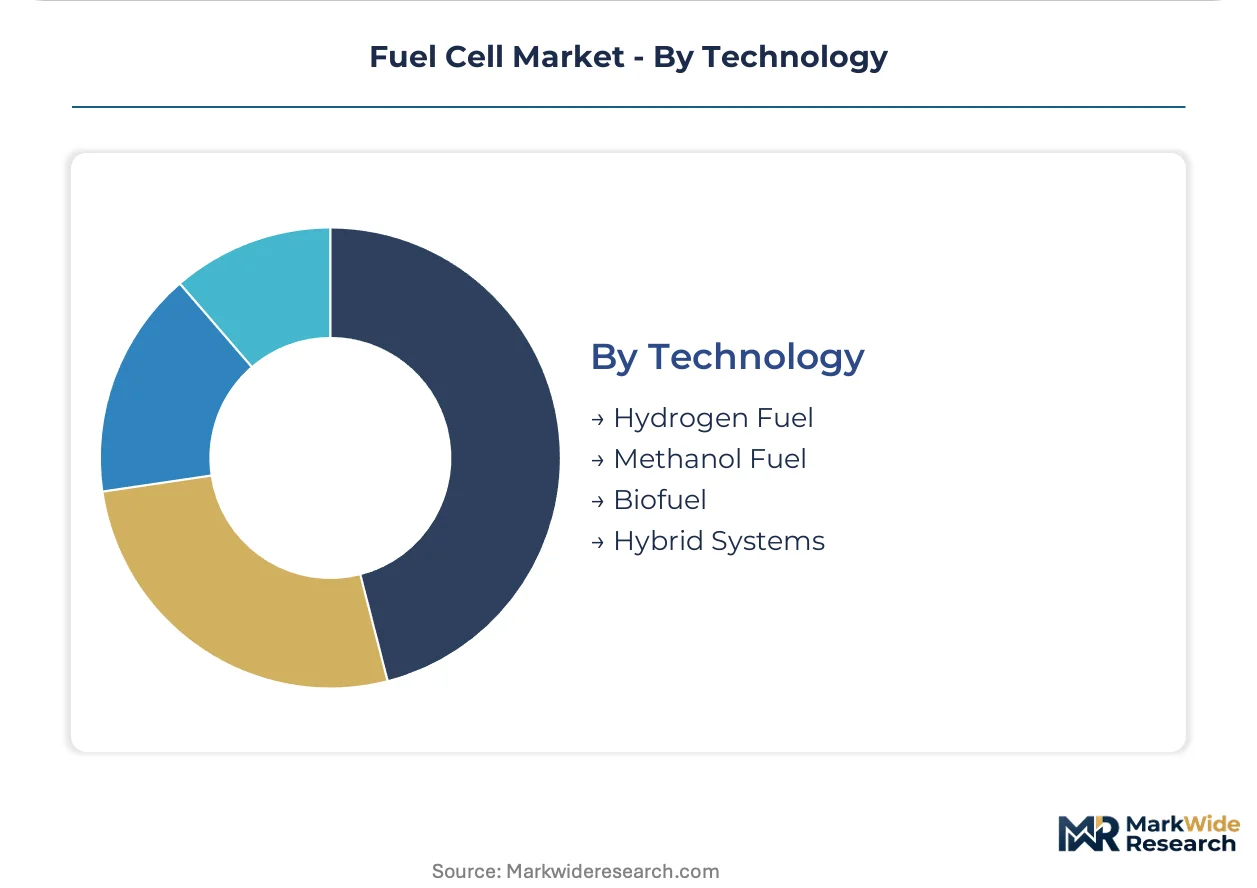
Technology:
Fuel flexibility requirements separate stationary industrial applications with reformate tolerance from mobility segments demanding high-purity hydrogen for rapid transient response.
- Hydrogen Fuel:High-purity gaseous or liquid hydrogen feeds proton exchange membrane and alkaline systems with rapid load-following capability, dominating transportation and portable power segments. US IRA production tax credits compress delivered hydrogen costs for California and Texas fleet operators.
- Methanol Fuel:Liquid fuel infrastructure compatibility supports direct methanol systems in remote stationary applications and portable electronics where hydrogen distribution remains uneconomic.
- Biofuel:Renewable methane and biogas reforming enables carbon-negative power generation in agricultural and waste processing facilities with on-site feedstock availability.
- Hybrid Systems:Battery-fuel cell combinations optimize duty cycles with battery handling peak loads and fuel cells managing continuous baseload, emerging in rail and maritime propulsion architectures.
Hydrogen Fuel maintains absolute volume leadership, with Hybrid Systems expanding most quickly as maritime and rail operators seek optimized powertrain configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ulsan's industrial complex anchors hydrogen fuel cell manufacturing with dedicated supply chains feeding domestic vehicle production and export markets. National hydrogen roadmaps in Germany, Japan, and South Korea direct public procurement toward fuel cell buses, trains, and stationary power systems. Regulatory frameworks across these jurisdictions coordinate electrolyzer subsidies with fleet electrification mandates.
United States
California's Central Valley freight corridors concentrate heavy-duty trucking deployments as hydrogen hub infrastructure matures under IRA funding. The EPA coordinates zero-emission vehicle mandates with Department of Energy hydrogen production tax credits. Texas renewable energy clusters pair electrolyzer-fuel cell combinations with solar and wind curtailment for dispatchable power.
Germany
The Ruhr industrial cluster anchors grid-scale stationary installations with exhaust heat recovery for district heating integration. EU F-Gas Regulation phase-down schedules force membrane reformulation while Green Deal renewable hydrogen targets mandate 10 million tons domestic production by 2030. Public procurement mandates for fuel cell buses and regional trains create guaranteed offtake volumes.
Japan
METI hydrogen and fuel cell technology roadmaps direct public-private investment toward residential cogeneration and industrial decarbonization. The Ulsan complex across the Korea Strait supplies stack components while domestic manufacturing serves passenger vehicle and stationary power segments. Retail infrastructure investment concentrates in Tokyo and Osaka metropolitan corridors.
South Korea
Ulsan's dedicated hydrogen supply anchors domestic fuel cell vehicle manufacturing with export-oriented stack production. National hydrogen roadmaps mirror Japan's METI frameworks with coordinated electrolyzer deployment and fueling infrastructure buildout. Busan-Ulsan industrial belt concentrates membrane electrode assembly and system integration capacity.
Netherlands
Port of Rotterdam operations integrate electrolyzer-fuel cell systems for maritime auxiliary power and industrial cluster decarbonization. EU Green Deal mandates drive hydrogen import terminal development linking North Sea offshore wind to stack manufacturing feedstock. Eindhoven's technology corridor hosts solid oxide system development for data center backup applications.
Fuel Cell Market Vendor Landscape
Global majors compete with regional champions across membrane electrode assembly production and captive hydrogen supply integration. The vendor base stratifies between integrated hydrogen-fuel cell service providers, specialized stack manufacturers, and steel-supported solid oxide technology developers. Three archetypes dominate: electrolyzer-fuel cell integrators bundling infrastructure with stack maintenance; pure-play membrane electrode assembly suppliers serving heavy-duty transportation; and materials specialists advancing catalyst layer engineering. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with manufacturing scale and hydrogen offtake contract structures determining positioning.
Within the integrated service tier, Plug Power Inc. and Ballard Power Systems exemplify divergent geographic anchoring with North American and European manufacturing footprints respectively. Ceres Power Holdings PLC occupies a position in the steel-supported solid oxide specialization segment. These three entities represent the archetype spectrum without implying specific strategic actions or market shares beyond their visible positioning in industry documentation.
| Leading Market Players |
|---|
| Plug Power Inc. |
| Ballard Power Systems |
| Bloom Energy |
| FuelCell Energy Inc. |
| SFC Energy AG |
| AISIN Corporation |
| Doosan Fuel Cell |
| Ceres Power Holdings PLC |
| Hydrogenics Corporation |
| Others |
Supply Flow & Price Mechanics
Anion exchange membrane commercialization is compressing stack economics while redrawing supplier maps away from platinum-dependent catalyst networks toward nickel-cobalt deposition specialists. This technology transition simultaneously collapses precious metal cost exposure and fragments membrane electrode assembly supplier concentration across new qualification pathways.
Pricing Analysis
Input-cost pass-through from platinum group metals dominates proton exchange membrane stack pricing, with South African mining concentration amplifying volatility into catalyst layer quotations. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-grade durability specifications from material handling fleet contracts and stationary power installations. Pricing pressure stems from alkaline system competition in cost-sensitive backup power segments. Material handling fleet operators exhibit highest price sensitivity due to total cost of ownership comparisons against battery-electric alternatives, while data center operators accept premium tier pricing for 99.999% availability guarantees.
Supply Chain Analysis
NFPA 2 and SAE J2601 certification gating constrains membrane electrode assembly supplier qualification to Ballard Power Systems and Plug Power facilities in Canada and the United States, with Ceres Power Holdings PLC anchoring steel-supported solid oxide capacity in the United Kingdom. Platinum catalysts draw from South African and Russian mining operations, while perfluorinated membrane materials rest on Chemours and Solvay production in the United States and Belgium. Single-source vulnerability concentrates in precision coating equipment for catalyst deposition. Distribution runs through integrated hydrogen service contracts bundling stack maintenance with electrolyzer output rather than discrete component sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on platinum loading reduction trajectories outpacing manufacturing scale economies, with premium-tier solid oxide systems capturing data center backup power value pools.
For Market Incumbents: Deploy captive green hydrogen supply integration to lock in fleet operator total cost of ownership advantages against emerging alkaline system competitors. Ballard Power Systems and Plug Power should accelerate membrane electrode assembly technician training pipelines to relieve second-source supplier bottlenecks. Steel-supported solid oxide specialists must defend position by securing data center operator performance guarantees before ceramic design incumbents reformulate for faster thermal cycling. For New Entrants and Emerging Players: Anion exchange membrane technology without platinum group metals offers the most penetrable wedge into material handling forklift replacement contracts at Amazon and Walmart distribution centers. Maritime auxiliary power units under International Maritime Organization emission targets present white-space demand with less entrenched incumbent relationships. Target port operators in California and Texas with electrolyzer-fuel cell bundled service models mirroring Central Valley trucking procurement patterns. For Investors and Strategic Acquirers: Valuations sit cheapest among alkaline system manufacturers serving cost-sensitive stationary power, where technology stigma from lower power density obscures margin recovery potential. Long-term viability framing centers on electrolyzer-fuel cell integration capability across industrial clusters in the Netherlands and Spain. Watch green hydrogen offtake contract pricing as the inflection signal—contract structures compressing delivered hydrogen costs below diesel parity trigger accelerated fleet procurement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Platinum Loading Reduction Program | Advanced catalyst layer engineering at Ballard Power Systems cuts precious metal content without sacrificing membrane electrode assembly durability specifications. |
| Steel-Supported Solid Oxide Scale-Up | Ceres Power Holdings PLC's lower-temperature ceramic designs enable faster thermal cycling for data center backup power modular packaging. |
| Integrated Hydrogen Service Contracts | Plug Power Inc. bundles electrolyzer output, compression, and dispensing with stack maintenance for California Central Valley freight operators. |
| Anion Exchange Membrane Qualification | Eliminating platinum group metals entirely rewrites cost structures for Amazon and Walmart material handling fleet forklift replacements. |
| Maritime Auxiliary Power Unit Deployment | International Maritime Organization emission targets for port operations create demand for solid oxide fuel cells in container ship cold-ironing applications. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fuel cell stack manufacturing executives, hydrogen procurement leads at heavy-duty trucking fleets, electrolyzer project developers, and membrane electrode assembly technicians with secondary validation. SEC 10-K filings from Ballard Power Systems and Plug Power Inc., Department of Energy hydrogen hub funding disclosures, EU F-Gas Regulation implementation guidance, and METI hydrogen roadmap progress reports anchored supply-side and demand-side sizing. Bottom-up electrolyzer capacity build-up and top-down fleet electrification mandate trajectories were triangulated against manufacturer order backlogs.
Comparable-period anchoring tied projection assumptions to historical deployment rates across California hydrogen hub infrastructure buildout and German public procurement mandate fulfillment curves. Segmentation modeling tracked proton exchange membrane, solid oxide, alkaline, and direct methanol architectures by automotive, industrial, stationary power, and transportation end uses, with hydrogen purity and fuel flexibility specifications as cross-cutting dimensions. CAGRs were derived from electrolyzer cost curve assumptions and green hydrogen offtake contract pricing trends rather than simple extrapolation.
The model holds under sustained IRA hydrogen production tax credit authorization and EU Green Deal renewable hydrogen target enforcement; deviation in South African platinum export restrictions or electrolyzer capital cost inflation would shift stack manufacturing economics. Forecasts reflect documented assumptions about membrane electrode assembly technician availability and hydrogen fueling station certification timelines. A model refresh is warranted upon material change in green hydrogen delivered cost trajectories or International Maritime Organization emission target acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuel Cell Technology
PEM Electrolyzer Market
Fuel Cell Technology
Hydrogen Fuel Cell Stack and Membrane Recycling for EU Mobility Market
Fuel Cell Technology
Fuel Cells for CHP Application Market
Fuel Cell Technology
Helium Recovery Systems Market
Fuel Cell Technology
Solid Oxide Fuel Cell Market
Fuel Cell Technology
North America Fuel Cell Market
Fuel Cell Technology
Europe Direct Methanol Fuel Cell Market
Fuel Cell Technology
Fuel Cell for Stationary Power Market
Fuel Cell Technology
North America Fuel Cell Technology Market
Fuel Cell Technology
Fuel Cells for Marine Vessels Market
Fuel Cell Technology
France Fuel Cell Market
Fuel Cell Technology
Portable Fuel Cells Market
Fuel Cell Technology
China Fuel Cell Market
Fuel Cell Technology
Bipolar Plate Coatings Market
Fuel Cell Technology
Aircraft Fuel Cell Market
Fuel Cell Technology
Proton Exchange Membrane Fuel Cell (PEMFC) Market