
 North America Fuel Cell Technology Market | 2026-2036
North America Fuel Cell Technology Market Size, Share, and Industry Trends Forecast 2026-2036
North America Fuel Cell Technology Market Analytics
The direct sales channel between stack manufacturers and fleet operators is narrowing as long-term service contracts replace transactional equipment purchases. Ballard Power Systems leverages its proton exchange membrane specialization to secure multi-year supply agreements with transit agencies. Plug Power anchors its position through backward integration into green hydrogen production and refueling infrastructure. Bloom Energy Corporation differentiates via solid oxide fuel cell systems designed for stationary industrial power generation.
Fuel cell technology converts chemical energy from hydrogen or hydrocarbon fuels into electrical power through electrochemical reactions, typically operating at efficiencies of 40-60% for proton exchange membrane systems and up to 85% for solid oxide configurations when waste heat is recovered. The primary commercial purpose is delivering reliable, low-emission baseload power for applications where grid dependency or battery weight creates operational constraints. Proton exchange membrane systems lead transportation deployments due to rapid cold-start capability and power density advantages, while solid oxide technology captures margin pools in stationary industrial settings where high operating temperatures enable combined heat and power configurations. The stationary deployment segment sustains the largest revenue base through utility-scale and on-site industrial installations, though mobile applications are expanding fastest as heavy-duty trucking electrification accelerates.
The US Environmental Protection Agency and Department of Energy shape product standards through emissions certification and hydrogen fuel quality specifications, while Canada's Clean Fuel Regulations mandate declining carbon intensity thresholds that expand addressable demand for fuel cell systems. State-level zero-emission vehicle mandates in California and New York further segment market access requirements, creating compliance-driven procurement cycles. Stakeholders must monitor hydrogen infrastructure buildout timelines and regional tax credit implementation to align manufacturing capacity with demand geography.
Market Dynamics
The US Inflation Reduction Act's hydrogen production tax credits are compressing electrolyzer capital costs and rewiring procurement economics for fleet operators across California's freight corridors.
Growth Catalysts
- Zero-Emission Vehicle Mandates:California's Advanced Clean Trucks regulation mandates escalating zero-emission truck sales percentages, forcing heavy-duty fleet operators into fuel cell procurement decisions ahead of battery-electric alternatives.
- Hydrogen Hub Infrastructure:The US Department of Energy's Regional Clean Hydrogen Hubs program is anchoring production capacity in the Central Valley, creating captive supply for long-haul trucking corridors.
- Proton Exchange Membrane Advances:Stack power density improvements are extending vehicle range without weight penalties, enabling fuel cell systems to penetrate weight-sensitive Class 8 trucking applications.
Market Restraints
- Platinum Group Metal Dependency:Proton exchange membrane catalyst layers require iridium and platinum inputs concentrated in South African and Russian supply chains, exposing stack manufacturers to geopolitical price volatility.
- Hydrogen Delivery Cost Structure:Compressed gas tube trailer logistics impose delivered hydrogen costs that erode total cost of ownership advantages versus diesel in corridors lacking pipeline or liquid hydrogen infrastructure.
- Stationary Solid Oxide Efficiency Limits:High-temperature thermal cycling degradation constrains system lifetime in industrial combined heat and power applications, limiting warranty terms and financing options.
Strategic Opportunities
- Canadian Clean Fuel Regulations:Declining carbon intensity thresholds for liquid and gaseous fuels create compliance-driven demand in Alberta's oil sands operations and British Columbia's port logistics.
- Data Center Backup Power:Solid oxide fuel cell systems are penetrating hyperscale facility deployments in Texas and Arizona where grid reliability constraints and emissions commitments intersect.
- Electrolyzer-Fuel Cell Integration:On-site hydrogen production paired with stationary power generation is opening behind-the-meter applications for industrial parks in the US Midwest.
Industry Challenges
- Electrochemical Engineer Talent Scarcity:Stack manufacturing scale-up is constrained by limited pipeline of specialists in membrane electrode assembly fabrication and system thermal management.
- EPA Certification Timelines:Heavy-duty engine emissions certification cycles for new fuel cell powertrain configurations extend 18-24 months, delaying commercial deployment schedules.
- Legacy Fleet Integration Complexity:Retrofit compatibility with existing vehicle platforms requires custom power electronics and cooling system redesigns that fragment engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Fuel Cell Technology Market |
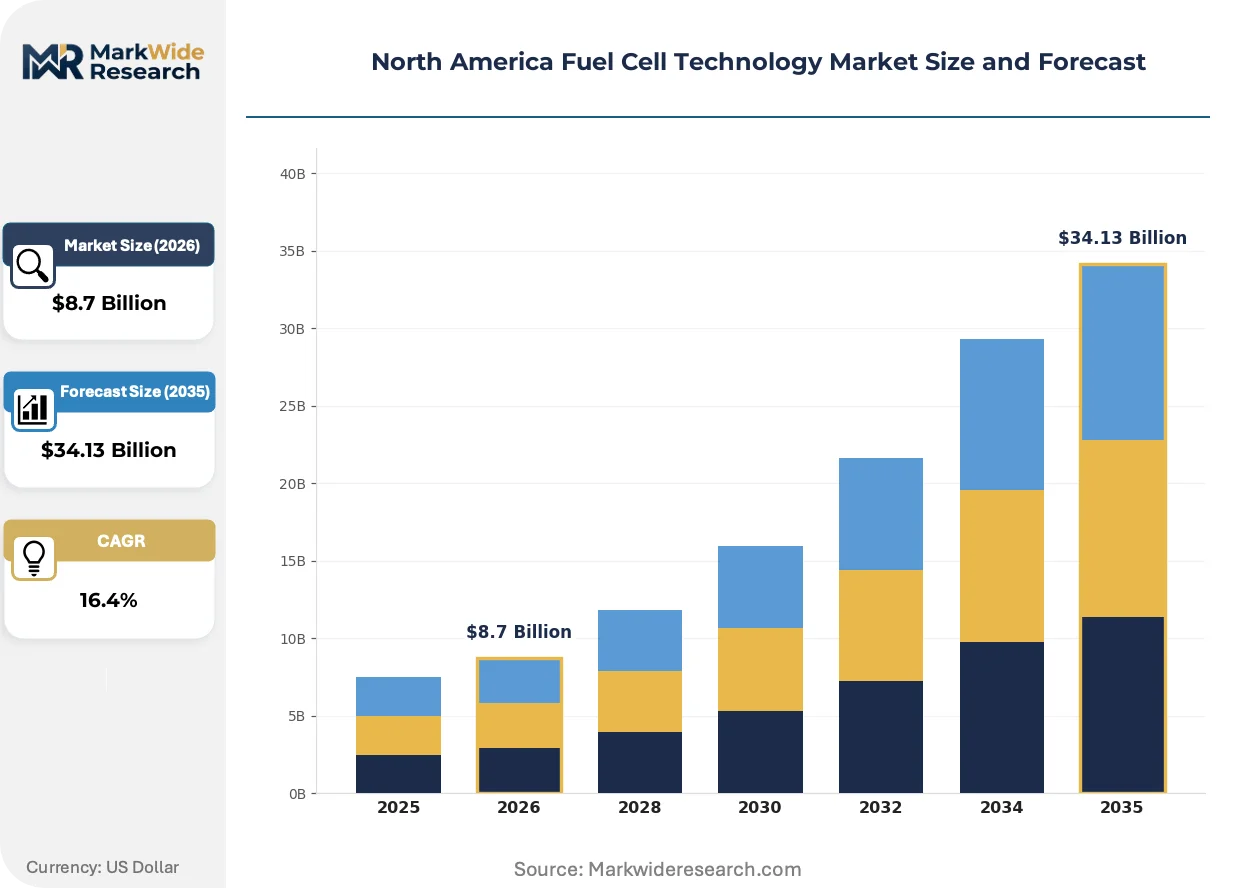
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proton Exchange Membrane, Solid Oxide, Phosphoric Acid, Molten Carbonate End User: Transportation, Industrial, Residential, Portable Deployment: On-site, Off-site, Mobile, Stationary Component: Fuel Processor, Power Controller, Air Separator, Stack |
| Companies Covered | FuelCell Energy, Nuvera Fuel Cells, Ballard Power Systems, SFC Energy, Doosan Fuel Cell America, Plug Power, Cummins, Hydrogenics Corporation, Bloom Energy Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Fuel Cell Technology Market Evolving Landscape
Technology migration, regulatory compression, and procurement model evolution are converging to restructure competitive positioning across the North American fuel cell value chain.
Solid oxide fuel cell technology is migrating from experimental industrial pilots to commercial baseload power installations. Data center operators in Nevada and Arizona are adopting 200-kilowatt modular systems for 24/7 operations. This technology shift is enabling fuel cell manufacturers to capture margin pools previously held by diesel generator sets and grid-tied battery systems.
The US Inflation Reduction Act's Section 45V hydrogen production tax credit is reshaping project finance structures for electrolyzer deployments. Developers are structuring power purchase agreements around renewable energy qualification requirements. The credit's implementation timeline is accelerating final investment decisions in Texas wind corridors and California solar zones.
Long-term hydrogen supply agreements are displacing spot market purchases for fleet operators. Transit agencies in California and New York are locking in 10-year fixed-price contracts with integrated infrastructure providers. This contracting pattern is most visible in municipal bus procurements where total cost of ownership certainty outweighs capital expenditure flexibility.
North America Fuel Cell Technology Market Segmentation
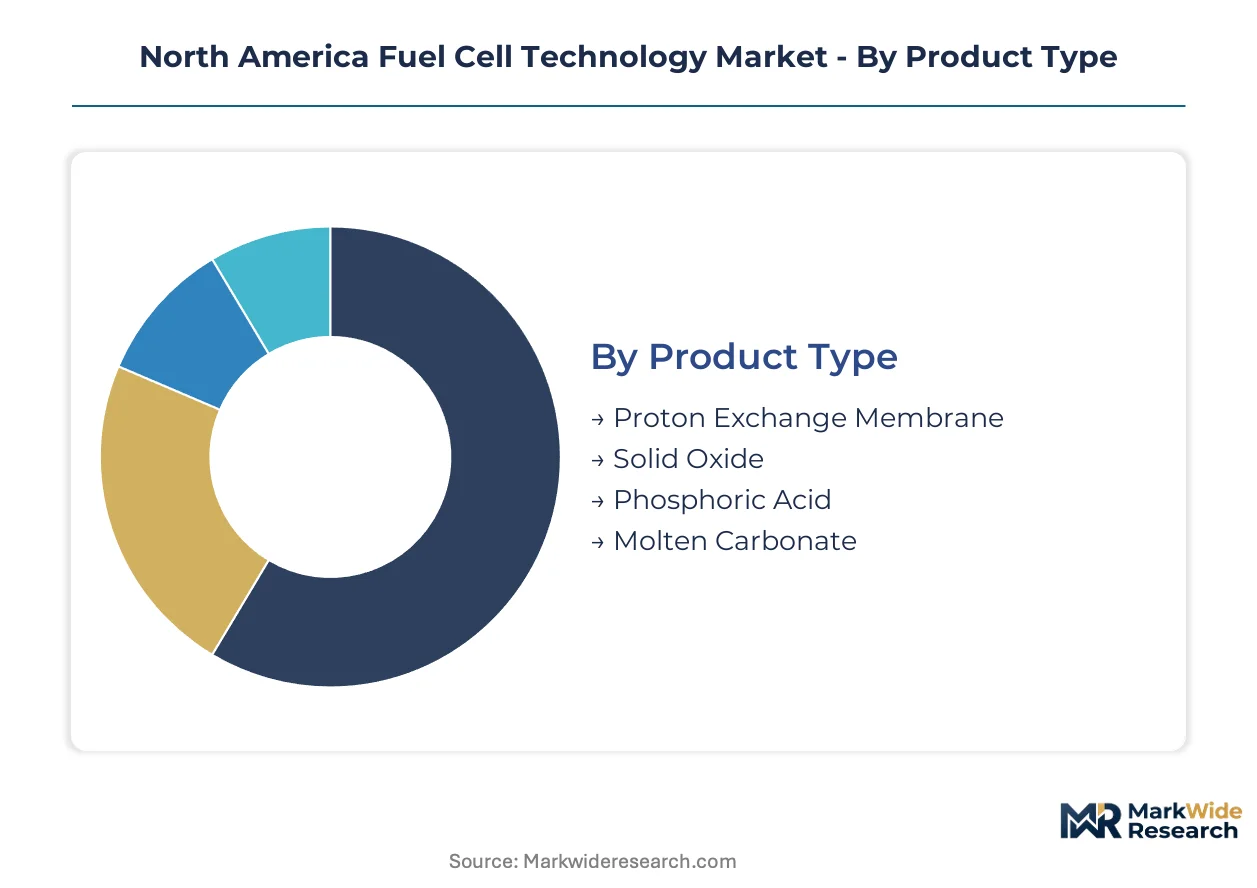
Segmentation in the North American fuel cell market exposes divergent capital cycles and margin structures across electrochemical technologies. Understanding these distinctions enables suppliers to align manufacturing capacity with procurement rhythms in heavy-duty trucking, industrial power, and emerging portable applications.
Product Type:
Cycle times vary dramatically: proton exchange membrane systems turn over every 5-7 years in fleet applications, while solid oxide installations operate on 15-20 year industrial depreciation schedules.
- Proton Exchange Membrane:Low-temperature electrochemical conversion using a polymer electrolyte membrane enables rapid cold-start performance below freezing. California's Central Valley freight corridors concentrate procurement as the Advanced Clean Trucks regulation forces fleet compliance decisions ahead of battery-electric alternatives.
- Solid Oxide:Ceramic electrolyte systems operating at 600-1000°C achieve up to 85% efficiency when waste heat is recovered for combined heat and power. Data center operators in Nevada and Arizona anchor demand where grid reliability constraints and emissions commitments intersect.
- Phosphoric Acid:Mature technology dominates stationary 200-kilowatt commercial installations with proven durability exceeding 40,000 operating hours.
- Molten Carbonate:High-temperature carbonate salt electrolytes suit large-scale distributed generation above one megawatt in industrial parks.
Proton exchange membrane anchors the volume base while solid oxide gains share at the steepest rate.
End User:
Cost tiers separate these segments: transportation demands volume manufacturing economies, while industrial buyers prioritize uptime guarantees and long-term service contracts.
- Transportation:Heavy-duty trucking fleets across California and Texas drive procurement as zero-emission mandates tighten and hydrogen hub infrastructure materializes.
- Industrial:Oil sands operations in Alberta and petrochemical facilities along the US Gulf Coast anchor stationary power demand under Canada's Clean Fuel Regulations.
- Residential:Combined heat and power systems penetrate net-zero building developments in British Columbia and New York state where utility rate structures reward on-site generation.
- Portable:Backup power for telecommunications and emergency response concentrates in remote Canadian territories and Alaska lacking grid connectivity.
Industrial installations capture the highest margin pools while transportation expands most quickly.
Deployment:
Geographic concentration patterns distinguish these modes: mobile systems track freight corridor development, while stationary assets cluster near hydrogen production hubs.
- On-site:Behind-the-meter industrial generation paired with captive electrolyzer production is penetrating Midwest manufacturing parks where grid interconnection queues extend years.
- Off-site:Utility-scale fuel cell parks in Connecticut and South Korea (export reference for technology validation) deliver baseload power under power purchase agreements.
- Mobile:Class 8 trucking and transit bus fleets in California and New York operate under 10-year hydrogen supply contracts with integrated infrastructure providers.
- Stationary:Data center backup installations in Texas and Arizona displace diesel generator sets where emissions commitments constrain fuel choices.
Stationary deployment sustains the revenue base while mobile applications climb the fastest.
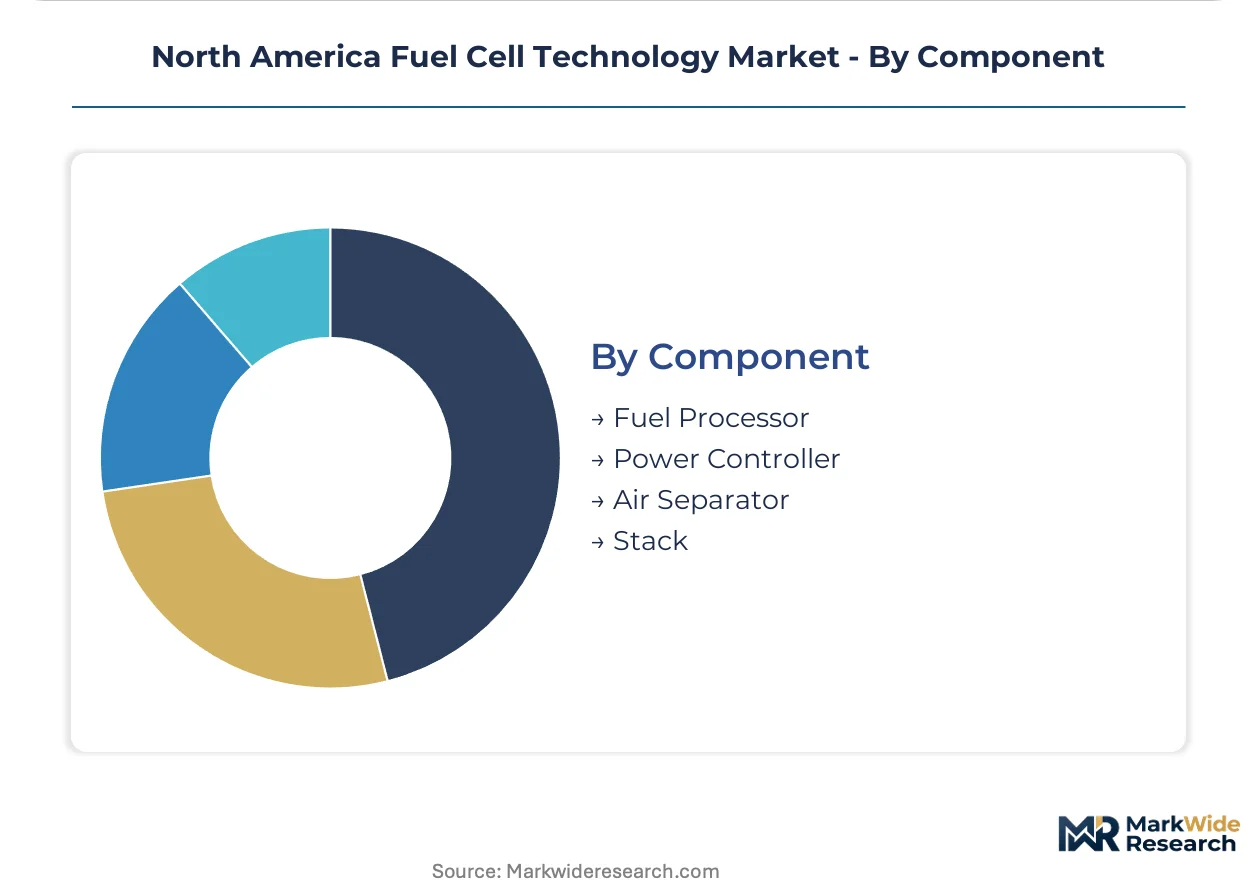
Component:
Supply concentration and manufacturing maturity separate these subsystems: stack production requires electrochemical engineering specialization, while power controllers leverage established power electronics supply chains.
- Stack:Membrane electrode assemblies with platinum group metal catalyst layers concentrate manufacturing in Massachusetts and British Columbia, constrained by iridium supply from South African and Russian sources.
- Fuel Processor:Reforming subsystems convert natural gas or methanol to hydrogen for stationary applications lacking direct hydrogen pipeline access.
- Power Controller:DC-AC inverters and grid synchronization electronics integrate fuel cell output with industrial electrical systems and utility interconnection standards.
- Air Separator:Compressor and humidification modules manage cathode oxygen supply, with thermal management critical for proton exchange membrane durability.
Stack components command the highest value share while power controllers scale fastest with manufacturing automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Inflation Reduction Act's hydrogen production tax credits are rewiring investment flows across North American fuel cell markets, compressing project timelines in established corridors while drawing capital into emerging production zones.
United States
California's Central Valley freight corridors anchor heavy-duty trucking deployment as the Advanced Clean Trucks regulation forces fleet compliance decisions. The EPA's emissions certification cycles shape product launch timelines for new powertrain configurations. Hydrogen hub infrastructure development concentrates in Texas wind corridors and California solar zones where developers structure power purchase agreements around renewable energy qualification requirements.
Canada
Alberta's oil sands operations and British Columbia's port logistics drive stationary power demand under Clean Fuel Regulations mandating declining carbon intensity thresholds. Environment and Climate Change Canada oversees carbon intensity compliance frameworks. Manufacturing clusters in Ontario and Quebec supply membrane electrode assemblies to North American stack producers constrained by platinum group metal supply chains.
Mexico
Baja California's maquiladora corridor and northern border states attract electrolyzer component manufacturing seeking USMCA tariff advantages. The country's national energy regulator shapes hydrogen infrastructure permitting timelines. Industrial parks in Nuevo León are evaluating behind-the-meter fuel cell installations where grid interconnection queues extend procurement cycles for conventional power.
North America Fuel Cell Technology Market Competitive Landscape
On the supply side, the industry is consolidating around integrated hydrogen-fuel cell platforms rather than standalone equipment sales. Stack manufacturers and electrolyzer developers are merging capability sets through strategic partnerships and captive supply arrangements. Two archetypes dominate: proton exchange membrane specialists targeting transportation applications and solid oxide developers capturing industrial combined heat and power margin pools. Competitive intensity centers on backward integration into green hydrogen production and long-term service contract structures displacing transactional procurement.
Among North American developers, Ballard Power Systems, Plug Power, and Bloom Energy Corporation exemplify divergent strategic positioning. Ballard anchors the transportation-focused tier through membrane electrode assembly specialization and transit agency relationships. Plug Power occupies the integrated infrastructure position combining electrolyzer manufacturing with hydrogen distribution networks. Bloom Energy Corporation represents the stationary power archetype targeting data center and industrial baseload applications where waste heat recovery drives efficiency advantages.
| Leading Market Players |
|---|
| FuelCell Energy |
| Nuvera Fuel Cells |
| Ballard Power Systems |
| SFC Energy |
| Doosan Fuel Cell America |
| Plug Power |
| Cummins |
| Hydrogenics Corporation |
| Bloom Energy Corporation |
| Others |
Value Network & Pricing Analysis
South African and Russian platinum group metal deposits concentrate catalyst layer supply for proton exchange membrane stacks, anchoring margin capture with membrane electrode assembly fabricators in Massachusetts and British Columbia while compressing pricing flexibility for downstream stack integrators.
Pricing Analysis
Volume-discount tiering structures separate municipal transit agencies locking in decade-long hydrogen supply contracts from spot-market fleet operators purchasing single-digit unit volumes. Pricing stratifies across performance tiers distinguished by membrane durability warranties and EPA certification status. Cost compression in the mid-tier intensifies as Ballard Power Systems and Plug Power expand manufacturing scale. Transit agencies exhibit the lowest price sensitivity due to total cost of ownership modeling under zero-emission mandates, while independent trucking operators face acute capital constraints.
Supply Chain Analysis
Extended payment terms from electrolyzer developers to membrane electrode assembly suppliers are lengthening working capital cycles across the value chain. Manufacturing concentrates in the United States, Canada, and South Korea for stack assembly, while iridium and platinum sourcing remains tethered to South African and Russian extraction. Single-source vulnerability in platinum group metal supply chains exposes stack producers to geopolitical price volatility. Distribution runs through integrated hydrogen infrastructure providers bundling equipment, fuel, and maintenance under long-term service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
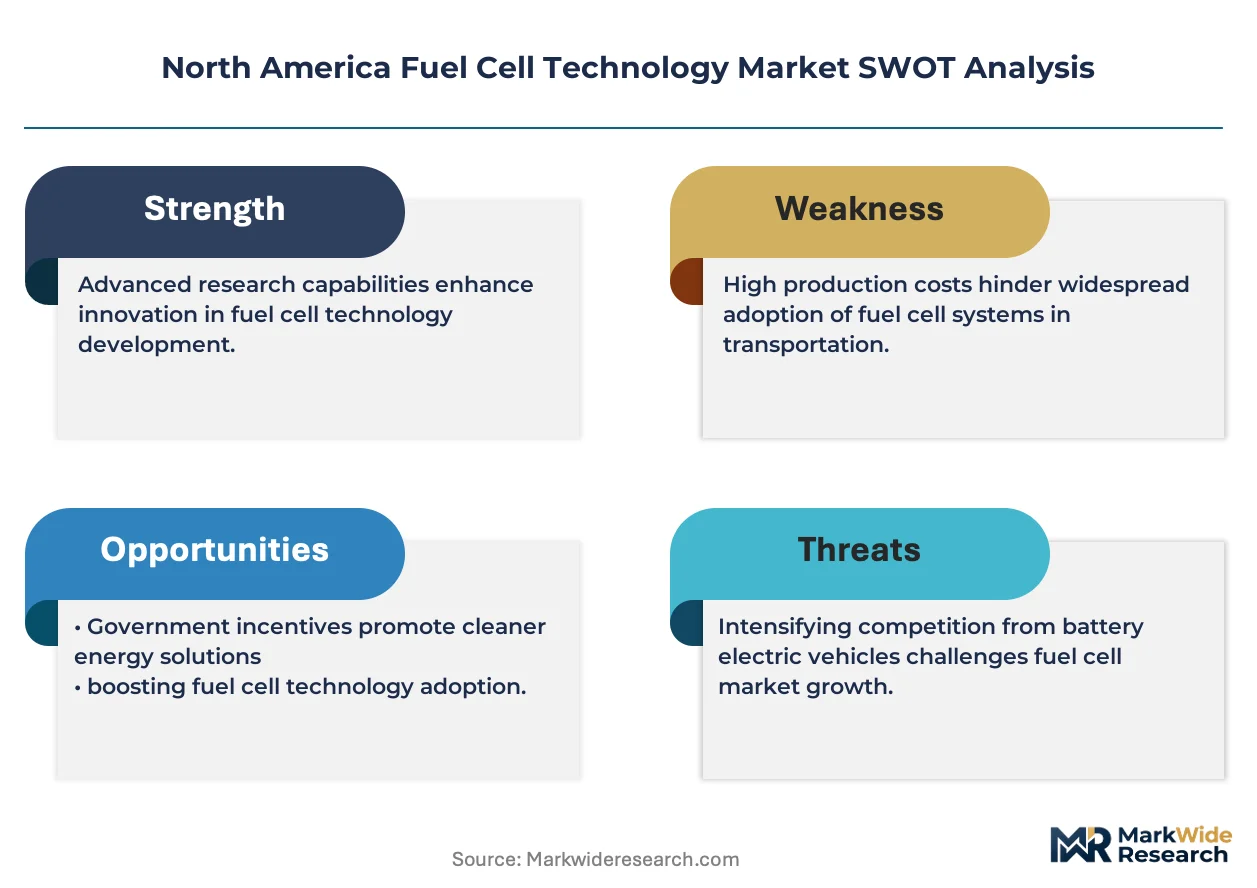
Fuel cell incumbents face substitution defense against battery-electric powertrains as zero-emission mandates mature and lithium-ion energy density improves, requiring strategic repositioning around applications where weight and refueling speed sustain competitive advantage.
For Market Incumbents: Harden membrane electrode assembly supply security through captive offtake agreements with South African platinum group metal refiners. Expand solid oxide manufacturing capacity in Nevada and Arizona to capture data center backup power margins before diesel generator incumbents electrify. Battery-electric range limitations in Class 8 trucking represent the critical defensive perimeter.
For New Entrants and Emerging Players: Alberta oil sands combined heat and power retrofits represent the most penetrable entry point under Canada's Clean Fuel Regulations carbon intensity compliance deadlines. Behind-the-meter industrial installations in Midwest manufacturing parks with grid interconnection queue delays offer second-mover positioning. Partner with captive electrolyzer developers to bundle hydrogen production with stationary power generation.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated hydrogen-fuel cell platforms combining electrolyzer manufacturing with long-term hydrogen supply contracting. Five-to-ten year viability hinges on IRA Section 45V credit extension and hydrogen hub infrastructure completion timelines. Monitor EPA heavy-duty engine certification cycle durations as the critical inflection signal for commercial deployment velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Green Hydrogen Production | Captures IRA tax credits while securing captive fuel supply for fleet customers under long-term contracts. |
| Membrane Electrode Assembly Capacity Expansion | Reduces platinum group metal exposure through scale economies and recycling process development. |
| Solid Oxide Data Center Deployment Partnership | Penetrates Nevada and Arizona hyperscale facilities where grid reliability constraints intersect emissions commitments. |
| Regional Clean Hydrogen Hub Consortium Participation | Locks in Central Valley freight corridor infrastructure access ahead of competitor positioning. |
| EPA Certification Pre-Submission Investment | Compresses 18-24 month heavy-duty powertrain approval timelines to accelerate commercial fleet deliveries. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with fuel cell system engineers, fleet procurement managers, electrolyzer project developers, and EPA certification specialists; and secondary validation through DOE hydrogen hub announcements, EPA emissions certification filings, FERC interconnection queue data, and SEC disclosures from publicly traded stack manufacturers. Bottom-up unit economics modeling triangulated against top-down market sizing across technology segments.
Forecast inputs span proton exchange membrane and solid oxide technology trajectories, transportation versus stationary end-use deployment rates, and regional hydrogen infrastructure buildout timelines across the projection horizon. Segmentation dimensions include electrochemical technology type, deployment mode, end-user industry, and component subsystem. CAGRs derive from installed capacity build rates, fleet turnover cycles, and regulatory compliance deadline clustering.
Macroeconomic conditions sit as an overlay; deviation in renewable energy capital costs, platinum group metal spot prices, or IRA credit implementation would shift the trajectory. Forecasts reflect documented assumptions about hydrogen delivery cost compression and electrolyzer manufacturing scale curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuel Cell Technology
Phosphoric Acid Fuel Cell Market
Fuel Cell Technology
France Fuel Cell Market
Fuel Cell Technology
Fuel Cell Technology Market
Fuel Cell Technology
Fuel Cell Interconnectors Market
Fuel Cell Technology
Fuel Vending Machines Market
Fuel Cell Technology
Hydrogen Fuel Cells Market
Fuel Cell Technology
Fuel Cell for Data Center Market
Fuel Cell Technology
Hydrogen Fuel Cell Vehicle Market
Fuel Cell Technology
Asia-Pacific Fuel Cell Market
Fuel Cell Technology
Global Micro Fuel Cells Market
Fuel Cell Technology
Asia-Pacific Direct Methanol Fuel Cell Market
Fuel Cell Technology
Direct Methanol Fuel Cell Market
Fuel Cell Technology
Solid Oxide Fuel Cell Market
Fuel Cell Technology
Hydrogen Fuel Cell Stack Durability and Performance Test Equipment Market
Fuel Cell Technology
Residential Fuel Cell Market
Fuel Cell Technology
Japan Fuel Cell Market