
 Membrane Electrode Assembly Market | 2026-2036
Membrane Electrode Assembly Market Size, Share, and Industry Trends Forecast 2026-2036
Membrane Electrode Assembly Market Intelligence
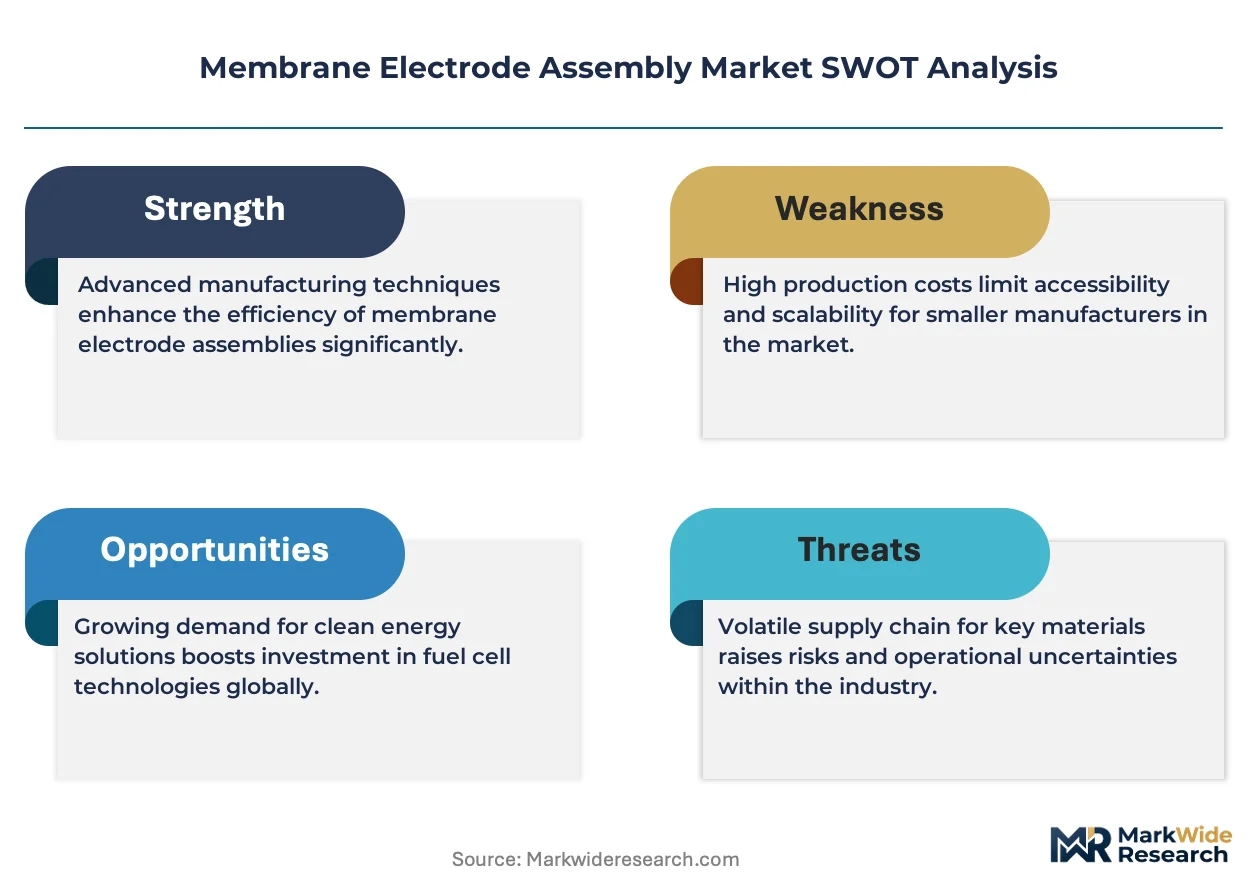
The modularization of membrane electrode assemblies into pre-qualified, integrated units is realigning procurement patterns for fuel cell and electrolyzer manufacturers. This shift favors suppliers with extensive system-level expertise. Johnson Matthey leverages its deep catalyst and PGM knowledge to offer high-performance solutions. Ballard Power Systems competes on the basis of its long-standing fuel cell stack integration experience and established supply chains.
A Membrane Electrode Assembly is the core component of a fuel cell, comprising a proton-exchange membrane situated between two catalyst-coated electrodes. Its primary function is to facilitate the electrochemical reaction, with performance often defined by catalyst loading in mg/cm². Fuel cells for transportation OEMs constitute the largest application segment. While Proton Exchange Membranes currently dominate, Anion Exchange Membranes are emerging as a key growth area due to their potential to lower system costs.
Regulatory frameworks such as the US EPA's emissions standards and China's GB standards for fuel cell vehicles create direct demand for zero-emission powertrain technologies. Directives like the EU's Renewable Energy Directive establish market access and subsidy mechanisms for electrolyzer deployments. Key decisions for manufacturers now center on securing supply chains for critical raw materials like platinum and ionomers to manage cost and scale production.
Market Dynamics
The primary force defining the market is the industrialization of MEA manufacturing. This shift is driven by automotive OEM demands for cost-effective, high-volume production to support the deployment of fuel cell vehicles at scale, moving beyond bespoke, low-volume fabrication.
Growth Catalysts
- EU Green Deal:The European Union's renewable energy directives and hydrogen strategy create direct incentives for electrolyzer projects, boosting demand for high-performance MEAs for green hydrogen production.
- Heavy-Duty Mobility:Adoption in fuel cell electric trucks and buses, particularly within automotive clusters in Germany and the United States, provides a large-scale, predictable demand stream for MEA manufacturers.
- Chinese Policy:China's dual carbon goals, reinforced by national GB standards for fuel cell vehicles, mandate a transition to zero-emission powertrains and stimulate domestic MEA consumption.
Market Restraints
- PGM Cost Volatility:The market's dependence on platinum group metals for catalysts exposes manufacturers and end-users to significant price fluctuations and supply chain risks tied to mining in specific geographies.
- Ionomer Supply Bottlenecks:The supply of high-performance perfluorosulfonic acid (PFSA) ionomers is concentrated among a few specialized chemical companies, creating potential production constraints and pricing power.
- Durability and Degradation:Limited operational lifetime and performance degradation under real-world conditions remain a technical hurdle, affecting the total cost of ownership for fuel cell and electrolyzer systems.
Strategic Opportunities
- Anion Exchange Membranes:The development of AEM technology presents an opportunity to eliminate costly platinum catalysts, potentially lowering system costs and opening new applications in cost-sensitive markets.
- Stationary and Maritime Power:Underpenetrated sectors like stationary power generation for data centers and maritime shipping represent significant future markets for MEAs as decarbonization pressures intensify in these industries.
- Emerging Hydrogen Economies:National strategies like India's National Green Hydrogen Mission are creating new, large-scale markets for electrolyzer components, offering geographic diversification for suppliers.
Industry Challenges
- Manufacturing Scale-Up:Transitioning from lab-scale or low-volume production to high-speed, automated roll-to-roll manufacturing requires significant capital investment and expertise in quality control to minimize defect rates.
- Standardization Gaps:The absence of universally accepted standards for MEA testing protocols and performance reporting complicates component comparison and procurement for global OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Membrane Electrode Assembly Market |
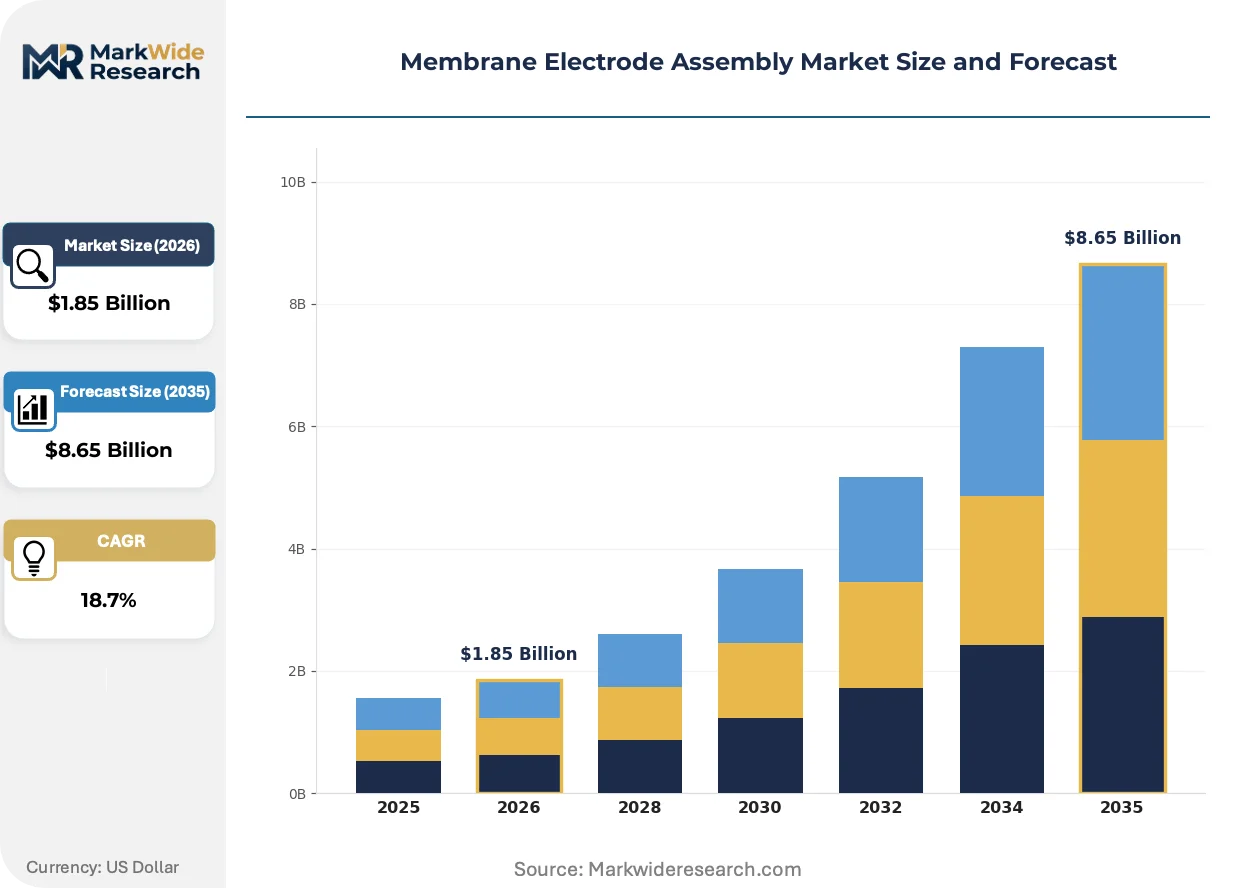
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $8.65 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proton Exchange Membrane, Anion Exchange Membrane, Composite Membrane, Hydrocarbon Membrane Technology: Polymer Electrolyte Membrane, Catalyst Coating, Gas Diffusion Layer, Membrane Reinforcement Application: Fuel Cells, Electrolyzers, Energy Storage Systems, Portable Power Devices End User: Transportation OEMs, Stationary Power Providers, Consumer Electronics, Industrial Equipment Manufacturers |
| Companies Covered | BASF SE, Plug Power Inc., Ballard Power Systems, FuelCellsEtc, Johnson Matthey, W. L. Gore & Associates, Giner Inc., Greenerity GmbH, Danish Power Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Membrane Electrode Assembly Market Strategic Shifts & Innovations
Industrialization is transforming the Membrane Electrode Assembly market from a component-centric business to a system-focused one. This evolution prioritizes modularity, performance validation, and supply chain reliability to meet the scaling demands of vehicle and electrolyzer manufacturers.
Advanced roll-to-roll processing applies catalyst inks directly onto the proton-exchange membrane, creating a unified catalyst-coated membrane. Fuel cell stack manufacturers are rapidly adopting this method to improve throughput. This high-volume technique is automating the core MEA fabrication process, reducing variability and lowering per-unit production costs.
The United States' Inflation Reduction Act (IRA) provides significant tax credits for domestic green hydrogen production. This policy directly incentivizes the construction of large-scale electrolyzer facilities within the US. Consequently, MEA suppliers are facing demand for products optimized for the specific operational parameters and durability requirements of utility-scale electrolysis.
A clear shift is occurring from sourcing individual layers to procuring fully integrated MEAs as pre-qualified units. This change simplifies the supply chain for OEMs, placing the burden of component integration and validation on the MEA supplier. This behavior is most prominent among transportation OEMs in Germany and Japan seeking to accelerate powertrain development cycles.
Membrane Electrode Assembly Market Segmentation
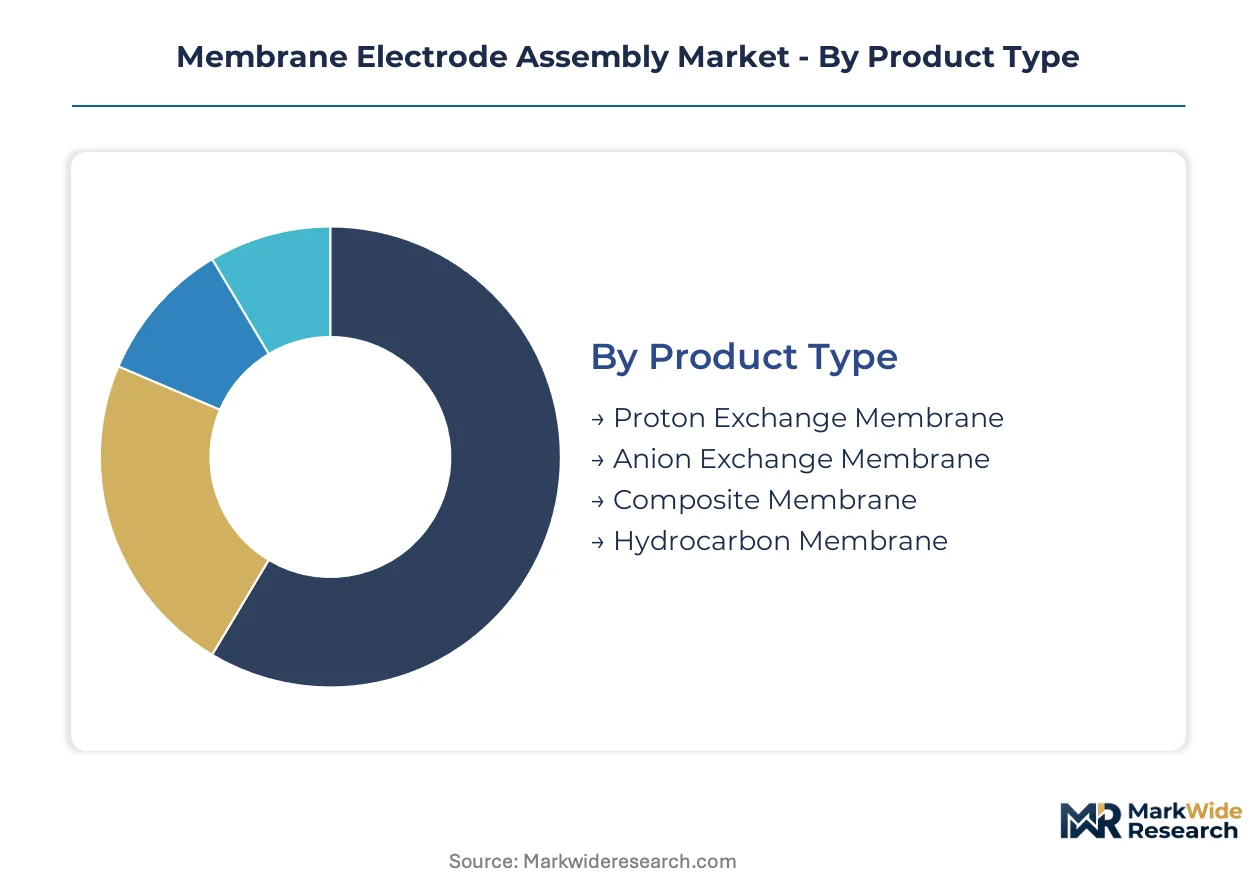
Membrane Electrode Assembly market segmentation provides a granular view of component variations, technological approaches, and end-use applications. This detailed breakdown helps manufacturers align product development with specific performance requirements and market demand across diverse fuel cell and electrolyzer systems. Understanding these segments is crucial for strategic investment and supply chain optimization.
Product Type:
Product type segmentation differentiates MEA core components based on their chemical composition and functional integration within the overall stack architecture.
- Proton Exchange Membrane:This type features a solid polymer electrolyte that conducts protons, separating reactant gases while blocking electron flow. Demand is high in automotive fuel cell applications, particularly for heavy-duty trucks, driven by established performance and durability standards.
- Anion Exchange Membrane:AEMs conduct hydroxide ions, offering the potential to use non-platinum group metal catalysts and operate in alkaline environments. This technology presents a significant opportunity to lower system costs, especially for emerging electrolyzer deployments.
- Composite Membrane:These membranes combine properties of different materials to enhance mechanical strength, chemical stability, or conductivity. Composite membranes are gaining traction in specialized applications requiring improved longevity.
- Hydrocarbon Membrane:Hydrocarbon-based membranes offer a lower-cost alternative to perfluorosulfonic acid membranes, addressing cost sensitivity in certain stationary power applications.
Volume placements concentrate in Proton Exchange Membrane; the faster expansion belongs to Anion Exchange Membrane.
Technology:
MEA technology components exhibit varying cost structures, influencing overall system economics and manufacturing complexity.
- Catalyst Coating:This involves applying platinum group metal (PGM) or non-PGM catalysts onto the membrane or gas diffusion layer to facilitate electrochemical reactions. High-volume automotive OEM demand for fuel cells drives innovation in low-PGM catalyst formulations.
- Polymer Electrolyte Membrane:The central component of the MEA, this selectively conducts ions while acting as a barrier for reactant gases. Advancements in membrane materials are critical for enhancing durability and efficiency in high-power electrolyzer systems.
- Gas Diffusion Layer:The GDL manages reactant gas supply, product water removal, and electrical current collection within the MEA structure. Optimization of GDL properties is essential for maximizing power density and operational stability in diverse fuel cell applications.
- Membrane Reinforcement:This technology integrates structural elements to improve the mechanical integrity and dimensional stability of the polymer electrolyte membrane. Reinforcement enhances MEA longevity under demanding operational cycles.
Catalyst Coating technology currently drives significant value; Gas Diffusion Layer is climbing the fastest due to performance optimization needs.
Application:
Application segments delineate where MEA demand aggregates, reflecting distinct volume requirements and performance specifications.
- Fuel Cells:MEAs are integral to fuel cell systems that convert chemical energy from hydrogen and oxygen into electricity. Transportation OEMs, especially for heavy-duty mobility in Germany and the United States, represent the largest market for these MEAs.
- Electrolyzers:These systems use MEAs to split water into hydrogen and oxygen through electrolysis, crucial for green hydrogen production. Policy incentives like the EU Green Deal and the US Inflation Reduction Act are accelerating demand for high-performance electrolyzer MEAs.
- Energy Storage Systems:MEAs are employed in certain redox flow batteries and other advanced electrochemical energy storage technologies. This segment requires MEAs optimized for long cycle life and high energy efficiency.
- Portable Power Devices:Small-scale fuel cells using MEAs provide compact and efficient power solutions for various portable electronic devices. This segment emphasizes miniaturization and rapid startup capabilities.
Fuel Cells represent the largest volume segment; Electrolyzers are on the steepest expansion trajectory.
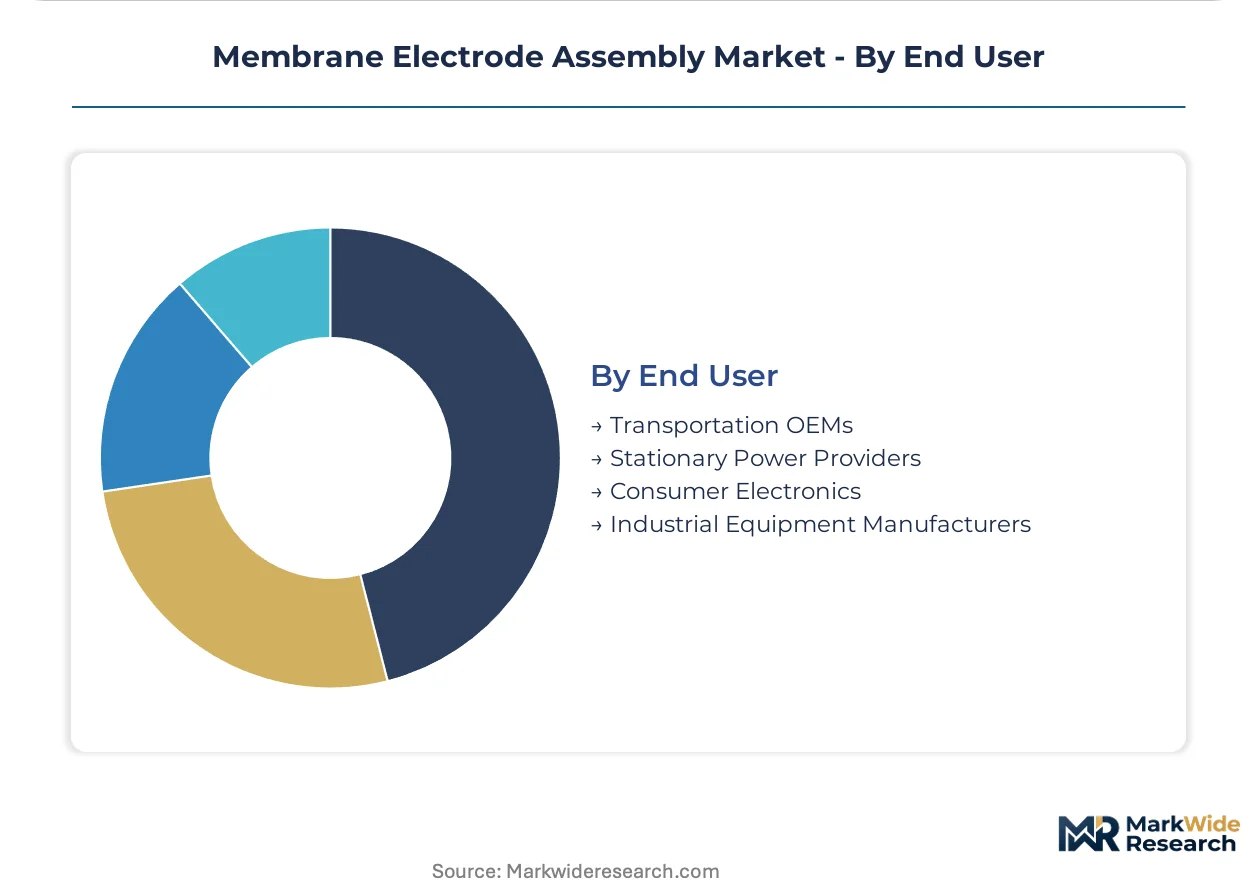
End User:
End-user categories define the primary customer base for MEA manufacturers, influencing product development and supply chain engagement.
- Transportation OEMs:These manufacturers integrate MEAs into fuel cell electric vehicles, including passenger cars, buses, and heavy-duty trucks. China's GB standards and EU emission regulations directly stimulate demand from this sector.
- Industrial Equipment Manufacturers:This segment includes producers of electrolyzers for hydrogen production and other industrial fuel cell systems. These manufacturers prioritize MEAs with high efficiency and robust durability for continuous operation.
- Stationary Power Providers:Companies deploying fuel cell systems for backup power, distributed generation, or grid support utilize MEAs. This sector values long operational lifetimes and consistent performance.
- Consumer Electronics:Manufacturers of portable electronic devices and small-scale power solutions are end-users for compact MEAs. This segment requires MEAs that offer high power density within a small footprint.
Transportation OEMs command the largest share; Industrial Equipment Manufacturers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Membrane Electrode Assembly market exhibits a complex regional dynamic, balancing localized production capabilities against global consumption patterns. Demand for MEAs is concentrating in key automotive and industrial clusters. Strategic investments in hydrogen infrastructure are reshaping regional market shares.
United States
Demand for MEAs in the United States stems from heavy-duty mobility and large-scale electrolyzer deployments. The Inflation Reduction Act (IRA) provides significant tax credits for domestic green hydrogen production, incentivizing electrolyzer facilities. Automotive clusters in Michigan and California are driving fuel cell vehicle integration and MEA adoption.
Germany
Germany's MEA demand is propelled by ambitious EU Green Deal targets for green hydrogen and fuel cell vehicle adoption. The EU's Renewable Energy Directive establishes market access and subsidy mechanisms for electrolyzer deployments. Industrial clusters in Bavaria and North Rhine-Westphalia focus on high-performance MEAs for both fuel cells and electrolyzers.
China
China's substantial MEA consumption is driven by its dual carbon goals and the rapid expansion of fuel cell electric vehicles. National GB standards for fuel cell vehicles mandate a transition to zero-emission powertrains. Major automotive manufacturing hubs like Shanghai and Guangdong are scaling up MEA integration into commercial vehicles.
Japan
Japanese demand for MEAs arises from its strategic focus on hydrogen-based energy systems and advanced automotive applications. METI initiatives support research and development in fuel cell technology and hydrogen infrastructure. Industrial centers around Tokyo and Nagoya are key sites for MEA innovation and fuel cell stack manufacturing.
India
India's emerging MEA market is spurred by the National Green Hydrogen Mission, aiming for large-scale green hydrogen production. The PLI scheme for automotive and advanced chemistry cell manufacturing indirectly supports fuel cell component development. New industrial corridors, particularly in Gujarat and Karnataka, are attracting investments in electrolyzer component production.
Membrane Electrode Assembly Market Key Industry Players
The competitive structure tilts toward specialized material science companies and established fuel cell system integrators, rather than broad generalists. The market exhibits a tiered structure, with a few large players dominating high-volume automotive and industrial segments. Key archetypes include PGM catalyst specialists, advanced membrane developers, and vertically integrated fuel cell stack manufacturers. Strategic partnerships to secure critical raw material supply chains and significant capital investments in manufacturing scale-up are dominant competitive moves.
Within the integrated stack manufacturer archetype, Ballard Power Systems exemplifies extensive fuel cell stack integration experience, anchoring its position through established supply chains for complete MEA units. Johnson Matthey leverages its deep catalyst and PGM knowledge, representing a strong material science foundation for high-performance MEA solutions, particularly concerning catalyst layers. Plug Power Inc. sits within the broader hydrogen solutions providers, representing companies that integrate MEA technology into comprehensive energy systems for various applications. These players collectively demonstrate the diverse approaches to securing market share in the evolving MEA landscape.
| Leading Market Players |
|---|
| BASF SE |
| Plug Power Inc. |
| Ballard Power Systems |
| FuelCellsEtc |
| Johnson Matthey |
| W. L. Gore & Associates |
| Giner Inc. |
| Greenerity GmbH |
| Danish Power Systems |
| Others |
Cost & Logistics Intelligence
Platinum Group Metal (PGM) price volatility directly influences Membrane Electrode Assembly (MEA) manufacturing costs, cascading into varied pricing tiers for end-users. This dynamic shapes procurement patterns for fuel cell and electrolyzer manufacturers.
Pricing Analysis
Cost-down pressure on transportation OEMs accelerates because of their demand for high-volume, cost-effective MEAs. The dominant pricing model involves contract-based long-term offtake agreements for integrated units. Price differentiation stems from performance validation and volume scale. Transportation OEMs exhibit the highest price sensitivity, while stationary power providers prioritize long operational lifetimes.
Supply Chain Analysis
US Inflation Reduction Act incentives for domestic green hydrogen production are reshaping MEA sourcing for electrolyzer facilities. The supply chain draws from PGM mining in specific geographies and highly concentrated perfluorosulfonic acid (PFSA) ionomer producers. Single-source vulnerability for ionomers presents a structural risk. Distribution runs through direct supply channels from MEA manufacturers to transportation OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Membrane Electrode Assembly market is poised for consolidation, as the significant capital investment required for manufacturing scale-up forces out smaller, less capitalized players. This shift prioritizes robust financial backing and established production capabilities.
For Market Incumbents:
Acquire advanced membrane developers to mitigate ionomer supply bottlenecks and gain expertise in Anion Exchange Membrane (AEM) technology. Deepen backward integration into catalyst material production to counter PGM cost volatility. Invest heavily in automated roll-to-roll manufacturing to meet high-volume OEM demands. This outcompetes smaller players on cost and scale.
For New Entrants and Emerging Players:
The price-point gap between high-performance PEM MEAs and cost-sensitive applications creates an entry point for Anion Exchange Membrane (AEM) technology. Target underpenetrated sectors like stationary power generation and maritime shipping with AEM-based solutions. Focus on emerging hydrogen economies such as India, leveraging its National Green Hydrogen Mission. Offer cost-effective, non-PGM catalyst MEAs as a primary go-to-market angle.
For Investors and Strategic Acquirers:
Distressed-cycle entries favor specialized material science companies in Europe and the United States, particularly those with strong intellectual property in Anion Exchange Membranes. The long-term viability of fuel cells and electrolyzers for decarbonization remains strong over the next decade. Target MEA manufacturers with proven high-volume manufacturing capabilities. Sustained policy support for hydrogen infrastructure, like the EU Green Deal, is a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Meets escalating high-volume demand from transportation OEMs in Germany. |
| Backward Integration into Ionomer Production | Secures critical raw material supply and mitigates pricing volatility for MEA manufacturers. |
| Joint Venture for AEM Development | Accelerates commercialization of cost-effective, non-platinum group metal MEA solutions. |
| Investment in Roll-to-Roll Manufacturing | Reduces per-unit production costs and improves quality consistency for fuel cell components. |
| Geographic Expansion into India | Capitalizes on the National Green Hydrogen Mission and new electrolyzer deployments. |
Research Approach
EU Green Deal documents, US Department of Energy reports, and China's GB standards formed the secondary backbone for this analysis. This was complemented by primary interviews with fuel cell R&D directors, automotive OEM procurement managers, electrolyzer system integrators, and hydrogen policy analysts. The data was rigorously triangulated using both bottom-up and top-down approaches to ensure accuracy.
A comprehensive bottom-up and top-down analytical framework guided the market forecast across the analysis window. Segmentation dimensions modeled included product type, technology, application, end user, and regional policy environment. Compound Annual Growth Rates were derived through regression analysis and market share shifts. Key inputs included hydrogen infrastructure buildout rates and automotive OEM production targets.
Underlying measurement precision varies by segment; established fuel cell applications carry tighter precision than emerging AEM technologies. Forecasts reflect assumptions regarding technological advancements and policy stability, though PGM price volatility and ionomer supply constraints are key risks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuel Cell Technology
High-Performance Fuel Cells Market
Fuel Cell Technology
PEM Electrolyzer Market
Fuel Cell Technology
Hydrogen Fuel Cell Stack and Membrane Recycling for EU Mobility Market
Fuel Cell Technology
North America Microbial Fuel Cell Market
Fuel Cell Technology
Aircraft Fuel Cell Market
Fuel Cell Technology
Direct Methanol Fuel Cell Market
Fuel Cell Technology
Asia-Pacific Direct Methanol Fuel Cell Market
Fuel Cell Technology
China Fuel Cell Market
Fuel Cell Technology
France Fuel Cell Market
Fuel Cell Technology
Fuel Cells for Marine Vessels Market
Fuel Cell Technology
Fuel Cell Technology Market
Fuel Cell Technology
Fuel Cells for CHP Application Market
Fuel Cell Technology
Bipolar Plate Coatings Market
Fuel Cell Technology
North America Fuel Cell Technology Market
Fuel Cell Technology
Hydrogen Recirculation Blower for Fuel Cell Market
Fuel Cell Technology
Global Fuel Cell Balance of Plant (BOP) Market