
 Lithium Battery Recycling Equipment Market | 2026-2036
Lithium Battery Recycling Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium Battery Recycling Equipment Market Insights
Skilled pyrometallurgical engineers is reorganizing competitive dynamics as facilities race to commission commercial-scale furnaces. Umicore leverages its integrated refining complex in Hoboken to anchor European cathode precursor output. Redwood Materials dominates North American feedstock aggregation through partnerships with automakers in Nevada and Tennessee. Li-Cycle Holding Corporation specializes in hub-and-spoke hydrometallurgical configurations that minimize transportation costs for black mass.
Lithium battery recycling equipment encompasses industrial machinery designed to dismantle, shred, separate, and chemically recover active materials from spent lithium-ion cells, with systems typically processing feedstock at temperatures between 200°C and 1,500°C depending on the recovery pathway. The primary purpose is to extract cobalt, lithium, nickel, and manganese at purity levels suitable for reintroduction into cathode manufacturing. Hydrometallurgical systems command the deepest margin pools due to their selective leaching precision and lower energy intensity relative to pyrometallurgical alternatives. Shredders and separators retain volume leadership as every recycling line requires front-end size reduction and ferrous-nonferrous separation regardless of downstream chemistry. Direct recycling, though nascent, attracts R&D capital because it preserves crystalline cathode structure and avoids full elemental decomposition.
The EPA oversees hazardous waste classification for spent batteries under RCRA, while the EU Battery Regulation mandates minimum recovery rates for lithium and cobalt by 2031, compelling equipment purchasers to specify compliance-ready configurations. China's MIIT enforces GB standards for recycled battery material quality, creating a dual-track market where export-facing recyclers adopt stricter specifications than domestic-only operators. Stakeholders must monitor how divergent regional purity standards fragment equipment design requirements and determine whether modular plant architectures can bridge regulatory gaps without full reconfiguration.
Market Dynamics
Equipment manufacturers face pressure from the EU Battery Regulation's recycled content mandates, which force recyclers to upgrade processing lines before 2031 deadlines. This regulatory compression is accelerating capital deployment toward closed-loop recovery infrastructure.
Growth Catalysts
- EU Battery Regulation:Mandatory lithium recovery thresholds compel recyclers across Germany, France, and Poland to install compliant shredding and separation systems ahead of enforcement deadlines.
- Automotive OEM captive programs:Electric vehicle manufacturers are internalizing recycling capacity to secure cathode material supply chains, directly funding equipment procurement for dedicated facilities.
- Hydrometallurgical precision:Selective leaching systems extract battery-grade lithium carbonate at higher purity than pyrometallurgical alternatives, attracting investment from precursor chemical producers.
Market Restraints
- Feedstock concentration risk:Black mass supply clusters in Nevada and Ontario create geographic dependency for North American equipment operators without diversified sourcing.
- Energy cost volatility:Pyrometallurgical furnaces consuming natural gas face margin compression when European energy prices spike, disadvantaging high-temperature recovery pathways.
- Technical limitation in direct recycling:Cathode structure preservation requires uniform cell chemistry inputs that current sorting infrastructure cannot reliably deliver at commercial scale.
Strategic Opportunities
- India's PLI scheme:Battery manufacturing incentives are spawning domestic recycling capacity needs, creating first-mover advantage for equipment vendors establishing local service networks.
- Direct recycling convergence:Integration of artificial intelligence-driven sorting with electrochemical regeneration processes promises to bypass full material decomposition.
- Service unbundling:Equipment vendors are separating hardware sales from continuous technical support contracts, opening recurring revenue streams in maintenance and process optimization.
Industry Challenges
- Pyrometallurgical engineer scarcity:Commercial furnace operation requires specialized expertise in high-temperature chemistry that vocational training programs have not scaled to meet.
- Certification timeline compression:CE marking and EPA hazardous waste permitting processes extend equipment commissioning by 12-18 months, delaying revenue recognition for plant operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium Battery Recycling Equipment Market |
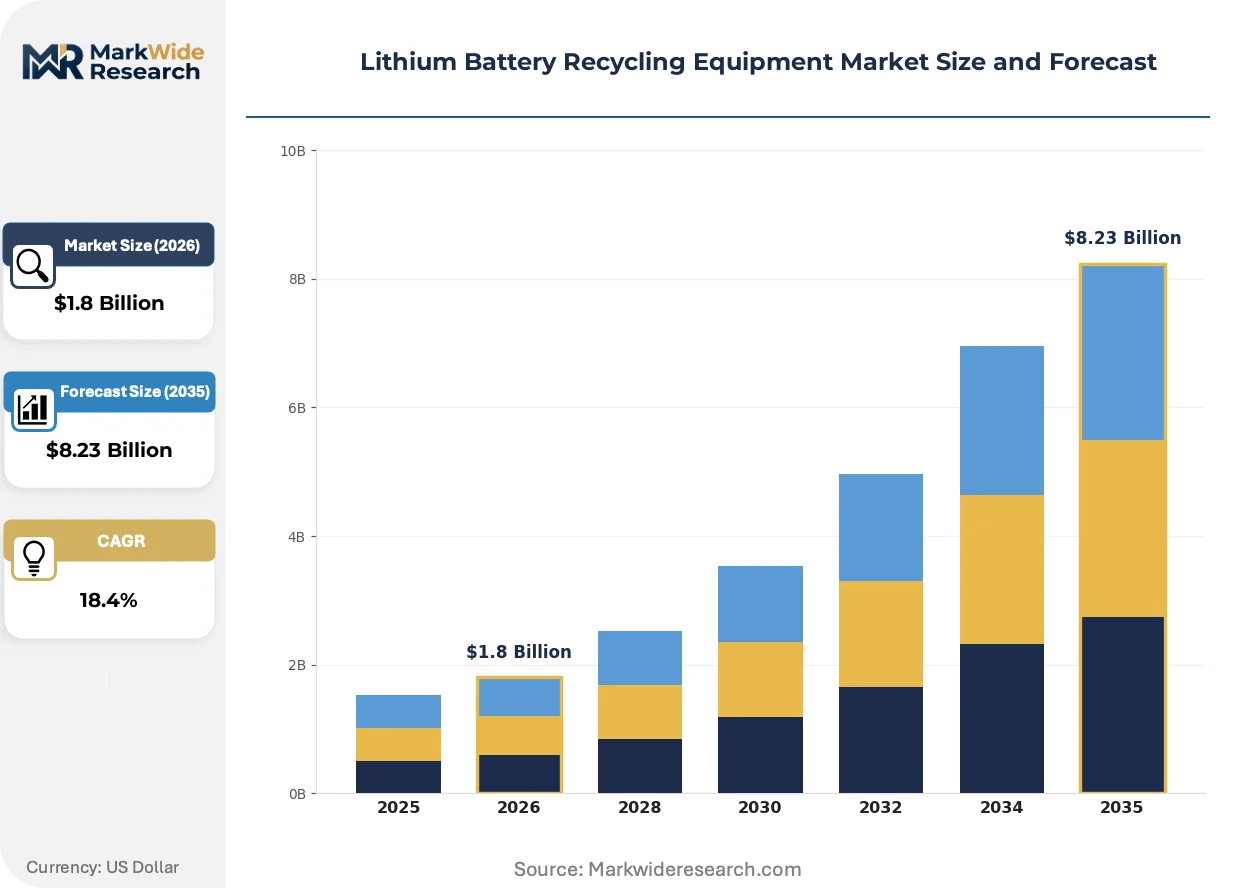
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.23 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shredders, Separators, Conveyors, Hydrometallurgical Systems Technology: Physical Recycling, Pyrometallurgical Recycling, Hydrometallurgical Recycling, Direct Recycling End User: Battery Manufacturers, Recyclers, Automotive Industry, Consumer Electronics Application: Electric Vehicles, Energy Storage Systems, Portable Electronics, Industrial Applications |
| Companies Covered | Umicore, Cirba Solutions, Li-Cycle Holding Corporation, Redwood Materials, Grand Energy Manufacturing Co., Ltd., Miracle Automation Engineering Co., Ltd., Hosokawa Micron Group, SSI Shredding Systems, Inc, Eldan Recycling A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium Battery Recycling Equipment Market Trends and Innovations
Recycling technology is pivoting toward energy-efficient recovery pathways as electricity costs and carbon accounting reshape equipment selection criteria. Process intensification and modular plant design are emerging as dominant architectural principles.
Mechanical pre-treatment systems with advanced optical sorting are supplanting manual disassembly lines in commercial facilities. Tier-1 recyclers in Germany and South Korea are adopting these automated configurations to handle heterogeneous feedstock from multiple battery formats. The shift is compressing labor costs while enabling higher throughput for subsequent hydrometallurgical stages.
REACH compliance requirements for recovered material traceability are mandating digital integration between shredding equipment and laboratory information management systems. European recyclers must now demonstrate batch-level material provenance to downstream cathode manufacturers. This interoperability demand is driving equipment vendors to embed sensor networks and data logging capabilities as standard features rather than optional upgrades.
Automakers are consolidating recycling procurement under single-source equipment-and-service agreements rather than purchasing discrete machinery components. Battery manufacturers in Japan and the United States are favoring vendors offering guaranteed uptime contracts and shared responsibility for output purity. This bundling pattern favors integrated solution providers with in-house metallurgical expertise over pure-play equipment fabricators.
Lithium Battery Recycling Equipment Market Segmentation
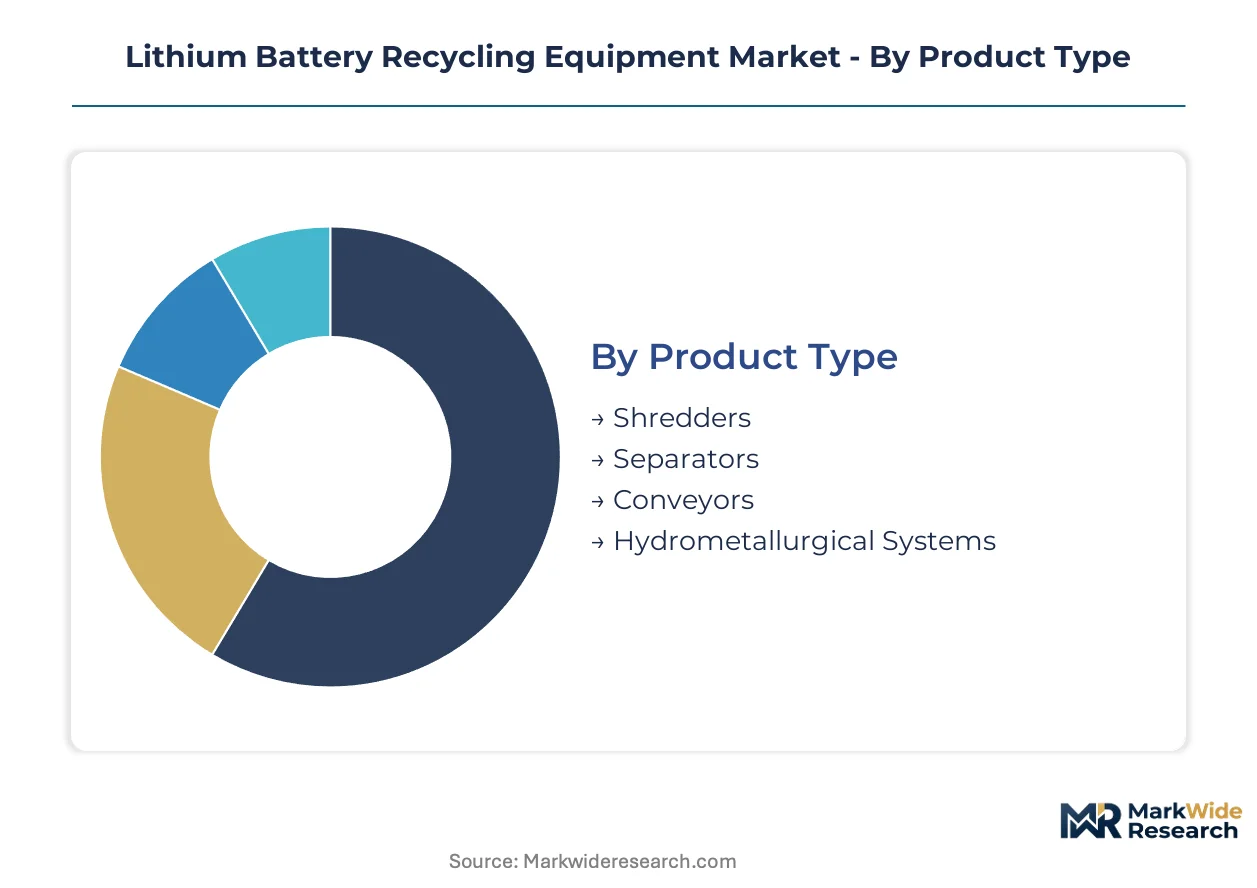
Segmentation in lithium battery recycling equipment reveals how capital deployment flows through distinct technology pathways and customer channels. Equipment purchasers prioritize configurations that align with feedstock chemistry, regulatory mandates, and downstream offtake agreements.
Product Type:
Shredders and separators move through distributor networks serving mid-scale recyclers, while hydrometallurgical systems sell direct to integrated operators with captive chemical processing.
- Shredders:Industrial-grade size reduction units process spent cells at throughput rates exceeding 500 kg per hour, reducing material to black mass consistency. German recyclers around Dresden deploy these as front-end infrastructure for closed-loop recovery clusters serving automotive OEMs. The EU Battery Regulation's lithium recovery thresholds are accelerating replacement of legacy manual disassembly lines.
- Hydrometallurgical Systems:Selective leaching and solvent extraction trains recover battery-grade lithium carbonate and nickel sulfate at purity levels meeting cathode precursor specifications. Precursor chemical producers in South Korea and Japan specify these systems to secure supply chain independence from mined material. Energy intensity advantages over pyrometallurgical alternatives are widening adoption in markets with volatile electricity pricing.
- Separators:Magnetic and eddy-current separation units extract ferrous and non-ferrous fractions from shredded feedstock.
- Conveyors:Automated material handling systems integrate shredding and separation stages with minimal manual intervention.
By volume, shredders lead. By growth pace, hydrometallurgical systems are climbing the fastest.
Technology:
Cost tiers separate these pathways: physical recycling occupies the economy position, pyrometallurgical sits at mid-tier capital intensity, while hydrometallurgical and direct recycling command premium equipment pricing.
- Hydrometallurgical Recycling:Acid leaching and solvent extraction circuits achieve selective metal recovery with lower carbon intensity than thermal alternatives. South Korean battery manufacturers specify these systems to meet ESG-linked financing requirements and supply chain traceability mandates. The precision enables recovery of lithium at grades suitable for direct cathode remanufacturing.
- Direct Recycling:Electrochemical regeneration processes preserve crystalline cathode structure without full elemental decomposition, promising 30-40% energy reduction versus conventional routes. R&D investment from US national laboratories and Japanese automotive OEMs is pushing pilot-scale demonstrations toward commercial viability. Feedstock uniformity requirements currently limit deployment to single-chemistry battery streams.
- Physical Recycling:Mechanical shredding and separation without chemical processing yields black mass for downstream sale.
- Pyrometallurgical Recycling:High-temperature smelting furnaces recover cobalt and nickel alloys with established operational protocols.
Physical recycling dominates installed base. Direct recycling shows the steepest expansion trajectory in R&D funding.
End User:
Application requirements differ sharply: battery manufacturers demand equipment with traceability integration, while recyclers prioritize throughput flexibility for heterogeneous feedstock.
- Automotive Industry:Electric vehicle OEMs are internalizing recycling capacity through captive facilities in Nevada, Tennessee, and Germany to secure cathode material supply chains. These operators specify integrated shredding-to-chemical-recovery lines with guaranteed uptime contracts. Equipment vendors with metallurgical expertise are winning bundled procurement agreements over pure-play fabricators.
- Recyclers:Independent operators process mixed feedstock from multiple battery formats and chemistry generations, requiring modular equipment configurations. Facilities in Ontario and Nevada face geographic concentration risk for black mass supply, driving demand for transportation-efficient hub-and-spoke architectures. Margin pressure from feedstock price volatility favors equipment with rapid chemistry changeover capability.
- Battery Manufacturers:Cell producers install recycling lines for manufacturing scrap recovery and closed-loop material circulation.
- Consumer Electronics:Smaller-scale operators handle portable battery streams with lower capital equipment requirements.
Recyclers hold the largest equipment installed base. Automotive industry procurement is gaining share fastest.
Application:
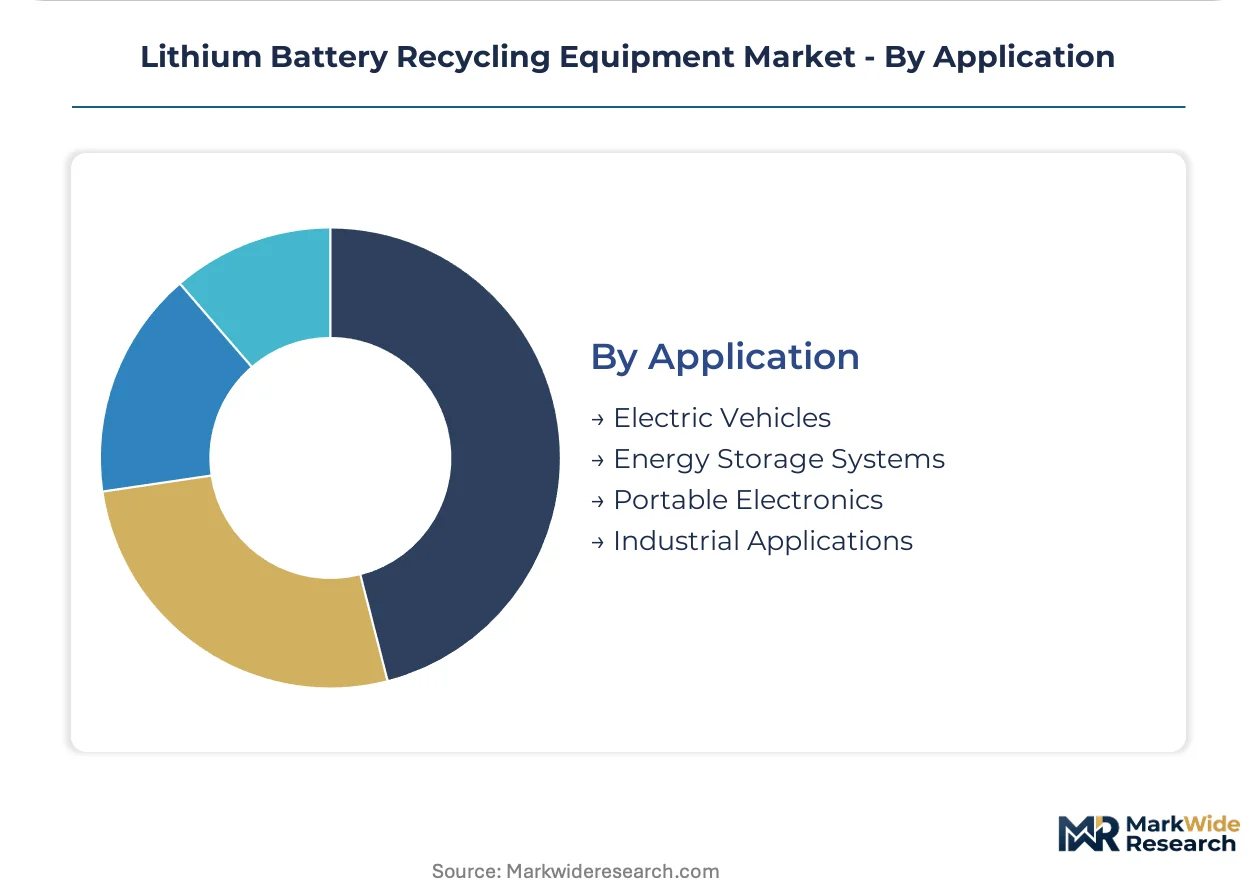
Volume concentration tracks battery retirement curves: electric vehicle packs dominate mass flow, while portable electronics contribute fragmented, distributed feedstock.
- Electric Vehicles:End-of-life lithium-ion packs from passenger cars and commercial trucks constitute the primary feedstock mass for large-scale recycling infrastructure. European operators in Germany and Poland are configuring lines to handle NMC and LFP chemistries simultaneously as fleet composition diversifies. The EU Battery Regulation's recycled content mandates are forcing equipment upgrades ahead of enforcement deadlines.
- Energy Storage Systems:Stationary battery installations from grid-scale projects and residential solar-plus-storage systems are entering early retirement phases, creating new feedstock categories. These systems often employ LFP chemistry with different shredding safety protocols and recovery economics than automotive packs. Equipment configurations must accommodate larger form factors and slower discharge characteristics.
- Portable Electronics:Smartphones, laptops, and power tools contribute distributed, low-mass feedstock requiring collection aggregation before processing.
- Industrial Applications:Forklifts, medical devices, and stationary industrial batteries generate specialized recycling requirements.
Electric vehicles dominate mass throughput. Energy storage systems are expanding most quickly as early grid installations retire.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Battery Regulation mandates minimum recycled content thresholds that compress equipment upgrade timelines across member states. Germany anchors European capacity expansion through industrial clusters integrating closed-loop recovery infrastructure.
Germany
Automotive OEM captive programs drive equipment procurement around Dresden and Hamburg industrial zones. The EU Battery Regulation forces recyclers to install compliant shredding and separation systems before 2031 enforcement deadlines. Facilities in Saxony are configuring lines to handle simultaneous NMC and LFP chemistry processing as fleet composition diversifies.
United States
EPA hazardous waste classification under RCRA shapes equipment specifications for spent battery handling. Automakers in Nevada and Tennessee are internalizing recycling capacity through dedicated facility investments. Black mass supply concentration in Nevada creates geographic dependency risks for equipment operators lacking diversified feedstock sourcing.
China
MIIT enforces GB standards for recycled battery material quality, creating dual-track market conditions. Export-facing recyclers adopt stricter specifications than domestic-only operators, fragmenting equipment design requirements. Industrial provinces are scaling hydrometallurgical capacity to meet precursor chemical producer demand for supply chain independence.
South Korea
Battery manufacturers specify hydrometallurgical systems to satisfy ESG-linked financing requirements and traceability mandates. Precursor chemical producers demand equipment achieving battery-grade lithium carbonate purity for direct cathode remanufacturing. National recycling infrastructure concentrates around metropolitan industrial corridors serving the domestic cell production base.
India
PLI scheme incentives for battery manufacturing are spawning domestic recycling capacity needs. First-mover equipment vendors are establishing local service networks to capture emerging procurement cycles. State-level industrial zones are integrating collection aggregation infrastructure ahead of projected end-of-life battery volume growth.
Lithium Battery Recycling Equipment Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the former commanding bundled procurement agreements and the latter competing on modular equipment configurations. The structure rewards metallurgical expertise over pure fabrication capability. Three archetypes dominate: captive automotive integrators, independent hub-and-spoke operators, and precursor chemical-aligned technology providers. Competitive moves concentrate on strategic partnerships with automakers and geographic expansion into emerging battery manufacturing regions.
Within the integrated refining tier, Umicore anchors European cathode precursor output through its Hoboken complex. Li-Cycle Holding Corporation exemplifies the hub-and-spoke hydrometallurgical model that minimizes transportation costs for black mass aggregation. Redwood Materials occupies a position in North American feedstock consolidation through automaker partnerships in Nevada and Tennessee.
| Leading Market Players |
|---|
| Umicore |
| Cirba Solutions |
| Li-Cycle Holding Corporation |
| Redwood Materials |
| Grand Energy Manufacturing Co., Ltd. |
| Miracle Automation Engineering Co., Ltd. |
| Hosokawa Micron Group |
| SSI Shredding Systems, Inc |
| Eldan Recycling A/S |
| Others |
Pricing and Supply Chain Analysis
Twenty-four-month equipment commissioning timelines compress pricing power for European recyclers facing EU Battery Regulation deadlines, concentrating procurement leverage among German automotive OEMs with captive facility investments while fragmenting margin pools for independent operators dependent on spot black mass markets.
Pricing Analysis
Geographic price spreads between German industrial clusters and North American feedstock hubs exceed thirty percent for equivalent hydrometallurgical system configurations. Three-tier pricing structure across premium, standard, and economy levels separates integrated solution providers with metallurgical expertise from pure-play fabricators and regional distributors. Cost compression in pyrometallurgical furnace segments is intensifying because energy price volatility disadvantages high-temperature recovery pathways. Automotive OEM captive programs demonstrate lowest price sensitivity due to supply chain security premiums, while independent recyclers in Ontario and Nevada exhibit highest elasticity to equipment capital expenditure.
Supply Chain Analysis
China and South Korea anchor cathode precursor chemical production, with Germany and the United States scaling downstream recycling infrastructure. Equipment manufacturing draws from specialized steel alloys for high-temperature furnace components, precision leaching vessel fabrication, and sensor-integrated shredding assemblies. Single-source vulnerability concentrates in rare earth magnet supply for separator systems, creating tariff exposure for European and North American equipment assemblers. Distribution runs through direct sales channels for integrated hydrometallurgical trains, while shredders and mechanical separators move via distributor networks serving mid-scale recyclers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against direct recycling technology maturation, which threatens to displace conventional elemental decomposition equipment with electrochemical regeneration processes preserving crystalline cathode structure.
For Market Incumbents: Consolidate metallurgical engineering capabilities through targeted capability acquisitions in pyrometallurgical furnace operation, where vocational training program output lags facility commissioning demand. Lock in multi-year service contracts with German automotive OEMs to secure recurring revenue streams against emerging hub-and-spoke operators. Prioritize backward integration into black mass preprocessing to defend margin position from feedstock price volatility.
For New Entrants and Emerging Players: Differentiate on artificial intelligence-driven sorting integration for direct recycling feedstock preparation, where uniform cell chemistry requirements currently limit commercial deployment. Target India's PLI scheme procurement cycles before established vendors complete local service network buildouts. Pursue joint development agreements with US national laboratories advancing electrochemical regeneration pilot demonstrations.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hydrometallurgical system manufacturing as precursor chemical producers demand battery-grade lithium carbonate purity specifications. Five-to-ten-year viability favors equipment vendors with integrated metallurgical expertise over pure fabrication plays. Monitor CE marking and EPA hazardous waste permitting timeline compression as inflection indicators for revenue recognition delays affecting plant operator valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Black Mass Aggregation | Reduces feedstock price volatility exposure for Nevada and Ontario equipment operators. |
| Artificial Intelligence-Driven Sorting Development | Enables direct recycling commercialization by delivering uniform cell chemistry inputs. |
| Local Service Network Establishment | Captures India's PLI scheme procurement before incumbent vendors complete footprint. |
| Multi-Year Uptime Guarantee Contracts | Secures bundled procurement agreements with Japanese and US battery manufacturers. |
| Pyrometallurgical Engineering Capability Acquisition | Addresses skilled furnace operator scarcity compressing European facility commissioning. |
Research Methodology
Operator-level perspectives from pyrometallurgical engineers, hydrometallurgical plant managers, automotive OEM procurement leads, and precursor chemical producer technical directors anchored the qualitative base. Primary interviews combined with secondary validation against EPA hazardous waste filings under RCRA, EU Battery Regulation implementation guidance, MIIT GB standards documentation, and customs trade data for lithium carbonate and nickel sulfate movements. Bottom-up equipment unit economics triangulated against top-down cathode material demand projections.
Sensitivity analysis tested forecast robustness across energy price volatility scenarios, feedstock concentration risk assumptions, and regulatory deadline enforcement variations. Segmentation dimensions modeled include recovery technology pathway, equipment product type, end-user industry vertical, and application feedstock chemistry. CAGRs derived from installed base expansion rates, replacement cycle timing, and technology shift elasticities. Industry-specific inputs incorporated black mass supply cluster formation patterns and CE marking timeline compression observations.
The analysis sits within stated boundaries; outcomes outside EU Battery Regulation enforcement adherence, MIIT GB standard export-tier compliance, or sustained lithium carbonate price bands would require recalibration. Forecasts reflect documented assumptions regarding pyrometallurgical engineer training program scaling, direct recycling pilot-to-commercial transition pacing, and automotive OEM captive facility investment continuity. Recalibration cycles align with material shifts in regulatory deadline enforcement, feedstock supply cluster geographic diversification, and direct recycling technology maturation milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Recycling
Automotive Oil Recycling Market
Battery Recycling
Battery Scrap Market
Battery Recycling
Global Lead Recycling Battery Market
Battery Recycling
Battery Materials Recycling Market
Battery Recycling
Middle East and Africa Lithium-Ion Battery Recycling Market
Battery Recycling
Lithium Iron Phosphate Battery Recycling Market
Battery Recycling
Lithium Battery Recycling Market
Battery Recycling
Lithium Ion Battery and Material Recycling Market
Battery Recycling
Europe Solar Panel Recycling Market
Battery Recycling
Lithium-Ion Battery Recycling Service Market
Battery Recycling
Solar Components Recycling Market
Battery Recycling
Battery Recycling Market
Battery Recycling
Global Primary Battery Recycling Market
Battery Recycling
Electric Vehicle (EV) Battery Recycling Market
Battery Recycling
Lithium-Ion Battery Recycling Solution Market
Battery Recycling
North America Lithium-Ion Battery Recycling Market