
 Industrial Water Cooling System Market | 2026-2036
Industrial Water Cooling System Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Water Cooling System Market Foresight
The split between premium engineered systems and commodity packaged units is restructuring the competitive landscape for industrial water cooling. Johnson Controls leverages its building automation integration to command specification-driven projects in data center and pharmaceutical applications. Trane Technologies anchors its position through chiller technology leadership and deep contractor relationships. GESON Chiller competes aggressively on modular configurations for mid-scale manufacturing plants across Asia.
Industrial water cooling systems manage thermal rejection through circulating water loops, heat exchangers, and evaporative or mechanical refrigeration processes, typically operating across temperature ranges from 4°C to 35°C depending on process requirements. These systems serve critical functions in protecting capital equipment, maintaining process chemistry, and enabling continuous manufacturing operations. Chilled water systems and cooling towers represent the dominant installed base, though closed loop configurations are gaining preference as water scarcity intensifies operational constraints on open loop designs. Modular systems are expanding fastest among configurations, driven by data center colocation providers seeking phased capacity deployment without centralized plant construction.
The US EPA enforces discharge temperature and chemical limits under the Clean Water Act, while the EU F-Gas Regulation progressively restricts refrigerants with high global warming potential in new cooling equipment. China's MEE implements increasingly stringent industrial wastewater thermal discharge standards in key river basins. Facility engineers and procurement teams must weigh refrigerant transition timelines against equipment replacement cycles as regulatory phase-downs accelerate.
Market Dynamics
AI-driven thermal loads in hyperscale computing facilities are forcing a fundamental reconfiguration of cooling infrastructure specifications, with discharge temperature compliance emerging as the binding constraint on system design across all major industrial jurisdictions.
Growth Catalysts
- EPA Clean Water Act thermal discharge limits:Stricter enforcement of Section 316(b) intake standards and temperature variance requirements drives replacement demand for legacy once-through cooling systems at power generation and petrochemical facilities in the United States.
- Data center liquid cooling adoption:Direct-to-chip and immersion cooling architectures for GPU-intensive AI training clusters require engineered water cooling loops with precision temperature control and redundancy specifications.
- Yangtze River Delta industrial clustering:Concentrated expansion of semiconductor fabrication and battery cell manufacturing in Jiangsu and Zhejiang provinces generates concentrated procurement of closed-loop chilled water systems.
Market Restraints
- Copper and aluminum price volatility:Heat exchanger fabrication depends on non-ferrous metals whose commodity price swings compress equipment margins and destabilize project bidding.
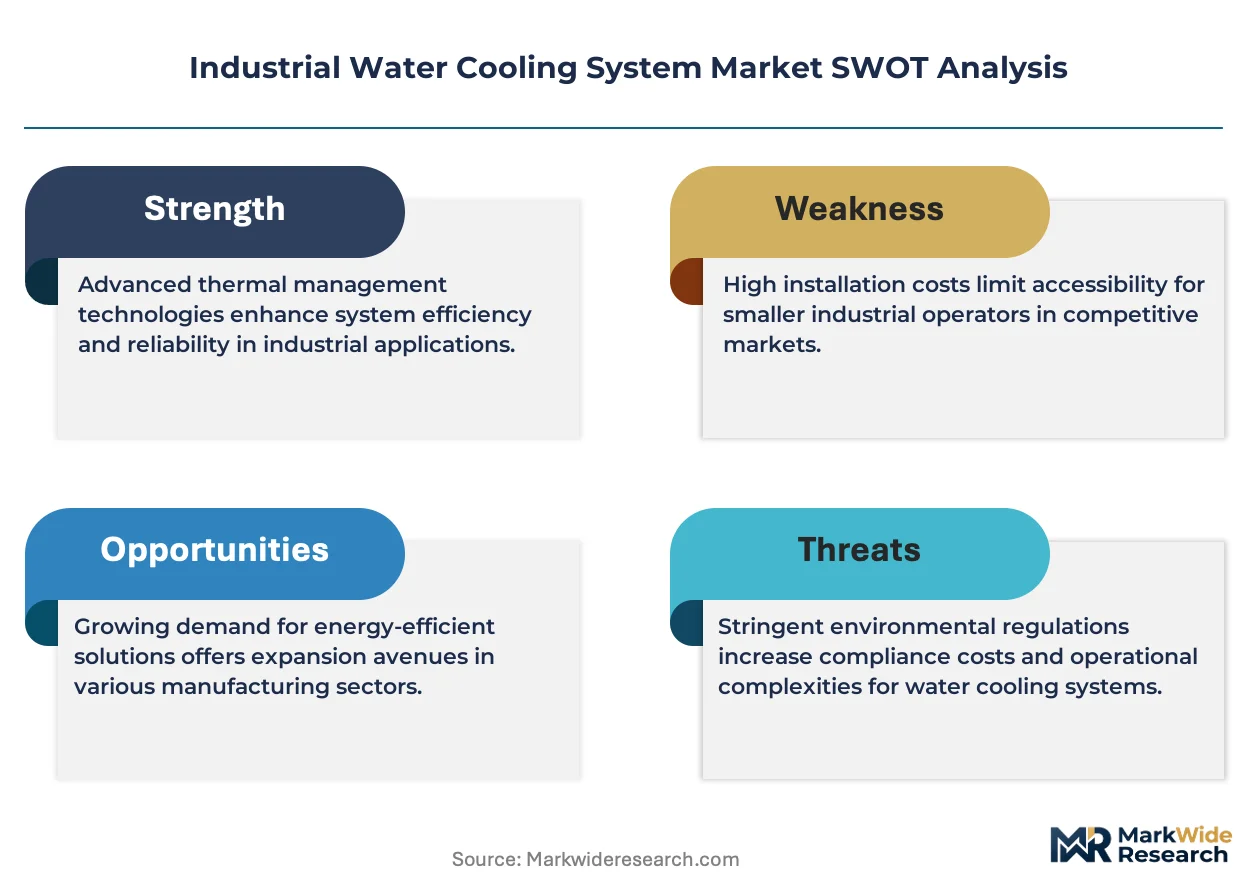
- Refrigerant supply concentration:Production of low-GWP hydrofluoroolefins concentrates among three chemical manufacturers, creating allocation risk as EU F-Gas Regulation phase-downs accelerate.
- Water scarcity in southwestern China:MEE discharge restrictions in the Pearl River basin limit open-loop cooling tower deployment for steel and cement operations.
Strategic Opportunities
- Modular cooling-as-a-service models:Colocation providers in Frankfurt and Amsterdam adopt subscription-based thermal capacity provisioning to avoid upfront capital deployment.
- Waste heat recovery integration:District heating network interconnection requirements in Denmark and Sweden create specification pull for absorption chiller hybrids in industrial parks.
- India PLI scheme for green hydrogen:Electrolyzer manufacturing scale-up under the Production Linked Incentive program demands specialized low-temperature cooling for PEM stack operations.
Industry Challenges
- Refrigerant handling certification gaps:Technician shortages for A2L and A3 refrigerant systems delay commissioning timelines in markets with accelerated phase-down schedules.
- Legacy SCADA integration complexity:Brownfield facilities require protocol bridging between proprietary chiller controls and modern building management networks.
- Cross-border equipment certification:Divergent pressure vessel codes between ASME and PED jurisdictions extend approval cycles for multinational project deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Water Cooling System Market |
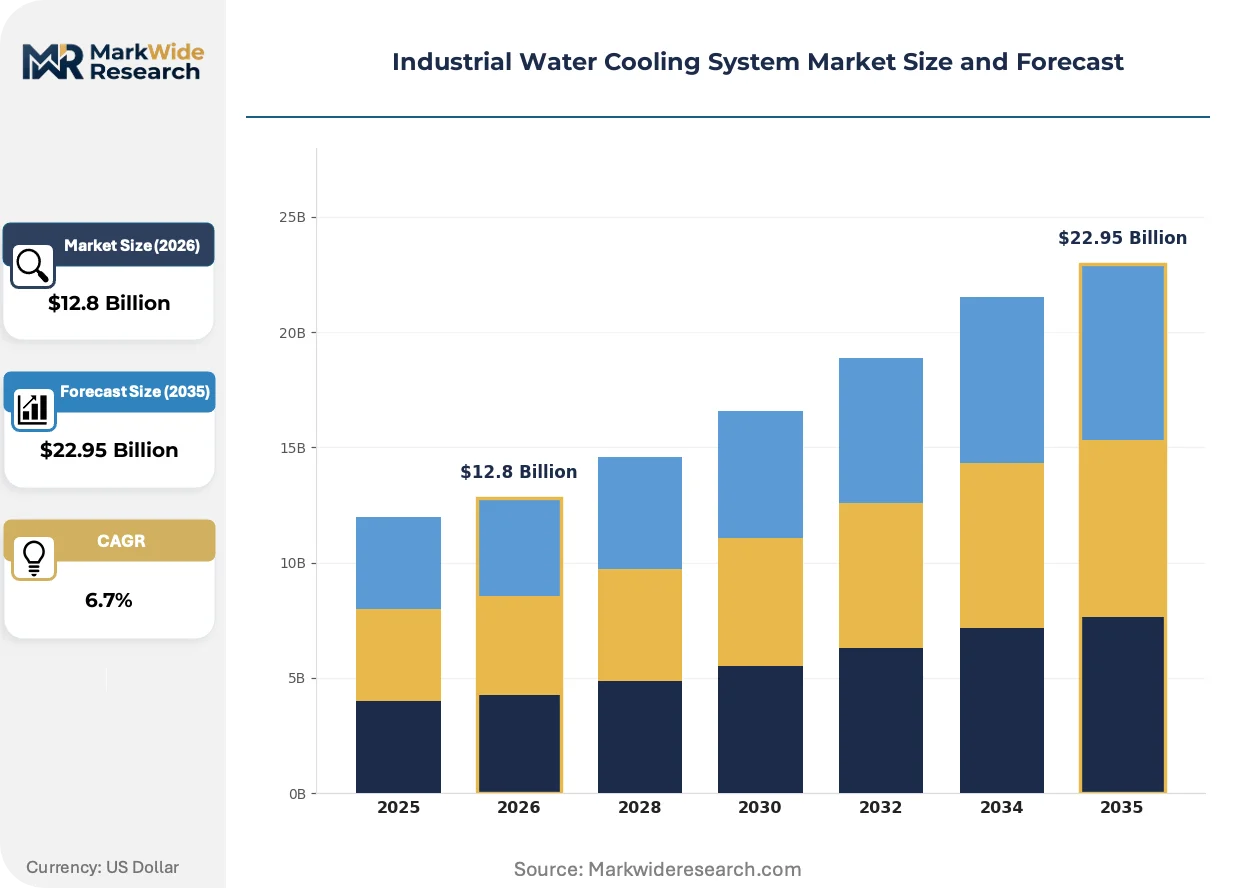
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Chilled Water Systems, Cooling Towers, Heat Exchangers, Refrigeration Units End User: Manufacturing Plants, Power Generation, Data Centers, Chemical Processing Technology: Ifan Technology, Evaporative Cooling, Closed Loop Systems, Open Loop Systems Configuration: Modular Systems, Centralized Systems, Portable Units, Custom Solutions |
| Companies Covered | Johnson Controls, Drake Chillers, Atlas Copco, GESON Chiller, TopChiller, Parker Hannifin, Daikin Industries, Filtrine, Trane Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Water Cooling System Market Shifts & Advancements
Equipment intelligence and thermal energy recovery are converging to redefine system value propositions, with buyers prioritizing operational flexibility over peak efficiency ratings.
Adiabatic cooling modules with evaporative pre-cooling stages are expanding into data center applications in Singapore and Sydney where water restrictions prohibit conventional tower operation. Colocation operators deploy these hybrid systems to maintain PUE targets without municipal water dependence. The technology is expanding into markets previously dominated by air-cooled chillers by eliminating the efficiency penalty of dry-only operation in high-ambient conditions.
EU F-Gas Regulation revision proposals tighten GWP limits for new stationary refrigeration equipment to 150 by 2027, compressing the viable refrigerant set for large-tonnage chillers. Equipment manufacturers accelerate R-1234ze and R-515B qualification programs while lobbying for heat pump exemptions. Process cooling applications in pharmaceutical and chemical sectors face the steepest compliance timeline given longer equipment replacement cycles.
Specification authority is migrating from facilities engineering to sustainability procurement functions with explicit carbon accounting mandates. Corporate net-zero commitments drive preference for systems with embodied carbon disclosures and refrigerant charge minimization. This shift is most visible in European automotive battery gigafactories where supply chain emissions reporting extends to auxiliary plant equipment.
Industrial Water Cooling System Market Segmentation
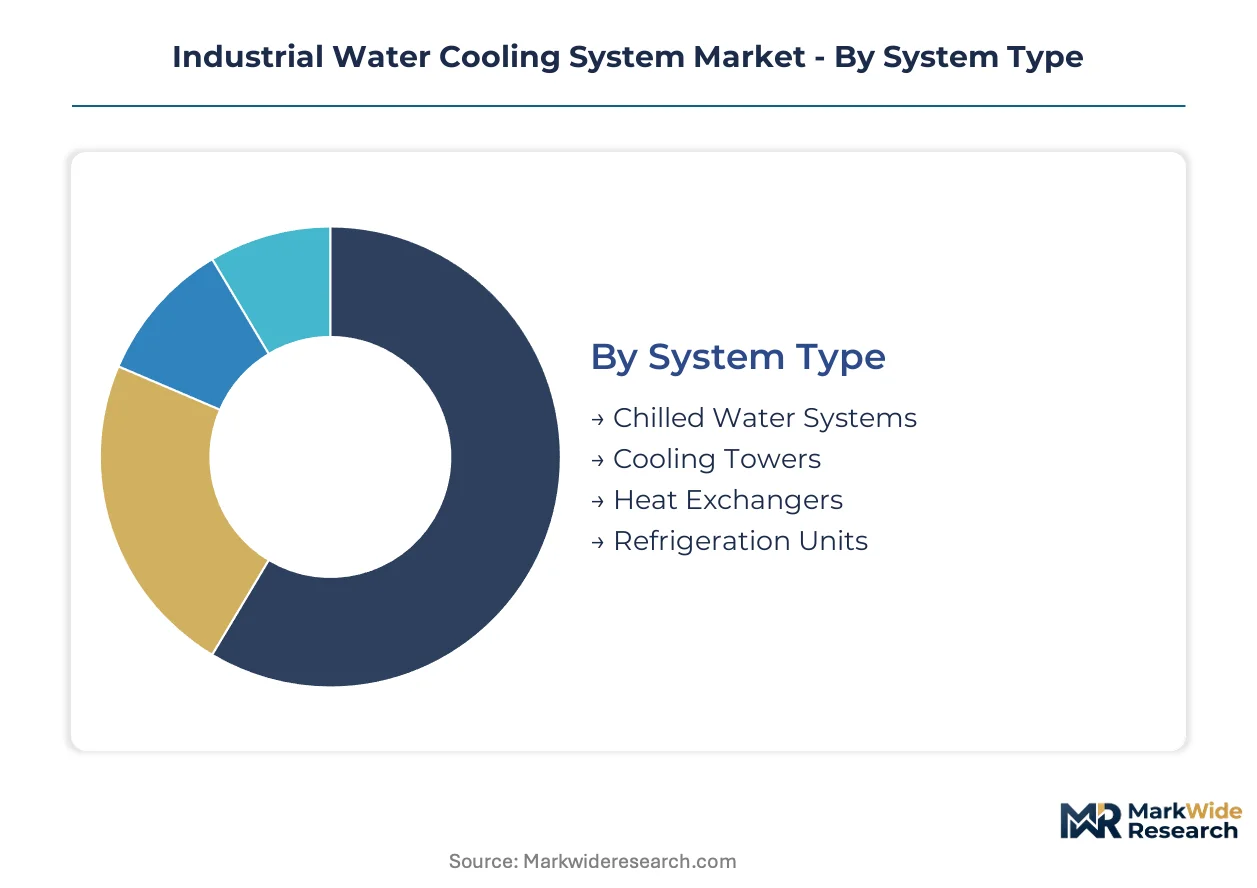
Industrial water cooling systems fragment across multiple technical and commercial dimensions that determine procurement criteria and supplier positioning. Engineers specify based on thermal load characteristics, regulatory constraints, and integration complexity with existing plant infrastructure. Understanding these segment boundaries clarifies where modular, standardized solutions displace engineered custom configurations.
System Type:
Standalone thermal rejection equipment dominates heavy industrial applications, while embedded cooling loops integrate directly into process lines for precision temperature control.
- Chilled Water Systems:Centralized refrigeration plants circulate glycol-water mixtures through distribution networks to maintain process temperatures between 4°C and 12°C. Demand concentrates in pharmaceutical manufacturing facilities across Germany and Switzerland where batch consistency requirements mandate redundant cooling capacity. The EU F-Gas Regulation phase-down accelerates replacement cycles for systems using high-GWP refrigerants.
- Cooling Towers:Evaporative heat rejection structures dissipate thermal loads through water-air contact, achieving approach temperatures within 3-5°C of ambient wet-bulb conditions. Deployment clusters at petrochemical complexes along the US Gulf Coast where EPA Clean Water Act discharge limits restrict once-through alternatives. Water scarcity in Texas and Louisiana drives hybrid dry-wet tower adoption.
- Heat Exchangers:Shell-and-tube and plate-frame configurations transfer thermal energy between process streams without refrigerant circulation.
- Refrigeration Units:Packaged mechanical cooling systems provide sub-ambient temperatures for specialized industrial processes.
Volume placements concentrate in Cooling Towers; the faster expansion belongs to Chilled Water Systems.
End User:
Capital intensity and thermal precision requirements create distinct procurement patterns across industrial sectors, with hyperscale computing facilities driving specification innovation.
- Manufacturing Plants:Automotive stamping and injection molding operations require continuous cooling for hydraulic systems and tooling temperature stability. Procurement in China's Yangtze River Delta industrial corridor favors modular configurations that scale with production line expansion. MEE thermal discharge standards in Jiangsu province mandate closed-loop designs for new facilities.
- Data Centers:GPU-intensive AI training clusters generate heat densities exceeding 50 kW per rack, forcing direct-to-chip liquid cooling adoption. Hyperscale operators in Virginia's Loudoun County and Amsterdam's Schiphol-Rijk corridor specify engineered redundancy with N+1 chiller configurations. Sustainability procurement teams prioritize systems with embodied carbon disclosures.
- Power Generation:Combined-cycle gas turbine plants and thermal power stations deploy large-tonnage cooling for condenser duty and auxiliary systems.
- Chemical Processing:Exothermic reaction control and solvent recovery operations demand corrosion-resistant materials and precise temperature band maintenance.
Manufacturing Plants anchor current installed capacity; Data Centers are climbing the fastest as AI infrastructure deployment accelerates.
Technology:
Water availability and ambient climate conditions determine whether evaporative, mechanical, or hybrid approaches deliver optimal lifecycle economics.
- Evaporative Cooling:Water-intensive thermal rejection achieves efficiency ratios exceeding mechanical alternatives by exploiting latent heat of vaporization. Deployment concentrates in Singapore and Sydney data centers where adiabatic pre-cooling modules circumvent municipal water restrictions. Colocation operators accept higher water consumption to maintain PUE targets below 1.25.
- Closed Loop Systems:Recirculating configurations eliminate continuous water withdrawal and discharge, reducing regulatory exposure under tightening MEE standards. Semiconductor fabrication facilities in South Korea's Gyeonggi Province specify closed-loop chilled water to protect ultra-pure process chemistry from contamination. Capital costs run 15-25% above open-loop alternatives.
- Ifan Technology:Induced-draft fan systems optimize airflow distribution across cooling tower fill media.
- Open Loop Systems:Once-through designs withdraw and discharge water directly to natural sources, facing regulatory phase-out.
Evaporative Cooling retains volume leadership in water-abundant regions; Closed Loop Systems are gaining share fastest where scarcity constraints intensify.
Configuration:
Deployment architecture determines capital commitment timing and operational flexibility for facilities with uncertain growth trajectories.
- Modular Systems:Prefabricated chiller and heat exchanger skids enable phased capacity expansion without centralized plant construction. Frankfurt and Amsterdam colocation providers adopt cooling-as-a-service subscription models to convert capital expenditure to operational expenditure. Factory acceptance testing reduces commissioning risk versus field-built alternatives.
- Custom Solutions:Engineered-to-order systems address non-standard thermal loads, space constraints, or integration with legacy SCADA networks. Pharmaceutical batch processing facilities in Ireland and Switzerland specify custom stainless steel piping configurations to meet FDA and EMA validation requirements. Extended design cycles and proprietary controls complicate supplier switching.
- Centralized Systems:Single large-tonnage plants serve entire facility thermal loads through extensive distribution networks.
- Portable Units:Temporary cooling capacity addresses emergency outages, maintenance bypass, or seasonal peak supplementation.
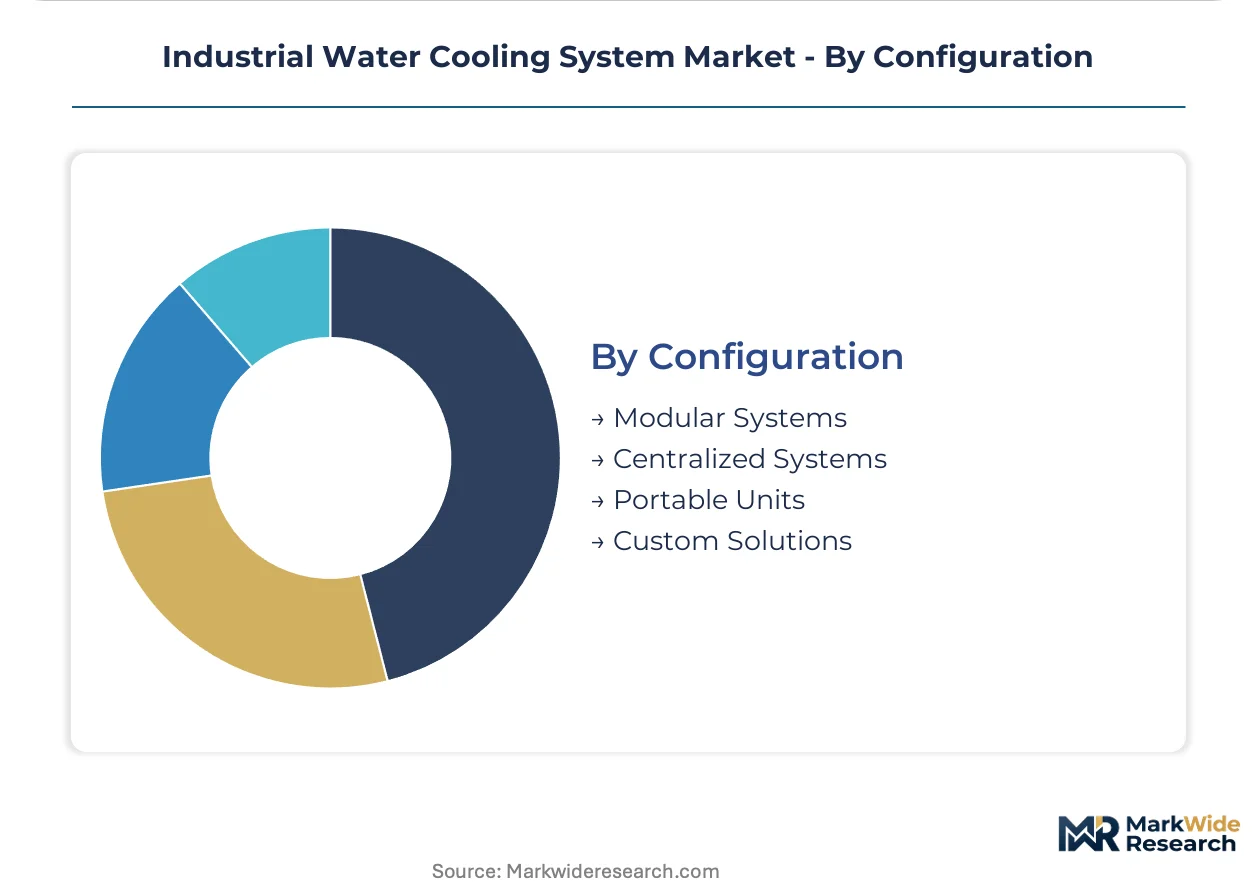
Centralized Systems dominate legacy installed base; Modular Systems show the steepest expansion trajectory as colocation and manufacturing seek capital flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Loudoun County in Virginia anchors hyperscale data center deployment, with Ashburn's concentration of AI training facilities driving precision cooling specifications that cascade into global equipment standards.
United States
Power generation and petrochemical facilities along the Gulf Coast face EPA Clean Water Act Section 316(b) enforcement that mandates replacement of once-through cooling systems. The EPA's thermal discharge variance requirements tighten quarterly. Texas and Louisiana industrial clusters pivot toward hybrid dry-wet cooling towers as water scarcity intensifies operational constraints.
Germany
Pharmaceutical manufacturing in Ludwigshafen and Leverkusen demands redundant chilled water capacity for batch process consistency. The EU F-Gas Regulation's 150 GWP limit for new equipment compresses refrigerant selection timelines. Frankfurt's colocation corridor experiments with cooling-as-a-service subscription models to convert capital expenditure to operational expenditure.
China
Semiconductor fabrication and battery cell manufacturing concentrate in Jiangsu and Zhejiang provinces along the Yangtze River Delta. MEE thermal discharge standards in key river basins mandate closed-loop configurations for new facilities. Suzhou and Hangzhou industrial parks scale modular chilled water systems to match production line expansion cycles.
Singapore
Data center operators deploy adiabatic cooling modules with evaporative pre-cooling stages to circumvent municipal water restrictions while maintaining PUE targets below 1.25. The city-state's tropical climate and land scarcity force vertical facility design that favors compact, high-density thermal rejection equipment. Colocation providers in the Jurong Lake District prioritize systems with embodied carbon disclosures.
India
Electrolyzer manufacturing scale-up under the PLI scheme for green hydrogen demands specialized low-temperature cooling for PEM stack operations. The CEA's grid integration requirements for industrial loads influence thermal system sizing. Gujarat's industrial corridor attracts cooling equipment procurement as hydrogen hub development accelerates.
Industrial Water Cooling System Market Competitive Landscape
Premium-margin players sit above commodity-margin players across specification complexity and integration depth. The market structures into three tiers: building automation integrators commanding engineered projects, chiller technology specialists anchoring contractor relationships, and modular fabricators competing on configuration flexibility. Consolidation pressures concentrate among mid-scale manufacturers as refrigerant transition timelines compress replacement cycles. Strategic moves center on M&A for controls capabilities and geographic expansion into Yangtze River Delta industrial clusters.
Within the building automation tier, Johnson Controls represents specification-driven positioning for data center and pharmaceutical applications. Trane Technologies anchors chiller technology leadership through deep contractor channel relationships. GESON Chiller exemplifies the modular configuration archetype competing aggressively for mid-scale manufacturing plants across Asia. These three occupy distinct competitive spaces without direct overlap in procurement criteria or customer engagement models.
| Leading Market Players |
|---|
| Johnson Controls |
| Drake Chillers |
| Atlas Copco |
| GESON Chiller |
| TopChiller |
| Parker Hannifin |
| Daikin Industries |
| Filtrine |
| Trane Technologies |
| Others |
Supply & Pricing Matrix
Copper and aluminum heat exchanger fabrication costs cascade through three distinct pricing tiers, with commodity-grade packaged units absorbing the steepest margin compression while engineered systems for data centers and pharmaceuticals retain specification premiums through integrated controls and compliance bundling.
Pricing Analysis
Uptime guarantees and thermal compliance outcomes anchor value-based pricing for premium-tier installations, with hyperscale data center operators accepting 40-60% cost premiums for N+1 redundancy configurations and embodied carbon disclosures. Three-tier pricing structure across premium, standard, and economy levels separates specification-driven projects from modular mid-scale deployments and commodity replacement units. Cost compression in the economy tier is intensifying because copper price volatility erodes fabricator margins on standardized heat exchangers. Pharmaceutical and semiconductor facilities demonstrate the lowest price sensitivity due to batch consistency requirements, while steel and cement operations in water-scarce regions exhibit acute cost consciousness.
Supply Chain Analysis
Dual-sourcing mandates from European automotive battery gigafactories and North American data center operators require qualification of at least two heat exchanger fabricators per component category, compressing supplier consolidation incentives. Manufacturing concentration centers on China for copper tube and fin stock, Germany for precision-engineered chiller assemblies, and South Korea for closed-loop system electronics. Raw material dependencies encompass Chilean copper cathode, Australian bauxite for aluminum alloys, and Japanese refrigerant-grade steel. Single-source vulnerability concentrates in low-GWP hydrofluoroolefin supply, where three chemical manufacturers control global production allocation. Distribution runs through regional HVAC contractor networks for installation and aftermarket service, with direct OEM relationships dominating hyperscale data center procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct-to-chip liquid cooling architectures are displacing conventional air-cooled infrastructure in AI training facilities, creating a technology-transition window where refrigerant compliance and thermal density specifications reshape competitive positioning.
For Market Incumbents: Deploy refrigerant transition acceleration as the primary defensive lever. Johnson Controls and Trane Technologies should front-load R-1234ze and R-515B qualification programs ahead of EU F-Gas Regulation enforcement timelines, while acquiring modular controls specialists to counter GESON Chiller's configuration flexibility in Asian manufacturing corridors. Channel control through contractor certification programs defends specification authority against emerging entrants. For New Entrants and Emerging Players: The mid-tier price-point gap between premium engineered systems and commodity packaged units offers white-space opportunity in India's green hydrogen electrolyzer cooling segment and Southeast Asian battery cell manufacturing. Target PEM stack low-temperature cooling applications where incumbent refrigerant portfolios face compliance delays. Pursue cooling-as-a-service subscription models with Frankfurt and Amsterdam colocation providers to bypass capital-intensive direct sales cycles. For Investors and Strategic Acquirers: MEE thermal discharge standard tightening in China's Yangtze River Delta is the leading indicator that closed-loop system demand will outpace open-loop alternatives across Asian industrial clusters. Five-to-ten-year viability favors manufacturers with captive refrigerant handling certification capabilities and modular fabrication footprints. Monitor A2L and A3 refrigerant technician training program expansion as the signal for accelerated replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Portfolio Transition | Early qualification of R-1234ze systems captures EU F-Gas Regulation compliance premiums in pharmaceutical applications. |
| Modular Configuration Expansion | Prefabricated skid deployment reduces commissioning risk for data center colocation providers in Frankfurt and Amsterdam. |
| Controls Capability Acquisition | SCADA integration expertise bridges legacy brownfield infrastructure with modern building management networks. |
| Geographic Manufacturing Footprint | Production presence in Jiangsu and Zhejiang provinces aligns with Yangtze River Delta industrial clustering. |
| Technician Certification Program | A2L and A3 refrigerant handling training accelerates commissioning timelines in accelerated phase-down markets. |
Research Methodology
Independent corroboration across facility engineering directors, HVAC contractor procurement leads, refrigerant supply specialists, and sustainability officers at hyperscale data center operators underwrites the qualitative findings in this study. Primary interviews with plant managers at semiconductor fabrication facilities, maintenance directors at petrochemical complexes, and aftermarket service heads at regional distributor networks combined with secondary validation from EPA enforcement databases, EU F-Gas Regulation revision proposals, and MEE thermal discharge standard filings. Bottom-up equipment shipment analysis and top-down industrial cooling intensity modeling triangulate volume estimates.
Comparable historical periods anchored the forecast window to replacement cycle patterns observed through prior refrigerant phase-downs and Clean Water Act enforcement intensification. The analytical framework segments across system type, end-use industry, technology configuration, and deployment architecture throughout the projection horizon. CAGRs derive from equipment retirement schedules, regulatory compliance deadlines, and AI infrastructure deployment trajectories. Industry-specific inputs include data center power density specifications, pharmaceutical batch consistency requirements, and hydrogen electrolyzer thermal load profiles.
Inputs from EPA enforcement actions, EU regulatory filings, and Chinese provincial environmental disclosures were available through the study window; gaps in real-time refrigerant allocation data and unannounced data center construction timelines introduce uncertainty bands around near-term deployment estimates. Deviation in MEE enforcement intensity or F-Gas Regulation revision timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Air Source Heat Pump Market
Cooling Systems
Global Energy Efficient HVAC Systems Market
Cooling Systems
Solar Cooling Market
Cooling Systems
Critical Power and Cooling Market
Cooling Systems
Marine Cooling Systems Market
Cooling Systems
Fluid Coolers Market
Cooling Systems
Heat Pipe Market
Cooling Systems
Solar-Assisted Heat Pump Market
Cooling Systems
Solar Fan Market
Cooling Systems
United States Heat Pump Market
Cooling Systems
Radiant Cooling Systems Market
Cooling Systems
Solar Ventilation Systems Market
Cooling Systems
Air to Air Heat Pumps Sales Market
Cooling Systems
Solar Air Conditioning Market
Cooling Systems
Cryosystem Market
Cooling Systems
Microchannel Heat Exchanger Market