
 Global Planar Solid Oxide Fuel Cell Market | 2026-2036
Global Planar Solid Oxide Fuel Cell Market Size, Share, and Industry Trends Forecast 2026-2036
Global Planar Solid Oxide Fuel Cell Market Intelligence
The historical scarcity of high-temperature ceramic engineering and electrochemistry expertise is unwinding as academic programs and corporate training initiatives expand the talent pool. Bloom Energy leverages its proprietary solid oxide technology for large-scale stationary power applications in the United States. Ceres Power Holdings differentiates with its steel-cell technology, targeting data centers and commercial buildings through licensing partnerships.
A planar solid oxide fuel cell is an electrochemical conversion device that produces electricity directly from oxidizing a fuel. Its design features flat, plate-like components, including a dense ceramic electrolyte typically made of yttria-stabilized zirconia (YSZ), which operates at high temperatures to facilitate ion transport. Within applications, distributed power generation for commercial and industrial sites represents the largest segment due to high electrical efficiency. The power plants end-user category is poised for significant expansion, driven by grid stability and decarbonization requirements.
Incentives within the U.S. Inflation Reduction Act (IRA) and directives under the EU Green Deal directly support fuel cell deployments for clean power generation. In Japan, policies from the Ministry of Economy, Trade and Industry (METI) promote hydrogen and fuel cell technology as part of the national energy strategy. Stakeholder success depends on navigating evolving safety standards and securing supply chains for critical raw materials like rare earth elements.
Market Dynamics
The central force shaping the planar SOFC market is the imperative for non-intermittent, clean power generation. National decarbonization targets are creating structural demand for high-efficiency, fuel-flexible technologies that complement variable renewable sources like solar and wind.
Growth Catalysts
- Favorable Government Policies:The European Union's Green Deal and national hydrogen strategies in Japan and South Korea provide direct subsidies and regulatory support, accelerating fuel cell deployment for grid support and industrial power.
- Data Center Power Demand:The need for highly reliable, 24/7 power with low emissions drives adoption in the data center industry, where SOFCs offer superior electrical efficiency and on-site generation benefits.
- Advancements in Material Science:Improvements in ceramic electrolyte and interconnect materials are enhancing the durability and operational lifespan of fuel cell stacks, lowering the total cost of ownership for end-users.
Market Restraints
- High Material Costs:The price and supply volatility of critical raw materials, including rare earth elements like yttria and scandia used in electrolytes and electrodes, present a significant cost barrier to mass production.
- Thermal Degradation:Planar SOFCs are susceptible to performance degradation from thermal cycling. This limits their suitability for applications requiring frequent starts and stops, favoring continuous baseload operation.
- Supply Chain Concentration:The global supply of high-purity ceramic powders and specialized manufacturing equipment is concentrated among a few suppliers, creating potential bottlenecks and pricing pressures for cell manufacturers.
Strategic Opportunities
- Marine Sector Decarbonization:New applications for auxiliary power units (APUs) in the maritime industry offer a significant growth vector, helping shippers meet stringent emissions regulations from the International Maritime Organization.
- Expansion in Developing Economies:Markets like India present opportunities for distributed power in areas with unreliable grids, supported by government initiatives like the National Green Hydrogen Mission to foster clean energy ecosystems.
- Carbon Capture Integration:Combining SOFC systems with carbon capture technology at industrial facilities creates a pathway for negative-emission power generation, appealing to companies with aggressive corporate sustainability goals.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of engineers with expertise in high-temperature electrochemistry and ceramic processing hinders research, development, and manufacturing scale-up across the industry.
- Standardization Hurdles:The lack of globally harmonized safety and performance standards complicates international trade and system integration, increasing compliance costs and time-to-market for manufacturers.
- High Capital Expenditure:The significant upfront investment required to establish and scale automated manufacturing lines for SOFC stacks and systems remains a substantial barrier for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Planar Solid Oxide Fuel Cell Market |
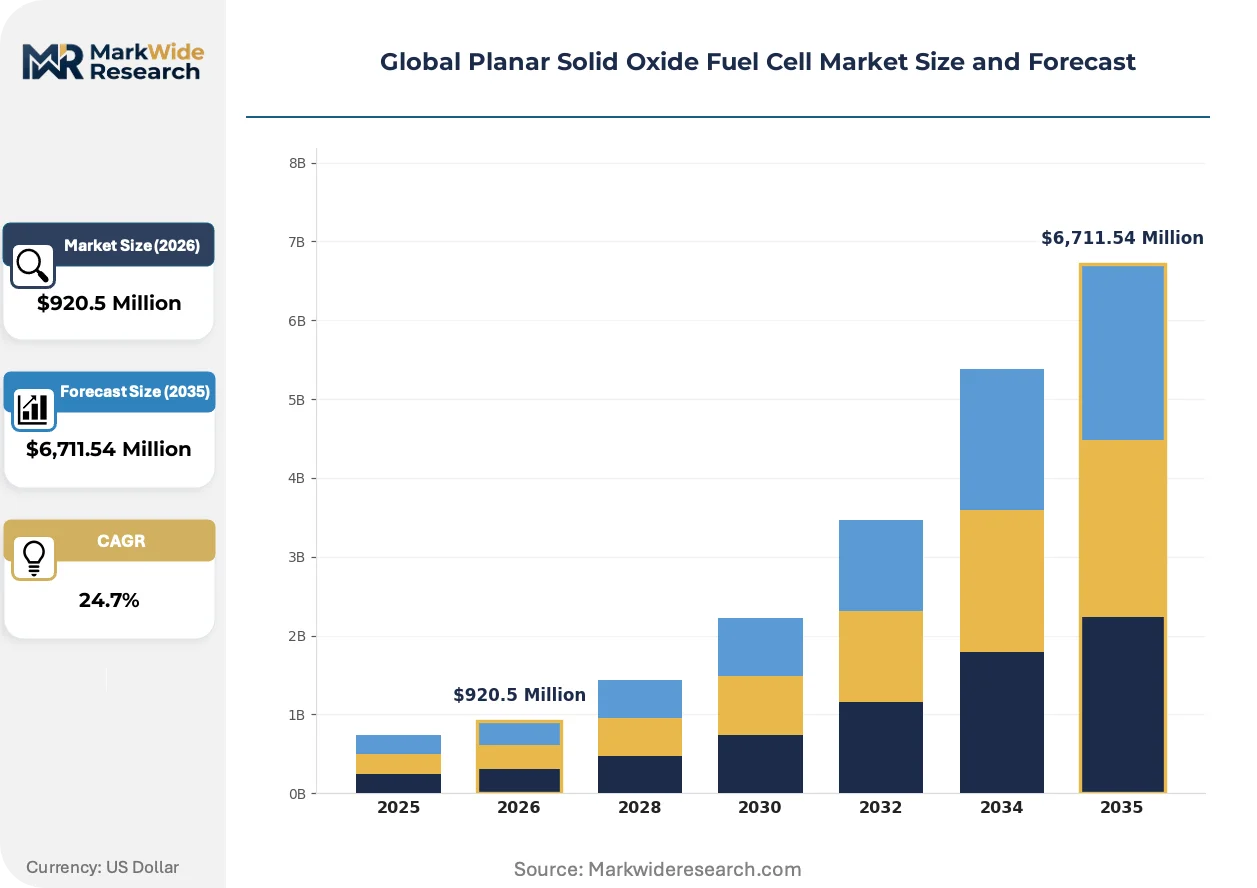
| Market Size in 2026 | $920.5 Million |
| Market Size in 2035 | $6,711.54 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Planar Stack, Monolithic Cell, Tubular Cell, Anode Supported Cell, Electrolyte Supported Cell Technology: Ceramic Electrolyte, Composite Electrolyte, Thin Film Technology, Microtubular Technology, Metal Supported Technology Application: Distributed Power Generation, Auxiliary Power Units, Residential Power, Commercial Power, Backup Power Systems End User Industry: Power Plants, Maritime Vessels, Aerospace Systems, Telecommunications, Industrial Manufacturing |
| Companies Covered | Mitsubishi Power, Ltd., Doosan Fuel Cell Co., Ltd., Bloom Energy Corp., SOLIDpower S.p.A., KYOCERA Corporation, Ceres Power Holdings, FuelCell Energy Inc., Elcogen, Aisin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Planar Solid Oxide Fuel Cell Market Strategic Shifts & Innovations
The market's evolution is defined by a transition from research-intensive development to commercially viable deployment at scale. This shift is driven by innovations in cell architecture, supportive regulatory frameworks, and new business models for asset deployment.
Steel-supported cell designs offer an alternative to traditional all-ceramic structures, providing enhanced mechanical robustness and tolerance to thermal cycling. Data center and heavy industry end-users are adopting this technology through strategic licensing partnerships with specialized developers. This innovation is miniaturizing the balance-of-plant components, thereby reducing the overall system footprint and installation complexity.
Incentives within the U.S. Inflation Reduction Act (IRA) provide substantial tax credits for clean power generation and domestic manufacturing of fuel cell components. This policy directly improves the economic case for SOFC installations by lowering their levelized cost of energy. The stationary power segment for commercial and utility-scale applications in the United States is responding by accelerating project financing and development.
A shift toward long-term Energy-as-a-Service (EaaS) agreements is altering procurement patterns away from direct capital equipment purchases. This model allows end-users to secure clean, reliable power with no upfront cost, paying only for the energy consumed. This trend is most visible in the United States and South Korea for large-scale commercial and industrial power consumers.
Global Planar Solid Oxide Fuel Cell Market Segmentation
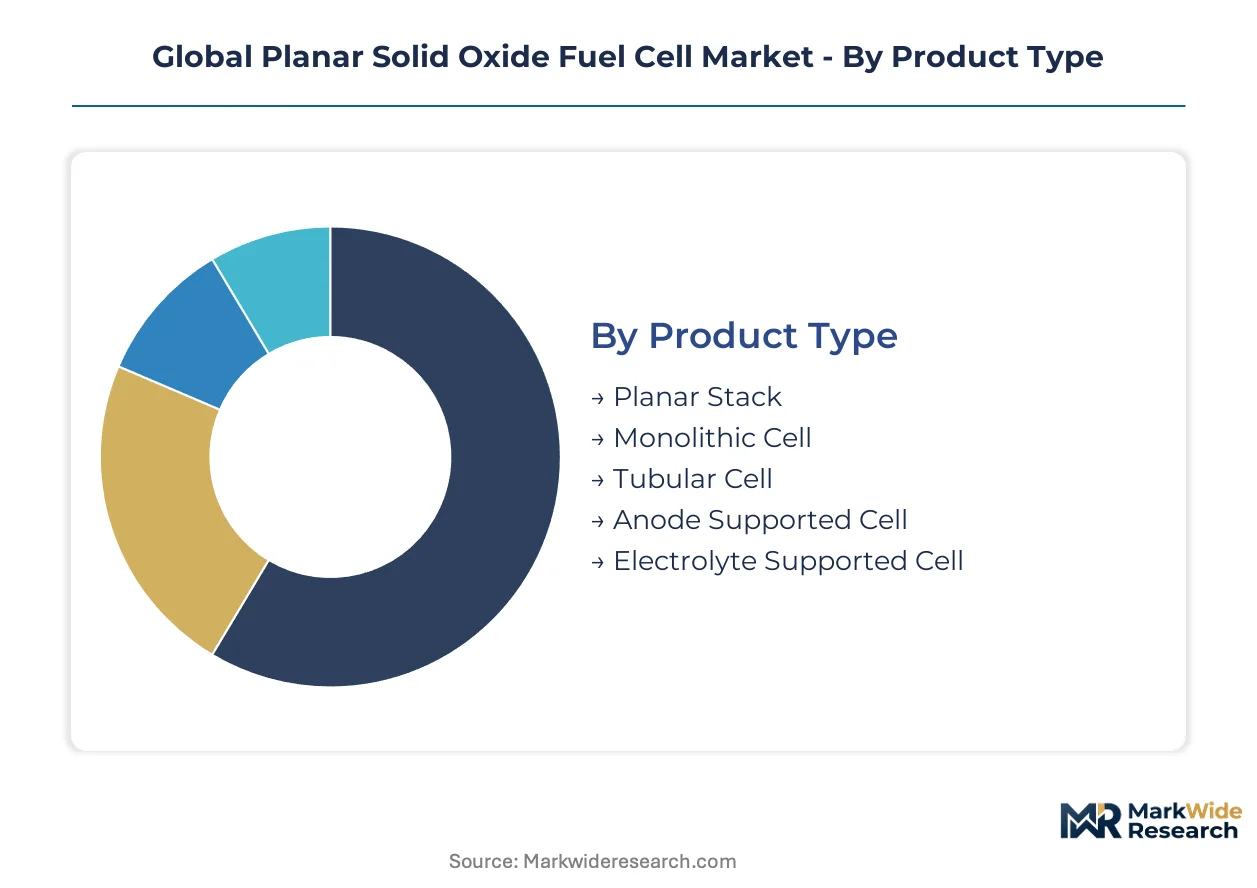
The global planar solid oxide fuel cell market's segmentation reflects diverse technological approaches and end-use requirements for clean power generation. Different product architectures and material compositions address varying operational demands and cost sensitivities across industrial and commercial applications. Understanding these segments is crucial for strategic market entry and product development.
Product Type:
Product type segments face varying substitution pressures from alternative fuel cell designs and conventional power sources.
- Planar Stack:This design features flat, plate-like components, optimizing power density and manufacturing scalability. Demand concentrates in large-scale distributed power generation in the United States, driven by high electrical efficiency requirements.
- Anode Supported Cell:Characterized by a thick, porous anode that provides mechanical support and reduces electrolyte thickness, enhancing performance at lower operating temperatures. Data centers in South Korea increasingly adopt these cells for their robust and efficient on-site power.
- Monolithic Cell:This compact design integrates all cell components into a single ceramic block, aiming for high power density.
- Tubular Cell:Featuring a cylindrical design, this cell offers enhanced mechanical robustness and resistance to thermal cycling.
- Electrolyte Supported Cell:A traditional design where the dense ceramic electrolyte provides structural integrity, often requiring higher operating temperatures.
Planar Stack retains volume leadership; Anode Supported Cell holds the steepest expansion curve.
Technology:
Technology segments are differentiated by their maturity levels and the associated risks in commercial deployment.
- Ceramic Electrolyte:Typically composed of yttria-stabilized zirconia (YSZ), this foundational technology facilitates ion transport at high temperatures. Its established reliability supports large-scale power plant installations globally.
- Metal Supported Technology:This innovative approach uses a metallic support structure, offering superior mechanical robustness and rapid thermal cycling capability. Data centers in Europe are exploring this technology for its resilience and compact footprint.
- Composite Electrolyte:Combining multiple materials, this technology aims to optimize ionic conductivity and reduce operating temperatures.
- Thin Film Technology:Utilizing extremely thin layers of materials, this technology seeks to minimize material usage and improve power density.
- Microtubular Technology:This design employs very small diameter tubes, offering enhanced thermal cycling capabilities for specific niche applications.
Cost optimization remains a critical factor, with Metal Supported Technology offering significant advancements in system integration.
Application:
Application segments are primarily driven by the volume of electricity required and the criticality of uninterrupted power.
- Distributed Power Generation:These systems provide on-site electricity directly where it is consumed, reducing transmission losses. Industrial facilities in Germany utilize this application for energy independence and grid stability.
- Auxiliary Power Units:These units generate power for non-propulsive functions in vehicles or vessels, reducing engine idling and emissions. The maritime sector is a significant adopter for meeting IMO emissions regulations.
- Residential Power:Small-scale systems provide electricity for homes, often integrated with renewable energy sources.
- Commercial Power:Fuel cells supply electricity to businesses, offering reliable and clean energy solutions.
- Backup Power Systems:These systems ensure continuous power supply during grid outages for critical infrastructure.
Efficiency gains are paramount, with Distributed Power Generation leading in overall energy conversion.
End User Industry:
End-user industry segments are heavily influenced by sector-specific regulatory frameworks and decarbonization mandates.
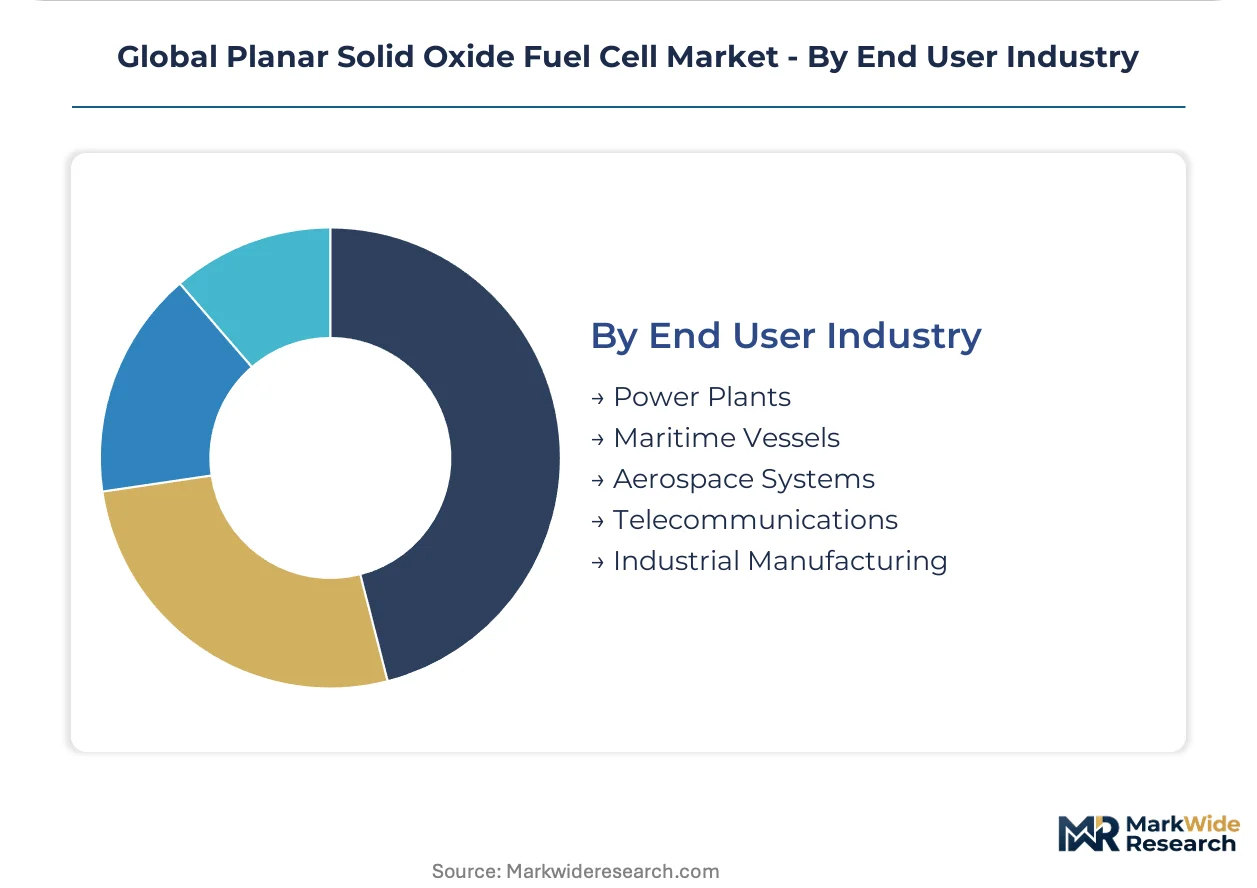
- Power Plants:Large-scale installations integrate SOFCs for grid-level electricity generation, supporting grid stability and decarbonization. The U.S. Inflation Reduction Act incentivizes these deployments for clean power.
- Maritime Vessels:SOFCs provide auxiliary power or propulsion for ships, helping the shipping industry meet stringent emissions targets. International Maritime Organization (IMO) regulations drive this adoption.
- Industrial Manufacturing:Fuel cells supply reliable, clean power to factories, reducing operational emissions and energy costs.
- Telecommunications:Critical infrastructure like cell towers use SOFCs for reliable backup power in remote locations.
- Aerospace Systems:Niche applications in aircraft or spacecraft utilize fuel cells for efficient, lightweight power generation.
Strategic partnerships are shaping the landscape, particularly in Power Plants and Maritime Vessels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The U.S. Inflation Reduction Act (IRA) significantly shapes the global planar solid oxide fuel cell market. This legislation provides substantial tax credits for clean power generation and domestic fuel cell manufacturing. Such policies accelerate project financing and development for stationary power applications.
United States
Demand for distributed power generation and data center reliability drives SOFC adoption. The U.S. Inflation Reduction Act (IRA) offers direct support for clean energy deployments. California's Silicon Valley sees increased interest for on-site, low-emission power solutions within its tech infrastructure.
South Korea
Government incentives strongly support fuel cell installations for commercial and utility-scale power. Policies from the Ministry of Trade, Industry and Energy (MOTIE) promote hydrogen and fuel cell technology. The Gyeonggi province, a prominent manufacturing hub, focuses on advanced fuel cell production and deployment.
Germany
Industrial decarbonization targets and grid stability requirements propel SOFC demand. The EU Green Deal provides a comprehensive framework for clean energy transition across Europe. Bavaria's industrial sector explores SOFCs for energy independence and reduced operational emissions.
Japan
National energy strategies promote hydrogen and fuel cell technology for diverse applications. The Ministry of Economy, Trade and Industry (METI) actively supports research and commercialization efforts. Tokyo's metropolitan area investigates SOFCs for resilient and clean urban power infrastructure.
India
Distributed power generation in areas with unreliable grids represents a significant opportunity. The National Green Hydrogen Mission aims to foster clean energy ecosystems. Gujarat, with its expanding industrial corridors, is a potential hub for SOFC integration in manufacturing facilities.
Global Planar Solid Oxide Fuel Cell Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the planar solid oxide fuel cell market. This tiered structure reflects varying capabilities in material science and system integration. Strategic archetypes include large industrial conglomerates, specialized fuel cell developers, and component manufacturers. Dominant competitive moves involve technology licensing agreements and strategic partnerships for market penetration.
Specialized fuel cell developers like Bloom Energy Corp. exemplify the push for proprietary solid oxide technology, often targeting large-scale stationary power applications. Ceres Power Holdings represents a key player differentiating through its steel-cell technology, frequently engaging in strategic licensing partnerships for data centers and commercial buildings. Doosan Fuel Cell Co., Ltd., a South Korea-based entity, sits within the archetype of national industrial players contributing to domestic and international clean energy initiatives.
| Leading Market Players |
|---|
| Mitsubishi Power, Ltd. |
| Doosan Fuel Cell Co., Ltd. |
| Bloom Energy Corp. |
| SOLIDpower S.p.A. |
| KYOCERA Corporation |
| Ceres Power Holdings |
| FuelCell Energy Inc. |
| Elcogen |
| Aisin Corporation |
| Others |
Cost & Logistics Intelligence
The U.S. Inflation Reduction Act (IRA) directly gates supply qualification and price differentiation for planar solid oxide fuel cells, influencing domestic manufacturing incentives and project costs. This legislation creates distinct pricing advantages for U.S.-based production, impacting the global competitive landscape. Supply concentration in critical raw materials further shapes the market's cost structure.
Pricing Analysis
Geographic price spreads for planar solid oxide fuel cells vary significantly, influenced by regional subsidies and local manufacturing capabilities. Project-based pricing dominates for large-scale installations, while licensing agreements define technology transfer costs for specialized components. Price differentiation stems from technology maturity, such as ceramic electrolyte versus advanced metal-supported designs, and the extent of after-sales service and maintenance contracts. Pricing pressure intensifies due to the high material costs of rare earth elements, particularly for anode-supported cells. Data centers and utility-scale power plants, requiring high reliability and efficiency, exhibit lower price sensitivity than smaller commercial or residential applications.
Supply Chain Analysis
Concentration of high-purity ceramic powder production, essential for yttria-stabilized zirconia electrolytes, creates a chokepoint in the planar solid oxide fuel cell supply chain. Key material suppliers are primarily located in China for rare earth elements like yttria and scandia, alongside specialized manufacturing equipment from Germany and Japan. The industry relies heavily on these critical raw materials and highly specialized manufacturing equipment, leading to potential single-source vulnerability. Logistics chokepoints, particularly for delicate ceramic components, also pose a structural risk. Downstream distribution runs predominantly through direct sales channels for large industrial and power plant projects, complemented by strategic licensing partnerships for broader market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The planar solid oxide fuel cell market presents a fragmentation opportunity, driven by the increasing demand for decentralized, reliable power generation solutions in diverse industrial and commercial settings.
For Market Incumbents:Shield proprietary solid oxide technology through continuous R&D investments in advanced materials and manufacturing processes. Consolidate market share by expanding long-term service agreements for existing installations, mitigating the threat from emerging alternative clean energy technologies. Pursue vertical integration into critical component manufacturing, particularly for high-temperature ceramic materials, to secure supply chains and manage costs. Invest in capacity additions within key growth geographies like South Korea to leverage national hydrogen strategies.
For New Entrants and Emerging Players:Certification fast-track programs, such as those encouraged by the EU Green Deal, offer a strategic entry point for novel planar SOFC designs. Target underpenetrated niche applications, including auxiliary power units in the maritime sector or remote distributed power for unreliable grids in India. Develop specialized metal-supported cell technologies for rapid thermal cycling capabilities, appealing to data centers requiring robust on-site power. A go-to-market strategy focused on strategic licensing partnerships with established industrial players can accelerate market access and reduce capital expenditure.
For Investors and Strategic Acquirers:Carve-out targets emerge from industrial conglomerates divesting non-core energy divisions, presenting opportunities for focused investment in planar SOFC technology. The long-term viability of the market is anchored in global decarbonization mandates and the need for non-intermittent clean power. Focus on specialized SOFC developers with strong intellectual property in advanced materials or system integration capabilities. A key signal to watch for inflection is the increased adoption of Energy-as-a-Service (EaaS) models for large-scale commercial and industrial deployments.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Material R&D Investment | Enhances cell durability and efficiency, reducing the total cost of ownership for power plant operators. |
| Strategic Licensing Partnerships | Accelerates market penetration for specialized developers, particularly in data centers and industrial facilities. |
| Vertical Integration into Ceramic Production | Secures supply chains for critical raw materials like yttria and scandia, stabilizing manufacturing costs. |
| Expansion in Marine Auxiliary Power | Addresses stringent IMO emissions regulations, opening a significant growth vector for maritime vessels. |
| Energy-as-a-Service Model Adoption | Lowers upfront costs for end-users, driving wider adoption in commercial and utility-scale applications. |
Research Approach
The analysis maps key sub-sectors, including distributed power generation, marine auxiliary power, and industrial manufacturing, each validated through extensive primary interviews. These discussions included power plant operators, marine engineers, industrial facility managers, and material scientists. Secondary data sources encompassed IEA reports, national energy agency statistics, corporate annual reports, and technical journals. A rigorous bottom-up and top-down triangulation approach ensured data consistency and accuracy.
Model outputs underwent rigorous consistency checks against reported historical deployments and national energy roadmaps to validate projections across the analysis window. The analytical framework incorporated segmentation dimensions such as product type, technology, application, end-user industry, and regional policy frameworks. Compound annual growth rates were derived by integrating historical performance trends with future market drivers. Key forecast inputs included raw material price trends and evolving regulatory incentive levels, particularly the U.S. Inflation Reduction Act.
The analysis sits within stated boundaries; outcomes outside significant geopolitical shifts affecting raw material supply or rapid technological breakthroughs by alternative clean energy solutions would require recalibration. Forecasts reflect assumptions regarding continued policy support and material science advancements. Practitioners should keep alternative scenarios live as global energy policies and material costs evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuel Cell Technology
Bipolar Plate Coatings Market
Fuel Cell Technology
Hydrogen Fuel Cell Stack and Membrane Recycling for EU Mobility Market
Fuel Cell Technology
Helium Recovery Systems Market
Fuel Cell Technology
North America Fuel Cell Technology Market
Fuel Cell Technology
Fuel Cell Technology Market
Fuel Cell Technology
Japan Fuel Cell Market
Fuel Cell Technology
Global Fuel Cell Balance of Plant (BOP) Market
Fuel Cell Technology
France Fuel Cell Market
Fuel Cell Technology
Fuel Cell for Stationary Power Market
Fuel Cell Technology
PEM Electrolyzer Market
Fuel Cell Technology
Europe Direct Methanol Fuel Cell Market
Fuel Cell Technology
Hydrogen Fuel Cell Stack Durability and Performance Test Equipment Market
Fuel Cell Technology
Fuel Vending Machines Market
Fuel Cell Technology
Fuel Cell Interconnectors Market
Fuel Cell Technology
Fuel Cells for Marine Vessels Market
Fuel Cell Technology
Portable Fuel Cells Market