
 France Fuel Cell Market | 2026-2036
France Fuel Cell Market Size, Share, and Industry Trends Forecast 2026-2036
France Fuel Cell Market Foresight
Fleet operators in warehousing and municipal transit are unwinding reliance on diesel backup generators, redirecting procurement toward proton exchange membrane systems for material handling and stationary power. Symbio Fcell SA dominates integration partnerships with French automotive OEMs. Ballard Power Systems Inc. leverages its heavy-duty module expertise to anchor long-haul truck pilots. Plug Power Inc. sustains its position in material handling through direct sales to logistics hubs near Lyon and Lille.
A fuel cell electrochemically converts hydrogen and oxygen into electricity, with proton exchange membrane variants operating at 60-80°C using a perfluorinated sulfonic acid electrolyte to deliver 40-60% electrical efficiency for vehicular and stationary applications. Solid oxide systems occupy the highest-temperature tier at 600-1000°C and suit utility-scale combined heat and power where waste heat recovery improves total system efficiency. Portable power and telecommunications backup segments are expanding fastest as off-grid reliability requirements intensify for emergency services and rural network infrastructure.
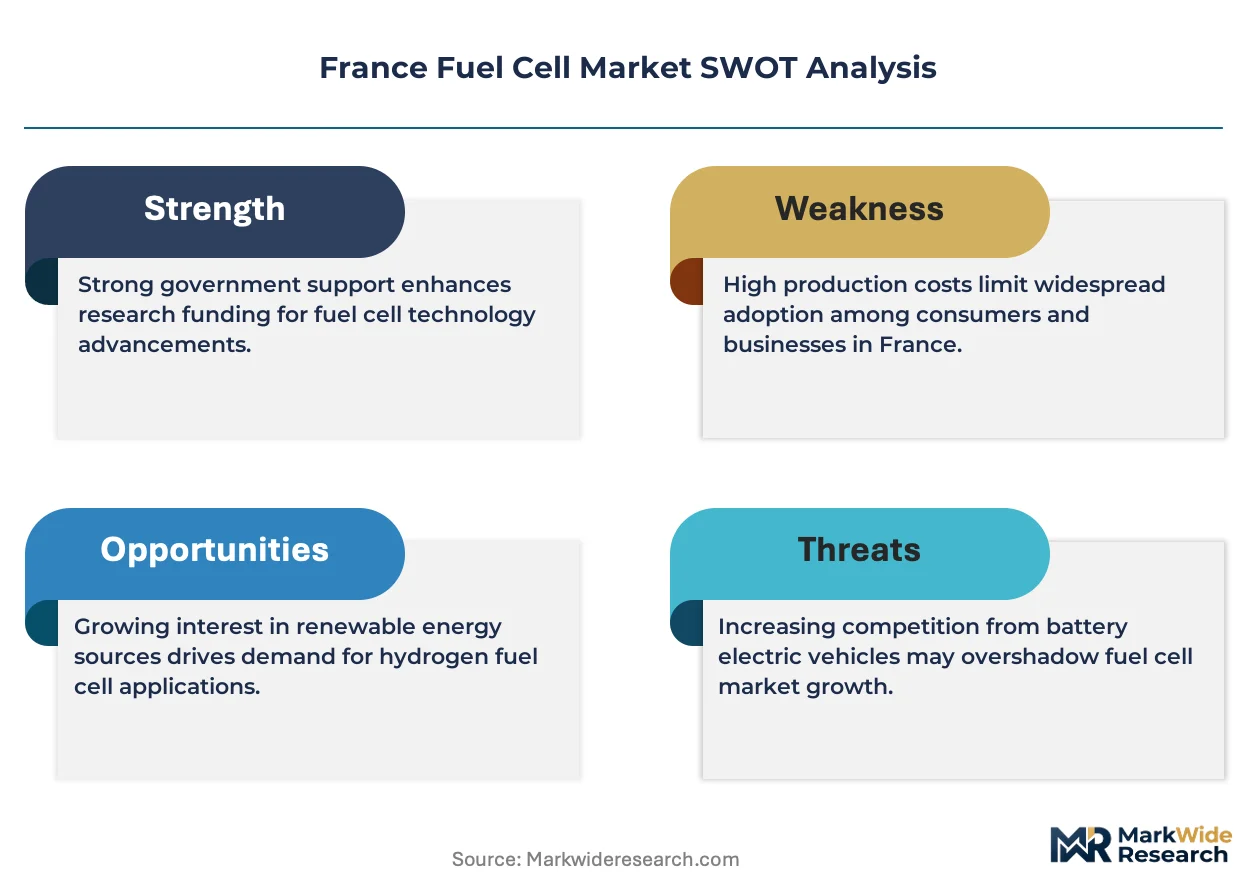
France's national hydrogen strategy aligns with EU Green Deal funding mechanisms and REPowerEU targets, while ANSM oversees hydrogen purity standards for transport applications and the French Environment and Energy Management Agency channels subsidies toward electrolyzer deployment. The EU AI Act and emerging digital twin requirements for energy assets will shape certification pathways for intelligent fuel cell management systems. Stakeholders must monitor how the EU's forthcoming hydrogen bank auction structures and France's carbon border adjustments reshape cost competitiveness against imported fuel cell stacks.
Market Dynamics
The France Fuel Cell Market is experiencing structural pressure from the EU Green Deal's binding decarbonization mandates, which force heavy-duty transport and industrial power users toward hydrogen alternatives ahead of cost parity with diesel or grid electricity.
Growth Catalysts
- EU Green Deal funding mechanisms:REPowerEU targets channel public capital into electrolyzer manufacturing clusters across the Rhône-Alpes corridor, lowering hydrogen production costs for captive fuel cell users.
- Heavy-duty fleet electrification:Logistics operators near Lyon and Lille are unwinding diesel backup generator contracts in favor of proton exchange membrane systems for material handling and stationary power.
- Perfluorinated sulfonic acid electrolyte advances:Improved membrane durability at 60-80°C operating temperatures extends vehicular fuel cell stack life, reducing total cost of ownership for municipal transit procurement.
Market Restraints
- Platinum group metal input volatility:Fuel cell catalyst costs fluctuate with South African and Russian mining supply disruptions, compressing stack manufacturer margins.
- Hydrogen distribution infrastructure gaps:Limited high-pressure refueling stations along Atlantic and Mediterranean freight corridors strand long-haul truck pilots in depot-bound routes.
- Grid electricity price competition:Nuclear baseload power in France undercuts green hydrogen economics for stationary backup applications below 100kW scale.
Strategic Opportunities
- Portable power for emergency services:Off-grid reliability requirements in rural Auvergne and Corsica create demand for solid oxide systems in telecommunications backup.
- ANSM hydrogen purity standard alignment:Certification to transport-grade H2 specifications opens material handling equipment exports to Benelux markets.
- Digital twin convergence with fuel cell management:EU AI Act compliance pathways for intelligent monitoring systems differentiate French stack integrators in EU-wide tenders.
Industry Challenges
- Electrolyzer technician skill gaps:Shortage of certified installers for alkaline and PEM electrolysis equipment delays project commissioning in Greater Paris transit networks.
- CE marking timeline compression:Emerging CSRD disclosure requirements for energy assets extend fuel cell system certification cycles by 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Fuel Cell Market |
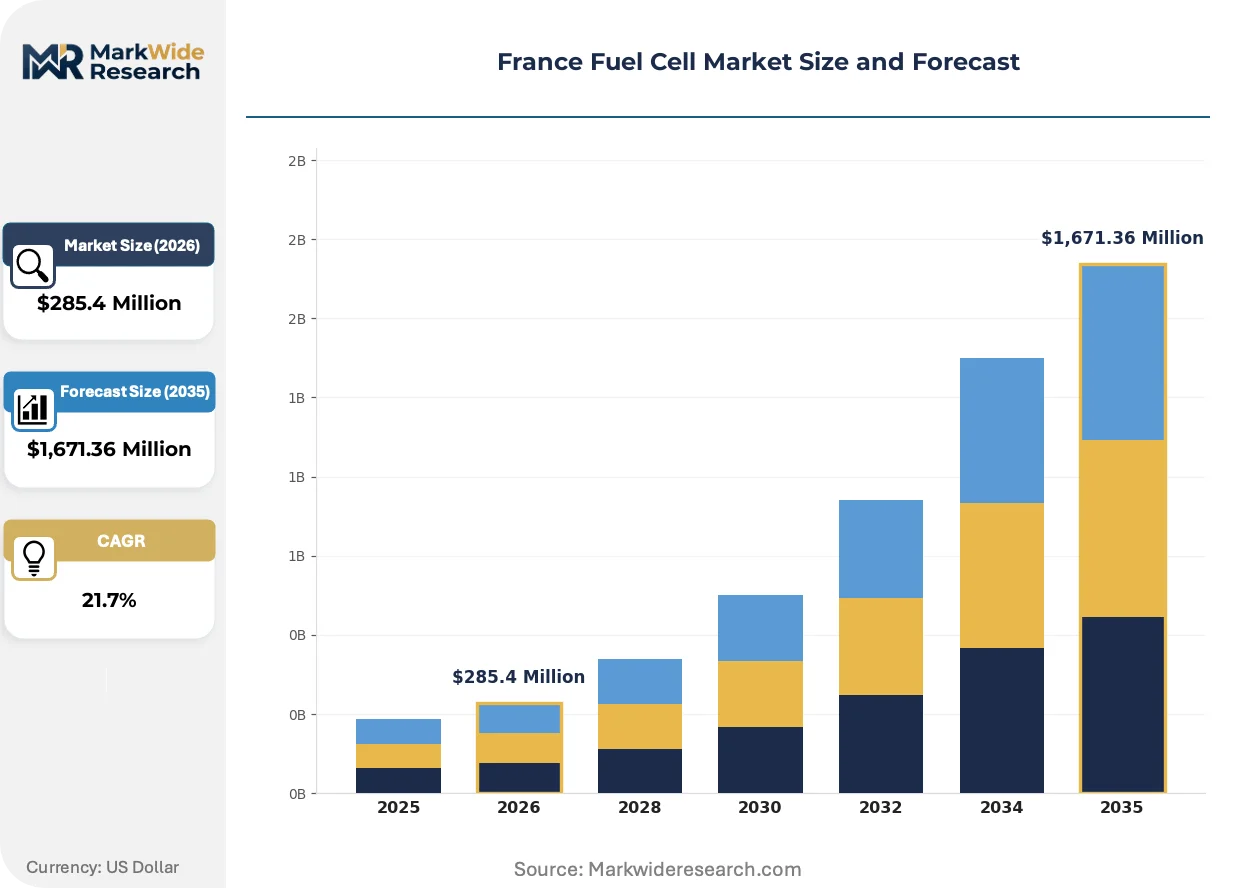
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $1,671.36 Million |
| CAGR (2026 – 2036) | 21.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proton Exchange Membrane, Solid Oxide, Phosphoric Acid, Molten Carbonate Application: Residential Power, Portable Power, Telecommunications Backup, Material Handling Equipment End User: Utilities, Warehousing Operations, Emergency Services, Telecommunications Providers Distribution Channel: Direct Sales, Online Platforms, Authorized Dealers, Energy Solution Providers |
| Companies Covered | Symbio Fcell SA, Ballard Power Systems Inc., FuelCell Energy Inc., Plug Power Inc., Powercell Sweden AB, SFC Energy AG, Ceres Power Holdings plc, Bloom Energy Corporation, Nuvera Fuel Cells LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Fuel Cell Market Shifts & Advancements
Fuel cell architecture is diverging by application temperature and scale, with proton exchange membrane variants consolidating transport while solid oxide systems capture utility-scale combined heat and power.
Stack design is fragmenting across three thermal tiers. Proton exchange membrane fuel cells operating at 60-80°C dominate material handling and municipal bus procurement in Lyon and Paris. Solid oxide systems at 600-1000°C target industrial CHP where waste heat recovery improves total efficiency. Alkaline electrolysis paired with these stacks is concentrating manufacturing investment in Grenoble and Belfort.
France's national hydrogen strategy aligns subsidy allocation with REPowerEU auction structures, directing ADEME funding toward electrolyzer deployment rather than downstream fuel cell stack production. This policy sequencing favors integrated energy companies with captive hydrogen supply over pure-play fuel cell vendors. Heavy-duty truck pilots now face revised carbon border adjustment calculations that penalize imported stack components.
Logistics procurement teams are consolidating vendor relationships around performance-guaranteed service contracts rather than equipment ownership. Warehousing operators near Lille now specify fuel cell uptime commitments in forklift fleet agreements. This shift compresses supplier margins while locking in long-term hydrogen offtake arrangements with industrial gas distributors.
France Fuel Cell Market Segmentation
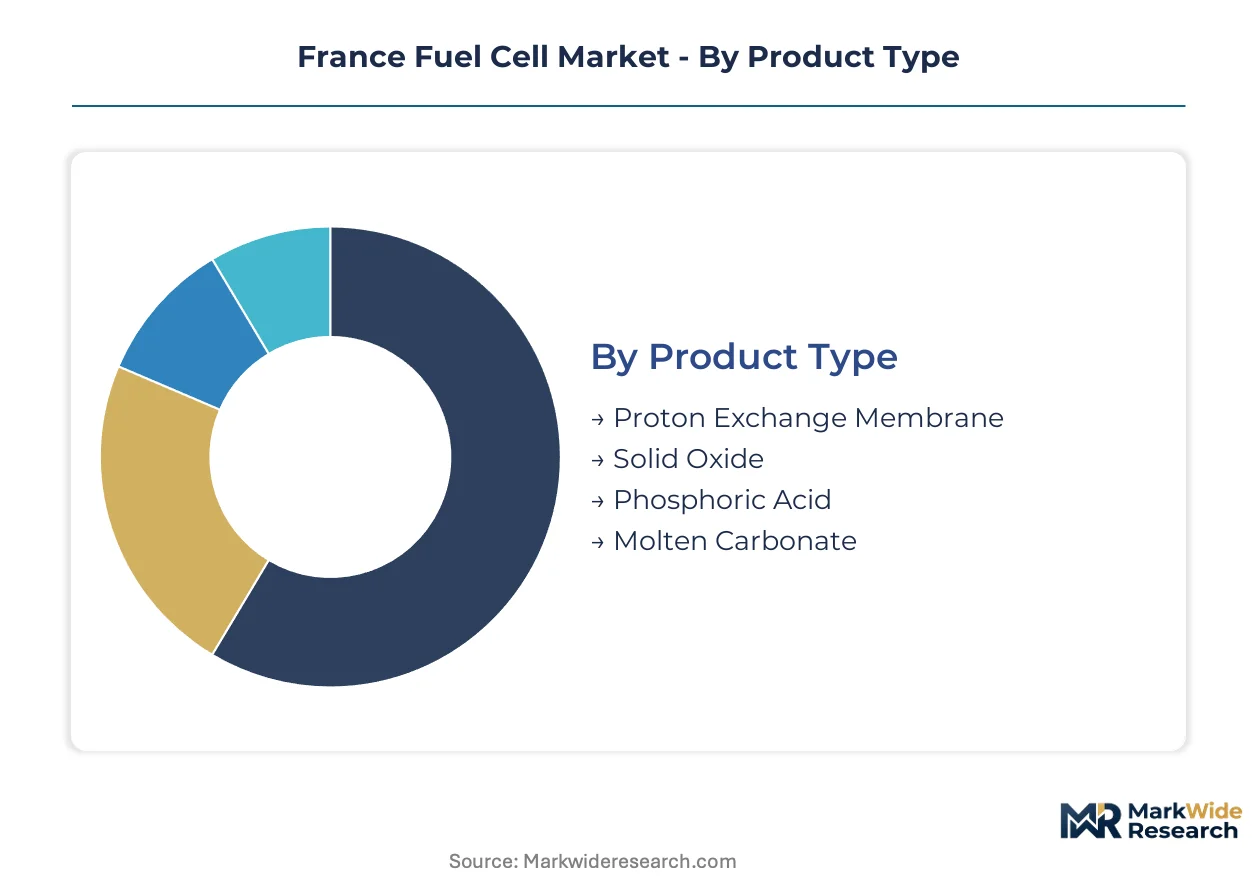
Fuel cell procurement in France fragments across thermal performance tiers and operational scale requirements. Channel selection varies sharply by application maturity and customer technical sophistication.
Product Type:
Channel mix diverges by operating temperature and integration complexity, with low-temperature variants flowing through equipment distributors while high-temperature systems require direct manufacturer engagement.
- Proton Exchange Membrane:These systems operate at 60-80°C using perfluorinated sulfonic acid electrolyte membranes to deliver 40-60% electrical efficiency. Municipal bus fleets in Greater Paris and material handling operators near Lyon procure through authorized dealers with service contracts. ADEME subsidies channel procurement toward French-assembled stacks.
- Solid Oxide:Operating at 600-1000°C, these ceramic-electrolyte systems suit industrial combined heat and power where waste heat recovery improves total system efficiency. Rhône-Alpes chemical processors and Auvergne district heating networks source through energy solution providers with long-term hydrogen supply agreements.
- Phosphoric Acid:Molten phosphoric acid electrolyte at 150-200°C serves stationary commercial backup with moderate efficiency. Telecommunications providers in Corsica deploy these through direct sales channels for remote cell tower reliability.
- Molten Carbonate:Carbonate salt electrolyte at 650°C targets utility-scale generation above 100kW. Limited deployment concentrates in pilot projects near Belfort manufacturing clusters.
Proton Exchange Membrane dominates installed base. Solid Oxide is where expansion concentrates.
Application:
Cost tier stratification separates premium industrial backup from economy residential units, with pricing scaling directly by thermal output and redundancy requirements.
- Residential Power:Sub-10kW systems for single-family homes in rural Auvergne and Corsica. Grid electricity price competition from nuclear baseload limits adoption to off-grid properties.
- Portable Power:Compact sub-kW units for emergency services field operations. Gendarmerie and Sécurité Civile procurement concentrates through defense contractors with ruggedization specifications.
- Telecommunications Backup:5-50kW stationary systems replacing diesel generators at cell towers. Orange and SFR specify 72-hour autonomy for Mediterranean coastal infrastructure exposed to grid instability.
- Material Handling Equipment:Forklift and pallet jack power systems dominate warehouse electrification near Lille and Lyon. Logistics operators specify performance-guaranteed uptime contracts rather than equipment purchase.
Material Handling Equipment captures the steepest expansion trajectory. Telecommunications Backup holds the largest contracted backlog.
End User:
Customer technical maturity determines procurement channel, with sophisticated operators specifying integrated hydrogen supply while smaller users rely on turnkey solutions.
- Utilities:EDF and Engie subsidiaries pilot solid oxide CHP at industrial sites. Procurement flows through energy solution providers with captive electrolyzer partnerships.
- Warehousing Operations:Carrefour Supply Chain and Geodis facilities near Lyon specify fuel cell forklift fleets. Direct sales relationships with stack integrators include hydrogen offtake arrangements.
- Emergency Services:SAMU and fire service commands in rural departments procure portable power through defense procurement frameworks with interoperability requirements.
- Telecommunications Providers:Orange, SFR, and Bouygues Telecom standardize backup specifications through centralized procurement with authorized dealer networks for installation.
Warehousing Operations lead volume deployment. Emergency Services are climbing the fastest as rural resilience mandates tighten.
Distribution Channel:
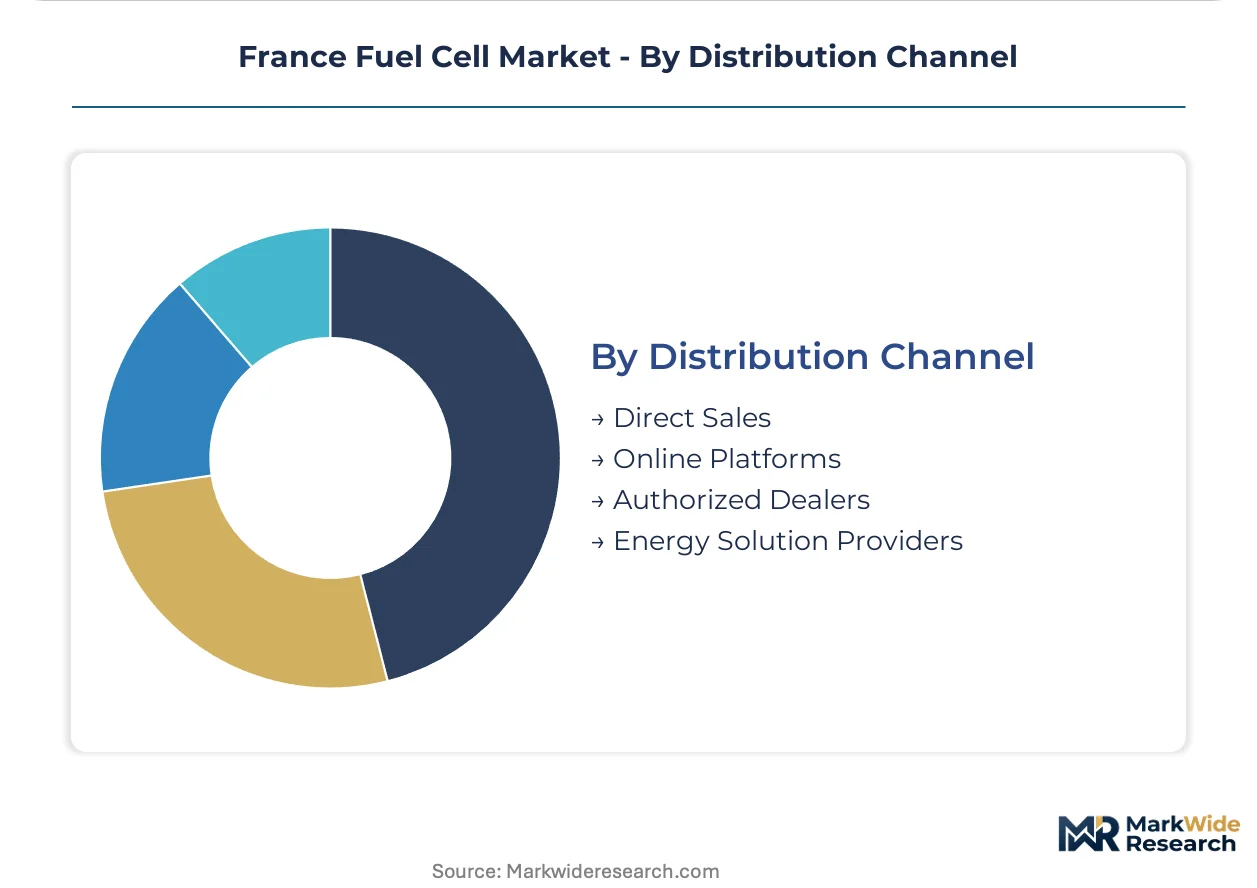
Supply concentration in Grenoble and Belfort manufacturing clusters shapes regional channel availability, with direct access privileging large-volume accounts.
- Direct Sales:Major utilities and national logistics operators negotiate stack supply and hydrogen offtake as bundled contracts. Symbio Fcell SA and Ballard Power Systems anchor these relationships with dedicated account teams.
- Online Platforms:Limited to spare parts, membranes, and small portable units below 5kW. B2B procurement portals serve municipal procurement offices with simplified tender compliance.
- Authorized Dealers:Regional equipment distributors in Lyon, Lille, and Paris maintain service technician networks for material handling and bus fleet maintenance. ANSM certification requirements limit dealer authorization.
- Energy Solution Providers:Integrated hydrogen project developers bundle electrolyzer, storage, and fuel cell deployment. These channels concentrate in Rhône-Alpes with ADEME subsidy coordination.
Authorized Dealers dominate installed base. Energy Solution Providers are gaining share fastest as integrated hydrogen projects scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Fos-sur-Mer hydrogen import terminal anchors France's role in European fuel cell supply chains, channeling electrolyzer feedstock to industrial clusters along the Mediterranean coast.
Germany
Heavy-duty truck manufacturers in Baden-Württemberg are accelerating fuel cell module procurement for long-haul decarbonization pilots. The KBA enforces stringent type-approval protocols for hydrogen-powered commercial vehicles entering cross-border service. Manufacturing investment clusters around Stuttgart and Munich, where automotive OEMs integrate Ballard-derived stacks into prototype tractor-trailers.
Netherlands
Rotterdam Port Authority's hydrogen backbone pipeline is drawing fuel cell backup system orders from data center operators seeking grid independence. The Dutch Environment and Transport Inspectorate aligns maritime hydrogen safety rules with EU Green Deal implementation timelines. Equipment distributors in Eindhoven are expanding service technician networks for PEM forklift fleets.
Spain
Solar-to-hybrid projects in Extremadura are pairing alkaline electrolyzers with fuel cell buffers for 24-hour renewable dispatch. The Spanish Ministry for Ecological Transition channels NextGenerationEU funds toward hydrogen valley development. Industrial gas distributors near Barcelona are signing long-term hydrogen offtake contracts with material handling operators.
Belgium
Antwerp's chemical processing corridor is deploying solid oxide systems for combined heat and power at chlor-alkali plants. The Federal Agency for Nuclear Control coordinates hydrogen safety standards with neighboring jurisdictions. Engineering firms in Ghent are packaging fuel cell modules with captive electrolyzer supply for port logistics applications.
Italy
Milan's fashion logistics hub is specifying fuel cell material handling equipment to meet Scope 3 emissions targets. The Ministry of Environment and Energy Security administers hydrogen IPCEI project selection with French cross-border coordination. System integrators in Turin are adapting automotive fuel cell architectures for warehouse automation.
France Fuel Cell Market Competitive Landscape
Concentration sits with integrated stack-and-system providers that bundle hydrogen supply with equipment deployment. The vendor base stratifies across three tiers: multinational module suppliers with dedicated French account teams, regional integrators leveraging ADEME subsidy coordination, and specialized service contractors for fleet maintenance. Competitive positioning depends on electrolyzer partnerships and long-term uptime guarantee structures. Market participants are pursuing backward integration into membrane manufacturing and geographic anchoring through Rhône-Alpes production facilities.
Among North American-listed suppliers, Ballard Power Systems Inc. and Plug Power Inc. exemplify contrasting archetypes—the former anchoring heavy-duty vehicle integration partnerships, the latter dominating material handling fleet turnover. Symbio Fcell SA occupies a distinctive position as a France-based integrator with automotive OEM relationships. These three entities represent the spectrum from pure module supply to full-service hydrogen ecosystem deployment.
| Leading Market Players |
|---|
| Symbio Fcell SA |
| Ballard Power Systems Inc. |
| FuelCell Energy Inc. |
| Plug Power Inc. |
| Powercell Sweden AB |
| SFC Energy AG |
| Ceres Power Holdings plc |
| Bloom Energy Corporation |
| Nuvera Fuel Cells LLC |
| Others |
Supply & Pricing Matrix
CE marking and ANSM hydrogen purity certification gate both stack qualification and price differentiation simultaneously, forcing vendors to absorb compliance costs upfront while tiering offerings by membrane grade and service bundling.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations, with municipal bus fleets and national logistics operators securing 15-25% reductions against list pricing through multi-year hydrogen offtake commitments. Price differentiation hinges on membrane durability guarantees and geographic service density, with Rhône-Alpes-based integrators commanding premiums for localized technician networks. Cost compression in the sub-100kW stationary backup segment is intensifying because nuclear baseload power undercuts green hydrogen economics. Small warehousing operators in peripheral regions exhibit highest price sensitivity, while EDF and Engie subsidiaries prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Platinum group metal sourcing from South Africa and Russia anchors raw material vulnerability, with catalyst cost volatility compressing stack manufacturer margins during supply disruptions. Manufacturing concentrates in Germany, Japan, and South Korea for membrane electrode assemblies, while France's Grenoble and Belfort clusters handle final system integration. The supply chain rests on perfluorinated sulfonic acid membrane imports and high-pressure carbon fiber tank fabrication from specialized European suppliers. Single-source vulnerability in electrolyzer stack assembly creates commissioning delays for Greater Paris transit projects. Distribution runs through authorized dealer networks for material handling fleets and direct manufacturer engagement for utility-scale deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent fuel cell vendors face substitution defense against battery-electric alternatives in sub-200km logistics routes, where improving lithium-ion energy density threatens hydrogen's range advantage in medium-duty applications.
For Market Incumbents: Fortify membrane supply security through backward integration into perfluorinated sulfonic acid production or captive partnerships with Solvay-grade suppliers. Lock in municipal transit procurement through 10-year service contracts that bundle stack replacement with hydrogen delivery, neutralizing battery-electric total-cost-of-ownership comparisons. Prioritize Rhône-Alpes production footprint expansion to capture ADEME subsidy allocation tied to domestic manufacturing.
For New Entrants and Emerging Players: Anchor in Corsica and rural Auvergne telecommunications backup, where grid instability and diesel generator bans create urgent replacement demand with limited incumbent presence. Target solid oxide system deployment for district heating networks in medium-sized cities outside Lyon-Paris corridors, where integrated energy companies lack localized service density. Pursue defense procurement frameworks for Sécurité Civile portable power specifications, leveraging ruggedization requirements as competitive moats.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automotive Tier 1 suppliers holding fuel cell integration capabilities but lacking captive hydrogen infrastructure. Five-to-ten year viability hinges on electrolyzer cost curves and carbon border adjustment enforcement against imported Asian stacks. Monitor EU hydrogen bank auction clearing prices as the inflection signal for project finance viability and downstream equipment demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Electrolyzer Manufacturing Partnership | ADEME subsidy capture requires captive hydrogen supply for fuel cell system bundling. |
| Membrane Durability Guarantee Extension | Perfluorinated sulfonic acid stack life commitments differentiate municipal transit tenders. |
| Rhône-Alpes Production Footprint Expansion | Proximity to Grenoble-Belfort clusters reduces logistics costs for French OEM integration. |
| Digital Twin Platform Development | EU AI Act compliance for intelligent fuel cell management opens cross-border tender access. |
| Hydrogen Purity Certification Investment | ANSM transport-grade H2 alignment enables Benelux material handling equipment exports. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ADEME subsidy disbursement records, EU hydrogen bank auction documentation, and SEC filings from North American-listed fuel cell suppliers. Interviews with electrolyzer project developers, municipal transit procurement officers, and industrial gas distribution managers informed demand-side validation. Trade data from French customs authorities and IEA hydrogen project databases anchored supply-side triangulation. Bottom-up stack deployment estimates and top-down hydrogen consumption projections were cross-referenced for convergence.
Segmentation dimensions modeled include fuel cell operating temperature tier, application scale, end-user technical sophistication, and distribution channel structure across the analysis window. CAGRs were derived from logistic diffusion curves fitted to announced project pipelines and historical deployment trajectories. Forecast inputs incorporated REPowerEU funding allocation schedules and carbon border adjustment implementation timelines without specifying enforcement dates.
Decision-makers should treat outputs as directional under continued EU Green Deal funding commitment and stable platinum group metal supply assumptions; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as battery-electric range improvements and grid electricity pricing reforms evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuel Cell Technology
Direct Methanol Fuel Cell Market
Fuel Cell Technology
Fuel Cells for CHP Application Market
Fuel Cell Technology
Membrane Electrode Assembly Market
Fuel Cell Technology
North America Microbial Fuel Cell Market
Fuel Cell Technology
Fuel Cell Interconnectors Market
Fuel Cell Technology
Global Fuel Cell Balance of Plant (BOP) Market
Fuel Cell Technology
Hydrogen Fuel Cells Market
Fuel Cell Technology
Hydrogen Fuel Cell Stack Durability and Performance Test Equipment Market
Fuel Cell Technology
Asia-Pacific Fuel Cell Market
Fuel Cell Technology
Global Planar Solid Oxide Fuel Cell Market
Fuel Cell Technology
North America Fuel Cell Technology Market
Fuel Cell Technology
Hydrogen Fuel Cell Vehicle Market
Fuel Cell Technology
Solid Oxide Fuel Cell Market
Fuel Cell Technology
Aircraft Fuel Cell Market
Fuel Cell Technology
Protonic Ceramic Fuel Cell (PCFC) Market
Fuel Cell Technology
Fuel Cell Market