
 Diesel As Fuel Market | 2026-2036
Diesel As Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
Diesel As Fuel Market Outlook
Fuel management subscriptions tied to telematics and consumption analytics is restructuring how diesel gets sold to large commercial accounts. ExxonMobil leverages its integrated refining network to sustain supply security for fleet operators across North American corridors. Shell plc anchors its position through differentiated low-carbon diesel blends aimed at European transport compliance. PetroChina Company Limited dominates domestic bulk distribution through controlled pipeline and storage infrastructure.
Diesel as fuel denotes a liquid petroleum distillate with a typical cetane number between 40 and 55 and a boiling range of 160 to 370 degrees Celsius, formulated for compression-ignition engines that rely on heat-of-compression rather than spark ignition for combustion. Ultra-low sulfur diesel leads the fuel type category due to entrenched regulatory baselines, while renewable diesel represents the fastest-growing pool as refiners retrofit hydrotreatment units to process waste feedstocks. Marine transportation commands durable volume within the application dimension, though power generation retains concentrated margin pools in emerging economies with grid instability.
The US EPA enforces Tier 3 sulfur standards that constrain refinery output specifications and shape product slate investments across American facilities. India's BIS mandates progressive sulfur reductions that force import-dependent marketers to certify supply chain compliance. The EU F-Gas Regulation and REACH framework indirectly pressure diesel-adjacent equipment manufacturers to improve leak containment and material traceability. Stakeholders must monitor how carbon border adjustments and clean fuel standards redefine competitive access across major demand centers.
Market Dynamics
India's BIS sulfur mandates are compressing supply chains as importers race to certify cleaner diesel batches before enforcement deadlines, forcing terminal operators to segregate storage by specification grade.
Growth Catalysts
- Freight electrification delays:Battery energy density constraints and charging infrastructure gaps in long-haul corridors sustain diesel dependence for commercial fleets operating beyond 500-kilometer routes.
- BIS sulfur phase-down:India's progressive reduction to 10 ppm sulfur specifications creates certified supply premiums for marketers with pre-positioned low-sulfur inventories at Mumbai and Chennai ports.
- Hydrotreatment retrofitting:Refiners are converting existing units to process waste oils and animal fats, expanding renewable diesel capacity without greenfield construction timelines.
Market Restraints
- Crude price volatility:Brent benchmark swings compress refining margins and destabilize procurement planning for independent distributors lacking long-term offtake agreements.
- Stranded asset risk:European refiners face accelerated depreciation schedules as the EU Green Deal and national ICE phase-out dates compress the useful life of hydrocracking investments.
- Renewable diesel feedstock competition:Waste oils and tallow face competing demand from sustainable aviation fuel producers, tightening input supply for ground transport fuel refiners.
Strategic Opportunities
- Industrial corridor micro-grids:Diesel-gasoline hybrid generators offer backup power for manufacturing clusters in Gujarat and Tamil Nadu facing grid instability during monsoon seasons.
- Telematics-integrated fuel cards:Fleet operators in Maharashtra are piloting subscription models linking real-time consumption analytics to dynamic pricing and route optimization services.
- Marine IMO 2020 compliance pools:Very low sulfur fuel oil blending demand creates arbitrage opportunities for coastal storage terminals positioned between refining centers and port bunkering hubs.
Industry Challenges
- Hydroprocessing catalyst scarcity:Specialized cobalt-molybdenum formulations face 18-24 month order backlogs, delaying refinery upgrade timelines and stranding capital commitments.
- Cross-border certification fragmentation:Divergent national testing protocols for sulfur content and cetane index create documentary friction for bulk traders operating across Indian Ocean rim markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diesel As Fuel Market |
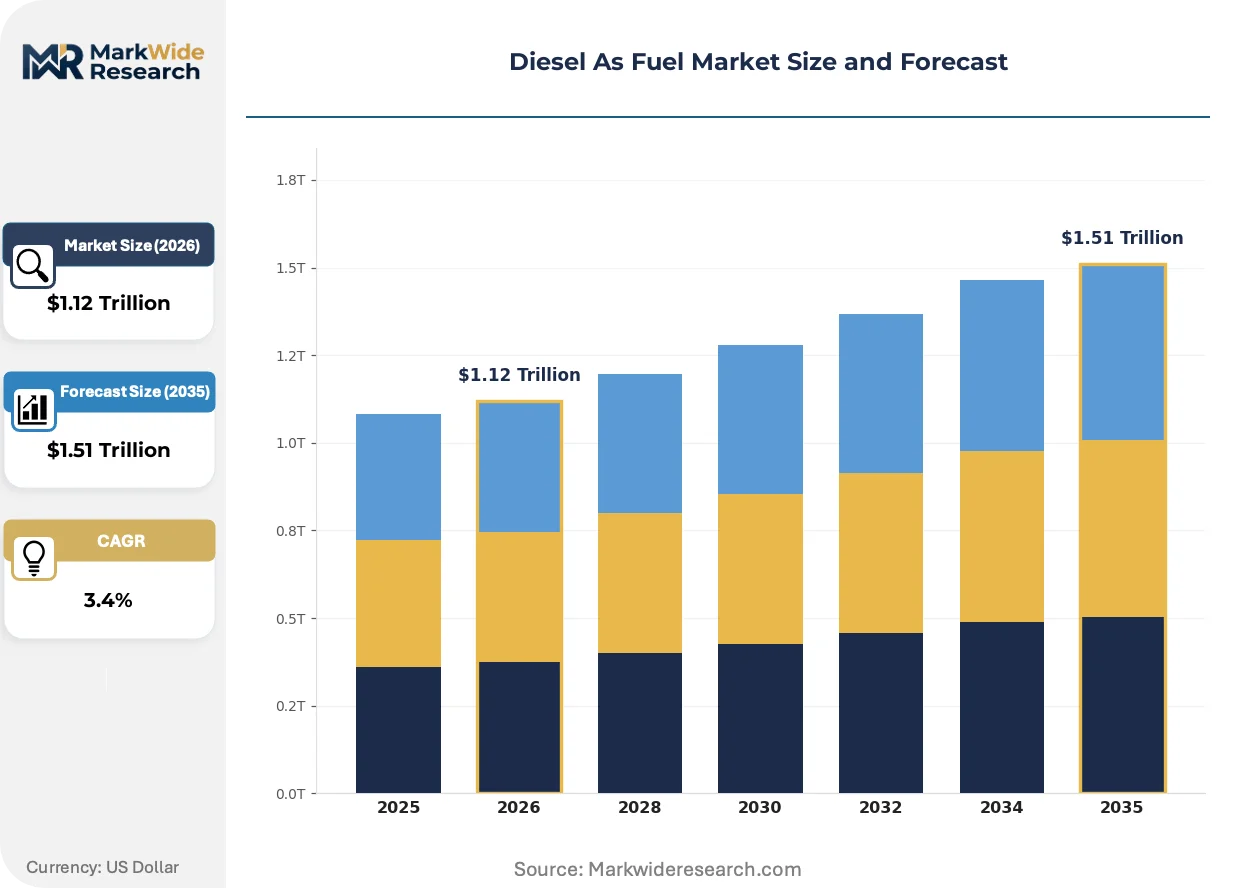
| Market Size in 2026 | $1.12 Trillion |
| Market Size in 2035 | $1.51 Trillion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: Ultra-Low Sulfur Diesel, Biodiesel, Renewable Diesel, Synthetic Diesel Application: Transportation, Power Generation, Agricultural Equipment, Marine Transportation End User: Commercial Fleet Operators, Power Plants, Agricultural Producers, Shipping Companies Distribution Channel: Bulk Distribution, Retail Outlets, Direct Supply, Online Platforms |
| Companies Covered | Saudi Aramco, ExxonMobil, Chevron Corporation, Shell plc, BP plc, PetroChina Company Limited, TotalEnergies SE, China Petroleum & Chemical Corporation (Sinopec), Reliance Industries Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diesel As Fuel Market Strategic Shifts
Compression-ignition technology is fragmenting into parallel development tracks as conventional efficiency gains converge with bio-derived feedstock processing and digital fuel management systems.
Advanced combustion control systems using real-time cylinder pressure feedback are automating injection timing optimization across variable load conditions. Mining and construction equipment fleets in Australia's Pilbara region are adopting these systems to maintain emissions compliance during high-torque operations. The technology is automating the trade-off between particulate matter formation and thermal efficiency that previously required manual calibration.
REACH framework amendments on persistent organic pollutants are tightening allowable concentrations of polycyclic aromatic hydrocarbons in diesel marketed across EU member states. Refiners must deploy additional hydrotreating stages or absorb blending penalties to maintain market access. Automotive OEMs are responding by tightening their own fuel quality specifications beyond regulatory minimums to protect exhaust after-treatment systems.
Commercial buyers are consolidating procurement through integrated fuel management platforms that unbundle supply from equipment maintenance and compliance reporting. Large logistics operators in India's National Capital Region are displacing spot market purchases with annual volume contracts tied to telematics-verified consumption data. This concentration is most visible among e-commerce fulfillment fleets operating 24-hour sorting hubs where downtime costs exceed fuel price differentials.
Diesel As Fuel Market Segmentation
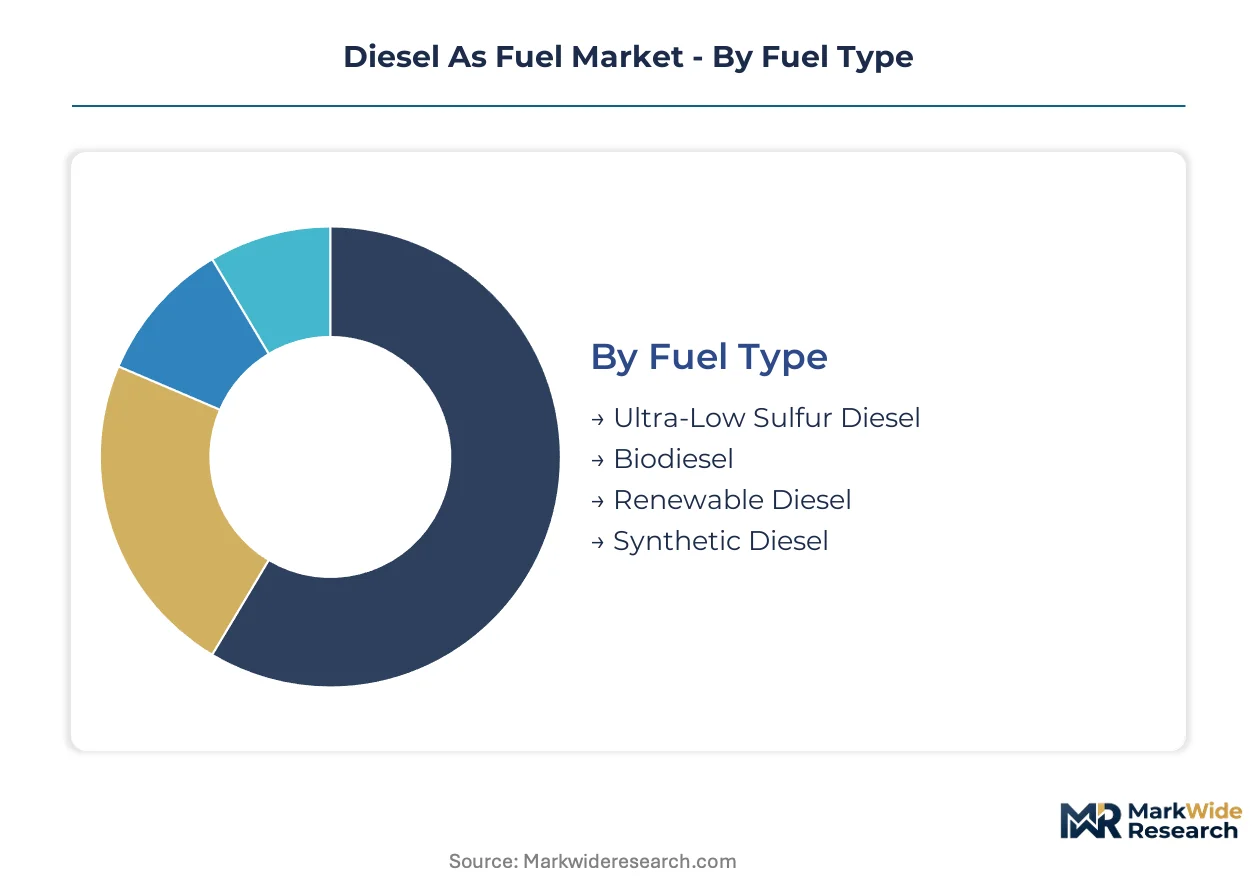
Diesel market segmentation reveals how fuel specifications, delivery mechanisms, and end-use requirements create distinct commercial battlegrounds. Each dimension carries different margin structures and regulatory exposure, forcing suppliers to prioritize capability investments across incompatible technical standards.
Fuel Type:
Some fuel types function as direct replacements in existing infrastructure; others demand dedicated storage, handling protocols, or engine modifications that fragment procurement decisions.
- Ultra-Low Sulfur Diesel:Petroleum distillate with sulfur content capped at 15 ppm under US EPA Tier 3 standards and 10 ppm under India's BIS mandates. Demand concentrates in long-haul trucking corridors across Maharashtra and Gujarat where fleet operators face enforcement deadlines for sulfur compliance. Refiners with hydrodesulfurization capacity command pricing premiums during specification transitions.
- Renewable Diesel:Hydrotreated vegetable oils and animal fats yielding drop-in compatibility with conventional diesel engines. Demand is accelerating fastest among California fleet operators seeking Low Carbon Fuel Standard credits and European transport companies under EU Green Deal pressure. Hydrotreatment retrofitting at existing refineries is expanding supply without greenfield construction.
- Biodiesel:Fatty acid methyl esters blended at 5-20% ratios with petroleum diesel, requiring separate cold-flow handling protocols. European biodiesel consumption is concentrating around rapeseed oil feedstock regions.
- Synthetic Diesel:Gas-to-liquid or biomass-to-liquid fuels produced via Fischer-Tropsch synthesis, commanding niche military and aviation backup applications. South African Sasol facilities anchor commercial production.
Volume placements concentrate in Ultra-Low Sulfur Diesel; the faster expansion belongs to Renewable Diesel.
Application:
Application segments diverge sharply in fuel quality tolerance, delivery scale, and price sensitivity, creating specialized supply relationships that resist commoditization.
- Transportation:Compression-ignition engines in commercial trucking, rail locomotives, and passenger vehicles. Freight electrification delays sustain diesel dependence for routes exceeding 500 kilometers where charging infrastructure gaps persist. India's National Capital Region e-commerce fulfillment fleets are consolidating procurement through telematics-integrated annual contracts.
- Marine Transportation:IMO 2020-compliant very low sulfur fuel oil and marine gas oil for ocean-going vessels. Bunkering demand concentrates at Singapore, Rotterdam, and Fujairah hub ports where blending arbitrage opportunities emerge between refining centers.
- Power Generation:Diesel-gasoline hybrid generators providing backup electricity for manufacturing clusters and data centers. Grid instability during India's monsoon seasons drives seasonal procurement spikes in Tamil Nadu industrial corridors.
- Agricultural Equipment:Seasonal demand from tractors, harvesters, and irrigation pumps with tolerance for higher sulfur content in unregulated rural markets. Procurement concentrates around planting and harvest windows.
Transportation commands the largest volume commitment; Marine Transportation is climbing the fastest on IMO regulatory enforcement.
End User:
End user categories separate by procurement sophistication, with large operators displacing spot markets through integrated fuel management platforms.
- Commercial Fleet Operators:Logistics companies, trucking cooperatives, and passenger transport services with centralized procurement functions. Maharashtra-based operators are piloting subscription models linking real-time consumption analytics to dynamic pricing.
- Shipping Companies:Container lines, bulk carriers, and tanker operators with global bunkering networks and stringent sulfur compliance requirements. EU F-Gas Regulation and REACH framework pressure equipment manufacturers to improve leak containment.
- Power Plants:Grid-tied and captive generation facilities using diesel for peaking or backup capacity. Concentrated margin pools exist in emerging economies with unreliable grid infrastructure.
- Agricultural Producers:Individual farmers and cooperative associations with fragmented purchasing patterns and price-sensitive procurement timing.
Commercial Fleet Operators dominate procurement scale; Shipping Companies are gaining share fastest on regulatory compliance premiums.
Distribution Channel:
Channel structure determines working capital intensity and customer intimacy, with bulk and direct models displacing retail for large accounts.
- Bulk Distribution:Pipeline, rail, and barge delivery to terminals and industrial consumers. PetroChina dominates domestic Chinese bulk distribution through controlled pipeline and storage infrastructure.
- Direct Supply:Refiner-to-fleet contracts with dedicated delivery scheduling and consumption monitoring. ExxonMobil leverages integrated refining networks to sustain supply security across North American corridors.
- Retail Outlets:Service stations and truck stops serving fragmented owner-operator and small fleet demand. Network density determines competitive position in highway corridors.
- Online Platforms:Digital procurement interfaces with dynamic pricing and route-optimized delivery scheduling. Emerging in India's National Capital Region for e-commerce logistics clusters.
Bulk Distribution anchors volume throughput; Direct Supply is expanding most quickly as large fleets consolidate procurement relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Refining capacity concentrates in the Middle East and Asia while consumption gravity shifts toward freight corridors and industrial zones in South Asia and North America. This geographic mismatch creates arbitrage-driven trade flows and shapes investment priorities for storage and logistics infrastructure.
United States
Gulf Coast refineries supply low-sulfur diesel to long-haul trucking networks across Texas and California freight corridors. The EPA enforces Tier 3 sulfur standards that constrain product slate flexibility and shape hydrocracking investment decisions. Houston and Los Angeles port complexes anchor bulk distribution terminals serving cross-border Mexican trade and domestic e-commerce fulfillment fleets.
India
Industrial corridors in Gujarat and Tamil Nadu drive diesel procurement for manufacturing backup power and heavy goods transport. The BIS mandates progressive sulfur reductions to 10 ppm specifications that force import-dependent marketers to certify supply chain compliance. Mumbai and Chennai port terminals are segregating storage by specification grade as enforcement deadlines approach.
China
PetroChina and Sinopec dominate domestic bulk distribution through controlled pipeline networks feeding manufacturing clusters in the Yangtze and Pearl River deltas. The Ministry of Ecology and Environment enforces national VI fuel standards that align with ultra-low sulfur diesel specifications. Shandong province's independent refiners face margin compression as state-owned enterprises consolidate wholesale market share.
Germany
Ruhr industrial zones and Bavarian automotive supply chains sustain diesel demand despite passenger vehicle electrification trends. The EU Green Deal and national ICE phase-out dates compress hydrocracking asset lifespans and accelerate renewable diesel blending mandates. Rotterdam-connected Rhine corridor terminals serve as blending arbitrage points for very low sulfur fuel oil bound for Hamburg bunkering hubs.
Saudi Arabia
Saudi Aramco leverages integrated refining and export infrastructure to supply Asian and African markets with specification-grade diesel. The Kingdom's dual carbon goals under Vision 2030 drive hydrotreatment investments for cleaner product slates. Jubail industrial city anchors domestic consumption for petrochemical feedstock production and desalination power generation.
Diesel As Fuel Market Competitive Environment
Top-tier vendors anchor integrated refining and distribution networks, while mid-tier independents compete on regional sourcing flexibility and terminal access. The market structure favors players with captive crude supply, hydroprocessing capacity, and controlled logistics infrastructure. Three archetypes dominate: state-controlled national champions with pipeline monopolies, multinational majors with global bunkering networks, and independent refiners with spot market agility. Competitive moves concentrate on hydrotreatment unit retrofits for renewable diesel capacity and telematics-integrated fuel management platforms for fleet accounts.
Among state-controlled integrated players, Saudi Aramco and PetroChina Company Limited exemplify the national champion archetype with upstream-to-downstream control over domestic supply chains. ExxonMobil represents the multinational major model with corridor-focused supply security investments. These three entities occupy positions that reflect divergent geographic mandates: Middle East export orientation, China domestic consolidation, and North American freight corridor density.
| Leading Market Players |
|---|
| Saudi Aramco |
| ExxonMobil |
| Chevron Corporation |
| Shell plc |
| BP plc |
| PetroChina Company Limited |
| TotalEnergies SE |
| China Petroleum & Chemical Corporation (Sinopec) |
| Reliance Industries Limited |
| Others |
Value Chain & Pricing Dynamics
Captive pipeline infrastructure anchors supply security for state-controlled refiners while simultaneously constraining pricing power for independent distributors lacking terminal access. India's BIS sulfur mandates and the US EPA Tier 3 standards compress margin flexibility as compliance investments concentrate among hydroprocessing-capable facilities.
Pricing Analysis
Margin tightening in ultra-low sulfur diesel reflects hydrodesulfurization capacity scarcity and cobalt-molybdenum catalyst order backlogs stretching eighteen to twenty-four months. Three-tier pricing structure across certified low-sulfur, standard ultra-low sulfur, and transitional high-sulfur grades segments buyer archetypes, with commercial fleet operators least price-sensitive due to downtime cost premiums and agricultural producers most sensitive due to seasonal cash flow constraints.
Supply Chain Analysis
Bulk distribution via pipeline, rail, and coastal barge handles hyperscale demand from manufacturing clusters and power generation facilities. Supply concentrates in Saudi Arabia, China, and the United States as dominant refining centers, with crude oil, waste oil feedstocks, and hydrotreatment catalysts as critical input dependencies. Single-source vulnerability in specialized catalyst supply creates bottleneck risk for refinery upgrade timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where India's BIS sulfur phase-down to 10 ppm specifications erects capital-intensive barriers that strand non-compliant importers while rewarding pre-positioned low-sulfur inventory holders.
For Market Incumbents: Extend hydrotreatment retrofitting programs at existing refineries to capture renewable diesel capacity expansion without greenfield construction delays. Consolidate terminal storage positions at Mumbai and Chennai ports ahead of BIS enforcement deadlines to monetize certified supply premiums. Battery energy density constraints in long-haul freight electrification sustain diesel dependence through the projection window.
For New Entrants and Emerging Players: Launch via telematics-integrated fuel card subscriptions targeting Maharashtra-based commercial fleets piloting consumption analytics-linked procurement models. Target industrial corridor micro-grid backup power in Gujarat and Tamil Nadu where monsoon grid instability creates seasonal demand spikes. White-space exists in marine IMO 2020 compliance pooling at coastal storage terminals positioned between refining centers and bunkering hubs.
For Investors and Strategic Acquirers: Exit pathways concentrate in state-controlled national champions with pipeline monopolies and multinational majors with global bunkering networks. Long-term viability hinges on hydrotreatment asset positioning for renewable diesel transition rather than conventional hydrocracking exposure. Watch for carbon border adjustment mechanism implementation as inflection signal for competitive access redefinition.
| Strategic Initiative | Industry Significance |
|---|---|
| Hydrotreatment Retrofitting | Expands renewable diesel capacity without greenfield construction timelines at existing refineries. |
| Terminal Storage Segregation | Enables BIS-compliant supply certification at Mumbai and Chennai port facilities ahead of enforcement. |
| Telematics Platform Integration | Links real-time consumption analytics to dynamic pricing for Maharashtra commercial fleet operators. |
| Marine Compliance Pooling | Creates arbitrage opportunities at coastal terminals between refining centers and IMO 2020 bunkering hubs. |
| Industrial Micro-Grid Deployment | Positions diesel-gasoline hybrid generators for Tamil Nadu manufacturing clusters facing monsoon grid instability. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with refinery operations directors, commercial fleet procurement managers, marine bunkering coordinators, and terminal storage operators provided demand-side validation. EPA Tier 3 documentation, BIS fuel quality notifications, and IMO 2020 compliance records supplemented bottom-up volume modeling. Top-down triangulation against refining capacity databases and hydroprocessing unit utilization rates verified supply-side assumptions.
Segment-level granularity modeled fuel type, application, end user, and distribution channel dimensions across the projection horizon. CAGRs derived from elasticity-adjusted demand projections incorporating freight electrification delay scenarios and sulfur specification transition timelines. Hydrotreatment capacity expansion schedules and renewable diesel feedstock availability curves served as industry-specific forecast inputs.
Crude price volatility, catalyst supply disruption, and cross-border certification fragmentation are the dominant revision risks warranting scenario analysis. Forecasts reflect documented assumptions regarding regulatory enforcement timing and refinery upgrade completion rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Mobile Gas Pumping System Market
Fuels
Brazil LNG Market
Fuels
Global Liquid Gas Cylinder (LGC) Market
Fuels
United States Bunker Fuel Market
Fuels
Compressed Natural Gas (CNG) Dispenser Market
Fuels
No.2 Diesel Fuel Market
Fuels
Liquid Propellants Market
Fuels
LNG Filling Station Market
Fuels
LPG Cylinder Manufacturing Market
Fuels
Asia-Pacific Bunker Fuel Market
Fuels
Brazil Bunker Fuel Market
Fuels
Australia Coal Market
Fuels
Saudi Arabia Fuel Station Market
Fuels
High Octane Racing Fuel Market
Fuels
Aerospace Aviation Fuels Market
Fuels
North America LNG Bunkering Market