
 Hydrogen Fueling Nozzle Market | 2026-2036
Hydrogen Fueling Nozzle Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Fueling Nozzle Market Insights
Modular nozzle-adapter bundling is broadening procurement options for fleet operators seeking interchangeable hydrogen dispensing hardware. Air Liquide leverages its cryogenic expertise to anchor European infrastructure deployments. Nel competes through integrated electrolyzer-to-dispenser system architectures. Parker Hannifin specializes in precision sealing technologies that differentiate its high-pressure coupling designs.
A hydrogen fueling nozzle is a mechanically coded dispensing interface engineered to withstand 700-bar operating pressures while maintaining cryogenic compatibility and static-dissipative safety protocols; it serves as the terminal connection point transferring compressed hydrogen from station storage to onboard vehicle tanks. High-flow nozzle configurations command premium positioning within product type segments due to their throughput advantages for commercial fleet turnaround times. Fleet operators represent the most concentrated end user segment, with automotive OEM pull-through demand expanding as hydrogen passenger vehicle programs advance.
ISO 19880-1 governs gaseous hydrogen fueling station performance and safety parameters, while the EU's F-Gas Regulation shapes refrigerant pathway constraints affecting station compressor design. Germany's KBA enforces component-type approval requirements that filter market access for non-certified nozzle suppliers. Stakeholders must monitor standard harmonization between SAE J2601 protocols and emerging regional variants to anticipate compatibility-driven procurement shifts.
Market Dynamics
California's CARB emission mandates are compressing heavy-duty fleet conversion timelines, forcing procurement decisions for 700-bar dispensing hardware before station density reaches critical mass.
Growth Catalysts
- Heavy-Duty Fleet Mandates:CARB's Advanced Clean Trucks regulation in California is binding fleet operators to zero-emission pathways, creating captive demand for high-flow nozzle configurations at commercial depots.
- ISO 19880-1 Harmonization:Germany's accelerated certification timelines under DIN EN ISO 19880-1 are reducing supplier qualification periods, enabling faster infrastructure deployment across European corridors.
- Tokyo Bay Cluster Concentration:METI's hydrogen roadmap is aggregating procurement authority within Japan's industrial port zones, consolidating demand signals for nozzle manufacturers.
Market Restraints
- Specialized Alloy Input Costs:Aerospace-grade stainless steel and cryogenic-compatible polymers face supply volatility from limited specialty metal foundries in Germany and Japan.
- Component-Type Approval Friction:Germany's KBA enforces stringent filter mechanisms that exclude non-certified Asian suppliers from European infrastructure tenders.
- Station Utilization Thresholds:Low throughput at early-stage hydrogen stations in dispersed geographies stretches capital recovery timelines for nozzle deployment.
Strategic Opportunities
- Modular Adapter Architectures:Interchangeable nozzle-adapter bundling is opening fleet procurement flexibility, allowing operators to source hardware independent of station OEM lock-in.
- Electrolyzer-Dispenser Integration:On-site hydrogen production convergence with dispensing infrastructure is creating bundled system opportunities at industrial clusters in the Netherlands.
- High-Flow Premium Positioning:Commercial turnaround time pressures are elevating throughput-optimized nozzle variants above standard configurations in fleet procurement specifications.
Industry Challenges
- Cryogenic Sealing Expertise Scarcity:Precision engineering talent capable of 700-bar static-dissipative design remains concentrated among a handful of European and Japanese component specialists.
- SAE J2601 Protocol Fragmentation:Divergent regional implementations of fueling protocols are forcing manufacturers to maintain multiple certification tracks, extending product development cycles.
- Legacy CNG Infrastructure Incompatibility:Existing compressed natural gas dispensing footprints cannot accommodate hydrogen pressure and material requirements, requiring complete site reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Fueling Nozzle Market |
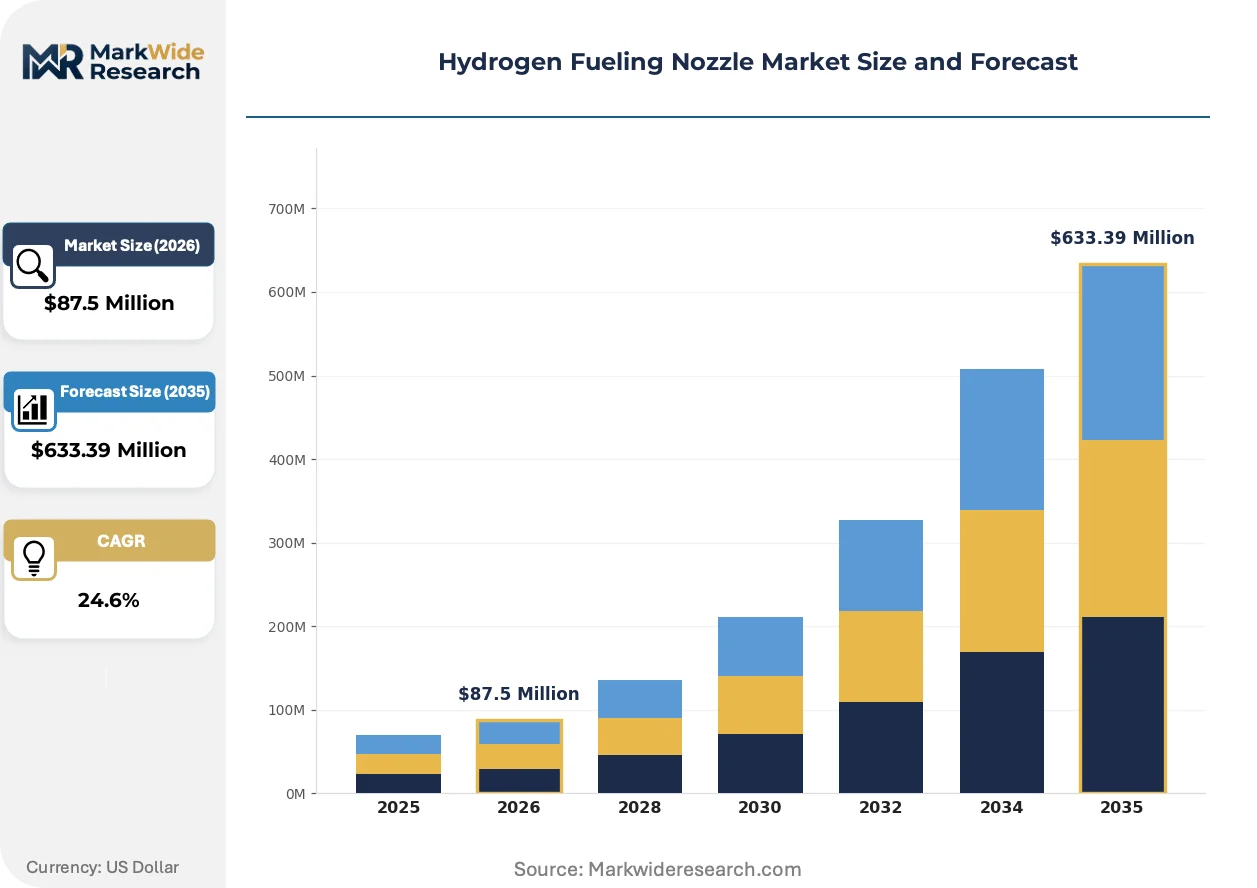
| Market Size in 2026 | $87.5 Million |
| Market Size in 2035 | $633.39 Million |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Nozzle, Compact Nozzle, High-Flow Nozzle, Flexible Nozzle Application: Fueling Stations, Mobile Refueling Units, Automotive, Hydrogen Infrastructure Technology: Compression Technology, Dispensing Technology, Sensors, Control Mechanisms End User: Automotive OEMs, Fleet Operators, Government Agencies, Research Institutions |
| Companies Covered | Air Liquide, Linde, Air Products and Chemicals, Nel, Shell Hydrogen, Parker Hannifin, MAXIMATOR Hydrogen GmbH, Hydrogen Refueling Solutions, ITM Power, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Fueling Nozzle Market Trends and Innovations
Hardware modularity and protocol standardization are compressing procurement cycles while elevating performance specifications for commercial fleet applications.
High-flow nozzle configurations are expanding into heavy-duty depot operations as fleet operators prioritize vehicle turnaround velocity over capital cost minimization. Trucking operators at California's Central Valley freight corridors are specifying 700-bar systems with accelerated fill rates. This expansion is compressing competitive positioning around throughput metrics rather than unit economics alone.
The EU's F-Gas Regulation is constraining refrigerant pathways for station compressor design, indirectly elevating nozzle thermal management requirements. Manufacturers must now engineer interfaces compatible with alternative cooling architectures. European infrastructure developers in the Netherlands and Germany are responding by specifying nozzles with expanded temperature operating ranges.
Fleet procurement consolidation is aggregating demand authority within operator procurement departments, displacing fragmented station-by-station purchasing. Large trucking operators in California are negotiating direct supply agreements with nozzle manufacturers, bypassing traditional station OEM channels. This pattern is most visible in heavy-duty segments where fleet scale justifies dedicated infrastructure investment.
Hydrogen Fueling Nozzle Market Segmentation
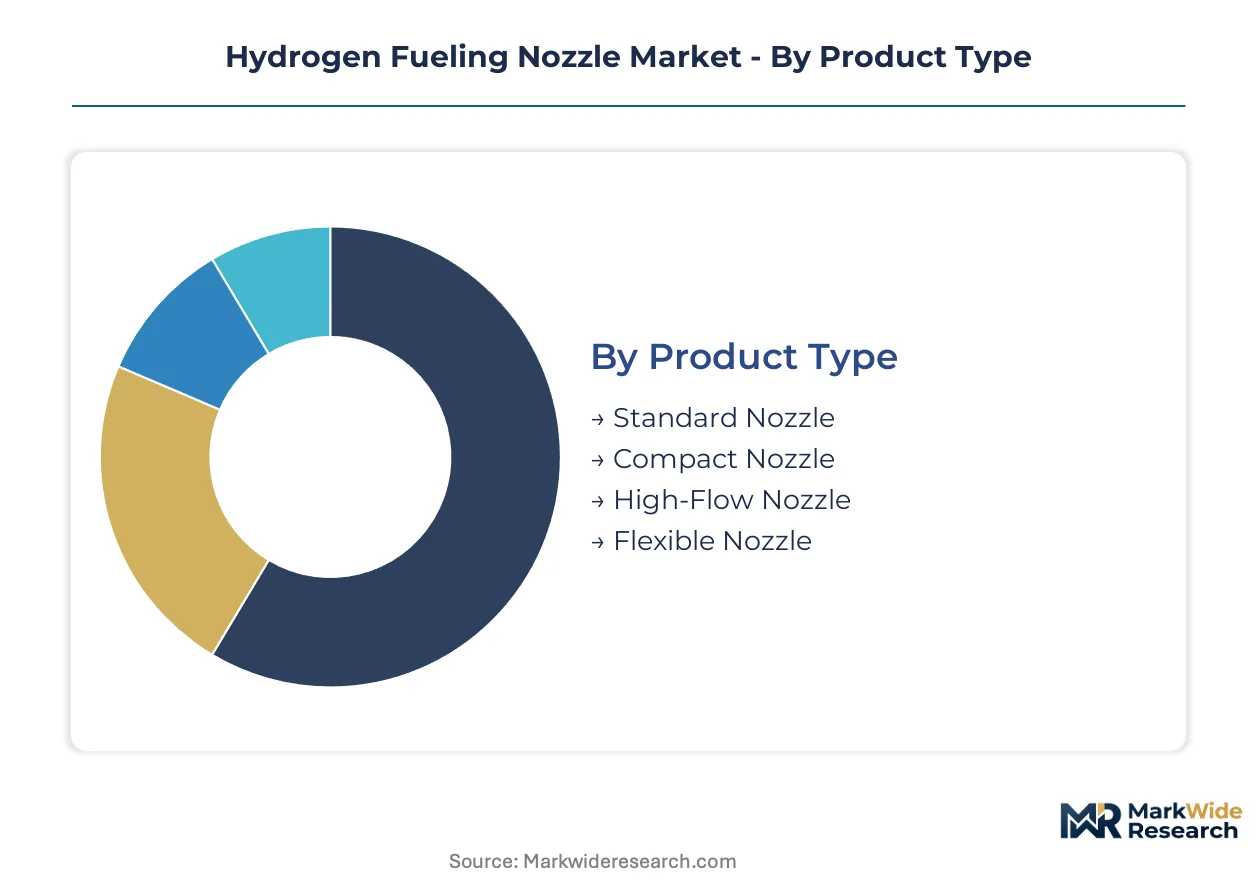
Nozzle configuration choices directly shape station capital efficiency and fleet turnaround economics. Procurement patterns across product types, applications, and end users reveal where infrastructure investment is concentrating versus where standardization pressures are compressing margins.
Product Type:
Upgrade cycles for dispensing hardware accelerate where fleet operators prioritize throughput over initial capital outlay.
- Standard Nozzle:Baseline 700-bar interface with static-dissipative safety protocols serves early-stage station deployments and passenger vehicle corridors. California's Central Valley freight operators are phasing out standard configurations in favor of high-flow variants as CARB mandates tighten commercial fleet conversion timelines.
- High-Flow Nozzle:Optimized mass-transfer geometry achieves accelerated fill rates critical for heavy-duty depot operations. Trucking fleets in Germany's Rhine-Alpine corridor specify these configurations to minimize vehicle downtime, compressing competitive positioning around throughput metrics rather than unit cost alone.
- Compact Nozzle:Reduced envelope dimensions suit space-constrained urban installations and passenger vehicle applications.
- Flexible Nozzle:Articulated hose-connector assemblies accommodate varied vehicle inlet positioning across mixed-fleet depots.
Volume placements concentrate in Standard Nozzle configurations; the faster expansion belongs to High-Flow Nozzle variants.
Application:
Station architecture choices fragment procurement patterns between fixed infrastructure and distributed mobile systems.
- Fueling Stations:Permanent 700-bar dispensing installations with integrated cooling and control systems anchor corridor infrastructure development. Germany's DIN EN ISO 19880-1 certification compression is accelerating deployment timelines across European highway networks, with KBA type-approval filtering supplier participation.
- Automotive:Passenger vehicle programs in Japan's Tokyo Bay clusters are scaling OEM-integrated dispensing specifications. METI's procurement consolidation within industrial port zones is standardizing nozzle interfaces for light-duty hydrogen vehicle rollouts.
- Mobile Refueling Units:Trailer-mounted dispensing systems serve off-grid fleet depots and temporary construction sites.
- Hydrogen Infrastructure:Utility-scale storage-to-dispenser integration projects span industrial hydrogen hubs.
Capital deployment concentrates in Fueling Stations; Automotive applications are climbing the fastest as OEM vehicle programs advance.
Technology:
Component-level specification choices determine thermal management performance and protocol compatibility.
- Compression Technology:High-pressure gas handling systems preceding nozzle interface govern fill rate consistency and energy efficiency. The EU's F-Gas Regulation is constraining refrigerant pathways, forcing redesign of pre-cooling architectures that interface directly with nozzle thermal specifications.
- Sensors:Real-time pressure, temperature, and flow monitoring arrays enable SAE J2601 protocol compliance and safety interlocks. Divergent regional implementations of fueling protocols are forcing manufacturers to maintain multiple certification tracks, extending development cycles for sensor-integrated nozzle designs.
- Dispensing Technology:Mechanical coupling and release mechanisms govern operator ergonomics and connection reliability.
- Control Mechanisms:Automated sequencing and emergency shutdown systems manage fill process safety.
Engineering resources concentrate in Compression Technology; Sensor integration is gaining share fastest as protocol complexity increases.
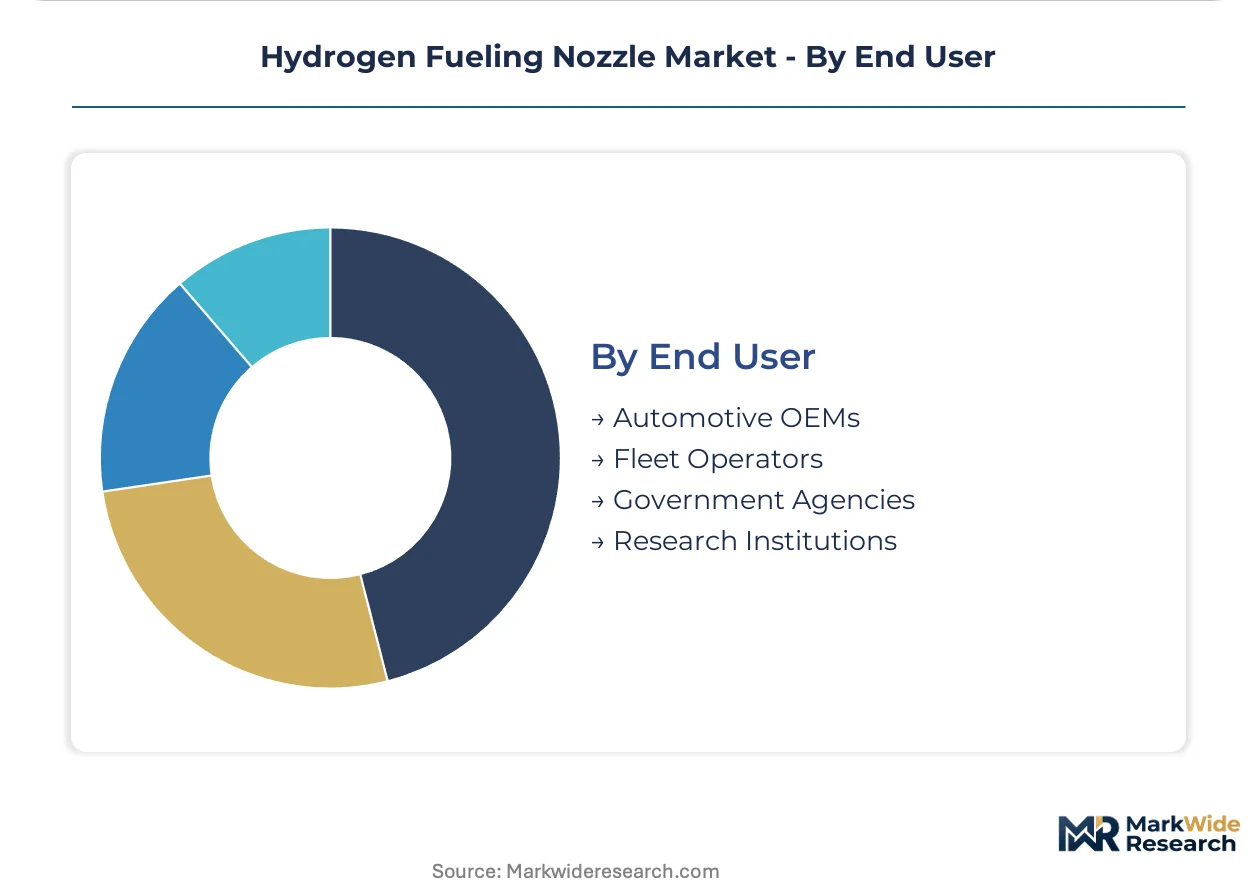
End User:
Procurement authority consolidation is displacing fragmented purchasing across customer categories.
- Fleet Operators:Large-scale commercial vehicle operators negotiate direct supply agreements, bypassing traditional station OEM channels. California's heavy-duty trucking operators are aggregating demand authority within procurement departments, creating captive demand for high-throughput nozzle configurations at dedicated depot infrastructure.
- Automotive OEMs:Vehicle manufacturers specify inlet interface standards that cascade backward through dispensing hardware requirements. Japan's passenger vehicle programs are concentrating procurement influence within Tokyo Bay industrial clusters, standardizing nozzle-to-vehicle compatibility specifications.
- Government Agencies:Public infrastructure tenders shape baseline certification and performance requirements.
- Research Institutions:Testing and validation facilities drive prototype specification and protocol development.
Contract volume concentrates with Fleet Operators; specification influence is expanding most quickly through Automotive OEMs as vehicle production scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in Germany and Japan while fleet deployment concentrates in California and the Netherlands, creating transatlantic and transpacific supply-demand asymmetries that shape procurement routing.
United States
California's Central Valley freight corridors drive heavy-duty fleet conversion under CARB's Advanced Clean Trucks regulation. The state's Air Resources Board compresses emission thresholds annually, forcing depot operators to procure 700-bar dispensing hardware ahead of station density maturation. Los Angeles-Long Beach port complexes aggregate hydrogen procurement authority for drayage truck electrification.
Germany
The Rhine-Alpine freight corridor anchors European heavy-duty hydrogen deployment with accelerated infrastructure buildout. DIN EN ISO 19880-1 standardization compresses nozzle certification timelines, while KBA type-approval filters non-certified suppliers from public tenders. Industrial clusters in North Rhine-Westphalia consolidate demand for high-throughput depot configurations.
Japan
Tokyo Bay industrial zones concentrate METI-coordinated procurement for passenger vehicle and commercial fleet programs. The hydrogen roadmap aggregates station development authority within port-industrial complexes, standardizing nozzle-to-vehicle interface specifications. Kanto region infrastructure deployment outpaces rural corridor development.
Netherlands
Rotterdam-Antwerp port industrial hubs drive electrolyzer-to-dispenser integration projects for maritime and trucking applications. The EU's F-Gas Regulation constrains refrigerant pathways, elevating thermal management requirements for nozzle specifications. Randstad logistics operators negotiate direct hardware procurement independent of station OEM channels.
South Korea
Ulsan industrial complexes anchor hydrogen production-to-dispensing integration for petrochemical and automotive manufacturing. National hydrogen economy roadmaps concentrate station development in southeastern coastal zones. Seoul Capital Area deployment lags industrial corridor prioritization.
Hydrogen Fueling Nozzle Market Competitive Landscape
The competitive structure tilts toward industrial gas incumbents with cryogenic infrastructure legacies. Tier-one positioning concentrates among hydrogen value chain integrators possessing electrolyzer-to-dispenser system capabilities. Three archetypes dominate: industrial gas majors leveraging existing distribution networks, precision engineering specialists commanding sealing and coupling expertise, and electrolyzer-integrated system architects bundling production with dispensing hardware. Geographic expansion and strategic partnerships constitute the dominant competitive vectors as suppliers race to anchor corridor infrastructure positions.
Within the industrial gas tier, Air Liquide and Linde occupy positions shaped by decades of cryogenic handling experience. Parker Hannifin exemplifies precision engineering specialization, while Nel represents electrolyzer-integrated system architecture. MAXIMATOR Hydrogen GmbH anchors German fabrication capabilities. These players collectively span the capability spectrum from gas production through terminal dispensing interface design.
| Leading Market Players |
|---|
| Air Liquide |
| Linde |
| Air Products and Chemicals |
| Nel |
| Shell Hydrogen |
| Parker Hannifin |
| MAXIMATOR Hydrogen GmbH |
| Hydrogen Refueling Solutions |
| ITM Power |
| Others |
Pricing and Supply Chain Analysis
High-flow nozzle configurations are simultaneously compressing unit economics and concentrating procurement leverage among aerospace-grade alloy foundries in Germany and Japan. This dual squeeze elevates cost transparency for fleet operators while fragmenting margin capture across cryogenic sealing specialists and precision machining tiers.
Pricing Analysis
Cost-down pressure on standard nozzle configurations accelerates because California fleet operators are consolidating procurement authority and negotiating direct supply agreements. Three-tier pricing structure across high-flow, standard, and compact levels separates certification-grade aerospace alloys from commercial-grade stainless variants. Price differentiation hinges on ISO 19880-1 compliance tier and after-sales service bundling. Heavy-duty fleet operators exhibit lowest price sensitivity; early-stage station developers in dispersed geographies face acute budget constraints.
Supply Chain Analysis
Freight costs from German and Japanese specialty foundries to California corridor deployments add substantial landed cost premiums for 700-bar dispensing hardware. Component fabrication concentrates in Germany, Japan, and South Korea. Raw material dependencies include aerospace-grade stainless steel, cryogenic-compatible fluoropolymers, and precision sensor arrays. Single-source vulnerability around cryogenic sealing expertise in European and Japanese engineering houses elevates supply risk. Distribution runs through direct OEM channels and fleet operator procurement departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints in cryogenic sealing engineering prop pricing power for incumbent specialists while compressing margins for assemblers lacking in-house precision manufacturing. Capacity scarcity at certified alloy foundries sustains premium positioning for vertically integrated producers.
For Market Incumbents: Deepen backward integration into aerospace-grade alloy supply through captive foundry partnerships in Germany or Japan. Lock long-term offtake agreements with Rhine-Alpine and Central Valley fleet operators before electrolyzer-integrated competitors scale bundled system offerings. For New Entrants and Emerging Players: Sensor-integrated nozzle architectures offer entry leverage against legacy mechanical coupling specialists. Target mobile refueling unit deployments in off-grid construction and temporary industrial sites where certification timelines remain shorter and incumbent presence thins. Pursue electrolyzer-dispenser bundling partnerships in Dutch port clusters. For Investors and Strategic Acquirers: Re-rating potential sits with cryogenic sealing engineering specialists given ISO 19880-1 harmonization compressing certification timelines across European corridors. Five-to-ten-year viability favors precision component houses with captive alloy sourcing and established KBA type-approval track records. Monitor CARB mandate acceleration in California as inflection signal for fleet procurement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Supply | Captive aerospace-grade sourcing insulates margin compression from German and Japanese foundry bottlenecks. |
| ISO 19880-1 Certification Acceleration | Compressed KBA approval timelines unlock European public tender participation before regional competitors qualify. |
| Electrolyzer-Dispenser Bundling | On-site production integration captures Dutch port cluster demand for maritime and heavy-duty trucking applications. |
| Direct Fleet Supply Agreements | Bypassing station OEM channels secures volume commitments from California trucking operators under CARB mandates. |
| Cryogenic Sealing R&D Investment | Precision engineering differentiation commands premium positioning in 700-bar high-flow nozzle specifications. |
Research Methodology
Document review covered hydrogen infrastructure deployment databases, regulatory filings with KBA and CARB, and equipment certification records, complemented by interviews with station engineering directors, fleet procurement managers, cryogenic component specialists, and electrolyzer system architects. Secondary sources included DIN EN ISO 19880-1 technical standards, METI hydrogen roadmap publications, EU F-Gas Regulation impact assessments, and customs trade data for specialty alloy flows. Bottom-up unit economics modeling triangulated against top-down corridor infrastructure investment forecasts.
Segmented outputs across product type, application technology, and end user dimensions were generated over the projection horizon. Modeled variables included nozzle configuration mix shifts, fleet conversion timelines under emission mandates, and station density maturation curves. CAGRs derived from equipment deployment trajectories and procurement pattern analysis, incorporating hydrogen production cost curves and dispensing hardware replacement cycles.
Several conditions sit outside the modeled scope, including breakthroughs in solid-state hydrogen storage, radical protocol standardization shifts, and geopolitical disruptions to specialty alloy trade flows. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuel Cell Technology
Hydrogen Fuel Cell Stack Durability and Performance Test Equipment Market
Fuel Cell Technology
Fuel Cell Market
Fuel Cell Technology
Solid Oxide Fuel Cell Market
Fuel Cell Technology
Asia-Pacific Direct Methanol Fuel Cell Market
Fuel Cell Technology
North America Fuel Cell Market
Fuel Cell Technology
Hydrogen Fuel Cell Stack and Membrane Recycling for EU Mobility Market
Fuel Cell Technology
Japan Fuel Cell Market
Fuel Cell Technology
Fuel Cell Stack Market
Fuel Cell Technology
North America Fuel Cell Technology Market
Fuel Cell Technology
China Fuel Cell Market
Fuel Cell Technology
High-Performance Fuel Cells Market
Fuel Cell Technology
Aircraft Fuel Cell Market
Fuel Cell Technology
Hydrogen Recirculation Blower for Fuel Cell Market
Fuel Cell Technology
Direct Methanol Fuel Cell Market
Fuel Cell Technology
Hydrogen Fuel Cell Drone Market
Fuel Cell Technology
France Fuel Cell Market