
 Regenerative Fuel Cell (RFC) Technologies Market | 2026-2036
Regenerative Fuel Cell (RFC) Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Regenerative Fuel Cell (RFC) Technologies Market Analytics
Solid oxide electrolysis integration with renewable curtailment is rewriting how utilities store intermittent wind and solar output. Bloom Energy Corporation leverages its solid oxide platform to anchor stationary power deployments across California data centers. Plug Power Inc. sustains North American hydrogen logistics through captive electrolyzer production. FuelCell Energy, Inc. competes on megawatt-scale carbonate systems for industrial microgrids.
Regenerative Fuel Cell Technologies combine electrochemical energy conversion with reversible operation, enabling systems to function alternately as fuel cells and electrolyzers using proton exchange membranes or solid oxide ceramics operating between 600°C and 1,000°C. Their primary purpose is to store surplus renewable electricity as hydrogen and regenerate it on demand, bridging multi-hour to seasonal storage gaps that batteries cannot address. Solid oxide technology dominates margin pools in heavy industrial applications where waste heat recovery improves round-trip efficiency. Proton exchange membrane electrolyzers lead transportation-linked deployments due to rapid response times compatible with vehicle refueling protocols. Alkaline systems occupy cost-sensitive backup power installations where capital expenditure constraints outweigh efficiency premiums.
The US Department of Energy coordinates with EPA and FERC to standardize green hydrogen certification and grid interconnection rules for reversible fuel cell assets. EU REACH and the EU Green Deal hydrogen strategy shape material sourcing requirements and carbon intensity thresholds for imported electrolyzer stacks. Japan's METI subsidizes solid oxide demonstrations through national hydrogen roadmaps. Stakeholders must monitor how the US Inflation Reduction Act credit duration intersects with electrolyzer manufacturing lead times to avoid stranded capacity commitments.
Market Dynamics
Solid oxide electrolysis integration with renewable curtailment is compressing round-trip efficiency gaps and forcing proton exchange membrane suppliers to defend their transportation stronghold through faster ramp rates.
Growth Catalysts
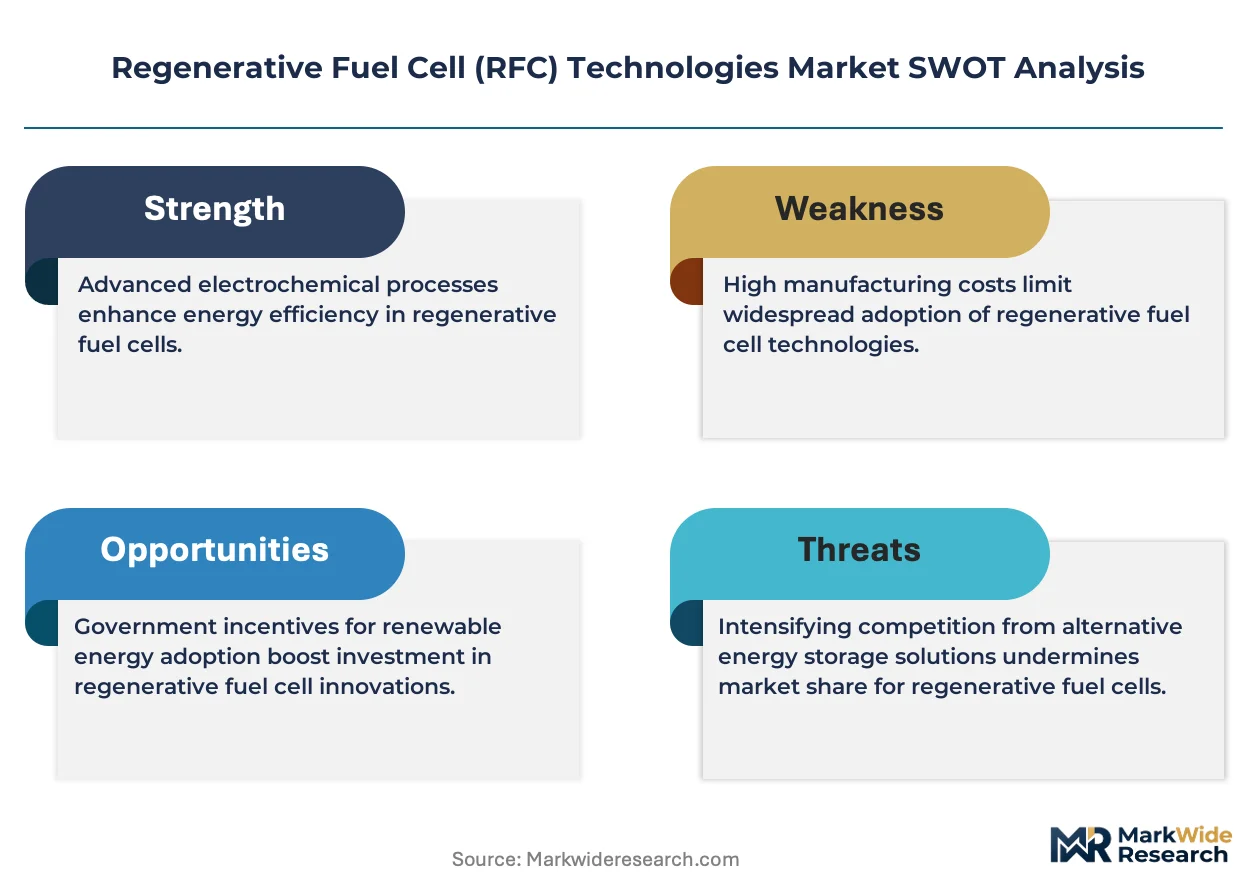
- US Inflation Reduction Act hydrogen production tax credits:These incentives are redirecting private capital toward electrolyzer manufacturing capacity and shortening project finance timelines for utility-scale deployments.
- Aerospace energy storage systems:Satellite operators in low-Earth orbit are specifying RFC systems for extended eclipse-season power cycles, creating qualification pathways for terrestrial spinoff applications.
- German industrial clusters:Steel decarbonization pilots around Hamburg and Frankfurt are anchoring demand for megawatt-scale reversible systems with waste heat recovery.
Market Restraints
- Platinum group metal cost volatility:Proton exchange membrane stacks depend on iridium and platinum catalysts, with price swings compressing stack manufacturing margins.
- Solid oxide ceramics supply concentration:Yttria-stabilized zirconia electrolyte production concentrates among Japanese and European specialty ceramics suppliers, creating single-source vulnerability.
- Round-trip efficiency ceiling:Alkaline systems face fundamental thermodynamic limits below solid oxide performance, locking them out of high-utilization revenue streams.
Strategic Opportunities
- Seasonal storage gaps in Nordic power grids:Norway and Sweden are evaluating RFC systems for hydroelectric reservoir augmentation during low-precipitation years.
- EU Green Deal hydrogen strategy carbon intensity thresholds:These mandates are creating import substitution demand for electrolyzer stacks manufactured within the bloc.
- Hybridization with battery buffering:Co-located RFC-battery systems are opening frequency regulation revenue streams that pure electrolysis cannot capture alone.
Industry Challenges
- High-temperature sealing engineering talent scarcity:Solid oxide stack manufacturers compete for materials scientists with molten carbonate fuel cell experience.
- Electrolyzer stack certification timeline compression:FERC interconnection queue delays and EPA green hydrogen certification uncertainty are extending project development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Regenerative Fuel Cell (RFC) Technologies Market |
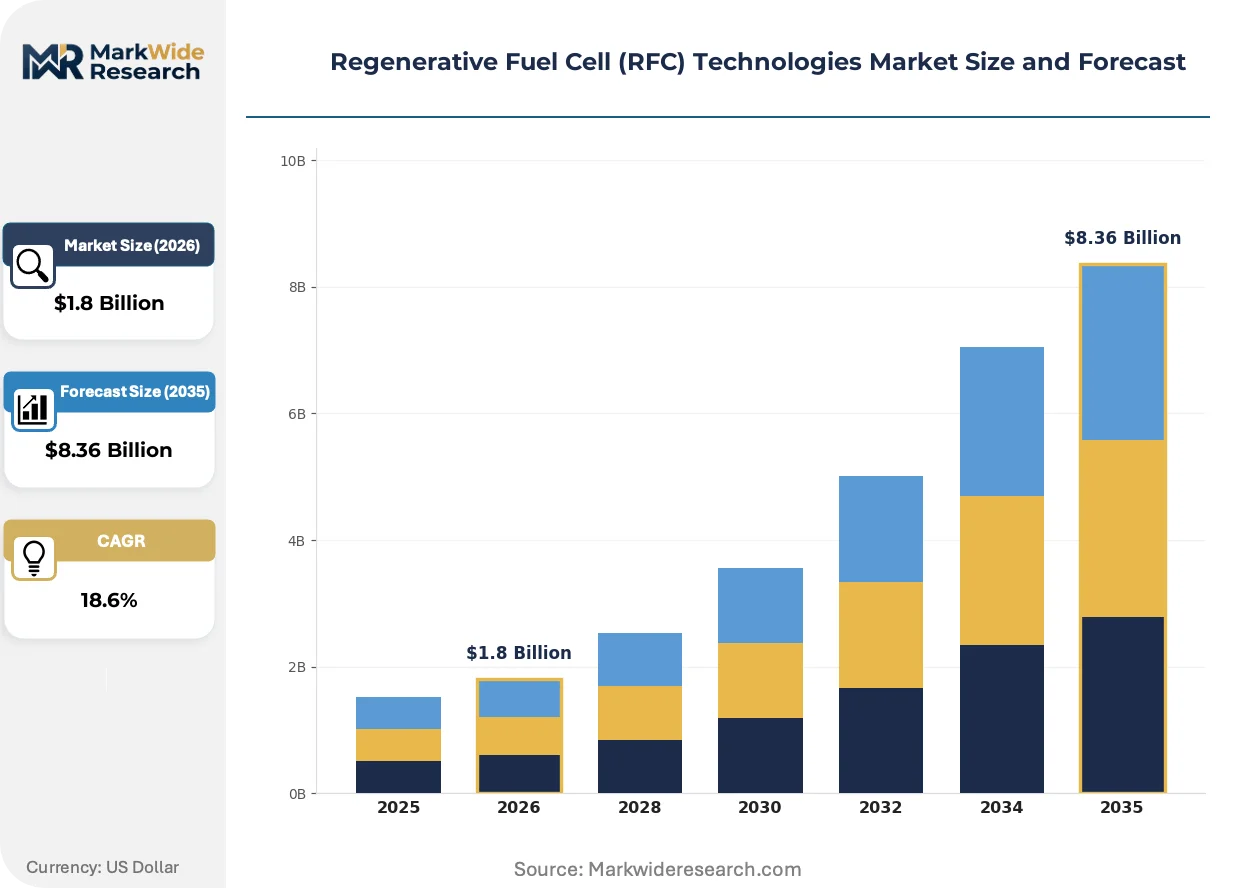
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Membrane Electrode Assembly, Bipolar Plates, Electrolyzer, Fuel Cell Stack End User: Aerospace, Automotive, Residential, Industrial Technology: Proton Exchange Membrane, Alkaline, Solid Oxide, Direct Methanol Application: Energy Storage, Backup Power, Transportation, Portable Devices |
| Companies Covered | Bloom Energy Corporation, FuelCell Energy, Inc., Plug Power Inc., Ballard Power Systems Inc., Ceres Power Holdings plc, Doosan Fuel Cell America, Inc., SFC Energy AG, Hitachi Ltd., ITM Power plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Regenerative Fuel Cell (RFC) Technologies Market Evolving Landscape
Reversible fuel cell architectures are fragmenting along temperature lines, with each branch pursuing distinct efficiency-service tradeoffs that reshape how utilities and industrials evaluate storage investments.
Solid oxide electrolysis is hybridizing with concentrated solar thermal systems to achieve thermal-electrical co-generation above 80% system efficiency. Industrial off-takers in Spain and Morocco are piloting this configuration for continuous ammonia production. The convergence is compressing the capital cost gap between green and gray hydrogen in sun-belt manufacturing zones.
EU REACH substance restrictions on perfluorinated materials are forcing proton exchange membrane suppliers to accelerate hydrocarbon membrane development. The regulation is disqualifying incumbent fluoropolymer-based stacks from public procurement tenders in Germany and France. Stack manufacturers are responding with accelerated ionomer qualification programs targeting 2027 compliance deadlines.
Power purchase agreement structures are unbundling electrolyzer availability guarantees from energy supply commitments. Data center operators in California are negotiating take-or-pay contracts that separate hydrogen delivery obligations from RFC asset performance risk. This shift is most visible in markets with mature renewable energy credit trading, where offtakers can arbitrage certificate values against fuel supply security premiums.
Regenerative Fuel Cell (RFC) Technologies Market Segmentation
Regenerative fuel cell markets fragment along temperature regimes, end-use durability requirements, and hydrogen purity specifications that dictate stack architecture choices. Each segmentation dimension reveals distinct margin structures and qualification barriers that reshape supplier competitiveness across aerospace, automotive, and stationary power deployments.
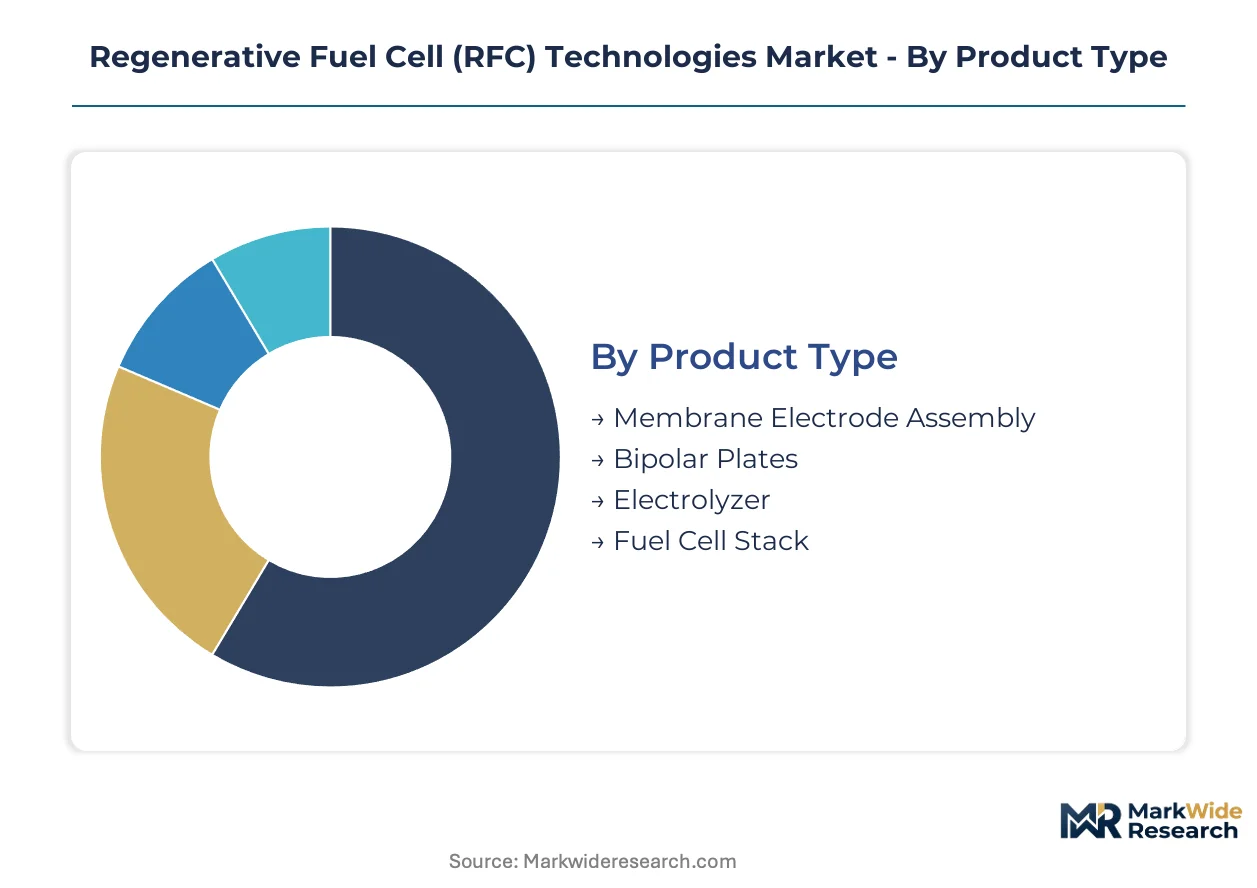
Product Type:
Component selection maps directly to system efficiency targets and maintenance intervals across reversible fuel cell deployments.
- Membrane Electrode Assembly:The core electrochemical interface layers catalyst-coated membranes with gas diffusion electrodes to enable proton transport and hydrogen evolution. Demand concentrates in PEM electrolyzer manufacturing facilities scaling in Germany and Texas, where iridium loading reduction programs are compressing catalyst costs. The dominant share belongs to Membrane Electrode Assembly, while Electrolyzer is closing the gap fastest.
- Bipolar Plates:These conductive separators distribute reactant gases and manage thermal flux across stacked cells, with graphite-composite variants dominating stationary systems and coated stainless steel penetrating transportation. Industrial microgrid developers in California specify metallic plates for rapid thermal cycling durability.
- Electrolyzer:Modular hydrogen generation units integrating stack, power electronics, and gas separation membranes for grid-scale or distributed deployment. Norwegian and Swedish utilities are evaluating these systems for hydroelectric reservoir augmentation during low-precipitation periods.
- Fuel Cell Stack:Assembled cell bundles delivering DC power output, with solid oxide architectures capturing margin in combined heat and power applications where waste heat recovery improves total system economics.
Membrane electrode assemblies command the highest value per kilowatt due to catalyst loading intensity, while electrolyzer module assembly is attracting capital seeking vertical integration into hydrogen supply chains.
End User:
Customer archetypes diverge sharply on operating temperature, duty cycle, and certification rigor.
- Aerospace:Satellite operators in low-Earth orbit specify RFC systems for extended eclipse-season power cycles, with qualification protocols creating barriers to terrestrial component crossover. NASA and ESA procurement standards are driving radiation-hardened stack development. Aerospace maintains technology leadership through qualification premiums, while Industrial is expanding volume fastest.
- Automotive:Vehicle OEMs demand rapid start-up and dynamic load response for fuel cell electric powertrains, favoring PEM architectures with sub-second ramp rates compatible with drive cycle transients.
- Residential:Single-family and multi-unit building installations prioritize quiet operation and modular scaling for combined heat and power, with Japanese utilities piloting solid oxide systems for neighborhood microgrids.
- Industrial:Steel, ammonia, and refining off-takers require megawatt-scale continuous operation with waste heat integration, anchoring demand for high-temperature reversible systems around Hamburg and Rotterdam industrial clusters.
Industrial offtakers generate the largest absolute revenue pools through unit scale, though aerospace qualification pathways are creating technology spillover effects that reshape terrestrial stack reliability standards.
Technology:
Temperature regime determines efficiency ceiling, material durability constraints, and compatible hydrogen end-uses.
- Proton Exchange Membrane:Low-temperature operation with rapid response dynamics suits transportation and backup power where start-up latency matters. EU REACH perfluorinated substance restrictions are forcing hydrocarbon membrane qualification programs targeting German and French compliance deadlines. Solid oxide captures the efficiency premium, while Proton Exchange Membrane defends the responsiveness advantage.
- Alkaline:Liquid electrolyte systems using potassium hydroxide achieve lower capital cost at reduced efficiency, occupying cost-sensitive backup power installations where capital constraints outweigh round-trip performance premiums.
- Solid Oxide:Ceramic electrolyte operation between 600°C and 1,000°C enables electrochemical co-generation with waste heat recovery, concentrating in steel decarbonization pilots and continuous industrial processes.
- Direct Methanol:Liquid fuel compatibility eliminates hydrogen infrastructure requirements for portable and remote applications, though energy density limitations restrict scaling beyond sub-kilowatt deployments.
Solid oxide systems dominate margin pools in heavy industrial applications, while alkaline technology is gaining traction fastest in emerging markets with capital-constrained procurement frameworks.
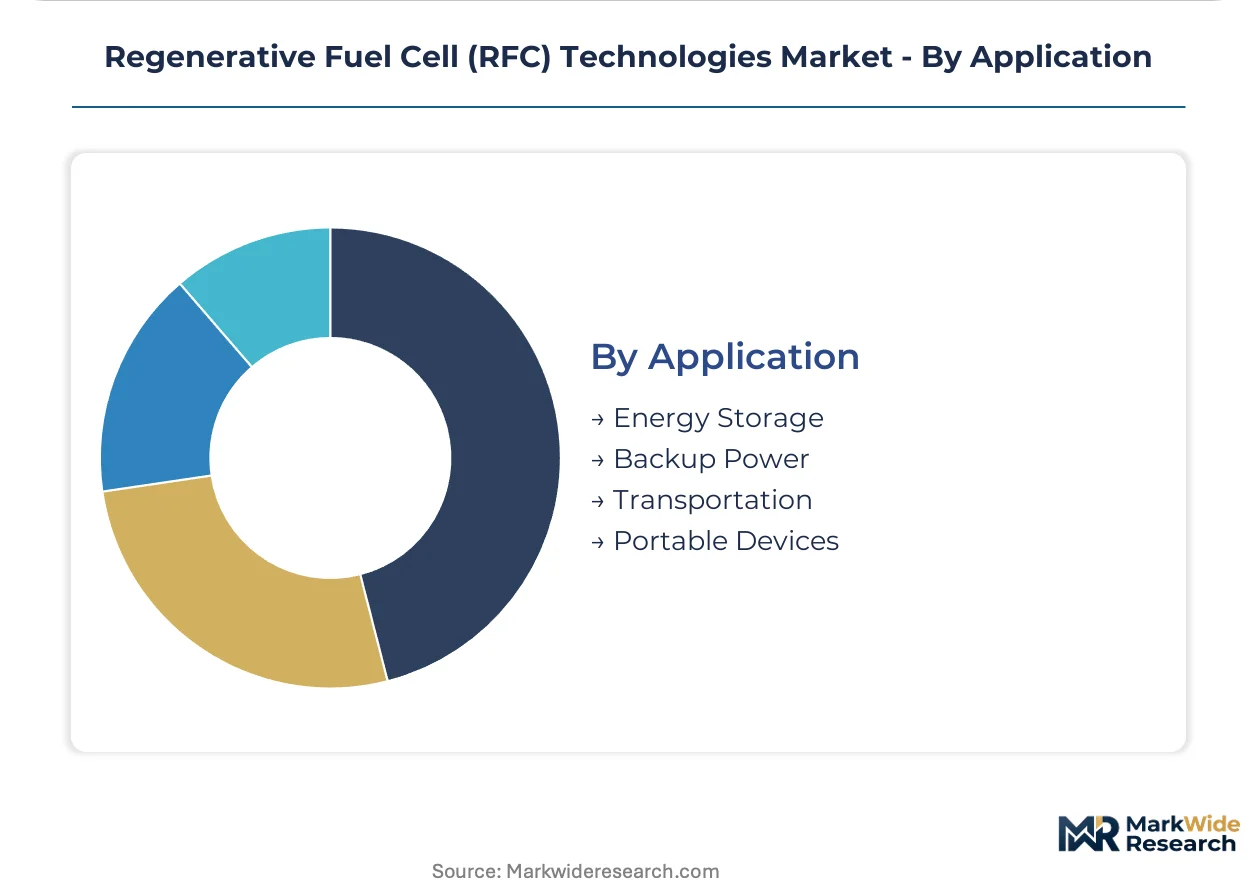
Application:
Use-case economics hinge on discharge duration, cycling frequency, and revenue stack complexity.
- Energy Storage:Multi-hour to seasonal electricity storage bridging renewable curtailment and grid dispatch, with solid oxide electrolysis integration achieving thermal-electrical co-generation above 80% system efficiency in Spanish and Moroccan solar-hydrogen pilots. Energy Storage anchors deployment scale, while Transportation is penetrating fastest.
- Backup Power:Critical facility resilience applications favoring rapid response and black-start capability, with data center operators in California negotiating availability-guarantee contracts that unbundle asset performance from energy supply risk.
- Transportation:Vehicle refueling infrastructure and onboard power systems demanding high-pressure hydrogen delivery and fast-fill protocols compatible with PEM electrolyzer ramp rates.
- Portable Devices:Field power and consumer electronics applications where methanol or compressed hydrogen cartridges replace battery charging logistics for military and expeditionary use cases.
Energy storage deployments generate the longest asset lifecycles through steady-state operation, though transportation-linked applications are scaling fastest through fleet electrification mandates and hydrogen corridor infrastructure commitments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German electrolyzer exports supply Nordic utilities and Dutch industrial clusters, while Japanese ceramics manufacturers feed solid oxide stack producers across three continents.
United States
Data center operators in California and Virginia are procuring RFC systems for carbon-neutral backup power commitments. The Inflation Reduction Act hydrogen production tax credits are compressing project finance timelines for utility-scale electrolyzer deployments. Houston and Los Angeles industrial corridors are anchoring hydrogen hub demonstrations linking RFC assets to port refueling infrastructure.
Germany
Steel decarbonization pilots in Hamburg and Frankfurt are driving megawatt-scale reversible system demand with waste heat recovery specifications. EU REACH substance restrictions on perfluorinated materials are disqualifying fluoropolymer-based stacks from federal procurement tenders. The Ruhr industrial cluster is integrating solid oxide electrolysis with blast furnace hydrogen injection trials.
Japan
METI subsidies for solid oxide demonstrations are accelerating national hydrogen roadmap milestones through 2030. The country's specialty ceramics suppliers concentrate yttria-stabilized zirconia electrolyte production for global stack manufacturers. Osaka and Nagoya industrial zones are hosting thermal-electrical co-generation pilots exceeding 80% system efficiency.
Norway
Utilities are evaluating RFC systems for hydroelectric reservoir augmentation during low-precipitation years. The national regulator coordinates grid interconnection standards for reversible fuel cell assets with Nordic power pool dispatch protocols. Bergen and Stavanger energy clusters are testing seasonal storage configurations bridging multi-week renewable curtailment gaps.
Spain
Concentrated solar thermal hybridization with solid oxide electrolysis is achieving thermal-electrical co-generation above 80% efficiency for continuous ammonia production. EU Green Deal carbon intensity thresholds are creating import substitution demand for electrolyzer stacks manufactured within the bloc. Andalusian solar-hydrogen pilots are compressing the capital cost gap between green and gray hydrogen in sun-belt manufacturing zones.
Regenerative Fuel Cell (RFC) Technologies Market Competitive Landscape
Channel-controlling players compete with product-specialist players across technology tiers defined by temperature regime and integration depth. The vendor base clusters around three strategic archetypes: solid oxide platform operators, proton exchange membrane rapid-response suppliers, and alkaline system cost leaders. Consolidation pressure concentrates in electrolyzer manufacturing capacity where Inflation Reduction Act credits are shortening project finance timelines. Dominant competitive moves include strategic partnerships for ceramics supply security and geographic expansion into German industrial clusters.
Among North American platform operators, Bloom Energy Corporation and Plug Power Inc. exemplify divergent temperature-regime specializations, while FuelCell Energy, Inc. anchors the carbonate system tier for industrial microgrid deployments. Ballard Power Systems Inc. occupies a position within transportation-linked proton exchange membrane supply chains. Ceres Power Holdings plc and ITM Power plc represent European stack manufacturing archetypes navigating EU REACH compliance deadlines. Doosan Fuel Cell America, Inc. and Hitachi Ltd. illustrate Asia-Pacific industrial conglomerate participation in stationary power verticals.
| Leading Market Players |
|---|
| Bloom Energy Corporation |
| FuelCell Energy, Inc. |
| Plug Power Inc. |
| Ballard Power Systems Inc. |
| Ceres Power Holdings plc |
| Doosan Fuel Cell America, Inc. |
| SFC Energy AG |
| Hitachi Ltd. |
| ITM Power plc |
| Others |
Value Network & Pricing Analysis
Electrolyzer manufacturing overcapacity in China is compressing stack pricing globally and forcing suppliers toward long-term service contracts with availability guarantees. This utilization dynamic rewards buyers with procurement leverage while squeezing pure-hardware margins across proton exchange membrane and alkaline system tiers.
Pricing Analysis
Cost-plus contracts with iridium and platinum indexation dominate membrane electrode assembly procurement, insulating stack manufacturers from catalyst volatility while passing through yttria-stabilized zirconia ceramic costs. Three-tier pricing structure across aerospace-qualified, industrial-standard, and cost-optimized alkaline levels separates qualification premiums from commodity backup power tiers. Price differentiation hinges on certification grade and volume scale, with German steel decarbonization pilots absorbing premium solid oxide pricing while Nordic utilities drive alkaline cost compression. Margins are tightening due to EU REACH compliance investments in hydrocarbon membrane development.
Supply Chain Analysis
Export controls on solid oxide ceramics manufacturing equipment limit technology transfer from Japan to emerging stack producers, concentrating yttria-stabilized zirconia electrolyte supply among Japanese and European specialty ceramics suppliers. Raw material dependencies center on iridium catalysts sourced from South African refiners, graphite composites from China, and high-purity nickel alloys from Germany. Single-source vulnerability in ceramic electrolyte production creates qualification bottlenecks for new stack entrants. Distribution runs through electrolyzer original equipment manufacturers with captive integration into hydrogen supply chains, linking California data center operators directly to Texas and German manufacturing facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The regenerative fuel cell market rewards service-attach strategies, with electrolyzer availability guarantees and predictive maintenance contracts expanding faster than hardware shipments as buyers seek performance risk transfer.
For Market Incumbents: Build switching-cost moats through captive hydrogen supply contracts that embed electrolyzer performance penalties. Deepen backward integration into yttria-stabilized zirconia ceramics to secure solid oxide stack margins against Japanese supply concentration. Defend against alkaline cost leaders by accelerating FERC interconnection pre-certification for utility-scale deployments. For New Entrants and Emerging Players: Establish a beachhead in seasonal storage gaps across Nordic power grids where incumbent presence remains thin. Target Norwegian and Swedish hydroelectric reservoir augmentation pilots with solid oxide configurations optimized for multi-week discharge cycles. Pursue joint development agreements with concentrated solar thermal developers in Spain and Morocco to anchor thermal-electrical co-generation system integration. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap stack manufacturers with proven solid oxide ceramics sourcing relationships and active EU REACH hydrocarbon membrane qualification programs. Long-term viability favors suppliers with demonstrated waste heat recovery integration in heavy industrial applications. Monitor FERC interconnection queue clearance rates as the inflection signal for utility-scale deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramics Supply Security Partnership | Japanese yttria-stabilized zirconia producers anchor solid oxide stack manufacturing capacity expansion. |
| Hydrogen Hub Infrastructure Commitment | Houston and Los Angeles port refueling corridors link RFC assets to maritime decarbonization pilots. |
| Hydrocarbon Membrane Qualification Program | EU REACH perfluorinated substance restrictions disqualify fluoropolymer stacks from German tenders. |
| Availability Guarantee Contract Structure | California data center operators unbundle asset performance risk from hydrogen delivery obligations. |
| Concentrated Solar Thermal Hybridization | Spanish and Moroccan pilots achieve thermal-electrical co-generation exceeding 80% system efficiency. |
Research Methodology
The analysis maps solid oxide, proton exchange membrane, alkaline, and direct methanol sub-sectors, each validated through utility planning officers, IPP project developers, EPC contractors, and fuel supply specialists. Primary interviews with electrolyzer procurement leads at German steel producers and California data center operators combined with secondary validation against EIA hydrogen hub disclosures, FERC interconnection filings, IEA renewable integration reports, and EU Green Deal hydrogen strategy documents. Bottom-up stack manufacturing capacity estimates triangulated against top-down utility procurement pipeline data.
Assumptions held fixed include IRA hydrogen production tax credit duration and EU carbon intensity threshold enforcement timelines, while electrolyzer manufacturing lead times and FERC interconnection queue clearance rates varied across sensitivity bands. Segmentation dimensions modeled span temperature regime, end-use durability requirements, hydrogen purity specifications, and regional regulatory framework clusters. CAGRs derived from installed capacity buildout trajectories calibrated against named industrial cluster commitments and aerospace qualification pathway timelines.
Stress conditions across iridium price volatility, ceramics supply disruption, and FERC interconnection delay scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding policy continuity and technology cost curves. Material shifts in US tax credit duration or EU REACH substance restriction enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuel Cell Technology
Helium Recovery Systems Market
Fuel Cell Technology
Phosphoric Acid Fuel Cell Market
Fuel Cell Technology
High-Performance Fuel Cells Market
Fuel Cell Technology
Hydrogen Fuel Cell Vehicle Market
Fuel Cell Technology
China Fuel Cell Market
Fuel Cell Technology
Hydrogen Fuel Cell Stack Durability and Performance Test Equipment Market
Fuel Cell Technology
Portable Fuel Cells Market
Fuel Cell Technology
Membrane Electrode Assembly Market
Fuel Cell Technology
Hydrogen Fuel Cells Market
Fuel Cell Technology
PEM Electrolyzer Market
Fuel Cell Technology
Hydrogen Fuel Cell Drone Market
Fuel Cell Technology
Fuel Cells for CHP Application Market
Fuel Cell Technology
Fuel Cell Stack Market
Fuel Cell Technology
Microbial Fuel Cell Market
Fuel Cell Technology
Fuel Cell for Stationary Power Market
Fuel Cell Technology
North America Fuel Cell Market