
 Portable Fuel Cells Market | 2026-2036
Portable Fuel Cells Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Fuel Cells Market Outlook
Defense contractor consolidation around prime integrators is realigning procurement pathways for portable fuel cell vendors. SFC Energy leverages its Bundeswehr relationships to anchor European military demand. Plug Power sustains North American leadership through intensive R&D spending on PEM stack efficiency. Doosan competes in Asian backup power with manufacturing scale at its Korean facilities.
Portable fuel cells are electrochemical devices that convert hydrogen, methanol, or other fuels into electricity through redox reactions, typically achieving 40-60% system efficiency in compact form factors designed for mobility. Proton Exchange Membrane systems dominate commercial shipments due to fast cold-start capability and favorable power density. The Direct Methanol segment occupies niche military and consumer electronics applications where liquid fuel logistics trump hydrogen infrastructure constraints. Above 100W power ratings concentrate margin pools as defense and emergency services specifications demand hardened packaging and extended runtime.
EPA zero-emission standards for stationary and portable generators are reshaping product certification requirements across North American sales channels. EU F-Gas Regulation and REACH compliance add material selection constraints for membrane and catalyst suppliers targeting European defense tenders. Military end users in NATO frameworks increasingly specify interoperability standards that favor PEM architectures with standardized fuel cartridges. Stakeholders must monitor how hydrogen refueling infrastructure buildout pace in Germany, Japan, and California affects deployment economics across remote location applications.
Market Dynamics
Defense procurement consolidation around prime integrators is compressing vendor access to NATO military buyers, while EPA zero-emission mandates for backup generators simultaneously pull commercial demand toward fuel cell alternatives. These dual forces create a bifurcated market structure with distinct certification and channel requirements.
Growth Catalysts
- EPA Stationary Generator Standards:Tightening emissions rules for backup power systems in the United States are disqualifying conventional diesel units from federal and state procurement lists, redirecting commercial buyers toward zero-emission fuel cell alternatives.
- Bundeswehr Field Power Programs:German military procurement for deployable off-grid units is anchoring European defense demand and establishing technical specifications that cascade into allied NATO frameworks.
- PEM Cold-Start Performance:Proton Exchange Membrane architectures achieve operational temperature in under 60 seconds, satisfying emergency services specifications that Solid Oxide alternatives cannot meet.
Market Restraints
- Platinum Group Metal Input Costs:Membrane electrode assemblies require iridium and platinum catalyst loadings that expose stack manufacturers to volatile precious metals markets and geopolitically concentrated refining capacity.
- Hydrogen Infrastructure Gaps:Remote deployment economics suffer where liquid hydrogen or high-pressure tube trailer delivery remains unavailable, constraining addressable market geography to industrial clusters with established supply.
- REACH Material Compliance:EU chemical registration requirements impose documentation burdens on membrane and catalyst suppliers that extend certification timelines and exclude non-compliant component vendors from defense tenders.
Strategic Opportunities
- California Backup Power Mandates:State-level zero-emission requirements for data center and telecommunications backup systems are creating certified demand pools that favor early-moving PEM suppliers with CARB verification.
- Methanol Reformer Integration:Liquid fuel logistics compatibility opens military and marine applications where hydrogen distribution infrastructure remains undeveloped, expanding addressable use cases beyond hydrogen-dependent architectures.
- Direct-to-Installer Channels:Bypassing traditional generator distributor networks through certified electrical contractor programs reduces channel margin capture and accelerates replacement cycle capture in commercial building retrofits.
Industry Challenges
- Membrane Electrode Assembly Talent Scarcity:Specialized electrochemist and stack manufacturing engineers concentrate at a handful of research institutions and incumbent firms, constraining scale-up capacity for new market entrants.
- Multi-Agency Certification Overlap:Military, hazardous location, and environmental safety approvals from distinct bodies create sequential testing requirements that extend product launch timelines and compound development burn rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Fuel Cells Market |
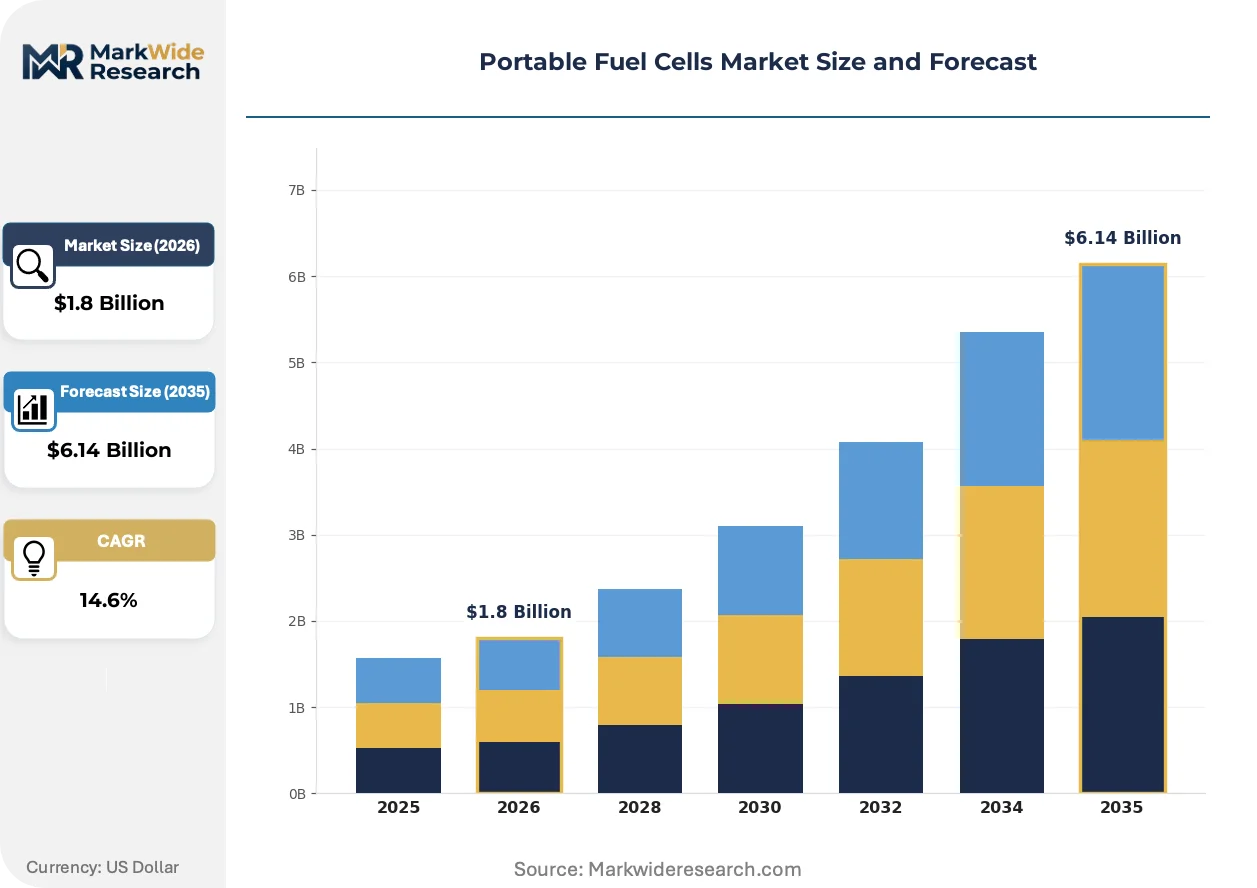
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proton Exchange Membrane, Direct Methanol, Solid Oxide, Alkaline End User: Consumer Electronics, Military, Automotive, Backup Power Power Rating: 1-5W, 5-25W, 25-100W, Above 100W Deployment: Remote Locations, Stationary Applications, Transportation, Emergency Services |
| Companies Covered | Plug Power Inc., Doosan Corporation, AFC Energy PLC, Intelligent Energy Limited, Toshiba Corporation, SFC Energy AG, Panasonic Corporation, Horizon Fuel Cell Technologies, Ballard Power Systems Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Fuel Cells Market Strategic Shifts
Stack architecture standardization and fuel cartridge interoperability are enabling vendor-agnostic procurement frameworks that reshape competitive dynamics. These developments compress switching costs and accelerate technology substitution cycles across defense and commercial segments.
Solid Oxide fuel cell technology is modularizing through ceramic substrate advances that reduce thermal cycling degradation. Industrial cogeneration buyers in Japan and Germany are piloting 1-5kW units for building-scale heat-and-power applications. This modularity is compressing the minimum efficient scale for distributed generation and opening mid-market segments previously reserved for combustion alternatives.
REACH authorization requirements for perfluorinated membrane materials are forcing reformulation investments across European supply chains. ECHA substance restrictions on long-chain fluorocarbons are disqualifying incumbent membrane chemistries from new product registrations. PEM stack manufacturers are responding with short-chain fluoropolymer alternatives that trade some proton conductivity for regulatory compliance certainty.
Defense procurement officers are consolidating vendor lists around interoperability-certified platforms that accept standardized fuel cartridges. Prime integrators are displacing direct OEM relationships as the primary commercial pathway to military buyers. This concentration is most visible in NATO framework agreements where SFC Energy and Plug Power have secured approved supplier status, compressing competitive access for unqualified vendors.
Portable Fuel Cells Market Segmentation
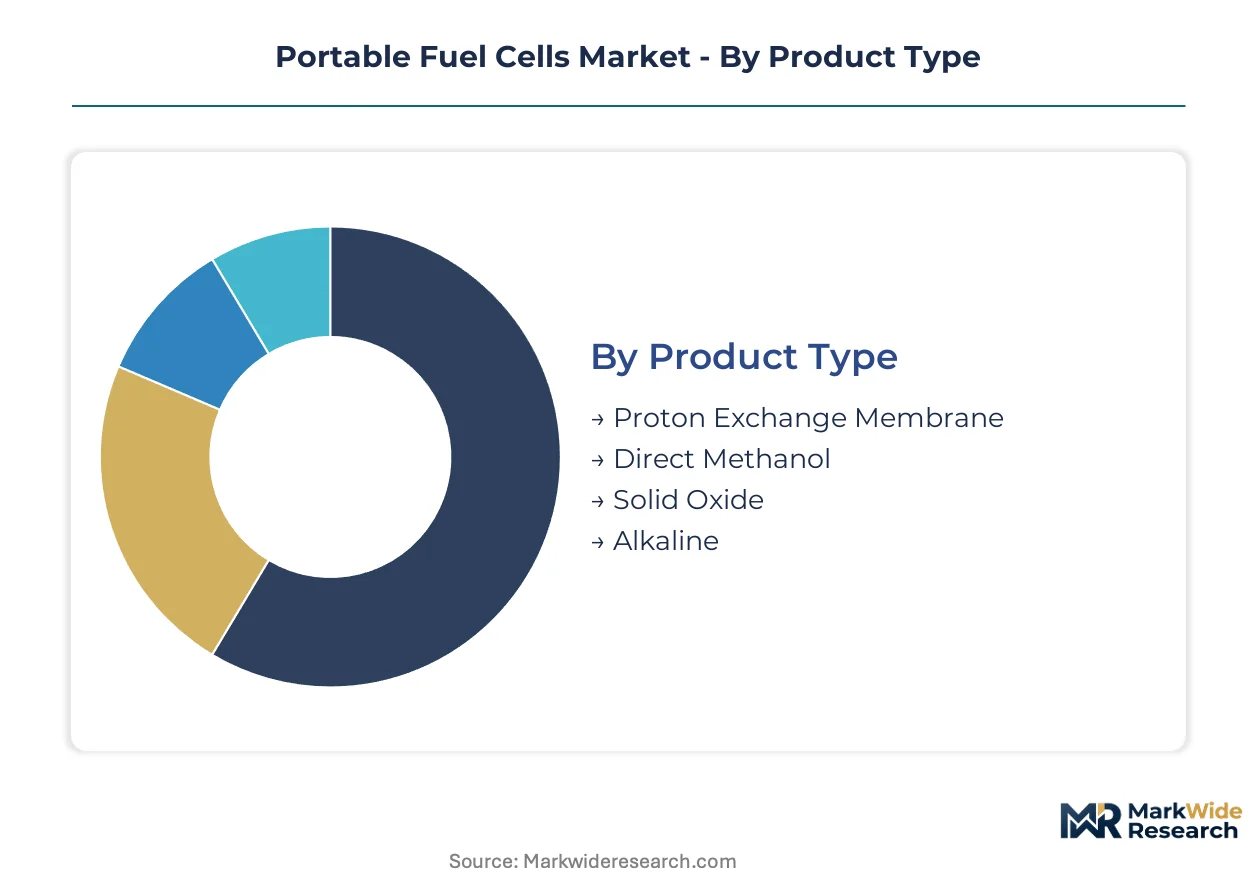
Portable fuel cells fragment across electrochemical architectures, power classes, and deployment contexts that each impose distinct manufacturing constraints and certification pathways. Understanding where margin pools concentrate versus where volume scales helps vendors prioritize R&D allocation and channel investments.
Product Type:
Membrane electrode assembly supply concentrates among Korean and German specialty chemical producers, creating input cost leverage points that cascade through stack manufacturer economics.
- Proton Exchange Membrane:Polymer electrolyte architectures achieve 40-60% system efficiency with sub-60-second cold-start capability. Defense procurement in Germany and emergency services specifications across California and Japan favor PEM for rapid deployment scenarios where thermal cycling delays are unacceptable.
- Direct Methanol:Liquid fuel compatibility eliminates hydrogen infrastructure dependencies, enabling military field units and marine applications where fuel logistics must mirror existing diesel supply chains. Methanol reformer integration opens remote deployment cases that hydrogen-dependent architectures cannot serve.
- Solid Oxide:Ceramic substrate designs operate at 600-800°C with superior efficiency for stationary cogeneration. Japanese building-scale heat-and-power pilots demonstrate modularity advances that compress minimum efficient scale.
- Alkaline:Aqueous electrolyte systems offer cost advantages in low-power consumer electronics where platinum catalyst loadings are prohibitive. Limited military adoption reflects cold-start performance gaps versus PEM alternatives.
Today's leader: Proton Exchange Membrane. Tomorrow's challenger: Direct Methanol.
End User:
Customer concentration varies sharply across procurement frameworks, with defense tender processes demanding multi-agency certification that excludes commercial-grade suppliers.
- Military:NATO framework agreements and Bundeswehr field power programs specify interoperability standards and standardized fuel cartridges. Prime integrator consolidation compresses vendor access to defense buyers.
- Backup Power:EPA zero-emission mandates for stationary generators and California data center requirements pull commercial demand toward CARB-verified PEM systems. Channel capture through electrical contractor programs accelerates replacement cycles.
- Consumer Electronics:Low-wattage alkaline and direct methanol units serve portable device charging where energy density trumps runtime extension. Price sensitivity limits margin expansion.
- Automotive:Auxiliary power units for electric vehicle range extension occupy a narrow niche where hydrogen refueling infrastructure availability constrains addressable geography.
Defense procurement anchors premium pricing; backup power segments are gaining share fastest.
Power Rating:
Manufacturing scale economies concentrate in higher-wattage classes where hardened packaging and extended runtime specifications justify specialized electrochemistry talent.
- Above 100W:Defense and emergency services specifications demand ruggedized enclosures, thermal management systems, and multi-day runtime. Margin pools concentrate here due to certification barriers and limited qualified supplier base.
- 25-100W:Professional field equipment and remote monitoring stations balance portability with sustained output. Methanol reformer compatibility expands addressable deployment contexts.
- 5-25W:Portable tool charging and recreational applications compete with lithium battery alternatives on total cost of ownership.
- 1-5W:Consumer electronics integration faces severe cost pressure from incumbent battery technologies and limited fuel cell miniaturization.
Above 100W commands structural premiums; 25-100W offers the steepest expansion trajectory.
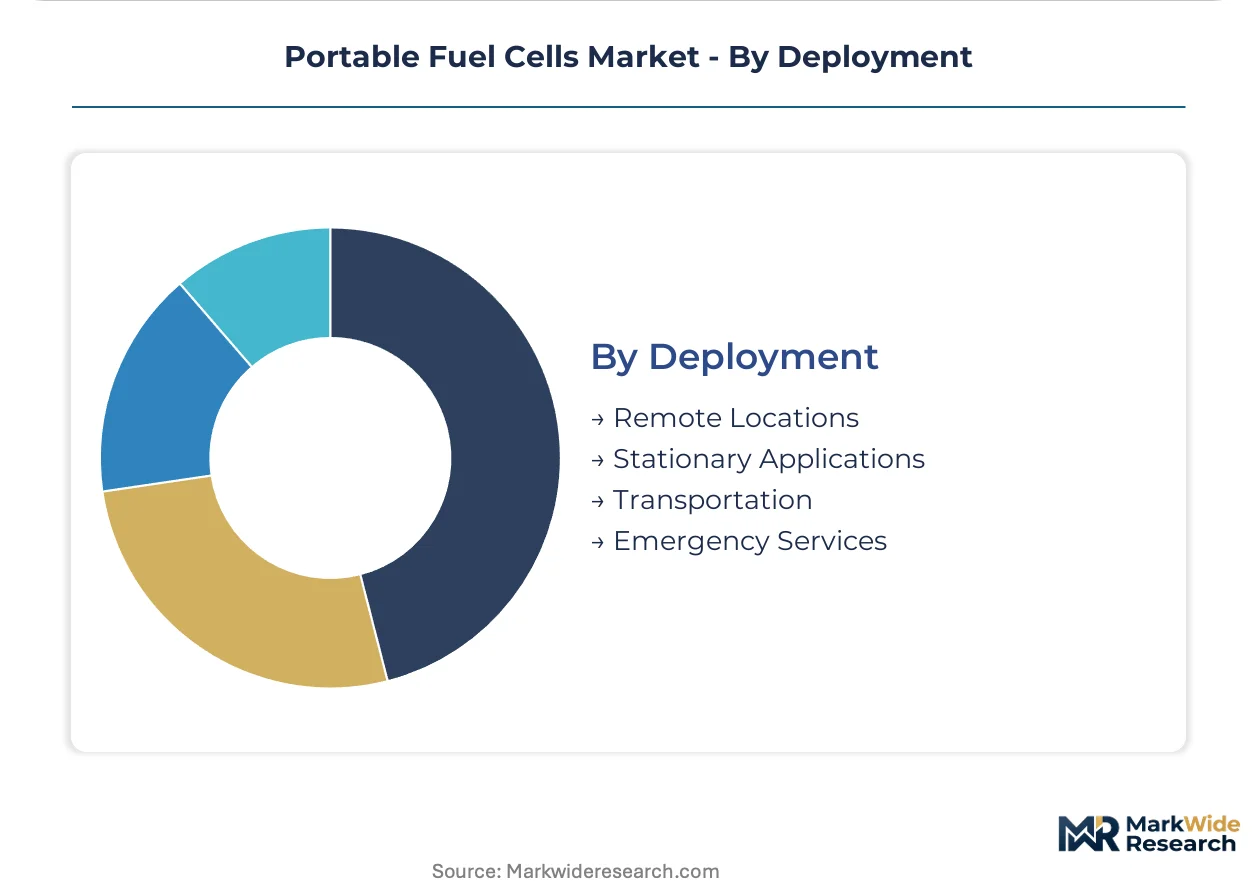
Deployment:
Geographic hydrogen infrastructure maturity and liquid fuel logistics availability determine which electrochemical architectures can serve each deployment context profitably.
- Remote Locations:Mining, forestry, and scientific field stations require off-grid reliability where diesel generator bans are tightening. Methanol logistics compatibility opens markets beyond hydrogen supply corridors.
- Emergency Services:First responder specifications demand sub-60-second startup and silent operation. PEM cold-start performance satisfies these constraints where solid oxide thermal cycling cannot.
- Stationary Applications:Building-scale backup and cogeneration favor higher efficiency over portability. Japanese and German pilot programs test solid oxide modularity for distributed generation.
- Transportation:Marine auxiliary power and recreational vehicle applications balance weight constraints with runtime requirements. Fuel cartridge standardization remains underdeveloped.
Remote Locations currently dominates volume; Emergency Services shows the fastest regulatory tailwind.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German defense procurement outpaces Japanese industrial pilots in deployment scale, while California's backup power mandates attract faster commercial certification cycles than Korean manufacturing clusters.
Germany
Bundeswehr field power programs and NATO interoperability standards anchor European military demand for PEM architectures. ECHA REACH compliance requirements for membrane materials extend certification timelines for stack suppliers. Bavaria's industrial corridor hosts SFC Energy's defense-focused manufacturing and testing facilities serving allied procurement frameworks.
United States
EPA zero-emission standards for backup generators and California data center mandates pull commercial buyers toward CARB-verified fuel cell systems. FERC grid interconnection rules affect stationary deployment economics for building-scale installations. The Pacific Northwest hydrogen hub development in Washington and Oregon expands refueling infrastructure for remote location applications.
Japan
METI-supported building-scale cogeneration pilots test solid oxide modularity for distributed heat-and-power applications. JIS standards for fuel cell safety certification create technical barriers for non-domestic stack manufacturers. The Kansai region around Osaka concentrates ceramic substrate research facilities advancing thermal cycling durability.
South Korea
Doosan Corporation's manufacturing scale at domestic facilities supplies Asian backup power markets with cost-competitive stack production. MFDS chemical registration requirements parallel EU REACH documentation burdens for membrane suppliers. The Seoul Capital Area anchors R&D talent pools for electrochemistry and systems integration engineering.
Portable Fuel Cells Market Competitive Environment
German producers anchor the defense-tier segment; Korean specialists hold manufacturing scale advantages in commercial backup power. Market structure bifurcates between interoperability-certified military suppliers and cost-optimized industrial vendors. Two strategic archetypes dominate: prime integrator partners serving NATO procurement frameworks, and vertically integrated stack manufacturers controlling membrane electrode assembly supply. Competitive moves concentrate on strategic partnerships with defense contractors and geographic expansion into hydrogen infrastructure corridors.
Within the prime integrator tier, SFC Energy AG exemplifies European defense anchoring through Bundeswehr relationships. Plug Power Inc. occupies a position representing North American PEM technology leadership through intensive R&D concentration. Doosan Corporation anchors Asian manufacturing scale for commercial backup power deployment.
| Leading Market Players |
|---|
| Plug Power Inc. |
| Doosan Corporation |
| AFC Energy PLC |
| Intelligent Energy Limited |
| Toshiba Corporation |
| SFC Energy AG |
| Panasonic Corporation |
| Horizon Fuel Cell Technologies |
| Ballard Power Systems Inc. |
| Others |
Value Chain & Pricing Dynamics
Bundeswehr and NATO defense procurement programs concentrate buyer power among interoperability-certified suppliers, embedding a project-based pricing structure where certification tier and runtime specifications determine contract value. This buyer concentration rewards early-moving PEM stack manufacturers with hardened packaging capabilities while compressing margins for commercial-grade suppliers lacking military approvals.
Pricing Analysis
Capacity additions in South Korea are reshaping price floors for commercial backup power segments. Three-tier pricing structure across defense-certified, industrial-grade, and consumer-tier levels separates segments by membrane electrode assembly quality and REACH compliance status. Cost compression in the consumer electronics tier intensifies because alkaline alternatives undercut direct methanol units on total cost of ownership. Military buyers exhibit the least price sensitivity due to mission-critical runtime requirements, while data center procurement teams negotiate aggressively on volume scale.
Supply Chain Analysis
German local-content mandates for defense procurement are reshaping sourcing patterns for membrane electrode assemblies. Manufacturing concentrates in South Korea, Germany, and Japan, with each hub feeding distinct certification pathways. Platinum group metal catalysts and perfluorinated membrane materials constitute critical input dependencies. Single-source vulnerability concentrates in Korean specialty chemical producers supplying iridium-based catalysts. Distribution runs through prime integrator channels for military end users and electrical contractor networks for commercial backup power deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where EPA zero-emission mandates and NATO interoperability standards are shifting procurement toward premium-certified PEM architectures with extended runtime specifications.
For Market Incumbents: Anticipate margin compression from methanol reformer integration technologies that expand addressable deployment contexts beyond hydrogen infrastructure corridors. Defensive consolidation around membrane electrode assembly talent pools in Bavaria and Seoul anchors manufacturing scale. Backward integration into short-chain fluoropolymer membrane production mitigates REACH authorization risks that disqualify incumbent chemistries. For New Entrants and Emerging Players: Marine auxiliary power buyers represent an underserved archetype where liquid fuel logistics compatibility opens white-space beyond hydrogen-dependent architectures. California data center backup mandates and Japanese building-scale cogeneration pilots offer the most penetrable regulatory tailwinds. A go-to-market angle through certified electrical contractor programs bypasses traditional generator distributor networks and captures replacement cycle velocity. For Investors and Strategic Acquirers: Defense prime integrators are the most active acquirer in this space, consolidating vendor lists around interoperability-certified platforms. The five-to-ten year viability window favors stack manufacturers with captive membrane electrode assembly supply and established Bundeswehr relationships. Watch for hydrogen refueling infrastructure buildout pace in Germany, Japan, and California as the critical inflection signal for remote location deployment economics.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Material Reformulation | Short-chain fluoropolymer alternatives satisfy ECHA REACH restrictions while preserving proton conductivity for defense tenders. |
| Prime Integrator Partnership | Approved supplier status within NATO framework agreements compresses competitive access for unqualified PEM vendors. |
| Methanol Reformer Integration | Liquid fuel logistics compatibility expands addressable use cases to marine and remote military applications beyond hydrogen corridors. |
| CARB Verification Investment | California Air Resources Board certification unlocks data center and telecommunications backup procurement pools under state mandates. |
| Electrical Contractor Channel Program | Direct-to-installer distribution reduces margin capture by traditional generator distributors in commercial building retrofits. |
Study Parameters
Bottom-up defense and industrial end-use modeling reconciled against top-down stack manufacturer production tracking forms the analytical core of this study. Primary interviews with Bundeswehr procurement officers, PEM stack engineering directors, membrane electrode assembly suppliers, data center facility managers, and CARB certification specialists combined with secondary validation from EPA regulatory filings, ECHA substance restriction databases, FERC interconnection rules, and NATO framework agreement documentation. Triangulation across these sources anchors volume and value estimates.
Input-output matrices map electrochemical architecture adoption against power rating classes, deployment contexts, and geographic hydrogen infrastructure maturity. Segmentation dimensions include product type, end user, power rating, and deployment context, with regional regulatory framework as an industry-specific overlay. CAGRs derive from deployment economics modeling across hydrogen supply corridors and liquid fuel logistics availability. Forecast inputs incorporate platinum group metal price volatility assumptions and membrane material authorization timelines.
Underlying measurement precision varies by segment; defense procurement volumes carry tighter precision than consumer electronics shipments due to tender documentation transparency. Forecasts reflect assumptions about hydrogen infrastructure buildout pace and REACH compliance pathway evolution. Regulatory acceleration or delays in EPA zero-emission implementation could revise commercial backup power adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuel Cell Technology
Direct Methanol Fuel Cell Market
Fuel Cell Technology
Japan Fuel Cell Market
Fuel Cell Technology
Protonic Ceramic Fuel Cell (PCFC) Market
Fuel Cell Technology
Europe Fuel Cell Market
Fuel Cell Technology
China Fuel Cell Market
Fuel Cell Technology
Fuel Cell Market
Fuel Cell Technology
North America Fuel Cell Market
Fuel Cell Technology
North America Fuel Cell Technology Market
Fuel Cell Technology
Asia-Pacific Fuel Cell Market
Fuel Cell Technology
Proton Exchange Membrane Fuel Cell (PEMFC) Market
Fuel Cell Technology
Asia-Pacific Direct Methanol Fuel Cell Market
Fuel Cell Technology
Global Micro Fuel Cells Market
Fuel Cell Technology
North America Microbial Fuel Cell Market
Fuel Cell Technology
Fuel Cell Interconnectors Market
Fuel Cell Technology
Hydrogen Fuel Cell Stack and Membrane Recycling for EU Mobility Market
Fuel Cell Technology
Fuel Vending Machines Market