
 China Fuel Cell Market | 2026-2036
China Fuel Cell Market Size, Share, and Industry Trends Forecast 2026-2036
China Fuel Cell Market Analysis
GB/T 24554 fuel cell engine performance testing is redrawing competitive access in China's hydrogen sector. Ballard Power Systems leverages its membrane electrode assembly expertise to anchor supply relationships with domestic bus manufacturers. Toyota Motor sustains technology leadership through its Mirai platform adaptations for Chinese fleet trials. Plug Power Inc. competes on electrolyzer-to-fuel-cell vertical integration for industrial hydrogen hubs.
A fuel cell converts chemical energy from hydrogen or hydrogen-rich fuels directly into electricity through electrochemical reactions, typically operating at 60-80°C for proton exchange membrane variants with power densities exceeding 2 kW per liter. The technology serves zero-emission transportation and distributed power generation without combustion byproducts. Proton exchange membrane systems dominate automotive end user demand due to cold-start capability and load-following performance, while solid oxide technology captures margin pools in stationary industrial applications through combined heat and output efficiencies above 60%. Transportation applications concentrate procurement volume around municipal bus and heavy truck segments, whereas backup power represents a mature niche with slower technology refresh cycles.
MIIT new energy vehicle catalog inclusion determines subsidy eligibility and manufacturer qualification, while SAMR enforces GB standard compliance for hydrogen storage and fuel cell stack safety. China's dual carbon goals mandate provincial hydrogen roadmaps that shape local demand patterns and infrastructure investment timelines. Stakeholders must monitor NMPA medical-grade hydrogen purity standards as they diffuse into industrial fuel specifications, and track MEE emissions accounting rules that redefine clean hydrogen certification thresholds for carbon intensity.
Market Dynamics
GB/T 24554 compliance requirements are compressing supplier qualification timelines while MIIT catalog inclusion gates determine subsidy access for domestic fuel cell engine manufacturers.
Growth Catalysts
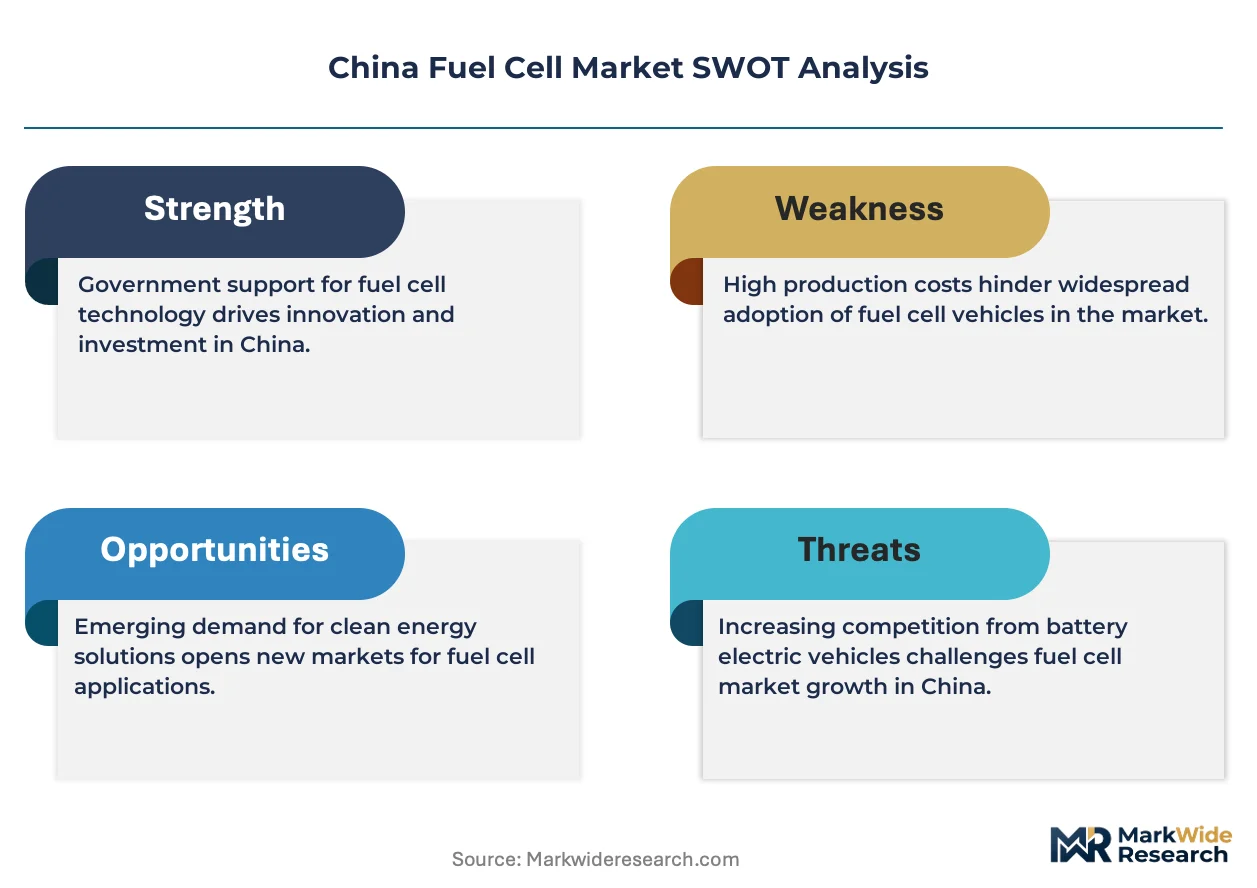
- Dual carbon policy mandate:Provincial hydrogen roadmaps in Shandong and Guangdong mandate fleet electrification targets that anchor demand visibility for heavy-duty trucking applications.
- PEM cold-start performance:Proton exchange membrane systems deliver sub-zero startup capability that unlocks year-round municipal bus deployment in northern Chinese provinces.
- Industrial zone clustering:Solid oxide fuel cell installations concentrate in coastal manufacturing corridors where combined heat and power economics outperform grid electricity tariffs.
Market Restraints
- Platinum group metal cost volatility:Membrane electrode assembly fabrication depends on iridium and platinum inputs subject to South African supply concentration and price swings.
- Hydrogen storage certification friction:SAMR enforcement of GB standards for 70 MPa composite tanks extends type-approval timelines for vehicle integrators.
- Battery electric substitution:Lithium-ion powertrains capture light-duty commercial segments where charging infrastructure outpaces hydrogen refueling station deployment.
Strategic Opportunities
- Western province penetration:Sichuan and Shaanxi hydrogen valleys offer untapped demand for stationary power systems serving energy-intensive industrial parks.
- Medical-grade hydrogen convergence:NMPA purity specifications diffusing into industrial fuel standards create premium certification tiers for electrolyzer-to-fuel-cell integrated suppliers.
- Refueling infrastructure buildout:Provincial SOE partnerships for hydrogen station networks open equipment procurement channels for compression and dispensing technology providers.
Industry Challenges
- Stack assembly technician scarcity:Precision membrane electrode assembly bonding and sealing operations require specialized cleanroom skills concentrated among limited training programs.
- GB standard harmonization delays:Divergent provincial interpretations of MIIT testing protocols create compliance fragmentation across manufacturing bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Fuel Cell Market |
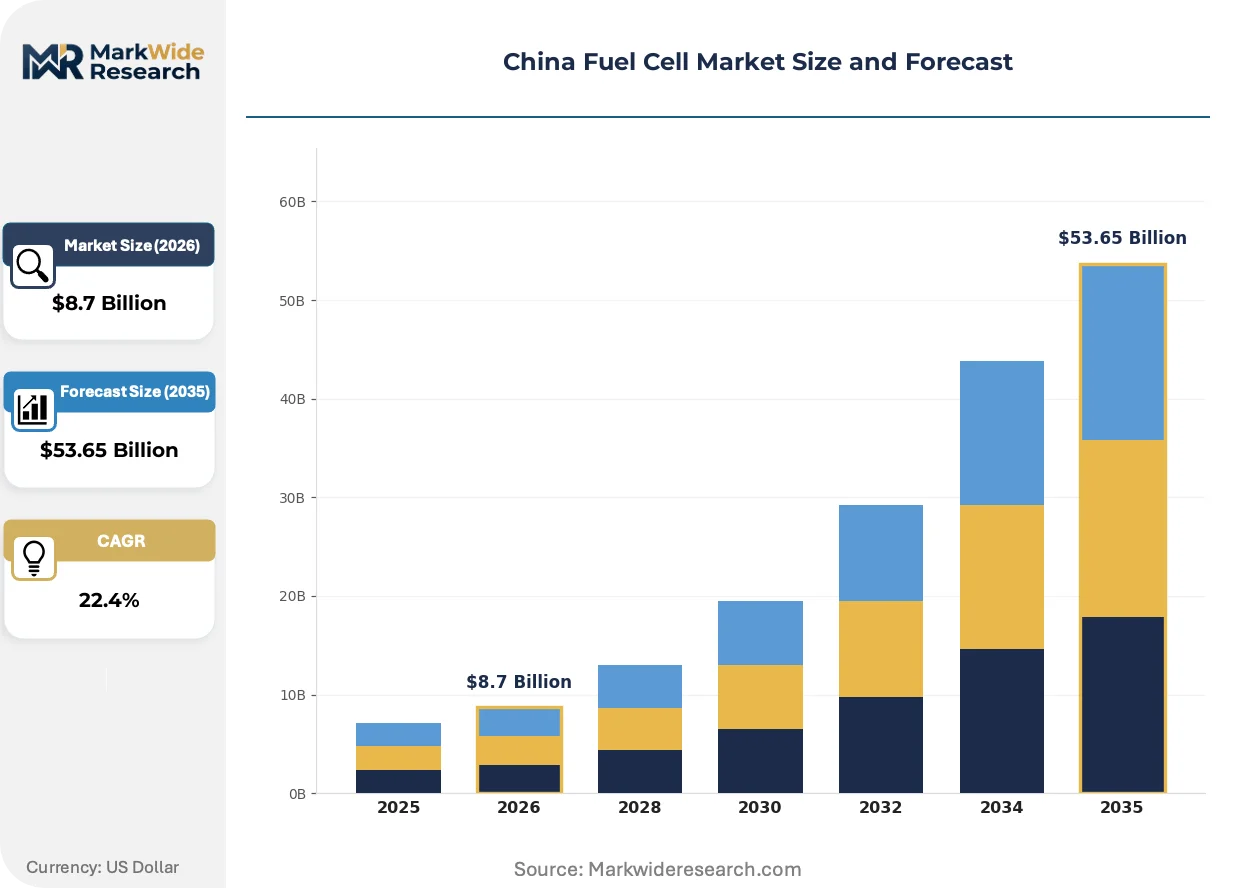
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $53.65 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proton Exchange Membrane, Solid Oxide, Molten Carbonate, Phosphoric Acid Application: Transportation, Stationary Power, Portable Power, Backup Power End User: Automotive, Industrial, Commercial, Residential Technology: Electrochemical, Reforming, Biogas, Hybrid |
| Companies Covered | Plug Power Inc., Ballard Power Systems, Toyota Motor, AISIN CORPORATION, Doosan Fuel Cell, Bloom Energy, SFC Energy AG, Hydrogenics Corporation, Nuvera Fuel Cells, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Fuel Cell Market Emerging Trajectories
Technology roadmaps are diverging between automotive PEM optimization and stationary solid oxide efficiency gains, while regulatory pressure accelerates domestic supply chain substitution.
Proton exchange membrane stack design is bifurcating between high-power density automotive variants and extended-lifetime stationary configurations. Bus manufacturers prioritize thin catalyst layer architectures that maximize volumetric power output for underfloor packaging constraints. This technical divergence is compressing supplier R&D budgets as dual development tracks strain engineering resources.
MEE emissions accounting rules are redefining clean hydrogen certification thresholds that determine carbon intensity eligibility for industrial fuel cell deployments. Manufacturing facilities must now document upstream electricity sources and steam methane reforming pathways to qualify for provincial green hydrogen subsidies. Heavy industry end-users in steel and chemicals sectors face the steepest compliance recalibration as they retrofit procurement specifications.
Fleet operators are consolidating procurement around integrated hydrogen service contracts that bundle fuel supply with maintenance and performance guarantees. Municipal bus authorities in Guangdong and Shandong increasingly specify total-cost-per-kilometer arrangements rather than discrete equipment purchases. This contracting evolution concentrates vendor selection among electrolyzer-to-dispensing integrated providers with captive hydrogen production assets.
China Fuel Cell Market Segmentation
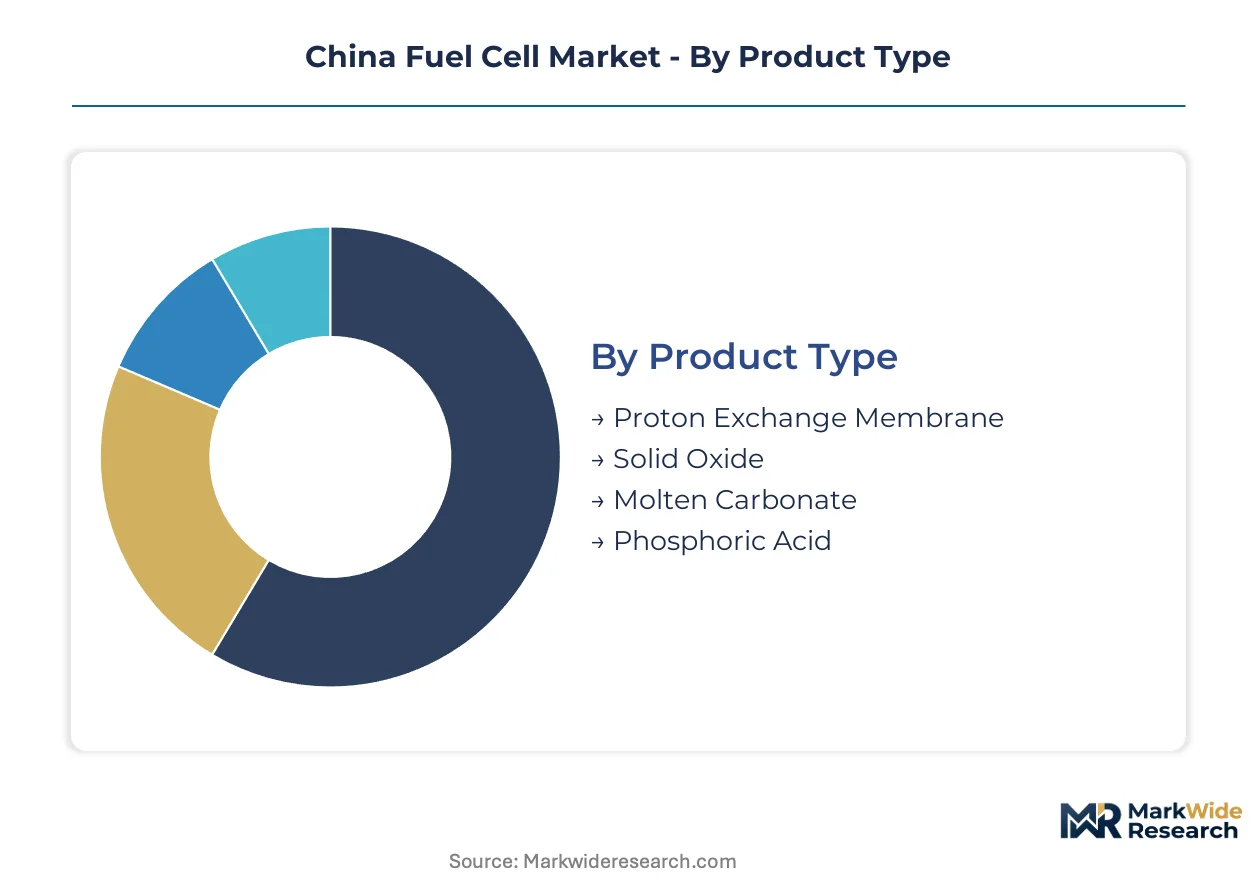
Technology differentiation across China's fuel cell market creates distinct procurement corridors governed by MIIT catalog standards and provincial hydrogen roadmaps. Segment boundaries harden around thermal operating regimes, end-use certification requirements, and infrastructure compatibility matrices that shape supplier qualification pathways.
Product Type:
MIIT new energy vehicle catalog inclusion criteria favor proton exchange membrane architectures for mobility subsidies, while MEE emissions accounting rules steer industrial buyers toward high-temperature variants with superior combined heat and power economics.
- Proton Exchange Membrane:Electrochemical conversion occurs at 60-80°C through platinum-catalyzed membrane electrode assemblies with power densities exceeding 2 kW per liter. Municipal bus fleets in northern Chinese provinces concentrate procurement here, driven by sub-zero cold-start capability that satisfies GB/T 24554 performance testing mandates.
- Solid Oxide:Ceramic electrolyte systems operate at 600-1000°C, achieving electrical efficiencies above 60% when configured for combined heat and power output. Coastal manufacturing corridors in Guangdong and Shandong anchor stationary deployments, where waste heat recovery economics outperform grid electricity tariffs for process industries.
- Molten Carbonate:Carbonate salt electrolyte systems suit large-scale baseload generation above 100 kW with internal reforming capability. Limited deployment concentrates in pilot hydrogen valleys where fuel flexibility offsets capital intensity.
- Phosphoric Acid:Mature phosphoric acid-doped silicon carbide matrix technology serves niche commercial cogeneration with proven 40,000-hour stack durability. Procurement volume trails emerging alternatives as efficiency benchmarks tighten.
Established volume favors proton exchange membrane; emerging adoption favors solid oxide.
Application:
End-use economics diverge sharply between mobility segments chasing total-cost-per-kilometer optimization and stationary installations capturing avoided grid charges.
- Transportation:Heavy-duty trucking and municipal bus fleets dominate procurement under Shandong and Guangdong provincial electrification mandates. SAMR hydrogen storage certification for 70 MPa composite tanks gates vehicle integrator participation.
- Stationary Power:Industrial parks and data centers deploy megawatt-scale systems for baseload substitution and grid independence. MEE clean hydrogen certification thresholds determine subsidy eligibility for carbon intensity documentation.
- Portable Power:Remote construction and emergency response applications drive sub-10 kW unit demand. Limited infrastructure dependence enables faster deployment timelines than stationary alternatives.
- Backup Power:Telecommunications and critical facility applications represent mature procurement with slower technology refresh cycles. Lithium-ion substitution pressure concentrates in shorter-duration outage protection segments.
Transportation commands procurement scale; stationary power captures margin expansion.
End User:
Customer sophistication varies across automotive OEM integration requirements, industrial process heat specifications, and commercial building energy management protocols.
- Automotive:Bus and truck manufacturers specify membrane electrode assembly performance under GB/T 24554 testing protocols. Dual carbon policy mandates create demand visibility through 2035 fleet electrification targets.
- Industrial:Steel, chemicals, and refining sectors retrofit procurement specifications around MEE emissions accounting rules. Hydrogen purity standards diffuse from NMPA medical-grade specifications into industrial fuel certifications.
- Commercial:Retail fueling stations and logistics hubs specify integrated hydrogen service contracts bundling supply with maintenance guarantees. Total-cost-per-kilometer arrangements displace discrete equipment purchases.
- Residential:Micro-cogeneration applications remain nascent due to hydrogen distribution infrastructure gaps and building code adaptation lags.
Automotive drives technology roadmap investment; industrial segments anchor profitability.
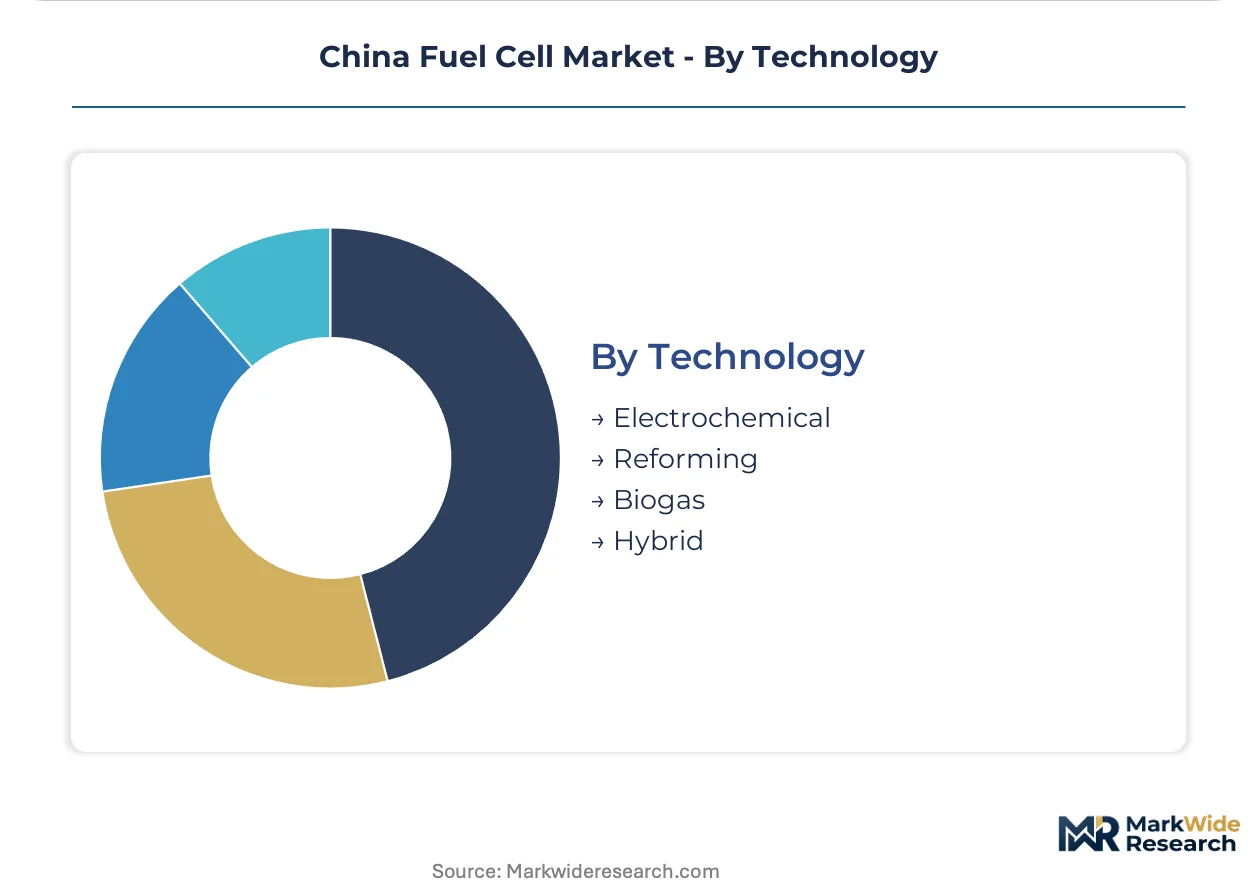
Technology:
Process pathway selection determines carbon intensity accounting, feedstock flexibility, and integration complexity with existing hydrogen production assets.
- Electrochemical:Direct hydrogen oxidation without combustion byproducts dominates automotive and stationary deployments. Platinum group metal cost volatility constrains membrane electrode assembly fabrication economics.
- Reforming:Natural gas and methanol reforming extends fuel flexibility for industrial zones lacking electrolyzer infrastructure. MEE upstream emissions documentation requirements complicate clean hydrogen certification.
- Biogas:Anaerobic digester output utilization serves agricultural and waste processing clusters with circular economy alignment. Scale limitations restrict deployment to distributed generation below 1 MW.
- Hybrid:Battery-fuel cell combinations optimize load-following performance for variable-duty transportation applications. System integration complexity elevates procurement qualification barriers.
Electrochemical systems hold technology leadership; reforming pathways retain transitional relevance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Heavy-duty fleet operators and industrial hydrogen buyers concentrate procurement decisions in provincial manufacturing corridors where MIIT catalog inclusion gates subsidy access. Provincial SOEs anchor infrastructure investment timelines through hydrogen refueling station buildout mandates.
Shandong Province
Heavy-duty trucking fleets drive demand concentration around Qingdao and Jinan industrial zones under provincial fleet electrification mandates. SAMR enforces GB standards for 70 MPa composite tank certification that gates vehicle integrator participation. Weifang hydrogen equipment manufacturing clusters host membrane electrode assembly bonding operations serving northern China bus procurement.
Guangdong Province
Pearl River Delta manufacturing corridors anchor stationary power deployments where solid oxide combined heat and power economics outperform grid tariffs. MEE emissions accounting rules redefine clean hydrogen certification thresholds for carbon intensity documentation. Shenzhen and Foshan industrial parks concentrate electrolyzer-to-fuel-cell integrated supplier qualification.
Sichuan Province
Hydrogen valleys in Chengdu-Chongqing economic circle offer untapped demand for stationary power systems serving energy-intensive industrial parks. Provincial hydrogen roadmaps under China's dual carbon goals shape local infrastructure investment timelines. Deyang and Mianyang manufacturing bases develop precision stack assembly technician training programs.
Jiangsu Province
Yangtze River Delta automotive OEM integration requirements concentrate membrane electrode assembly procurement around Suzhou and Nanjing. MIIT new energy vehicle catalog inclusion determines subsidy eligibility for domestic fuel cell engine manufacturers. Nantong and Changzhou industrial zones host cleanroom facilities for platinum-catalyzed layer fabrication.
Beijing-Tianjin-Hebei
Municipal bus authorities in Beijing specify total-cost-per-kilometer arrangements rather than discrete equipment purchases. GB/T 24554 fuel cell engine performance testing redrawing competitive access shapes vendor selection. Tianjin port logistics hubs pilot hydrogen refueling infrastructure for heavy truck corridor connectivity.
China Fuel Cell Market Vendor Landscape
Player mix skews toward multinational technology licensors and domestic system integrators competing on MIIT catalog qualification timelines. Market structure concentrates around membrane electrode assembly expertise and electrolyzer-to-dispensing integration capability. Two strategic archetypes dominate: automotive-focused PEM stack suppliers and stationary power solid oxide specialists. Competitive moves center on provincial SOE partnership formation and backward integration into hydrogen production assets.
Among North American technology providers, Ballard Power Systems and Plug Power Inc. occupy positions anchoring supply relationships with domestic bus manufacturers and industrial hydrogen hub development. Toyota Motor exemplifies automotive OEM adaptation strategies through fleet trial platforms. Ballard represents the membrane electrode assembly specialization archetype, while Plug Power sits within the electrolyzer-to-fuel-cell integration tier. SFC Energy AG and Doosan Fuel Cell anchor regional presence in stationary power segments.
| Leading Market Players |
|---|
| Plug Power Inc. |
| Ballard Power Systems |
| Toyota Motor |
| AISIN CORPORATION |
| Doosan Fuel Cell |
| Bloom Energy |
| SFC Energy AG |
| Hydrogenics Corporation |
| Nuvera Fuel Cells |
| Others |
Supply Flow & Price Mechanics
Ninety-day membrane electrode assembly procurement cycles concentrate pricing power among South African platinum group metal suppliers, compressing margins for domestic stack integrators while amplifying cost volatility pass-through to municipal bus fleet operators.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange platinum and iridium benchmarks dominate membrane electrode assembly procurement, with pricing stratifying across GB/T 24554-certified premium tiers, uncertified standard volumes, and economy-grade reformer-based systems. Price differentiation rests on MIIT catalog inclusion status and SAMR hydrogen storage certification level. Cost compression in economy-tier phosphoric acid systems is intensifying because battery electric substitution erodes addressable demand in light-duty segments. Municipal bus authorities exhibit highest price sensitivity due to total-cost-per-kilometer contracting mandates, while industrial stationary power buyers tolerate premium positioning for combined heat and power efficiency guarantees.
Supply Chain Analysis
Just-in-time membrane electrode assembly procurement prevails among automotive PEM stack manufacturers, whereas strategic stockpiling of iridium catalyst precursors characterizes stationary solid oxide deployments facing South African supply concentration. Geographic supply concentration centers on South Africa for platinum group metals, China for graphite bipolar plates and membrane substrates, and Japan for high-performance perfluorinated ionomer resins. Raw material dependencies draw from iridium, platinum, and yttria-stabilized zirconia ceramic electrolytes. Single-source vulnerability in South African mining operations constitutes the dominant structural risk. Distribution runs through provincial SOE hydrogen station networks that gate equipment procurement access for compression and dispensing technology providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's fuel cell market represents an early-cycle expansion story where dual carbon policy mandates create demand visibility through 2035 fleet electrification targets that outpace current supply chain readiness.
For Market Incumbents: Compound membrane electrode assembly expertise through backward integration into captive hydrogen production assets in Shandong and Guangdong hydrogen valleys. Defend qualification timelines against emerging domestic stack assemblers by accelerating GB/T 24554 testing protocol mastery. Prioritize technician training program scale-up to offset precision bonding skill scarcity that threatens capacity expansion.
For New Entrants and Emerging Players: Differentiate on electrolyzer-to-dispensing vertical integration to capture integrated hydrogen service contract procurement consolidating around Guangdong municipal bus authorities. Target Sichuan and Shaanxi western province hydrogen valleys where stationary power demand remains underpenetrated and local technician training infrastructure is nascent. Pursue NMPA medical-grade hydrogen purity certification as a go-to-market wedge to access premium industrial fuel specifications diffusing from medical applications.
For Investors and Strategic Acquirers: Long-term, this sits as a policy-anchored infrastructure play because provincial SOE hydrogen roadmaps create demand visibility unmatched by market-driven alternative energy transitions. Acquisition candidates should display membrane electrode assembly bonding capabilities or electrolyzer integration assets with MIIT catalog qualification momentum. Monitor MEE emissions accounting rule revisions as the critical inflection signal determining clean hydrogen subsidy eligibility thresholds for carbon intensity documentation.
| Strategic Initiative | Industry Significance |
|---|---|
| MIIT Catalog Qualification Acceleration | Determines subsidy access and gates competitive participation for domestic engine manufacturers. |
| Backward Integration into Electrolyzer Assets | Captures integrated hydrogen service contracts bundling fuel supply with maintenance guarantees. |
| Provincial SOE Partnership Formation | Opens equipment procurement channels for compression and dispensing technology providers. |
| Precision Stack Assembly Technician Training | Addresses skill scarcity threatening membrane electrode assembly bonding capacity expansion. |
| NMPA Medical-Grade Purity Certification | Creates premium tier access as industrial fuel specifications converge with medical standards. |
Methodological Framework
A spread of perspectives from fuel cell stack engineering directors, provincial SOE hydrogen infrastructure planners, MIIT certification specialists, and industrial park energy procurement managers converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against SAMR regulatory filings, MIIT new energy vehicle catalog databases, MEE emissions accounting guidelines, and provincial hydrogen roadmap policy documents. Bottom-up stack cost modeling and top-down provincial fleet electrification target aggregation provided triangulation checks across the analysis window.
Segmentation dimensions modeled span proton exchange membrane versus solid oxide versus molten carbonate technology architectures, transportation versus stationary versus portable power applications, and automotive OEM versus industrial process heat versus commercial fueling end-user categories. CAGRs derived from province-level fleet penetration curves and industrial zone combined heat and power economics. Forecast inputs incorporated platinum group metal price trajectory assumptions and GB standard harmonization timeline scenarios.
The analysis sits within stated boundaries; outcomes outside sustained dual carbon policy enforcement or accelerated battery electric substitution in light-duty segments would require recalibration. Forecasts reflect documented assumptions regarding SAMR certification timeline efficiency and MEE clean hydrogen threshold stability. Revision becomes warranted when South African platinum group metal supply disruption crosses logistical or geopolitical thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuel Cell Technology
Phosphoric Acid Fuel Cell Market
Fuel Cell Technology
Japan Fuel Cell Market
Fuel Cell Technology
Global Micro Fuel Cells Market
Fuel Cell Technology
High-Performance Fuel Cells Market
Fuel Cell Technology
Fuel Cell Interconnectors Market
Fuel Cell Technology
Europe Fuel Cell Market
Fuel Cell Technology
North America Fuel Cell Technology Market
Fuel Cell Technology
Hydrogen Fuel Cell Stack and Membrane Recycling for EU Mobility Market
Fuel Cell Technology
Proton Exchange Membrane Fuel Cell (PEMFC) Market
Fuel Cell Technology
North America Fuel Cell Market
Fuel Cell Technology
Residential Fuel Cell Market
Fuel Cell Technology
Global Planar Solid Oxide Fuel Cell Market
Fuel Cell Technology
Aircraft Fuel Cell Market
Fuel Cell Technology
France Fuel Cell Market
Fuel Cell Technology
Bipolar Plate Coatings Market
Fuel Cell Technology
Microbial Fuel Cell Market