
 High-Performance Fuel Cells Market | 2026-2036
High-Performance Fuel Cells Market Size, Share, and Industry Trends Forecast 2026-2036
High-Performance Fuel Cells Market Outlook
Multi-source membrane procurement is repositioning supply chain risk for stack assemblers. Ballard Power Systems anchors North American heavy-duty mobility through captive membrane partnerships. Toshiba Corporation leverages its solid oxide expertise to dominate Japan's stationary power segment. Plug Power Inc. sustains leadership in electrolyzer-integrated green hydrogen systems for material handling.
High-performance fuel cells are electrochemical devices converting hydrogen or hydrogen-rich fuels into electricity through controlled redox reactions, with proton-exchange membrane variants operating below 100°C and solid oxide variants exceeding 600°C for industrial cogeneration. Their primary purpose is delivering zero-emission baseload power where battery weight or charging duration disqualifies electrochemical storage. PEMFC technology leads transportation applications due to rapid cold-start capability and power density suited for vehicle propulsion. SOFC systems command margin pools in stationary power generation where waste heat recovery improves total system efficiency above 80 percent. Stack manufacturing remains the most concentrated value node, with membrane electrode assembly costs determining commercial viability across all product categories.
The US EPA and Department of Energy shape demand through IRA hydrogen hub funding and emerging NOx standards favoring zero-emission prime movers. The EU F-Gas Regulation and CE marking requirements under the MDR framework restrict fluorinated membrane chemistries while mandating lifecycle carbon disclosures for imported stacks. Stakeholders must monitor electrolyzer capacity buildouts against offtake commitments to assess whether green hydrogen supply will match fuel cell deployment timelines.
Market Dynamics
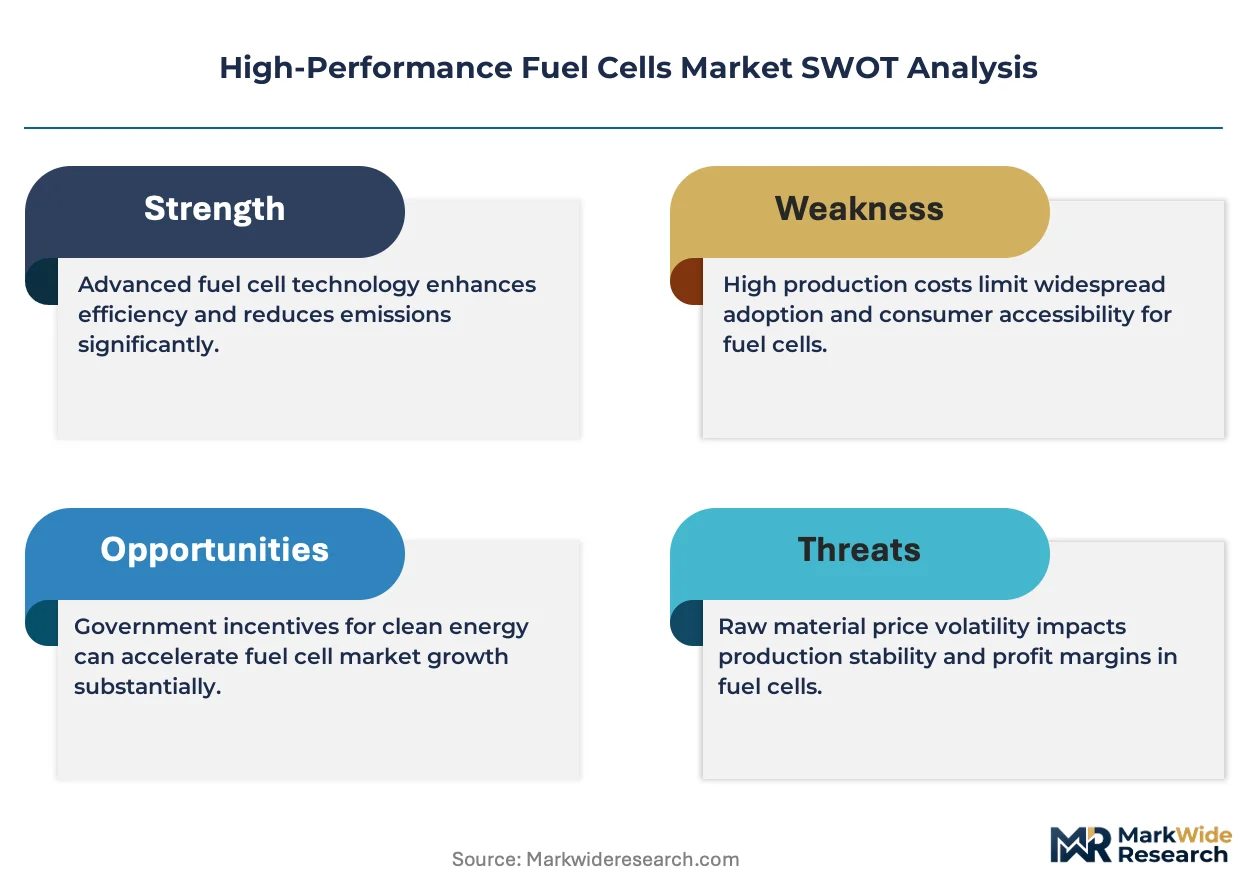
Stack assemblers face a structural squeeze between membrane supply concentration in Japan and Germany and offtake uncertainty from heavy-duty fleet operators awaiting hydrogen infrastructure buildouts. The tension between captive membrane partnerships and multi-source procurement strategies is forcing capital allocation decisions before demand curves stabilize.
Growth Catalysts
- US IRA hydrogen production tax credits:The Inflation Reduction Act's tiered credit structure rewards renewable-powered electrolysis, pulling private capital into green hydrogen supply chains that fuel cell deployments require.
- EU F-Gas Regulation phase-down:Restrictions on fluorinated greenhouse gases are accelerating membrane chemistry innovation toward fluorine-free alternatives while preserving European manufacturing capacity.
- Heavy-duty trucking fleet decarbonization mandates:California's Advanced Clean Trucks regulation and Germany's CO2 standards for commercial vehicles are creating guaranteed offtake volumes for proton-exchange membrane systems.
Market Restraints
- Platinum group metal cost volatility:Catalyst loading requirements for proton-exchange membrane stacks tie production economics to South African and Russian palladium-ruthenium supply disruptions.
- Electrolyzer capacity lag:Green hydrogen production timelines in the US Gulf Coast and Iberian Peninsula are trailing fuel cell manufacturing ramp schedules by 18-36 months.
- Solid oxide thermal cycling limitations:Ceramic stack degradation under rapid start-stop conditions restricts SOFC deployment to baseload industrial applications despite superior efficiency.
Strategic Opportunities
- Japan's port hydrogen hub infrastructure:METI-funded import terminals at Kobe and Yokohama are creating captive demand for megawatt-scale stationary fuel cells in maritime cold-ironing applications.
- Electrolyzer-fuel cell system integration:Bundled green hydrogen production and consumption assets allow developers to capture full value chain margins while hedging supply risk.
- Fluorine-free membrane chemistry breakthroughs:Hydrocarbon-based proton conductors are opening pathways to circumvent EU F-Gas restrictions and reduce catalyst loading requirements.
Industry Challenges
- Membrane electrode assembly technician scarcity:Precision coating and catalyst deposition skills concentrate at a handful of German and Japanese facilities, constraining stack quality at volume.
- CE marking timeline compression:The EU MDR framework's expanded technical documentation requirements are extending certification cycles for imported solid oxide systems by 8-14 months.
- Legacy fleet integration complexity:Retrofitting diesel terminal tractors and yard trucks with fuel cell powertrains requires custom driveline engineering absent standardized conversion kits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Performance Fuel Cells Market |
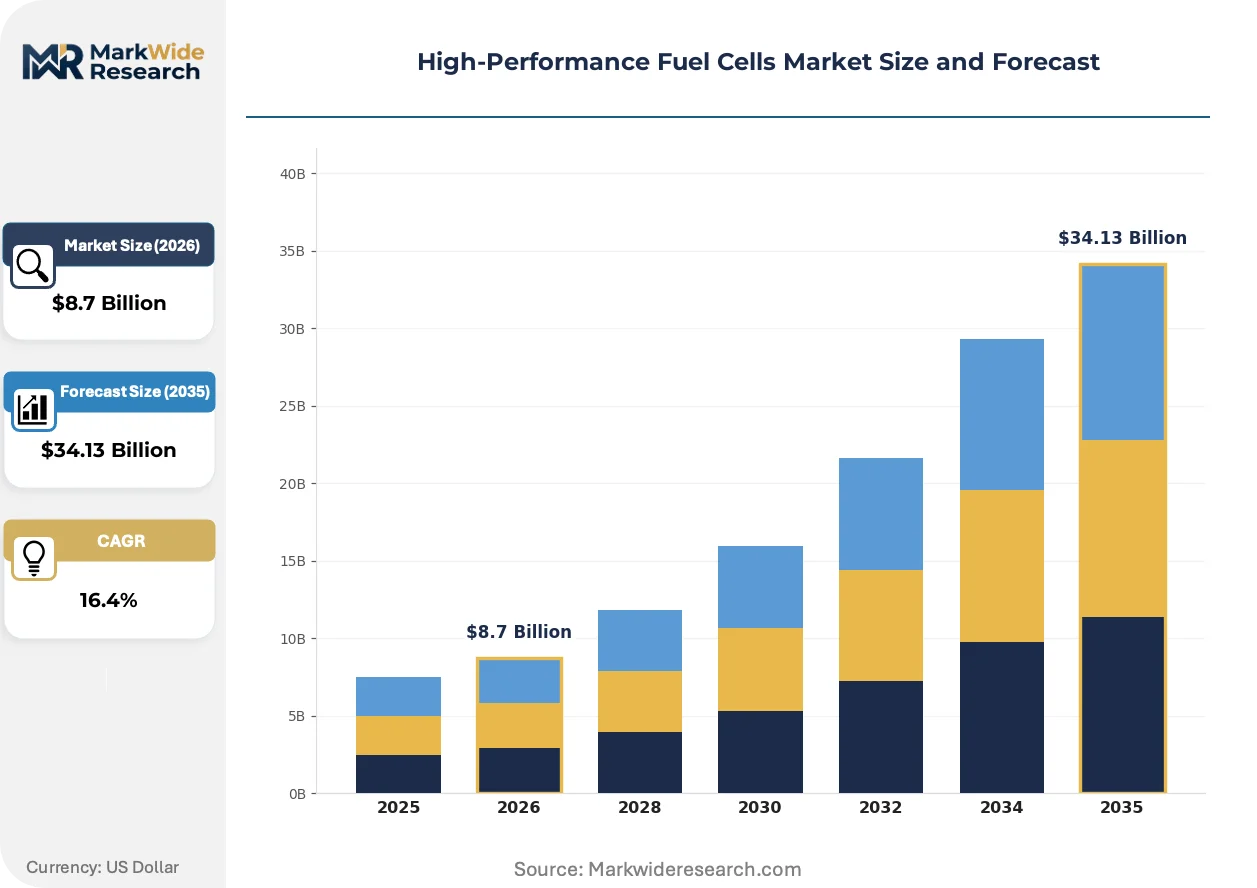
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PEMFC, SOFC, DMFC, AFC End User: Transportation, Industrial, Residential, Portable Devices Application: Power Generation, Backup Power, Vehicle Propulsion, Stationary Power Technology: Electrolyzer, Fuel Processor, Membrane, Stack |
| Companies Covered | Cummins Inc., FuelCell Energy, Inc., Ballard Power Systems Inc., Toshiba Corporation, Ceres Power Holdings PLC, Bloom Energy Corporation, Doosan Fuel Cell Co., Ltd., AFC Energy PLC, Plug Power Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Performance Fuel Cells Market Strategic Shifts
Anion-exchange membrane chemistry is disrupting the proton-exchange membrane dominance that has defined transportation fuel cells for three decades. Materials innovation, regulatory chemistry restrictions, and buyer procurement recalibration are converging to restructure competitive positioning.
Anion-exchange membranes are rewriting the cost structure for heavy-duty mobility by enabling platinum-free catalysts and wider operating temperature windows. Bus and truck manufacturers in South Korea and Germany are piloting AEM stacks at 500-kilowatt scale for regional delivery routes. The technology is rewriting supplier power dynamics by reducing dependence on South African platinum supply and Japanese perfluorinated membrane producers.
The EU F-Gas Regulation's accelerated phase-down schedule is forcing membrane manufacturers to retool production lines before 2030. Fluoropolymer-dependent proton-exchange membrane producers face stranded asset risk if hydrocarbon alternatives reach automotive durability targets. The regulation is compressing most acutely in Germany's industrial cluster supply chains, where stack assemblers are dual-sourcing fluorine-free membranes from Korean and domestic startups.
Fleet operators are consolidating procurement decisions under energy service companies that bundle hydrogen supply, fuel cell assets, and maintenance into single-contract structures. This disintermediates traditional equipment vendors and transfers performance risk to fuel cell system integrators. The shift is most visible in California's San Pedro Bay port complex, where terminal operators have transferred capital deployment to third-party hydrogen infrastructure developers.
High-Performance Fuel Cells Market Segmentation
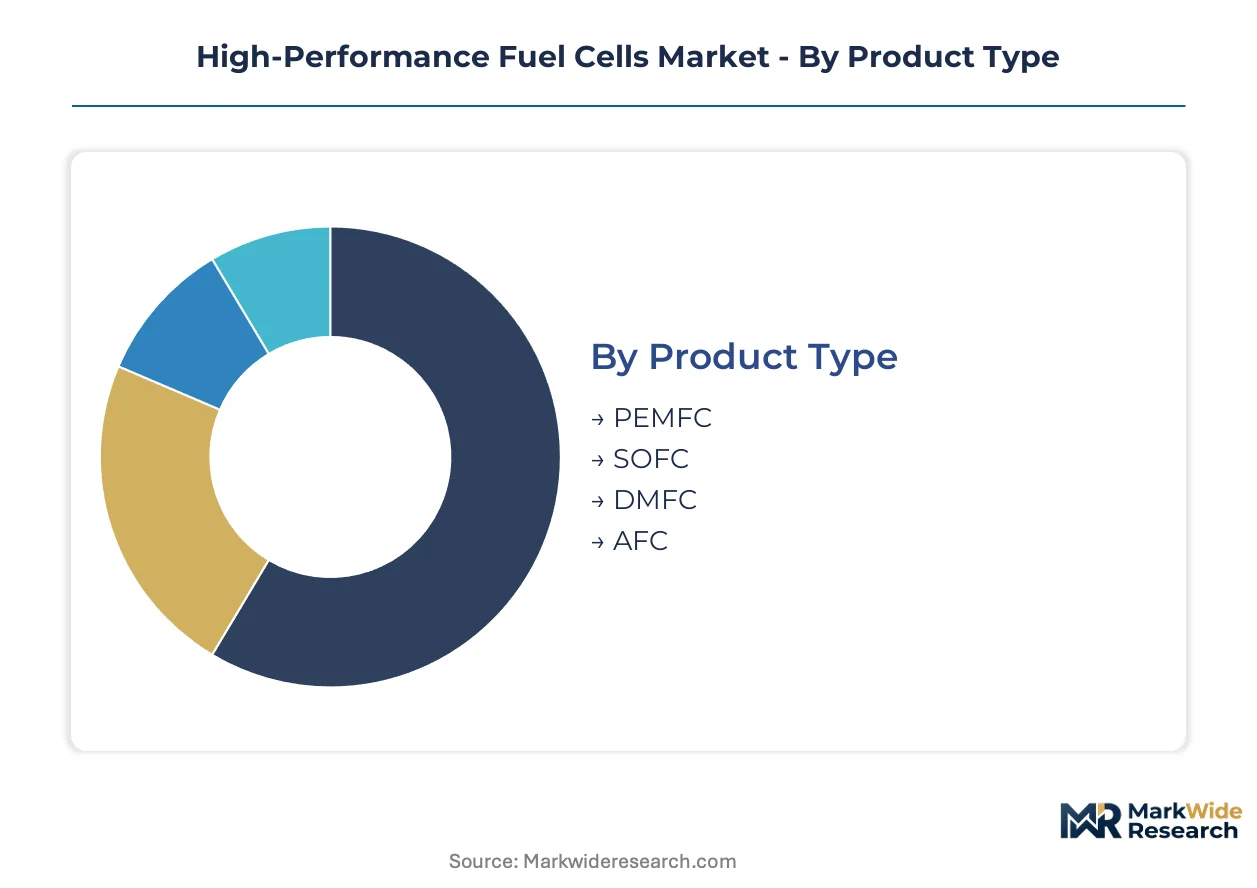
Segmentation in high-performance fuel cells determines which regulatory pathways manufacturers must navigate. CE marking under the EU MDR framework applies differentially across product types, while transportation deployments trigger NHTSA safety certifications in the United States.
Product Type:
PEMFC and SOFC systems carry distinct certification burdens under EU F-Gas Regulation and EPA emissions frameworks, with membrane chemistry dictating compliance timelines.
- PEMFC:Proton-exchange membrane fuel cells operate below 100°C using perfluorinated or hydrocarbon membranes. California's Advanced Clean Trucks regulation and Germany's freight corridor subsidies are concentrating demand for heavy-duty vehicle propulsion, though platinum catalyst loading ties economics to South African supply chains.
- SOFC:Solid oxide fuel cells exceed 600°C operating temperatures, enabling industrial cogeneration with waste heat recovery above 80% system efficiency. Japan's METI-funded port hydrogen hubs at Kobe and Yokohama anchor stationary power demand, constrained by ceramic stack degradation under thermal cycling.
- DMFC:Direct methanol fuel cells use liquid fuel logistics bypassing hydrogen infrastructure. Portable and light mobility applications in South Korea and Germany leverage existing methanol distribution networks.
- AFC:Alkaline fuel cells employ liquid electrolyte systems with lower material costs. Niche aerospace and maritime backup power deployments concentrate where hydrogen purity can be guaranteed.
Leading the category by volume: PEMFC. Growing fastest: SOFC.
End User:
Customer archetypes split procurement patterns between fleet-scale hydrogen service contracts and individual asset purchases.
- Transportation:Heavy-duty trucking fleets in California, Germany, and Japan negotiate bundled hydrogen supply agreements. The US IRA production tax credits reduce fuel costs for Class 8 truck operators committing to zero-emission mandates.
- Industrial:Chemical plants and steel mills deploy megawatt-scale SOFC systems for process heat and power. EU carbon border adjustment mechanisms accelerate adoption in German industrial clusters.
- Residential:Combined heat and power units in Japan and South Korea serve single-family homes with grid-independent baseload. Subsidy programs in Tokyo and Seoul offset capital costs.
- Portable Devices:Military and emergency response units require field-deployable power without fuel logistics. DMFC and small PEMFC systems dominate this fragment.
Highest capital deployment: Transportation. Steepest expansion trajectory: Industrial.
Application:
Use-case segmentation tracks whether systems operate continuously or cyclically, determining stack durability specifications.
- Power Generation:Grid-connected fuel cell parks in Japan and South Korea provide dispatchable clean electricity. METI and KEMCO tariffs support 24/7 operation contracts.
- Backup Power:Telecommunications and data center operators in Germany and California install fuel cells for grid outage resilience. SOFC systems dominate where extended runtime exceeds battery economics.
- Vehicle Propulsion:Bus and truck powertrains in California's San Pedro Bay and Germany's Rhine-Alpine corridor require rapid cold-start capability. PEMFC technology leads due to power density and start times under 30 seconds.
- Stationary Power:Industrial facilities and port operations use fixed installations with waste heat recovery. Japan's maritime cold-ironing regulations at Yokohama create captive demand.
Dominant by installed capacity: Stationary Power. Gaining share fastest: Vehicle Propulsion.
Technology:
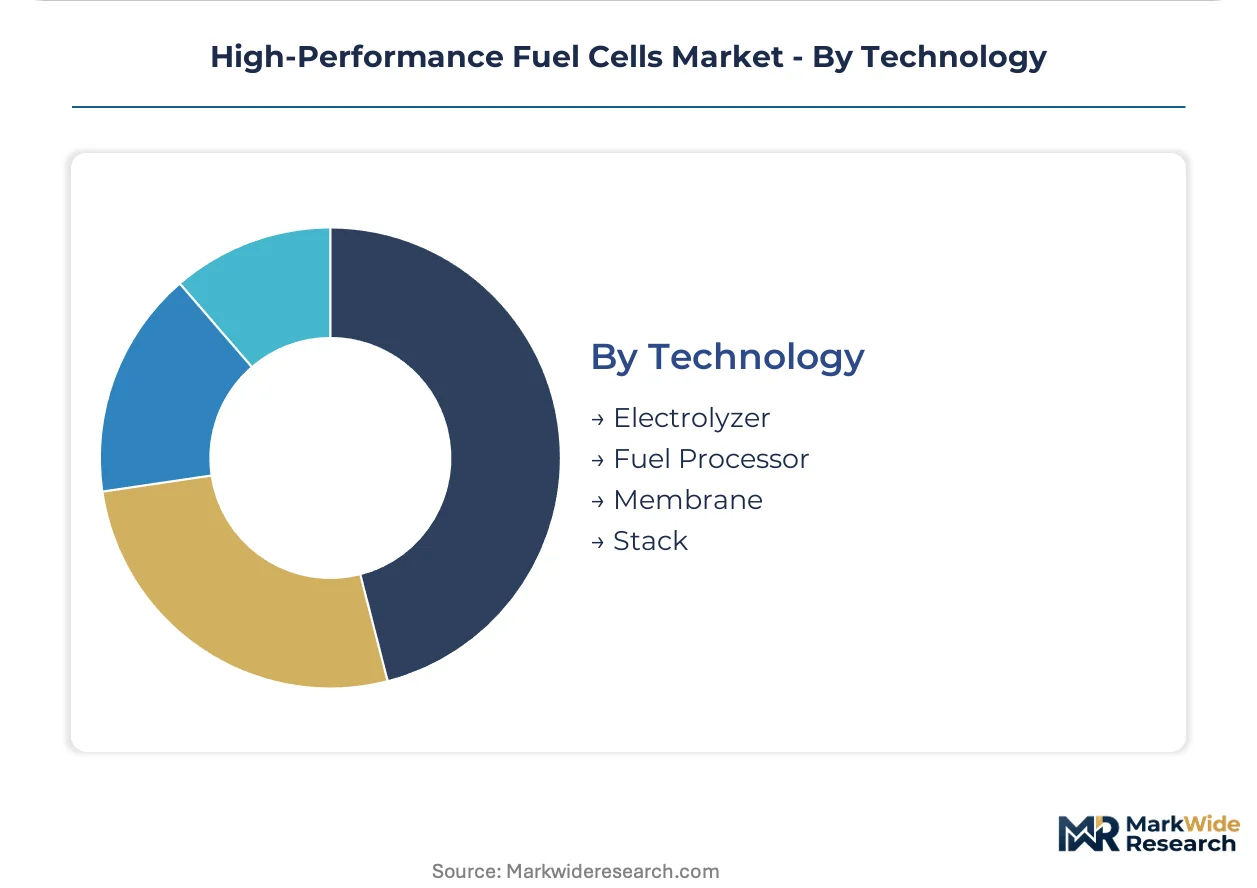
Value chain position determines margin capture and supply chain risk exposure for component manufacturers.
- Electrolyzer:Green hydrogen production systems integrate with fuel cell deployments in bundled asset configurations. US Gulf Coast and Iberian Peninsula capacity buildouts lag fuel cell manufacturing ramps by 18-36 months.
- Fuel Processor:Reforming units convert natural gas or methanol to hydrogen-rich feedstock. Industrial applications in Germany and Japan leverage existing pipeline infrastructure.
- Membrane:Proton and anion-exchange materials determine stack efficiency and regulatory compliance. EU F-Gas Regulation phase-down accelerates fluorine-free chemistry development.
- Stack:Membrane electrode assembly manufacturing concentrates in German and Japanese facilities. Technician scarcity for precision coating constrains quality at volume.
Capturing highest value per kilowatt: Stack. Expanding production capacity most aggressively: Electrolyzer.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platinum group metal deposits in South Africa and Russia anchor catalyst supply chains for proton-exchange membrane stacks, concentrating procurement risk in jurisdictions with volatile export regimes. Japan's port hydrogen infrastructure and Germany's industrial cluster policy are reshaping regional deployment patterns.
United States
Heavy-duty trucking fleets along California's freight corridors and Gulf Coast hydrogen hubs drive PEMFC demand for Class 8 vehicles. The EPA and Department of Energy coordinate IRA hydrogen production tax credits with NHTSA safety certifications. The San Pedro Bay port complex hosts terminal operators transferring capital deployment to third-party hydrogen infrastructure developers.
Germany
Rhine-Alpine corridor freight operators and chemical plant operators in North Rhine-Westphalia anchor SOFC demand for industrial cogeneration. The EU F-Gas Regulation and CE marking requirements under the MDR framework restrict fluorinated membrane chemistries. Baden-Württemberg's automotive suppliers are dual-sourcing fluorine-free membranes from domestic startups.
Japan
METI-funded port hydrogen hubs at Kobe and Yokohama create captive demand for megawatt-scale stationary fuel cells in maritime cold-ironing applications. JIS standards and METI tariff structures support 24/7 operation contracts for grid-connected fuel cell parks. Tokyo's residential combined heat and power subsidy programs offset capital costs for single-family installations.
South Korea
Bus and truck manufacturers are piloting anion-exchange membrane stacks at 500-kilowatt scale for regional delivery routes. The MFDS and KEMCO coordinate certification with tariff support for dispatchable clean electricity. Seoul's energy service companies bundle hydrogen supply, fuel cell assets, and maintenance into single-contract structures.
United Kingdom
Ceres Power Holdings PLC anchors solid oxide expertise for industrial cogeneration applications. The country's national energy regulator coordinates with ECHA on REACH compliance for membrane materials. Oxfordshire's manufacturing facilities concentrate ceramic stack production for export to European industrial clusters.
High-Performance Fuel Cells Market Competitive Environment
Capacity expansion dominates the current landscape as stack assemblers race to secure membrane electrode assembly output before demand curves stabilize. The vendor base concentrates around three strategic archetypes: captive membrane partnerships, electrolyzer-integrated system bundlers, and solid oxide specialists pursuing industrial cogeneration. Geographic expansion and technology licensing represent the dominant competitive moves, with players seeking to circumvent EU F-Gas restrictions through hydrocarbon-based proton conductor development.
Among North American heavy-duty mobility specialists, Ballard Power Systems Inc. and Plug Power Inc. occupy positions within the captive partnership tier. Toshiba Corporation exemplifies the solid oxide archetype dominating Japan's stationary power segment. These three companies represent distinct strategic postures: membrane supply security, electrolyzer-fuel cell integration, and high-temperature industrial cogeneration respectively.
| Leading Market Players |
|---|
| Cummins Inc. |
| FuelCell Energy, Inc. |
| Ballard Power Systems Inc. |
| Toshiba Corporation |
| Ceres Power Holdings PLC |
| Bloom Energy Corporation |
| Doosan Fuel Cell Co., Ltd. |
| AFC Energy PLC |
| Plug Power Inc. |
| Others |
Value Chain & Pricing Dynamics
Fleet operator consolidation under energy service company contracts is forcing stack assemblers to absorb performance risk and bundle long-term maintenance, compressing upfront equipment margins while shifting revenue toward service annuities.
Pricing Analysis
Warranty and service bundling separates premium-tier proton-exchange membrane stacks with 10-year membrane replacement guarantees from unbundled economy configurations where operators assume degradation risk. Price differentiation hinges on CE marking tier under EU MDR and platinum catalyst loading grade. Cost compression in mid-tier transportation stacks is intensifying because anion-exchange membrane alternatives are displacing perfluorinated materials. Heavy-duty trucking fleets in California's freight corridors exhibit highest price sensitivity, while Japan's port hydrogen hub operators prioritize reliability over capital cost.
Supply Chain Analysis
Platinum group metal supply rests on South African mining operations and Russian export channels, with palladium-ruthenium catalyst feedstock drawing from concentrated refining capacity in those jurisdictions. Membrane electrode assembly production concentrates in German precision coating facilities and Japanese perfluorinated polymer plants. Single-source vulnerability in fluoropolymer supply chains has intensified as EU F-Gas Regulation accelerates phase-down timelines. Distribution runs through captive membrane partnerships for North American heavy-duty mobility and direct procurement for European industrial cogeneration deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around stack assemblers with secured membrane supply and electrolyzer integration capabilities, as electrolyzer capacity lag and technician scarcity force subscale players toward exit or acquisition.
For Market Incumbents: Cement membrane supply security through dual-sourcing hydrocarbon alternatives from Korean and domestic startups before EU F-Gas deadlines harden. Expand captive electrolyzer capacity in US Gulf Coast and Iberian Peninsula clusters to capture full value chain margins and hedge green hydrogen supply risk against fuel cell manufacturing ramp schedules. For New Entrants and Emerging Players: Direct-to-fleet digital procurement platforms offer lower customer acquisition costs than traditional equipment vendor channels for anion-exchange membrane pilot programs. Target South Korean bus and truck manufacturers piloting 500-kilowatt AEM stacks for regional delivery routes, where platinum-free catalysts circumvent South African supply concentration. For Investors and Strategic Acquirers: Re-rating potential sits with solid oxide specialists possessing ceramic stack durability expertise given Japan's METI-funded port hydrogen hub buildouts and maritime cold-ironing regulations. Long-term viability favors acquisitions of membrane electrode assembly technicians and precision coating facilities in Germany's industrial clusters. Watch electrolyzer capacity buildout against fuel cell offtake commitments as the inflection signal for supply-demand balance.| Strategic Initiative | Industry Significance |
|---|---|
| Fluorine-Free Membrane Chemistry Development | EU F-Gas Regulation compliance accelerates hydrocarbon proton conductor commercialization before 2030 deadlines. |
| Electrolyzer-Fuel Cell System Integration | Bundled green hydrogen production and consumption assets capture full value chain margins in California and Germany. |
| Membrane Electrode Assembly Capacity Expansion | German and Japanese precision coating facilities face technician scarcity constraining quality at volume. |
| Anion-Exchange Membrane Pilot Scale-Up | South Korean 500-kilowatt AEM deployments enable platinum-free catalysts and wider operating temperature windows. |
| Port Hydrogen Hub Infrastructure Partnership | METI-funded terminals at Kobe and Yokohama create captive demand for megawatt-scale stationary fuel cells. |
Study Parameters
SEC 10-K filings, EU F-Gas Regulation compliance disclosures, and METI hydrogen hub funding announcements formed the secondary backbone for market sizing and regulatory timeline validation. Primary interviews with stack manufacturing executives, membrane electrode assembly technicians, fleet procurement managers, and electrolyzer project developers were triangulated against customs data for platinum group metal imports and bottom-up stack shipment tracking.
Bottom-up unit economics modeling of membrane electrode assembly costs, catalyst loading requirements, and system integration margins was cross-validated against top-down hydrogen demand projections from industrial cluster policies. Segmentation by product type, end user, application, and technology captured differential regulatory pathways across CE marking, NHTSA certification, and JIS standards. CAGRs were derived from electrolyzer capacity buildout schedules and fuel cell manufacturing ramp assumptions across the analysis window.
Inputs from primary fieldwork and regulatory filing databases were available through the study window; gaps in real-time electrolyzer commissioning data and membrane electrode assembly technician headcounts introduce uncertainty bands around capacity expansion timelines. Forecasts reflect documented assumptions regarding IRA hydrogen production tax credit continuity and EU CO2 standards enforcement. A small set of triggers—electrolyzer commissioning delays, platinum supply disruptions, and fluorine-free membrane durability validation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuel Cell Technology
Regenerative Fuel Cell (RFC) Technologies Market
Fuel Cell Technology
Hydrogen Fuel Cell Drone Market
Fuel Cell Technology
Global Planar Solid Oxide Fuel Cell Market
Fuel Cell Technology
Europe Fuel Cell Market
Fuel Cell Technology
Fuel Cell Interconnectors Market
Fuel Cell Technology
Hydrogen Fuel Cell Stack and Membrane Recycling for EU Mobility Market
Fuel Cell Technology
Fuel Cell Stack Market
Fuel Cell Technology
Helium Recovery Systems Market
Fuel Cell Technology
Fuel Cell for Stationary Power Market
Fuel Cell Technology
Germany Fuel Cell Market
Fuel Cell Technology
Fuel Cell for Data Center Market
Fuel Cell Technology
Fuel Cell Technology Market
Fuel Cell Technology
Asia-Pacific Fuel Cell Market
Fuel Cell Technology
Global Fuel Cell Balance of Plant (BOP) Market
Fuel Cell Technology
North America Fuel Cell Market
Fuel Cell Technology
France Fuel Cell Market