
 Europe Smart Grid Security Market | 2026-2036
Europe Smart Grid Security Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Smart Grid Security Market Intelligence
The convergence of operational technology and information technology layers is narrowing attack surfaces across European power networks. Siemens AG leverages deep domain expertise in substation automation to anchor its position in hardware-integrated security stacks. Schneider Electric SE differentiates through end-to-end software platforms that span grid operations from transmission to prosumer endpoints. Cisco Systems, Inc. competes on network visibility tools purpose-built for IEC 61850 protocol environments.
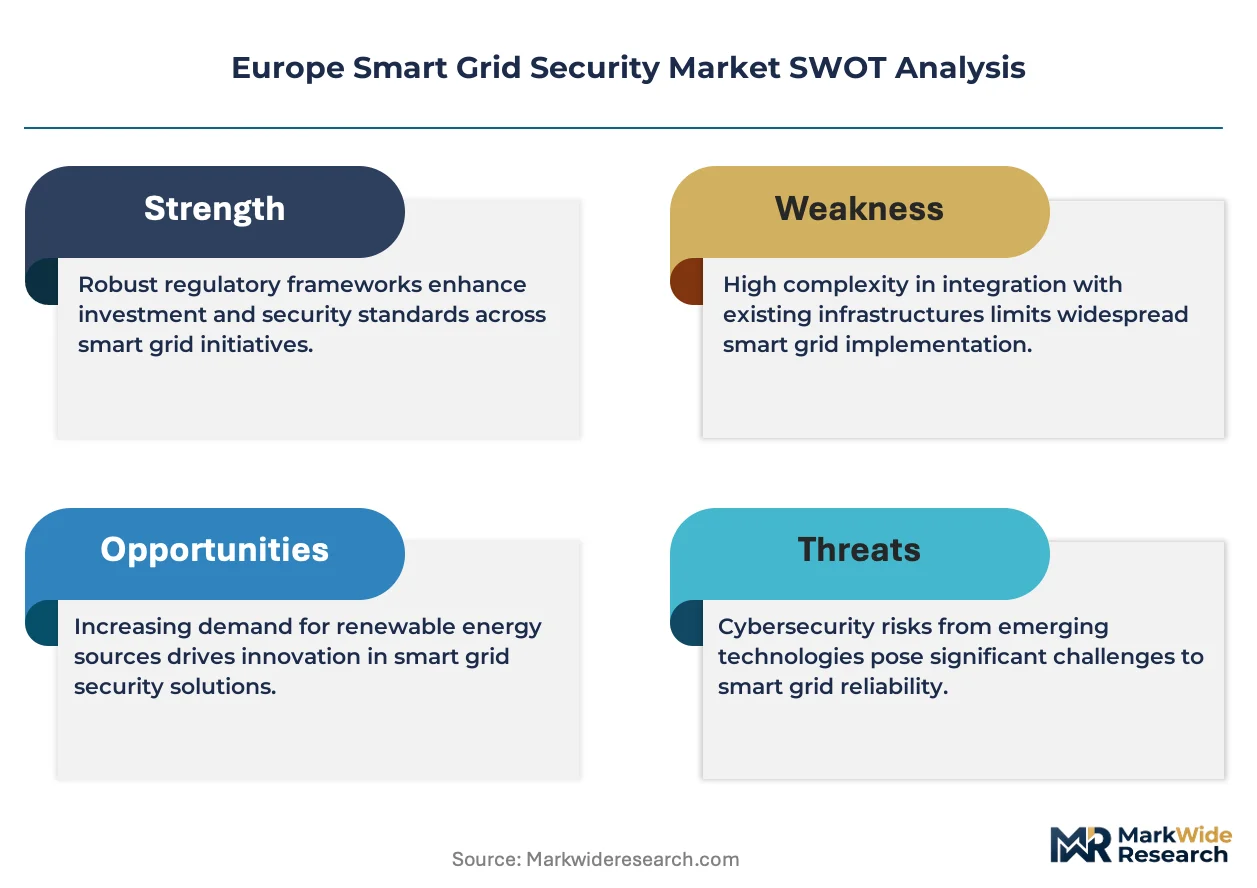
Europe Smart Grid Security encompasses cryptographic protection, anomaly detection, and access governance systems engineered to safeguard bidirectional communication between generation assets, transmission systems, and distributed energy resources against cyber-physical intrusion. These systems typically deploy AES-256 encryption, behavioral analytics engines processing thousands of SCADA events per second, and zero-trust architectures to maintain grid stability and consumer data integrity. Encryption and identity management segments attract premium margins as utilities confront NIS2-mandated supply chain authentication requirements. Cloud-based deployment models represent the fastest-growing structural category, though on-premises architectures still dominate among transmission system operators with sovereign data constraints.
The EU Cybersecurity Act, NIS2 Directive, and ENISA technical standards collectively reshape product certification requirements and procurement criteria for European utilities. ECHA chemical safety protocols and CE marking obligations further constrain hardware component sourcing for grid security appliances. Stakeholders must track evolving ENISA threat intelligence frameworks and national transposition timelines to anticipate compliance-driven replacement cycles.
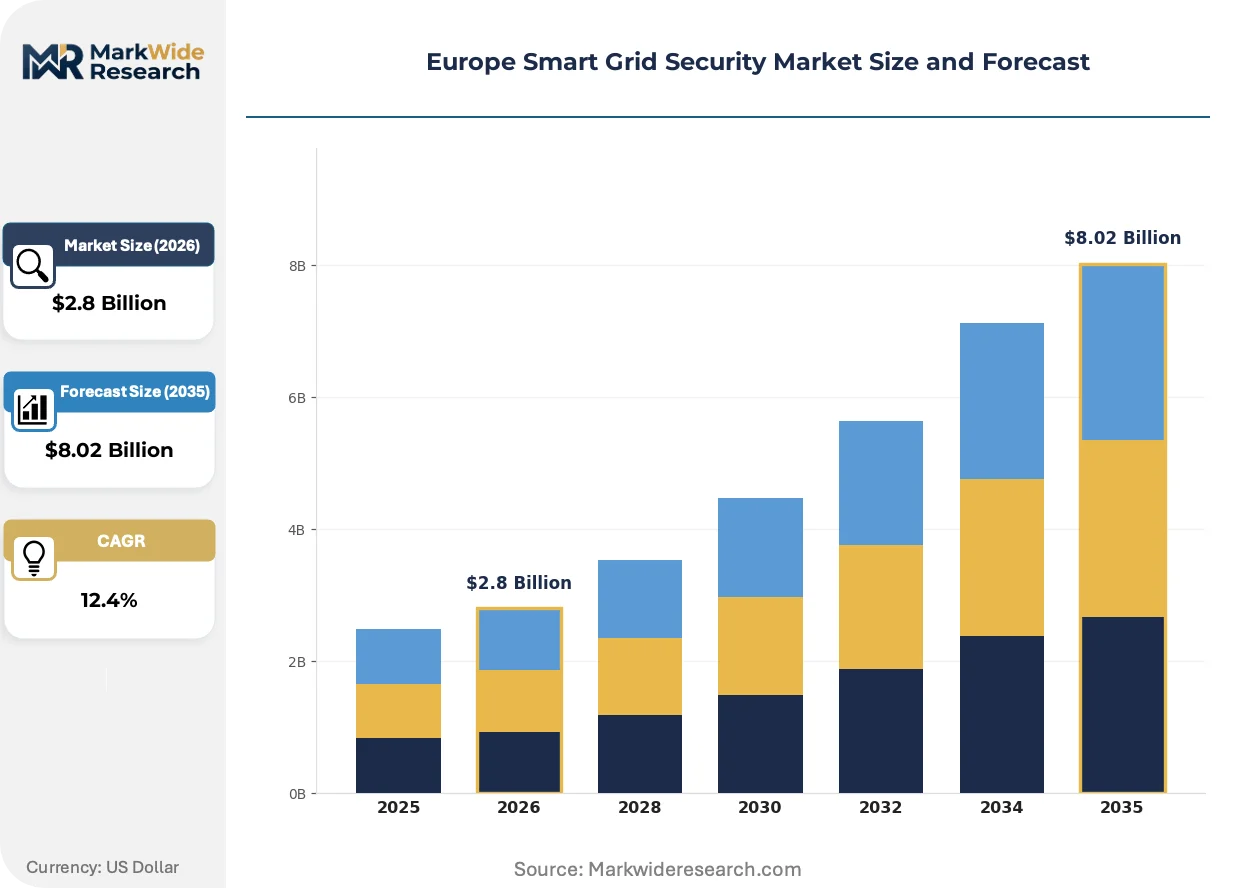
Market Dynamics
The EU Cybersecurity Act and NIS2 Directive are compressing compliance timelines for critical energy infrastructure, forcing distribution system operators across Germany, France, and the Nordics to accelerate procurement of encryption and intrusion detection systems ahead of statutory deadlines.
Growth Catalysts
- NIS2 Directive mandates:The directive imposes binding cybersecurity risk management measures and incident reporting obligations on energy utilities, creating immediate procurement pressure for encryption and access governance systems.
- German grid digitalization:Federal cybersecurity mandates for transmission operators and substantial grid modernization investments generate the region's deepest deployment pipeline for hardware-integrated security stacks.
- SCADA behavioral analytics:Processing thousands of SCADA events per second through anomaly detection engines enables real-time threat identification across operational technology networks.
Market Restraints
- CE marking complexity:ECHA chemical safety protocols and CE marking obligations constrain hardware component sourcing for grid security appliances, extending product certification cycles.
- Sovereign data constraints:Transmission system operators with strict data localization requirements resist cloud-based deployment models, limiting addressable market for SaaS security platforms.
- Legacy protocol fragmentation:Heterogeneous IEC 61850 implementations across European substations create integration friction that slows unified security architecture deployment.
Strategic Opportunities
- Polish and Romanian grid modernization:These markets show underpenetrated security infrastructure relative to Western European peers, with EU cohesion funds financing accelerated digitalization programs.
- Prosumer endpoint protection:Bidirectional communication security for distributed energy resources and residential smart meters represents an emerging application segment with limited incumbent competition.
- ENISA certification frameworks:The agency's evolving threat intelligence frameworks and product certification schemes create first-mover advantages for vendors achieving early Common Criteria evaluation.
Industry Challenges
- Cyber-physical systems expertise gap:Utilities struggle to recruit personnel with combined operational technology and information technology security competencies, particularly for IEC 61850 protocol environments.
- Zero-trust architecture migration:Reconfiguring decades-old perimeter-based security models for zero-trust architectures demands substantial capital reallocation and extended operational disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Smart Grid Security Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $8.02 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Intrusion Detection System, Firewall, Encryption, Identity Management End User: Utility Companies, Government Agencies, Enterprises, Residential Users Application: Data Protection, Network Security, Infrastructure Security, Access Control Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services |
| Companies Covered | Siemens AG, Schneider Electric SE, ABB Group, IBM Corporation, Cisco Systems, Inc., Honeywell International, Inc., General Electric Company, Oracle Corporation, Broadcom, Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Smart Grid Security Market Strategic Shifts & Innovations
Post-quantum cryptographic standards and AI-driven threat detection are actively reshaping product roadmaps across European grid security vendors, compressing development cycles and redefining competitive differentiation.
Quantum-resistant encryption algorithms are rendering obsolete classical public-key infrastructure across transmission system operator networks. German and French utilities are piloting lattice-based cryptography for substation-to-control-center communications. This migration is rendering obsolete hardware security modules lacking firmware upgrade paths for post-quantum transitions.
ENISA's updated threat intelligence frameworks and mandatory incident reporting under NIS2 are tightening product certification requirements. European utilities now demand Common Criteria EAL4+ evaluation for security appliances before procurement approval. Distribution system operators in the Nordics are responding by pre-qualifying vendors against anticipated ENISA technical standards eighteen months ahead of formal adoption.
Subscription-based security monitoring is displacing perpetual license models among mid-sized distribution utilities. Managed detection and response services delivered through regional cybersecurity operations centers are capturing preference over in-house security operations. France and Benelux markets exhibit the most pronounced shift, with municipal utilities consolidating vendor relationships under multi-year service agreements.
Europe Smart Grid Security Market Segmentation
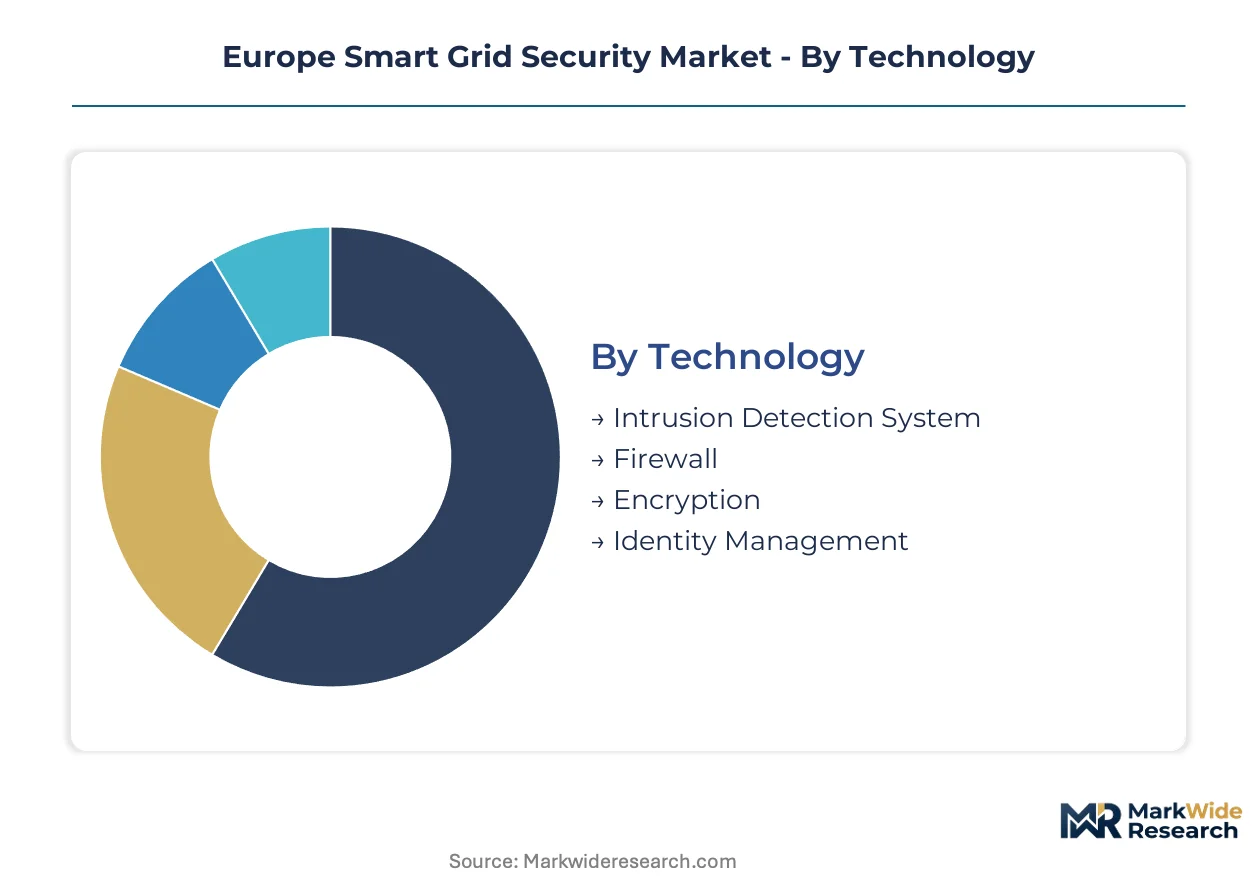
Segmentation in the Europe Smart Grid Security Market reveals how procurement priorities diverge across regulatory environments and infrastructure maturity levels. Understanding these splits helps vendors align product roadmaps with the specific compliance pressures and operational constraints shaping utility buying behavior.
Technology:
After-sales service intensity varies sharply across technology categories, with encryption and intrusion detection systems demanding continuous threat intelligence updates and firmware patches that lock utilities into long-term vendor relationships.
- Encryption:AES-256 and post-quantum lattice-based algorithms protect substation-to-control-center communications. German transmission operators are driving demand for hardware security modules with firmware upgrade paths as federal cybersecurity mandates tighten.
- Intrusion Detection System:Behavioral analytics engines process thousands of SCADA events per second to identify anomalies in operational technology networks. French distribution system operators are accelerating deployment ahead of NIS2 Directive deadlines.
- Firewall:Protocol-aware gateways filter traffic across IEC 61850 environments. Nordics utilities favor integrated appliances that combine firewall functions with network visibility tools.
- Identity Management:Zero-trust access governance systems authenticate personnel and devices across grid operations. NIS2-mandated supply chain authentication requirements are elevating procurement priority for this segment.
By volume, Intrusion Detection System leads. By growth pace, Encryption is ahead.
End User:
Cost tier differentiation separates end user categories, with utility companies absorbing premium pricing for certified appliances while residential users access stripped-down endpoint protection through bundled service models.
- Utility Companies:Transmission and distribution system operators constitute the core revenue base. Polish and Romanian grid modernization programs are expanding the addressable market beyond Western European incumbents.
- Government Agencies:National cybersecurity authorities and energy regulators procure monitoring and threat intelligence platforms. ENISA technical standards influence procurement specifications directly.
- Enterprises:Industrial consumers with on-site generation assets deploy perimeter security for facility interconnection points. Manufacturing clusters in Benelux exhibit concentrated demand.
- Residential Users:Smart meter security and home energy management system protection remain nascent. Prosumer endpoint protection represents an emerging application with limited incumbent competition.
By volume, Utility Companies dominate. By growth pace, Residential Users are expanding most quickly.
Application:
Application segmentation tracks where security spending concentrates as grid digitalization deepens, with data protection and network security capturing the bulk of current investment.
- Network Security:IEC 61850 protocol-aware monitoring and segmentation tools safeguard transmission-level communications. Cisco Systems competes aggressively in this space with visibility platforms purpose-built for substation environments.
- Data Protection:Cryptographic safeguarding of consumer usage patterns and grid operational data. GDPR compliance obligations and NIS2 incident reporting requirements are elevating procurement priority.
- Infrastructure Security:Physical-digital convergence protection for generation assets and substations. Hardware-integrated security stacks from Siemens anchor this segment.
- Access Control:Identity verification and privilege management across operational technology environments. Zero-trust architecture migration is reshaping product requirements.
By volume, Network Security leads. By growth pace, Data Protection is climbing the fastest.
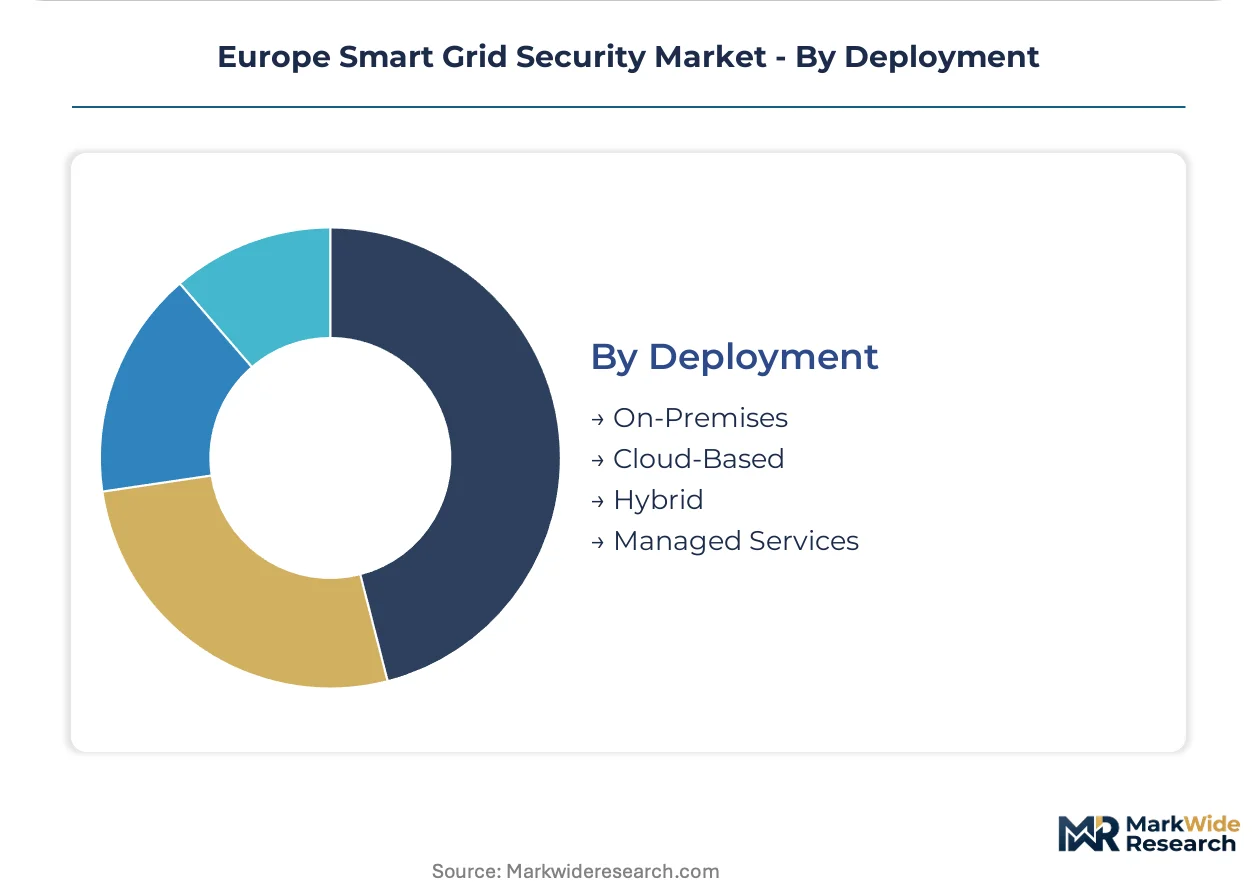
Deployment:
Deployment models reflect sovereign data constraints and internal capability gaps, with transmission system operators resisting cloud migration while mid-sized utilities embrace managed services.
- On-Premises:Appliance-based deployment within utility-owned data centers. Transmission system operators with strict data localization requirements maintain preference for this model despite higher capital burden.
- Managed Services:Regional cybersecurity operations centers deliver detection and response capabilities. France and Benelux municipal utilities are consolidating vendor relationships under multi-year service agreements.
- Cloud-Based:Subscription security monitoring platforms. This deployment category is gaining share fastest among distribution utilities without sovereign data constraints.
- Hybrid:Split architectures retaining sensitive operational technology functions on-premises while pushing analytics to cloud environments. German utilities are piloting this model for behavioral analytics workloads.
By volume, On-Premises leads. By growth pace, Managed Services is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Transmission system operators and distribution utilities constitute the dominant buyer archetypes, with procurement concentrated among German, French, and Nordic grid operators facing compressed NIS2 compliance timelines.
Germany
Federal cybersecurity mandates for transmission operators and substantial grid modernization investments generate Europe's deepest deployment pipeline for hardware-integrated security stacks. The German Bundesamt für Sicherheit in der Informationstechnik enforces technical baseline protection standards that accelerate certification requirements. Bavarian and North Rhine-Westphalian utilities are piloting hybrid cloud architectures for behavioral analytics workloads while retaining critical operational technology functions on-premises.
France
French distribution system operators are accelerating intrusion detection deployment ahead of NIS2 Directive deadlines, with municipal utilities consolidating vendor relationships under multi-year managed service agreements. The Agence nationale de la sécurité des systèmes d'information shapes procurement specifications through threat intelligence frameworks. Industrial clusters in Île-de-France and Auvergne-Rhône-Alpes exhibit concentrated demand for facility interconnection security among manufacturing consumers with on-site generation assets.
Nordics
Swedish, Norwegian, and Finnish utilities favor integrated appliances combining firewall functions with IEC 61850 protocol-aware network visibility tools. ENISA technical standards influence procurement directly, with operators pre-qualifying vendors eighteen months ahead of formal adoption. Copenhagen and Stockholm municipal utilities are consolidating cybersecurity operations center relationships under subscription-based monitoring contracts.
Poland
EU cohesion funds are financing accelerated grid digitalization programs in this underpenetrated security infrastructure market relative to Western European peers. The Polish national cybersecurity authority imposes incident reporting obligations that elevate procurement priority for encryption and access governance systems. Warsaw-based distribution operators are expanding addressable market opportunity beyond traditional Western European incumbent territories.
Romania
Romanian grid modernization programs funded through EU structural instruments are creating procurement pressure for certified security appliances. The national energy regulator transposes NIS2 requirements into binding technical specifications for critical infrastructure operators. Bucharest and Transylvanian industrial zones are emerging as focal points for transmission-level security investments.
Europe Smart Grid Security Market Key Industry Players
Channel-controlling players compete with product-specialist players across a tiered market structure where transmission system operator relationships confer defensive positioning. The vendor base organizes around three strategic archetypes: industrial conglomerates with deep operational technology heritage, network infrastructure specialists with protocol-specific expertise, and software-centric platforms with end-to-end integration capabilities. Dominant competitive moves include strategic partnerships for ENISA certification alignment and portfolio diversification into post-quantum cryptographic readiness.
Among industrial conglomerates with embedded grid automation expertise, Siemens AG and ABB Group exemplify the hardware-integrated security stack archetype, anchoring their positions through substation domain knowledge. Schneider Electric SE occupies a position representing the end-to-end software platform approach, spanning grid operations from transmission infrastructure to distributed energy resource endpoints. Cisco Systems, Inc. sits within the network visibility specialist tier, competing through tools purpose-built for IEC 61850 protocol environments.
| Leading Market Players |
|---|
| Siemens AG |
| Schneider Electric SE |
| ABB Group |
| IBM Corporation |
| Cisco Systems, Inc. |
| Honeywell International, Inc. |
| General Electric Company |
| Oracle Corporation |
| Broadcom, Inc. |
| Others |
Cost & Logistics Intelligence
Munich and Stuttgart industrial clusters anchor European production of hardware security modules and substation automation components, with their capacity utilization rates directly transmitting into pricing leverage for encryption appliance vendors serving German transmission operators under federal cybersecurity mandates.
Pricing Analysis
Cost-plus contracts with semiconductor price indexation dominate procurement agreements between utilities and security appliance vendors. Three-tier pricing structure across Common Criteria EAL4+ certified, EAL2+ compliant, and uncertified equipment levels separates transmission operators from distribution utilities from municipal operators. Pricing pressure stems from EU Cybersecurity Act certification requirements extending product development cycles. Municipal utilities in France and Benelux exhibit highest price sensitivity due to consolidated vendor negotiations under multi-year managed service agreements.
Supply Chain Analysis
Upstream feedstock for cryptographic processors draws from Taiwan, South Korea, and Germany, with advanced lithography nodes for hardware security modules resting on TSMC and Samsung foundry capacity. Legacy FPGA components for IEC 61850 protocol gateways hinge on constrained Xilinx and Intel supply allocations. Single-source vulnerability concentrates in post-quantum cryptography IP licensing from NIST-standardization participants. Distribution runs through authorized systems integrators with substation automation expertise rather than direct vendor-to-utility channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among transmission system operators consolidating procurement under framework agreements, fragmenting the addressable base for point-product vendors while elevating integrated platform providers.
For Market Incumbents: Entrench position through ENISA certification pre-qualification eighteen months ahead of formal adoption timelines. Deepen backward integration into firmware development for post-quantum cryptographic upgrade paths, neutralizing hardware obsolescence risk from lattice-based algorithm migration. Anchor substation automation relationships against Cisco's protocol-specific network visibility encroachment.
For New Entrants and Emerging Players: Polish and Romanian distribution system operators present underpenetrated security infrastructure relative to Western European peers, with EU cohesion funds financing accelerated digitalization programs absent entrenched incumbent relationships. Prosumer endpoint protection for residential smart meters offers limited competition from established grid vendors. Pursue managed detection and response service models rather than appliance sales to bypass capital expenditure approval barriers.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance-recurring-revenue play because NIS2 Directive mandates create non-discretionary procurement cycles with decade-long replacement horizons. Acquisition targets should demonstrate Common Criteria evaluation capabilities and active ENISA technical working group participation. Monitor national transposition timelines for NIS2 as inflection indicator for procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| ENISA Certification Pre-Qualification | Early Common Criteria evaluation locks in procurement preference ahead of NIS2 enforcement deadlines. |
| Post-Quantum Cryptography R&D Partnership | Lattice-based algorithm development with German BSI accelerates federal mandate compliance. |
| Managed Security Service Expansion | Regional cybersecurity operations centers capture French municipal utility consolidation trends. |
| Polish Distribution Operator Partnership | EU cohesion fund access opens underpenetrated Eastern European security infrastructure markets. |
| Prosumer Endpoint Protection Launch | Residential smart meter security addresses emerging bidirectional communication vulnerabilities. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with transmission system planning officers, distribution utility cybersecurity directors, substation automation engineers, and ENISA technical standards participants. Secondary validation drew from EU Cybersecurity Act implementation documents, NIS2 Directive national transposition filings, ENISA threat intelligence frameworks, and utility procurement database records. Bottom-up segment sizing triangulated against top-down regulatory compliance timeline modeling.
Calibration against historical certification cycle durations and procurement lag patterns anchored projection assumptions across the analysis window. Segmentation dimensions modeled include technology category, deployment architecture, end-user scale tier, and national regulatory transposition status. CAGRs derived from utility capital expenditure pipeline analysis weighted by NIS2 compliance deadline proximity. Forecast inputs incorporated ENISA technical standard adoption curves and post-quantum cryptography migration timelines.
Practitioners should monitor national NIS2 transposition delays and semiconductor foundry capacity allocations for early signals of forecast revision. Cross-checking against European Network of Transmission System Operators for Electricity investment disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Grid
Global Microgrid As a Service Market
Smart Grid
Smart Grid Adoption Market
Smart Grid
Europe Microgrid Market
Smart Grid
South and Central America Smart Grid Market
Smart Grid
Demand Response Market
Smart Grid
Europe Automated Demand Response Market
Smart Grid
Saudi Arabia Smart Grid Market
Smart Grid
Smart Demand Response Market
Smart Grid
Middle-East Smart Grid Network Market
Smart Grid
Smart Grid Data Management Market
Smart Grid
Smart Microgrid Market
Smart Grid
Europe Smart Grid Network Market
Smart Grid
Automated Demand Response Management Systems Market
Smart Grid
North America Smart Grid Market
Smart Grid
Global Self-Healing Grid Market
Smart Grid
Smart Energy Switch Market