
 Helium Recovery Systems Market | 2026-2036
Helium Recovery Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Helium Recovery Systems Market Insights
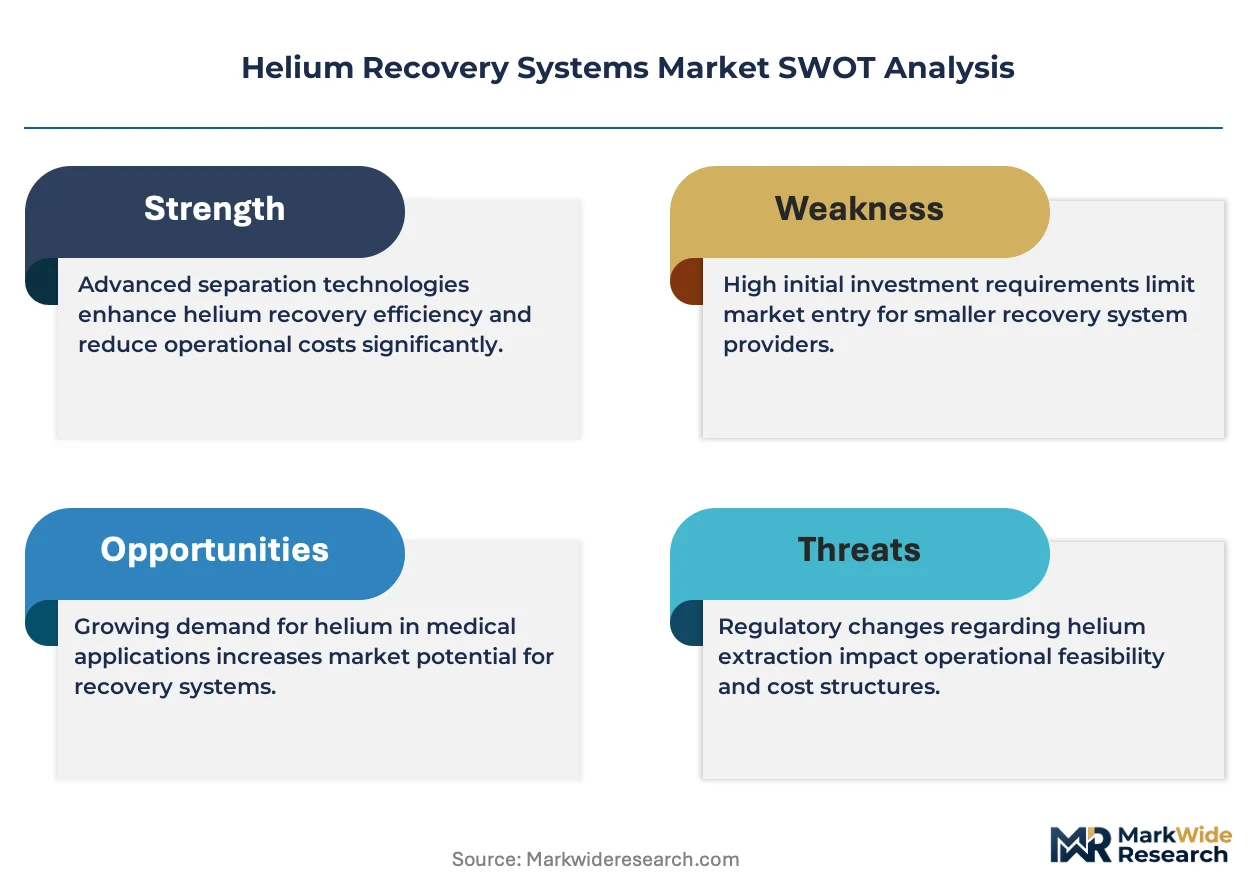
Ultra-high-purity (UHP) grade recovery is bifurcating the competitive landscape into specification-led and cost-led tiers. Air Liquide leverages cryogenic distillation expertise to anchor premium positioning in semiconductor-grade helium loops. Linde competes through backward integration into industrial gas supply chains, sustaining margin capture across multiple recovery stages. Grasys specializes in compact adsorption units, occupying niche deployment environments where footprint constraints dominate buyer criteria.
Helium recovery systems capture vented or waste helium from industrial processes, compressing and purifying the gas through membrane separation, cryogenic distillation, or pressure-swing adsorption to restore usable purity levels typically exceeding 99.999 percent. These systems serve critical functions in leak detection, superconducting magnet cooling, and process gas recycling where helium's inertness and ultra-low boiling point remain irreplaceable. Cryogenic Systems command the deepest margin pools due to energy-intensive infrastructure and technical complexity barriers. Hybrid Systems represent the fastest-growing product category as end users seek modular configurations combining membrane pre-separation with cryogenic finishing. Research Institutions drive disproportionate technology pull through demand for closed-loop cooling in nuclear magnetic resonance and particle accelerator applications.
The U.S. Bureau of Land Management's helium stewardship transitions and China's MEE emissions enforcement are tightening supply-side accountability, compelling facility operators to install on-site recovery rather than rely on volatile bulk helium markets. The EU F-Gas Regulation's indirect pressure on fluorinated gas alternatives reinforces helium's protected status in precision applications, while REACH compliance obligations elevate documentation requirements for recovered gas requalification. Stakeholders must monitor BLM auction timing, Chinese carbon intensity benchmarks, and emerging membrane material breakthroughs to calibrate capacity commitments against supply security priorities.
Market Dynamics
Semiconductor fabs in Taiwan and South Korea are scaling helium recycling infrastructure to curb supply chain exposure, creating a structural pull for on-site recovery systems that bypass volatile bulk helium markets. This concentration of demand in East Asian electronics manufacturing corridors is reshaping competitive positioning toward specification-led tiers.
Growth Catalysts
- BLM Auction Reforms:The U.S. Bureau of Land Management's stewardship transitions are tightening supply-side accountability and compelling facility operators to install captive recovery rather than rely on federal helium auctions.
- China's Dual Carbon Goals:MEE emissions enforcement and national carbon intensity benchmarks are accelerating facility-level recovery mandates across industrial gas consumers.
- Membrane Pre-Separation:Hybrid system configurations combining membrane technology with cryogenic finishing are reducing energy intensity and expanding addressable deployment environments.
Market Restraints
- Energy Input Volatility:Cryogenic distillation's electricity intensity exposes operators to power cost swings that compress marginal recovery economics during price spikes.
- BLM Supply Concentration:Federal helium reserve depletion and auction timing uncertainty create feedstock access risk for non-integrated recovery system operators.
- Fluorinated Gas Substitution:EU F-Gas Regulation pressure on fluorinated alternatives reinforces helium's protected status but also invites long-term substitution research in select cooling applications.
Strategic Opportunities
- Research Institution Loops:Nuclear magnetic resonance and particle accelerator facilities present underpenetrated demand for closed-loop cooling systems with ultra-high-purity specifications.
- Modular Adsorption Units:Compact footprint systems for space-constrained semiconductor fabs and laboratory environments represent white space beyond centralized cryogenic infrastructure.
- REACH Documentation Services:Compliance obligations for recovered gas requalification create adjacent service revenue streams for system vendors with analytical capabilities.
Industry Challenges
- Cryogenic Engineering Talent:Scarcity of specialized technicians for distillation system commissioning and maintenance extends deployment timelines and elevates service costs.
- Legacy Integration Complexity:Retrofitting recovery loops into existing semiconductor process gas architectures requires custom engineering that delays payback realization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Helium Recovery Systems Market |
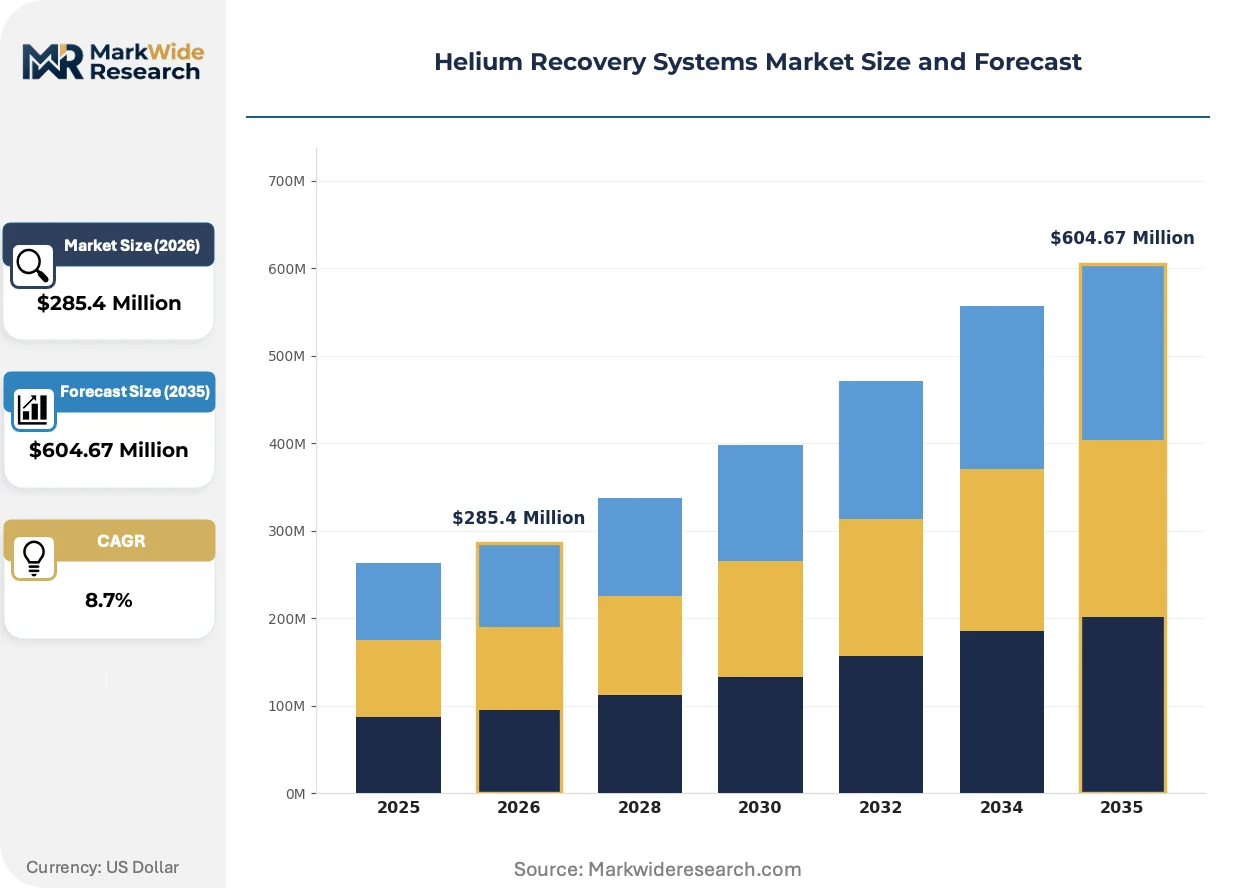
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $604.67 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compression Systems, Adsorption Systems, Cryogenic Systems, Hybrid Systems End User: Aerospace, Healthcare, Electronics, Research Institutions Technology: Membrane Separation, Distillation, Adsorption, Cryogenics Application: Leak Detection, Coolant Systems, Gas Mixing, Instrument Calibration |
| Companies Covered | Vacuum Instruments Corporation, Grasys, Air Liquide, BBS Automation, Leybold, Linde, Burke Porter Group, GENERON, Cryomech Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Helium Recovery Systems Market Trends and Innovations
Technology convergence between membrane separation and cryogenic finishing is compressing the cost-performance frontier, while regulatory pressure on supply security and emissions accountability accelerates facility-level investment in closed-loop infrastructure.
Hybrid membrane-cryogenic systems are displacing standalone cryogenic units in mid-scale semiconductor applications. Taiwan-based fabs are adopting these configurations to reduce energy intensity without sacrificing 99.999% purity thresholds. The technology is displacing capital-intensive centralized recovery models with modular, expandable footprints that match capacity to wafer output ramps.
EU F-Gas Regulation amendments are tightening fluorinated gas phase-down schedules, indirectly reinforcing helium's protected status in precision cooling applications. Industrial gas consumers are responding by locking in long-term recovery system contracts to insulate against supply disruption. Semiconductor-grade helium loops in Germany and France face the most acute compliance documentation requirements.
After-sales service unbundling is fragmenting traditional equipment-plus-maintenance bundles into separate performance contracts and spare parts subscriptions. Korean electronics manufacturers are driving this shift through competitive tender processes that separate capex and opex decisions. The model is most visible in East Asian electronics corridors where fab operators prioritize operational flexibility over bundled vendor relationships.
Helium Recovery Systems Market Segmentation
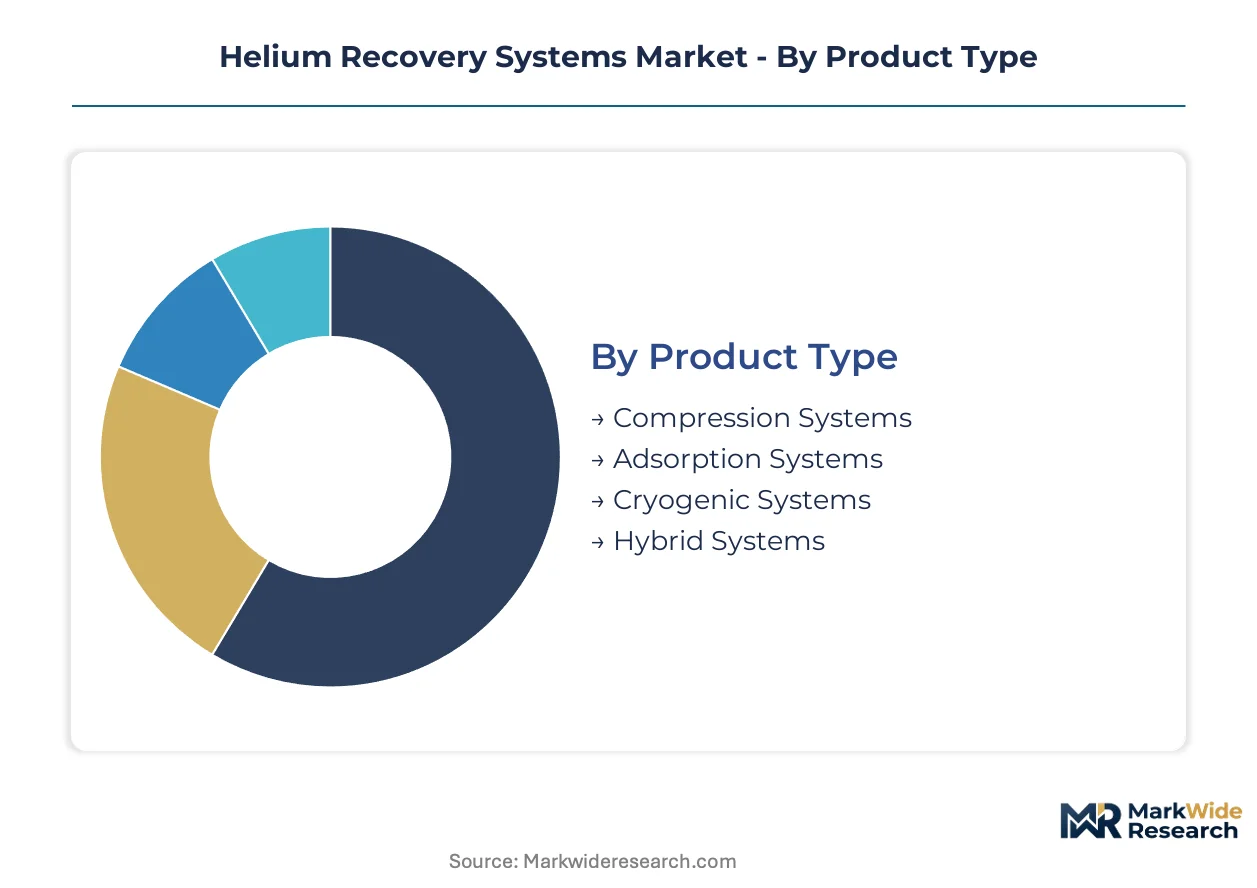
Helium recovery systems fragment across four structural dimensions that determine capital intensity, purity thresholds, and customer procurement patterns. Product type and technology choices lock in operational economics for decades, while end-user concentration in East Asian electronics corridors reshapes competitive priorities.
Product Type:
Substitution pressure from fluorinated gas alternatives and energy cost volatility hit cryogenic configurations hardest, compressing their addressable market to ultra-high-purity niches where membrane systems cannot compete.
- Cryogenic Systems:These units employ multi-stage distillation at temperatures approaching absolute zero to achieve 99.999% purity. Taiwan Semiconductor Manufacturing and Samsung Foundry anchor demand in Hsinchu and Pyeongtaek, where quantum computing and advanced node fabrication require uncompromised helium grades despite electricity intensity.
- Hybrid Systems:Configurations combining membrane pre-separation with cryogenic finishing reduce energy consumption by 30-40% while maintaining semiconductor-grade specifications. South Korean fabs in Yongin and Chinese display panel manufacturers in Hefei are adopting these for mid-scale deployments where full cryogenic infrastructure proves capital-prohibitive.
- Adsorption Systems:Pressure-swing adsorption units using zeolite or carbon molecular sieves serve laboratory and healthcare environments in Boston and Basel where footprint constraints dominate site selection.
- Compression Systems:Mechanical compression stages for bulk gas recovery support industrial gas distributors in Houston and Rotterdam with established liquid helium logistics networks.
Cryogenic Systems anchor the volume base while Hybrid Systems gain share at the steepest rate.
End User:
Cost tier stratification separates specification-sensitive buyers willing to pay recovery premiums from price-elastic segments where helium conservation remains discretionary.
- Electronics:Semiconductor and display manufacturing in Taiwan, South Korea, and Japan consumes the largest recovery system volumes. TSMC's Kaohsiung 2nm fab and SK Hynix's Icheon DRAM complex mandate closed-loop helium infrastructure under supply security protocols.
- Research Institutions:Nuclear magnetic resonance facilities and particle accelerators in Geneva, Chicago, and Tsukuba drive demand for ultra-high-purity closed-loop cooling where helium substitution remains technically impossible.
- Healthcare:Magnetic resonance imaging installations in Munich and Melbourne represent mature demand with slower replacement cycles and greater price sensitivity to recovery capital expenditure.
- Aerospace:Rocket propulsion testing and satellite thermal management in Cape Canaveral and Kourou generate intermittent, high-volume recovery opportunities tied to launch schedules.
Electronics commands the dominant revenue share while Research Institutions deliver the highest margin per installed unit.
Technology:
Application maturity determines technology selection, with established industrial processes favoring proven distillation methods and emerging deployment environments accepting membrane innovation.
- Distillation:Cryogenic distillation remains the reference standard for semiconductor-grade helium, requiring specialized aluminum heat exchangers and turboexpanders. Air Liquide's proprietary cold box designs dominate this layer in Leuna and Kawasaki.
- Membrane Separation:Polymeric membrane modules from Ube Industries and Air Products enable compact, modular pre-separation for hybrid configurations. Chinese industrial gas distributors in Shanghai and Shenzhen are deploying these for rapid capacity scaling.
- Adsorption:Pressure-swing and temperature-swing adsorption cycles serve helium-nitrogen separation in natural gas processing facilities in Qatar and Algeria.
- Cryogenics:Broad cryogenic engineering capabilities encompass liquefaction, storage, and transfer systems integrated with recovery loops at CERN and Brookhaven National Laboratory.
Distillation retains the largest installed base while Membrane Separation expands most quickly through hybrid configurations.
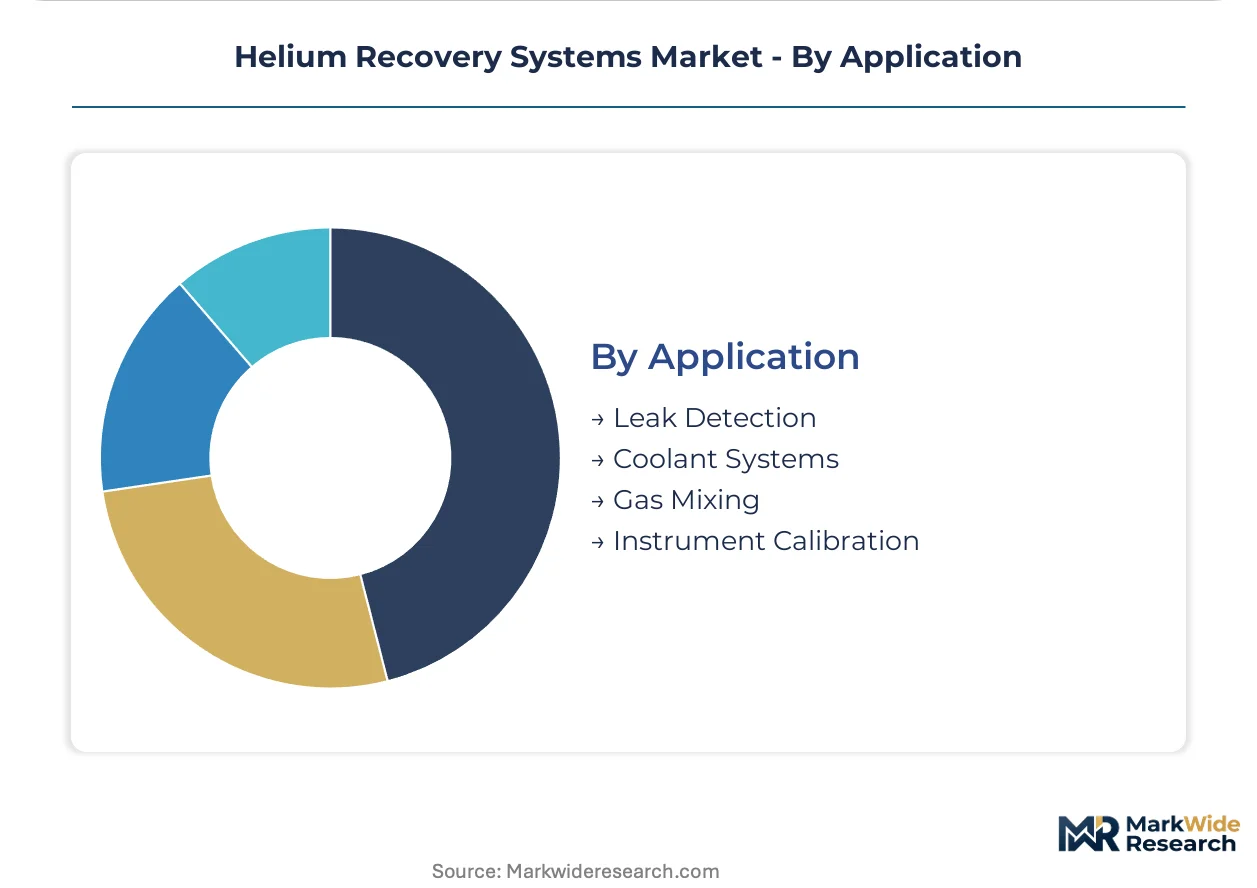
Application:
Supply concentration in helium-producing regions dictates recovery system deployment patterns, with coolant applications clustering near BLM pipeline infrastructure and leak detection dispersing across manufacturing geographies.
- Coolant Systems:Superconducting magnet cooling for MRI and NMR equipment represents the most technically demanding application, requiring continuous circulation at 4.2 Kelvin. Siemens Healthineers in Erlangen and GE Healthcare in Milwaukee specify recovery-integrated magnet designs.
- Leak Detection:Mass spectrometer leak testing in automotive and aerospace manufacturing employs helium as a tracer gas. BMW's Leipzig assembly plant and Airbus Toulouse operations deploy point-source recovery for cost containment.
- Gas Mixing:Controlled atmosphere welding and diving gas blending in Bremen and Yokohama utilize recovered helium for argon-helium mixtures where purity requirements permit.
- Instrument Calibration:Chromatography and spectrometry reference standards in analytical laboratories across Cambridge and Zurich require modest recovery volumes with extreme purity verification.
Coolant Systems anchor the volume base while Leak Detection gains share at the steepest rate as automotive electrification expands precision manufacturing quality protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Helium recovery infrastructure concentrates where semiconductor manufacturing clusters intersect with supply security anxieties. Taiwan, South Korea, and China anchor system deployment volumes, while the United States and Germany sustain demand through research institutions and healthcare networks.
United States
BLM stewardship transitions are compelling domestic operators toward captive recovery rather than federal auction dependence. The EPA's emissions enforcement framework elevates documentation requirements for industrial gas consumers. Houston anchors industrial gas distributor demand, while Boston and Chicago sustain laboratory and healthcare system procurement.
Taiwan
TSMC's foundry expansion in Kaohsiung and Hsinchu is mandating closed-loop helium infrastructure under supply security protocols. The island's industrial regulator enforces facility-level recovery benchmarks for electronics manufacturers. Advanced node fabrication at 2nm and below requires uncompromised 99.999% purity specifications that lock in cryogenic system specifications.
South Korea
Samsung Foundry and SK Hynix are scaling recycling infrastructure across Pyeongtaek and Icheon complexes to curb bulk helium exposure. MFDS-equivalent industrial safety mandates are tightening emissions accountability for process gas consumers. Yongin-based fabs are adopting hybrid membrane-cryogenic configurations to reduce energy intensity without sacrificing purity thresholds.
China
MEE emissions enforcement and national dual carbon goals are accelerating recovery mandates across industrial gas consumers. The country's SAMR standards framework elevates compliance documentation for requalified helium streams. Hefei display panel manufacturers and Shanghai industrial gas distributors are deploying modular membrane systems for rapid capacity scaling.
Germany
EU F-Gas Regulation amendments are tightening fluorinated gas phase-down schedules, indirectly reinforcing helium's protected status in precision cooling. REACH compliance obligations elevate documentation requirements for recovered gas requalification. Erlangen and Munich sustain healthcare and research institution demand through Siemens Healthineers specifications and Max Planck Institute procurement.
Helium Recovery Systems Market Competitive Landscape
Concentration sits with diversified industrial gas conglomerates and specialized cryogenic engineering houses. The vendor base stratifies across specification-led premium tiers and cost-optimized standard tiers. Three archetypes dominate: integrated industrial gas suppliers with backward control over supply chains, cryogenic technology specialists with proprietary cold box designs, and compact system fabricators targeting footprint-constrained deployment environments. Capacity expansion and technology licensing constitute the dominant competitive moves, with Korean and Taiwanese fabs driving performance-contract unbundling that separates capex and opex decisions.
Among diversified industrial gas suppliers, Air Liquide and Linde exemplify scale-driven positioning through integrated supply chain control. Grasys occupies the specialized tier, representing compact adsorption system architecture for space-constrained semiconductor fabs and laboratory environments. Vacuum Instruments Corporation anchors the leak detection recovery segment, where point-source capture systems serve automotive and aerospace quality protocols.
| Leading Market Players |
|---|
| Vacuum Instruments Corporation |
| Grasys |
| Air Liquide |
| BBS Automation |
| Leybold |
| Linde |
| Burke Porter Group |
| GENERON |
| Cryomech Inc |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between semiconductor fabs and industrial gas suppliers lock in both helium feedstock access and price visibility, insulating buyers from BLM auction volatility while embedding energy-cost pass-through clauses that expose operators to electricity price swings.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure across the European installed base, compelling facility operators toward premium-grade recovery systems that satisfy REACH documentation requirements for requalified gas streams. Three-tier pricing structure across premium, standard, and economy levels separates specification-sensitive semiconductor fabs from cost-optimized industrial gas distributors. Cost compression in standard-tier adsorption systems is intensifying because Chinese manufacturers are scaling modular membrane production. Healthcare MRI operators demonstrate the highest price sensitivity, while research institutions with NMR and particle accelerator mandates accept recovery premiums without negotiation.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication demand, drawing cryogenic cold box components from German engineering houses and polymeric membrane modules from Japanese specialty chemical producers. Aluminum heat exchanger fabrication rests on Austrian and Swiss precision metalworking capabilities, while turboexpander assemblies hinge on US and French rotating equipment specialists. Single-source vulnerability concentrates in helium feedstock access, where BLM reserve depletion and Qatar blockade risk create supply interruption exposure. Distribution runs through industrial gas majors with captive liquid helium logistics networks in Houston, Rotterdam, and Singapore.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among East Asian semiconductor foundries, where TSMC and Samsung Foundry procurement centralization is forcing equipment vendors toward unbundled performance contracts that separate capital expenditure from operational expenditure decisions.
For Market Incumbents: Compound specification-led positioning through proprietary cryogenic distillation IP and backward integration into helium liquefaction infrastructure. Defend against emerging membrane technology substitution by embedding long-term service contracts with take-or-pay clauses. Prioritize certification investment in EU REACH documentation capabilities to capture compliance-driven upgrade cycles among German and French research institutions. For New Entrants and Emerging Players: CE marking fast-track for compact adsorption units creates immediate addressable market access among space-constrained European laboratories and Asian display panel manufacturers. Target South Korean Yongin fab complexes with hybrid membrane-cryogenic configurations that reduce energy intensity without purity sacrifice. Lead with operational flexibility messaging and expandable modular footprints that match capacity to wafer output ramps. For Investors and Strategic Acquirers: Capital is best deployed toward cryogenic engineering specialists with proprietary cold box designs and established technician training pipelines. Long-term viability hinges on technology licensing revenue streams and after-sales service attach rates rather than equipment shipment volumes. Watch Chinese MEE enforcement intensity as the inflection indicator for accelerated facility-level recovery mandates across industrial gas consumers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Helium Liquefaction | Air Liquide and Linde secure captive feedstock access independent of BLM auction timing. |
| Hybrid System Technology Licensing | Membrane-cryogenic configurations reduce Korean fab energy costs while maintaining TSMC purity specifications. |
| REACH Documentation Service Expansion | Adjacent revenue streams capture EU compliance obligations for recovered gas requalification. |
| Compact Adsorption Unit Scale-Up | Grasys and specialized fabricators address white space in footprint-constrained Boston and Basel laboratories. |
| Technician Training Pipeline Investment | Cryogenic engineering scarcity extends deployment timelines; captive training defends service revenue. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, encompassing semiconductor fab process gas engineers, industrial gas procurement directors, cryogenic system commissioning technicians, and research facility operations managers. Secondary validation drew from BLM stewardship transition filings, EPA emissions enforcement records, EU F-Gas Regulation amendment texts, and SEC disclosures from listed industrial gas conglomerates. Bottom-up installed base enumeration triangulated against top-down market sizing from trade flow analysis.
Across the analysis window, the analytical framework modeled product type segmentation, end-user industry concentration, technology adoption patterns, and application-specific purity requirements. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion announcements. Forecast inputs incorporated electricity price trajectory assumptions for cryogenic energy intensity and membrane material breakthrough timelines from patent filing analysis.
Decision-makers should treat outputs as directional under base assumptions of sustained BLM auction reform implementation and Chinese dual carbon goal enforcement; material deviation in either regulatory trajectory would warrant model refresh. Recalibration cycles align with material shifts in MEE emissions benchmark stringency, EU F-Gas phase-down schedules, and superconducting magnet cooling demand from nuclear magnetic resonance facility construction.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuel Cell Technology
Fuel Cell Market
Fuel Cell Technology
Fuel Cell Stack Market
Fuel Cell Technology
China Fuel Cell Market
Fuel Cell Technology
Europe Direct Methanol Fuel Cell Market
Fuel Cell Technology
Europe Fuel Cell Market
Fuel Cell Technology
Fuel Cell Technology Market
Fuel Cell Technology
Global Micro Fuel Cells Market
Fuel Cell Technology
France Fuel Cell Market
Fuel Cell Technology
High-Performance Fuel Cells Market
Fuel Cell Technology
Alkaline Fuel Cell Market
Fuel Cell Technology
Germany Fuel Cell Market
Fuel Cell Technology
Aircraft Fuel Cell Market
Fuel Cell Technology
Direct Methanol Fuel Cell Market
Fuel Cell Technology
Hydrogen Fuel Cell Stack Durability and Performance Test Equipment Market
Fuel Cell Technology
Protonic Ceramic Fuel Cell (PCFC) Market
Fuel Cell Technology
Hydrogen Fueling Nozzle Market