
 Fuel Cells for Marine Vessels Market | 2026-2036
Fuel Cells for Marine Vessels Market Size, Share, and Industry Trends Forecast 2026-2036
Fuel Cells for Marine Vessels Market Analysis
IMO 2025 Tier III compliance specifications for nitrogen oxide emissions is collapsing the viability of conventional auxiliary power units in coastal shipping routes. Ballard Power Systems leverages its PEMFC stack density advantages to dominate short-sea ferry retrofits across Nordic ports. Siemens AG anchors integrated propulsion system contracts through its SISHIP BlueDrive platform, combining fuel cell modules with battery buffers. Doosan Fuel Cell specializes in megawatt-class SOFC architectures for large commercial vessels requiring continuous baseload power.
A fuel cell for marine vessels is an electrochemical power generation system that converts hydrogen or hydrogen-rich fuels directly into electricity through redox reactions, typically operating at 40-60% electrical efficiency with exhaust streams of water vapor and heat, designed to replace or supplement diesel generators for propulsion and hotel loads aboard ships. PEMFC systems currently lead the product type landscape for sub-megawatt installations where rapid cold-start capability and modular footprint outweigh thermal efficiency trade-offs. SOFC technology occupies the high-power output segment above two megawatts, where its 60% electrical efficiency and fuel flexibility with liquefied natural gas reforming create margin concentration for oceangoing commercial vessels. The installation type dimension shows retrofit demand concentrating in European ports where shoreside hydrogen bunkering infrastructure from Rotterdam to Hamburg enables vessel repowering without full hull replacement.
The International Maritime Organization's revised GHG strategy and the EU Emissions Trading System extension to maritime transport are forcing fleet operators to document carbon intensity indicators or face port access restrictions and escalating carbon costs. The US Coast Guard and classification societies including DNV and Lloyd's Register have issued interim rules for fuel cell system placement, hydrogen storage tank separation distances, and ventilation requirements that shape system integrator design choices and yard retrofit timelines. Stakeholders must monitor hydrogen supply chain certification schemes and bunkering standard harmonization between Asian manufacturing hubs and European demand centers to avoid stranded asset risk in vessel powertrain investments.
Market Dynamics
IMO Tier III nitrogen oxide mandates are collapsing the economic viability of conventional diesel auxiliary power units across coastal shipping corridors, forcing fleet operators toward hydrogen-electric repowering decisions before regulatory enforcement deadlines.
Growth Catalysts
- EU Emissions Trading System maritime extension:Carbon pricing mechanisms now cover vessel operators calling at Rotterdam, Hamburg, and Antwerp, creating direct cost pressure that accelerates fuel cell retrofits over scrubber installations.
- Japanese national hydrogen strategy port investments:Yokohama and Kobe hydrogen bunkering terminals enable SOFC-powered coastal cargo vessels to refuel without diverting to foreign ports, anchoring domestic shipbuilder order books.
- Scandinavian commercial ferry electrification mandates:Norwegian and Danish route licenses now require zero-emission capability for new vessel approvals, concentrating short-sea operator procurement toward PEMFC stacks with rapid cold-start specifications.
Market Restraints
- Platinum group metal cost volatility:PEMFC stack manufacturing remains exposed to palladium and platinum price swings from South African and Russian mining concentration, compressing module supplier margins during supply disruptions.
- Limited high-pressure hydrogen storage certification:Type IV composite tank approval timelines from Lloyd's Register and DNV stretch 18-24 months, delaying vessel retrofit schedules and yard slot availability.
- LNG dual-fuel engine substitution threat:Established marine engine manufacturers offer methane-slip-reduced two-stroke designs at lower capital cost, capturing risk-averse bulk carrier operators unconvinced by hydrogen infrastructure readiness.
Strategic Opportunities
- Great Lakes-St. Lawrence Seaway corridor electrification:US and Canadian short-sea routes lack hydrogen bunkering but possess abundant hydropower-for-electrolysis potential, creating first-mover advantage for fuel cell integrators establishing regional service networks.
- SOFC-carbon capture convergence:Japanese shipyards are piloting integrated systems that capture CO2 from onboard LNG reforming, positioning vessels for future carbon accounting schemes while retaining fuel flexibility.
- Power purchase agreement financing innovation:Vessel operators in Germany and the Netherlands now structure fuel cell retrofits through hydrogen supply contracts with port authorities, transferring technology risk away from shipowner balance sheets.
Industry Challenges
- Marine electrical systems integration complexity:Fuel cell DC output requires sophisticated power management coordination with existing AC hotel loads and variable-speed propulsion drives, extending shipyard commissioning timelines and warranty disputes.
- High-voltage technician certification scarcity:Classification society training programs for 1000V+ marine fuel cell systems have certified fewer than 500 engineers globally, constraining fleet deployment velocity and maintenance network expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fuel Cells for Marine Vessels Market |
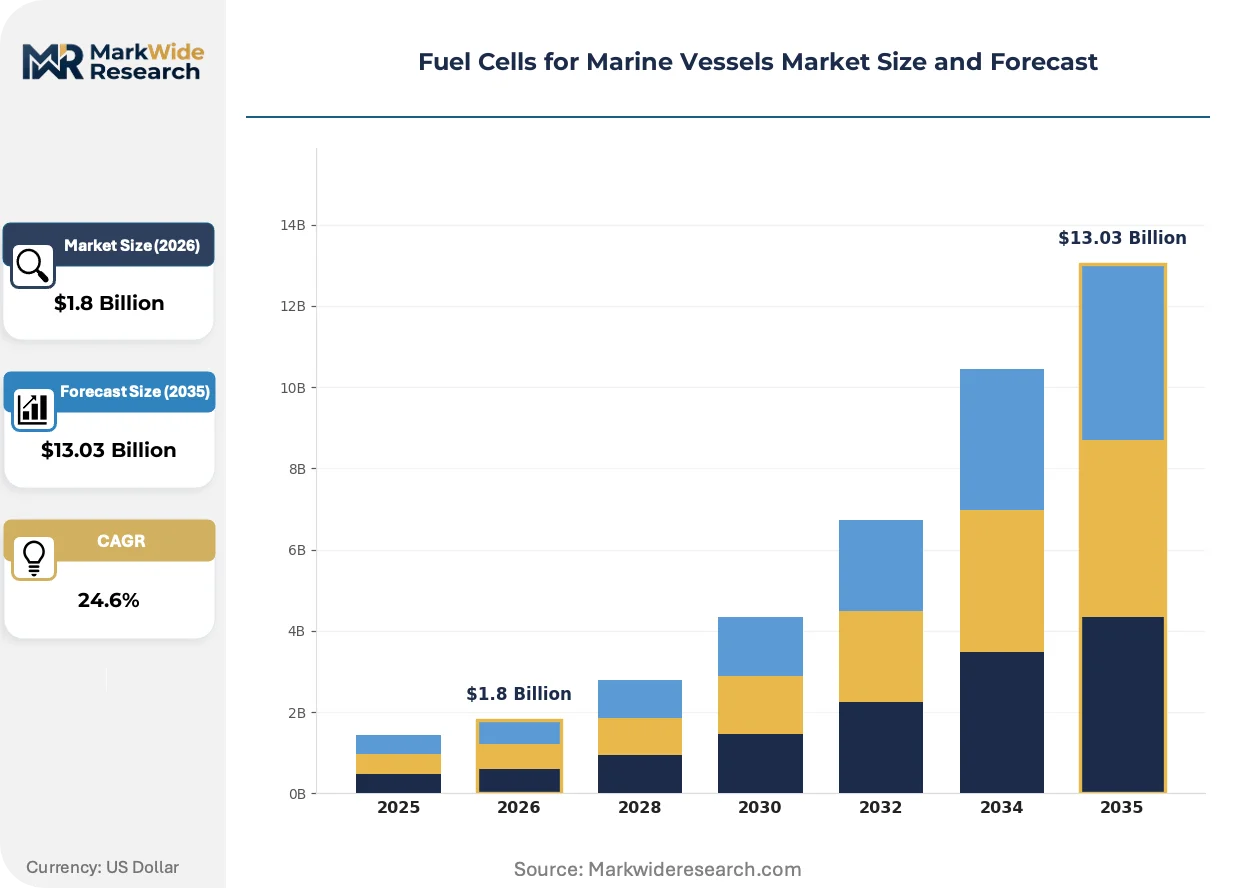
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $13.03 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PEMFC, SOFC, DMFC, AFC End User: Commercial Vessels, Defense, Leisure Boats, Research Vessels Installation Type: Onboard, Retrofit, Integrated, Standalone Power Output: Low, Medium, High, Ultra-High |
| Companies Covered | ABB Ltd., Doosan Fuel Cell, Ballard Power Systems Inc., Advent Technologies Holdings Inc., Bloom Energy Corp., PowerCell Sweden AB, Freudenberg, Siemens AG, TECO 2030 ASA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fuel Cells for Marine Vessels Market Emerging Trajectories
Marine fuel cell technology trajectories center on thermal efficiency gains, regulatory compliance automation, and procurement model restructuring that transfers technology risk from vessel operators to system integrators and energy suppliers.
Solid oxide fuel cell architectures operating at 800°C are displacing medium-speed diesel generators in cruise ship and ro-ro vessel applications where waste heat recovery drives desalination and HVAC loads. Carnival Corporation and MSC Cruises have specified SOFC auxiliary power for newbuilds in the 50-100MW range, compressing conventional genset supplier revenue in the premium passenger segment. The technology is displacing incumbent prime mover market share fastest in itineraries requiring extended port stays with shore power limitations.
EU F-Gas Regulation phase-down schedules for fluorinated greenhouse gases are forcing refrigerant-dependent PEMFC cooling system redesigns toward CO2-based heat pumps and ambient air cooling. The industrial consequence is extended engineering validation timelines for European integrators, with Ballard Power Systems and Siemens AG accelerating stack thermal management R&D to maintain CE marking compliance. Nordic ferry operators face the most immediate compliance pressure, as their high-frequency route structures maximize cooling system annual operating hours.
Charter-party fuel clauses are restructuring vessel operator incentives toward performance-guaranteed powertrain contracts rather than capital equipment ownership. Greek and Singapore-based shipowners now prefer fuel-cell-as-a-service arrangements where the integrator retains stack ownership and charges per-kWh delivered, displacing traditional marine engineering procurement through shipyard newbuild specifications. This behavioral shift concentrates fastest in container feeder vessels where route predictability enables accurate energy consumption modeling and risk allocation.
Fuel Cells for Marine Vessels Market Segmentation
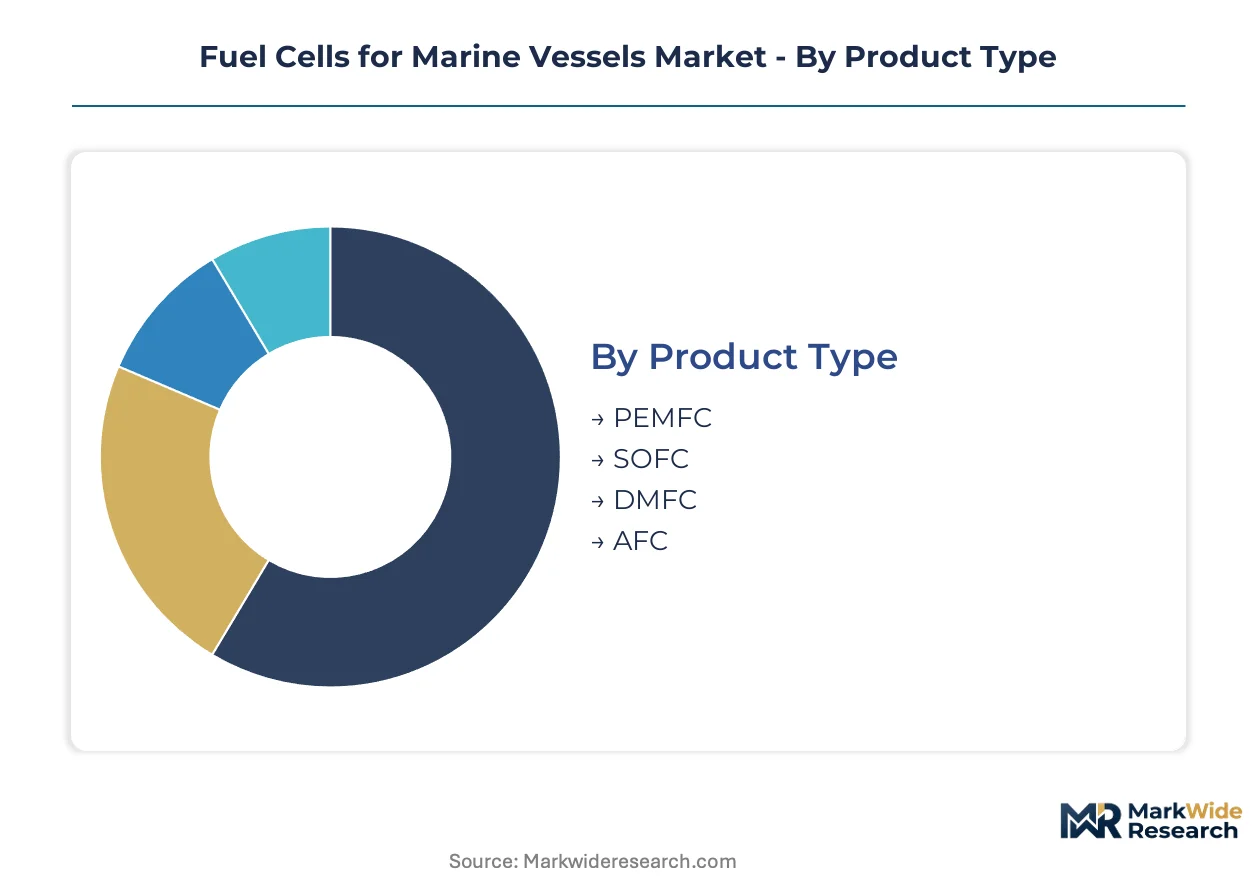
Segmentation in marine fuel cells reveals how technology choices diverge across vessel operating profiles and regulatory environments. Product type and installation decisions cluster around route predictability, port infrastructure maturity, and vessel lifecycle stage.
Product Type:
PEMFC systems dominate export-led demand from Nordic and Japanese shipyards serving international ferry routes, while SOFC architectures concentrate in domestic Japanese coastal cargo programs and European cruise newbuilds.
- PEMFC:Proton exchange membrane fuel cells operate at 60-80°C with rapid cold-start capability below 30 seconds, enabling frequent port calls. Norwegian short-sea ferry operators specify PEMFC stacks for routes requiring 10-15 daily departures, where thermal cycling tolerance outweighs efficiency trade-offs against SOFC alternatives.
- SOFC:Solid oxide fuel cells achieve 60% electrical efficiency at 800°C operating temperatures, with exhaust heat recovery driving desalination and HVAC loads. Japanese shipbuilders deploy megawatt-class SOFC systems for coastal cargo vessels under the national hydrogen strategy, leveraging LNG reforming flexibility where hydrogen bunkering remains sparse.
- DMFC:Direct methanol fuel cells offer liquid fuel logistics advantages for leisure boat segments in Mediterranean and Caribbean charter markets, avoiding compressed hydrogen handling complexity for recreational operators.
- AFC:Alkaline fuel cell systems occupy niche research vessel applications where pure hydrogen supply certainty exists and platinum catalyst cost sensitivity drives alkaline electrolyte chemistry selection.
PEMFC holds the largest share; momentum sits with SOFC as LNG reforming integration expands addressable vessel classes.
End User:
Cost tier stratification separates defense procurement with guaranteed hydrogen supply chains from commercial operators exposed to bunkering infrastructure risk.
- Commercial Vessels:Container feeders and ro-ro operators in Germany and the Netherlands structure power purchase agreements with port authorities, transferring fuel cell technology risk off shipowner balance sheets through per-kWh contracting models.
- Defense:Naval applications prioritize operational energy security over unit economics, with classification societies certifying military-grade hydrogen storage systems for extended endurance requirements in contested maritime environments.
- Leisure Boats:Yacht builders in Italy and the Netherlands integrate compact PEMFC modules for hybrid-electric propulsion, targeting emission-controlled marina access in Monaco and Amsterdam.
- Research Vessels:Oceanographic institutions specify fuel cell auxiliary power for silent station-keeping operations, with Arctic research programs leading adoption due to diesel generator cold-start reliability limitations.
Commercial vessels command the dominant revenue position; research vessels are climbing the fastest as silent operations mandates expand beyond military applications.
Installation Type:
Volume concentration favors retrofit programs in European ports with established hydrogen bunkering, while integrated newbuild specifications accelerate in Asian shipyards with captive fuel cell module production.
- Onboard:Factory-installed fuel cell systems in newbuilds at Korean and Chinese shipyards capture scale economies through standardized module placement and pre-commissioned power management integration.
- Retrofit:European short-sea operators in Rotterdam, Hamburg, and Antwerp repower existing hulls, leveraging shoreside hydrogen infrastructure to avoid full vessel replacement capital requirements.
- Integrated:Hybrid architectures combining fuel cells with battery buffers dominate cruise ship specifications, where Siemens AG and Ballard Power Systems coordinate DC power distribution across multiple prime mover types.
- Standalone:Modular fuel cell skids for harbor craft and pilot boats enable rapid deployment without hull structural modification, concentrating in Danish and Swedish port service fleets.
Retrofit installations hold the largest share; integrated systems are expanding most quickly as newbuild specifications standardize hybrid powertrain architectures.
Power Output:
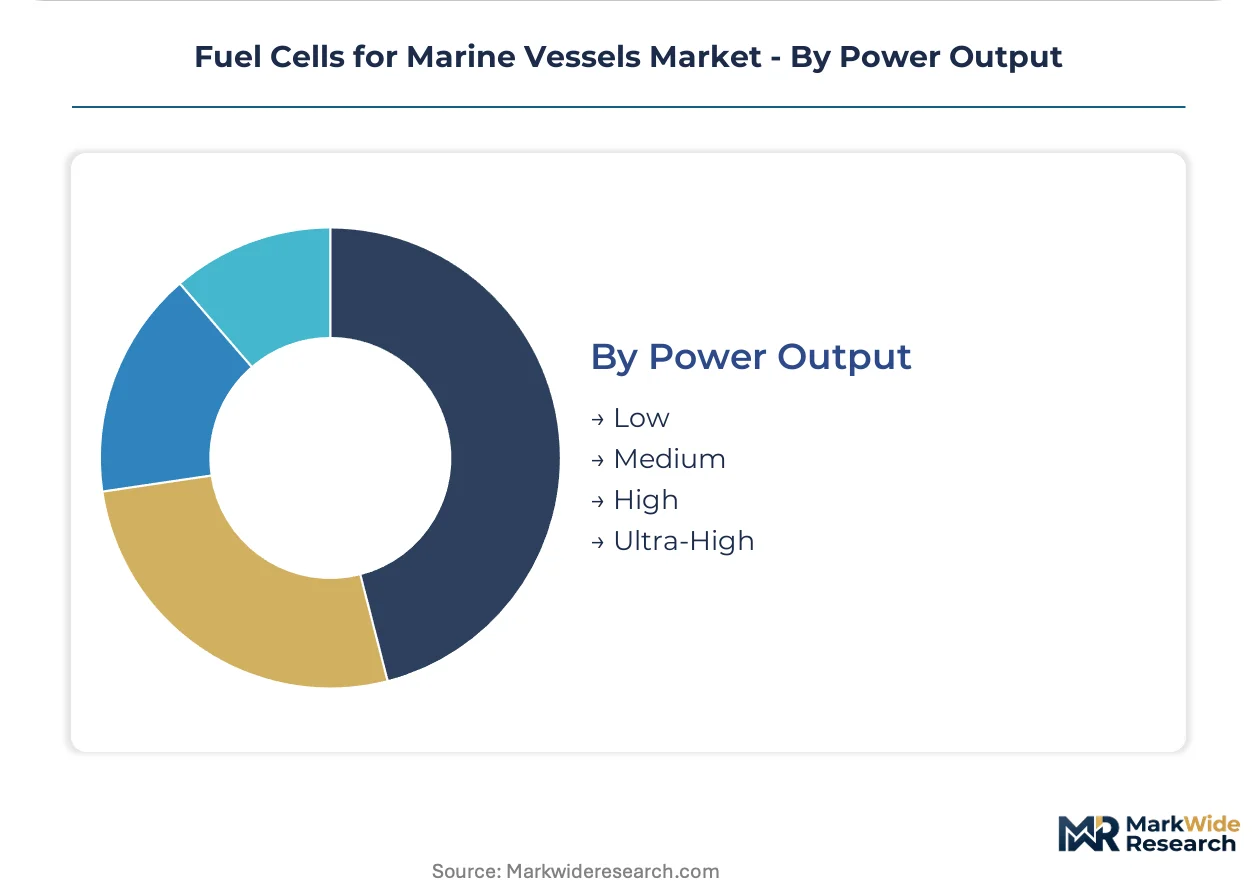
Customer type segmentation aligns power class with vessel tonnage and route duration, from sub-megawatt harbor craft to 50MW+ cruise ship auxiliary plants.
- Low:Sub-100kW systems serve harbor patrol and pilot boats in Scandinavian ports, where PEMFC modularity enables distributed auxiliary power without centralized engine room footprint constraints.
- Medium:100kW-2MW installations dominate European short-sea ferries, matching propulsion loads for 50-150 passenger vessels on 30-90 minute crossing routes.
- High:2-10MW SOFC systems anchor coastal cargo vessel specifications in Japan, where continuous baseload operation justifies higher capital cost against diesel-electric alternatives.
- Ultra-High:Above-10MW configurations target cruise ship hotel loads, with Carnival Corporation and MSC Cruises specifying SOFC auxiliary power for 50-100MW total installed capacity in newbuild programs.
Medium power output holds the largest share; ultra-high configurations are gaining share fastest as cruise operators displace conventional gensets for port emissions compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Marine fuel cell manufacturing clusters in Germany, Japan, Norway, South Korea, and the United States shape supply capacity and technology specialization across vessel classes. Each concentration anchors distinct regulatory pathways and bunkering infrastructure development trajectories.
Germany
Port authorities in Hamburg and Bremen deploy shoreside electrolysis capacity to service North Sea ferry routes. The EU Emissions Trading System maritime extension forces fleet operators to document carbon intensity indicators or face escalating port access costs. Siemens AG anchors integrated propulsion contracts through its SISHIP BlueDrive platform, coordinating fuel cell modules with battery buffers for container feeder vessels.
Japan
METI's national hydrogen strategy funds Yokohama and Kobe bunkering terminals for coastal cargo operations. Classification society rules from ClassNK shape hydrogen storage tank separation distances and ventilation requirements for shipyard retrofit timelines. Kawasaki Heavy Industries and domestic shipbuilders pilot SOFC-carbon capture convergence systems that position vessels for future carbon accounting schemes.
Norway
Scandinavian route licenses now require zero-emission capability for new vessel approvals, concentrating short-sea operator procurement toward PEMFC stacks. DNV certifies high-pressure hydrogen storage systems for ferry retrofits across Oslofjord and Bergen corridors. Norwegian ferry operators structure power purchase agreements with port authorities, transferring technology risk away from shipowner balance sheets.
South Korea
DSME and Hyundai Heavy Industries integrate factory-installed fuel cell systems in newbuilds, capturing scale economies through standardized module placement. The Ministry of Trade, Industry and Energy directs port hydrogen infrastructure investments at Busan and Ulsan to service intra-Asian container routes. Korean shipyards dominate integrated newbuild specifications with captive fuel cell module production.
United States
The US Coast Guard issues interim rules for fuel cell system placement and hydrogen storage certification that shape system integrator design choices. Great Lakes-St. Lawrence Seaway operators explore hydropower-for-electrolysis potential where hydrogen bunkering remains absent. California Air Resources Board port emissions rules accelerate harbor craft electrification mandates in Los Angeles and Long Beach.
Fuel Cells for Marine Vessels Market Vendor Landscape
Concentration sits with diversified industrial conglomerates and specialized fuel cell stack manufacturers competing across distinct vessel power classes. The market structure tiers between integrated propulsion system providers and component specialists, with technology licensing agreements bridging capability gaps. Strategic archetypes include maritime-heritage engineering groups, automotive-originated fuel cell specialists, and energy-sector diversifiers. Dominant competitive moves center on port authority partnership structures and classification society co-certification programs that accelerate vessel approval timelines.
Among Nordic and North American fuel cell specialists, Ballard Power Systems and PowerCell Sweden AB exemplify stack-density-focused archetypes targeting frequent cold-start ferry applications. Doosan Fuel Cell occupies a position within the megawatt-class baseload segment, representing Korean industrial diversification into maritime power generation. Siemens AG anchors the integrated systems tier, exemplifying European engineering conglomerate positioning across hybrid propulsion architectures.
| Leading Market Players |
|---|
| ABB Ltd. |
| Doosan Fuel Cell |
| Ballard Power Systems Inc. |
| Advent Technologies Holdings Inc. |
| Bloom Energy Corp. |
| PowerCell Sweden AB |
| Freudenberg |
| Siemens AG |
| TECO 2030 ASA |
| Others |
Supply Flow & Price Mechanics
Platinum-to-palladium substitution in PEMFC catalyst layers is redrawing procurement geography from South African mines to Russian extraction zones while compressing stack manufacturer margins during supply disruptions. This input volatility intersects with EU carbon pricing enforcement to create divergent cost structures across coastal shipping corridors.
Pricing Analysis
EU Emissions Trading System maritime extension dictates the pricing tier structure across European retrofit markets. Three-tier pricing structure across premium, standard, and economy levels separates IMO-certified systems with DNV/Lloyd's Register approval from uncertified modules and gray-market imports. Cost compression in economy-tier PEMFC stacks is intensifying because South African palladium supply disruptions force Japanese and Korean manufacturers toward alternative catalyst formulations. Container feeder operators in Germany and the Netherlands exhibit highest price sensitivity due to thin charter margins, while cruise operators prioritize certification tier over unit cost.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg elevates inbound logistics costs for Korean-manufactured SOFC modules arriving via Asia-Europe trade lanes. Manufacturing concentrates in South Korea, Japan, and Germany, with stack production drawing from platinum group metal feedstocks anchored in South Africa and Russia. Electrolyzer membrane supply rests on fluoropolymer production concentrated in China and the United States, creating tariff exposure from dual-use technology export controls. Distribution runs through port-authority-coordinated hydrogen hubs that bundle fuel cell procurement with bunkering infrastructure deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as IMO 2025 enforcement deadlines force fleet operators toward committed repowering decisions before regulatory lock-in. The penetration inflection stems from Scandinavian zero-emission route mandates that eliminate conventional auxiliary power unit options for new vessel approvals.
For Market Incumbents: Shield core revenue in Nordic ferry retrofits by securing exclusive port-authority partnership structures that transfer technology risk through power purchase agreements. LNG dual-fuel engine manufacturers are capturing risk-averse bulk carrier operators with methane-slip-reduced designs at lower capital cost. Backward integration into platinum group metal recycling or alternative catalyst R&D defends margin position against raw material volatility. For New Entrants and Emerging Players: Anchor in Great Lakes-St. Lawrence Seaway corridor electrification where abundant hydropower-for-electrolysis potential meets absent hydrogen bunkering infrastructure. Harbor craft and pilot boat segments in Danish and Swedish port service fleets offer the most penetrable white-space for modular fuel cell skid deployment without hull structural modification. A fuel-cell-as-a-service contracting model transfers stack ownership to integrators while charging per-kWh delivered, displacing traditional capital equipment procurement. For Investors and Strategic Acquirers: The market sits at a technology-validation phase that favors classification society co-certification capabilities and port infrastructure bundling. Long-term viability across the analysis window hinges on hydrogen supply chain certification scheme harmonization between Asian manufacturing hubs and European demand centers. Acquisition targets should demonstrate Lloyd's Register or DNV certification pipelines and established yard retrofit relationships. The signal to watch is Type IV composite tank approval timeline compression from 18-24 months toward 12-month cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Classification Society Co-Certification Program | DNV and Lloyd's Register joint validation compresses vessel approval timelines for Scandinavian ferry operators. |
| Port Authority Power Purchase Agreement | Hamburg and Rotterdam hydrogen supply contracts transfer technology risk from shipowner balance sheets to integrators. |
| SOFC-Carbon Capture Convergence | Kawasaki Heavy Industries pilots position Japanese coastal cargo vessels for future carbon accounting schemes. |
| Platinum Group Metal Recycling Integration | Stack manufacturers secure alternative feedstock channels against South African and Russian supply concentration. |
| High-Voltage Technician Certification Expansion | Classification society training programs address engineer scarcity constraining fleet deployment velocity. |
Methodological Framework
A spread of perspectives from shipyard engineering directors, port authority infrastructure planners, classification society technical leads, and fuel cell stack procurement managers converged on the working assumptions driving this analysis. Primary interviews with vessel operators and system integrators combined with secondary validation from IMO regulatory filings, EU ETS maritime extension documentation, Lloyd's Register and DNV certification databases, and national hydrogen strategy publications from METI and the EU Commission. Bottom-up vessel order book analysis and top-down market sizing triangulated volume and value estimates across the projection horizon.
Segmentation dimensions modeled include fuel cell technology type, vessel class, installation configuration, power output tier, and regional regulatory cluster throughout the forecast period. CAGRs derive from installed base growth trajectories, retrofit penetration rates, and newbuild specification share shifts. Industry-specific forecast inputs incorporate hydrogen bunkering terminal commissioning schedules, classification society rule publication timelines, and platinum group metal price volatility bands.
Material uncertainties — hydrogen supply chain certification delays, Type IV tank approval timeline extensions, and LNG dual-fuel engine cost competitiveness — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement consistency and port infrastructure investment continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuel Cell Technology
Residential Fuel Cell Market
Fuel Cell Technology
Solid Oxide Fuel Cell Market
Fuel Cell Technology
Asia-Pacific Fuel Cell Market
Fuel Cell Technology
Fuel Cell for Data Center Market
Fuel Cell Technology
Hydrogen Fuel Cell Stack Durability and Performance Test Equipment Market
Fuel Cell Technology
Proton Exchange Membrane Fuel Cell (PEMFC) Market
Fuel Cell Technology
Fuel Cell Interconnectors Market
Fuel Cell Technology
Hydrogen Fuel Cell Vehicle Market
Fuel Cell Technology
France Fuel Cell Market
Fuel Cell Technology
Germany Fuel Cell Market
Fuel Cell Technology
Hydrogen Fueling Nozzle Market
Fuel Cell Technology
Fuel Vending Machines Market
Fuel Cell Technology
Global Planar Solid Oxide Fuel Cell Market
Fuel Cell Technology
China Fuel Cell Market
Fuel Cell Technology
Fuel Cell Stack Market
Fuel Cell Technology
Regenerative Fuel Cell (RFC) Technologies Market