
 Belgium Wind Energy Market | 2026-2036
Belgium Wind Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Belgium Wind Energy Market Outlook
IEC 61400 offshore turbine certification is collapsing the field of qualified suppliers bidding into Belgian zone developments. Siemens Gamesa Renewable Energy leverages its factory footprint in northern France to anchor blade supply for the Belgian North Sea pipeline. Parkwind competes through integrated project development from seabed lease through grid connection. ENGIE Electrabel sustains utility-scale offtake dominance via long-term power purchase agreements with federal-backed price mechanisms.
Belgium wind energy encompasses turbine-based electricity generation systems rated from sub-megawatt units to 15 MW offshore machines, converting kinetic wind flux through variable-pitch rotor assemblies into grid-synchronous AC power for industrial and utility dispatch. Horizontal axis platforms dominate installed megawatt capacity while floating wind technology captures developer attention for water depths exceeding 60 meters where fixed foundation economics deteriorate. Offshore turbines command the structural margin pool given Belgian seabed lease scarcity and transmission cost concentration, whereas small-scale turbines occupy limited rooftop and agricultural niches with compressed returns.
The EU Green Deal and Belgium's federal offshore spatial planning framework shape licensing timelines and environmental clearance requirements for North Sea lease rounds. Flanders and Brussels regional regulators enforce grid code compliance and building permits for onshore installations under divergent permitting procedures. Stakeholders must monitor federal auction design evolution and transmission operator TenneT's interconnector buildout schedule to time capital deployment against lease windows and offtake contract availability.
Market Dynamics
Belgium's offshore wind sector faces a structural bottleneck where seabed lease scarcity concentrates developer capital around TenneT's high-voltage transmission corridors, compressing project timelines against federal auction windows.
Growth Catalysts
- EU Green Deal framework:Federal renewable procurement mandates accelerate industrial offtake agreements, pulling capital into North Sea lease rounds ahead of 2030 decarbonization targets.
- Port cluster infrastructure:Ostend and Zeebrugge assembly yards reduce turbine component logistics costs, anchoring blade and nacelle staging capacity for serial project deployment.
- Floating foundation technology:Water depths exceeding 60 meters unlock seabed areas previously excluded from fixed-bottom economics, expanding viable lease inventory beyond current zones.
Market Restraints
- Foundation steel input volatility:Monopile and jacket fabrication costs fluctuate with European steel plate pricing, squeezing EPC margins on fixed-price construction contracts.
- Grid connection queue concentration:TenneT's HVDC converter station buildout limits parallel project energization, forcing developers into sequential commissioning slots.
- IEC 61400 certification scarcity:Offshore turbine type certification collapses the qualified supplier field, constraining equipment sourcing flexibility for Belgian zone developers.
Strategic Opportunities
- Flanders onshore repowering:Aging sub-2 MW turbine fleets in agricultural zones present retrofit potential with modern 4-6 MW units under streamlined regional permitting.
- Power-to-X convergence:Electrolyzer co-location at offshore substations converts surplus wind generation into hydrogen molecules for industrial offtake at Port of Antwerp-Bruges.
- Corporate PPA channel expansion:Large industrial consumers bypass utility intermediaries through direct renewable supply contracts, opening bilateral pricing structures outside regulated tariffs.
Industry Challenges
- Marine coordination specialist scarcity:Jack-up vessel operators and subsea cable installation crews face recruitment gaps, extending construction windows beyond original schedules.
- Environmental clearance sequencing:Natura 2000 habitat assessments and benthic impact studies prolong federal licensing timelines, misaligning capital deployment with auction deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Belgium Wind Energy Market |
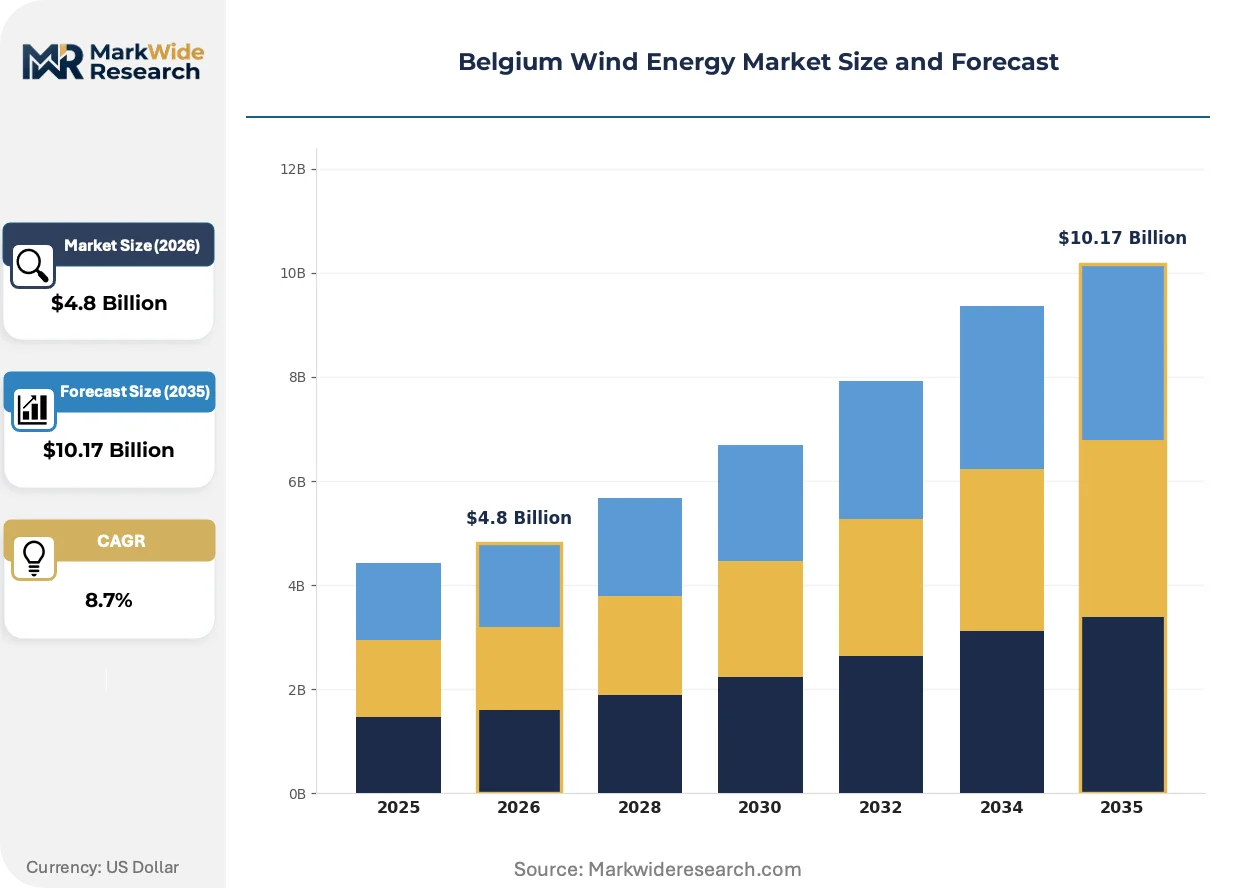
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Onshore Turbines, Offshore Turbines, Small-Scale Turbines, Hybrid Systems Technology: Horizontal Axis, Vertical Axis, Floating Wind, Fixed Foundation Capacity: Up to 50 kW, 51-100 kW, 101-500 kW, Above 500 kW End User: Utilities, Industrial Users, Commercial Entities, Residential Customers |
| Companies Covered | Siemens Gamesa Renewable Energy, PoweratSea, Parkwind, Renewable Energy Base Oostende, Storm Management, ENGIE Electrabel, Eneco Wind Belgium, Senvion, EDF Luminus, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Belgium Wind Energy Market Strategic Shifts
Technology trajectories in Belgian waters center on scaling turbine dimensions and integrating generation with downstream molecule production, while regulatory pressure accelerates supply chain localization requirements.
Direct-drive generator architecture is decomposing the traditional gearbox supply chain in offshore turbines rated above 12 MW. Parkwind and Engie Electrabel specify direct-drive units for their Belgian North Sea pipeline, eliminating gearbox maintenance cycles and compressing drivetrain supplier margins. This technology shift reduces offshore service vessel call frequency, altering O&M contract structures toward condition-based monitoring rather than scheduled gearbox replacement.
Belgium's federal offshore spatial planning framework mandates stepped-up supply chain localization quotas for seabed lease awards. Developers must demonstrate Belgian port content and domestic employment thresholds to qualify for auction participation, reshaping procurement patterns toward northern France and Dutch component suppliers with Belgian assembly footprints. Flanders and Brussels regional regulators enforce divergent onshore permitting procedures, fragmenting project development expertise across administrative boundaries.
Industrial offtakers are consolidating renewable procurement through consortium structures rather than individual corporate PPAs. Chemical and metals processors at Port of Antwerp-Bruges pool electricity demand to negotiate volume-discounted supply contracts directly with offshore wind developers, bypassing Engie Electrabel's traditional utility-scale intermediation. This buyer concentration compresses developer margin structures while accelerating project financing close timelines through committed revenue streams.
Belgium Wind Energy Market Segmentation
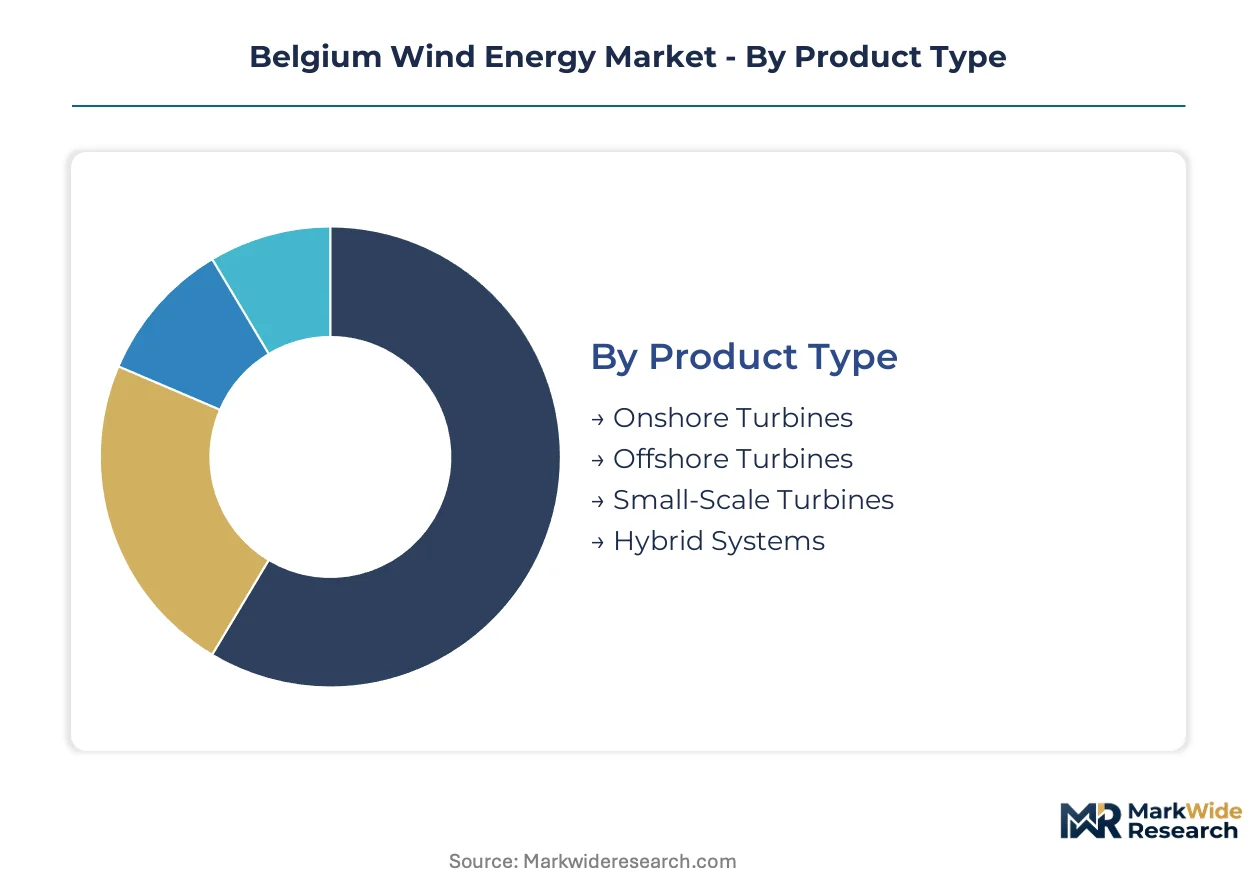
Segmentation in Belgian wind energy reveals how capital flows diverge between utility-scale offshore developments and fragmented onshore niches. Channel structures vary sharply across product types and end-user categories, with federal lease auctions concentrating developer attention on high-capacity offshore machines while regional permitting governs smaller-scale deployment.
Product Type:
Channel distribution splits between TenneT-interconnected offshore projects feeding utility offtake and regional grid codes governing onshore installations.
- Onshore Turbines:Ground-mounted systems rated 2-6 MW dominate Flanders agricultural zones, with repowering demand concentrating around aging sub-2 MW fleets. Regional regulators enforce divergent permitting timelines between Flanders and Brussels, compressing developer margins through administrative fragmentation.
- Offshore Turbines:Fixed-bottom and floating platforms rated 12-15 MW anchor the revenue pool, with seabed lease scarcity forcing capital concentration around Ostend and Zeebrugge port clusters. Direct-drive generator architecture is displacing gearbox supply chains, altering O&M contract structures toward condition-based monitoring.
- Small-Scale Turbines:Sub-100 kW units occupy limited rooftop and agricultural niches with compressed returns.
- Hybrid Systems:Wind-solar or wind-storage configurations serve industrial microgrids seeking dispatchable renewable supply.
By volume, Offshore Turbines leads. By growth pace, Hybrid Systems is expanding most quickly.
Technology:
Cost tier stratification separates mature horizontal-axis platforms from emerging floating foundations commanding premium EPC margins.
- Horizontal Axis:Three-blade upwind configurations dominate installed megawatt capacity across Belgian waters, with variable-pitch rotor assemblies optimizing energy capture. Parkwind and Engie Electrabel specify these platforms for their North Sea pipeline, leveraging established supply chains from northern France.
- Floating Wind:Semi-submersible and tension-leg platforms unlock water depths exceeding 60 meters where fixed-bottom economics deteriorate. Federal spatial planning mandates are accelerating lease inventory expansion beyond current zones, though IEC 61400 certification scarcity constrains qualified supplier fields.
- Vertical Axis:Darrieus and Savonius designs occupy niche urban applications with limited Belgian deployment.
- Fixed Foundation:Monopile and jacket structures anchor current offshore capacity, with steel input volatility squeezing EPC margins on fixed-price contracts.
By installed base, Horizontal Axis dominates. By investment momentum, Floating Wind is gaining share fastest.
Capacity:
Volume concentration clusters at the extremes: utility-scale machines above 500 kW and sub-50 kW agricultural units, with mid-range segments thinning.
- Above 500 kW:Utility-scale turbines command the structural margin pool, with offshore machines in the 12-15 MW range concentrating developer capital around federal auction windows. TenneT's HVDC converter station buildout limits parallel project energization, forcing sequential commissioning slots.
- Up to 50 kW:Small agricultural and residential units serve distributed generation needs under streamlined Flanders regional permitting. Rooftop installations face compressed returns relative to utility-scale developments.
- 51-100 kW:Mid-scale commercial applications bridge agricultural and industrial demand segments.
- 101-500 kW:Commercial and light industrial installations occupy a narrowing channel with limited project finance availability.
By revenue contribution, Above 500 kW leads. By project count growth, Up to 50 kW is climbing the fastest.
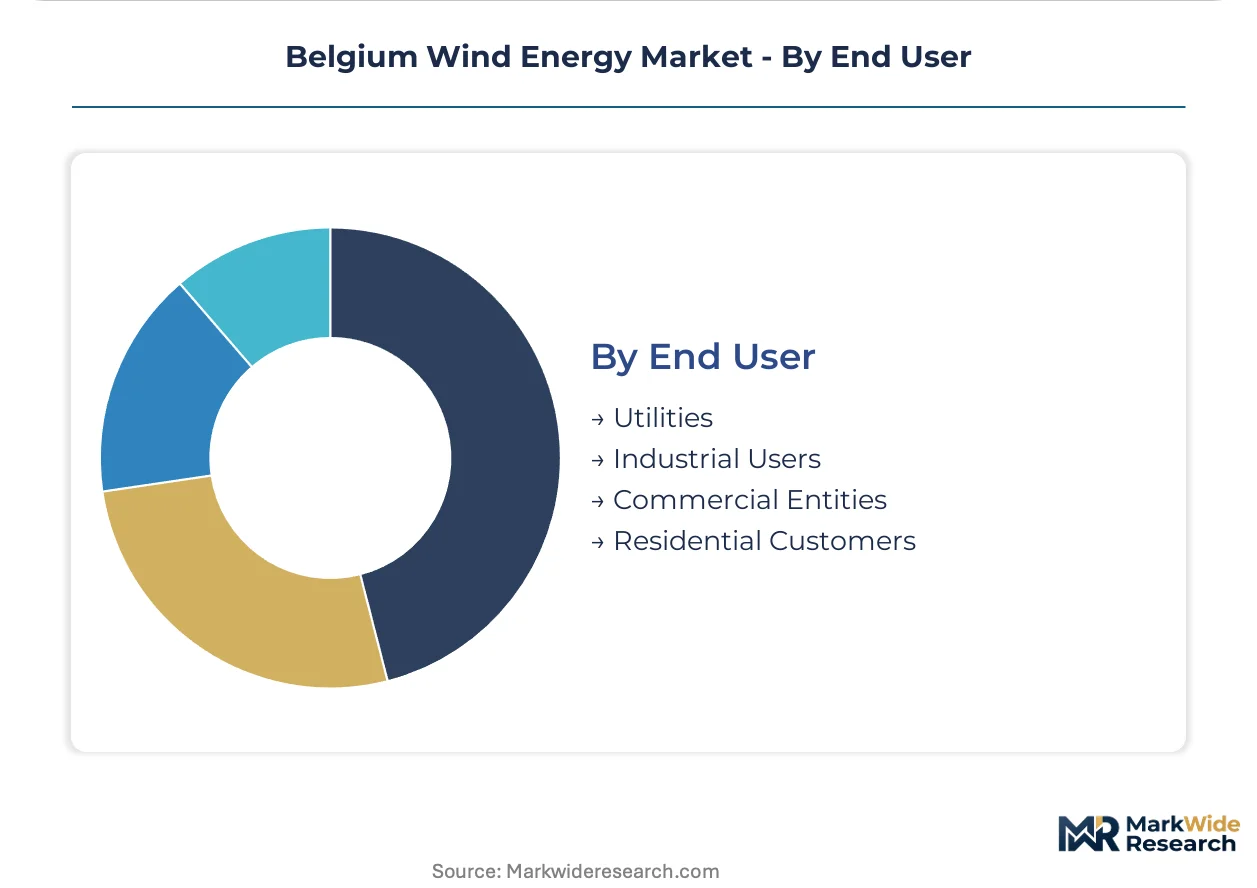
End User:
Customer type determines contract structure: utilities anchor long-term power purchase agreements while industrial users pursue direct procurement outside regulated tariffs.
- Utilities:Engie Electrabel sustains offtake dominance via federal-backed price mechanisms and long-term PPAs with offshore developers. Utility intermediation is compressing as industrial consortiums bypass traditional channels.
- Industrial Users:Chemical and metals processors at Port of Antwerp-Bruges pool electricity demand for volume-discounted supply contracts, accelerating project financing timelines through committed revenue streams.
- Commercial Entities:Mid-size enterprises seek corporate PPAs with bilateral pricing structures outside regulated tariffs.
- Residential Customers:Distributed generation adopters face limited channel support relative to utility-scale segments.
By contracted capacity, Utilities leads. By procurement innovation, Industrial Users shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial offtakers at Port of Antwerp-Bruges and utility-scale developers cluster capital around North Sea lease corridors, with federal spatial planning dictating seabed allocation timelines. Flanders and Brussels regional regulators enforce divergent permitting frameworks for onshore installations.
Flanders
Agricultural zones host aging sub-2 MW turbine fleets ripe for repowering with modern 4-6 MW units. The Flanders regional regulator enforces streamlined permitting procedures that compress development timelines relative to Brussels. Ostend anchors blade and nacelle staging capacity for serial offshore project deployment.
Brussels-Capital Region
Rooftop and distributed generation applications dominate given dense urban constraints on ground-mounted installations. Brussels regional regulators enforce stricter building codes and grid compliance requirements than Flanders. Limited channel support constrains small-scale turbine deployment relative to utility-scale segments.
Wallonia
Onshore wind development concentrates in southern agricultural corridors with lower population density than Brussels. The country's federal renewable procurement mandates pull industrial offtake agreements across regional boundaries. Sparse port infrastructure limits offshore supply chain participation relative to Flanders.
North Sea Zone
Federal seabed lease scarcity forces developer capital concentration around TenneT's HVDC transmission corridors. The EU Green Deal framework accelerates auction windows ahead of 2030 decarbonization targets. Zeebrugge assembly yards reduce turbine component logistics costs for serial deployment.
Belgium Wind Energy Market Competitive Environment
Player mix skews toward integrated developers with seabed lease holdings and utility-scale offtake relationships. Siemens Gamesa Renewable Energy anchors equipment supply through its northern France factory footprint. Parkwind and ENGIE Electrabel exemplify contrasting archetypes: Parkwind pursues integrated project development from seabed lease through grid connection, while ENGIE Electrabel sustains utility-scale offtake dominance via long-term power purchase agreements. Competitive moves center on strategic partnerships for transmission access and portfolio diversification into floating foundation technology.
Among Belgium-based developers, Parkwind occupies a position representing the integrated developer archetype with end-to-end project control. ENGIE Electrabel sits within the utility-intermediary tier, anchoring offtake relationships through federal-backed price mechanisms. Siemens Gamesa Renewable Energy represents the equipment-supplier archetype, leveraging proximity manufacturing to serve the Belgian North Sea pipeline. These three entities exemplify how certification requirements and lease scarcity collapse the qualified field into concentrated relationships.
| Leading Market Players |
|---|
| Siemens Gamesa Renewable Energy |
| PoweratSea |
| Parkwind |
| Renewable Energy Base Oostende |
| Storm Management |
| ENGIE Electrabel |
| Eneco Wind Belgium |
| Senvion |
| EDF Luminus |
| Others |
Value Chain & Pricing Dynamics
Fourteen-month lead times for monopile steel orders concentrate inventory risk at Belgian developers while amplifying pricing power for northern European fabricators with confirmed TenneT slot allocations. This duration mismatch between procurement cycles and federal auction windows forces capital pre-commitment before final offtake pricing is fixed.
Pricing Analysis
Fixed-price EPC contracts with European steel plate indexation dominate Belgian offshore project structures. Price differentiation hinges on IEC 61400 certification tier and foundation fabrication scale, with certified suppliers commanding premiums over uncertified competitors. Cost compression in monopile supply is intensifying because Belgian port content mandates redirect procurement toward higher-wage assembly zones. Industrial consortiums at Port of Antwerp-Bruges exhibit lowest price sensitivity due to volume-committed offtake structures, while independent developers face acute margin pressure from sequential TenneT queue slots.
Supply Chain Analysis
Strategic stockpiling of steel plate and nacelle components dominates over just-in-time preferences given fourteen-month procurement cycles and federal auction deadline rigidity. Supply concentrates in Germany, Denmark, and the Netherlands for foundation fabrication and drivetrain assembly. Belgian developers draw from specialized jack-up vessel operators and subsea cable installation crews concentrated in northern European maritime clusters. Single-source vulnerability sits with IEC-certified turbine suppliers, as only two manufacturers currently qualify for Belgian zone developments. Distribution runs through Ostend and Zeebrugge port clusters for blade staging and pre-assembly logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Belgium's wind energy market operates as a substitution defense against nuclear phase-out and natural gas price volatility, with incumbent utilities and industrial offtakers racing to lock renewable capacity before federal auction windows close.
For Market Incumbents: Compound seabed lease holdings through early-mover participation in federal spatial planning rounds before floating foundation zones open. Deepen backward integration into Belgian port assembly capacity to satisfy domestic content thresholds. Defend against industrial consortium bypass by offering indexed pricing structures that match direct PPA economics. For New Entrants and Emerging Players: IEC 61400 certification fast-track through joint qualification programs with established turbine OEMs offers the most viable entry path. Target Flanders onshore repowering segments where regional permitting streamlines development timelines against offshore bottlenecks. Pursue electrolyzer co-location partnerships at Port of Antwerp-Bruges to capture Power-to-X revenue stacking. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across floating foundation technology as water depths exceed sixty-meter thresholds. Five-to-ten year viability favors developers with confirmed TenneT transmission slots and long-term industrial offtake contracts. Watch federal auction design evolution as the inflection signal—shifts toward bilateral contract structures would revalue integrated developer portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Seabed Lease Acquisition | Federal spatial planning rounds allocate development rights through competitive auction mechanisms. |
| Port Infrastructure Investment | Ostend and Zeebrugge assembly yards reduce turbine component logistics costs for serial deployment. |
| Direct-drive Technology Adoption | Eliminates gearbox maintenance cycles and compresses drivetrain supplier margins in offshore units. |
| Industrial PPA Structuring | Chemical and metals processors pool demand to negotiate volume-discounted supply contracts. |
| Floating Foundation Development | Unlocks water depths exceeding sixty meters where fixed-bottom economics deteriorate. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with offshore project developers, TenneT grid planning officers, EPC contractors, and industrial offtake managers at Port of Antwerp-Bruges; and secondary validation through IEA offshore wind databases, federal spatial planning documents, and TenneT transmission buildout disclosures. Bottom-up project pipeline aggregation and top-down federal capacity target reconciliation provided cross-verification.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning turbine product type, foundation technology, capacity tier, and end-user category against regulatory framework variations. CAGRs were derived from installed base trajectories and auction pipeline conversion rates. Forecast inputs incorporated steel plate pricing volatility bands and TenneT HVDC commissioning schedules.
Decision-makers should treat outputs as directional under sustained EU Green Deal procurement mandates and federal offshore spatial planning continuity; material deviation would warrant model refresh. Revision becomes warranted when TenneT transmission queue sequencing or federal auction design crosses structural inflection thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Global Marine Wind Turbine Market
Wind Energy Systems
Wind Turbine Yaw and Pitch Gearbox Market
Wind Energy Systems
Offshore Wind Tower Market
Wind Energy Systems
Iran Wind Energy Market
Wind Energy Systems
Wind Turbine Pitch and Yaw Control System Market
Wind Energy Systems
Wind Turbine Shaft Market
Wind Energy Systems
North America Wind Power Market
Wind Energy Systems
Italy Wind Energy Market
Wind Energy Systems
Wind Turbine Brakes Market
Wind Energy Systems
Wind Turbine Gearbox Vibration and Condition Monitoring Test Platforms Market
Wind Energy Systems
Wind Turbine Decommissioning Market
Wind Energy Systems
Wind Power Forgings Market
Wind Energy Systems
Wind Speed Alarm Market
Wind Energy Systems
Wind Services Market
Wind Energy Systems
Wind Turbine Control System Market
Wind Energy Systems
Wind Energy Equipment Logistics Market