
 Bipolar Plate Coatings Market | 2026-2036
Bipolar Plate Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Bipolar Plate Coatings Market Insights
High-purity corrosion resistance specifications is redrawing competitive benchmarks across the bipolar plate coatings supply base. Impact Coatings AB leverages its PVD expertise to anchor technology leadership in fuel cell stack applications. VON ARDENNE GmbH sustains geographic dominance through European vacuum coating equipment installations. Schunk Carbon Technology differentiates via integrated carbon composite plate and coating production.
Bipolar plate coatings are thin functional layers applied to metallic, carbon, or composite substrates to prevent corrosion, reduce contact resistance, and ensure gas impermeability in electrochemical cells, typically achieving coating thicknesses below five micrometers with through-plane resistivity under ten milliohm-square centimeters. These coatings enable proton exchange membrane fuel cells and alkaline electrolyzers to maintain efficiency across thousands of operating hours. Metal coatings dominate current procurement volumes due to compatibility with stamped stainless steel plate architectures, while carbon-based coatings capture expanding share in high-temperature stationary power generation where thermal cycling tolerance proves critical. Physical vapor deposition leads technology adoption in automotive fuel cell programs demanding precise thickness control, whereas spray coating occupies cost-sensitive industrial electrolyzer segments.
EPA emission standards, the EU Green Deal hydrogen bank framework, and South Korea's METI-aligned hydrogen economy roadmap collectively mandate coated plate performance thresholds that filter out unqualified suppliers. REACH compliance and RoHS substance restrictions further constrain coating formulation chemistries, particularly for chromium-containing conversion coatings. Stakeholders must monitor evolving certification requirements across multiple jurisdictions while positioning coating technology portfolios for electrolyzer scale-up timelines that diverge from established fuel cell qualification pathways.
Market Dynamics
Corrosion-resistant coating specifications for proton exchange membrane fuel cell stacks are compressing supplier qualification timelines while electrolyzer manufacturers impose distinct performance thresholds, forcing coating specialists to maintain dual certification pathways.
Growth Catalysts
- EU F-Gas Regulation:Tightened fluorinated gas restrictions accelerate substitution of uncoated metallic plates in European electrolyzer manufacturing, mandating coated alternatives for new hydrogen production capacity.
- Physical vapor deposition:Automotive fuel cell programs demand precise thickness control below five micrometers, anchoring PVD as the dominant coating technology for transportation applications.
- Gigafactory clustering:Hydrogen equipment fabrication concentrates in Germany, South Korea, and the United States, creating localized procurement gravity that pulls coating capacity toward these production hubs.
Market Restraints
- Precious metal input costs:Platinum and iridium price volatility directly impacts noble metal coating formulations, compressing margins for suppliers locked into fixed-price automotive contracts.
- Chromium conversion coating phase-out:REACH substance restrictions and RoHS compliance mandates eliminate hexavalent chromium chemistries, forcing reformulation of legacy corrosion protection systems.
- Single-source PVD equipment:European vacuum coating system manufacturers dominate equipment supply, creating geographic concentration risk for stack producers scaling outside the region.
Strategic Opportunities
- Alkaline electrolyzer retrofit:Existing uncoated plate installations in industrial hydrogen plants present coating upgrade potential as efficiency standards tighten.
- South Korea METI hydrogen roadmap:Government-backed demand guarantees for domestic fuel cell deployment create protected procurement channels for qualified coating suppliers.
- Spray coating-industrial electrolyzer convergence:Cost-sensitive stationary power applications favor high-throughput spray processes over precision PVD, opening volume segments with different margin structures.
Industry Challenges
- Fuel cell versus electrolyzer qualification divergence:Stack manufacturers and electrolyzer builders impose incompatible testing protocols, forcing coating houses to maintain separate validation laboratories and documentation systems.
- Coating-thickness metrology standardization:Absence of unified through-plane resistivity measurement methods across ISO, IEC, and automotive OEM specifications creates certification friction and retesting costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bipolar Plate Coatings Market |
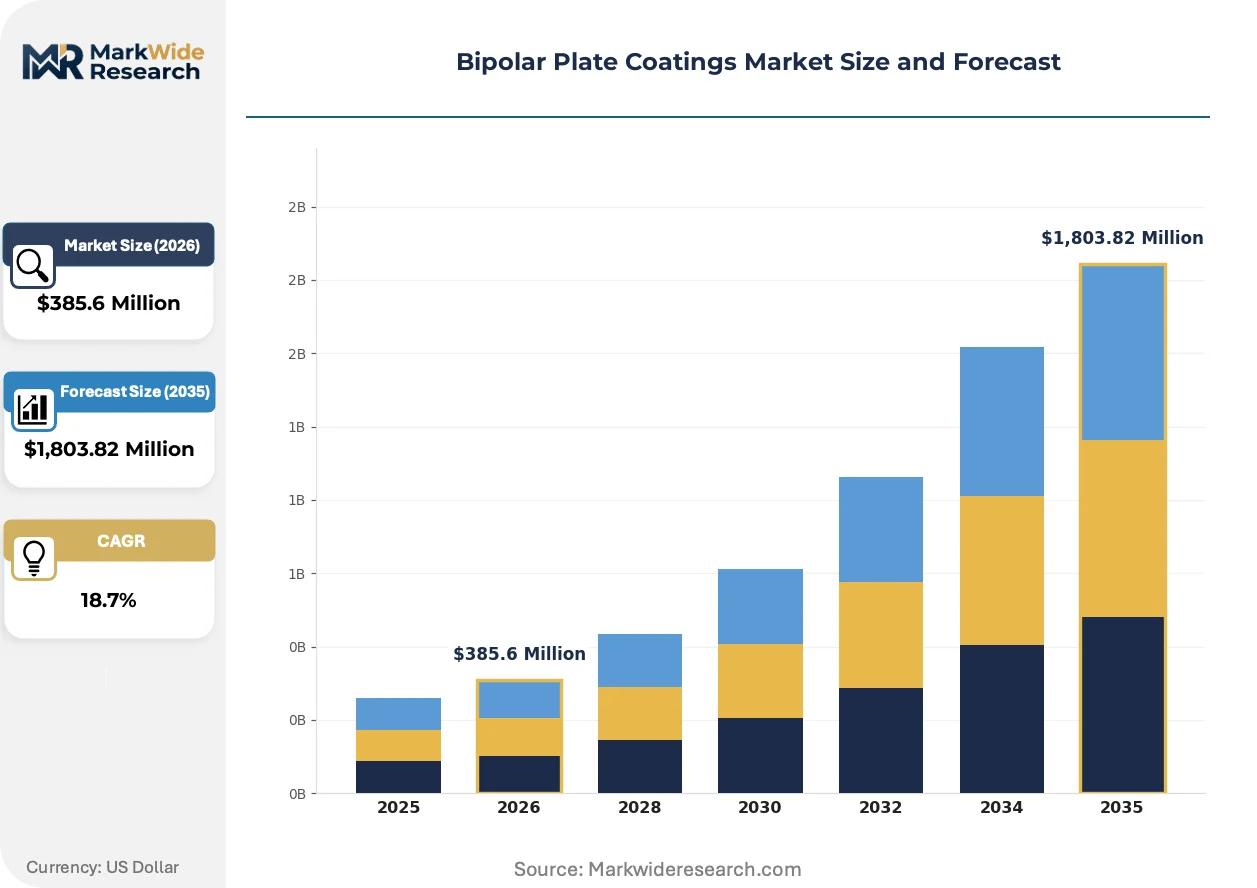
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,803.82 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon-based Coatings, Metal Coatings, Polymer Coatings, Composite Coatings Application: Fuel Cells, Electrolyzers, Energy Storage, Power Generation End User: Automotive, Aerospace, Renewable Energy, Industrial Technology: Physical Vapor Deposition, Chemical Vapor Deposition, Spray Coating, Electroplating |
| Companies Covered | Impact Coatings AB, VON ARDENNE GmbH, Sandvik, Changzhou E-Material-Technic, Dana Limited, Cell Impact, Schunk Carbon Technology, SGL Carbon, Ballard Power Systems Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bipolar Plate Coatings Market Trends and Innovations
Coating technology roadmaps are diverging between automotive precision requirements and industrial electrolyzer cost targets, with process innovation accelerating at both ends of the performance-cost spectrum.
Carbon-based coating formulations are bifurcating the thermal management segment. Composite plate manufacturers serving stationary power generation adopt graphite-doped polymer coatings for high-temperature tolerance above 150°C. Stack producers in solid oxide fuel cell programs specify these materials for thermal cycling resistance across thousands of hours. This technology split is compressing metallic coating dominance in temperature-stressed applications while expanding addressable market scope for carbon composite specialists.
The EU Green Deal hydrogen bank framework is mandating coated plate performance thresholds that filter supplier pools. ECHA REACH compliance timelines now constrain coating formulation chemistries for any stack destined for European electrolyzer builds. German and Dutch hydrogen project developers are responding by pre-qualifying coating houses against combined EU-F-Gas and automotive OEM specifications before contract award.
Buyer concentration among proton exchange membrane stack manufacturers is compressing supplier negotiation leverage. Tier-one automotive fuel cell programs now specify coating performance guarantees spanning decade-long operational lifetimes, transferring degradation risk onto coating providers. South Korean and German stack producers are consolidating qualified supplier lists to three-to-five coating houses per plate architecture, locking out smaller specialists from volume procurement.
Bipolar Plate Coatings Market Segmentation
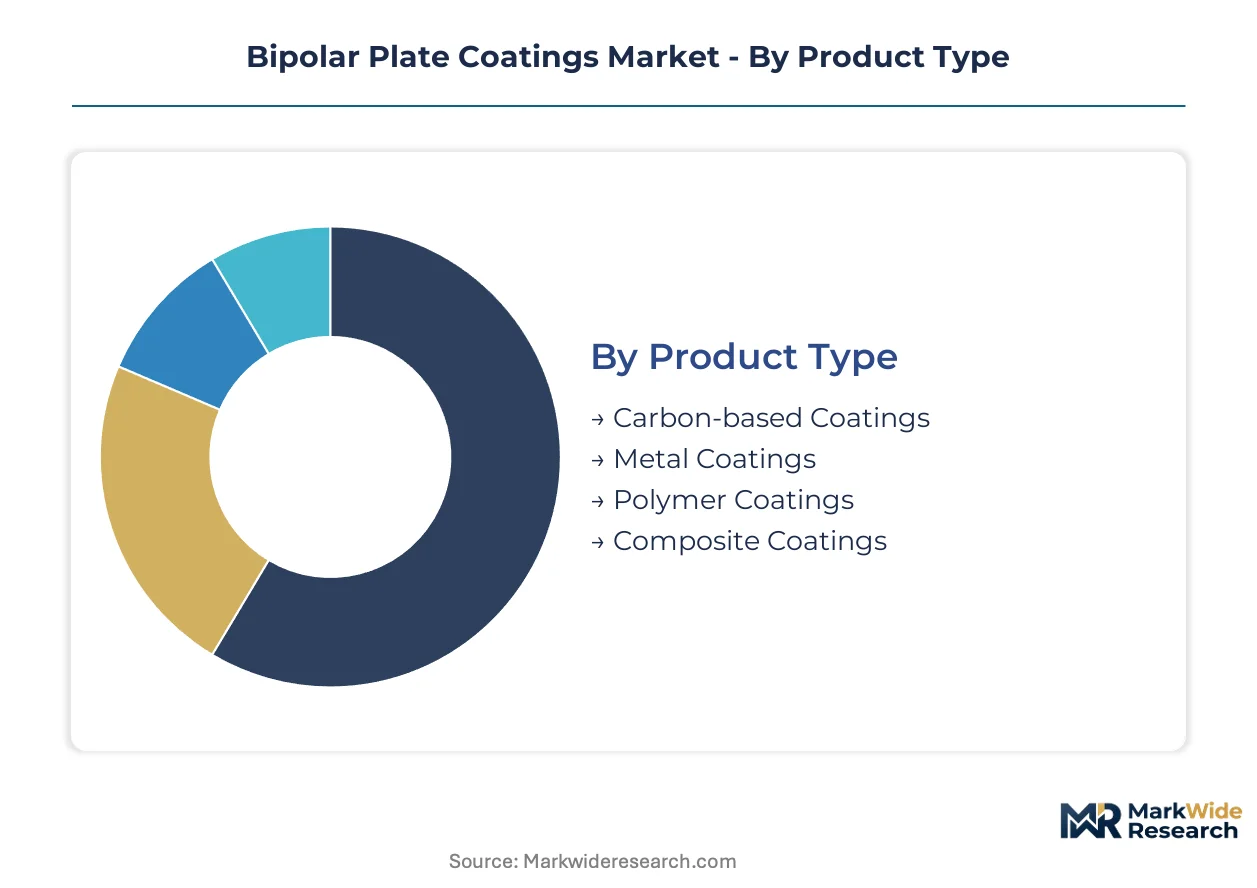
Coating technology selection directly determines stack longevity and manufacturing economics across hydrogen infrastructure deployments. Segment boundaries in this market reflect divergent performance requirements between automotive precision demands and industrial electrolyzer cost constraints.
Product Type:
Margin pools concentrate in formulations that balance corrosion resistance with through-plane conductivity specifications demanded by proton exchange membrane stack builders.
- Metal Coatings:Noble metal formulations including platinum and iridium alloys deliver sub-ten milliohm-square centimeter contact resistance for stamped stainless steel architectures. Procurement concentrates among German and South Korean automotive fuel cell programs where EPA emission standards and METI hydrogen roadmaps mandate decade-long operational guarantees.
- Carbon-based Coatings:Graphite-doped polymer layers achieve thermal cycling tolerance above 150°C for stationary power generation. Demand clusters in solid oxide fuel cell deployments where thermal management requirements exceed metallic coating limits.
- Polymer Coatings:Fluoropolymer and conductive polymer matrices serve cost-sensitive alkaline electrolyzer segments in industrial hydrogen plants.
- Composite Coatings:Hybrid ceramic-polymer systems address niche applications requiring combined chemical resistance and mechanical durability.
The dominant share belongs to Metal Coatings, while Carbon-based Coatings is closing the gap fastest as high-temperature stationary applications expand.
Application:
Volume distribution tracks hydrogen infrastructure build-out timelines across transportation and industrial decarbonization pathways.
- Fuel Cells:Proton exchange membrane stacks for electric vehicle powertrains require sub-five micrometer coating thickness with precise uniformity. South Korean and German gigafactory clusters anchor procurement gravity for automotive-qualified coating houses.
- Electrolyzers:Alkaline and proton exchange membrane hydrogen production equipment impose distinct performance thresholds, with EU F-Gas Regulation mandating coated alternatives for new European capacity.
- Energy Storage:Redox flow battery bipolar plates utilize modified coating formulations optimized for aqueous electrolyte compatibility.
- Power Generation:Combined heat and power systems specify coatings tolerant to intermittent operation and thermal transients.
Fuel Cells commands the largest procurement volumes, though Electrolyzers is expanding most quickly as green hydrogen production scales.
End User:
Customer concentration patterns reflect divergent qualification timelines between automotive OEMs and industrial equipment builders.
- Automotive:Tier-one fuel cell electric vehicle programs specify coating performance guarantees spanning full vehicle lifetimes, transferring degradation risk to suppliers. German and South Korean manufacturers consolidate qualified coating house lists to three-to-five per plate architecture.
- Industrial:Chemical, steel, and ammonia producers retrofit existing hydrogen plants with coated plates as efficiency standards tighten, creating upgrade demand distinct from new-build procurement.
- Renewable Energy:Off-grid and grid-scale hydrogen production facilities specify coatings optimized for variable renewable input profiles.
- Aerospace:Auxiliary power unit and unmanned aerial vehicle applications drive lightweight coating development with severe weight constraints.
Automotive holds the dominant position, while Industrial is gaining share fastest through retrofit opportunities in established hydrogen plants.
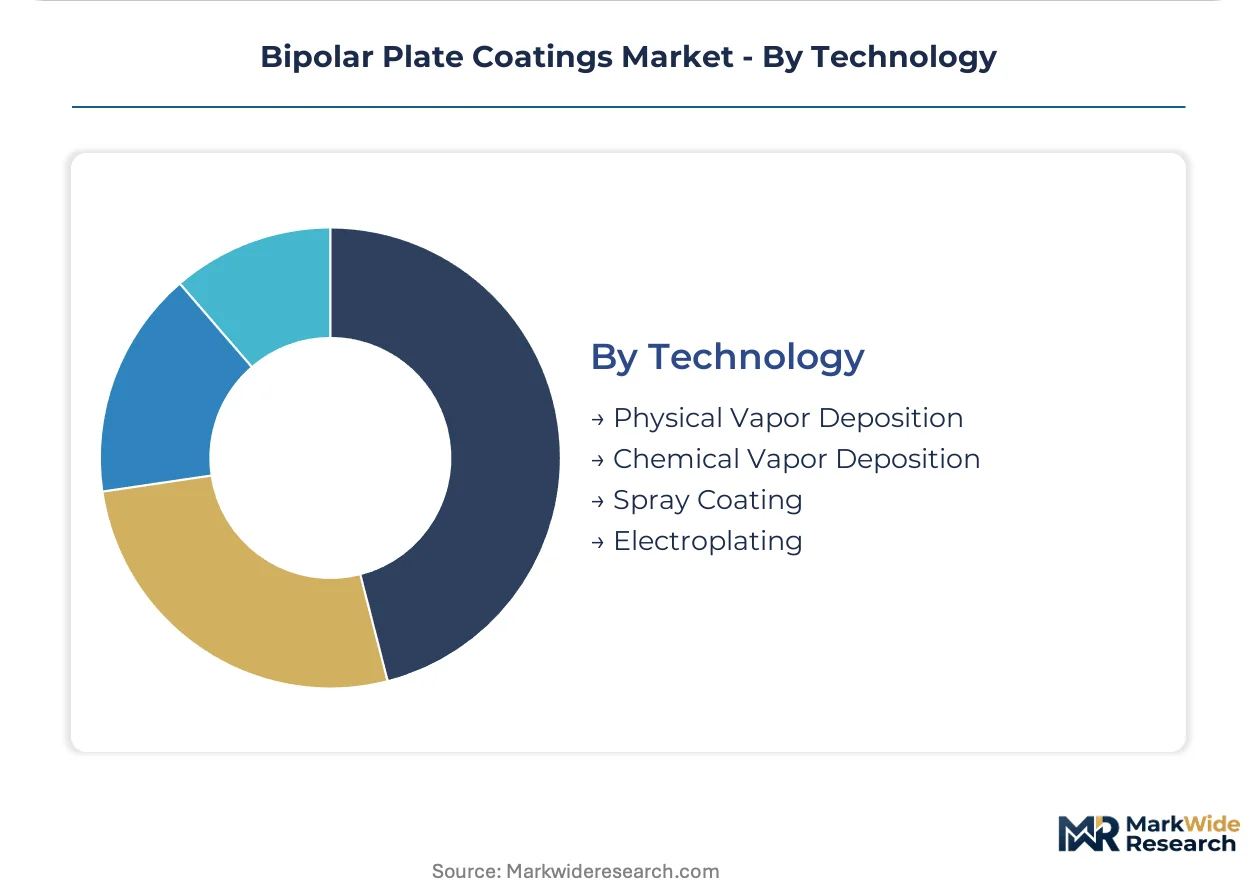
Technology:
Process selection separates precision-controlled automotive supply from high-throughput industrial coating operations.
- Physical Vapor Deposition:Sputtering and evaporation techniques achieve sub-five micrometer thickness control with exceptional uniformity. PVD dominates automotive fuel cell programs where ISO and automotive OEM specifications demand precise metrology documentation.
- Spray Coating:Airless and plasma spray processes deliver cost-efficient coverage for large-format electrolyzer plates. Industrial hydrogen equipment builders favor this approach for alkaline systems where tolerance bands exceed automotive requirements.
- Chemical Vapor Deposition:CVD enables conformal coating of complex flow field geometries with ceramic and metal-organic precursors.
- Electroplating:Aqueous deposition of noble metals persists in legacy formulations though REACH and RoHS constraints limit hexavalent chromium chemistries.
Physical Vapor Deposition leads in value terms, while Spray Coating is climbing the fastest as electrolyzer manufacturing scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coating capacity clusters where hydrogen equipment fabrication scales fastest, with procurement gravity pulling toward Germany, South Korea, and the United States as gigafactory build-outs accelerate.
Germany
Automotive fuel cell programs and electrolyzer manufacturing drive coating demand across Bavaria and North Rhine-Westphalia. The EU F-Gas Regulation and EU Green Deal hydrogen bank framework mandate corrosion-resistant specifications for all new hydrogen production capacity. Stuttgart and Munich anchor qualified supplier networks serving BMW, Mercedes-Benz, and Bosch fuel cell divisions.
South Korea
Hyundai Motor Group and Doosan Fuel Cell anchor stack production in Ulsan and Incheon, creating concentrated procurement channels. METI-aligned hydrogen economy roadmaps guarantee domestic demand through government-backed deployment targets. Gwangju and Busan host specialized coating houses pre-qualified under combined automotive and stationary power specifications.
United States
EPA emission standards and Inflation Reduction Act hydrogen production credits accelerate coated plate adoption for transportation and industrial applications. California's zero-emission vehicle mandates and Texas hydrogen hub investments concentrate demand on the coasts. Detroit and Los Angeles metropolitan areas host Tier-1 automotive fuel cell qualification programs.
China
Dual carbon goals and MIIT fuel cell vehicle subsidies expand domestic coating demand beyond import-dependent supply chains. Yangtze River Delta clusters in Shanghai and Suzhou integrate bipolar plate stamping with localized coating operations. State-backed electrolyzer manufacturing in Sichuan-Chongqing creates secondary demand centers for industrial hydrogen equipment.
Japan
METI hydrogen society roadmaps and JIS standardization efforts maintain coating demand for Toyota and Honda fuel cell platforms. Nagoya and Tokyo metropolitan areas concentrate precision coating capacity serving automotive OEM qualification timelines. Osaka-based industrial gas suppliers drive alkaline electrolyzer coating specifications for chemical sector decarbonization.
Bipolar Plate Coatings Market Competitive Landscape
Concentration sits with vacuum coating equipment specialists and integrated carbon composite manufacturers. Three tiers structure supply: PVD technology leaders, high-throughput spray coating operators, and captive in-house coating divisions of stack producers. Consolidation pressure intensifies as automotive OEMs reduce qualified supplier lists to three-to-five coating houses per plate architecture. Strategic moves center on dual-certification investments spanning fuel cell and electrolyzer qualification pathways.
Among European vacuum coating specialists, VON ARDENNE GmbH anchors equipment supply for precision deposition systems. Impact Coatings AB exemplifies the technology-licensing archetype serving stack manufacturers without captive coating capacity. Schunk Carbon Technology occupies the integrated producer position combining composite plate fabrication with in-house coating operations.
| Leading Market Players |
|---|
| Impact Coatings AB |
| VON ARDENNE GmbH |
| Sandvik |
| Changzhou E-Material-Technic |
| Dana Limited |
| Cell Impact |
| Schunk Carbon Technology |
| SGL Carbon |
| Ballard Power Systems Inc. |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day coating qualification timelines compress procurement cycles and amplify pricing power for pre-qualified suppliers serving German and South Korean automotive fuel cell programs. This lead-time band tightens supplier selection to PVD specialists with dual electrolyzer-fuel cell certification, concentrating margin capture among three-to-five coating houses per plate architecture.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure across European hydrogen equipment procurement. Three-tier pricing structure across premium, standard, and economy levels separates automotive PVD-qualified coatings from industrial spray-applied alternatives and unqualified commodity suppliers. Price differentiation centers on certification grade — ISO and automotive OEM specifications command 40-60% premiums over industrial-grade formulations. Cost compression in the standard tier intensifies because South Korean stack producers consolidate supplier lists to capture scale discounts. Industrial electrolyzer builders demonstrate highest price sensitivity, while automotive OEMs prioritize decade-long performance guarantees over unit cost.
Supply Chain Analysis
Sixty-to-ninety-day coating qualification timelines expose single-source PVD equipment dependencies concentrated in Germany. Raw material sourcing draws from South Korean iridium refiners, South African platinum suppliers, and Chinese graphite processors. Supply chain risk centers on noble metal price volatility — platinum and iridium spot movements directly compress coating formulation margins. Distribution runs through qualified supplier networks anchored in Stuttgart, Ulsan, and Detroit metropolitan clusters, with captive in-house coating divisions at major stack producers capturing 30-35% of automotive volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal hydrogen bank framework creates a high-growth disruption as electrolyzer manufacturing scales diverge from established fuel cell qualification pathways, forcing coating specialists to maintain dual certification investments.
For Market Incumbents: Fortify automotive qualification positions against electrolyzer-specialist entrants by expanding captive PVD capacity in South Korea and Germany. Secure backward integration into noble metal precursor supply through long-term offtake agreements with South African and South Korean refiners. Accelerate dual-certification laboratory investments to capture alkaline electrolyzer retrofit demand as EU F-Gas Regulation tightens. For New Entrants and Emerging Players: Spray coating service gaps in cost-sensitive industrial electrolyzer segments present white-space entry points. Target Chinese and Indian alkaline electrolyzer manufacturing clusters where tolerance bands exceed automotive precision requirements. Pursue technology licensing partnerships with European vacuum equipment specialists to bypass PVD equipment single-source bottlenecks. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial coating conglomerates with under-monetized fuel cell divisions. Position acquisitions for five-to-ten-year hydrogen infrastructure build-out trajectories. Monitor EU ECHA REACH compliance timeline acceleration as the inflection signal for coating formulation chemistry constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Laboratory Investment | Captures fuel cell and electrolyzer procurement as qualification pathways diverge under EU F-Gas Regulation. |
| Backward Integration into Noble Metal Supply | Secures iridium and platinum precursor access against South Korean and South African supply concentration. |
| Spray Coating Capacity Expansion | Serves cost-sensitive alkaline electrolyzer demand in Chinese and Indian manufacturing clusters. |
| Automotive OEM Performance Guarantee Structuring | Transfers decade-long degradation risk to coating providers while locking in volume commitments. |
| Captive PVD Equipment Manufacturing | Reduces geographic concentration risk from European vacuum coating system suppliers. |
Research Methodology
The analysis maps metal coating, carbon-based coating, polymer coating, and composite coating sub-sectors, each validated through coating technology directors, fuel cell stack procurement managers, electrolyzer project developers, and vacuum equipment specialists. Primary fieldwork combined structured interviews with secondary validation against SEC filings, EU ECHA REACH registration databases, hydrogen project development trackers, and automotive OEM supplier qualification documentation. Bottom-up coating volume estimates triangulated against top-down hydrogen equipment deployment projections.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include coating technology type, application category, end-user industry, and regional manufacturing cluster. CAGRs derived from equipment deployment timelines, regulatory mandate effective dates, and supplier capacity expansion announcements. Noble metal price trajectory assumptions and electrolyzer-fuel cell qualification divergence timelines served as industry-specific forecast inputs.
Material uncertainties — platinum-iridium price volatility, EU F-Gas Regulation enforcement intensity, automotive OEM supplier consolidation pace — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from these factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuel Cell Technology
Fuel Cell for Data Center Market
Fuel Cell Technology
Direct Methanol Fuel Cell Market
Fuel Cell Technology
Europe Direct Methanol Fuel Cell Market
Fuel Cell Technology
Global Micro Fuel Cells Market
Fuel Cell Technology
Asia-Pacific Direct Methanol Fuel Cell Market
Fuel Cell Technology
Residential Fuel Cell Market
Fuel Cell Technology
North America Microbial Fuel Cell Market
Fuel Cell Technology
Fuel Cells for CHP Application Market
Fuel Cell Technology
Regenerative Fuel Cell (RFC) Technologies Market
Fuel Cell Technology
Membrane Electrode Assembly Market
Fuel Cell Technology
Hydrogen Fuel Cell Stack and Membrane Recycling for EU Mobility Market
Fuel Cell Technology
China Fuel Cell Market
Fuel Cell Technology
Hydrogen Fuel Cell Vehicle Market
Fuel Cell Technology
Proton Exchange Membrane Fuel Cell (PEMFC) Market
Fuel Cell Technology
North America Fuel Cell Technology Market
Fuel Cell Technology
Fuel Cell Market