
 Solid Oxide Fuel Cell Market | 2026-2036
Solid Oxide Fuel Cell Market Size, Share, and Industry Trends Forecast 2026-2036
Solid Oxide Fuel Cell Market Intelligence
The trend toward modular, scalable power generation systems is hardening buyer preference for flexible deployments over monolithic installations. This shift favors suppliers with adaptable technology platforms. Bloom Energy leverages its modular architecture for large-scale power projects in the data center and utility sectors. Ceres Power Holdings specializes in an asset-light licensing model, enabling partners to integrate its technology. Meanwhile, Sunfire differentiates through its focus on reversible SOFCs that can also produce green hydrogen via high-temperature electrolysis.
A solid oxide fuel cell is an electrochemical device that converts chemical energy from a fuel directly into electricity. It operates at high temperatures, typically between 600 and 1,000 degrees Celsius, using a solid ceramic material as the electrolyte. This high-temperature operation allows for fuel flexibility and high electrical efficiency. Stationary power generation applications for industrial facilities and data centers constitute the dominant end-use segment. Among product types, planar SOFCs lead in market adoption due to superior power density and established manufacturing processes.
Regulatory frameworks are critical in shaping market development. The US Inflation Reduction Act (IRA) and the EU Green Deal provide significant tax credits and subsidies for clean energy technologies, including high-efficiency fuel cells. In Asia, policies from Japan's Ministry of Economy, Trade and Industry (METI) promote SOFCs for residential and commercial energy security. The ability to secure supply chains for critical ceramic and metallic components will dictate manufacturing scalability and cost competitiveness.
Market Dynamics
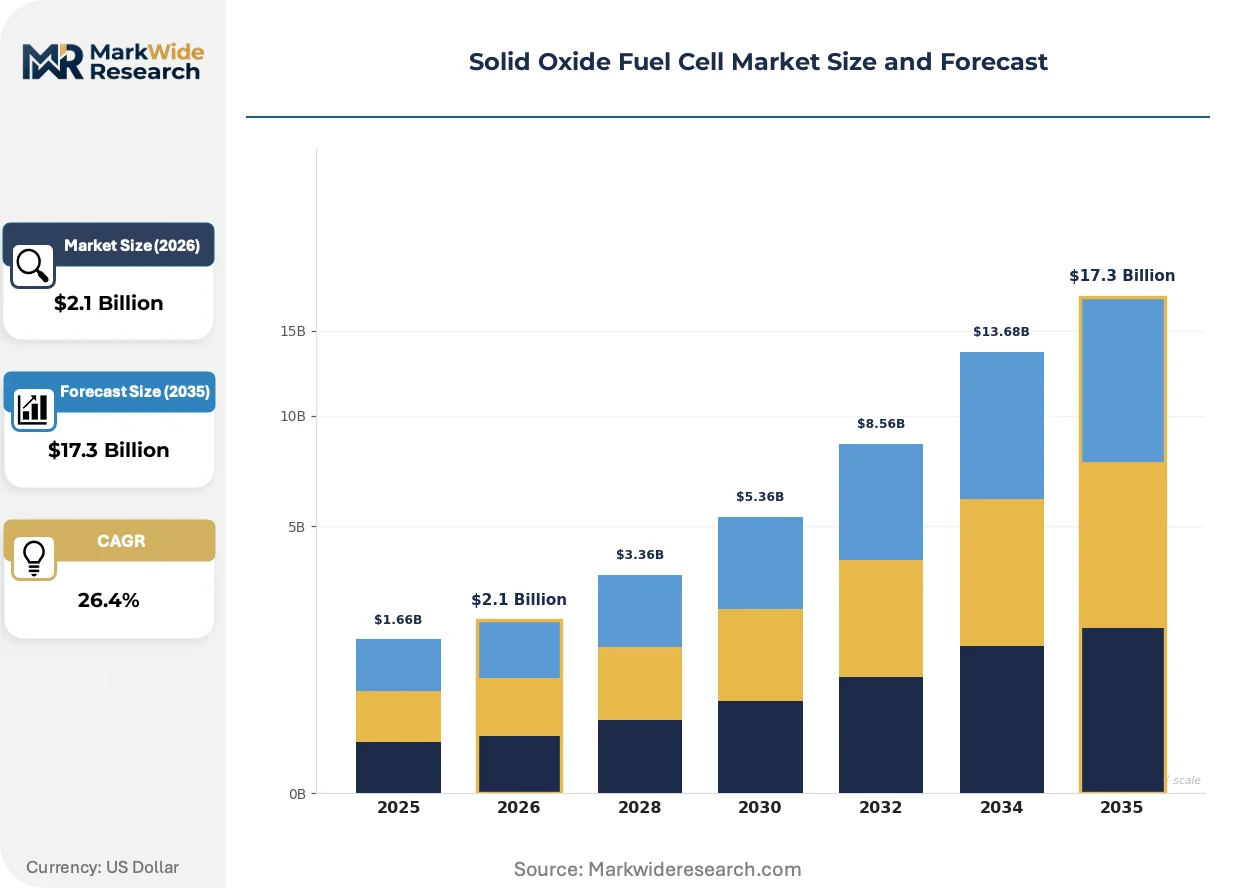
The central dynamic shaping the Solid Oxide Fuel Cell market is the push for high-efficiency, fuel-flexible power generation clashing with the high-temperature material science and manufacturing cost challenges inherent to the technology's core design.
Growth Catalysts
- Supportive Regulatory Frameworks:The US Inflation Reduction Act (IRA) provides significant tax credits for high-efficiency fuel cells, directly lowering the capital expenditure for adopters in stationary power and hydrogen production applications.
- Data Center Power Demand:The need for reliable, continuous, and low-emission power for data centers is a primary catalyst, as SOFCs offer on-site generation that improves energy security and reduces grid dependency.
- Energy Security Policies:Government initiatives, particularly from Japan's Ministry of Economy, Trade and Industry (METI), promote SOFC deployment in residential and commercial sectors to enhance national energy resilience and meet decarbonization goals.
Market Restraints
- High Capital Costs:The use of expensive ceramic materials and specialized high-temperature alloys for components like interconnects and seals results in a high initial system cost, hindering widespread adoption compared to conventional power technologies.
- Material Degradation:Long-term operation at high temperatures leads to material degradation, particularly at the electrode-electrolyte interface, which can reduce performance and operational lifespan, creating a significant technical barrier.
- Fuel Purity Requirements:SOFC systems are sensitive to contaminants like sulfur in the fuel stream, which can poison the anode. This necessitates additional fuel processing equipment, increasing system complexity and cost.
Strategic Opportunities
- Maritime Sector Decarbonization:The global shipping industry's search for alternatives to fossil fuels presents a major opportunity for SOFCs, which can operate on future fuels like ammonia and hydrogen to meet stringent emissions regulations.
- Reversible SOFC Systems:The development of reversible solid oxide cells (rSOCs) that can operate in both fuel cell and electrolysis modes opens new markets for integrated energy storage and green hydrogen production.
- Hybrid Power Plant Integration:Opportunities exist to integrate SOFCs with gas turbines in hybrid power cycles, significantly boosting overall electrical efficiency and creating a pathway for decarbonizing existing thermal power assets.
Industry Challenges
- Manufacturing Scale-Up:Achieving high-volume, automated manufacturing of SOFC stacks while maintaining tight quality control and reducing per-unit costs remains a primary operational challenge for producers seeking to meet projected demand.
- System Integration Complexity:Integrating SOFC modules with the balance-of-plant components, including heat exchangers, fuel processors, and power electronics, requires specialized engineering expertise and adds to project timelines.
- Long Start-Up Times:The need for slow, controlled heating to prevent thermal shock to ceramic components results in long start-up times, limiting the technology's suitability for applications that require rapid power dispatch.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solid Oxide Fuel Cell Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $17.3 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Planar, Tubular, Monolithic, Flat-Plate, Corrugated Technology: Metallic Interconnect, Ceramic Interconnect, Electrolyte Supported, Anode Supported, Cathode Supported Application: Stationary Power Generation, Auxiliary Power Units, Military Power Systems, Distributed Generation, Backup Power Systems End User: Industrial Facilities, Residential Complexes, Commercial Buildings, Remote Telecom Stations, Data Centers |
| Companies Covered | Kyocera Corporation, FuelCell Energy, Bloom Energy, Elcogen, Sunfire, Mitsubishi Heavy Industries, Ceres Power Holdings, Doosan Fuel Cell, AISIN Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solid Oxide Fuel Cell Market Strategic Shifts & Innovations
A fundamental shift from research-focused development to commercial-scale deployment defines the market. This transition prioritizes modularity, manufacturing efficiency, and integration with emerging hydrogen infrastructure, moving SOFCs into mainstream power generation roles.
Planar SOFC design utilizes flat, plate-like ceramic cells stacked together to achieve high power density. Stationary power generation for industrial facilities and mission-critical data centers represents the primary adopter of this configuration. The technology's superior efficiency and established manufacturing processes are consolidating its position as the dominant architecture over older tubular designs for large-scale projects.
The EU Green Deal provides a comprehensive policy framework and financial incentives for clean energy technologies, including high-efficiency fuel cells and green hydrogen production. This directive accelerates private and public investment in SOFC manufacturing capacity and deployment projects across the European Union. The industrial power segment is most affected, with companies in Germany and the Netherlands integrating SOFC systems to comply with emissions reduction mandates.
Buyers are increasingly favoring flexible, modular power generation systems that can be scaled in stages to match evolving demand. This preference disrupts the traditional procurement of large, monolithic power installations, creating an advantage for suppliers with adaptable and repeatable system architectures. This trend is most visible in the data center sector, where power capacity must be added incrementally without interrupting operations.
Solid Oxide Fuel Cell Market Segmentation
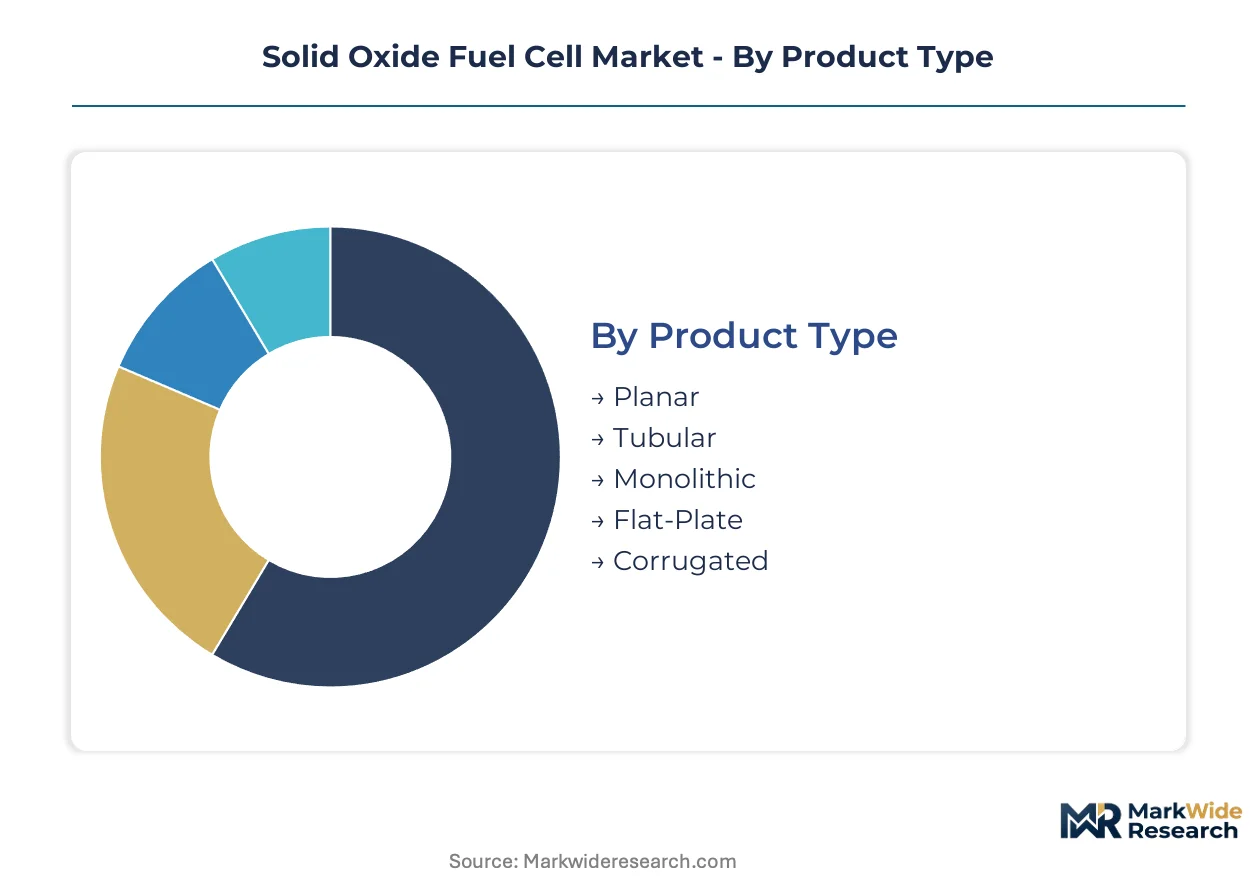
The Solid Oxide Fuel Cell market's segmentation provides a detailed lens into the technology's evolving adoption patterns and commercial viability. Understanding these distinct categories helps stakeholders identify specific growth pockets and material science challenges within the broader energy transition. Each segment reflects unique operational demands and technological preferences shaping the competitive landscape.
Product Type:
The market for solid oxide fuel cells sees continuous innovation driving upgrade and replacement cycles, particularly in product design.
- Planar:This configuration utilizes flat, plate-like ceramic cells stacked together, offering high power density and established manufacturing processes. Demand concentrates in large-scale stationary power generation projects for industrial facilities due to its superior efficiency.
- Tubular:These designs feature cylindrical cells, which historically offered better thermal cycling stability but generally lower power density per unit volume. The maritime sector explores tubular SOFCs for their robustness in dynamic environments.
- Monolithic:Monolithic SOFCs integrate electrodes and electrolytes into a single, co-fired structure, aiming for reduced manufacturing costs and increased power density. This design targets compact, high-performance applications where space is a premium.
- Flat-Plate:Flat-plate designs offer a simplified manufacturing process compared to more complex geometries, facilitating easier scaling. These are often considered for cost-sensitive applications requiring moderate power output.
- Corrugated:Corrugated SOFCs introduce a wavy cell structure to increase the active surface area within a given volume, aiming for enhanced power output. This approach seeks to balance power density with structural integrity.
Planar SOFCs sit at the top of the volume ranking, with Monolithic designs climbing the fastest.
Technology:
Material science advancements influence the cost tiering of SOFC technologies.
- Metallic Interconnect:These interconnects are cost-effective and offer good electrical conductivity, making them prevalent in many commercial SOFC stacks. The technology faces material degradation challenges at high temperatures.
- Anode Supported:This design places the structural support on the anode, allowing for thinner electrolyte layers and lower operating temperatures, which improves electrical efficiency. Data centers adopt anode-supported systems for their high performance and reliability.
- Ceramic Interconnect:Ceramic interconnects provide superior chemical stability and thermal compatibility with other cell components, extending operational lifespan. They are often chosen for applications requiring extreme durability.
- Electrolyte Supported:In this traditional design, the electrolyte provides the mechanical strength for the cell, requiring thicker electrolyte layers and higher operating temperatures. This configuration offers robust performance in specific industrial settings.
- Cathode Supported:Cathode-supported designs are less common but offer potential advantages in specific material combinations and fabrication processes. Research focuses on optimizing their performance for niche applications.
Metallic Interconnect technology holds the largest share, while Cathode Supported designs show significant promise for future cost reductions.
Application:
The diverse application landscape reflects varying energy demands and operational requirements.
- Stationary Power Generation:SOFCs provide continuous, high-efficiency electricity for industrial facilities and commercial buildings, often displacing conventional grid power. The US Inflation Reduction Act provides tax credits for these high-efficiency fuel cells.
- Distributed Generation:This application involves smaller-scale power generation units located closer to end-users, enhancing energy resilience and reducing transmission losses. Japan's METI promotes distributed SOFCs for national energy security.
- Auxiliary Power Units:SOFCs serve as efficient power sources for vehicles and ships, reducing fuel consumption and emissions during idling or auxiliary operations. The maritime sector evaluates these for decarbonization efforts.
- Military Power Systems:These systems require robust, reliable, and often silent power solutions for field operations and remote bases. SOFCs offer fuel flexibility and high efficiency for critical defense infrastructure.
- Backup Power Systems:SOFCs provide reliable emergency power during grid outages, ensuring continuous operation for critical infrastructure like data centers and hospitals. Their long run-time capabilities are a key advantage.
Stationary Power Generation remains the dominant application, with Distributed Generation expanding most quickly in new deployments.
End User:
End-user adoption patterns reveal distinct operational priorities and infrastructure needs.
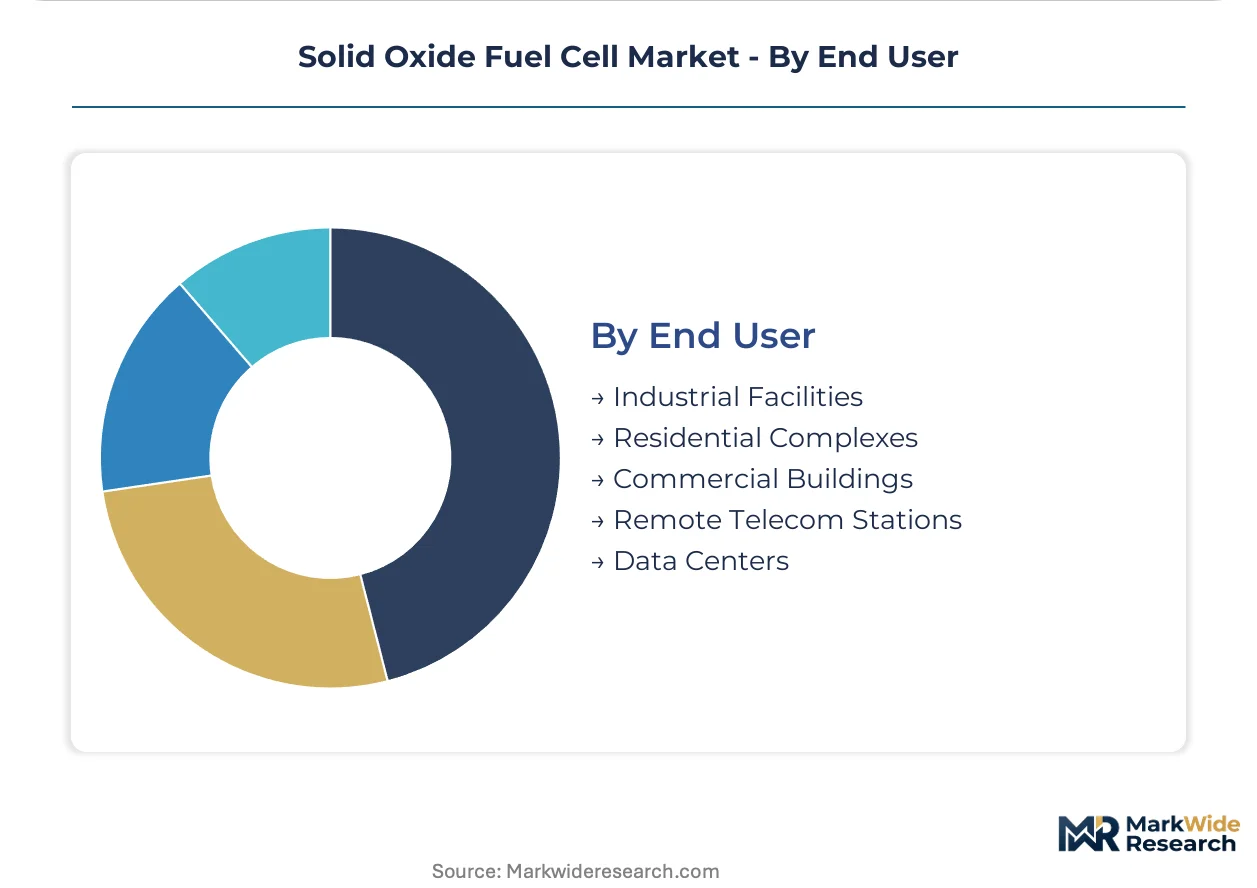
- Data Centers:These facilities require highly reliable, continuous, and low-emission power, making SOFCs an ideal on-site generation solution. Data centers prioritize energy security and reduced grid dependency.
- Industrial Facilities:Manufacturing plants and processing facilities utilize SOFCs for combined heat and power (CHP) applications, maximizing energy efficiency. The EU Green Deal incentivizes SOFC integration in industrial settings to meet emissions reduction mandates.
- Residential Complexes:SOFCs provide highly efficient micro-CHP solutions for multi-unit dwellings, reducing energy bills and carbon footprints. Government initiatives in Japan support residential SOFC deployment.
- Commercial Buildings:Offices, retail spaces, and hotels deploy SOFC systems for on-site power generation, improving energy independence and sustainability. These users seek consistent power quality and operational cost savings.
- Remote Telecom Stations:SOFCs offer a reliable and low-maintenance power source for off-grid or difficult-to-access communication infrastructure. Their fuel flexibility is critical for remote site operations.
Data Centers represent a critical demand segment, and Remote Telecom Stations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Solid Oxide Fuel Cell technology gained early traction in countries prioritizing energy independence and high-efficiency power generation. Early research and development efforts laid the groundwork for its current commercial deployment. This foundational work established the market's initial regional strongholds.
Japan
Demand for SOFCs in Japan stems from a national focus on energy security and decarbonization goals. Japan's Ministry of Economy, Trade and Industry (METI) actively promotes SOFC deployment for both residential and commercial applications. Tokyo and Osaka metropolitan areas see significant uptake in micro-CHP systems for urban energy resilience.
United States
The US market for SOFCs is driven by the critical need for reliable, low-emission power in data centers and industrial facilities. The US Inflation Reduction Act (IRA) provides substantial tax credits, significantly lowering capital expenditures for adopters. California's tech hubs and Texas's industrial corridors are integrating SOFCs for on-site power generation.
Germany
Industrial facilities in Germany seek SOFC solutions for high-efficiency combined heat and power applications. The EU Green Deal provides a comprehensive policy framework and financial incentives for clean energy technologies, including SOFCs. The Ruhr region's heavy industries and Bavaria's manufacturing sector are adopting SOFC systems to meet stringent emissions reduction mandates.
South Korea
Government support for hydrogen economies strongly influences South Korea's SOFC market, alongside national emissions reduction targets. Policies from the Ministry of Trade, Industry and Energy (MOTIE) foster hydrogen fuel cell development and deployment. Ulsan and Gyeonggi Province are emerging as key centers for SOFC manufacturing and integration into industrial hydrogen infrastructure.
Netherlands
Decarbonization efforts within the industrial sector are a primary demand driver for SOFCs in the Netherlands. The EU Green Deal incentivizes companies to integrate high-efficiency fuel cells to comply with environmental regulations. The Port of Rotterdam and industrial clusters in North Brabant are piloting SOFC installations for sustainable energy production.
Solid Oxide Fuel Cell Market Key Industry Players
Premium-margin players sit above commodity-margin players across technological innovation and system integration capabilities, reflecting varied business models. The market exhibits a tiered structure, with established industrial giants coexisting with specialized technology developers and component manufacturers. Strategic archetypes include integrated system providers, asset-light technology licensors, and niche application specialists focusing on specific fuel types or operational modes. Dominant competitive moves involve strategic partnerships for market access, continuous investment in R&D to enhance material science, and capacity expansions to meet demand.
Specialists in technology licensing and modular system design, such as Ceres Power Holdings, represent a significant segment driving market adaptability and broader technology integration. Bloom Energy exemplifies integrated solution providers, leveraging its modular architecture for large-scale power projects in critical infrastructure sectors. Meanwhile, Sunfire occupies a position among innovators focusing on reversible SOFCs for green hydrogen production, showcasing diversification into new energy vectors and expanding the technology's application scope.
| Leading Market Players |
|---|
| Kyocera Corporation |
| FuelCell Energy |
| Bloom Energy |
| Elcogen |
| Sunfire |
| Mitsubishi Heavy Industries |
| Ceres Power Holdings |
| Doosan Fuel Cell |
| AISIN Corporation |
Cost & Logistics Intelligence
Expensive ceramic and metallic components dictate the Solid Oxide Fuel Cell system's initial capital expenditure, influencing its pricing structure for stationary power generation projects. This material cost flows directly into the final system price for data centers and industrial facilities.
Pricing Analysis
Project-based contracting characterizes the Solid Oxide Fuel Cell market, where system integrators offer tailored solutions to large industrial and data center clients. Price differentiation stems from the level of system customization required for specific facility integration and the guaranteed operational performance tier. Pricing softness reflects competition from established conventional power generation technologies and the high initial capital outlay. Residential complexes, often supported by government incentives, exhibit the highest price sensitivity for SOFC deployments.
Supply Chain Analysis
Material recovery and refurbishment flows for high-value ceramic components represent an emerging focus for Solid Oxide Fuel Cell manufacturers aiming to extend product lifecycles. Supply concentration centers on specialized material producers in countries like Japan, South Korea, and China. The market draws from critical ceramic materials and specialized metallic alloys, essential for high-temperature operation. Geopolitical tensions affecting rare earth elements or specialized alloy sourcing present a structural supply chain risk, while distribution runs through direct sales channels to large industrial off-takers and technology licensing agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Solid Oxide Fuel Cell market acts as a stable compounder, driven by global decarbonization mandates and the increasing demand for high-efficiency, low-emission power solutions. This market offers consistent long-term growth for strategic participants.
For Market Incumbents: Lock in long-term supply agreements for specialized ceramic and metallic components to mitigate raw material price volatility and ensure production stability. Expand automated manufacturing capacity in key geographies like South Korea and Germany to achieve economies of scale against high capital costs. Continuous R&D into advanced material science is essential to combat material degradation, a significant technical barrier. This strategy defends market share against emerging alternative clean energy technologies.
For New Entrants and Emerging Players: Specialized B2B marketplaces for modular energy solutions provide a direct route to engage industrial buyers seeking flexible power deployments. Target the nascent maritime sector decarbonization segment with SOFCs capable of utilizing future fuels like ammonia. Focus on developing reversible SOFC systems for integrated energy storage, leveraging a technology licensing model to penetrate markets like Japan and South Korea. This approach capitalizes on niche demand for high-efficiency, adaptable power solutions.
For Investors and Strategic Acquirers: Consolidation pressure builds where high capital expenditure for manufacturing scale-up meets the need for specialized material science expertise. The Solid Oxide Fuel Cell market offers long-term viability within the energy transition, particularly for high-efficiency stationary power and hydrogen applications. Target specialized component manufacturers or asset-light technology licensors like Ceres Power Holdings for strategic acquisitions. Monitor successful large-scale project deployments and substantial cost reduction breakthroughs as key inflection indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Manufacturing | Achieves economies of scale for SOFC stacks, lowering per-unit costs and meeting projected demand. |
| Technology Licensing Agreements | Enables broader market penetration for core SOFC technology through established partners, expanding adoption. |
| Advanced Material Science R&D | Extends operational lifespan and reduces material degradation, addressing a core technical barrier. |
| Long-term Critical Component Supply Agreements | Secures stable sourcing of specialized ceramics and alloys, mitigating supply chain risks. |
| Strategic Partnerships for System Integration | Facilitates seamless integration of SOFC modules with balance-of-plant components for complex projects. |
Research Approach
Direct dialogue with industrial facility managers, data center operators, SOFC technology developers, and government energy policy advisors forms the bedrock of this analysis. This primary research is rigorously validated against extensive secondary sources including US Inflation Reduction Act documents, EU Green Deal policy papers, and company annual filings. A robust bottom-up and top-down triangulation approach ensures data accuracy across all market segments.
Market sizing and growth projections were generated through a comprehensive analytical framework, integrating historical trends with future adoption forecasts across the analysis window. Segmentation dimensions modeled include product type, technology, application, end-user, and regional regulatory frameworks. Compound annual growth rates were derived from technological advancements and policy impacts. Decarbonization targets and hydrogen infrastructure development served as critical forecast inputs.
Material science breakthroughs, regulatory shifts, and manufacturing scale-up success are the dominant revision risks to market forecasts. These projections reflect assumptions regarding technological maturation and policy stability. Practitioners should monitor SOFC cost reduction trends and global hydrogen infrastructure development for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuel Cell Technology
France Fuel Cell Market
Fuel Cell Technology
Alkaline Fuel Cell Market
Fuel Cell Technology
Aircraft Fuel Cell Market
Fuel Cell Technology
North America Fuel Cell Technology Market
Fuel Cell Technology
Fuel Cell Stack Market
Fuel Cell Technology
Hydrogen Fuel Cells Market
Fuel Cell Technology
Europe Fuel Cell Market
Fuel Cell Technology
Portable Fuel Cells Market
Fuel Cell Technology
PEM Electrolyzer Market
Fuel Cell Technology
Germany Fuel Cell Market
Fuel Cell Technology
Global Planar Solid Oxide Fuel Cell Market
Fuel Cell Technology
Fuel Vending Machines Market
Fuel Cell Technology
Hydrogen Fueling Nozzle Market
Fuel Cell Technology
Asia-Pacific Fuel Cell Market
Fuel Cell Technology
Membrane Electrode Assembly Market
Fuel Cell Technology
Microbial Fuel Cell Market