
 Fuel Cell for Stationary Power Market | 2026-2036
Fuel Cell for Stationary Power Market Size, Share, and Industry Trends Forecast 2026-2036
Fuel Cell for Stationary Power Market Foresight
Platinum is consolidating its role against palladium and iridium alternatives in membrane electrode assemblies, lowering stack costs for high-duration stationary units. Bloom Energy leverages solid oxide architecture to anchor utility-scale deployments across California and South Korean industrial parks. FuelCell Energy sustains carbonate fuel cell manufacturing at scale for combined heat and power installations. Siemens Energy competes through electrolyzer-to-fuel-cell system integration, extending its power-to-x portfolio into stationary applications.
A fuel cell for stationary power electrochemically converts hydrogen or reformed natural gas into electricity through proton exchange, solid oxide, molten carbonate, or phosphoric acid chemistries, with electrical efficiencies ranging from 40 to 60 percent and total energy recovery exceeding 80 percent in combined heat and power configurations. Solid oxide systems lead in utility-scale prime power due to high operating temperatures enabling internal reforming, while proton exchange membrane stacks dominate backup power for data centers and telecommunications where rapid cold-start response matters. Combined heat and power applications capture the deepest margin pools by monetizing waste heat for district heating and industrial process steam.
The US EPA stationary source emission standards and FERC interconnection rules shape product certification timelines and grid access economics for domestic manufacturers. Japan's METI hydrogen supply chain targets and South Korea's renewable portfolio standards with fuel cell carve-outs direct procurement volumes toward specific technology classes. Stakeholders must monitor hydrogen purity specifications evolving under ISO 14687 and regional variants, as fuel quality thresholds will determine stack durability warranties and total cost of ownership competitiveness across end-use segments.
Market Dynamics
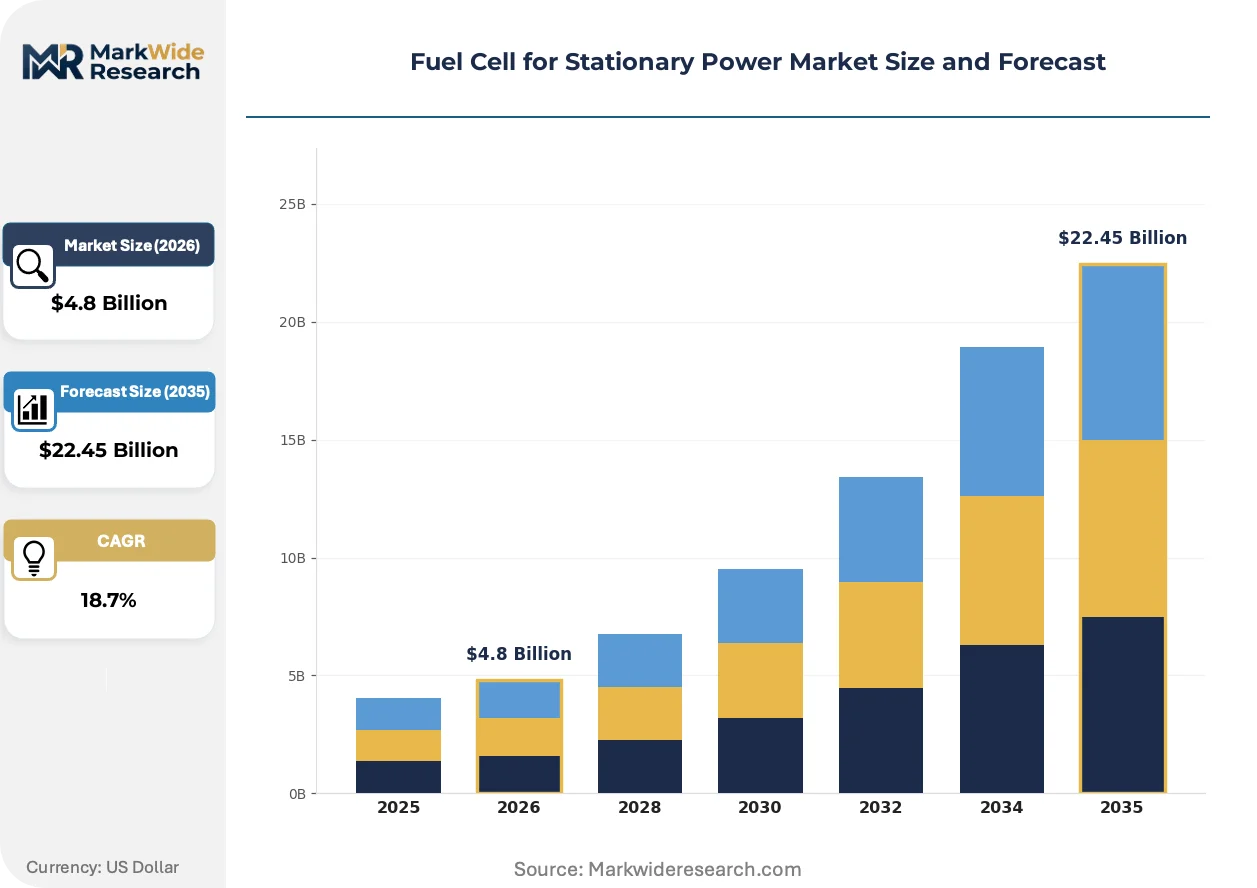
The stationary fuel cell market is undergoing a fundamental restructuring as production tax credits under the US Inflation Reduction Act and Japan's METI hydrogen supply chain targets redirect capital flows toward electrolyzer-integrated manufacturing clusters, compressing project development timelines for utility-scale deployments.
Growth Catalysts
- US IRA Production Tax Credits:The Inflation Reduction Act's hydrogen production and fuel cell manufacturing incentives are unlocking private capital for multi-hundred-megawatt installations. Developers in California and Texas are accelerating site permitting.
- Data Center Baseload Demand:Hyperscale operators are procuring solid oxide and molten carbonate systems for 24/7 carbon-free power. Microsoft and Amazon Web Services have issued tenders specifying fuel cell prime power for new hyperscale campuses.
- South Korea Renewable Portfolio Standards:The country's fuel cell carve-out mandates under RPS regulations are driving utility procurement of carbonate and phosphoric acid systems. KEPCO and regional utilities have established dedicated procurement tracks.
Market Restraints
- Platinum Group Metal Cost Volatility:Membrane electrode assemblies remain exposed to palladium and iridium price swings. Stack manufacturers are locking in multi-year supply contracts with South African and Russian miners to hedge input costs.
- Hydrogen Purity Specification Fragmentation:Diverging ISO 14687 regional variants are forcing duplicate certification testing. Stack warranties vary by fuel quality threshold, complicating cross-border equipment sales.
- Lithium-Ion Battery Substitution:Four-hour duration battery storage is capturing short-duration backup applications. Data center operators are defaulting to batteries for sub-100MW backup unless hydrogen infrastructure exists on-site.
Strategic Opportunities
- Industrial CHP in Germany:The EU Green Deal's emissions trading scheme tightening is creating retrofit demand at chemical and paper mills. Ruhr Valley industrial clusters are evaluating molten carbonate systems for process steam integration.
- Electrolyzer-Fuel Cell Coupling:Power-to-x system integration is opening revenue stacking through grid services and hydrogen resale. Siemens Energy and ITM Power are piloting reversible solid oxide architectures.
- India National Hydrogen Mission:The country's green hydrogen subsidies and PLI scheme for electrolyzer manufacturing are seeding stationary fuel cell demand for fertilizer and refinery applications. Reliance Industries has announced pilot deployments.
Industry Challenges
- Stack Degradation Modeling Talent Gap:Predictive warranty analytics requires electrochemists with 10,000+ hour operational data experience. OEMs are poaching from automotive fuel cell programs, compressing salary benchmarks.
- Interconnection Queue Delays:FERC Order 2023 implementation timelines are stretching grid connection studies to 18-24 months. Project developers are pre-positioning substation engineering resources two years ahead of commercial operation dates.
- Legacy Natural Gas Pipeline Hydrogen Blending:Utility infrastructure compatibility testing for 20% hydrogen blends is creating commissioning bottlenecks. Stationary fuel cell sites require dedicated pipeline lateral construction in most US jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fuel Cell for Stationary Power Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.45 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proton Exchange Membrane, Solid Oxide, Molten Carbonate, Phosphoric Acid Application: Backup Power, Prime Power, Combined Heat & Power, Remote Power Supply Installation Type: Onsite Generation, Offsite Generation, Grid-Connected, Standalone Units End User: Data Centers, Telecommunications, Commercial Buildings, Government Facilities |
| Companies Covered | Cummins, Ballard Power Systems, Bloom Energy, Siemens Energy, Plug Power, FuelCell Energy, SFC Energy, Ceres Power Holding, Doosan Fuel Cell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fuel Cell for Stationary Power Market Shifts & Advancements
Solid oxide fuel cell architecture is converging with electrolyzer manufacturing platforms, enabling reversible operation that shifts equipment utilization curves and compresses the payback period for capital-intensive installations.
Reversible solid oxide technology is converging with grid-scale battery management systems to create hybrid assets capable of arbitrage, frequency regulation, and hydrogen production. Data center operators in California are piloting these configurations to maximize capacity factor. The convergence is compressing standalone fuel cell project economics and forcing equipment suppliers to bundle software controls.
The EU F-Gas Regulation phase-down is tightening fluorinated gas availability for PEM membrane manufacturing. European stack producers are accelerating ceramic membrane R&D partnerships with German ceramics institutes. The regulation is most acute for sub-MW backup systems where fluoropolymer content per kilowatt remains highest.
Hyperscale data center operators are consolidating procurement under master service agreements spanning ten-year fuel supply and O&M bundles. Channel intermediaries are losing share to direct OEM relationships. This consolidation is most visible in Northern Virginia and Frankfurt, where Amazon Web Services and Equinix have issued consolidated tenders covering 500+ MW of capacity.
Fuel Cell for Stationary Power Market Segmentation
Stationary fuel cell procurement cycles vary sharply by segment, with data center operators replacing backup systems every 7-10 years while industrial prime power installations run 15-20 year depreciation schedules. Understanding these replacement rhythms shapes inventory planning and service contract structures for OEMs.
Product Type:
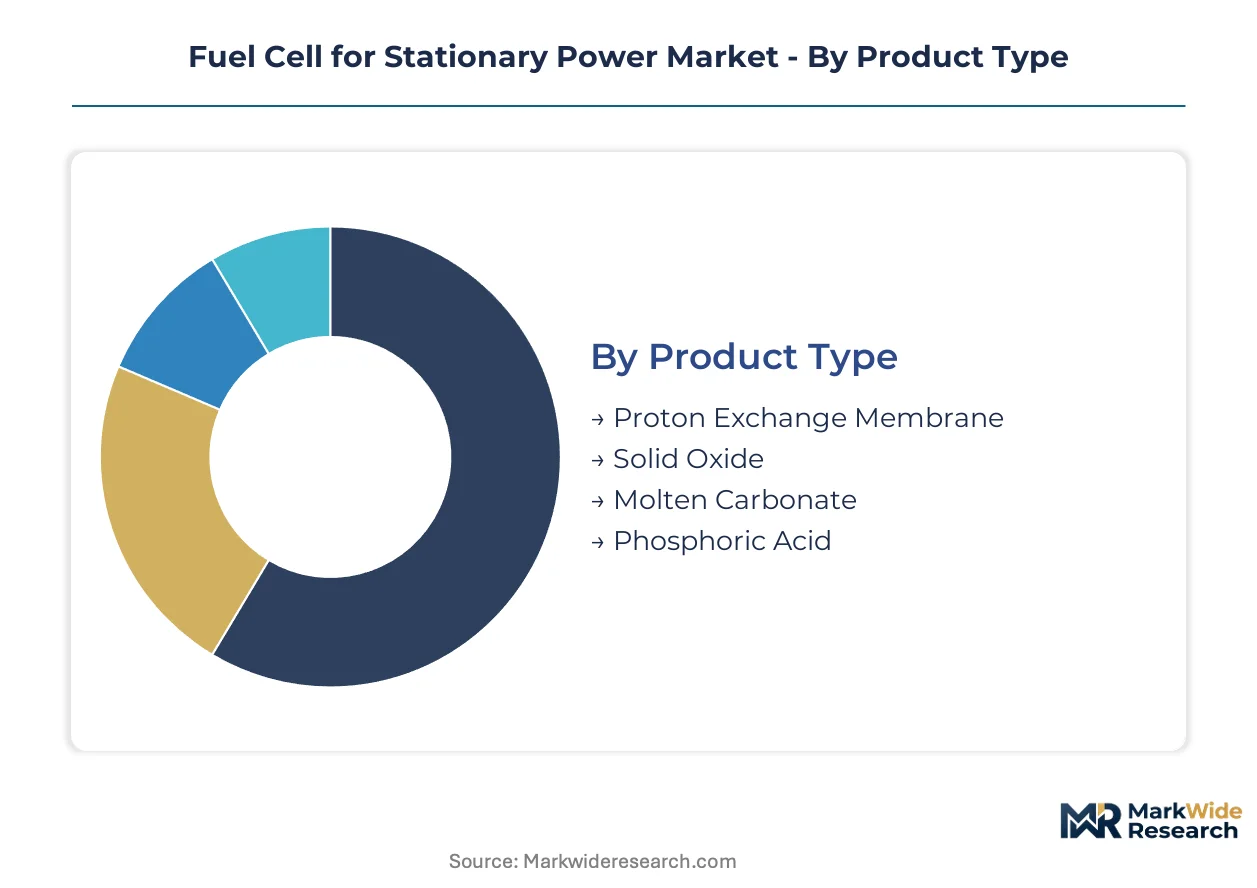
Upgrade cycles diverge dramatically across chemistries, with high-temperature systems demanding complete stack replacement while low-temperature platforms allow modular cell refurbishment.
- Proton Exchange Membrane:These stacks operate at 60-80°C with platinum-loaded membrane electrode assemblies enabling rapid cold-start capability. Data center operators in Northern Virginia and Frankfurt specify PEM for sub-100MW backup where hydrogen purity meets ISO 14687 Grade D thresholds.
- Solid Oxide:Ceramic electrolyte architectures reach 800-1000°C, enabling internal reforming of natural gas without external hydrogen supply. South Korean industrial parks and California utility-scale deployments favor SOFC for baseload prime power where waste heat recovery improves project economics.
- Molten Carbonate:Carbonate salt electrolytes at 650°C suit large-scale CHP with combined cycle efficiency above 80%. FuelCell Energy manufactures these at scale for district heating networks.
- Phosphoric Acid:Mature 200°C technology dominates legacy installations with 40,000+ hour proven durability. Japanese commercial buildings retain PAFC for grid-independent reliability.
Solid oxide sits at the top of the volume ranking, with proton exchange membrane climbing the fastest.
Application:
Cost tier segmentation separates capital-intensive prime power from lower-capex backup configurations, with CHP commanding premium pricing through heat monetization.
- Backup Power:Telecom towers and data centers deploy sub-10MW systems for grid failure protection. Microsoft and AWS tenders specify 48-hour fuel autonomy for hyperscale campuses.
- Prime Power:Continuous operation at 90%+ capacity factor requires multi-MW installations with 20-year service contracts. South Korea's RPS fuel cell carve-out drives utility procurement here.
- Combined Heat & Power:Capturing 80%+ total energy efficiency through process steam or district heating. German chemical mills under EU ETS tightening evaluate molten carbonate retrofit.
- Remote Power Supply:Off-grid mining and military installations use containerized units where diesel logistics prove prohibitive. Alaska and Australian outback operations anchor demand.
Combined heat and power commands the highest margin tier, though backup power is expanding most quickly.
Installation Type:
Customer type determines site configuration, with hyperscale operators preferring captive generation while utilities favor grid-interactive architectures.
- Onsite Generation:Behind-the-meter installations at industrial facilities and data campuses. Bloom Energy deploys these across California industrial parks with 10-year fuel supply bundles.
- Offsite Generation:Centralized fuel cell farms feeding dedicated transmission lines. KEPCO in South Korea operates offsite carbonate facilities under RPS mandates.
- Grid-Connected:FERC interconnection rules govern these installations, with queue delays stretching 18-24 months. Texas ERCOT and California CAISO territories dominate deployment.
- Standalone Units:Islanded operation for critical infrastructure resilience. Government facilities and hospitals specify these for emergency preparedness.
Grid-connected installations lead deployment volumes, with standalone units gaining share fastest in critical infrastructure segments.
End User:
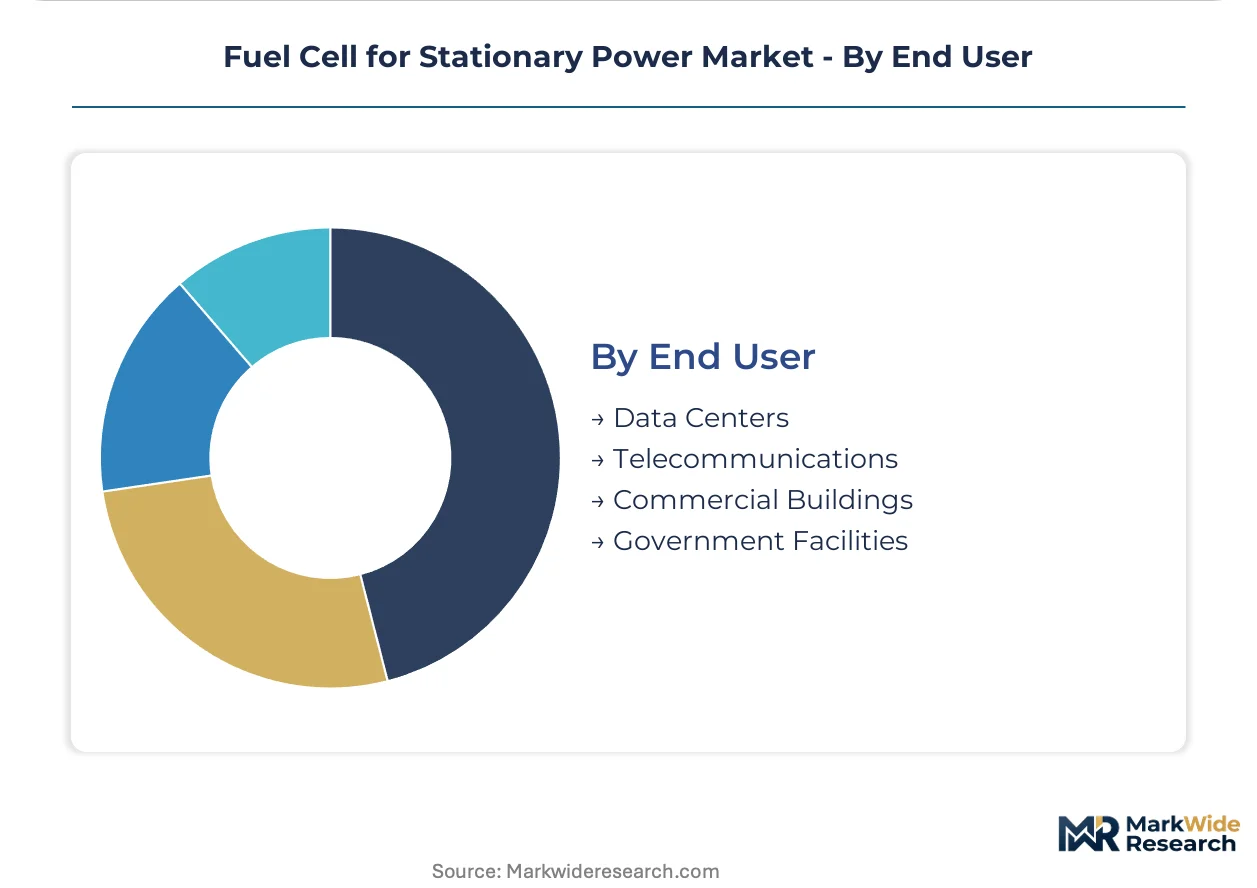
Application maturity varies by sector, with telecommunications representing legacy demand and data centers driving next-generation specifications.
- Data Centers:Hyperscale operators issue consolidated tenders covering 500+ MW with hydrogen supply and O&M bundles. Northern Virginia and Frankfurt clusters anchor procurement.
- Telecommunications:Tower operators maintain legacy phosphoric acid systems with 15-year replacement cycles. Rural network expansion in India seeds incremental demand.
- Commercial Buildings:Hotels and hospitals value quiet operation and emissions profiles. Japan's METI hydrogen roadmap subsidizes urban commercial deployment.
- Government Facilities:Federal resilience mandates and military energy security directives drive procurement. US Department of Defense microgrid programs specify fuel cell integration.
Data centers sit at the top of the volume ranking, with government facilities climbing the fastest under security-of-supply mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korean industrial parks anchor stationary fuel cell deployment volumes, with utility-scale installations concentrated around metropolitan manufacturing belts and data center clusters driving procurement across three continents.
United States
Data center operators in Northern Virginia and Texas are issuing multi-hundred-megawatt tenders for baseload power. The Inflation Reduction Act's production tax credits compress project development timelines for California and Texas developers. Microsoft and Amazon Web Services campuses in Loudoun County specify fuel cell prime power with 48-hour hydrogen autonomy.
South Korea
KEPCO and regional utilities operate dedicated procurement tracks for carbonate and phosphoric acid systems under renewable portfolio standard carve-outs. The country's hydrogen economy roadmap directs capital toward electrolyzer-integrated manufacturing clusters. Doosan Fuel Cell anchors production in the Seoul Capital Area with substantial installed capacity at industrial parks.
Germany
Chemical and paper mills in the Ruhr Valley evaluate molten carbonate retrofit under tightening EU emissions trading scheme obligations. The EU Green Deal's industrial decarbonization targets accelerate site assessments for process steam integration. BASF-operated complexes in Ludwigshafen pilot combined heat and power configurations.
Japan
Commercial buildings in Tokyo and Osaka retain phosphoric acid systems for grid-independent reliability under METI hydrogen supply chain subsidies. The national hydrogen roadmap directs urban deployment toward hotels and hospitals valuing quiet operation. Panasonic and Toshiba legacy installations dominate the Kanto region.
India
Reliance Industries pilots stationary fuel cells for fertilizer and refinery applications under National Hydrogen Mission subsidies. The production-linked incentive scheme for electrolyzer manufacturing seeds captive power demand. Gujarat petrochemical complexes and Maharashtra industrial zones anchor early deployment.
Fuel Cell for Stationary Power Market Competitive Landscape
Global majors compete with regional champions across technology architecture and fuel supply integration, producing a tiered structure where solid oxide specialists, carbonate fabricators, and PEM stack producers occupy distinct competitive positions. Three archetypes dominate: utility-scale prime power integrators, data center backup specialists, and combined heat and power system providers. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with electrolyzer-to-fuel-cell coupling emerging as a portfolio diversification vector.
Among US-based integrators, Bloom Energy and FuelCell Energy exemplify divergent technology bets on solid oxide versus molten carbonate architectures. Siemens Energy anchors European positioning through power-to-x system integration. These three occupy positions spanning prime power, backup, and reversible operation archetypes without overlapping core technology platforms.
| Leading Market Players |
|---|
| Cummins |
| Ballard Power Systems |
| Bloom Energy |
| Siemens Energy |
| Plug Power |
| FuelCell Energy |
| SFC Energy |
| Ceres Power Holding |
| Doosan Fuel Cell |
| Others |
Supply & Pricing Matrix
Performance-grade divergence between ISO 14687-certified stacks and industrial-grade alternatives bifurcates both procurement economics and sourcing networks, with premium-tier suppliers commanding captive hydrogen supply contracts while commodity-tier producers compete on platinum group metal hedging strategies.
Pricing Analysis
Input-cost pass-through from platinum group metal volatility dominates stack pricing, with membrane electrode assembly costs flowing directly into multi-year service contracts. Price differentiation hinges on ISO 14687 certification tier and after-sales warranty duration, with data center operators showing lowest price sensitivity due to resilience premiums while industrial CHP buyers negotiate aggressively on volume scale. Cost compression in the standard tier intensifies as lithium-ion battery substitution pressures four-hour backup applications.
Supply Chain Analysis
Domestic-content mandates under South Korea's renewable portfolio standards and India's PLI scheme for electrolyzer manufacturing are reshaping sourcing patterns toward localized ceramic electrolyte and catalyst production. Supply concentration centers on South Korea, Japan, and Germany for high-temperature stack assemblies, with raw material dependencies spanning South African platinum, Chinese rare earth ceramics, and Japanese precision metallurgy. Single-source vulnerability in membrane electrode assembly catalyst coating creates structural risk. Distribution runs through direct OEM relationships with hyperscale operators, bypassing traditional channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories in stationary fuel cells rest on platinum loading reduction in PEM stacks and reversible solid oxide architectures capturing premium power-to-x positioning.
For Market Incumbents: Deploy backward integration into electrolyzer manufacturing to anchor hydrogen supply economics against emerging pure-play electrolyzer entrants. Lock in multi-year platinum group metal offtake with South African miners to hedge input volatility. Fortify data center direct relationships through ten-year bundled fuel and O&M contracts before master service agreement consolidation accelerates. For New Entrants and Emerging Players: Launch via modular containerized systems targeting remote mining and military microgrid applications where diesel logistics create immediate payback visibility. Penetrate India's National Hydrogen Mission fertilizer and refinery pilots before domestic champions scale. Position around reversible solid oxide architectures to differentiate from established carbonate and phosphoric acid incumbents. For Investors and Strategic Acquirers: Consolidation pressure builds where stack degradation modeling talent scarcity compresses warranty underwriting capacity across mid-tier OEMs. Five-to-ten-year viability favors electrolyzer-coupled system integrators over standalone fuel cell fabricators. Target acquisition profiles center on solid oxide ceramic engineering specialists with 10,000+ hour operational datasets. Monitor FERC interconnection queue clearance rates as inflection signal for utility-scale deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Electrolyzer-Fuel Cell Coupling | Siemens Energy and ITM Power pilots demonstrate revenue stacking through grid services and hydrogen resale arbitrage. |
| Platinum Loading Reduction | Ceramic membrane R&D partnerships with German ceramics institutes address EU F-Gas Regulation fluoropolymer constraints. |
| Direct Hyperscale Procurement | Amazon Web Services and Equinix consolidated tenders in Northern Virginia and Frankfurt displace channel intermediaries. |
| Reversible Solid Oxide Scale-Up | Bloom Energy and Ceres Power architectures enable equipment utilization curve shifting between power generation and hydrogen production. |
| Domestic Content Compliance | Doosan Fuel Cell and KEPCO partnerships satisfy South Korea RPS carve-outs while securing utility procurement tracks. |
Research Methodology
Direct dialogue with fuel cell stack engineering directors, utility procurement officers at KEPCO and regional US utilities, data center infrastructure planners at hyperscale operators, and hydrogen supply specialists grounded qualitative findings. Secondary validation drew from FERC interconnection filings, EPA stationary source emission standard updates, METI hydrogen roadmap progress reports, and IEA hydrogen project databases. Bottom-up installation tracking across South Korean industrial parks, California utility-scale sites, and German Ruhr Valley chemical complexes triangulated against top-down policy incentive modeling.
Bottom-up capacity buildout analysis across chemistry types, application segments, and installation configurations structured the forecast framework throughout the projection horizon. Segmentation dimensions modeled include fuel cell chemistry architecture, prime power versus backup application, grid-connected versus standalone configuration, and end-use sector regulatory exposure. CAGRs derived from policy incentive trajectory analysis, hydrogen infrastructure deployment curves, and data center power demand elasticity estimates. Industry-specific inputs incorporated FERC Order 2023 implementation timelines and ISO 14687 regional variant adoption schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under platinum price spike scenarios, hydrogen purity specification fragmentation, or lithium-ion battery cost breakthroughs. Forecasts reflect assumptions regarding IRA production tax credit continuity, South Korea RPS enforcement rigor, and EU ETS carbon price trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuel Cell Technology
Proton Exchange Membrane Fuel Cell (PEMFC) Market
Fuel Cell Technology
Phosphoric Acid Fuel Cell Market
Fuel Cell Technology
North America Fuel Cell Technology Market
Fuel Cell Technology
China Fuel Cell Market
Fuel Cell Technology
Global Fuel Cell Balance of Plant (BOP) Market
Fuel Cell Technology
Alkaline Fuel Cell Market
Fuel Cell Technology
Helium Recovery Systems Market
Fuel Cell Technology
Hydrogen Fuel Cells Market
Fuel Cell Technology
North America Microbial Fuel Cell Market
Fuel Cell Technology
Hydrogen Recirculation Blower for Fuel Cell Market
Fuel Cell Technology
Fuel Cell Technology Market
Fuel Cell Technology
High-Performance Fuel Cells Market
Fuel Cell Technology
Fuel Cell Stack Market
Fuel Cell Technology
Membrane Electrode Assembly Market
Fuel Cell Technology
Hydrogen Fueling Nozzle Market
Fuel Cell Technology
Fuel Cell Market