
 Netherlands Geothermal Energy Market | 2026-2036
Netherlands Geothermal Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands Geothermal Energy Market Foresight
Modular project bundling is rebalancing buyer choice in the Netherlands geothermal sector, allowing greenhouse consortia to share subsurface risk across multiple operators. EGS Energy leverages its expertise in enhanced geothermal engineering to target deeper reservoirs beneath the North Brabant region. Geothermie Nederland anchors the industry association layer, coordinating drilling standards and knowledge exchange among Dutch developers. Shell extends its legacy in subsurface exploration toward geothermal project origination, competing with specialized pure-plays for concession access.
Netherlands geothermal energy harnesses heat from sedimentary aquifers at depths of 1.5 to 4 kilometers, where formation temperatures reach 60–120°C, primarily to displace natural gas in horticultural and residential heating applications. Binary cycle technology dominates current installed capacity due to compatibility with lower-temperature Dutch reservoirs, while flash steam configurations remain marginal. District heating represents the fastest-growing application segment as municipalities in Groningen and Flevoland retrofit gas networks, though direct use for greenhouse operations still occupies the largest margin pool through long-term offtake contracts.
The Ministry of Economic Affairs and Climate Policy enforces the Mining Act and Geothermal Heat Act, requiring operators to secure exploration permits and submit detailed reservoir management plans before production. The Netherlands Enterprise Agency (RVO) administers SDE++ and Stimulation Scheme for Sustainable Energy Production subsidies, which de-risk capital commitment for deep drilling campaigns. Stakeholders must monitor proposed revisions to the Heat Act that could mandate geothermal priority in zoning for new residential developments.
Market Dynamics
Modular project bundling is rebalancing risk allocation between developers and offtakers across the Netherlands geothermal sector, allowing greenhouse consortia to share subsurface exposure while specialized operators retain operational control.
Growth Catalysts
- SDE++ subsidy de-risking:The Netherlands Enterprise Agency's SDE++ scheme covers the revenue gap between production cost and market reference price, accelerating drilling campaigns in Westland and Limburg.
- District heating retrofit mandates:Municipalities in Groningen and Flevoland are converting legacy gas networks to geothermal-fed systems, creating anchor demand for shallow aquifer projects.
- Binary cycle maturation:Low-temperature organic Rankine cycle technology now operates reliably at 60–90°C reservoir conditions, unlocking marginal fields previously deemed uneconomic.
Market Restraints
- Exploration permit delays:The Mining Act's environmental impact assessment requirements extend pre-drilling timelines by 18–24 months, freezing capital deployment.
- Seismic risk liability:Operators face uncapped damages under Dutch civil code for induced seismicity above 0.5 magnitude, deterring deep EGS development in North Brabant.
- Natural gas price volatility:Benchmark TTF gas pricing below 25 EUR/MWh compresses geothermal heat competitiveness against fossil alternatives.
Strategic Opportunities
- Randstad corridor densification:Unconnected residential zones in Utrecht and Amsterdam North lack district heating infrastructure, representing greenfield connection potential.
- Heat Act revision anticipation:Proposed amendments mandating geothermal priority in new zoning classifications would lock in long-term offtake security for developers.
- Agricultural drying applications:Bulb and seed processors in Flevoland polders present untapped direct-use demand outside greenhouse horticulture.
Industry Challenges
- Reservoir engineering talent scarcity:Subsurface geologists with sedimentary basin experience command premium compensation, constraining project staffing.
- Drilling rig availability:Specialized geothermal rigs suitable for Dutch clay-sand sequences face 12-month booking backlogs, delaying project schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands Geothermal Energy Market |
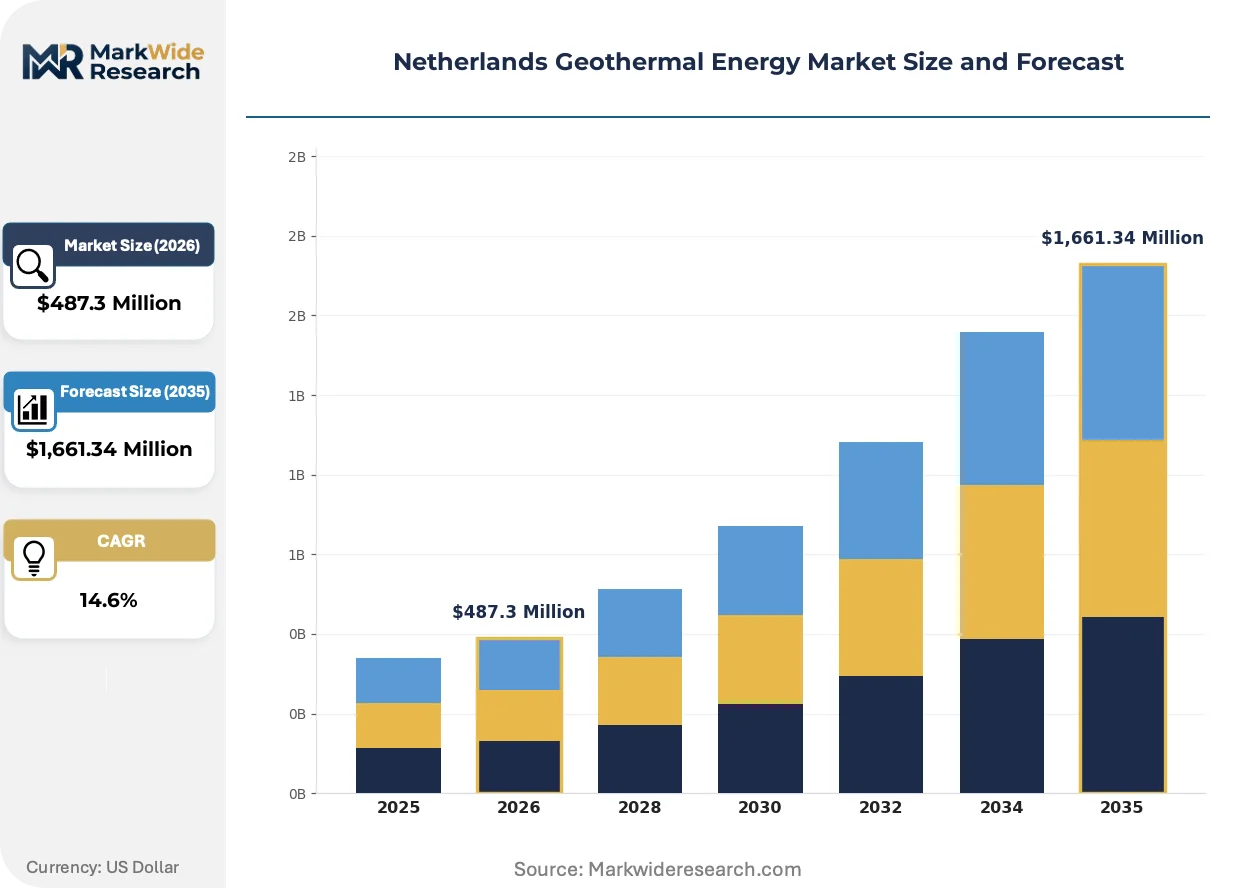
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,661.34 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Electricity Generation, Direct Use, District Heating, Enhanced Geothermal Systems Application: Agricultural Heating, Industrial Process Heat, Power Generation, Residential Heating End User: Utility Companies, Industrial Players, Commercial Establishments, Households Technology: Binary Cycle, Flash Steam, Dry Steam, Hot Dry Rock |
| Companies Covered | EGS Energy, Gaia Energy B.V., Geothermie Nederland, Mitsubishi Heavy Industries Ltd., Turboden S.p.A., Energy Resources Netherlands (EBN), TNO, Toshiba Corporation, Shell, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands Geothermal Energy Market Shifts & Advancements
Technology convergence, regulatory tightening, and buyer behavior evolution are restructuring how geothermal heat reaches end-users across Dutch sedimentary basins.
Closed-loop horizontal well designs are converging with distributed temperature sensing fiber optics to enable real-time reservoir monitoring without production interruption. Westland greenhouse operators are piloting these configurations to optimize thermal drawdown rates. This convergence is compressing the operational learning curve for shallow aquifer projects, reducing the time to stable output from five years to eighteen months.
The Geothermal Heat Act's 2023 amendment tightened reservoir management plan requirements, mandating annual pressure monitoring and mandatory reinjection ratios. Operators now submit detailed subsurface models to the State Supervision of Mines before production authorization. Greenhouse consortia in Limburg are responding by consolidating drilling campaigns to amortize compliance costs across multiple wells.
Long-term heat purchase agreements are displacing spot-market exposure as the dominant procurement mechanism. Municipal utilities in Groningen are signing 20–25 year indexed contracts with developers, transferring price risk to offtakers while securing baseload supply. This shift is most visible in district heating tenders where creditworthiness requirements now favor established greenhouse cooperatives over independent project developers.
Netherlands Geothermal Energy Market Segmentation
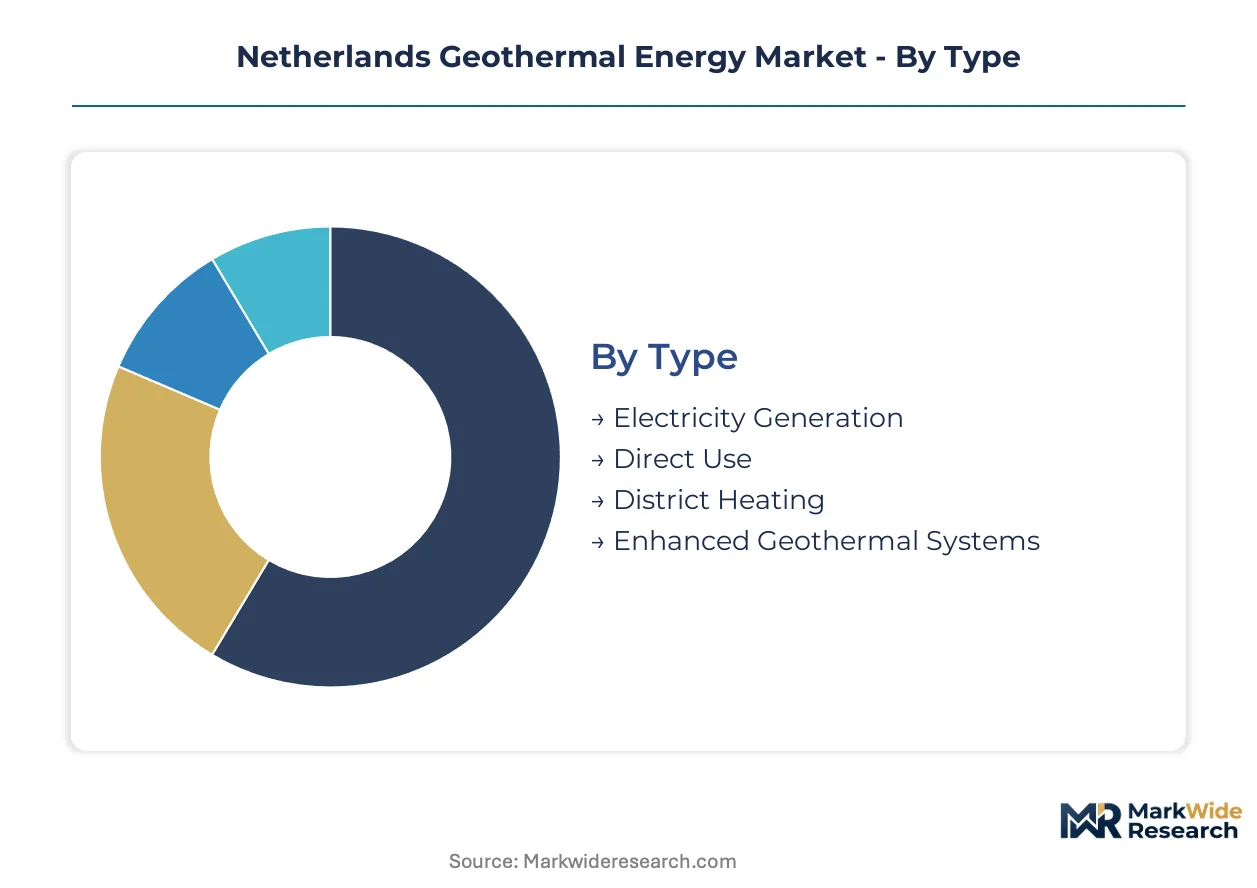
Dutch geothermal deployment fragments across distinct technical configurations and customer archetypes, each carrying unique capital intensity and regulatory exposure. Understanding these boundaries clarifies where SDE++ subsidies deliver maximum leverage and which segments face permit bottlenecks.
Type:
Binary cycle configurations dominate Dutch reservoir conditions, with technology choice directly shaping project economics and subsidy eligibility under RVO guidelines.
- Electricity Generation:Organic Rankine cycle plants convert 60–90°C aquifer fluids to grid power, though low enthalpy limits capacity factors. Westland pilot projects struggle against wholesale price compression when TTF gas benchmarks dip below viability thresholds.
- Direct Use:Greenhouse operators in Limburg deploy open-loop doublets for immediate thermal delivery without conversion losses. Long-term offtake contracts with horticultural cooperatives lock in baseload demand, insulating developers from spot market volatility.
- District Heating:Municipal utilities in Groningen retrofit legacy gas infrastructure with geothermal-fed distribution networks. SDE++ subsidies cover the revenue gap between production cost and consumer tariffs.
- Enhanced Geothermal Systems:Deep drilling targets beneath North Brabant face 18–24 month permit timelines under Mining Act environmental assessments. Induced seismicity liability caps above 0.5 magnitude deter institutional capital commitment.
Mature deployment sits with Direct Use. Newer deployment is concentrated in District Heating.
Application:
End-use thermal requirements dictate well depth, flow rate specifications, and heat exchanger sizing across Dutch sedimentary basins.
- Agricultural Heating:Bulb and seed processors in Flevoland polders present untapped demand outside greenhouse horticulture, requiring 40–60°C supply temperatures.
- Industrial Process Heat:Food manufacturers in Zeeland seek 80–120°C steam for sterilization, pushing developers toward deeper Triassic sandstone targets with higher completion risks.
- Power Generation:Grid-connected plants face merchant price exposure despite SDE++ support, constraining project finance availability.
- Residential Heating:Dense Randstad corridor neighborhoods lack distribution infrastructure, creating greenfield connection opportunities in Utrecht and Amsterdam North.
Residential Heating is gaining share fastest as municipalities convert legacy networks. Agricultural Heating maintains the largest installed base.
End User:
Counterparty creditworthiness and contract duration vary sharply across customer categories, reshaping developer risk allocation.
- Utility Companies:Municipal heat distributors in Groningen sign 20–25 year indexed purchase agreements, transferring price risk to ratepayers while securing baseload offtake.
- Industrial Players:Process heat consumers negotiate shorter tenors tied to production cycles, demanding flexibility clauses for seasonal demand fluctuations.
- Commercial Establishments:Greenhouse cooperatives in Westland pool drilling costs across multiple operators, sharing subsurface risk through modular project bundling structures.
- Households:Individual residential connections remain marginal due to high connection fees and absence of Heat Act mandates for new construction.
Utility Companies anchor established capacity. Commercial Establishments show the steepest expansion trajectory through cooperative structures.
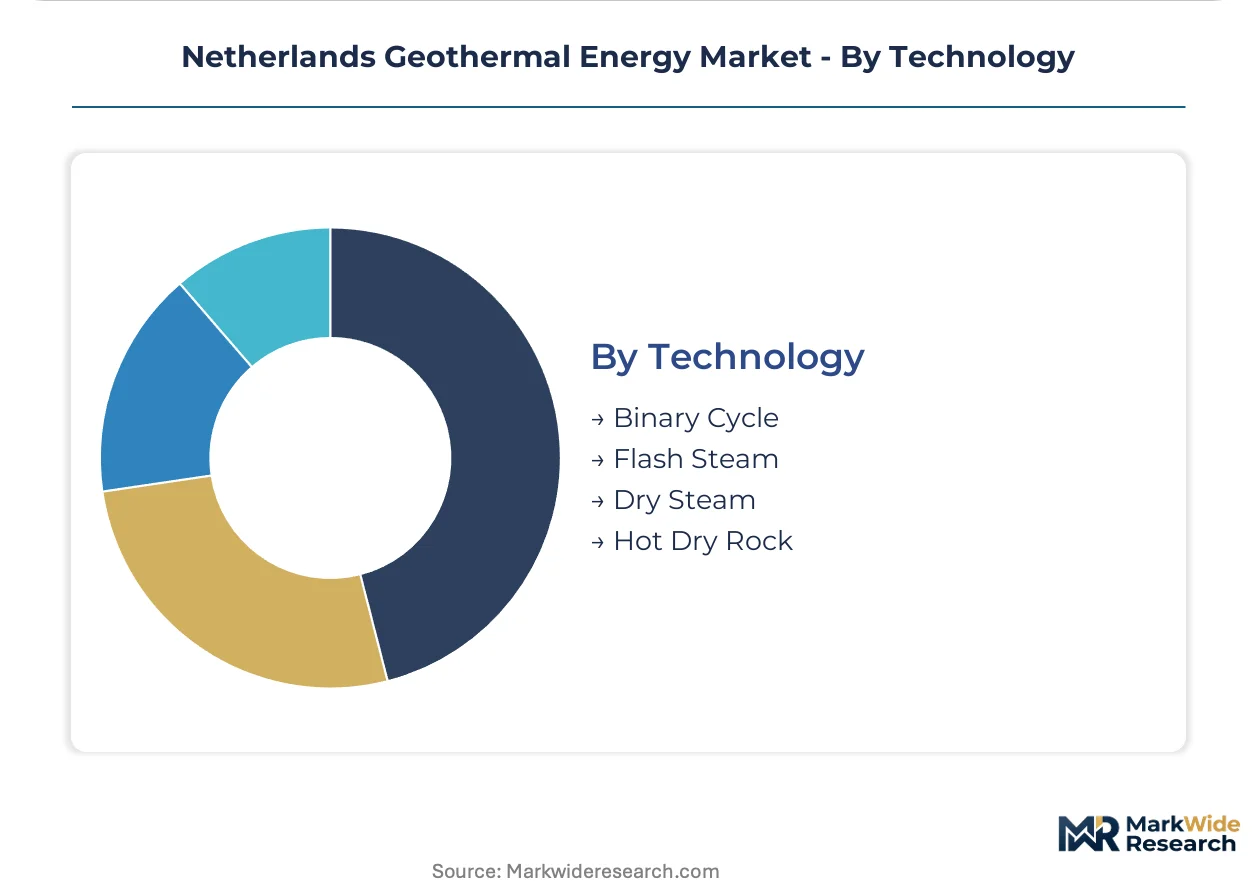
Technology:
Thermodynamic cycle selection locks in equipment sourcing, maintenance protocols, and efficiency curves for multi-decade asset lifespans.
- Binary Cycle:Low-temperature organic Rankine cycle systems operate reliably at 60–90°C, matching Dutch aquifer conditions. Closed-loop horizontal well designs with distributed temperature sensing optimize thermal drawdown rates.
- Flash Steam:Requires reservoir temperatures above 120°C rarely found at drillable depths in the Netherlands, limiting deployment to hypothetical deep EGS targets.
- Dry Steam:Absent from Dutch geology; no volcanic resource base exists within sedimentary basin architecture.
- Hot Dry Rock:Experimental stimulation techniques face uncapped seismic liability under Dutch civil code, blocking commercial development despite technical feasibility.
Binary Cycle commands the installed base. Hot Dry Rock remains pre-commercial pending regulatory liability reform.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in the Westland and Limburg greenhouse belts while consumption spreads across Randstad municipalities retrofitting gas networks. This geographic mismatch drives infrastructure investment toward transmission pipelines connecting rural drilling sites to urban heat demand.
Westland
Greenhouse horticulture operators dominate thermal offtake, requiring 40–80°C baseload supply for year-round crop cultivation. The Ministry of Economic Affairs and Climate Policy administers SDE++ subsidies that de-risk doublet drilling campaigns beneath the glasshouse clusters. Westland hosts the densest concentration of operational geothermal wells, with operators piloting closed-loop horizontal designs to optimize reservoir performance.
Limburg
Modular project bundling allows greenhouse consortia to share subsurface risk across multiple drilling campaigns. The Geothermal Heat Act mandates annual pressure monitoring and reinjection ratios for all production licenses. Venlo and Venray anchor the regional development corridor, where cooperatives consolidate compliance costs across pooled well portfolios.
Groningen
Municipal utilities retrofit legacy gas distribution networks with geothermal-fed district heating infrastructure. The Netherlands Enterprise Agency channels Stimulation Scheme funding toward shallow aquifer projects displacing residential natural gas consumption. The city of Groningen and surrounding municipalities sign 20–25 year indexed heat purchase agreements, transferring price risk to ratepayers.
North Brabant
Deep EGS targets beneath the region face 18–24 month permit timelines under Mining Act environmental assessments. Uncapped seismic liability above 0.5 magnitude deters institutional capital commitment despite favorable Triassic sandstone temperatures. Eindhoven and Tilburg represent prospective demand centers awaiting regulatory clarity on induced seismicity risk allocation.
Flevoland
Agricultural drying applications for bulb and seed processors present untapped direct-use demand outside greenhouse horticulture. The State Supervision of Mines reviews reservoir management plans before authorizing production from polder aquifers. Lelystad and Almere concentrate pilot projects targeting 40–60°C supply temperatures for post-harvest processing operations.
Netherlands Geothermal Energy Market Competitive Landscape
The competitive structure tilts toward specialized geothermal developers with sedimentary basin expertise rather than diversified energy majors. Pure-play operators retain operational control while greenhouse consortia absorb subsurface risk through modular bundling structures. Two archetypes dominate: engineering-technology specialists supplying binary cycle equipment, and project originators securing exploration permits and long-term offtake contracts. Competitive moves center on concession access races and strategic partnerships with municipal utilities for district heating anchor demand.
Within the project development tier, EGS Energy and Gaia Energy B.V. exemplify specialized operators targeting Dutch reservoir conditions. Geothermie Nederland occupies a coordinating position across the industry association layer, anchoring standards development and knowledge exchange. Shell represents the integrated energy major archetype, leveraging legacy subsurface capabilities toward geothermal origination. Among equipment suppliers, Turboden S.p.A. and Mitsubishi Heavy Industries Ltd. sit within the binary cycle technology vector, while TNO provides research-backed technical validation for emerging projects.
| Leading Market Players |
|---|
| EGS Energy |
| Gaia Energy B.V. |
| Geothermie Nederland |
| Mitsubishi Heavy Industries Ltd. |
| Turboden S.p.A. |
| Energy Resources Netherlands (EBN) |
| TNO |
| Toshiba Corporation |
| Shell |
| Others |
Supply & Pricing Matrix
Long-term heat purchase agreements from Groningen municipal utilities are compressing developer margins and forcing equipment suppliers toward standardized binary cycle configurations that sacrifice customization for cost predictability.
Pricing Analysis
Cost-down pressure on district heating tariffs accelerates as SDE++ subsidies phase down and municipalities demand indexed 20–25 year contracts. Pricing stratifies across premium engineering-intensive EGS projects, standard sedimentary aquifer doublets, and economy-scale bundled greenhouse consortia. Certification under the Geothermal Heat Act's reservoir management requirements drives cost differentiation between compliant and non-compliant developers. Greenhouse cooperatives in Westland exhibit highest price sensitivity due to thin horticultural margins, while utility offtakers in Groningen absorb cost pass-through via ratepayer mechanisms.
Supply Chain Analysis
CE-marked binary cycle equipment from Italy, Japan, and Germany gates project finance eligibility under RVO guidelines. Drilling rig fabrication draws from specialized suppliers in the Netherlands, Belgium, and Norway, with completion hardware resting on forged steel from German and Austrian mills. Single-source vulnerability concentrates in high-temperature downhole pumps sourced from limited European foundries. Distribution runs through EPC contractors who bundle engineering, procurement, and construction risk for municipal tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Netherlands geothermal sector sits at a technology-transition inflection where closed-loop horizontal well designs displace conventional open-loop doublets, rewarding operators who master real-time reservoir monitoring.
For Market Incumbents: Deploy backward integration into drilling rig capacity to secure 12-month booking windows that currently freeze project timelines. Incumbent developers must consolidate sedimentary basin expertise through captive geologist teams, as reservoir engineering talent scarcity threatens execution capacity against emerging EGS specialists targeting North Brabant deep targets. For New Entrants and Emerging Players: Agricultural drying cooperatives in Flevoland polders present an underserved buyer archetype outside greenhouse horticulture saturation. New entrants should prioritize 40–60°C direct-use applications for bulb processors, leveraging simplified permitting under existing agricultural zoning rather than competing for contested district heating concessions in Randstad corridors. For Investors and Strategic Acquirers: The window for entry favors pure-play developers with secured exploration permits and signed offtake MOUs over equipment suppliers facing margin compression. Long-term viability hinges on regulatory clarity around induced seismicity liability caps. Investors should monitor State Supervision of Mines permitting velocity as the inflection signal for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Reservoir Monitoring Technology Licensing | Closed-loop fiber optic systems compress operational learning curves for Westland operators. |
| Drilling Rig Joint Venture | Shared rig pools amortize capital burden across Limburg greenhouse consortia. |
| SDE++ Stacking Optimization | Layered subsidy capture improves project IRRs for Groningen district heating retrofits. |
| Seismic Risk Insurance Product | Structured liability coverage unlocks institutional capital for North Brabant EGS targets. |
| Agricultural Offtake Partnership | Flevoland processor alliances diversify revenue beyond greenhouse horticulture dependence. |
Research Methodology
Document review covered State Supervision of Mines production licenses, RVO SDE++ award databases, and Geothermie Nederland technical standards, complemented by interviews with geothermal project developers, drilling contractors, municipal utility planning officers, and greenhouse cooperative energy managers. Secondary sources included Mining Act regulatory filings, district heating infrastructure databases, and sedimentary basin geological surveys. Bottom-up project pipeline aggregation was cross-validated against top-down subsidy allocation analysis.
Historical capacity installation rates were cross-referenced against expert panel inputs from reservoir engineers and EPC contractors. The analytical framework modeled deployment across the analysis window by technology type, application segment, end-user category, and regional grid integration complexity. CAGRs were derived from project-level economics incorporating drilling cost trajectories, subsidy phase-down schedules, and natural gas price sensitivity bands.
Revisions become necessary when Mining Act permit timelines extend beyond modeled assumptions or when TTF gas benchmarks sustain prolonged suppression below geothermal breakeven thresholds. A model refresh is warranted upon material change in Heat Act zoning mandate proposals or SDE++ budget allocation revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geothermal Energy
Global Geothermal Heat Pumps Market
Geothermal Energy
Geothermal Power Generation Market
Geothermal Energy
Enhanced Geothermal System Market
Geothermal Energy
Philippines Geothermal Energy Market
Geothermal Energy
Asia-Pacific Geothermal Energy Market
Geothermal Energy
Sweden Geothermal Energy Market
Geothermal Energy
Geothermal Energy Market
Geothermal Energy
US Geothermal Heat Pump Market
Geothermal Energy
Geothermal Power Market
Geothermal Energy
Indonesia Geothermal Energy Market
Geothermal Energy
Geothermal Power Infrastructure and Components Market
Geothermal Energy
Denmark Geothermal Energy Market
Geothermal Energy
Hungary Geothermal Energy Market
Geothermal Energy
United Kingdom Geothermal Energy Market
Geothermal Energy
Geothermal Power Infrastructure Market