
 Fuel Cells for CHP Application Market | 2026-2036
Fuel Cells for CHP Application Market Size, Share, and Industry Trends Forecast 2026-2036
Fuel Cells for CHP Application Market Analysis
MW-class system reliability is collapsing the historical barrier between backup power and baseload CHP operation. Bloom Energy leverages solid oxide electrolyzer integration to sustain long-term service contracts with data center operators. FuelCell Energy anchors the US utility-scale segment through carbonate fuel cell platforms paired with carbon capture. Doosan Fuel Cell dominates South Korean city gas-linked deployments, while Ballard Power Systems specializes in proton exchange membrane stacks for industrial hydrogen feeds.
Fuel cells for combined heat and power electrochemically convert hydrogen-rich fuels into electricity and usable thermal energy, typically achieving electrical efficiencies of 40-60% and total energy utilization exceeding 80% when heat recovery is optimized. Solid oxide fuel cells operate at 600-1000°C, enabling internal reforming of natural gas and direct integration with industrial process heat loops. The industrial end user segment leads installed capacity due to continuous thermal demand profiles, while hydrogen fuel type installations represent the fastest-expanding category as green hydrogen supply chains mature. Grid-connected installation types concentrate margin pools through capacity payment structures, whereas off-grid configurations occupy niche applications in remote mining and island communities.
The US EPA enforces stationary source emission thresholds that favor low-NOx fuel cell CHP over conventional combustion turbines, while the EU ETS carbon pricing mechanism accelerates payback periods for zero-emission hydrogen configurations. Japan's METI maintains residential fuel cell subsidies through the Ene-Farm program, directly shaping product standardization around 700W-1kW household units. Stakeholders must monitor hydrogen pipeline injection regulations across multiple jurisdictions, as blending ratios will determine whether existing natural gas fuel cell fleets require retrofit or replacement.
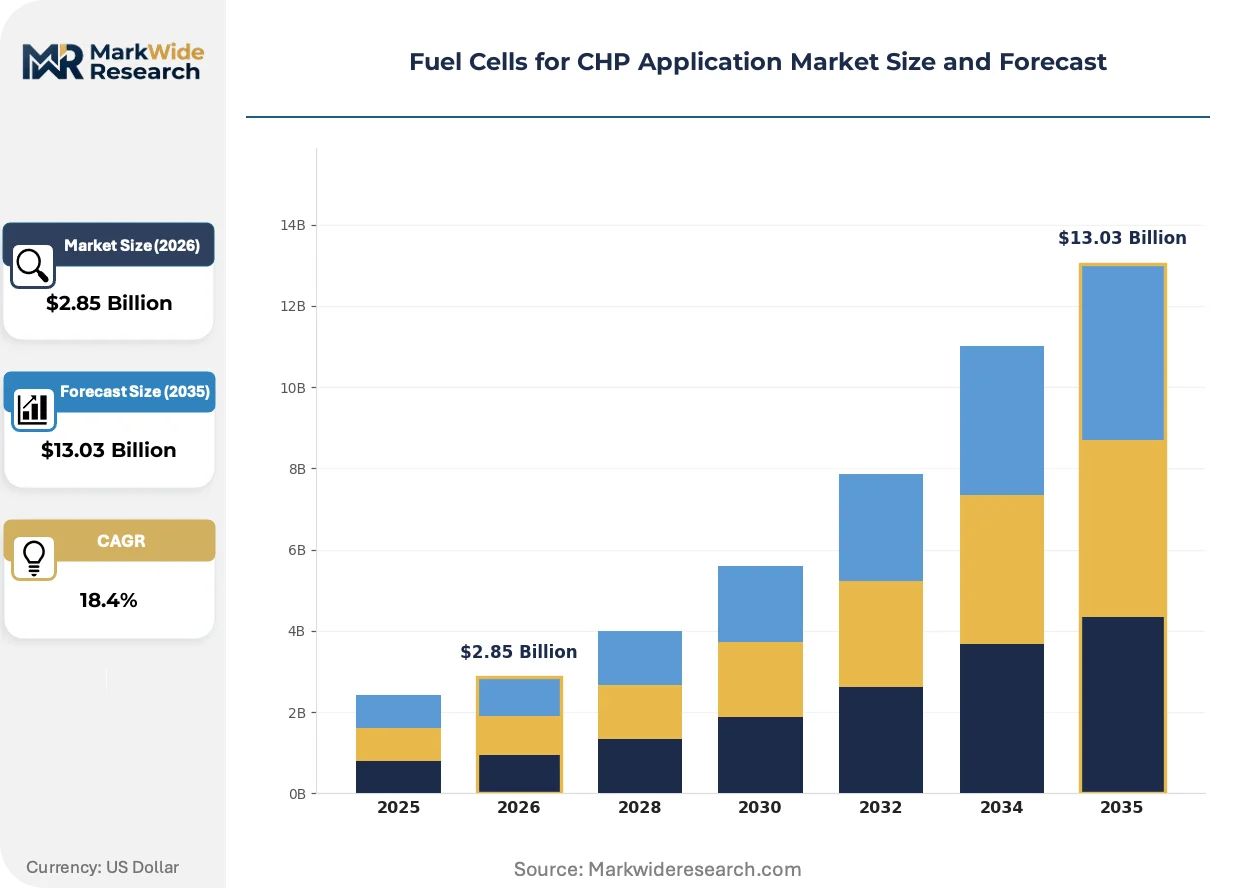
Market Dynamics
The convergence of electrolyzer manufacturing scale-up and hydrogen pipeline injection mandates is collapsing the cost delta between natural gas-reformed and green hydrogen feedstocks for stationary fuel cell systems.
Growth Catalysts
- EU F-Gas Regulation:Tightening containment standards for fluorinated gases in stationary power equipment accelerate SOFC stack replacement cycles and create aftermarket service revenue pools.
- Data center thermal loads:Hyperscale operators in Northern Virginia and Frankfurt are procuring MW-class fuel cell CHP to displace diesel backup generators and capture waste heat for cooling loops.
- Japan METI Ene-Farm subsidies:Residential deployment targets of 5.3 million units by 2030 standardize 700W-1kW PEM product architectures across Asian supply chains.
Market Restraints
- Platinum group metal volatility:PEM stack catalyst costs fluctuate with South African and Russian mining output, compressing gross margins for sub-MW system integrators.
- Electrolyzer supply concentration:European alkaline and PEM electrolyzer manufacturing clusters in Norway and Germany face order backlogs exceeding 24 months, delaying hydrogen fuel cell CHP commissioning timelines.
- Grid interconnection standards:IEEE 1547 and local utility technical requirements create jurisdiction-by-jurisdiction certification burdens that fragment product platform strategies.
Strategic Opportunities
- Industrial process heat integration:SOFC systems operating at 850°C enable direct coupling with cement and steel plant thermal loops, opening captive power markets previously served by combined cycle gas turbines.
- US Inflation Reduction Act hydrogen production tax credits:Section 45V credits reduce levelized hydrogen costs for fuel cell CHP operators below natural gas parity in Texas and Louisiana corridor.
- Remote mining electrification:Off-grid fuel cell deployments in Western Australian and Chilean copper belt operations displace diesel-battery hybrid microgrids with 24/7 baseload thermal output.
Industry Challenges
- High-temperature sealing materials:SOFC stack manufacturers face yield losses exceeding 15% in glass-ceramic seal production, constraining volume ramp and service parts availability.
- Fuel quality certification:Hydrogen fuel cell CHP operators must verify contaminant thresholds for sulfur and halides at ppb levels, requiring capital-intensive gas chromatography infrastructure at point of use.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fuel Cells for CHP Application Market |
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $13.03 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proton Exchange Membrane, Solid Oxide, Alkaline, Molten Carbonate End User: Industrial, Residential, Commercial, Institutional Installation Type: On-Site, Remote, Grid-Connected, Off-Grid Fuel Type: Natural Gas, Biogas, Hydrogen, Others |
| Companies Covered | Ballard Power Systems, Bloom Energy, FuelCell Energy, SFC Energy AG, Viessmann, SOLIDpower, Cummins, AISIN Corporation, Doosan Fuel Cell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fuel Cells for CHP Application Market Emerging Trajectories
Electrochemical system architectures are bifurcating between low-temperature PEM platforms optimized for rapid cycling and high-temperature SOFC configurations engineered for baseload thermal export.
Solid oxide electrolyzer cell (SOEC) technology paired with reversible fuel cell operation is supplanting discrete hydrogen production and power generation assets in industrial microgrid designs. German chemical parks in Ludwigshafen and Leverkusen are piloting reversible systems that absorb grid electricity during negative pricing events and discharge power during peak demand. This operational flexibility compresses payback periods by capturing both electricity arbitrage and thermal energy revenues.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon refrigerants and insulating gases is forcing SOFC manufacturers to redesign thermal management subsystems with CO2-based heat pumps and vacuum panel insulation. Stack OEMs in Denmark and Sweden are accelerating validation programs to maintain CE marking compliance ahead of 2027 containment thresholds. The industrial CHP segment bears the highest retrofit burden, as legacy 250kW-2MW installations face extended downtime for balance-of-plant modifications.
Energy-as-a-service contracting models are displacing direct equipment purchases among commercial real estate owners in Tokyo and Osaka. Kansai Electric Power and Tokyo Gas now structure 15-year heat and power purchase agreements that transfer fuel cell CHP ownership and O&M liability to utility balance sheets. This procurement pattern concentrates financing capability with regional gas distributors and compresses vendor margins to long-term service fee structures rather than equipment markups.
Fuel Cells for CHP Application Market Segmentation
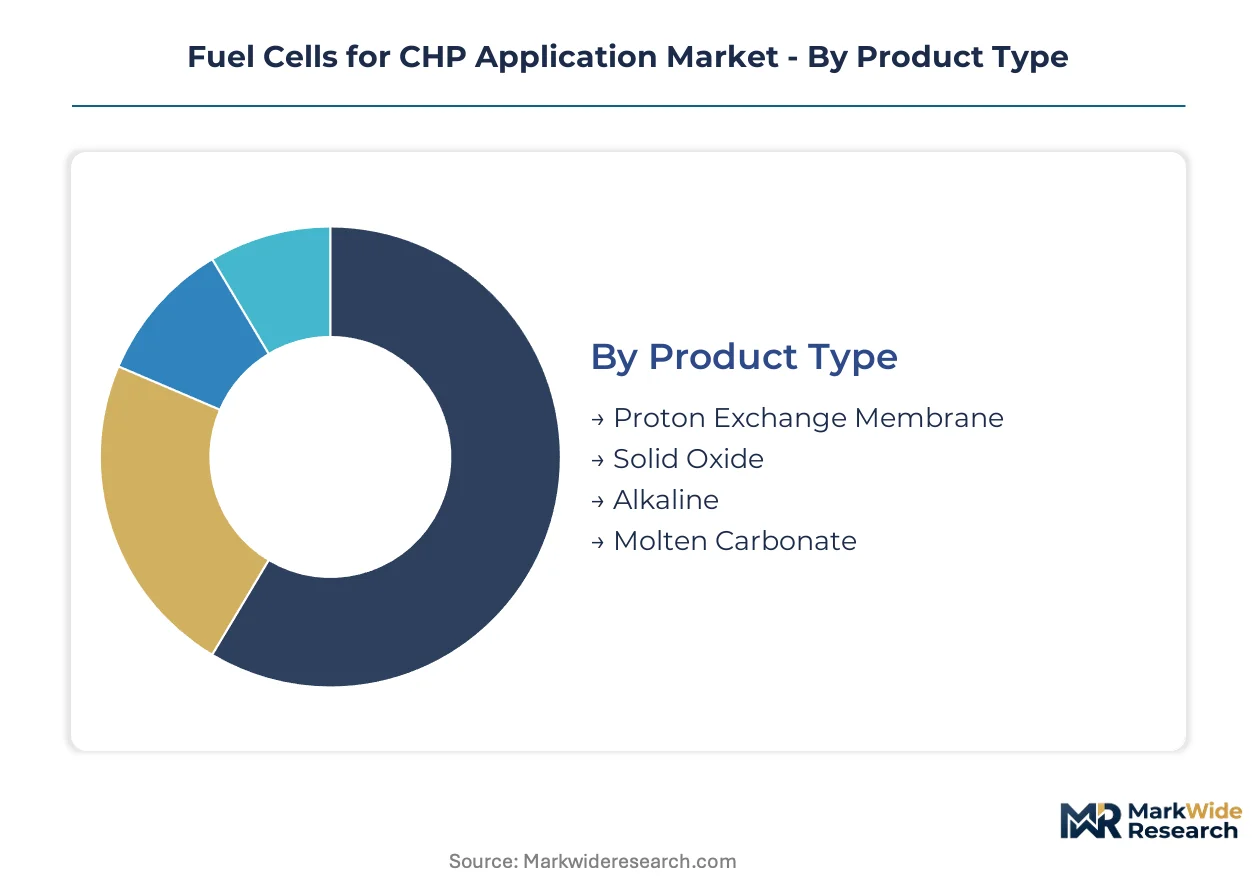
Fuel cell CHP architectures diverge sharply across temperature regimes, thermal duty cycles, and fuel purity requirements. Product selection determines stack materials, reformer complexity, and heat recovery integration, with each configuration carrying distinct regulatory compliance burdens and service revenue profiles.
Product Type:
EU F-Gas Regulation containment standards for fluorinated gases create divergent compliance pathways across temperature classes, with high-temperature platforms facing stack replacement cycles that reshape aftermarket economics.
- Solid Oxide:Ceramic electrolyte systems operate at 600-1000°C, enabling internal methane reforming and direct industrial process heat coupling. German utilities in North Rhine-Westphalia are expanding distributed generation contracts for SOFC installations to meet combined heat and power quotas under the EU Energy Efficiency Directive.
- Proton Exchange Membrane:Polymer electrolyte membranes achieve rapid cold-start capability below 100°C, suited for load-following and backup power transitions. Japan's METI Ene-Farm program standardizes 700W-1kW PEM architectures for residential deployment, concentrating manufacturing scale in Osaka and Nagoya supply clusters.
- Molten Carbonate:Carbonate salt electrolytes at 650°C support large-scale baseload generation with combined cycle integration.
- Alkaline:Liquid potassium hydroxide electrolyte systems offer capital cost advantages for stationary applications with pure hydrogen feeds.
Solid Oxide handles the majority of throughput; Hydrogen is gaining share fastest as green hydrogen supply chains mature.
End User:
Continuous thermal demand profiles determine capacity factor economics, with round-the-clock operations amortizing stack replacement costs across maximum operating hours.
- Industrial:Cement, steel, and chemical plants leverage SOFC exhaust temperatures for direct process heat integration, displacing combined cycle gas turbines in captive power configurations. US EPA stationary source emission thresholds favor low-NOx fuel cell CHP over combustion turbines in Texas and Louisiana industrial corridors.
- Residential:Single-family and multi-unit buildings deploy sub-kW systems for combined electricity and hot water supply. Japanese prefectures subsidize Ene-Farm installations through regional gas distributor financing, concentrating deployment in Tokyo, Osaka, and Aichi prefectures.
- Commercial:Hotels, hospitals, and office complexes utilize mid-scale systems for thermal load matching.
- Institutional:Universities and government facilities procure fuel cells for resilience and sustainability mandates.
Industrial handles the majority of throughput; Residential is expanding most quickly on policy subsidy density.
Installation Type:
Grid interconnection standards fragment product platform strategies, with IEEE 1547 and local utility technical requirements creating jurisdiction-by-jurisdiction certification burdens.
- Grid-Connected:Synchronized systems capture capacity payments and ancillary service revenues through utility dispatch agreements. Northern Virginia and Frankfurt hyperscale data centers procure MW-class fuel cell CHP to displace diesel backup while feeding waste heat into cooling loops.
- Off-Grid:Islanded configurations serve remote mining and island communities without transmission infrastructure. Western Australian and Chilean copper belt operations deploy off-grid fuel cells to displace diesel-battery hybrid microgrids with continuous thermal output.
- On-Site:Behind-the-meter installations prioritize energy cost reduction over grid services.
- Remote:Containerized systems address temporary or mobile power requirements in extraction industries.
Grid-Connected handles the majority of throughput; Off-Grid is climbing the fastest on mining electrification timelines.
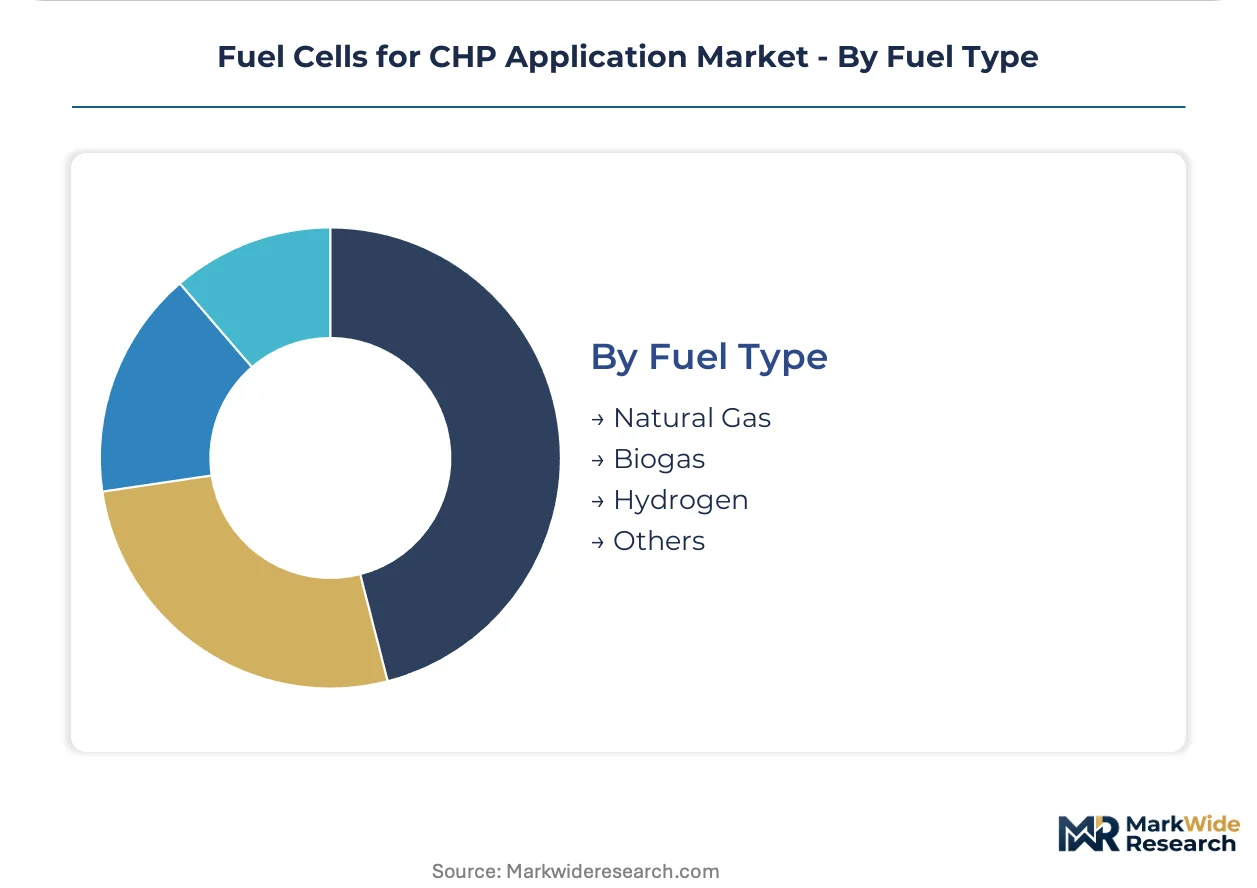
Fuel Type:
Feedstock cost trajectories and carbon intensity regulations determine lifecycle economics, with hydrogen blending ratios dictating retrofit requirements for existing natural gas fuel cell fleets.
- Hydrogen:Zero-emission operation qualifies for EU ETS carbon pricing exemptions and US Inflation Reduction Act Section 45V production tax credits. Texas and Louisiana corridor operators achieve levelized hydrogen costs below natural gas parity through IRA incentives, accelerating electrolyzer-backed fuel cell deployments.
- Natural Gas:Mature infrastructure and established supply chains sustain near-term deployment volumes. German city gas networks in Bavaria and Baden-Württemberg anchor SOFC installations with pipeline delivery certainty under existing distribution contracts.
- Biogas:Anaerobic digester output powers agricultural and wastewater treatment facilities.
- Others:Methanol, ethanol, and synthetic fuel trials address niche maritime and aviation applications.
Natural Gas handles the majority of throughput; Hydrogen is the fastest mover on decarbonization policy alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SOFC stack manufacturing concentrates in Germany, Japan, and South Korea, with electrolyzer integration driving deployment economics across Texas, North Rhine-Westphalia, and Gyeonggi-do industrial corridors.
United States
Data center thermal loads in Northern Virginia and Dallas-Fort Worth anchor MW-class fuel cell procurement. The EPA enforces stationary source emission thresholds that favor low-NOx CHP over combustion turbines. Texas and Louisiana corridor operators leverage IRA Section 45V credits to achieve hydrogen cost parity with natural gas.
Germany
North Rhine-Westphalia utilities expand distributed generation contracts for SOFC installations under EU Energy Efficiency Directive quotas. The EU F-Gas Regulation tightens fluorinated gas containment standards for stationary power equipment. Ludwigshafen and Leverkusen chemical parks pilot reversible SOEC systems for electricity arbitrage and thermal export.
Japan
Residential Ene-Farm deployments concentrate in Tokyo, Osaka, and Aichi prefectures through regional gas distributor financing. METI maintains subsidies targeting 5.3 million units by 2030. Osaka and Nagoya supply clusters standardize 700W-1kW PEM architectures for household CHP.
South Korea
City gas-linked fuel cell deployments anchor demand in Seoul Capital Area and Busan-Ulsan industrial zones. National hydrogen economy roadmaps accelerate electrolyzer-backed CHP commissioning. Doosan Fuel Cell dominates captive power configurations for steel and petrochemical facilities.
Australia
Western Australian and Chilean copper belt operations deploy off-grid fuel cells to displace diesel-battery hybrid microgrids. Remote mining electrification timelines compress payback periods through continuous thermal output. Containerized systems address temporary power requirements in Pilbara extraction corridors.
Fuel Cells for CHP Application Market Vendor Landscape
Concentration sits with integrated stack OEMs and utility-scale project developers. The vendor base spans three tiers: electrolyzer-integrated platform providers, regional gas distributor partnerships, and specialist PEM fabricators for sub-MW residential segments. Strategic moves cluster around long-term service contracting and reversible cell technology licensing.
Among North American platform providers, Bloom Energy and FuelCell Energy occupy positions spanning data center and utility-scale verticals. Ballard Power Systems exemplifies the PEM specialist archetype for industrial hydrogen feed applications. These three anchors represent divergent technology bets across temperature regimes and thermal duty cycles.
| Leading Market Players |
|---|
| Ballard Power Systems |
| Bloom Energy |
| FuelCell Energy |
| SFC Energy AG |
| Viessmann |
| SOLIDpower |
| Cummins |
| AISIN Corporation |
| Doosan Fuel Cell |
| Others |
Supply Flow & Price Mechanics
Green hydrogen electrolyzer capacity additions in Texas and Louisiana are displacing natural gas reformer economics, simultaneously shifting procurement geography toward electrolyzer manufacturing clusters and compressing feedstock cost premiums for stationary fuel cell operators. This substitution dynamic reconfigures both upstream supply contracts and downstream pricing power across the CHP value chain.
Pricing Analysis
The EU F-Gas Regulation dictates the pricing tier structure across SOFC stack replacement cycles and aftermarket service bundles. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked high-temperature systems from legacy installations facing retrofit compliance costs from uncertified balance-of-plant components. Cost compression in standard-tier PEM residential units is intensifying because platinum group metal volatility compresses integrator margins. Industrial end users exhibit lowest price sensitivity due to continuous thermal demand amortization, while commercial real estate owners in Japanese urban markets demonstrate highest sensitivity under energy-as-a-service contracting.
Supply Chain Analysis
Germany and Japan anchor SOFC stack ceramic electrolyte production, while South Korea concentrates carbonate fuel cell platform manufacturing. Raw material dependencies draw from zirconium oxide feedstocks for ceramic components, platinum group metals for PEM catalyst layers, and glass-ceramic precursors for high-temperature sealing. Single-source vulnerability sits with South African and Russian mining output for platinum group metals. Distribution runs through regional gas distributor partnerships in developed markets and EPC contractor networks for industrial project deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fuel cell CHP sits at an early-cycle expansion story justified by accelerating data center thermal load procurement and hydrogen pipeline injection mandates collapsing green hydrogen cost deltas against natural gas parity.
For Market Incumbents: Compound service revenue streams through long-term heat and power purchase agreement structures that transfer O&M liability to utility balance sheets. Defend against PEM stack cost volatility by securing platinum group metal offtake contracts with South African mining consortiums. Prioritize backward integration into electrolyzer manufacturing partnerships to anchor hydrogen feedstock supply certainty for Texas and Louisiana corridor deployments. For New Entrants and Emerging Players: Differentiate on reversible SOEC system architectures that capture electricity arbitrage revenues in German chemical parks during negative pricing events. Target off-grid mining electrification in Western Australian Pilbara corridors where diesel displacement timelines compress payback periods. Pursue containerized system deployment models for temporary extraction industry power requirements with minimal grid interconnection certification burdens. For Investors and Strategic Acquirers: The market sits at a technology consolidation phase that favors integrated stack OEMs with electrolyzer platform capabilities. Long-term viability hinges on hydrogen pipeline injection regulatory alignment across multiple jurisdictions determining retrofit requirements for existing natural gas fuel cell fleets. Acquisition archetypes center on SOFC stack manufacturers with validated glass-ceramic seal production yields above 85%. The signal to watch is hydrogen blending ratio announcements from German and Japanese network operators as inflection indicators for fleet replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Reversible SOEC System Deployment | German chemical parks in Ludwigshafen capture electricity arbitrage and thermal export revenues simultaneously. |
| Long-term Service Contracting | Kansai Electric Power structures 15-year heat and power purchase agreements transferring CHP ownership to utility balance sheets. |
| Electrolyzer Manufacturing Partnership | Texas and Louisiana corridor operators achieve hydrogen cost parity through IRA Section 45V credit stacking. |
| CE Marking Compliance Investment | Danish and Swedish stack OEMs accelerate validation programs ahead of 2027 EU F-Gas containment thresholds. |
| Platinum Group Metal Supply Security | South African mining offtake contracts stabilize PEM stack catalyst costs against geopolitical supply disruptions. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with utility planning officers, data center facility directors, industrial plant engineers, and regional gas distributor procurement leads. Secondary validation drew from EIA generation data, IEA hydrogen technology reports, FERC interconnection filings, and EU Energy Efficiency Directive implementation tracking. Bottom-up capacity installation tracking across German distributed generation contracts and Japanese Ene-Farm deployment registries was triangulated against top-down market sizing from electrolyzer manufacturing order backlogs.
Across the analysis window, volume and value outputs were modeled through segmentation by fuel cell temperature regime, installation scale tier, grid interconnection type, and regional regulatory framework cluster. CAGRs were derived from electrolyzer manufacturing capacity ramp schedules, hydrogen pipeline injection mandate timelines, and data center power procurement disclosure patterns. Forecast inputs incorporated SOFC stack replacement cycle economics under EU F-Gas phasedown schedules and residential subsidy density trajectories from METI program extensions.
Material uncertainties — hydrogen blending ratio regulatory decisions, platinum group metal supply disruptions, and grid interconnection standard fragmentation — sit outside the modeled envelope. Forecasts reflect assumptions regarding electrolyzer manufacturing yield improvements and carbon pricing mechanism continuity. Recalibration cycles align with material shifts in hydrogen infrastructure deployment timelines and F-Gas Regulation enforcement patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuel Cell Technology
Fuel Cell Technology Market
Fuel Cell Technology
Germany Fuel Cell Market
Fuel Cell Technology
Phosphoric Acid Fuel Cell Market
Fuel Cell Technology
Hydrogen Fuel Cell Drone Market
Fuel Cell Technology
Global Planar Solid Oxide Fuel Cell Market
Fuel Cell Technology
Fuel Cell Market
Fuel Cell Technology
Microbial Fuel Cell Market
Fuel Cell Technology
Aircraft Fuel Cell Market
Fuel Cell Technology
Fuel Vending Machines Market
Fuel Cell Technology
High-Performance Fuel Cells Market
Fuel Cell Technology
Fuel Cell Stack Market
Fuel Cell Technology
Japan Fuel Cell Market
Fuel Cell Technology
North America Fuel Cell Technology Market
Fuel Cell Technology
China Fuel Cell Market
Fuel Cell Technology
Regenerative Fuel Cell (RFC) Technologies Market
Fuel Cell Technology
Global Fuel Cell Balance of Plant (BOP) Market