
 Aircraft Fuel Cell Market | 2026-2036
Aircraft Fuel Cell Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Fuel Cell Market Analysis
Multi-source hydrogen supply contracting is pivoting from aviation's traditional single-fuel dependency toward diversified procurement. Plug Power leverages its electrolyzer manufacturing scale to anchor early airport hydrogen hub deployments. Ballard Power Systems sustains technology leadership in heavy-duty fuel cell stacks adapted for aviation powertrains. Airbus SE dominates integrated airframe-electrification roadmaps through its ZEROe concept program.
Aircraft fuel cells electrochemically convert hydrogen into electricity through proton exchange membranes or solid oxide architectures, generating water as the sole byproduct while delivering continuous power outputs from below 100 kW to above 500 kW for propulsion and auxiliary loads. Proton exchange membrane systems occupy the near-term commercialization path due to favorable power density and cold-start characteristics for regional aviation. Solid oxide fuel cells compete for longer-haul applications where higher operating temperatures yield superior electrical efficiency. The 100 kW–250 kW power rating bracket leads current demonstration activity, while above 500 kW systems represent the fastest-growing development priority as manufacturers target narrowbody replacement markets.
FAA certification standards for hydrogen propulsion systems and EPA greenhouse gas regulations for aviation are reshaping product development timelines and airworthiness requirements for fuel cell integrators. The EU Green Deal's ReFuelEU Aviation mandate and EASA's dedicated hydrogen propulsion certification pathway are accelerating European market access conditions for approved powertrain configurations. Stakeholders must monitor hydrogen infrastructure buildout pace against aircraft certification schedules to align capital deployment with operational readiness thresholds.
Market Dynamics
The Aircraft Fuel Cell Market pivots on hydrogen infrastructure buildout velocity lagging behind airframe electrification roadmaps, creating a deployment gap that concentrates capital flows toward certification-ready powertrain integrators with secured fuel supply contracts.
Growth Catalysts
- EU Green Deal ReFuelEU Aviation:Binding sustainable aviation fuel quotas and hydrogen adoption timelines force fleet operators to accelerate zero-emission propulsion procurement for regional route networks.
- Proton exchange membrane advancement:Improved power density and cold-start performance below freezing thresholds unlock year-round operations in Nordic and alpine airport environments.
- German cluster concentration:Stuttgart and Hamburg hydrogen hub investments coordinate electrolyzer capacity with adjacent aerospace manufacturing corridors.
Market Restraints
- Platinum group metal cost volatility:Fuel cell catalyst dependency on palladium and iridium exposes stack manufacturers to raw material price swings from South African and Russian supply corridors.
- FAA hydrogen propulsion certification backlog:Absence of finalized airworthiness standards for pressurized hydrogen storage extends type certification timelines beyond conventional propulsion cycles.
- Liquid hydrogen handling infrastructure scarcity:Airport ground support equipment for cryogenic fueling remains limited to test sites in Bavaria and California.
Strategic Opportunities
- Japan METI hydrogen aircraft roadmap:National funding for 2030 commercial service targets creates procurement pathways for fuel cell systems certified under JCAB parallel validation.
- Solid oxide fuel cell hybridization:Integration with turbine auxiliary power units offers efficiency gains for long-haul cargo applications requiring sustained high-kilowatt output.
- Airport hydrogen hub concession models:Long-term offtake agreements between airlines and electrolyzer operators reshape capital deployment toward integrated fuel-production-propulsion ecosystems.
Industry Challenges
- Cryogenic systems engineering talent scarcity:Specialized expertise in minus 253 degrees Celsius liquid hydrogen containment and transfer limits workforce scalability for production ramp.
- Dual certification complexity:Simultaneous EASA and FAA validation requirements for hydrogen storage tanks and fuel cell stacks fragment engineering resources across divergent documentation standards.
- Legacy avionics integration friction:Power management system incompatibility between fuel cell output characteristics and conventional electrical bus architectures necessitates custom inverter development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Fuel Cell Market |
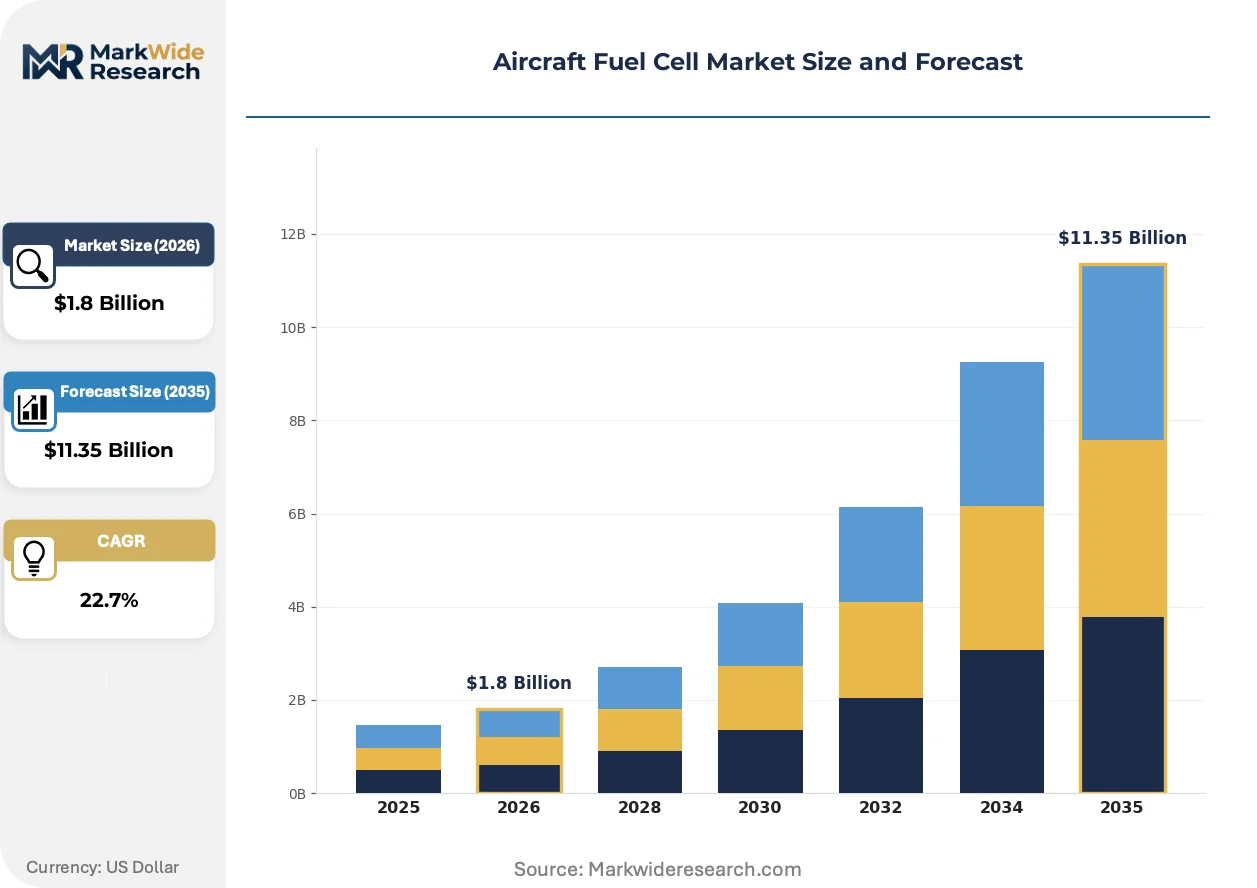
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $11.35 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proton Exchange Membrane, Solid Oxide Fuel Cell, Direct Methanol Fuel Cell, Alkaline Fuel Cell End User: Commercial Aviation, Military Aviation, Business Jets, Unmanned Aerial Vehicles Power Rating: Below 100 kW, 100 kW–250 kW, 250 kW–500 kW, Above 500 kW Technology: Hybrid Systems, Fuel Processing, Renewable Hydrogen, Energy Management |
| Companies Covered | Plug Power, Linde, Ballard Power Systems, PowerCell Sweden AB, Airbus SE, ZeroAvia Inc., Intelligent Energy Limited, Doosan Mobility Innovation, Air Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Fuel Cell Market Emerging Trajectories
Technology convergence between aerospace propulsion and heavy-duty transport fuel cell architectures is compressing development cycles while regulatory pressure forces premature standardization commitments from integrators.
Stack architecture is modularizing across the 100 kW to 500 kW range, enabling regional aircraft manufacturers to configure propulsion systems through standardized cell block assembly rather than custom engineering. Tier-one suppliers in Germany and Japan are adopting platform approaches that reduce non-recurring engineering costs per airframe program. This modularity is compressing time-to-certification for derivative aircraft variants targeting different passenger capacities.
REACH chemical substance restrictions and the EU F-Gas Regulation are tightening material compliance requirements for fuel cell membrane manufacturing and thermal management fluids used in aviation powertrains. Stack producers must reformulate proton exchange membranes to eliminate perfluorinated compounds while maintaining ionic conductivity specifications. European integrators face the steepest reformulation timelines, with EASA mandating full substance disclosure for type certification submissions.
Airline procurement departments are consolidating hydrogen supply contracting under fleet-level master service agreements rather than airport-specific fuel purchases, transferring price volatility risk to electrolyzer operators and infrastructure developers. This concentration of buying power favors carriers with multi-hub networks in Germany, France, and the Netherlands. The shift is most visible among flag carriers restructuring regional subsidiary fleets around zero-emission mandates.
Aircraft Fuel Cell Market Segmentation
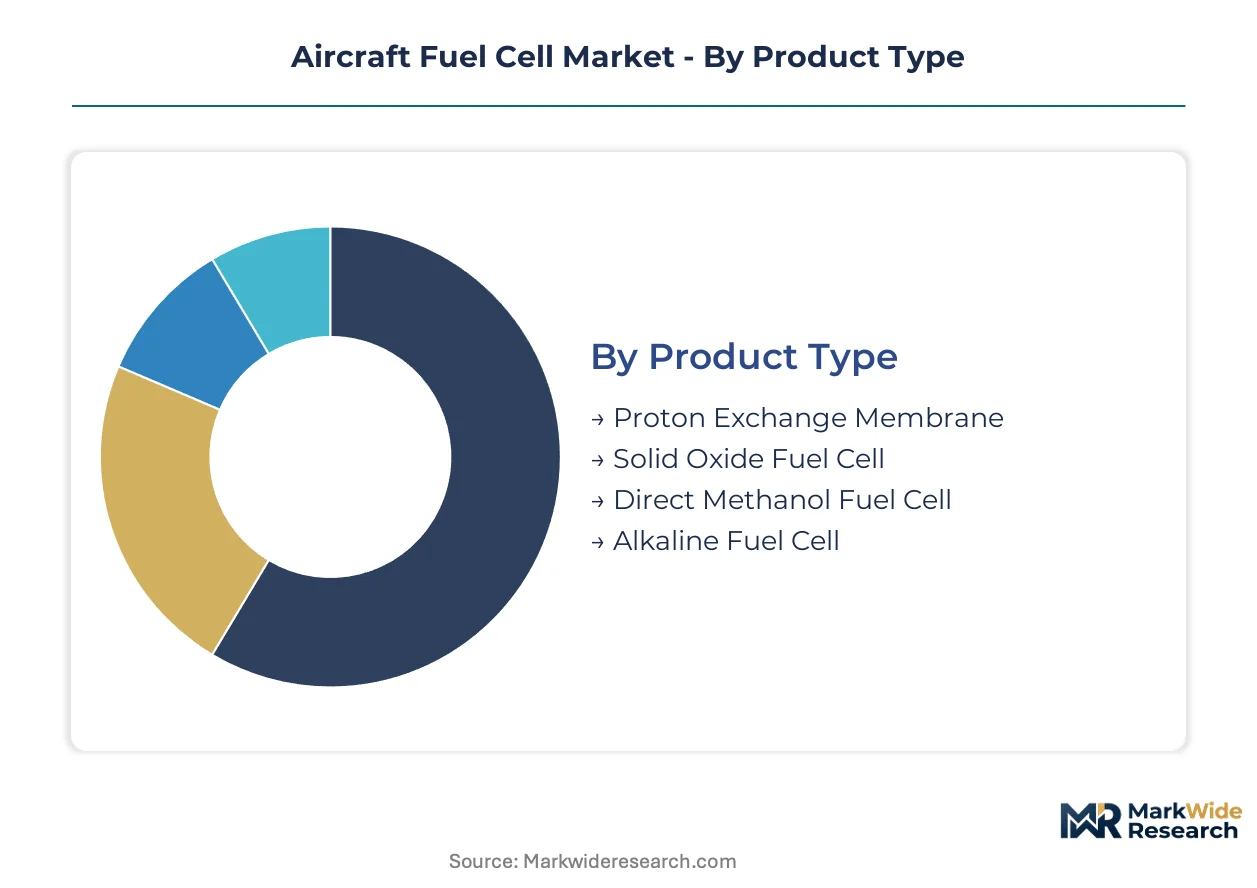
Aircraft fuel cell segmentation tracks divergent certification timelines across propulsion architectures. Procurement patterns cluster around power ratings that match regional route economics. Technology choices reflect hydrogen infrastructure maturity at specific airport hubs.
Product Type:
Buyers prioritize power density against thermal management tradeoffs when selecting stack chemistry for airframe integration.
- Proton Exchange Membrane:Polymer electrolyte architecture operates below 100°C with rapid cold-start capability suited to Nordic airport rotations. Stuttgart and Hamburg demonstration programs anchor near-term procurement volumes for regional turboprop replacements.
- Solid Oxide Fuel Cell:Ceramic electrolyte systems reach 600-1000°C operating temperatures, delivering superior electrical efficiency for sustained cruise phases. Long-haul cargo operators in Germany evaluate hybrid configurations combining SOFC auxiliary power with turbine propulsion.
- Direct Methanol Fuel Cell:Liquid fuel compatibility eliminates cryogenic handling infrastructure for unmanned platforms. Military drone programs in Bavaria test methanol reforming for extended endurance missions.
- Alkaline Fuel Cell:Aqueous potassium hydroxide electrolyte offers cost advantages for ground support equipment applications. Airport hydrogen hub developers in California deploy alkaline systems for apron vehicle electrification.
Volume sits with Proton Exchange Membrane; growth tilts toward Solid Oxide Fuel Cell.
End User:
Regulatory pressure intensity varies sharply across operator categories, reshaping procurement urgency.
- Commercial Aviation:EU Green Deal ReFuelEU mandates force fleet operators toward zero-emission regional aircraft. Lufthansa and Air France-KLM restructuring programs concentrate orders on 19-50 seat fuel cell platforms.
- Military Aviation:Stealth and forward-deployed logistics drive interest in reduced thermal and acoustic signatures. German defense procurement evaluates fuel cell propulsion for tactical airlift modernization.
- Business Jets:Range anxiety and FBO hydrogen availability constrain adoption despite corporate sustainability commitments. Munich and Geneva airport infrastructure investments target this segment for early premium positioning.
- Unmanned Aerial Vehicles:Endurance requirements favor fuel cell energy density against battery alternatives. ZeroAvia and DLR flight-test programs in Germany validate hydrogen powertrain integration for cargo drones.
Procurement concentrates in Commercial Aviation; technology maturation is expanding most quickly in Unmanned Aerial Vehicles.
Power Rating:
Airframe size and route length determine kilowatt specifications, with certification complexity rising nonlinearly above 250 kW.
- Below 100 kW:Compact stacks power auxiliary loads and ground support equipment. German airport hydrogen hubs deploy sub-100 kW systems for electric tow tractors and baggage loaders.
- 100 kW–250 kW:Twin-motor regional aircraft configurations dominate current flight-test activity. Airbus ZEROe concept and ZeroAvia ZA-600 programs in Germany and California target this bracket for 19-seat airliner certification.
- 250 kW–500 kW:Single-aisle replacement markets drive stack modularization efforts. EASA hydrogen propulsion certification pathway accelerates engineering investment for 50-100 seat platforms.
- Above 500 kW:Narrowbody-equivalent output requires parallel stack arrays and advanced thermal management. Boeing and Airbus roadmaps project commercial readiness beyond current analysis window.
Certification activity clusters at 100 kW–250 kW; capital deployment is climbing the fastest toward Above 500 kW.
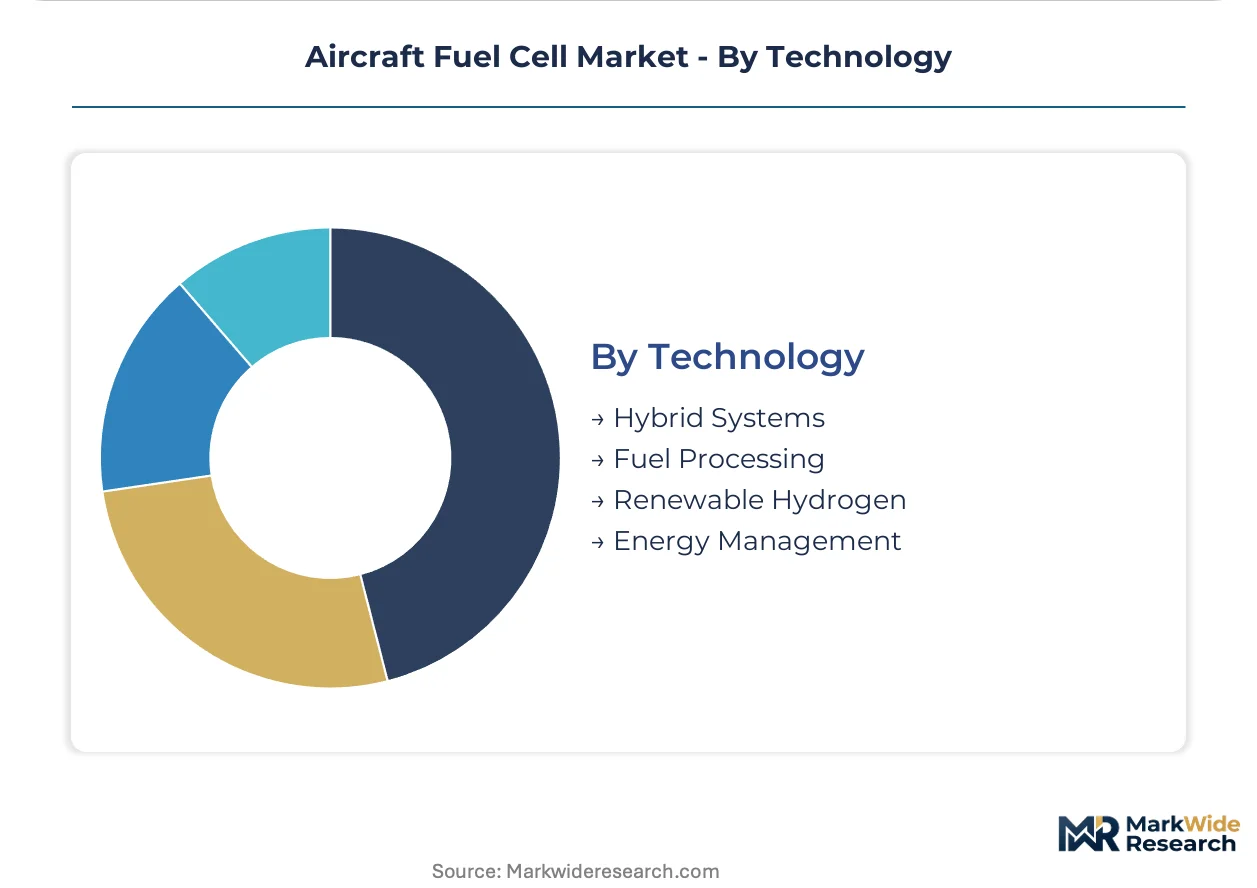
Technology:
System integration complexity separates component suppliers from full propulsion integrators.
- Hybrid Systems:Fuel cell-battery combinations optimize power density for takeoff climb segments. Dornier 228 retrofits in Germany demonstrate turbine-fuel cell hybrid architectures.
- Fuel Processing:Onboard reforming and purification systems enable alternative hydrogen carriers. Liquid organic hydrogen carrier research at German aerospace institutes addresses storage density constraints.
- Renewable Hydrogen:Green hydrogen certification requirements shape supply contracting terms. EU Green Deal delegated acts define renewable origin standards for aviation fuel claims.
- Energy Management:Power distribution and thermal regulation software coordinates multi-source propulsion. Custom inverter development addresses legacy avionics bus incompatibility.
Revenue concentrates in Hybrid Systems; differentiation is gaining share fastest in Energy Management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platinum group metal deposits in South Africa and Russia anchor catalyst supply chains for fuel cell stack manufacturing. German industrial clusters coordinate electrolyzer capacity with aerospace manufacturing corridors. Japanese and US hydrogen hub investments are accelerating parallel certification pathways for commercial aviation deployment.
Germany
Airbus ZEROe demonstrator programs and ZeroAvia flight testing drive stack procurement volumes. EU Green Deal ReFuelEU Aviation mandates binding hydrogen adoption timelines for fleet operators. Stuttgart and Hamburg hydrogen hubs align electrolyzer capacity with adjacent aerospace manufacturing in Bavaria and Baden-Württemberg.
United States
FAA hydrogen propulsion certification development and California airport hub investments concentrate early deployment. EPA greenhouse gas regulations for aviation tighten emission standards for regional fleet operators. ZeroAvia's Hollister test site and Plug Power's Rochester electrolyzer manufacturing anchor West Coast and Northeast corridor development.
Japan
METI hydrogen aircraft roadmap targets 2030 commercial service deadlines for domestic route networks. JCAB parallel validation protocols create certification pathways for fuel cell systems under bilateral agreements with EASA. Nagoya aerospace manufacturing clusters integrate heavy-duty transport fuel cell architectures into aviation powertrain development.
United Kingdom
Jet Zero Council funding accelerates hydrogen propulsion demonstration programs for regional aircraft. UK Research and Innovation clean aviation mandates prioritize fuel cell-battery hybrid architectures. ZeroAvia's Kemble and Cranfield test facilities validate 19-seat platform certification timelines under CAA-EASA coordination.
France
Airbus SE headquarters in Toulouse anchors integrated airframe-electrification roadmaps through ZEROe concept maturation. ANSM substance disclosure requirements for EASA type certification submissions tighten membrane manufacturing compliance. Île-de-France and Occitanie aerospace clusters coordinate with Netherlands hydrogen import infrastructure for Orly and Charles de Gaulle hub development.
Aircraft Fuel Cell Market Vendor Landscape
Strategic partnerships dominate the current landscape as stack manufacturers align with airframe integrators and hydrogen suppliers. The vendor base clusters around three distinct tiers: electrolyzer-scale hydrogen producers, fuel cell stack specialists, and integrated aerospace propulsion developers. Technology licensing agreements and joint flight-test programs represent the primary competitive moves, with airport hydrogen hub concessions emerging as a secondary battleground for long-term offtake relationships.
Within the integrated aerospace tier, Airbus SE exemplifies full-system development spanning airframe electrification and hydrogen storage integration. Ballard Power Systems and Plug Power occupy distinct positions in the powertrain supply hierarchy, with the former representing heavy-duty fuel cell stack adaptation and the latter anchoring electrolyzer manufacturing scale for airport hub deployment. ZeroAvia Inc. sits within the emerging propulsion-integrator category, bridging stack procurement with certification-ready aircraft configurations.
| Leading Market Players |
|---|
| Plug Power |
| Linde |
| Ballard Power Systems |
| PowerCell Sweden AB |
| Airbus SE |
| ZeroAvia Inc. |
| Intelligent Energy Limited |
| Doosan Mobility Innovation |
| Air Products |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between FAA-validated and pre-certification fuel cell stacks creates a bifurcated procurement landscape where validated systems command substantial premiums while development-stage hardware competes on unit economics and service bundling. This tier split manifests in divergent supply chain configurations: certified stack manufacturers anchor production in Germany and California with captive catalyst supply agreements, while emerging integrators source modular cell blocks from tier-two suppliers with flexible volume commitments.
Pricing Analysis
Warranty and flight-hour guarantee bundling separates premium stack procurement from bare-hardware transactions in this market. Three-tier pricing structure across certified-flight, test-program, and ground-support equipment levels reflects EASA validation status and thermal management complexity. Price differentiation stems from platinum group metal loading densities and cryogenic containment integration scope. Cost compression in sub-100 kW auxiliary systems is intensifying because alkaline fuel cell alternatives displace PEM architectures for apron vehicle electrification. Regional airlines exhibit highest price sensitivity due to thin route margins, while military procurement tolerates premium positioning for signature-reduction specifications.
Supply Chain Analysis
EASA and FAA airworthiness qualification gates constrain supplier participation to stack manufacturers with documented membrane traceability and catalyst provenance. Manufacturing concentrates in Germany, Japan, and the United States, with Ballard Power Systems and PowerCell Sweden AB anchoring high-volume PEM production. Supply chains draw from South African platinum deposits, Chinese membrane substrates, and Korean bipolar plate stamping. Single-source vulnerability in palladium and iridium refining exposes integrators to geopolitical disruption in Russian supply corridors. Distribution runs through aerospace tier-one integrators rather than direct OEM sales, with Airbus and ZeroAvia controlling stack specification and certification pathway access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where EU Green Deal ReFuelEU Aviation mandates erect substantial capital barriers, entrenching early-mover integrators with completed hydrogen propulsion certification pathways against capital-constrained challengers.
For Market Incumbents: To counter emerging solid oxide fuel cell hybrid architectures from Japanese competitors, Airbus SE and ZeroAvia must accelerate backward integration into membrane manufacturing and secure long-term offtake agreements with Stuttgart and Hamburg electrolyzer operators. Certification investment in the 250 kW–500 kW power bracket represents the critical defensive lever against narrowbody replacement market entry by Boeing-affiliated propulsion developers. For New Entrants and Emerging Players: Enter via unmanned aerial vehicle auxiliary power applications where EASA certification requirements remain less prescriptive than manned aviation standards. Bavarian military drone programs and California cargo drone testbeds offer the most penetrable entry points. A go-to-market angle emphasizing liquid organic hydrogen carrier compatibility bypasses cryogenic infrastructure scarcity constraining PEM competitors. For Investors and Strategic Acquirers: Re-rating potential sits with full-stack integrators possessing FAA-EASA dual validation given accelerating ReFuelEU Aviation enforcement timelines and binding fleet renewal mandates. Long-term viability across a decade horizon favors acquisition targets with demonstrated flight-test hours and secured airport hydrogen hub concessions. The signal to watch is JCAB-EASA bilateral validation protocol expansion, which would unlock Japanese domestic route procurement volumes for certified European powertrain configurations.| Strategic Initiative | Industry Significance |
|---|---|
| Airport Hydrogen Hub Concession | Long-term offtake agreements with Lufthansa and Air France-KLM restructure capital deployment toward integrated fuel-production-propulsion ecosystems. |
| Dual Certification Investment | Simultaneous FAA and EASA validation for hydrogen storage tanks fragments engineering resources but secures transatlantic market access. |
| Membrane Reformulation Program | Elimination of perfluorinated compounds under REACH and F-Gas Regulation mandates stack producer R&D allocation toward compliant ionic conductivity solutions. |
| Modular Stack Platform Launch | Standardized cell block assembly across 100 kW to 500 kW range compresses time-to-certification for derivative regional aircraft variants. |
| Platinum Group Metal Hedging | Forward contracting with South African and Russian refiners mitigates raw material price volatility exposure for catalyst-dependent stack manufacturing. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with fuel cell stack engineering directors, EASA certification leads, airport hydrogen hub project developers, airline fleet procurement managers, and electrolyzer manufacturing executives. Bottom-up triangulation combined installed base estimates from German and California demonstration programs with top-down validation against EU Green Deal delegated act implementation schedules. Secondary sources included EASA type certification submission disclosures, FAA hydrogen propulsion advisory circular drafts, ReFuelEU Aviation mandate compliance reports, and customs records tracking platinum group metal import flows.
Data-stream reconciliation across shipment volumes, certification timelines, and infrastructure investment databases informed the analytical framework. Segmentation modeling tracked power rating brackets, propulsion architecture chemistry, end-user categories spanning commercial and military aviation, and regional regulatory cluster divergence. CAGRs were derived from fitted adoption curves calibrated against binding mandate enforcement dates and electrolyzer capacity buildout schedules. Industry-specific forecast inputs incorporated flight-test program progression rates and airport ground support equipment electrification procurement cycles.
Revisions become necessary when hydrogen infrastructure buildout velocity materially diverges from aircraft certification schedules, or when platinum group metal supply disruptions alter stack manufacturing cost structures. Forecasts reflect documented assumptions regarding EASA-FAA regulatory harmonization timelines and electrolyzer manufacturing scale economies. A model refresh is warranted upon material change in ReFuelEU Aviation mandate enforcement stringency or JCAB bilateral validation protocol expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuel Cell Technology
Hydrogen Fuel Cell Drone Market
Fuel Cell Technology
Hydrogen Fuel Cell Vehicle Market
Fuel Cell Technology
Helium Recovery Systems Market
Fuel Cell Technology
Europe Direct Methanol Fuel Cell Market
Fuel Cell Technology
Fuel Cells for Marine Vessels Market
Fuel Cell Technology
Solid Oxide Fuel Cell Market
Fuel Cell Technology
Global Fuel Cell Balance of Plant (BOP) Market
Fuel Cell Technology
Hydrogen Fuel Cell Stack and Membrane Recycling for EU Mobility Market
Fuel Cell Technology
Regenerative Fuel Cell (RFC) Technologies Market
Fuel Cell Technology
Fuel Cell for Stationary Power Market
Fuel Cell Technology
Global Planar Solid Oxide Fuel Cell Market
Fuel Cell Technology
Residential Fuel Cell Market
Fuel Cell Technology
Europe Fuel Cell Market
Fuel Cell Technology
Hydrogen Fuel Cell Stack Durability and Performance Test Equipment Market
Fuel Cell Technology
Japan Fuel Cell Market
Fuel Cell Technology
Alkaline Fuel Cell Market