
 Ghana Solar Energy Market | 2026-2036
Ghana Solar Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Ghana Solar Energy Market Foresight
Modular solar-plus-storage bundling is expanding buyer choice across Ghana's commercial and industrial segments. JinkoSolar Holdings Co. Ltd leverages its vertically integrated cell-to-module production to anchor large-scale utility procurement in West Africa. Trina Solar Ltd competes through high-efficiency bifacial module specialization, while PEG Africa dominates pay-as-you-go distributed energy financing for underserved households and SMEs.
Photovoltaic systems convert sunlight into direct-current electricity through semiconductor junctions, with crystalline silicon modules achieving commercial efficiencies between 19% and 22% under standard test conditions; concentrated solar power employs mirrors or lenses to focus thermal energy for steam-driven generation, serving grid-scale dispatchable output. Photovoltaics leads installed capacity due to declining module costs and simpler balance-of-system requirements, while off-grid solutions represent the fastest-expanding application segment as rural electrification gaps persist. Grid-tied systems command the largest revenue pool where distribution infrastructure exists, though hybrid systems capture margin concentration by addressing load-shedding reliability concerns.
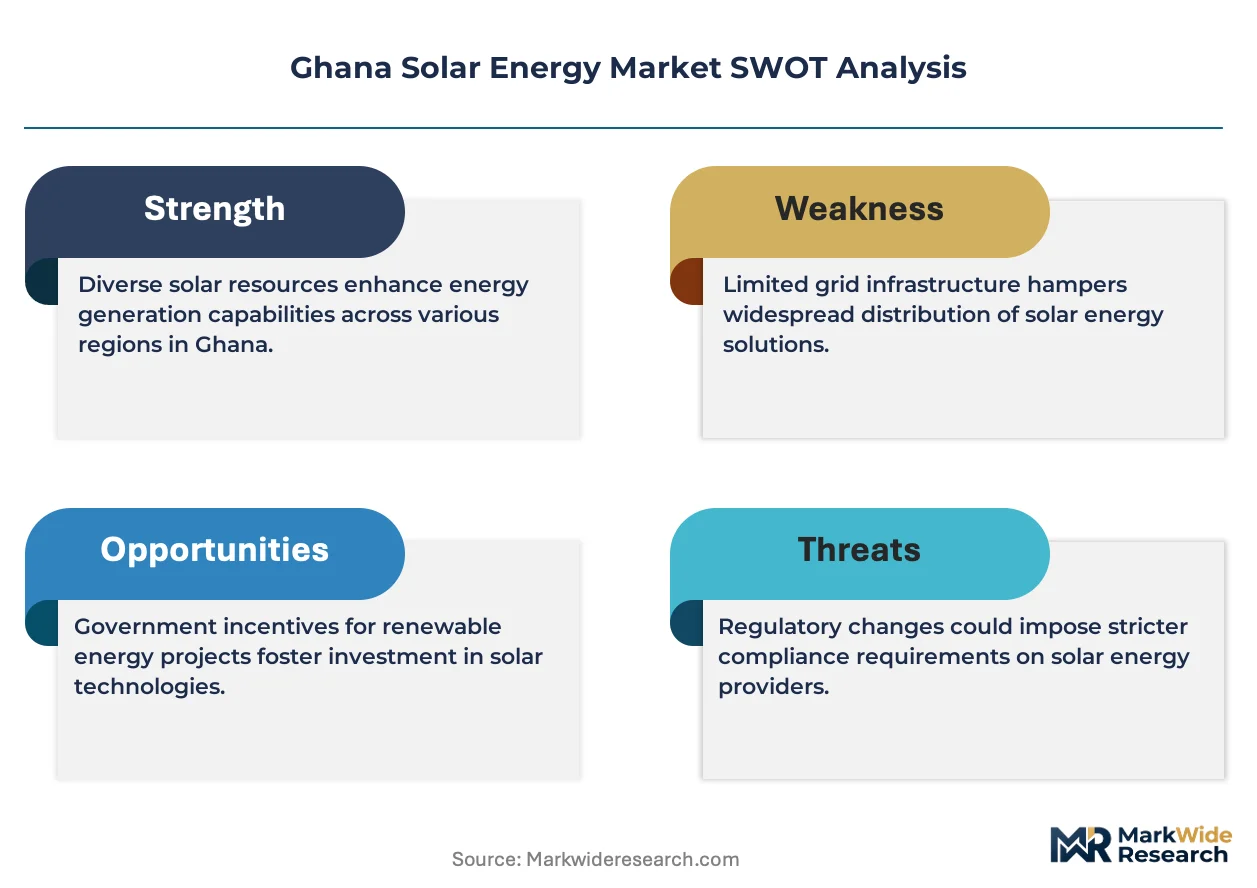
Ghana's Energy Commission administers renewable energy licensing and net metering protocols, while the Public Utilities Regulatory Commission sets feed-in tariffs that directly determine project bankability and private capital flows. The country's national petroleum regulator and Bui Power Authority coordinate hydropower-solar hybrid scheduling to optimize grid stability. Stakeholders must monitor forthcoming revisions to local content requirements and customs duty waivers for solar equipment imports, as these instruments will determine whether domestic assembly capacity develops ahead of projected demand inflection.
Market Dynamics
Feed-in tariff revisions by Ghana's Public Utilities Regulatory Commission are restructuring project economics, redirecting capital toward commercial and industrial installations while utility-scale procurement faces margin compression from revised power purchase agreement terms.
Growth Catalysts
- Net Metering Protocols:Ghana's Energy Commission streamlined interconnection standards for distributed generation, enabling commercial facilities to offset grid purchases through behind-the-meter solar installations.
- Industrial Load Expansion:Manufacturing clusters in Tema and Sekondi-Takoradi are deploying captive solar to hedge against grid instability and volatile thermal generation costs.
- Bifacial Module Maturation:High-efficiency dual-glass photovoltaic technology is improving energy yield per hectare, making land-constrained urban projects financially viable.
Market Restraints
- Import Duty Exposure:Customs duty waivers for solar equipment remain subject to periodic renewal, creating uncertainty in project pro forma calculations and lender due diligence.
- Currency Mismatch:Dollar-denominated module procurement against cedi-denominated power offtake exposes developers to foreign exchange volatility that debt providers struggle to hedge.
- Grid Absorption Limits:Distribution infrastructure in rural Northern Region lacks capacity to evacuate utility-scale solar output without substantial transmission reinforcement.
Strategic Opportunities
- Agricultural Processing Integration:Cocoa drying and cold storage facilities in Ashanti Region represent untapped demand for hybrid solar-diesel systems with battery buffering.
- Local Assembly Incentives:Pending revisions to local content requirements could reward domestic module assembly with preferential grid access queue positioning.
- Pay-as-you-go Scaling:Mobile money-enabled distributed energy financing is penetrating peri-urban SME segments previously excluded from conventional credit.
Industry Challenges
- Technical Workforce Scarcity:Certified photovoltaic installers and battery system integrators remain concentrated in Greater Accra, constraining deployment velocity in secondary cities.
- Permitting Timeline Variability:Environmental assessment approvals through Ghana's Environmental Protection Agency exhibit inconsistent duration, complicating construction scheduling and equipment staging.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ghana Solar Energy Market |
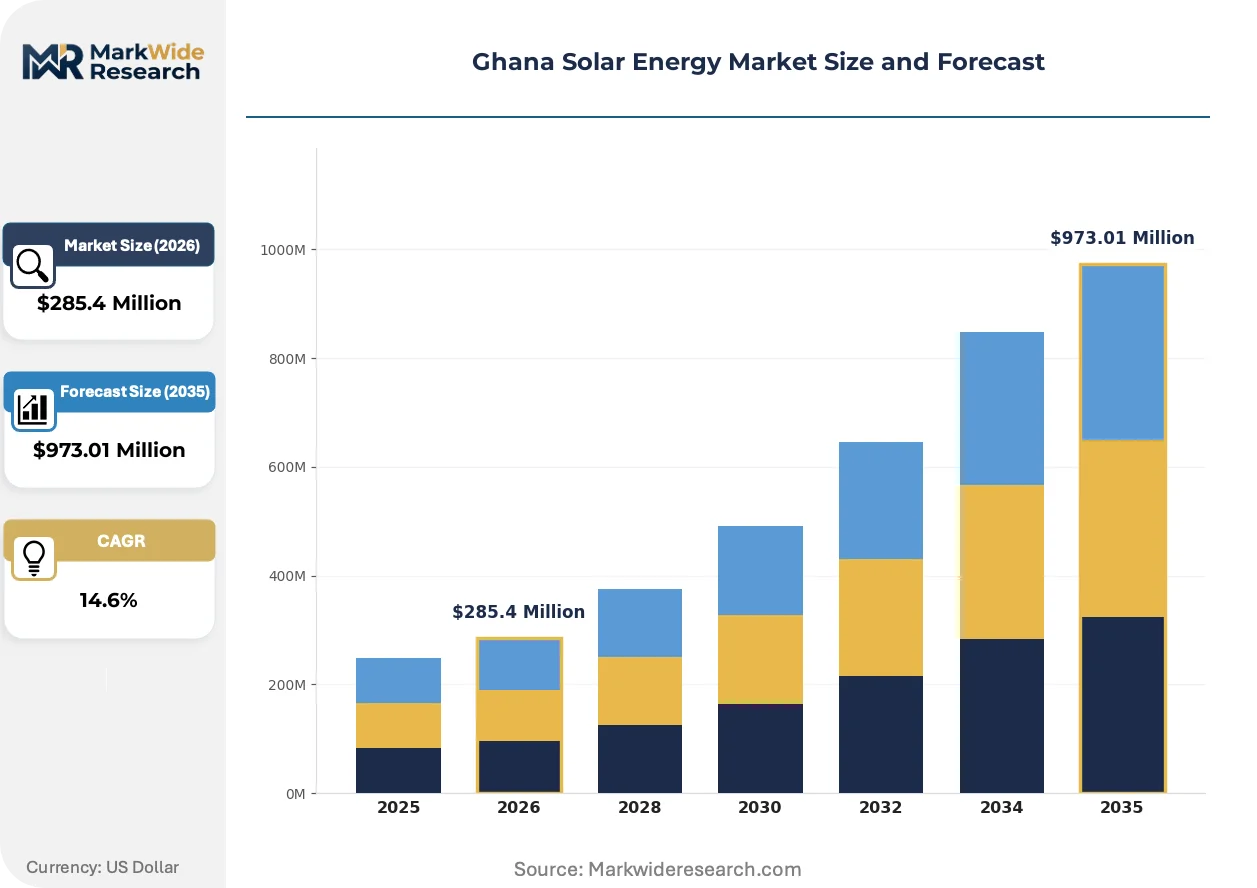
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $973.01 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Photovoltaics, Concentrated Solar Power, Bifacial Modules, Thin-Film Solar Application: Residential, Commercial, Industrial, Off-Grid Solutions Delivery Mode: Grid-Tied Systems, Standalone Systems, Hybrid Systems, Portable Solutions End User: Government, NGOs, Private Sector, Households |
| Companies Covered | JinkoSolar Holdings Co. Ltd, Trina Solar Ltd, Redavia Solar Power, Translight Solar, SunPower Innovations, PEG Africa, BXC Ghana, Daystar Power Ghana, Bui Power Authority, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ghana Solar Energy Market Shifts & Advancements
Technology convergence and financing innovation are compressing deployment cycles across Ghana's solar value chain, with distributed generation models gaining traction relative to centralized procurement.
Lithium iron phosphate battery storage is overtaking lead-acid alternatives in commercial solar-plus-storage configurations. Mining operations and manufacturing facilities in Obuasi and Tarkwa are specifying four-hour duration systems to ride through grid outages. This chemistry shift is compressing balance-of-system costs and extending project asset life beyond prior financing tenors.
Ghana's renewable energy feed-in tariff revisions are redirecting developer attention toward self-consumption and wheeling arrangements. The Public Utilities Regulatory Commission's reduced utility-scale tariffs have stalled greenfield independent power producer pipelines. Commercial offtakers are responding by negotiating bilateral power purchase agreements that bypass wholesale market exposure.
Aggregated procurement platforms are emerging as the dominant channel for mid-scale commercial installations. Facility managers in Accra and Kumasi are pooling demand to achieve module pricing previously reserved for utility procurement. This collective buying is most visible among hospitality and retail chains seeking standardized equipment specifications across multiple properties.
Ghana Solar Energy Market Segmentation
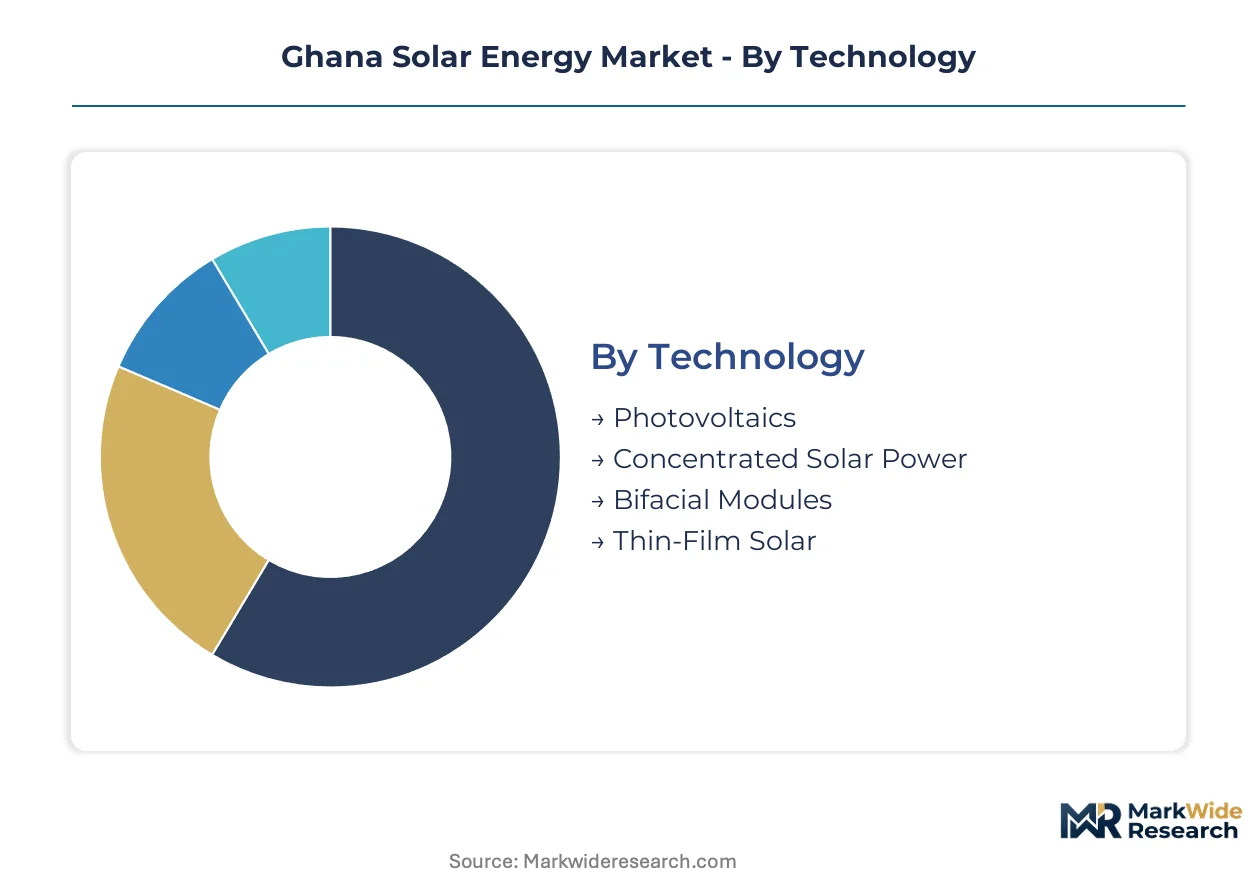
Technology choice in Ghana's solar market determines capital intensity, land requirements, and financing structure. Application and delivery mode selections reflect grid reliability conditions and offtaker creditworthiness across the country's uneven electrification landscape.
Technology:
Module efficiency and manufacturing scale separate commercial buyers from specialized applications in this category.
- Photovoltaics:Crystalline silicon modules dominate commercial procurement through declining unit costs and simplified balance-of-system engineering. Manufacturing clusters in Tema and Sekondi-Takoradi specify monocrystalline systems to hedge diesel price volatility and grid instability.
- Concentrated Solar Power:Mirror-based thermal collection enables dispatchable generation with molten salt storage integration. The Bui Power Authority coordinates CSP-hydro hybrid scheduling to stabilize Northern Region transmission constraints where photovoltaic evacuation faces bottlenecks.
- Bifacial Modules:Dual-glass construction captures reflected irradiance from albedo surfaces, improving yield per hectare for land-constrained urban installations in Greater Accra.
- Thin-Film Solar:Cadmium telluride and copper indium gallium selenide technologies serve portable and building-integrated applications where weight and flexibility outweigh efficiency metrics.
Photovoltaics leads volumes today; bifacial modules are gaining share fastest.
Application:
Load profile predictability and tariff exposure differentiate buyers across residential, commercial, and industrial segments.
- Residential:Distributed rooftop installations serve grid-connected households in Accra and Kumasi through net metering protocols. Pay-as-you-go financing models penetrate peri-urban segments previously excluded from conventional credit.
- Commercial:Behind-the-meter solar offsets grid purchases for retail chains, hospitality groups, and office complexes. Aggregated procurement platforms enable facility managers to achieve module pricing previously reserved for utility-scale buyers.
- Industrial:Captive generation at mining operations and manufacturing facilities in Obuasi and Tarkwa specifies four-hour lithium iron phosphate storage to ride through outages. Cocoa drying and cold storage facilities in Ashanti Region represent emerging demand for hybrid solar-diesel systems.
- Off-Grid Solutions:Standalone systems address rural electrification gaps in Northern Region where distribution infrastructure lacks capacity for centralized supply. Mobile money-enabled financing accelerates deployment velocity among underserved households and SMEs.
Industrial applications command the largest revenue pool; off-grid solutions show the steepest expansion trajectory.
Delivery Mode:
Interconnection requirements and backup duration specifications shape procurement decisions in this dimension.
- Grid-Tied Systems:Synchronous inverters feed directly into distribution networks where infrastructure exists, maximizing capacity factor through unlimited export. Ghana's Energy Commission streamlined interconnection standards to accelerate commercial adoption.
- Standalone Systems:Battery-buffered configurations serve locations beyond distribution reach, requiring oversized array capacity to maintain supply through seasonal irradiance variation.
- Hybrid Systems:Grid-connected installations with storage capture margin concentration by addressing load-shedding reliability concerns. Mining and manufacturing specifications prioritize four-hour duration to bridge outage intervals.
- Portable Solutions:Lightweight foldable panels and power stations serve construction sites, agricultural processing, and emergency response where permanent installation is impractical.
Grid-tied systems dominate current deployment; hybrid configurations are climbing the fastest as reliability concerns intensify.
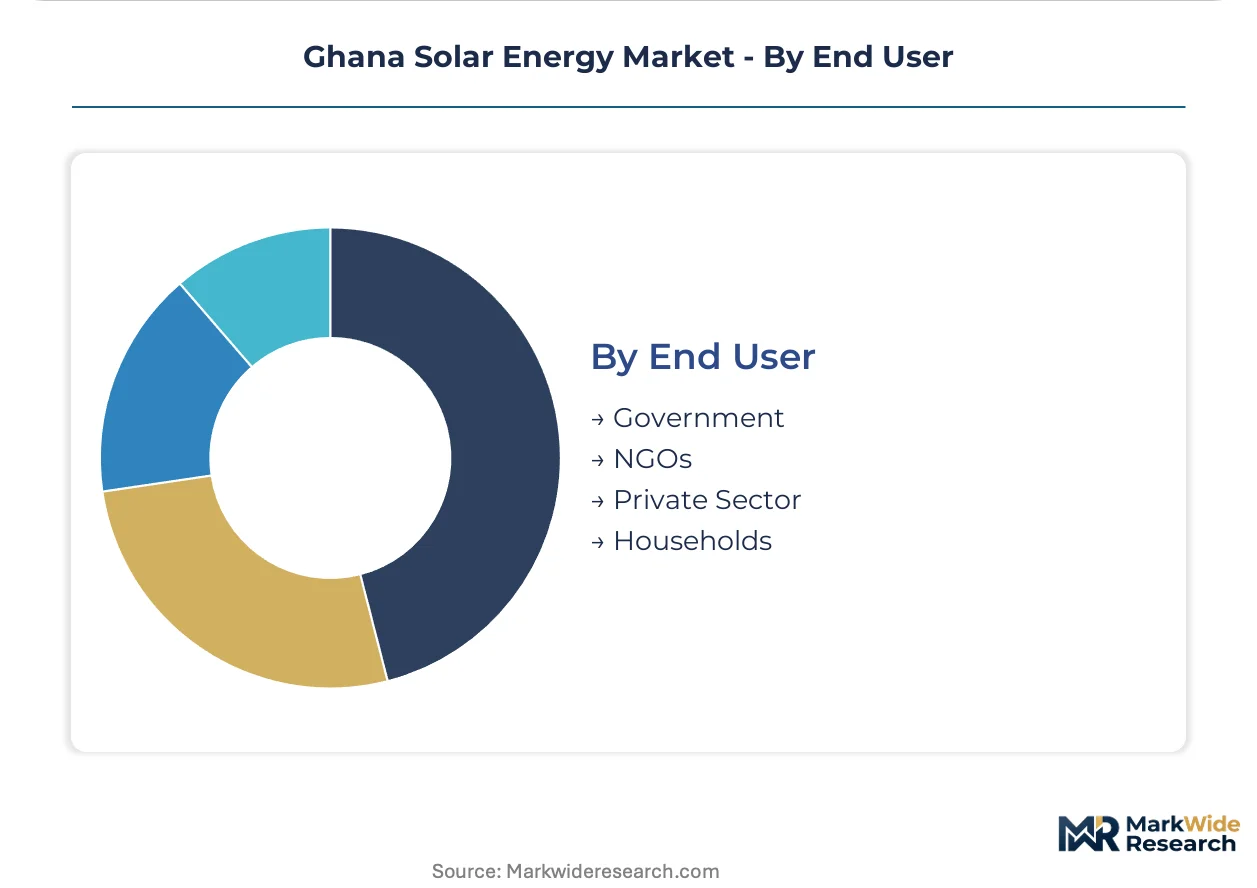
End User:
Financing capacity and procurement process complexity separate institutional buyers from household decision-makers.
- Government:Public Utilities Regulatory Commission procurement drives utility-scale independent power producer pipelines, though revised feed-in tariffs have stalled greenfield development. Ministries and agencies specify standardized equipment across facility portfolios.
- NGOs:Development finance institutions and international organizations fund rural electrification programs in Northern Region, prioritizing community ownership models and local technician training.
- Private Sector:Bilateral power purchase agreements bypass wholesale market exposure for manufacturing and mining offtakers. Corporate sustainability commitments accelerate procurement among multinational subsidiaries.
- Households:Distributed energy financing through mobile money platforms penetrates credit-constrained segments. Urban households in Greater Accra and Ashanti Region concentrate demand through grid-connected rooftop installations.
Private sector procurement leads absolute volumes; household segments are expanding most quickly through pay-as-you-go scaling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ghana's solar sector traces its modern lineage to the 2011 Renewable Energy Act, which established the feed-in tariff framework that attracted initial independent power producer investment into West Africa's most electrified economy.
Greater Accra
Industrial load growth and grid reliability challenges drive commercial solar procurement in Ghana's capital region. The Energy Commission's streamlined net metering protocols enable behind-the-meter installations for manufacturing and logistics facilities. Tema's port corridor hosts captive solar deployments at warehousing and processing operations hedging against volatile thermal generation costs.
Ashanti Region
Cocoa processing and cold storage facilities generate emerging demand for hybrid solar-diesel systems with battery buffering. The Public Utilities Regulatory Commission's revised tariffs redirect developer attention toward self-consumption arrangements in Kumasi's industrial zone. Obuasi's mining operations specify four-hour lithium iron phosphate storage to bridge grid outage intervals.
Northern Region
Rural electrification gaps and weak distribution infrastructure accelerate standalone system deployment across Ghana's northern territories. Bui Power Authority coordinates hydropower-solar hybrid scheduling to stabilize transmission constraints where photovoltaic evacuation faces bottlenecks. Mobile money-enabled financing penetrates peri-urban SME segments previously excluded from conventional credit.
Western Region
Sekondi-Takoradi's manufacturing clusters deploy captive generation to offset grid instability and diesel price volatility. The national petroleum regulator coordinates with energy stakeholders on offshore-industrial load integration. Takoradi's port and processing facilities represent concentrated demand for commercial-scale rooftop and ground-mount installations.
Ghana Solar Energy Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology specialization and financing model differentiation in Ghana's solar market. Vertically integrated Chinese module manufacturers anchor utility-scale procurement through cost leadership, while distributed energy financiers capture margin concentration in underserved household and SME segments. Three archetypes dominate: integrated cell-to-module producers, high-efficiency technology specialists, and pay-as-you-go platform operators. Competitive moves center on aggregated procurement platforms for mid-scale commercial buyers and lithium iron phosphate storage bundling to address reliability concerns.
Within the integrated manufacturing tier, JinkoSolar Holdings Co. Ltd and Trina Solar Ltd represent the dominant procurement anchors for Ghana's utility and large commercial segments. PEG Africa occupies a distinct position exemplifying the pay-as-you-go financing archetype that has expanded distributed energy access across peri-urban and rural markets. These three entities collectively illustrate the market's bifurcation between scale-driven module supply and localized customer financing innovation.
| Leading Market Players |
|---|
| JinkoSolar Holdings Co. Ltd |
| Trina Solar Ltd |
| Redavia Solar Power |
| Translight Solar |
| SunPower Innovations |
| PEG Africa |
| BXC Ghana |
| Daystar Power Ghana |
| Bui Power Authority |
| Others |
Supply & Pricing Matrix
Bifurcation between premium high-efficiency modules and commodity crystalline silicon separates procurement tiers across Ghana's solar market, with pricing power concentrating in manufacturers commanding superior cell-to-module yields while downstream distributors absorb margin compression from currency volatility and duty uncertainty. This tier divergence manifests in supply chain configurations where vertically integrated Chinese producers anchor utility-scale procurement through captive polysilicon supply, while regional assemblers serving commercial segments face working capital strain from dollar-denominated component imports against cedi-denominated receivables.
Pricing Analysis
Project-based long-term offtake structures dominate Ghana's solar procurement, with pricing stratifying across premium, standard, and economy tiers according to module efficiency ratings and balance-of-system bundling. Price differentiation hinges on certification grade — IEC 61215 compliance versus enhanced PID resistance warranties — and volume scale, with aggregated procurement platforms achieving module pricing previously reserved for utility buyers. Cost compression in standard-tier crystalline silicon is intensifying because Chinese manufacturers are flooding West African markets with excess inventory. Industrial offtakers in Tema and Sekondi-Takoradi show least price sensitivity due to diesel hedge value, while peri-urban households through pay-as-you-go financing represent the most price-constrained segment.
Supply Chain Analysis
Single-source vulnerability sits with Chinese polysilicon and wafer supply, which feeds Ghana's module procurement through manufacturing clusters in Vietnam and Malaysia serving as secondary assembly points. Raw material dependencies center on metallurgical-grade silicon, silver paste for cell metallization, and aluminum frames for module construction. Tariff exposure constitutes the dominant structural risk, as Ghana's customs duty waivers for solar equipment remain subject to periodic renewal without legislative certainty. Distribution runs through Accra-based EPC contractors and regional distributors who stage inventory to bridge construction timelines against permitting delays.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ghana's solar market represents a late-cycle quality story where module efficiency and storage integration now determine competitive viability, as commercial offtakers shift procurement specifications toward four-hour lithium iron phosphate buffering to ride through grid instability.
For Market Incumbents: Anchor market position through backward integration into battery storage system assembly within Ghana's emerging industrial zones, defending against margin erosion from Chinese module oversupply by capturing value-added integration margins. Prioritize certification investment in IEC 62619 battery safety standards to differentiate hybrid system offerings from commodity panel suppliers. For New Entrants and Emerging Players: Ghana's Energy Commission net metering protocol revisions open a window for behind-the-meter commercial installations bypassing utility-scale tariff compression. Target peri-urban SME segments in Kumasi and Tamale with mobile money-enabled financing platforms, penetrating credit-constrained demand previously excluded from conventional procurement channels through standardized equipment leasing structures. For Investors and Strategic Acquirers: Consolidation pressure builds where distributed energy financing platforms lack captive generation assets to match customer acquisition scale. Position for long-term viability by acquiring pay-as-you-go operators with established mobile money payment rails and technician training networks, watching for feed-in tariff stabilization as the inflection signal for utility-scale independent power producer pipeline revival.| Strategic Initiative | Industry Significance |
|---|---|
| Vertical Integration into Storage | Battery system assembly in Tema industrial zone captures hybrid project margins beyond module supply. |
| Power Purchase Agreement Restructuring | Bilateral commercial offtake contracts bypass Public Utilities Regulatory Commission wholesale tariff exposure. |
| Technology Licensing | Bifacial module IP partnerships enable domestic assembly qualifying for local content preferential queue positioning. |
| Green Certification Program | Corporate sustainability commitments accelerate procurement among multinational mining subsidiaries in Obuasi. |
| Capacity Buildout | Four-hour lithium iron phosphate manufacturing lines serve mining and manufacturing reliability specifications. |
Research Methodology
Multiple input streams — structured interviews with utility planning officers and independent power producer developers, customs and trade data from Ghana Revenue Authority, and project development databases tracking pipeline progression — were reconciled through bottom-up installation tracking and top-down market sizing validation. Primary fieldwork engaged EPC contractors, commercial facility managers in Accra and Kumasi, and pay-as-you-go platform operators alongside secondary analysis of Energy Commission licensing records and Public Utilities Regulatory Commission tariff determinations.
Data-stream reconciliation across technology, application, and delivery mode segmentation enabled projection construction over the analysis window, with CAGRs derived from installed capacity build rates and revenue per watt trajectories. Modeled dimensions span photovoltaic versus concentrated solar power technology, grid-tied versus hybrid versus standalone delivery configurations, and residential through industrial application tiers. Forecast inputs incorporated feed-in tariff revision scenarios and currency volatility assumptions affecting module import economics.
Revisions become necessary when regulatory instruments including local content requirements and customs duty waivers undergo substantive modification, or when grid absorption infrastructure investment materially lags generation capacity additions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
GCC Solar Water Heater Market
Solar Power Systems
Building Integrated Photovoltaics Module Market
Solar Power Systems
Middle East and Africa Solar PV Inverters Market
Solar Power Systems
Solar Microgrid Market
Solar Power Systems
Solar Panels Frame Market
Solar Power Systems
Half-Cell Solar Module Market
Solar Power Systems
High Concentration Photovoltaics Market
Solar Power Systems
Solar System in Kuwait Market
Solar Power Systems
Floating Solar System Market
Solar Power Systems
Solar Grid-Tied Systems Market
Solar Power Systems
Polycrystalline Solar Panel Market
Solar Power Systems
Printable Solar Cells Market
Solar Power Systems
Residential Solar Energy Market
Solar Power Systems
Southeast Asia Solar Energy Market
Solar Power Systems
Mexico Solar Photovoltaic (PV) Market
Solar Power Systems
Solar PV Junction Box Market