
 Foot and Ankle Devices Market | 2026-2036
Foot and Ankle Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Foot and Ankle Devices Market Intelligence
Hospital procurement networks is reconfiguring how foot and ankle devices reach surgical suites, with integrated delivery systems consolidating vendor contracts across orthopedic service lines. Stryker Corporation leverages its trauma and extremities portfolio to anchor premium implant placements in tier-one medical centers. Zimmer Biomet Holdings Inc competes through specialized foot and ankle reconstruction systems that target complex deformity correction. Smith & Nephew plc differentiates via advanced wound management integration with post-operative bracing protocols.
Foot and ankle devices encompass orthopedic implants, external fixation systems, prosthetic components, and supportive appliances engineered from titanium alloys, PEEK polymers, or carbon fiber composites to restore biomechanical function after trauma, degenerative disease, or congenital deformity. Implant segments sustain the highest margin pools due to regulatory complexity and surgeon training requirements, while 3D printing technology is displacing conventional machining in custom orthotic production. Sports performance applications represent the fastest-growing demand vector as professional and amateur athletes seek injury prevention and biomechanical optimization solutions.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development timelines and commercialization costs for manufacturers seeking multi-regional market access. ISO 13485 quality management systems and ASTM F2077 testing standards govern material validation and mechanical performance benchmarks that determine reimbursement eligibility. Stakeholders must monitor evolving digital health integration requirements as smart device capabilities expand beyond passive support into real-time gait analytics and remote patient monitoring.
Market Dynamics
Hospital procurement consolidation is restructuring vendor relationships across foot and ankle device markets, as integrated delivery networks demand bundled pricing across orthopedic service lines and post-operative care protocols.
Growth Catalysts
- Aging Demographics:Germany, Japan, and the United States exhibit concentrated demand clusters where expanding elderly populations require arthrodesis and joint replacement procedures.
- EU MDR Harmonization:Centralized conformity assessment procedures are streamlining multi-country commercialization for established manufacturers with robust technical documentation systems.
- Additive Manufacturing:3D printing technology is enabling patient-specific implant geometries and custom orthotic production at reduced lead times compared to conventional machining.
Market Restraints
- Titanium Alloy Supply Concentration:Aerospace and defense sectors compete for limited high-grade titanium feedstock, creating input cost volatility for implant manufacturers.
- FDA 510(k) Pathway Complexity:Substantial equivalence determinations for novel implant designs require extensive predicate device analysis, extending premarket timelines.
- Biologic Substitutes:Autograft and allograft bone grafting procedures retain preference in certain fusion applications, limiting synthetic graft material penetration.
Strategic Opportunities
- Ambulatory Surgical Center Expansion:Outpatient procedural migration creates demand for simplified fixation systems and disposable instrument kits designed for lower-acuity settings.
- Smart Device Convergence:Integration of pressure sensors and accelerometers into post-operative bracing enables remote gait analytics and adherence monitoring.
- Japan's Sports Medicine Infrastructure:Professional baseball and soccer league medical partnerships offer specialized channels for performance-oriented injury prevention devices.
Industry Challenges
- Surgeon Training Bottlenecks:Complex deformity correction systems require extended proctoring periods and cadaveric lab certification, constraining adoption velocity.
- Legacy EHR Integration:Smart device data streams lack standardized interoperability protocols with hospital information systems, complicating remote monitoring deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foot and Ankle Devices Market |
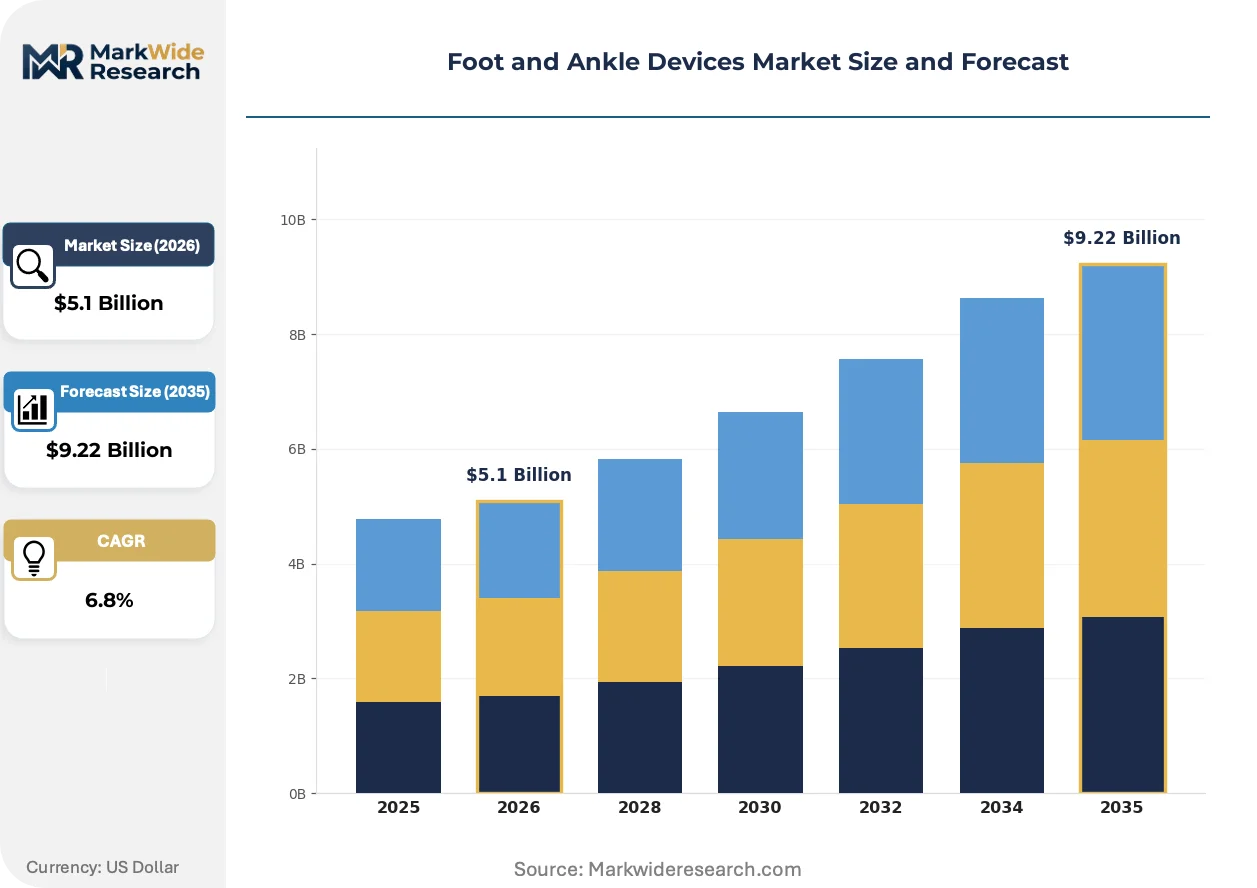
| Market Size in 2026 | $5.1 Billion |
| Market Size in 2035 | $9.22 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Orthotic Braces, Ankle Supports, Footwear, Implants Application: Rehabilitation, Injury Prevention, Surgery, Sports Performance End User: Hospitals, Clinics, Home Care, Sports Facilities Technology: 3D Printing, Biodegradable Materials, Smart Devices, Custom Molding |
| Companies Covered | Stryker Corporation, Arthrex Inc, Zimmer Biomet Holdings Inc, DePuy Synthes Companies, Smith & Nephew plc, Acumed LLC, Johnson & Johnson, Enovis Corp, Orthofix Medical Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foot and Ankle Devices Market Strategic Shifts & Innovations
Digital health capabilities are penetrating passive orthopedic devices, transforming braces and supports into connected care platforms that capture biomechanical data and enable proactive intervention.
Sensor-embedded orthotics is digitizing post-operative monitoring by capturing real-time plantar pressure distribution and range-of-motion metrics. Tier-one medical centers in the United States are piloting these systems for high-risk diabetic foot ulcer patients. This capability compression is collapsing the traditional separation between acute surgical care and chronic disease management.
EU MDR technical documentation requirements are elevating clinical evidence standards for implantable fixation systems. Manufacturers must now submit prospective clinical data or rigorous post-market surveillance programs to maintain CE marking. Small-to-mid sized orthopedic firms face particular strain as notified body capacity constrains conformity assessment timelines.
Integrated delivery networks are consolidating vendor contracts across orthopedic service lines, replacing individual surgeon preference with system-level value analysis committees. Hospital procurement teams now evaluate total episode cost including implant, instrumentation, and post-operative bracing. This concentration is most visible in Germany's Krankenhausversorgung networks and United States IDN expansion into outpatient surgery.
Foot and Ankle Devices Market Segmentation
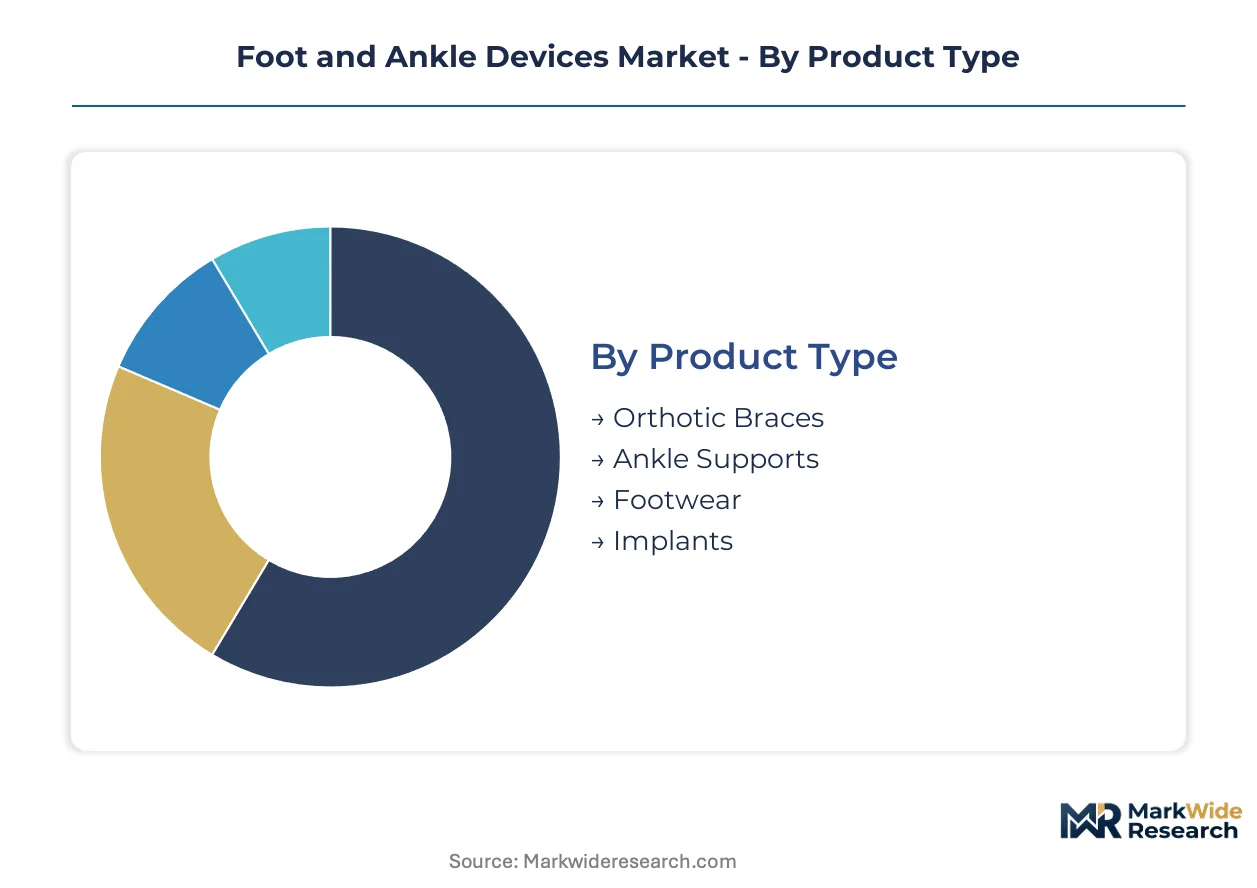
Device segmentation in foot and ankle markets determines service intensity, inventory turnover, and reimbursement pathways. Product architecture varies sharply between acute surgical implants and chronic care appliances, with distinct margin profiles and regulatory burdens shaping competitive strategy.
Product Type:
After-sales service intensity diverges dramatically across product categories, with implantable systems requiring surgeon training programs and explant support while passive bracing demands minimal technical assistance.
- Orthotic Braces:Rigid and semi-rigid polymer structures stabilize post-operative recovery and chronic conditions. Demand concentrates in United States integrated delivery networks where bundled episode payments incentivize standardized bracing protocols. Hospital procurement teams now evaluate total cost including fitting labor and replacement schedules.
- Implants:Titanium alloy and PEEK polymer fixation systems anchor arthrodesis and fracture repair procedures. Germany's Krankenhausversorgung networks concentrate demand for premium trauma implants as ambulatory surgical centers expand service lines. Regulatory complexity and predicate device requirements extend commercialization timelines.
- Ankle Supports:Elastic and neoprene compression sleeves address mild instability and prophylactic use.
- Footwear:Diabetic therapeutic shoes and custom-molded insoles redistribute plantar pressure.
By volume, Orthotic Braces leads. By growth pace, Implants is ahead.
Application:
Cost tier stratification separates acute surgical interventions from preventive and maintenance applications, with reimbursement codes and provider settings determining accessible price points.
- Surgery:Internal fixation and arthroplasty procedures address trauma, arthritis, and deformity correction. United States ambulatory surgical centers are migrating lower-complexity fusions from inpatient settings, creating demand for streamlined instrumentation kits. Surgeon proctoring requirements constrain adoption velocity for novel implant geometries.
- Sports Performance:Injury prevention and biomechanical optimization solutions target professional and amateur athletes. Japan's professional baseball and soccer league medical partnerships offer specialized distribution channels for performance-oriented devices. Sensor-embedded orthotics enable real-time gait analytics in training environments.
- Rehabilitation:Post-operative mobilization and range-of-motion restoration protocols.
- Injury Prevention:Prophylactic bracing and protective equipment for high-risk activities.
By procedure count, Surgery dominates. By expansion trajectory, Sports Performance is climbing the fastest.
End User:
Customer type determines purchasing authority, with institutional procurement committees replacing individual clinician preference in concentrated health systems.
- Hospitals:Tier-one medical centers anchor complex reconstruction and trauma volume. Germany's university hospitals and United States academic medical centers concentrate demand for premium fixation systems with advanced instrumentation. Value analysis committees now evaluate implant, disposable, and post-operative bracing as unified episodes.
- Home Care:Direct-to-patient channels for chronic disease management and maintenance bracing. United States Medicare durable medical equipment reimbursement shapes product selection and supplier consolidation. Remote patient monitoring integration is penetrating diabetic foot ulcer prevention protocols.
- Clinics:Orthopedic and podiatric offices delivering non-surgical interventions.
- Sports Facilities:Professional team medical staffs and training centers.
By revenue concentration, Hospitals leads. By structural shift, Home Care is gaining share fastest.
Technology:
Manufacturing maturity separates established fabrication methods from emerging production platforms with distinct capital requirements and regulatory pathways.
- 3D Printing:Additive manufacturing enables patient-specific implant geometries and custom orthotic production at compressed lead times. FDA 510(k) clearance pathways for printed titanium devices are establishing precedent for multi-regional commercialization. Aerospace-grade titanium powder supply constraints create input cost volatility.
- Smart Devices:Pressure sensors and accelerometers embedded in post-operative bracing capture real-time biomechanical data. United States pilot programs for high-risk diabetic patients are validating remote monitoring reimbursement models. Legacy EHR interoperability gaps complicate hospital system integration.
- Biodegradable Materials:Resorbable polymers for temporary fixation and scaffold applications.
- Custom Molding:Vacuum-formed and direct-milled patient-specific appliances.
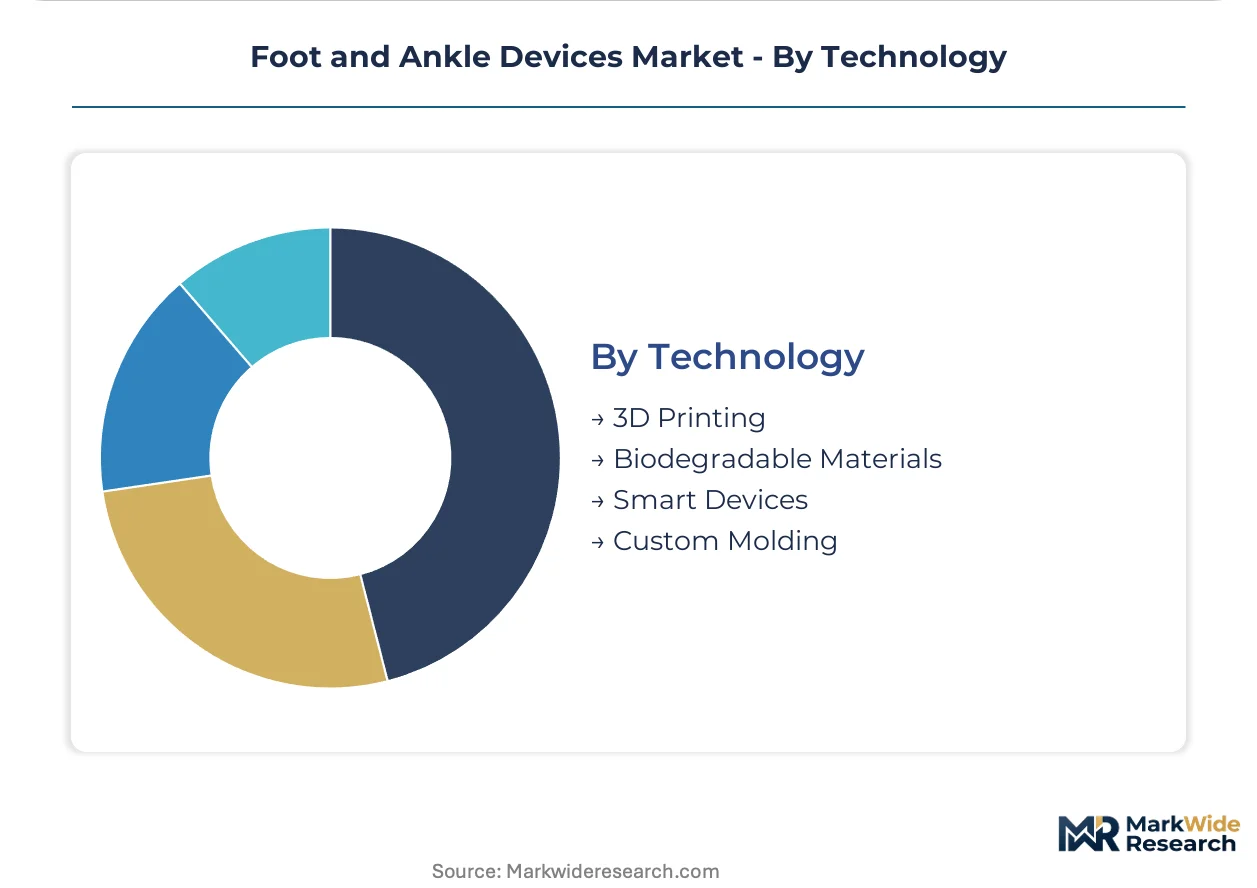
By installed base, Custom Molding leads. By development velocity, Smart Devices is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German hospital procurement networks command premium pricing leverage that Brazilian distributors cannot replicate, creating a structural asymmetry in implant economics across developed and emerging markets.
United States
Medicare bundled payment pilots and ambulatory surgical center expansion are redirecting arthrodesis procedures from inpatient to outpatient settings. FDA 510(k) clearance timelines for novel fixation geometries extend commercialization windows. Cleveland Clinic and Mayo Clinic anchor demand for advanced trauma systems in the Midwest.
Germany
Krankenhausversorgung networks consolidate vendor contracts across orthopedic service lines, replacing individual surgeon preference with value analysis committees. EU MDR conformity assessments through notified bodies like TÜV SÜD elevate clinical evidence requirements. Berlin and Munich university hospitals concentrate complex deformity correction volume.
Japan
Aging demographics and professional baseball league medical partnerships drive demand for sports medicine infrastructure. PMDA premarket approval pathways for titanium alloy implants maintain rigorous mechanical testing standards. Tokyo and Osaka medical centers pilot sensor-embedded orthotics for diabetic foot ulcer prevention.
China
NMPA regulatory harmonization with international standards accelerates market access for multinational manufacturers. Domestic titanium powder production expansion reduces import dependency for implant feedstock. Shanghai and Beijing tertiary hospitals anchor premium fixation system adoption in the Yangtze River Delta.
United Kingdom
NHS England procurement frameworks standardize orthotic bracing protocols across integrated care systems. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR technical documentation requirements. London teaching hospitals and Manchester trauma centers concentrate complex reconstruction demand.
Foot and Ankle Devices Market Key Industry Players
Diversified orthopedic conglomerates and specialized extremity-focused firms split the market into distinct capability tiers. Consolidation pressure intensifies as integrated delivery networks demand bundled pricing across implant, instrumentation, and post-operative care protocols. Strategic archetypes include full-line orthopedic multinationals with trauma portfolios, dedicated foot and ankle specialists with surgeon training ecosystems, and emerging additive manufacturing entrants with patient-specific production platforms. Dominant competitive moves center on vertical integration into titanium powder supply chains and strategic partnerships with ambulatory surgical center networks.
Among diversified orthopedic manufacturers, Stryker Corporation and Zimmer Biomet Holdings Inc exemplify the full-line archetype with extensive trauma and extremities portfolios. Smith & Nephew plc occupies a position within the advanced wound management integration tier, bridging post-operative bracing with tissue repair protocols. These three entities represent the prevailing competitive structure where scale-driven procurement leverage confronts specialized clinical application expertise.
| Leading Market Players |
|---|
| Stryker Corporation |
| Arthrex Inc |
| Zimmer Biomet Holdings Inc |
| DePuy Synthes Companies |
| Smith & Nephew plc |
| Acumed LLC |
| Johnson & Johnson |
| Enovis Corp |
| Orthofix Medical Inc |
| Others |
Cost & Logistics Intelligence
Aerospace-grade titanium powder production concentrates in the United States, China, and Japan, feeding directly into implant margin pools where PEEK polymer and carbon fiber composite alternatives command premium positioning against standard titanium fixation systems. Hospital procurement consolidation across Germany's Krankenhausversorgung networks and United States integrated delivery systems compresses pricing power for commoditized bracing while amplifying premiums for surgeon-training-intensive implant platforms.
Pricing Analysis
The customization-premium spread separates patient-specific 3D-printed titanium implants from standard machined fixation systems, with pricing stratifying across premium, standard, and economy tiers driven by FDA 510(k) predicate complexity and ISO 13485 certification grade. Price differentiation hinges on surgeon proctoring bundling and post-operative bracing integration, with ambulatory surgical centers exhibiting highest price sensitivity due to episode-based reimbursement constraints while tier-one academic medical centers absorb premium instrumentation costs.
Supply Chain Analysis
Contract manufacturing capacity for titanium alloy machining rests with specialized orthopedic foundries in Switzerland, Germany, and the United States, with additive manufacturing production lines drawing from aerospace-grade powder suppliers in China and Japan. Raw material dependencies center on titanium sponge, PEEK polymer resin, and carbon fiber prepreg, with single-source vulnerability in high-grade titanium feedstock creating exposure to aerospace sector demand surges. Distribution runs through hospital value analysis committees and GPO contracts rather than individual surgeon preference.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR conformity assessment bottlenecks and 3D printing regulatory precedents are reshaping competitive moats in foot and ankle devices, creating asymmetric expansion windows for firms with established technical documentation systems.
For Market Incumbents: Insulate implant margin pools through captive titanium powder supply agreements and backward integration into PEEK polymer compounding, while accelerating EU MDR technical documentation investments to exploit notified body capacity constraints that strand smaller competitors. Surgeon training ecosystem lock-in and explant service infrastructure defend against additive manufacturing entrants with patient-specific production platforms. For New Entrants and Emerging Players: Brazil's underpenetrated ambulatory surgical center networks and India's expanding orthopedic service lines offer white-space expansion corridors where simplified fixation systems and disposable instrument kits bypass incumbent training infrastructure. Target sports performance applications in Japan's professional baseball medical partnerships, leveraging direct-to-facility distribution to circumvent hospital procurement consolidation. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed extremity specialists possessing FDA 510(k) predicate libraries and established surgeon proctoring networks but lacking EU MDR transition resources. Long-term viability centers on additive manufacturing platform acquisition and smart device data monetization capabilities. Monitor FDA 510(k) clearance velocity and notified body appointment availability as inflection indicators for commercialization timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Notified body capacity constraints favor early movers with complete clinical evidence packages. |
| 3D Printing Platform Acquisition | Patient-specific implant geometries reduce inventory carrying costs and compress lead times versus conventional machining. |
| Ambulatory Surgical Center Partnership | Outpatient procedural migration demands simplified instrumentation kits designed for lower-acuity settings. |
| Smart Device Reimbursement Strategy | Remote patient monitoring integration with CMS pilot programs unlocks recurring revenue streams from diabetic foot ulcer prevention. |
| Titanium Powder Supply Agreement | Aerospace sector competition for high-grade feedstock necessitates captive supply or long-term offtake contracts. |
Research Approach
Operator-level perspectives from orthopedic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers anchored the qualitative base, cross-referenced with FDA 510(k) filings, EU MDR technical documentation submissions, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up demand modeling across implant, bracing, and prosthetic categories triangulated against top-down macroeconomic indicators and demographic projections.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation dimensions spanning product architecture, application setting, end-user purchasing authority, and manufacturing technology maturity. CAGRs derived from historical procedure volume trajectories, reimbursement pathway evolution, and regulatory approval timeline patterns, incorporating additive manufacturing adoption curves and smart device penetration assumptions specific to diabetic foot ulcer prevention protocols.
The forecast holds incumbent behavior within observed patterns; aggressive moves by additive manufacturing pure-plays or technology-enabled new entrants would shift outcomes beyond modeled ranges. Quarterly review of FDA 510(k) clearance velocity, notified body appointment availability, and ambulatory surgical center procedural migration rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Micro Balloon Catheter Market
Medical Devices
Global Cranial and Facial Implants Market
Medical Devices
Ankle Mobile Bearing System Market
Medical Devices
Electroencephalogram (EEG) Caps Market
Medical Devices
United Kingdom Contraceptive Devices Market
Medical Devices
Electronic Nasal Spray Devices Market
Medical Devices
US Neurothrombectomy Devices Market
Medical Devices
Human Anatomy Model Market
Medical Devices
Nasogastric Tube Market
Medical Devices
Critical Care Devices Market
Medical Devices
Eye Drop Dispenser Market
Medical Devices
Australia Ultrasound Devices Market
Medical Devices
Global Cosmetic Implants Market
Medical Devices
Vaginal Pessary Market
Medical Devices
Bronchial Thermoplasty Catheter Market
Medical Devices
Heel Pressure Injury Relieving Devices Market