
 Human Anatomy Model Market | 2026-2036
Human Anatomy Model Market Size, Share, and Industry Trends Forecast 2026-2036
Human Anatomy Model Market Insights
Hospital procurement consortiums is rewriting how anatomy models reach end-users, consolidating purchasing power across multi-institution networks. 3B Scientific GmbH leverages its European manufacturing footprint to sustain direct relationships with university hospitals. Gaumard Scientific Company competes through high-fidelity simulation integration that extends beyond static models into interactive patient simulators. Kyoto Kagaku Co., Ltd. anchors its position in Asian academic markets through specialized hepatobiliary and cardiovascular replicas.
Human anatomy models are three-dimensional physical or digital representations of biological structures, typically constructed from medical-grade plastics, silicone composites, or resin casts with anatomical accuracy measured against Visible Human Project datasets, serving primarily to train clinicians and educate students in structural relationships without cadaveric dissection. Plastic and resin materials dominate current production due to durability requirements and sterilization compatibility in clinical training environments. Virtual models represent the fastest-expanding segment as institutions integrate augmented reality headsets into curricula, while anatomical charts retain stable demand in resource-constrained settings where digital infrastructure remains limited.
The FDA regulates anatomical models used in medical device training under quality system requirements, while the EU Medical Device Regulation mandates CE marking for products supporting clinical skill certification, creating compliance barriers for non-certified manufacturers. ISO 9001 and ISO 13485 certifications increasingly function as gatekeeping standards for institutional procurement tenders across OECD markets. Stakeholders must monitor how accreditation bodies weight digital simulation hours against traditional cadaveric training when revising medical education standards.
Market Dynamics
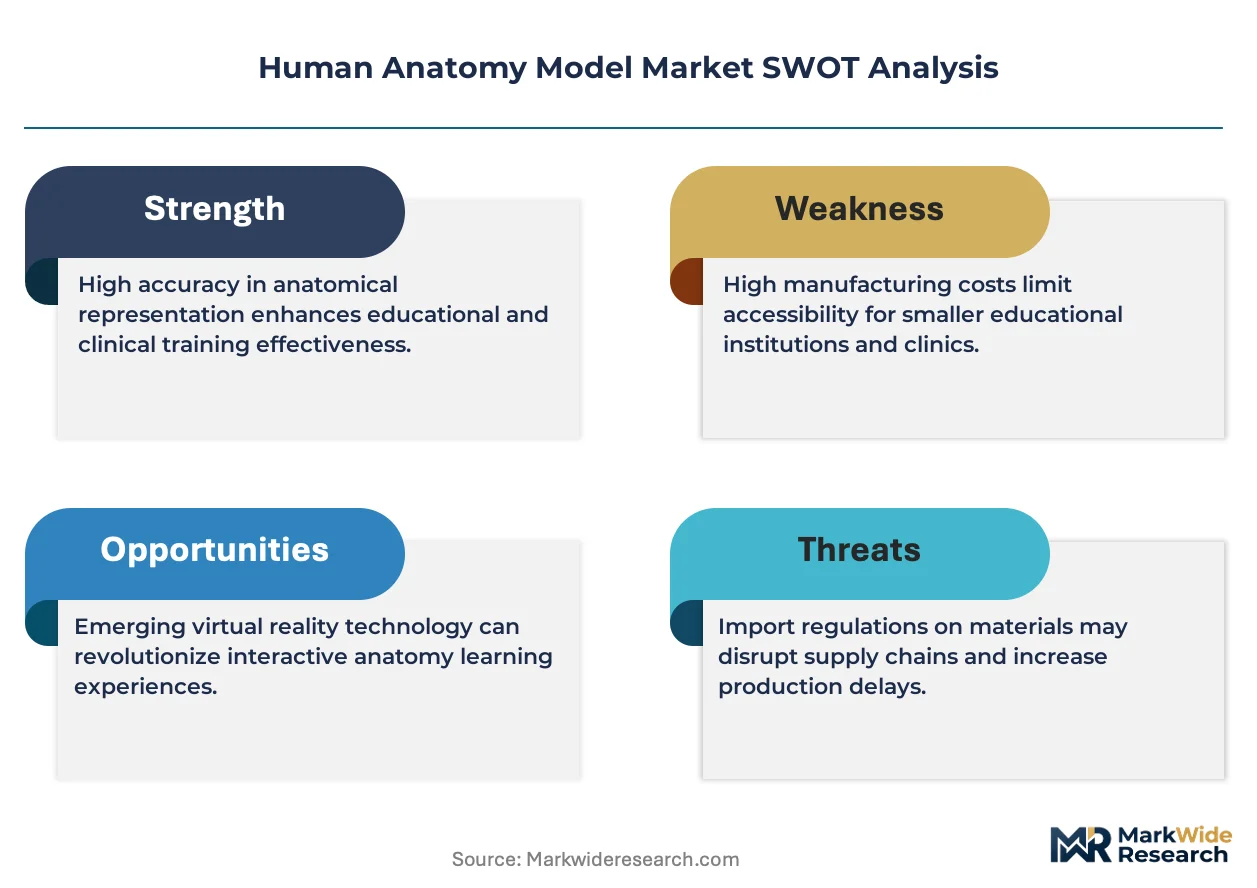
Hospital procurement consortiums are consolidating purchasing power across multi-institution networks, compressing margins for standalone manufacturers while favoring suppliers with ISO 13485 certification and direct distribution infrastructure. This structural shift is redistributing market access toward entities capable of serving centralized tender processes.
Growth Catalysts
- EU Medical Device Regulation:CE marking mandates for clinical skill certification products are institutionalizing quality benchmarks that filter out uncertified competitors, elevating demand for compliant anatomical teaching tools.
- Simulation-based curricula:Medical schools across Germany, the United States, and Japan are expanding hands-on training hours without cadaveric resources, pulling physical and digital anatomy models into core coursework.
- Augmented reality headsets:Hardware cost reductions and curriculum integration are accelerating adoption of virtual anatomy visualization in resource-constrained teaching environments.
Market Restraints
- Medical-grade silicone volatility:Petrochemical feedstock price swings compress margin predictability for manufacturers dependent on elastomeric tissue replicas.
- German manufacturing concentration:Precision instrument traditions cluster specialized production in Baden-Württemberg and Bavaria, creating geographic supply vulnerability.
- Cadaveric specimen availability:Donation program expansions at US academic medical centers present residual substitution pressure for entry-level plastic models.
Strategic Opportunities
- Indian medical education infrastructure:Government allocation increases for new All India Institutes of Medical Sciences campuses are opening tender opportunities for anatomical teaching equipment.
- Wearable haptic feedback convergence:Integration of force-feedback gloves with virtual anatomy platforms creates immersive training modalities beyond static visualization.
- US IRA healthcare workforce provisions:Federal funding for nursing and allied health expansion mandates simulation-based training components, channeling procurement toward certified model suppliers.
Industry Challenges
- ISO 13485 certification timelines:Quality management system audits for medical device training materials extend 12-18 months, delaying market entry for new entrants.
- Legacy cadaveric facility integration:Anatomy departments with existing wet lab infrastructure resist digital platform adoption due to sunk capital and faculty retraining requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Human Anatomy Model Market |
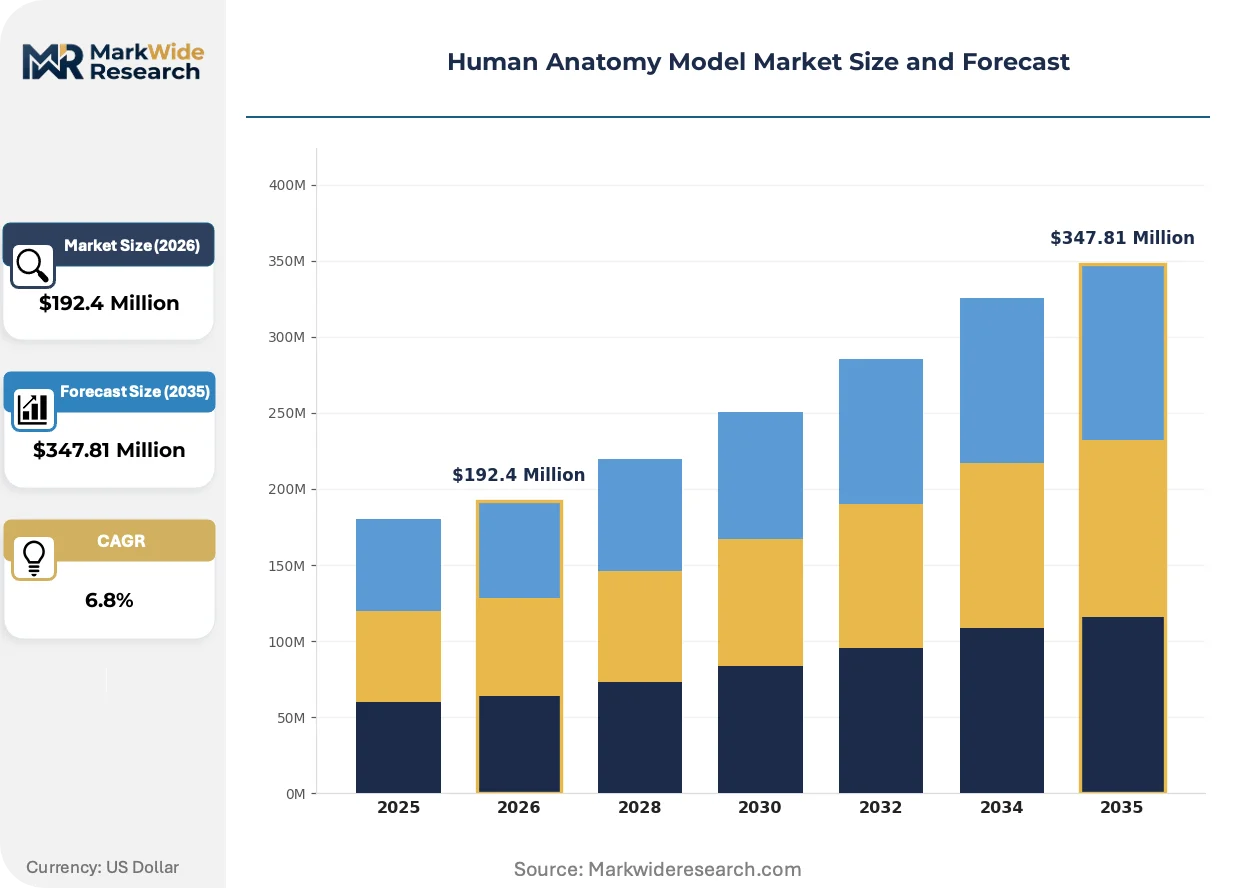
| Market Size in 2026 | $192.4 Million |
| Market Size in 2035 | $347.81 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3D Models, Scale Models, Anatomical Charts, Virtual Models Application: Education, Research, Medical Training, Public Awareness Material: Plastic, Resin, Foam, Metal Delivery Mode: Online Sales, Retail Stores, Direct Sales, Distributors |
| Companies Covered | GPI Anatomicals, Inc., Gaumard Scientific Company, 3B Scientific GmbH, CAE Healthcare Inc., Laerdal Medical AS, Erler-Zimmer GmbH, Limbs & Things Limited, Kyoto Kagaku Co., Ltd., SOMSO Modelle GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Human Anatomy Model Market Trends and Innovations
Augmented reality and haptic simulation are compressing the boundary between physical and digital anatomy instruction, forcing manufacturers to recalibrate product portfolios toward integrated training ecosystems rather than discrete model sales.
Photorealistic volumetric rendering derived from Visible Human Project datasets is virtualizing gross anatomy instruction at US osteopathic and allopathic medical schools. Early adopters include Midwestern academic health centers replacing 30% of cadaveric dissection hours with immersive headset-based exploration. This technology is virtualizing the traditional plastic model value proposition by enabling infinite structural isolation and pathological variation without physical inventory.
The EU Medical Device Regulation's 2021 enforcement is elevating documentation burdens for anatomical models supporting clinical certification. Manufacturers serving European university hospitals must now maintain technical files and post-market surveillance comparable to implantable device suppliers. German and Dutch teaching hospitals are prioritizing CE-marked products in tender evaluations, compressing demand for uncertified educational imports.
Consortium purchasing through multi-institution networks is displacing individual departmental procurement across North American academic medical centers. Buyers in California and Texas health systems now aggregate anatomy model demand through shared services organizations, extracting volume discounts and standardized service terms. This concentration is visible most acutely in replacement cycles for plastic musculoskeletal models, where three-year framework agreements are supplanting annual purchase orders.
Human Anatomy Model Market Segmentation
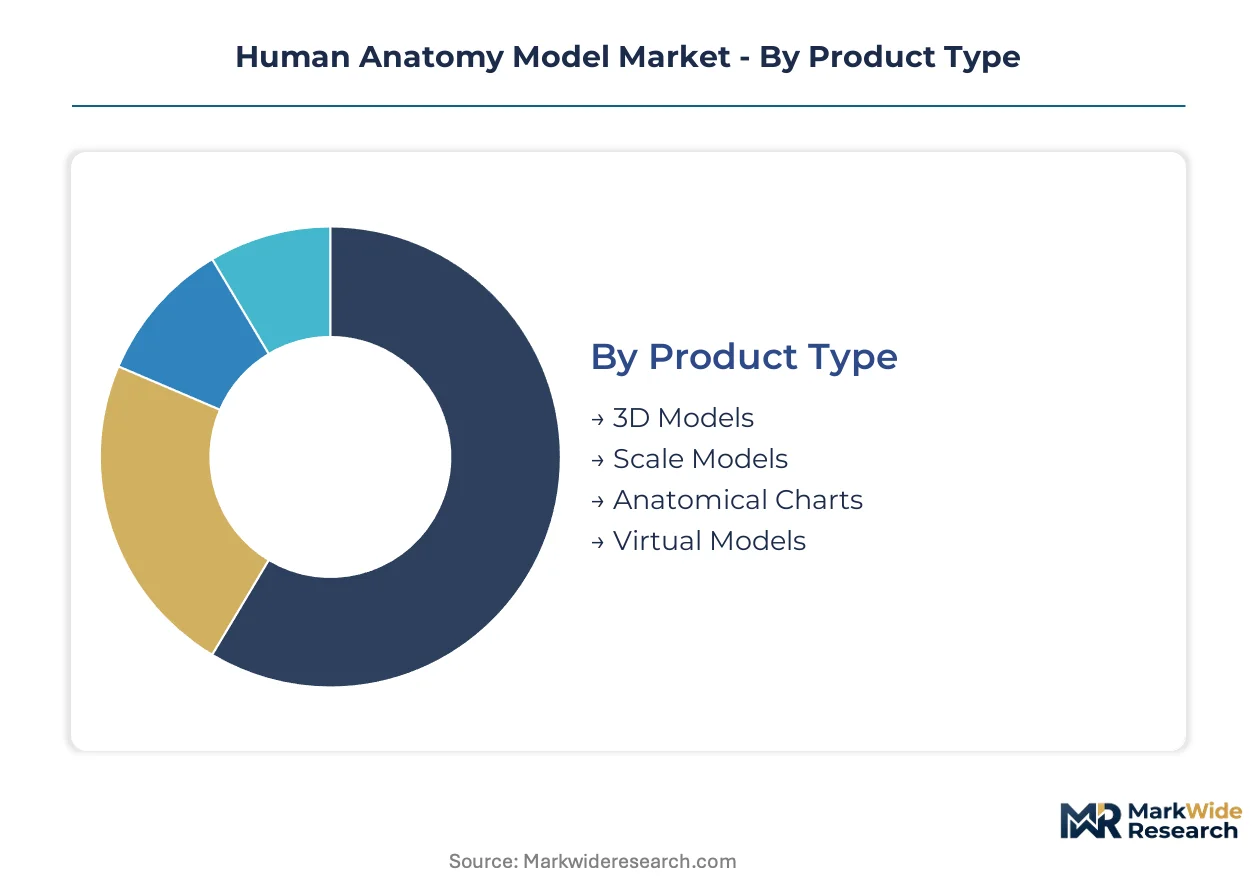
Segmentation in the anatomy model market reveals divergent service intensity requirements across product categories. Educational institutions and clinical training facilities impose distinct durability, accuracy, and certification standards that reshape supplier economics.
Product Type:
After-sales service intensity varies sharply across product categories, with virtual platforms demanding continuous software maintenance while physical models require warranty replacement programs.
- 3D Models:Constructed from medical-grade plastics or silicone composites with anatomical fidelity measured against Visible Human Project datasets. Demand concentrates in German university hospitals expanding simulation-based curricula without cadaveric resources.
- Scale Models:Reduced-dimension replicas targeting secondary education and patient consultation rooms. Demand clusters in US nursing schools where IRA workforce provisions mandate simulation components.
- Anatomical Charts:Two-dimensional reference materials retaining stable demand in resource-constrained Indian medical colleges where digital infrastructure remains limited.
- Virtual Models:Software-based visualization systems with augmented reality integration. These platforms are expanding most quickly as Midwestern US academic health centers replace cadaveric dissection hours with immersive headset-based exploration.
3D models hold the largest share; momentum sits with virtual models.
Application:
Cost tier stratification separates institutional procurement from individual practitioner purchases across use cases.
- Education:Secondary schools and undergraduate biology programs drive volume demand for entry-level plastic musculoskeletal replicas. Indian government allocations for new All India Institutes of Medical Sciences campuses are opening tender opportunities for anatomical teaching equipment.
- Research:Specialized pathological variants and custom fabrication for comparative anatomy studies. Demand localizes at European university hospitals prioritizing CE-marked products under EU Medical Device Regulation enforcement.
- Medical Training:High-accuracy replicas supporting clinical skill certification. US hospital procurement consortiums aggregate demand through shared services organizations, extracting volume discounts.
- Public Awareness:Patient education tools in clinical waiting areas and museum exhibitions. These applications tolerate lower accuracy tolerances than clinical training environments.
Medical training commands premium pricing; education delivers volume scale.
Material:
Supply concentration for medical-grade inputs creates geographic vulnerability in procurement planning.
- Plastic:Durable thermoplastics with sterilization compatibility for clinical training environments. German manufacturers in Baden-Württemberg leverage precision instrument traditions for injection-molded production.
- Resin:High-detail casting materials for fine anatomical features. Petrochemical feedstock price swings compress margin predictability for manufacturers dependent on resin-based tissue replicas.
- Foam:Lightweight, low-cost alternatives for introductory coursework.
- Metal:Skeletal replicas and joint mechanics demonstration models.
Plastic dominates procurement volume; resin captures premium positioning.
Delivery Mode:
Customer type determines channel economics, with institutional buyers demanding direct service relationships.
- Online Sales:E-commerce platforms serving individual students and small practices. These channels face compressed margins from price transparency.
- Retail Stores:Specialty medical supply storefronts with immediate availability for urgent replacement needs.
- Direct Sales:Manufacturer relationships with university hospitals and health system procurement consortiums. 3B Scientific GmbH sustains European market access through this channel structure.
- Distributors:Third-party logistics networks extending geographic reach. Distributor relationships require ISO 13485 documentation transfer for regulatory compliance.
Direct sales secure framework agreements; online channels expand addressable market.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German university hospitals while Indian procurement operates on compressed public-sector budgets. The United States splits between premium-tier academic medical centers and cost-constrained community colleges. Japan maintains mid-tier positioning through specialized hepatobiliary replica demand.
United States
Academic health centers in the Midwest are replacing cadaveric dissection hours with immersive headset-based exploration. The FDA regulates anatomical models used in medical device training under quality system requirements. Hospital procurement consortiums in California and Texas aggregate demand through shared services organizations.
Germany
University hospitals in Baden-Württemberg and Bavaria are expanding simulation-based curricula without cadaveric resources. The EU Medical Device Regulation mandates CE marking for products supporting clinical skill certification. Precision instrument traditions in Stuttgart and Munich cluster specialized manufacturers around injection-molded production.
India
Government allocations for new All India Institutes of Medical Sciences campuses are opening tender opportunities for anatomical teaching equipment. The country's national medical education regulator emphasizes infrastructure standards for simulation-based training. Resource-constrained medical colleges in Uttar Pradesh and Tamil Nadu retain demand for anatomical charts where digital infrastructure remains limited.
Japan
Specialized hepatobiliary and cardiovascular replica demand anchors position in Asian academic markets. The Pharmaceuticals and Medical Devices Agency oversees quality benchmarks for clinical training materials. Tokyo-based academic medical centers integrate augmented reality platforms into traditional anatomy departments.
United Kingdom
Nursing schools are expanding simulation-based training components under workforce development mandates. The Medicines and Healthcare products Regulatory Agency aligns with EU MDR transition timelines for CE-marked products. London teaching hospitals prioritize compliant anatomical imports through centralized procurement frameworks.
Human Anatomy Model Market Competitive Landscape
European precision manufacturers and North American simulation integrators split the market along physical-digital fault lines. Consolidation pressure from hospital procurement consortiums favors entities with ISO 13485 certification and direct distribution infrastructure. Three archetypes dominate: heritage German instrument makers, high-fidelity simulation specialists, and Asian precision replica fabricators. Competitive moves concentrate on M&A for technology licensing and vertical integration into software-hardware bundled offerings.
Within the heritage manufacturing tier, 3B Scientific GmbH and SOMSO Modelle GmbH represent Baden-Württemberg's precision instrument traditions. Kyoto Kagaku Co., Ltd. occupies a position among Asian specialists in organ-specific replicas. Gaumard Scientific Company exemplifies the simulation-integrator archetype bridging physical models into interactive patient systems.
| Leading Market Players |
|---|
| GPI Anatomicals, Inc. |
| Gaumard Scientific Company |
| 3B Scientific GmbH |
| CAE Healthcare Inc. |
| Laerdal Medical AS |
| Erler-Zimmer GmbH |
| Limbs & Things Limited |
| Kyoto Kagaku Co., Ltd. |
| SOMSO Modelle GmbH |
| Others |
Pricing and Supply Chain Analysis
Rhine-Alpine corridor freight rates from Rotterdam to Basel shape margin structures for German manufacturers exporting CE-marked anatomy models, compressing delivered pricing power for Baden-Württemberg suppliers while amplifying cost advantages for Asian competitors serving Indian medical colleges through maritime routes.
Pricing Analysis
Configured-to-order pricing for custom pathological replicas commands 40-60% premiums over standard plastic musculoskeletal models. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified clinical training tools from entry-level educational imports. Cost compression in standard plastic segments is intensifying because hospital procurement consortiums extract volume discounts through multi-year framework agreements. Community colleges and secondary education programs exhibit highest price sensitivity, while German university hospitals prioritize certification grade over unit cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for resin-based component sourcing. Manufacturing concentrates in Germany, China, and Japan, with Baden-Württemberg precision instrument clusters anchoring European production. Petrochemical feedstock volatility for medical-grade silicone and epoxy resins rests on naphtha cracking capacity in Northeast Asia. Distribution runs through hospital procurement consortiums and direct manufacturer relationships with university hospitals, displacing traditional medical supply distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face sustained substitution pressure from photorealistic volumetric rendering platforms that virtualize cadaveric dissection without physical inventory, forcing defensive portfolio repositioning.
For Market Incumbents: Pre-empt virtual platform encroachment by bundling haptic feedback hardware with legacy physical model lines, while securing ISO 13485 certification ahead of EU MDR enforcement waves. Backward integration into medical-grade silicone compounding in Stuttgart industrial zones defends margin position against petrochemical volatility. Channel control through direct university hospital relationships resists procurement consortium pricing pressure. For New Entrants and Emerging Players: White-space opportunity in Indian All India Institutes of Medical Sciences tender processes represents the most penetrable entry point, where public-sector budget constraints favor cost-optimized anatomical charts and plastic models over premium European imports. Wearable haptic feedback convergence for virtual anatomy platforms offers uncrowded positioning against established simulation integrators. Go-to-market execution should anchor on distributor partnerships with ISO 13485 documentation transfer capability. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with dormant medical education divisions holding CE-marked product lines and dormant European distribution infrastructure. Long-term viability hinges on software-hardware bundled offering development rather than discrete model manufacturing. Signal to watch: accreditation body rulings on digital simulation hour equivalence against traditional cadaveric training requirements.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | EU MDR technical file preparation opens German university hospital procurement channels before competitors complete audits. |
| Hospital System Partnership | Multi-year framework agreements with California and Texas shared services organizations lock in replacement cycle visibility. |
| Software Companion Development | AR headset integration with physical model lines defends against pure-play virtual platform substitution. |
| Backward Integration into Silicone Compounding | Captive supply of medical-grade elastomers insulates margin from petrochemical feedstock volatility. |
| Reimbursement Strategy Alignment | US IRA workforce provision compliance channels federal simulation training funding toward certified suppliers. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with hospital procurement managers, biomedical engineering faculty, GPO contracts specialists, and medical device regulatory affairs leads; and secondary validation through FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement tender records, and trade flow data from German and Dutch customs authorities. Bottom-up demand modeling triangulated against top-down market sizing from medical education institution counts and simulation lab capital expenditure disclosures.
Forecast inputs span product type segmentation across physical and virtual platforms, application tiers from secondary education through clinical certification, material grade stratification, and delivery mode channel economics across the analysis window. CAGRs derive from enrollment projections at accredited medical schools, government healthcare workforce expansion mandates, and hardware cost reduction curves for AR visualization equipment. Modeled variables include cadaveric specimen availability trends and accreditation body simulation hour equivalence rulings.
Practitioners should monitor EU MDR enforcement consistency, US academic medical center donation program expansions, and Indian medical education infrastructure allocation cycles for early signals of forecast deviation. Material shifts in regulatory equivalence standards between digital and physical training modalities would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Meniscal Rasps Market
Medical Devices
Handheld Ultrasound Devices Market
Medical Devices
Italy Medical Device Regulatory Affairs Market
Medical Devices
Global Lenses for Myopia Control Market
Medical Devices
United States Insulin Pumps Market
Medical Devices
Global Breast Pumps Market
Medical Devices
Spinal Trauma Devices Market
Medical Devices
Asia-Pacific Wearable Medical Devices Market
Medical Devices
Buccal Cavity Devices Market
Medical Devices
Lower Limb Prosthetics Market
Medical Devices
North America Electric Wheelchair Market
Medical Devices
Electroencephalography Systems/Devices Market
Medical Devices
Phototherapy Lamps Market
Medical Devices
South Korea Drug Delivery Devices Market
Medical Devices
Spinal Cord Stimulators Market
Medical Devices
Bronchial Thermoplasty Catheter Market