
 Micro Balloon Catheter Market | 2026-2036
Micro Balloon Catheter Market Size, Share, and Industry Trends Forecast 2026-2036
Micro Balloon Catheter Market Foresight
Interventional cardiologist shortages across tertiary hospitals is unwinding procedure throughput in several OECD markets. Medtronic plc leverages its integrated catheter manufacturing footprint to sustain supply continuity for high-volume balloon platforms. Boston Scientific Corporation competes through specialized drug-eluting balloon portfolios that anchor its interventional cardiology division.
A micro balloon catheter is a slender, flexible tube with an inflatable distal tip typically manufactured from polyether block amide or nylon composites, designed to dilate stenosed vessels or deploy stents during minimally invasive procedures. Its primary commercial purpose centers on restoring luminal patency while minimizing vascular trauma in percutaneous coronary and peripheral interventions. Inflatable product types dominate current revenue pools due to their established reimbursement pathways, while drug-eluting technology segments capture expanding margin pools as antiproliferative coating formulations advance through clinical validation. Cardiology applications maintain the largest installed base, though radiology-guided interventions represent the fastest-growing demand channel as embolization procedures multiply.
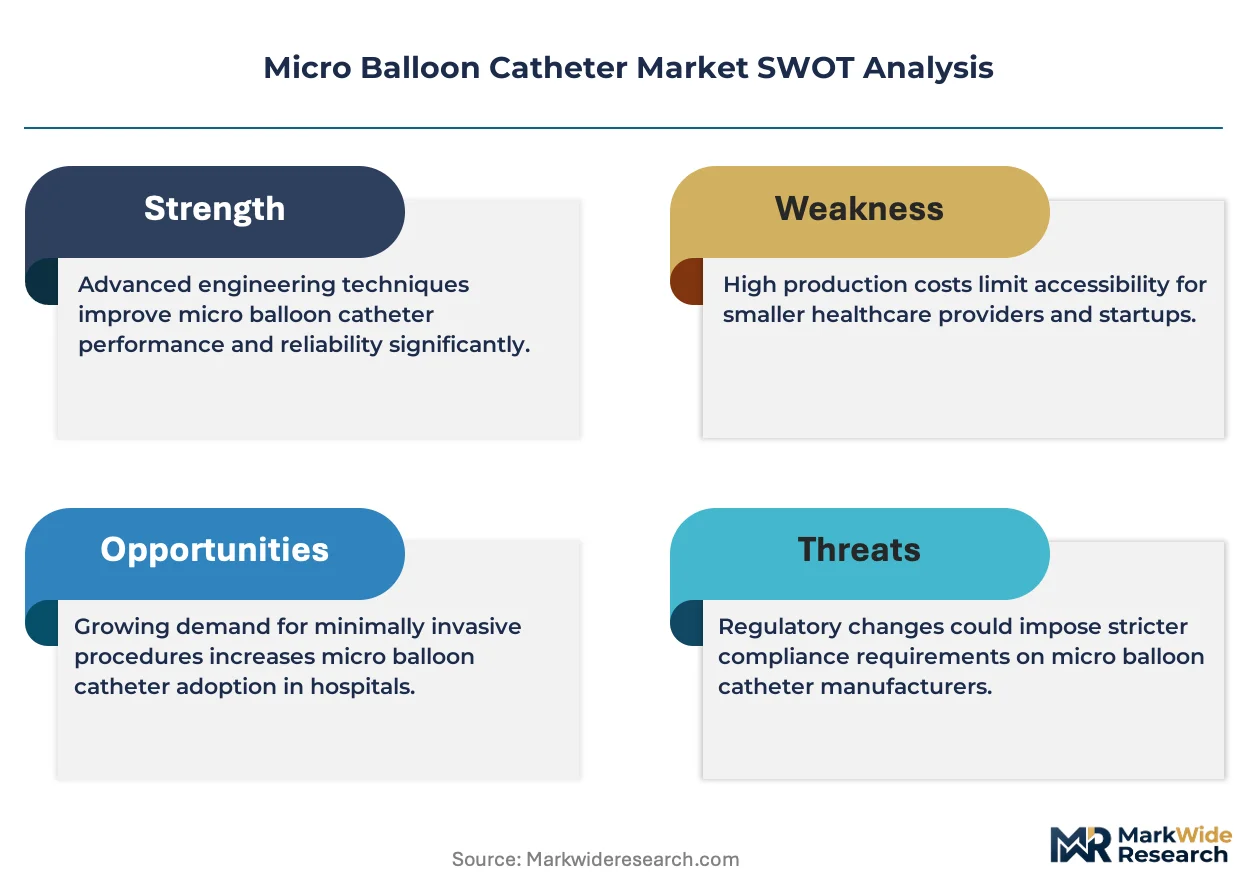
FDA premarket notification pathways and the EU Medical Device Regulation impose escalating biocompatibility and sterility validation burdens on balloon catheter manufacturers seeking market access. Japan's PMDA maintains distinct clinical data requirements that shape product registration timelines and regional launch sequencing. Stakeholders must monitor evolving notified body capacity constraints under MDR implementation and calibrate regulatory submission strategies accordingly.
Market Dynamics
The EU Medical Device Regulation's biocompatibility validation requirements are compressing product development timelines and forcing manufacturers to restructure notified body engagement strategies before market access.
Growth Catalysts
- Japan's catheterization laboratory expansion:Specialized interventional cardiology networks in tertiary hospitals are amplifying procedural throughput for minimally invasive vessel dilation.
- Drug-eluting coating advances:Antiproliferative formulation improvements are expanding margin pools in balloon platforms as clinical validation progresses through regulatory pathways.
- PMDA clinical data requirements:Distinct Japanese registration timelines are shaping regional launch sequencing that prioritizes high-value markets first.
Market Restraints
- Polyether block amide supply concentration:Specialty polymer feedstock dependence on limited European and Asian chemical suppliers creates input cost volatility.
- Notified body capacity constraints:MDR implementation bottlenecks are extending sterility validation timelines for manufacturers seeking CE marking.
- Interventional cardiologist shortages:Tertiary hospital staffing gaps across OECD markets are capping procedure volume expansion regardless of device availability.
Strategic Opportunities
- Radiology-guided embolization procedures:Peripheral vascular interventions outside cardiology represent the fastest-growing installed base for balloon catheter deployment.
- Integrated catheter manufacturing:In-house production of nylon composite balloon platforms enables supply continuity during external disruption events.
- FDA premarket notification alignment:Streamlined biocompatibility documentation pathways reward early regulatory strategy investment with accelerated market entry.
Industry Challenges
- Legacy catheterization laboratory integration:New balloon platforms require compatibility verification with existing imaging and deployment systems, extending sales cycles.
- Sterility validation workforce scarcity:Qualified personnel for MDR-compliant documentation are concentrated among specialized regulatory consultancies, inflating compliance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Micro Balloon Catheter Market |
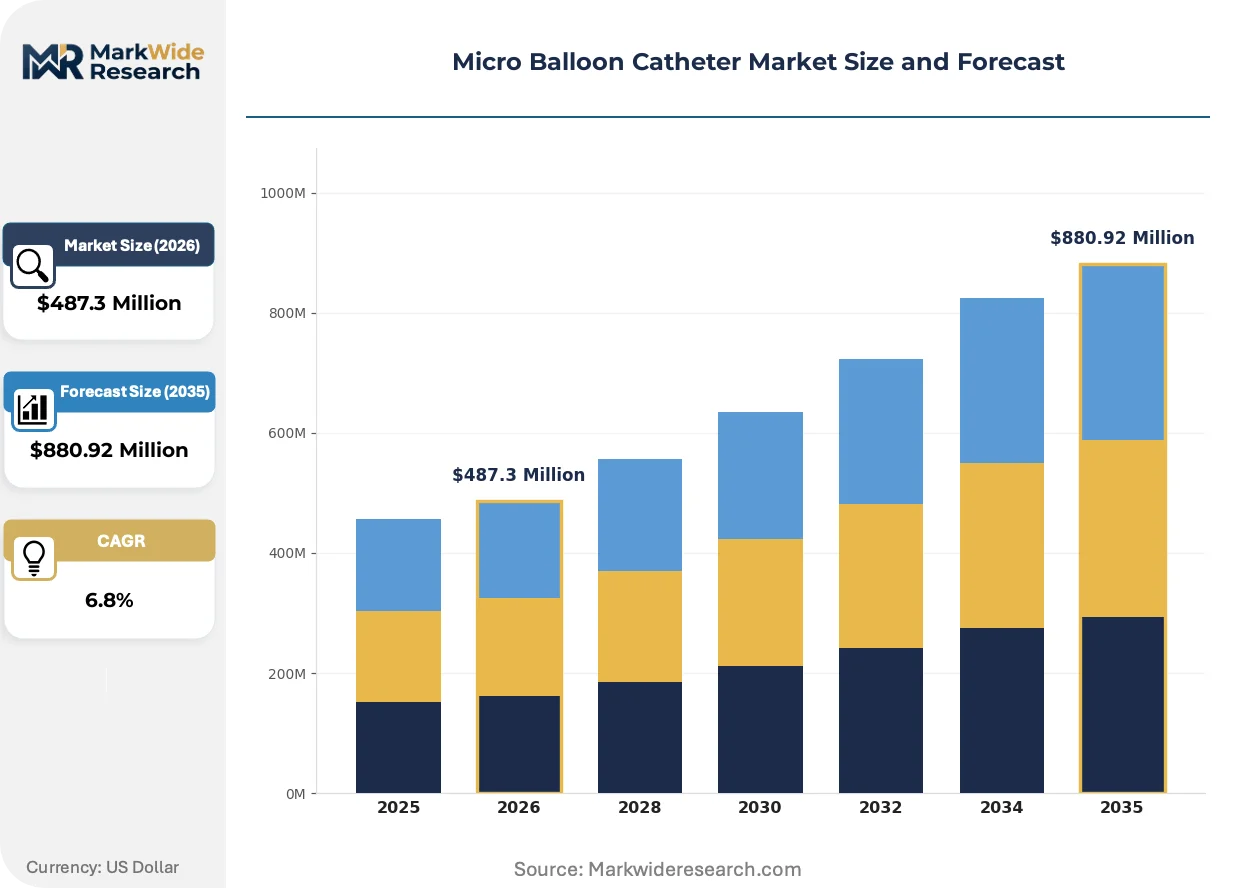
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inflatable, Non-Inflatable, Coated, Custom Technology: Drug-Eluting, Standard, Biodegradable, Biocompatible End User: Hospitals, Surgical Centers, Clinics, Diagnostic Labs Application: Cardiology, Radiology, Urology, Gastroenterology |
| Companies Covered | Medtronic plc, Boston Scientific Corporation, Stryker Corporation, Terumo Corporation, Cook Medical, B. Braun Melsungen AG, Cardinal Health, Abbott Laboratories, Teleflex Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Micro Balloon Catheter Market Shifts & Advancements
Balloon catheter technology is converging with advanced coating chemistry and digital navigation systems, reshaping how manufacturers differentiate beyond basic luminal dilation capability.
Drug-eluting balloon technology is supplanting bare-metal platforms in coronary interventions. Interventional cardiologists in German and Japanese tertiary hospitals are transitioning procurement preferences toward antiproliferative-coated devices. The shift is compressing margins for conventional inflatable balloons while elevating technical barriers to competitive entry.
MDR biocompatibility testing mandates are extending validation timelines for all balloon catheter submissions. Manufacturers must now document particle release profiles and endothelial interaction data beyond prior CE marking requirements. High-volume platform producers with established notified body relationships are absorbing these costs more efficiently than mid-tier competitors.
Hospital procurement committees are consolidating vendor relationships around full interventional cardiology portfolios rather than single-device contracts. Cardiac catheterization laboratories in United States health systems are reducing supplier counts to simplify inventory management and service agreements. This concentration rewards integrated device manufacturers with broad balloon, stent, and guidewire offerings while marginalizing specialized single-product vendors.
Micro Balloon Catheter Market Segmentation
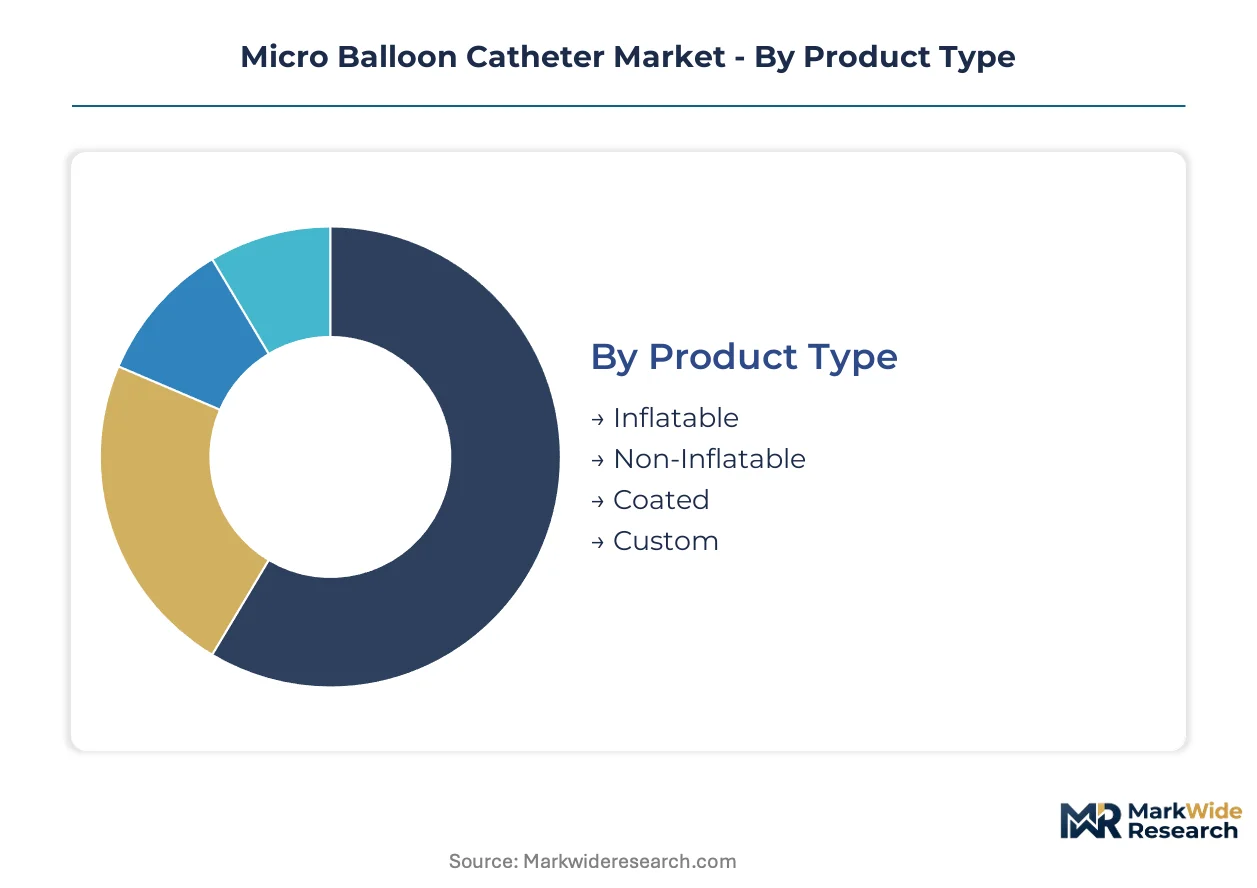
Micro balloon catheter manufacturers structure product portfolios around procedural specificity and reimbursement pathways. Segment boundaries determine pricing architecture, regulatory submission strategies, and sales force deployment across interventional specialties.
Product Type:
Margin pools concentrate in coated platforms where antiproliferative formulations command premium positioning against commodity inflatable alternatives.
- Inflatable:Polyether block amide or nylon composite balloons dominate procedural volumes through established 510(k) pathways and broad cath lab compatibility. Demand clusters in United States tertiary hospitals expanding interventional cardiology programs, though supply concentration in European and Asian polymer feedstocks creates input cost volatility.
- Coated:Drug-eluting surfaces incorporating paclitaxel or sirolimus analogues target restenosis prevention in complex lesions. Japanese PMDA clinical data requirements and FDA premarket notification burdens extend development timelines, but reimbursement premiums justify investment for manufacturers with integrated coating capabilities.
- Non-Inflatable:Fixed-diameter platforms serve specialized diagnostic and drainage applications where balloon expansion risks tissue trauma.
- Custom:Patient-specific geometries and proprietary shaft configurations address congenital anomalies or revision procedures in high-volume academic medical centers.
The dominant share belongs to Inflatable platforms, while Coated variants are gaining share fastest as antiproliferative evidence accumulates in coronary registries.
Technology:
Technology tiering separates validated clinical platforms from developmental categories still navigating biocompatibility validation frameworks.
- Drug-Eluting:Antiproliferative coating chemistry from German and Japanese manufacturers is displacing bare-metal platforms in coronary interventions. Tertiary hospital procurement committees in these markets prioritize drug-eluting inventories for de novo lesions, compressing margins for conventional alternatives while elevating technical barriers to entry.
- Standard:Unmodified polymeric balloons maintain installed base in cost-sensitive peripheral and diagnostic applications where reimbursement does not differentiate coating status.
- Biodegradable:Absorbable balloon materials and transient scaffolds remain in clinical validation, with MDR biocompatibility documentation requirements extending European market access timelines.
- Biocompatible:Enhanced endothelial interaction profiles and reduced thrombogenicity claims require particle release testing under FDA and notified body protocols, concentrating development resources among established manufacturers.
Drug-Eluting technology captures the steepest expansion trajectory, though Standard platforms retain volume leadership in peripheral vascular segments.
End User:
Customer type determines service intensity, inventory management requirements, and contract structure complexity.
- Hospitals:Tertiary cardiac catheterization laboratories in the United States, Germany, and Japan generate the majority of procedural throughput. These facilities demand 24-hour technical support, consignment inventory arrangements, and compatibility verification with existing imaging systems.
- Surgical Centers:Ambulatory settings concentrate in elective peripheral and diagnostic procedures where same-day discharge protocols favor streamlined balloon platforms.
- Clinics:Office-based interventions for urology and gastroenterology applications require compact, single-use configurations with simplified sterilization logistics.
- Diagnostic Labs:Imaging-guided biopsy and drainage procedures utilize smaller-diameter balloons with enhanced radiopacity for precision placement.
Hospitals command the dominant procurement volume, while Surgical Centers are expanding most quickly as ambulatory payment reforms accelerate site-of-service migration.
Application:
Clinical specialty boundaries shape regulatory strategy, clinical evidence requirements, and specialist sales force deployment.
- Cardiology:Percutaneous coronary and structural interventions represent the largest installed base, with drug-eluting balloons supplanting bare-metal platforms in German and Japanese tertiary hospitals. Interventional cardiologist shortages across OECD markets nonetheless cap procedural expansion regardless of device availability.
- Radiology:Embolization, angioplasty, and drainage guidance procedures outside cardiology constitute the fastest-climbing demand channel. United States health system consolidation around integrated interventional radiology networks amplifies procurement concentration.
- Urology:Stricture dilation and stone extraction applications require specialized balloon compliance profiles and hydrophilic coating formulations.
- Gastroenterology:Biliary and esophageal interventions utilize longer shaft configurations and higher burst pressure ratings for luminal patency restoration.
Cardiology maintains volume leadership, though Radiology is closing the gap fastest as embolization procedure volumes multiply across specialized laboratory networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA premarket notification requirements anchor the United States as the procedural volume leader, while Japan's PMDA and Europe's MDR reshape competitive entry sequencing across developed markets. Regulatory divergence is fragmenting launch timelines and concentrating investment in jurisdictions with established reimbursement pathways.
United States
Tertiary cardiac catheterization laboratories in Cleveland Clinic and Mayo Clinic networks are expanding interventional cardiology throughput. FDA 510(k) clearance pathways for polyether block amide balloons maintain predictable market access timelines. Boston Scientific and Medtronic manufacturing clusters in Minnesota and Massachusetts sustain supply continuity for high-volume platforms.
Germany
University hospital networks in Munich and Heidelberg are transitioning procurement toward drug-eluting balloon inventories for complex coronary lesions. EU MDR biocompatibility validation requirements are compressing product development timelines for notified body submissions. Baden-Württemberg medical technology clusters concentrate coating chemistry capabilities for antiproliferative formulations.
Japan
Specialized catheterization laboratory expansion in Tokyo and Osaka tertiary hospitals is amplifying procedural volumes for minimally invasive vessel dilation. PMDA clinical data requirements mandate distinct registration timelines that shape regional launch sequencing. Nagoya-based manufacturing operations supply nylon composite platforms for domestic and Asia-Pacific distribution.
United Kingdom
NHS procurement consolidation around integrated interventional cardiology portfolios is reducing supplier counts for cardiac catheterization laboratories. MHRA post-Brexit regulatory alignment with MDR frameworks extends sterility validation documentation requirements. London and Cambridge medical device clusters focus on biocompatibility testing services for balloon catheter submissions.
India
Corporate hospital chains in Mumbai and Delhi are installing specialized catheterization laboratories to capture domestic cardiac procedure demand. CDSCO medical device registration pathways are tightening import quality standards for balloon catheter platforms. Gujarat pharmaceutical and polymer processing clusters are developing domestic polyether block amide feedstock capabilities.
Micro Balloon Catheter Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with market structure consolidating around full interventional cardiology portfolio vendors. Tier-one participants command hospital procurement committee relationships through bundled balloon, stent, and guidewire offerings. Three strategic archetypes dominate: integrated multinationals with captive manufacturing, mid-tier specialists with coating technology differentiation, and regional fabricators serving price-sensitive peripheral segments. Competitive moves center on backward integration into polymer feedstock supply and strategic partnerships with academic medical centers for clinical validation.
Among integrated multinational participants, Medtronic plc and Boston Scientific Corporation exemplify the tier-one archetype through established catheterization laboratory relationships. Terumo Corporation occupies a distinct position within the Asia-Pacific manufacturing vector. Stryker Corporation represents the orthopedic-to-interventional diversification pattern visible among diversified medtech conglomerates.
| Leading Market Players |
|---|
| Medtronic plc |
| Boston Scientific Corporation |
| Stryker Corporation |
| Terumo Corporation |
| Cook Medical |
| B. Braun Melsungen AG |
| Cardinal Health |
| Abbott Laboratories |
| Teleflex Incorporated |
| Others |
Supply & Pricing Matrix
Scale economies in polyether block amide polymerization anchor cost floors for balloon catheter manufacturers, concentrating margin leverage among high-volume producers with captive nylon composite extrusion capacity. United States tertiary hospital procurement committees exploit this concentration through volume-based contracting that compresses per-unit pricing for standard inflatable platforms while preserving premiums for drug-eluting configurations.
Pricing Analysis
Geographic price spreads separate United States reimbursement premiums from European tender-based compression and Japanese PMDA-validated positioning. Three-tier pricing structure across drug-eluting, standard inflatable, and diagnostic economy levels reflects coating chemistry differentiation and clinical evidence depth. Pricing pressure stems from hospital procurement consolidation around full interventional cardiology portfolios that bundle balloons with stents and guidewires. Surgical centers exhibit highest price sensitivity due to ambulatory payment reform constraints, while academic medical centers prioritize clinical outcomes over per-unit cost.
Supply Chain Analysis
Strategic stockpiling of polyether block amide feedstock distinguishes integrated manufacturers from just-in-time dependent competitors facing European and Asian polymer supplier lead time volatility. Supply concentration rests on Germany, Japan, and United States for specialty polymer compounding and balloon forming equipment. Raw material dependencies include polyether block amide resins, nylon 12 composites, and platinum-iridium marker bands. Single-source vulnerability in European chemical feedstock channels creates disruption exposure. Distribution runs through hospital GPO contracts and direct cath lab consignment arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Micro balloon catheter platforms are approaching an interoperability inflection where drug-eluting coating chemistry and digital navigation integration determine ecosystem lock-in. Hospital procurement committees increasingly favor vendors with full interventional cardiology portfolios over single-device suppliers.
For Market Incumbents: Consolidate backward integration into polyether block amide polymer supply to defend margin position against feedstock cost volatility. Deepen notified body relationships under EU MDR to accelerate biocompatibility validation timelines relative to mid-tier competitors. Prioritize coating chemistry R&D partnerships with German and Japanese academic medical centers to sustain drug-eluting platform leadership.
For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for biodegradable balloon materials offer regulatory differentiation against established drug-eluting portfolios. Target radiology-guided embolization procedures as the fastest-growing application channel with lower incumbent concentration than cardiology. Deploy software companion development for imaging system integration as the primary go-to-market angle.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated manufacturers with captive polymer processing and established hospital GPO contracts. Long-term viability hinges on coating chemistry IP depth and regulatory submission capacity rather than device commoditization exposure. Watch PMDA approval velocity for biodegradable platforms as the signal indicating platform shift timing.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR biocompatibility documentation accelerates European market access for notified body-preferred manufacturers. |
| Hospital System Partnership | Consignment inventory arrangements with Cleveland Clinic and Mayo Clinic networks anchor United States volume. |
| Software Companion Development | Imaging system integration with Siemens and GE Healthcare platforms differentiates navigation-enabled balloons. |
| Backward Integration | In-house polyether block amide compounding insulates margin from European chemical supplier concentration. |
| Reimbursement Strategy | CMS coding alignment for drug-eluting balloons secures premium positioning in United States health systems. |
Research Methodology
A standing panel of interventional cardiologists, cath lab purchasing committee chairs, biomedical engineers, and GPO contracts managers provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with hospital procurement stakeholders and secondary validation against FDA 510(k) filings, PMDA approval databases, CMS Medicare reimbursement schedules, and hospital capital expenditure disclosures. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue segmentation.
Consistency checks validated volume and value outputs against external benchmarks including notified body submission timelines and polymer feedstock trade data. The analytical framework modeled product type, technology tier, end user facility class, and application specialty across the projection horizon. CAGRs derived from procedural throughput expansion rates, reimbursement trajectory assumptions, and technology substitution curves. Forecast inputs incorporated interventional cardiologist workforce projections and catheterization laboratory installation pipelines.
Underlying assumptions cover MDR implementation pacing, PMDA clinical data requirements, and polymer supply continuity, with deviation risk concentrated in notified body capacity constraints and cardiologist shortage severity. Revision becomes warranted when drug-eluting balloon reimbursement thresholds or biodegradable platform approval velocity crosses material thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Trial Prostheses Market
Medical Devices
Electrocardiograph (ECG) Market
Medical Devices
Global Colposcopy Devices Market
Medical Devices
Digital Ureteroscopes Market
Medical Devices
North America Sperm Separation Devices Market
Medical Devices
Europe Biopsy Devices Market
Medical Devices
Global Micro Guide Catheters Market
Medical Devices
Phlebotomy Equipments Market
Medical Devices
Dry Eye Treatment Devices Market
Medical Devices
Organ Care Market
Medical Devices
Hearing Aid with Lithium-Ion Battery Market
Medical Devices
Global Wearable Pregnancy Devices Market
Medical Devices
Rechargeable Medical Battery Market
Medical Devices
Pannus Retraction Device Market
Medical Devices
Embryo Transfer Catheters Market
Medical Devices
Cardiac Catheters and Guidewires Market