
 Orthopedic Devices Market | 2026-2036
Orthopedic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Orthopedic Devices Market Analysis
EU MDR is consolidating the cost-of-entry calculus for orthopedic device manufacturers, forcing smaller firms to absorb substantial conformity assessment expenses or exit European markets entirely. Stryker Corporation leverages its scale to navigate notified body bottlenecks, while Zimmer Biomet Holdings, Inc. sustains broad portfolio breadth across joint reconstruction and spine. Johnson & Johnson MedTech anchors its position through deep hospital system relationships and integrated digital surgery platforms.
Orthopedic devices comprise implantable and non-implantable instruments engineered from titanium alloys, cobalt-chrome, and ultra-high molecular weight polyethylene to restore musculoskeletal function following trauma, degeneration, or deformity. Joint replacement represents the most mature revenue pool, with established pricing benchmarks and concentrated supplier power, while smart implants and robotics command premium positioning as hospitals seek differentiation through surgical precision and post-operative monitoring capabilities.
FDA, EMA, and ISO 13485 collectively govern design controls, clinical evidence requirements, and quality management systems that determine market access timelines and commercial launch feasibility. These frameworks elevate R&D spending thresholds and compress margins for firms lacking regulatory infrastructure. Stakeholders must weigh capital allocation between robotics-enabled surgical ecosystems and bioresorbable fixation platforms as the next cycle of product differentiation takes shape.
Market Dynamics
Ambulatory surgical centers are capturing orthopedic procedure volume as CMS reimbursement policies tilt toward outpatient settings, compressing hospital inpatient revenue pools and forcing capital redeployment toward same-day surgery infrastructure.
Growth Catalysts
- CMS outpatient payment expansion:Medicare reimbursement parity for total joint replacement in ambulatory settings accelerates ASC capital investment in dedicated orthopedic suites.
- Titanium additive manufacturing:3D-printed patient-specific implants reduce revision rates and operating room time, commanding premium pricing from high-volume orthopedic service lines.
- Germany:Statutory health insurance coverage for robotic-assisted knee arthroplasty creates predictable demand for navigation-enabled surgical systems.
Market Restraints
- Cobalt-chrome powder supply:Aerospace sector competition for vacuum-induction-melted feedstock concentrates pricing power with three specialty alloy producers.
- EU MDR clinical evidence requirements:Legacy implant predicates lose validity, forcing costly PMCF studies or portfolio rationalization for mid-tier manufacturers.
- Motion-preserving alternatives:Cervical disc arthroplasty and subchondral bone drilling procedures displace fusion hardware in select spine and joint applications.
Strategic Opportunities
- Brazil:ANVISA's accelerated pathway for breakthrough orthopedic devices opens access to private hospital networks in São Paulo and Rio de Janeiro.
- Sensor-integrated implants:Convergence of load-bearing PEEK constructs with wireless strain monitoring creates post-operative telemetry revenue streams.
- Direct-to-ASC distribution:Implant consignment models bypass traditional hospital purchasing committees, shortening sales cycles for high-volume outpatient centers.
Industry Challenges
- Biomechanical simulation talent:Finite element analysis expertise for patient-specific implant design concentrates in academic medical centers and specialized software firms.
- ISO 13485:2016 transition:Notified body audit backlogs delay quality management system recertification, freezing new product submissions for certificate-dependent manufacturers.
- Legacy EMR integration:Robotic surgical platforms require proprietary data architectures that conflict with hospital IT standardization mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orthopedic Devices Market |
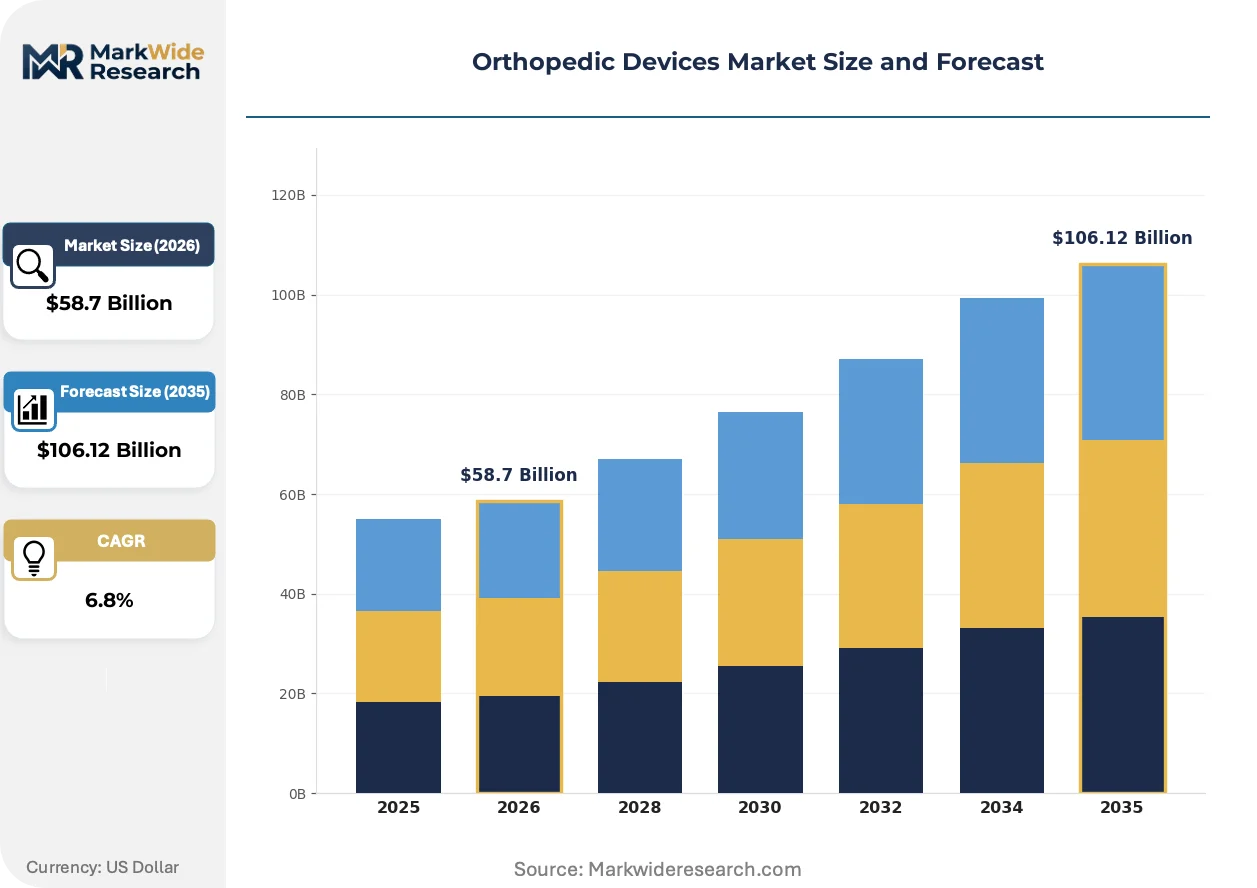
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $106.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Joint Replacement, Spine Devices, Trauma Fixation, Orthobiologics Application: Surgery, Rehabilitation, Pain Management, Injury Recovery Technology: 3D Printing, Wireless Monitoring, Smart Implants, Robotics End User: Hospitals, Ambulatory Surgical Centers, Rehabilitation Clinics, Home Care |
| Companies Covered | Stryker Corporation, Zimmer Biomet Holdings, Inc., Johnson & Johnson MedTech, Smith+Nephew, Medtronic, DePuy Synthes, Arthrex, Inc., Globus Medical, B. Braun, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orthopedic Devices Market Emerging Trajectories
Orthopedic device development is pivoting from mechanical durability to data-enabled performance, with implantable sensors and surgical robotics creating new value capture mechanisms beyond hardware margins.
Smart implant technology is consolidating clinical decision-making around real-time biomechanical feedback. Load-sensing tibial trays and instrumented spinal rods transmit gait and fusion data to cloud-based monitoring platforms. High-volume orthopedic groups in the United States are piloting these devices to reduce costly revision surgeries. The technology is consolidating surgeon preference around vendors capable of delivering integrated hardware-software ecosystems rather than standalone implants.
FDA's 510(k) modernization program is tightening predicate device requirements for implantable hardware. The agency now demands direct comparison to devices less than ten years old, invalidating many historical clearance pathways. Small and mid-sized manufacturers face compressed timelines to generate new clinical evidence or abandon product lines. Spine and extremity fixation categories are experiencing the most significant regulatory friction as legacy predicates expire.
Hospital purchasing committees are unbundling implant costs from procedural episode payments. Bundled payment mandates from commercial payers in the United States are forcing orthopedic service lines to scrutinize implant spend as a discrete cost center. This behavior is most pronounced in Medicare Advantage markets where gainsharing arrangements align surgeon and hospital incentives around total episode cost. Device vendors are responding with volume-commitment pricing and inventory management guarantees to defend account relationships.
Orthopedic Devices Market Segmentation
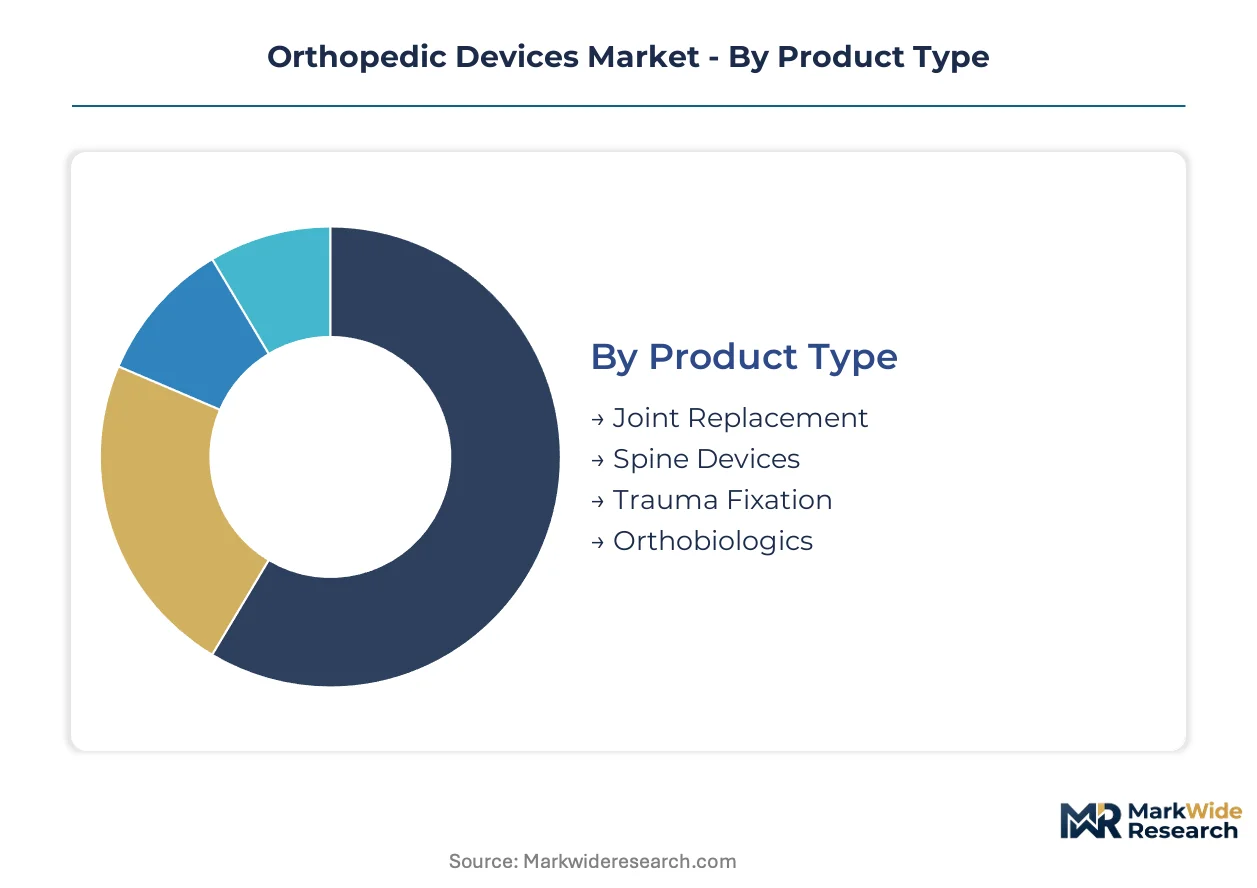
Orthopedic device segmentation reveals divergent capital requirements and margin profiles across hardware, biologics, and digital platforms. Manufacturers must calibrate portfolio depth against the specific regulatory burdens and reimbursement pathways governing each category.
Product Type:
Joint replacement platforms demand the heaviest upfront investment in sterile manufacturing infrastructure, clinical trial networks, and long-term implant registries.
- Joint Replacement:Titanium and cobalt-chrome constructs for hip, knee, and shoulder arthroplasty require Class III PMA pathways in the United States and extensive PMCF commitments under EU MDR. Demand concentrates in high-volume academic medical centers where bundled payment contracts align surgeon and hospital incentives around implant cost efficiency.
- Spine Devices:Pedicle screw systems, interbody cages, and motion-preserving discs incorporate PEEK and titanium alloys with precision-machined surfaces. Cervical disc arthroplasty is displacing anterior cervical discectomy and fusion in select patient populations, compressing hardware volumes in the United States.
- Trauma Fixation:Intramedullary nails and locking plates for fracture stabilization.
- Orthobiologics:Bone graft substitutes, growth factors, and cell-based therapies for enhanced osseointegration.
Joint replacement absorbs the bulk of installed capacity; orthobiologics is expanding most quickly.
Application:
Surgical intervention generates the steepest revenue per procedure, while rehabilitation and pain management create recurring revenue streams with lower capital intensity.
- Surgery:Open and minimally invasive procedures for joint reconstruction, spinal fusion, and fracture repair. Ambulatory surgical centers in the United States are capturing total joint replacement volume as CMS reimbursement parity eliminates site-of-service differentials.
- Rehabilitation:Post-operative physical therapy protocols and continuous passive motion devices. Germany's statutory health insurance system mandates standardized rehabilitation episodes following joint replacement, creating predictable demand for outpatient therapy services.
- Pain Management:Neuromodulation implants and targeted drug delivery systems for chronic musculoskeletal pain.
- Injury Recovery:Bracing, orthotics, and functional restoration protocols for sports and occupational trauma.
Surgery commands the highest average revenue per patient; rehabilitation delivers the most consistent repeat utilization.
Technology:
Digital and additive manufacturing platforms require specialized engineering talent and intellectual property portfolios distinct from traditional machining competencies.
- 3D Printing:Electron beam melting and selective laser sintering of titanium lattice structures for patient-specific implants. FDA's 510(k) modernization program now demands direct comparison to devices less than ten years old, invalidating historical clearance pathways for legacy additive designs.
- Robotics:Navigation-enabled surgical systems for knee and hip arthroplasty. Germany's statutory health insurance coverage for robotic-assisted procedures creates predictable demand curves for capital equipment vendors.
- Wireless Monitoring:Bluetooth-enabled wearables and implantable sensors for post-operative telemetry.
- Smart Implants:Load-sensing constructs with embedded strain gauges and cloud connectivity.
Robotics captures the majority of current capital expenditure; smart implants are climbing the fastest as sensor miniaturization costs decline.
End User:
Site-of-service economics are fragmenting procurement authority, with ambulatory centers bypassing traditional hospital purchasing committees.
- Hospitals:Inpatient orthopedic service lines with integrated operating rooms and implant consignment programs. Medicare Advantage gainsharing arrangements in the United States are forcing hospitals to scrutinize implant spend as a discrete cost center within bundled episodes.
- Ambulatory Surgical Centers:Dedicated orthopedic suites with same-day discharge protocols. Direct-to-ASC distribution models are shortening sales cycles and displacing traditional group purchasing organization contracts.
- Rehabilitation Clinics:Outpatient physical therapy and occupational rehabilitation facilities.
- Home Care:Remote patient monitoring and telehealth-guided recovery protocols.
Hospitals retain the largest installed base; ambulatory surgical centers are gaining share fastest as procedure migration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical device special economic zones in Costa Rica and Puerto Rico concentrate orthopedic manufacturing through tax-advantaged operations serving US demand. These zones attract precision machining and sterile packaging operations from multinational firms seeking proximity to the world's largest procedure market.
United States
Medicare Advantage penetration exceeds 50% in metropolitan markets, driving bundled payment adoption that compresses implant pricing. FDA's 510(k) modernization invalidates legacy predicates for spine hardware, forcing new clinical evidence generation. Warsaw, Indiana anchors global joint replacement manufacturing with concentrated sterile forging and polishing operations.
Germany
Statutory health insurance reimbursement for robotic-assisted knee procedures creates predictable demand curves for navigation-enabled systems. EU MDR notified body bottlenecks delay quality management recertification for mid-tier manufacturers. The Tuttlingen surgical instrument cluster supplies precision-machined orthopedic tools to European hospital systems.
Switzerland
Private hospital networks in Zurich and Geneva sustain premium pricing for patient-specific implants and additive-manufactured constructs. Swissmedic maintains stringent clinical evidence requirements that filter market entry to well-capitalized firms. The Jura Arc watchmaking precision base transfers micro-machining expertise to spinal implant manufacturing.
China
Volume-based procurement (VBP) tenders slash joint replacement prices by 80% in provincial hospital systems, forcing multinational firms into local manufacturing partnerships. NMPA accelerates review timelines for innovative orthopedic devices through breakthrough pathways. The Suzhou Industrial Park hosts sterile manufacturing operations serving domestic and export markets.
Brazil
Private health insurance expansion in São Paulo and Rio de Janeiro sustains demand for premium joint replacement systems outside the public SUS system. ANVISA's accelerated pathway for breakthrough orthopedic devices opens regulatory access for sensor-integrated implants. The Campinas medical device corridor concentrates distribution operations for multinational firms.
Orthopedic Devices Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across implantable hardware, surgical robotics, and biologics categories. The vendor base organizes into three tiers: integrated health technology conglomerates with deep hospital system relationships, mid-cap orthopedic specialists with concentrated product portfolios, and emerging players in smart implants and additive manufacturing. Consolidation pressure intensifies as EU MDR compliance costs and FDA predicate tightening compress margins for subscale operators. M&A activity targets robotics platforms and patient-matched implant capabilities; strategic partnerships bridge software-hardware integration gaps.
Within the diversified health technology tier, Stryker Corporation and Johnson & Johnson MedTech exemplify scale-driven positioning through integrated digital surgery ecosystems and deep hospital supply chain relationships. Zimmer Biomet Holdings, Inc. occupies a focused specialist position across joint reconstruction and spine categories. These three firms anchor competitive dynamics through their capacity to absorb regulatory compliance costs and fund next-generation platform development.
| Leading Market Players |
|---|
| Stryker Corporation |
| Zimmer Biomet Holdings, Inc. |
| Johnson & Johnson MedTech |
| Smith+Nephew |
| Medtronic |
| DePuy Synthes |
| Arthrex, Inc. |
| Globus Medical |
| B. Braun |
| Others |
Supply Flow & Price Mechanics
CMS reimbursement parity for total joint replacement in ambulatory settings forces manufacturers to reconfigure implant consignment models and absorb inventory carrying costs, compressing margins on standard constructs while preserving premium pricing for patient-matched additive designs.
Pricing Analysis
Expedited delivery premiums of fifteen to twenty percent apply to patient-specific implants requiring additive manufacturing turnaround, while spot purchases of standard cobalt-chrome and titanium constructs trade at contracted rates. Three-tier pricing structure across premium, standard, and economy levels reflects FDA clearance tier, volume commitment scale, and after-sales telemetry bundling. Cost compression in economy-tier trauma fixation is intensifying because Chinese volume-based procurement tenders reset regional price floors. Ambulatory surgical centers exhibit highest price sensitivity due to gainsharing arrangements, while Swiss private hospital networks retain lowest sensitivity for navigation-enabled systems.
Supply Chain Analysis
Regional distribution centers in Warsaw, Indiana, Tuttlingen, Germany, and Suzhou, China, maintain hub-and-spoke patterns serving sterile manufacturing clusters and hospital networks. Vacuum-induction-melted cobalt-chrome powder, titanium sponge, and ultra-high molecular weight polyethylene resin constitute critical feedstocks drawn from South African, Chinese, and German chemical processors. Single-source vulnerability concentrates in electron beam melting equipment for additive manufacturing, where three European vendors control installed base. Distribution runs through implant consignment programs at hospital accounts and direct-to-ASC models bypassing group purchasing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR clinical evidence requirements and FDA 510(k) predicate tightening erect substantial capital barriers, filtering market participation to firms with dedicated regulatory infrastructure and long-term implant registry capabilities.
For Market Incumbents: Acquire robotics platform capabilities and patient-matched additive manufacturing assets to defend against pure-play specialists and software-native entrants. Backward integration into titanium powder atomization secures feedstock priority during aerospace demand spikes. Hospital system partnership density remains the critical lever for bundled contract retention. For New Entrants and Emerging Players: Ambulatory surgical center procurement committees represent an underserved buyer archetype bypassed by incumbent field forces focused on academic medical centers. Brazil's private hospital networks and Germany's statutory insurance reimbursement for robotic procedures offer most penetrable geographic entry points. Direct consignment models with inventory guarantees differentiate against traditional GPO-contracted supply. For Investors and Strategic Acquirers: The window for entry favors mid-cap orthopedic specialists with EU MDR technical documentation already filed and FDA Q-Sub engagement underway. Long-term viability rests on regulatory infrastructure amortization across product portfolios rather than single-device revenue concentration. Watch FDA 510(k) modernization enforcement patterns as inflection signal for predicate-dependent product line rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Filing | Notified body engagement preserves European market access amid certificate backlog congestion. |
| Hospital System Partnership | Integrated digital surgery platforms anchor bundled payment contract renewals in Medicare Advantage markets. |
| Software Companion Development | Cloud-based post-operative telemetry creates recurring revenue streams beyond hardware margins. |
| Reimbursement Strategy | Statutory coverage for robotic-assisted procedures in Germany validates capital equipment demand curves. |
| FDA 510(k) Modernization Compliance | Direct predicate comparison to sub-ten-year-old devices satisfies tightened clearance pathways for spine hardware. |
Methodological Framework
Document review covered FDA 510(k) and PMA filings, EU MDR technical documentation databases, and CMS reimbursement rulemaking records, complemented by interviews with orthopedic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary sources included implant registry data, hospital procurement databases, and statutory health insurance coverage determinations. Bottom-up procedure volume modeling and top-down manufacturer revenue triangulation validated segmentation outputs.
Market size and growth trajectory outputs across the projection horizon reflect econometric modeling of procedure migration patterns, reimbursement parity effects, and capital equipment replacement cycles. Segmentation dimensions encompassed product type, application, technology platform, and end-user site-of-service. CAGRs were derived from regression analysis of historical implant sales against demographic and surgical volume drivers, incorporating additive manufacturing adoption curves and robotics penetration rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU MDR notified body capacity constraints, FDA enforcement discretion on predicate validity, and CMS site-of-service payment policy shifts. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Veterinary Orthopedic Injectable Drug Market
Orthopedic Devices
Cementless Total Knee Arthroplasty (TKA) Market
Orthopedic Devices
Global Orthopedic Navigation Systems Market
Orthopedic Devices
Bone Void Fillers Market
Orthopedic Devices
Veterinary Orthopedic Drills Market
Orthopedic Devices
Orthopedic Support Systems Market
Orthopedic Devices
Orthopedic Fracture Repairing Implants for Osteoporosis Market
Orthopedic Devices
Orthopedic Wire Pin Driver Market
Orthopedic Devices
Global Artificial Joints Market
Orthopedic Devices
Cartilage Repair Market
Orthopedic Devices
Outsourced Orthopedic Manufacturing Market
Orthopedic Devices
Global Veterinary Orthopedics Market
Orthopedic Devices
Global Acetabular Cups Market
Orthopedic Devices
Kyphoplasty Systems Market
Orthopedic Devices
Global Orthopedic Digit Implants Market
Orthopedic Devices
Medical Traction Devices Market