
 Nasogastric Tube Market | 2026-2036
Nasogastric Tube Market Size, Share, and Industry Trends Forecast 2026-2036
Nasogastric Tube Market Intelligence
Polyvinyl chloride (PVC) displacement by advanced polymers like polyurethane and silicone is pivoting product economics toward patient safety and longer indwelling times. Medtronic leverages its research and development in biocompatible materials to develop advanced enteral feeding solutions. B. Braun specializes in safety-engineered devices, including tubes with features to prevent misconnections and improve patient outcomes. Cardinal Health sustains its market presence through extensive distribution networks that supply hospitals with a broad portfolio of essential medical devices.
A nasogastric tube is a flexible catheter passed through the nose, down the esophagus, and into the stomach. These devices, often made from polyurethane and specified by French scale diameters, serve critical functions in healthcare. Nutritional support applications dominate device usage, particularly within the hospital end-user segment. While adult tubes constitute the largest product category, the pediatric tubes segment is expanding due to specialized neonatal and infant care requirements in clinical settings.
Market access is governed by stringent regulatory frameworks, including pre-market approval from the US FDA and CE marking under the EU's Medical Device Regulation (MDR). In China, the NMPA enforces specific GB standards for medical-grade polymers, influencing material selection for all manufacturers. Stakeholders must now navigate the development and adoption of safety-engineered connectors designed to prevent potentially fatal misconnections between enteral and other systems.
Market Dynamics
The central structural force shaping the nasogastric tube market is the heightened regulatory focus on patient safety. This pressure, exemplified by frameworks like the EU's Medical Device Regulation, is accelerating the transition from traditional materials to advanced, biocompatible polymers.
Growth Catalysts
- Biocompatibility Mandates:Regulations such as the EU's MDR are compelling manufacturers to adopt safer materials like polyurethane, which reduces patient complications and aligns with higher standards of care, thereby stimulating demand for premium products.
- Expanding Hospital Infrastructure:The rapid construction and upgrading of hospitals, particularly within China, creates a larger installed base for essential medical devices, directly increasing volume demand for tubes used in nutritional support and gastric decompression.
- Safety-Engineered Connectors:The development and mandated adoption of specialized connectors, designed to prevent dangerous misconnections between enteral and other systems, creates a product replacement cycle and introduces a new standard for device safety.
Market Restraints
- Material Cost Premiums:Advanced polymers like polyurethane and silicone carry a significant cost premium over traditional polyvinyl chloride (PVC), limiting their adoption in cost-sensitive healthcare systems and emerging markets.
- Regulatory Approval Timelines:Gaining pre-market approval from bodies like the US FDA or ensuring compliance with China's NMPA for new device materials involves lengthy and expensive validation processes, slowing down innovation cycles.
- Alternative Feeding Methods:For long-term nutritional needs, clinicians may opt for more invasive but permanent solutions like percutaneous endoscopic gastrostomy (PEG) tubes, which represents a direct substitution threat to nasogastric tube use.
Strategic Opportunities
- Pediatric and Neonatal Niches:There is an opportunity to develop and market specialized, small-bore tubes designed specifically for neonatal intensive care units (NICUs) in regions with high birth rates, an underpenetrated segment.
- Smart Tube Development:Integrating micro-sensors for real-time placement verification or pH monitoring can create a new category of premium, value-added devices that improve clinical decision-making and patient safety.
- Home Care Market Expansion:Developing kits and protocols for the safe use of nasogastric tubes in home care settings addresses the trend of shifting patient care out of hospitals, opening a new end-user channel.
Industry Challenges
- Regulatory Harmonization:Manufacturers face significant operational complexity in designing products that simultaneously comply with the distinct requirements of the EU's MDR, the FDA's 510(k) pathway, and China's GB standards.
- Polymer Supply Chain Stability:The supply of medical-grade polyurethane and silicone is subject to price volatility and allocation issues within the broader chemical industry, posing a risk to production continuity and cost control.
- Connector Standard Adoption:The global transition to ISO 80369-3 compliant enteral connectors is inconsistent across hospitals and regions, creating logistical challenges and persistent safety risks during the extended changeover period.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nasogastric Tube Market |
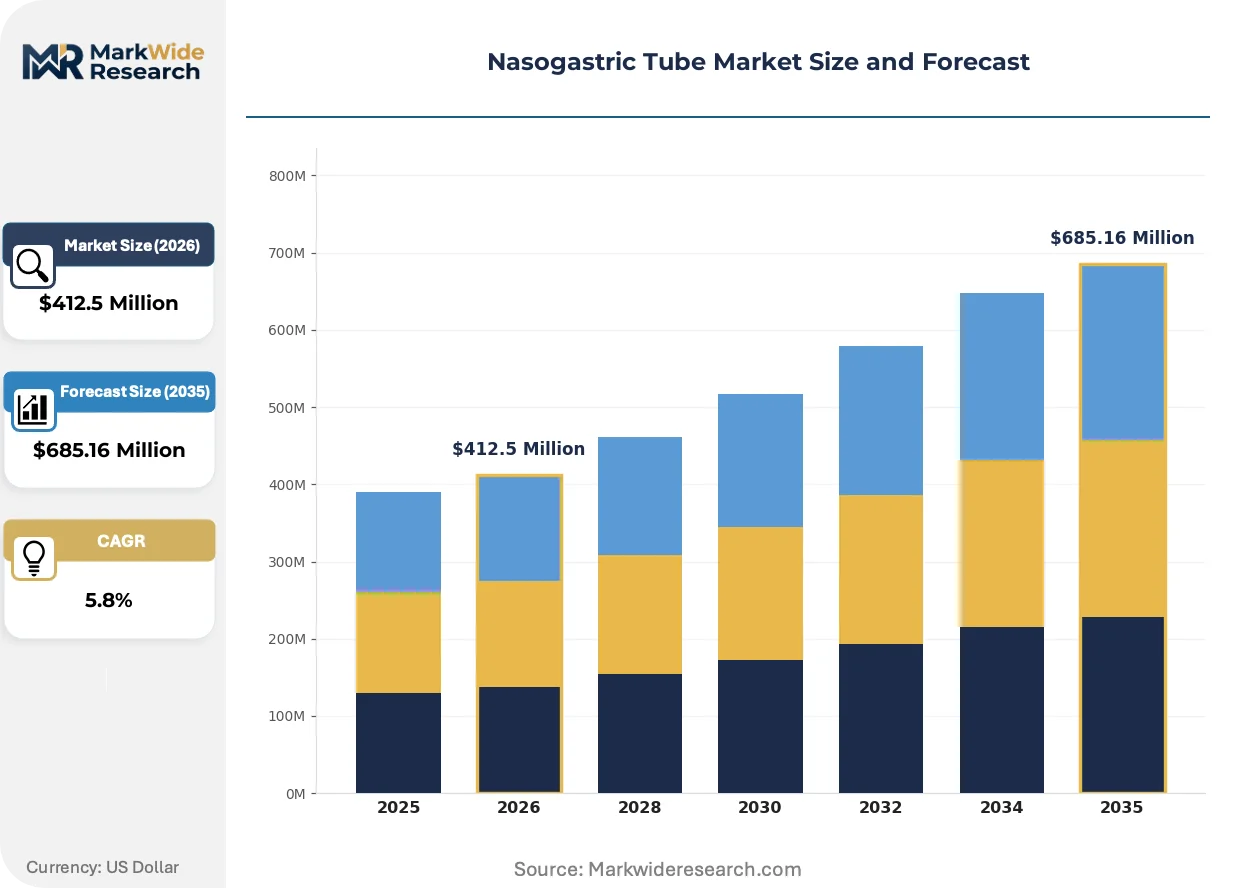
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adult Tubes, Pediatric Tubes, Specialty Tubes, Feeding Tubes Material: PVC, Silicone, Polyurethane, Latex End User: Hospitals, Home Care, Nursing Facilities, Clinics Application: Nutritional Support, Medication Administration, Gastrointestinal Decompression, Diagnostic Procedures |
| Companies Covered | Becton, Dickinson and Company, Cardinal Health, Medtronic, Fresenius Kabi, Vygon, B. Braun, Poly Medicure Limited, QMD, Angiplast Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nasogastric Tube Market Strategic Shifts & Innovations
The market's evolution is defined by the convergence of material science advancements and data-driven clinical practices. This combination aims to improve patient outcomes by reducing device-related complications and enhancing the precision of enteral therapies within hospital settings.
Biocompatible polyurethane is an advanced polymer used for its flexibility, durability, and reduced tissue irritation in nasogastric tubes. Hospitals and long-term care facilities are steadily adopting these materials for applications requiring longer indwelling times. This preference for improved patient safety and extended device life means polyurethane is overtaking traditional PVC in premium and mid-tier product segments.
Implementation of the ISO 80369 series of standards mandates specific, non-interchangeable connectors for different medical applications, including enteral feeding. This global initiative forces manufacturers to re-engineer device connectors to prevent potentially fatal misconnections with intravenous or respiratory lines. The enteral feeding segment is most affected, requiring significant product redesign and validation to meet compliance deadlines set by regulators like the FDA.
Hospital procurement is shifting from unit-cost-based purchasing to a total-cost-of-care model that values patient outcomes. This change favors devices that demonstrably reduce complications like aspiration or tissue trauma, even if their initial price is higher than traditional alternatives. This value-based approach is most visible within large, integrated health networks in the United States and parts of Western Europe.
Nasogastric Tube Market Segmentation
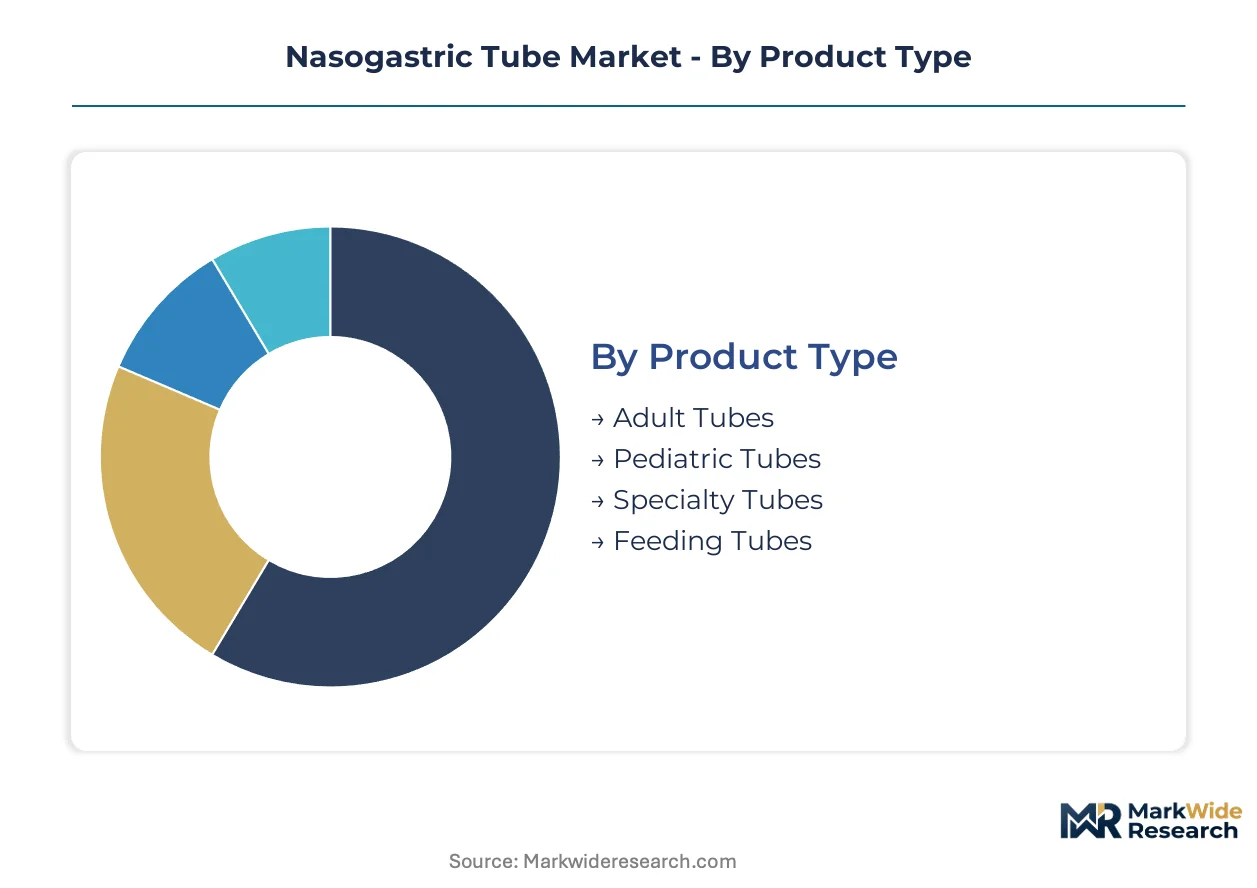
The nasogastric tube market segmentation provides a granular view of product variations and their specific applications across diverse healthcare settings. Analyzing these segments reveals where development efforts are concentrating and which end-user needs are driving demand for specialized solutions.
Product Type:
Product type segmentation reflects varying capital investments for manufacturing specialized designs.
- Adult Tubes:These standard, larger diameter tubes (often 12-18 Fr) facilitate general enteral feeding and gastric decompression for adult patients. Demand concentrates in general hospital wards across countries like the United States and Germany, driven by a broad patient demographic requiring temporary nutritional support.
- Pediatric Tubes:Smaller, more flexible tubes (typically <10 Fr) are specifically engineered for neonates and infants, minimizing trauma during insertion and indwelling. Demand is expanding within neonatal intensive care units in regions with high birth rates, such as India and Nigeria, where specialized care requirements are increasing.
- Specialty Tubes:These tubes incorporate features like weighted tips or multiple lumens for specific clinical needs such as aspiration prevention or simultaneous irrigation.
- Feeding Tubes:Designed primarily for delivering nutrition and hydration, these tubes are optimized for long-term indwelling and patient comfort.
Adult Tubes absorb the bulk of installed capacity; Pediatric Tubes are expanding most quickly.
Material:
Material selection directly influences device cost and patient safety outcomes.
- Polyurethane:This advanced polymer offers superior biocompatibility, flexibility, and durability, allowing for longer indwelling times and reduced tissue irritation. Adoption is driven by stringent regulatory frameworks like the EU's MDR and patient outcome-focused procurement in Western European hospitals.
- Silicone:Known for its inertness and softness, silicone provides excellent patient comfort and is often preferred for longer-term enteral access. Demand is notable in specialized care settings within countries such as Canada and Australia, where patient tolerance and extended use are critical.
- PVC:Polyvinyl chloride tubes are cost-effective and widely used for short-term applications, particularly in emerging markets like Brazil.
- Latex:Latex tubes, while flexible, are declining in use due to allergy concerns and inferior biocompatibility compared to synthetic alternatives.
Supply chain concentration for advanced polymers like polyurethane and silicone dictates pricing for premium products.
End User:
End-user segments reflect the diverse clinical environments where nasogastric tubes are deployed.
- Hospitals:Acute care hospitals represent the primary end-user segment, utilizing tubes for nutritional support, medication delivery, and gastric decompression across various departments. Volume demand is substantial in China's rapidly expanding hospital infrastructure and established healthcare systems in the United States.
- Home Care:This segment involves patients receiving nasogastric tube feeding or medication administration in their residences, often managed by visiting nurses or trained caregivers. Expansion is occurring in countries like the United Kingdom and Japan due to aging populations and policies promoting de-institutionalized care.
- Nursing Facilities:Long-term care and skilled nursing facilities use these tubes for residents requiring extended nutritional support or medication delivery.
- Clinics:Outpatient clinics utilize nasogastric tubes for specific diagnostic procedures or short-term interventions, typically on an elective basis.
Regulatory oversight is most stringent for hospital use, while home care applications demand robust patient education and device simplification.
Application:
Application segments exhibit varying margin profiles based on procedural complexity and device specialization.
- Nutritional Support:This application involves delivering liquid nutrition and hydration directly into the stomach for patients unable to consume food orally. It drives the largest volume demand within hospital settings globally, particularly for post-operative recovery and critical care patients in countries like India and France.
- Medication Administration:Nasogastric tubes facilitate the safe and precise delivery of liquid medications or crushed tablets dissolved in liquid to patients with impaired swallowing. This application is critical in intensive care units and long-term care facilities, emphasizing device compatibility with various drug formulations.
- Gastrointestinal Decompression:These tubes are used to remove excess air or fluid from the stomach, alleviating pressure and preventing nausea or vomiting in patients with intestinal obstructions.
- Diagnostic Procedures:Specific tubes aid in collecting gastric samples for analysis or performing diagnostic tests like pH monitoring or gastric lavage.
Technology integration focuses on enhancing safety and efficacy for nutritional support, while diagnostic applications increasingly leverage smart tube capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for nasogastric tubes concentrates significantly in regions with expanding healthcare infrastructure and stringent patient safety mandates. China's rapid hospital development creates substantial volume requirements for nutritional support devices. Established markets in North America and Europe emphasize advanced materials and safety-engineered connectors.
China
China's expanding hospital infrastructure fuels substantial demand for nasogastric tubes, particularly for nutritional support applications. The NMPA enforces specific GB standards for medical-grade polymers, influencing material selection for manufacturers. Manufacturing hubs in the Yangtze River Delta region are innovating to meet evolving material requirements.
United States
The United States market prioritizes patient safety and value-based care, driving adoption of biocompatible materials and safety-engineered connectors. The US FDA's pre-market approval processes influence device design and material choices for new products. Large integrated health networks in metropolitan areas like New York and Los Angeles increasingly procure premium, outcome-focused devices.
Germany
Germany exhibits consistent demand for adult nasogastric tubes within its well-established hospital system, driven by an aging population. Compliance with the EU's Medical Device Regulation (MDR) accelerates the transition to advanced polymers like polyurethane. Medical technology clusters in Bavaria and North Rhine-Westphalia focus on developing high-quality, safety-compliant devices.
India
India's high birth rates and increasing focus on specialized neonatal care are expanding the pediatric tubes segment. The Central Drugs Standard Control Organization (CDSCO) regulates medical devices, influencing material and design standards. Healthcare clusters in cities like Chennai and Mumbai are developing specialized solutions for infant nutritional support.
United Kingdom
The United Kingdom's home care market for nasogastric tubes is expanding due to policies promoting de-institutionalized care and an aging population. The Medicines and Healthcare products Regulatory Agency (MHRA) oversees device safety and efficacy. London and Southeast England health authorities are implementing protocols for safe tube use in community settings.
Nasogastric Tube Market Key Industry Players
Technology and material innovation dominates the current landscape, driving shifts towards advanced nasogastric tube designs. The market exhibits a tiered structure, with global healthcare conglomerates alongside specialized medical device manufacturers and regional players. Strategic archetypes include diversified healthcare giants, niche innovators, and cost-effective volume producers. Competitive moves center on research and development in biocompatible materials, ensuring regulatory compliance, and expanding distribution networks.
Within the diversified healthcare conglomerate tier, Becton, Dickinson and Company represents a broad portfolio spanning multiple medical device categories, serving diverse clinical needs. Medtronic occupies a position as a global leader in medical technology, leveraging extensive research and development capabilities to advance enteral feeding solutions. B. Braun, a German-based company, exemplifies specialization in safety-engineered devices, adhering to stringent European regulatory standards for patient outcomes. These entities collectively anchor innovation, distribution reach, and compliance efforts across various end-user segments.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Cardinal Health |
| Medtronic |
| Fresenius Kabi |
| Vygon |
| B. Braun |
| Poly Medicure Limited |
| QMD |
| Angiplast Pvt. Ltd. |
| Others |
Cost & Logistics Intelligence
The transition to biocompatible polymers like polyurethane and silicone simultaneously reshapes cost economics and supply concentration. This shift drives innovation while introducing new dependencies on specialized material suppliers for advanced nasogastric tube designs.
Pricing Analysis
The market exhibits a split between volume-driven unit-cost pricing for traditional devices and value-based pricing for advanced solutions. Pricing stratifies across premium, standard, and economy tiers based on material grade and safety features. Price differentiation stems from biocompatible material selection and compliance with safety-engineered connector standards. Pricing pressure intensifies on PVC tubes from cost-sensitive healthcare systems in emerging markets. Hospitals in Western Europe and the United States show less price sensitivity for premium, outcome-focused devices.
Supply Chain Analysis
Medical-grade polymer supply rests heavily on a few specialized chemical producers, primarily in Asia and Europe. Raw material dependencies include polyurethane, silicone, and specific components for ISO 80369-3 compliant connectors. Single-source vulnerability for these advanced materials presents a significant supply chain risk. Distribution runs through established medical device distributors and direct sales channels to hospitals, with emerging direct-to-consumer models for home care applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Limited manufacturing capacity for specialized medical-grade polymers and safety-engineered connectors frames this market as supply-constrained. This constraint props up premium pricing for advanced nasogastric tube solutions.
For Market Incumbents: Anchor ongoing research and development in next-generation biocompatible materials to maintain product differentiation. Pursue backward integration into medical-grade polymer sourcing to mitigate supply chain volatility. Expand manufacturing capacity for ISO 80369-compliant connectors to meet evolving regulatory mandates. Forge stronger partnerships with large hospital networks to defend market share against alternative feeding methods like PEG tubes.
For New Entrants and Emerging Players: Direct-to-consumer digital channels offer a viable route for specialized product launches in the home care segment. Target underpenetrated pediatric and neonatal niches with small-bore, trauma-minimizing tube designs. Focus on developing smart tube technologies with integrated sensors for real-time placement verification. A go-to-market angle could involve bundling specialized tubes with comprehensive patient education and caregiver training programs.
For Investors and Strategic Acquirers: Re-rating potential sits with niche innovators in smart tube technology given the increasing focus on patient safety and clinical efficiency. Long-term viability is supported by aging populations and expanding healthcare infrastructure globally. Acquisition targets should include firms with proprietary material science expertise or established distribution in high-growth pediatric segments. Watch for accelerated global regulatory harmonization as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | Ensures compliance with stringent European standards, unlocking significant market access for advanced devices. |
| Biocompatible Material R&D | Drives innovation in patient safety and extends indwelling times, reducing complication rates in clinical settings. |
| ISO 80369-3 Connector Redesign | Prevents dangerous misconnections, aligning devices with critical global safety mandates and improving patient outcomes. |
| Pediatric Device Portfolio Expansion | Addresses specialized needs in neonatal care, capturing growth in high-birth-rate regions and underserved segments. |
| Home Care Kit Development | Facilitates safe and effective device use outside hospitals, expanding end-user channels and supporting de-institutionalized care. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this market analysis. Primary research involved interviews with hospital procurement managers, neonatologists, regulatory affairs specialists, and medical device engineers. This approach combined qualitative insights with quantitative data, ensuring robust validation through bottom-up and top-down triangulation.
Data-stream reconciliation formed the basis of the forecast framework, projecting market trends across the analysis window. Segmentation dimensions modeled included product type, material, end-user, application, and regional regulatory compliance. Compound annual growth rates were derived from historical trends and projected market dynamics. Key forecast inputs included global hospital bed expansion rates and regional birth rates.
The model holds under current regulatory and supply chain conditions; deviation in medical-grade polymer supply or unforeseen regulatory shifts would shift projections. Forecasts reflect assumptions documented through extensive industry research. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Australia Insulin Delivery Devices Market
Medical Devices
Retinal Surgery Devices Market
Medical Devices
Europe Spinal Surgery Devices Market
Medical Devices
Intrapartum Monitors Market
Medical Devices
Self-Injections Market
Medical Devices
Corneal Cross Linking Devices Market
Medical Devices
Cranial Clamps Market
Medical Devices
Complementary Therapy Devices Market
Medical Devices
Thyroid Ablation Devices Market
Medical Devices
Lumbar Disc Replacement Device Market
Medical Devices
South Korea Massage Equipment Market
Medical Devices
Fluidics for Preclinical Market
Medical Devices
United States Organ Preservation Market
Medical Devices
Vascular Screening Devices Market
Medical Devices
Global Digital Dose Inhaler Market
Medical Devices
Dry Eye Treatment Devices Market