
 Single Tooth Implants and Dental Bridges Market | 2026-2036
Single Tooth Implants and Dental Bridges Market Size, Share, and Industry Trends Forecast 2026-2036
Single Tooth Implants and Dental Bridges Market Outlook
Prosthetic service revenue is tilting from bridge restoration toward implant-based solutions as durability expectations rise. Institut Straumann AG leverages its titanium implant heritage to dominate premium positioning across European dental laboratories. Dentsply Sirona sustains broad portfolio breadth spanning chairside digital workflows and conventional bridge fabrication. OSSTEM IMPLANT CO., LTD. anchors volume leadership in Asia-Pacific markets through cost-optimized surgical kits.
Single tooth implants and dental bridges constitute fixed prosthodontic devices engineered from titanium alloys, zirconium dioxide, or layered ceramics to restore masticatory function and aesthetic continuity after tooth loss, with implant systems typically achieving osseointegration thresholds of 35 Ncm insertion torque. The product type dimension shows implants capturing accelerating preference over bridges as clinicians prioritize bone preservation, while zirconia within the material category commands expanding share against titanium in anterior aesthetic zones due to biocompatibility and color-matching properties. Laboratories within the end user segment face margin compression as chairside CAD/CAM adoption shifts value toward dentist-operated milling systems.
The FDA regulates titanium and zirconia implants through 510(k) substantial equivalence reviews, while the EU Medical Device Regulation (MDR) imposes enhanced clinical evidence requirements for custom abutments and patient-specific prosthetics. ISO 14801 fatigue testing standards govern implant-abutment connection durability, shaping manufacturer R&D allocation toward screw-retained versus cement-retained restoration platforms. Stakeholders must monitor reimbursement parity between implant and bridge procedures across national health systems as coverage decisions reshape patient access economics.
Market Dynamics
Chairside CAD/CAM digitization is collapsing the traditional laboratory-dentist workflow, compressing turnaround times from weeks to hours while redistributing margin capture toward dental clinics equipped with in-house milling capacity.
Growth Catalysts
- MFDS fast-track approvals:South Korea's medical device regulator accelerates titanium implant registrations, reducing time-to-market for Korean manufacturers serving domestic dental chains.
- Osseointegration torque thresholds:ISO 14801 fatigue testing standardization builds clinician confidence in immediate-loading protocols, expanding same-day implant candidacy pools.
- Aging edentulism clusters:Germany's 65-plus demographic concentration drives prosthetic volume through statutory health insurance reimbursement parity for implant versus bridge procedures.
Market Restraints
- Titanium alloy input volatility:Aerospace and medical-grade titanium sponge supply concentrates in Chinese and Russian smelters, exposing implant manufacturers to export quota disruptions.
- EU MDR clinical evidence burdens:Custom abutment manufacturers face expanded patient-specific prosthetic documentation requirements, lengthening certification timelines.
- Bridge substitution persistence:Conventional three-unit bridges retain preference in Medicaid-restricted US markets where implant coverage exclusions limit patient access.
Strategic Opportunities
- India's dental tourism corridor:Mumbai and Chennai clinic clusters attract Middle Eastern and African patients seeking cost-optimized implant packages at 40-60% below US pricing.
- Digital workflow convergence:Intraoral scanner-integrated implant planning software merges with robotic surgical guidance, enabling flapless precision in complex posterior cases.
- US IRA preventive care incentives:Medicare Advantage expansion of dental benefits creates reimbursement tailwinds for implant-restorative bundles in senior populations.
Industry Challenges
- Prosthodontist training bottlenecks:US and European residency programs graduate insufficient implantologists to match chairside CAD/CAM deployment rates, creating treatment capacity constraints.
- Legacy PMS integration friction:Digital impression systems require costly middleware upgrades to synchronize with decade-old practice management software dominating independent dental clinics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single Tooth Implants and Dental Bridges Market |
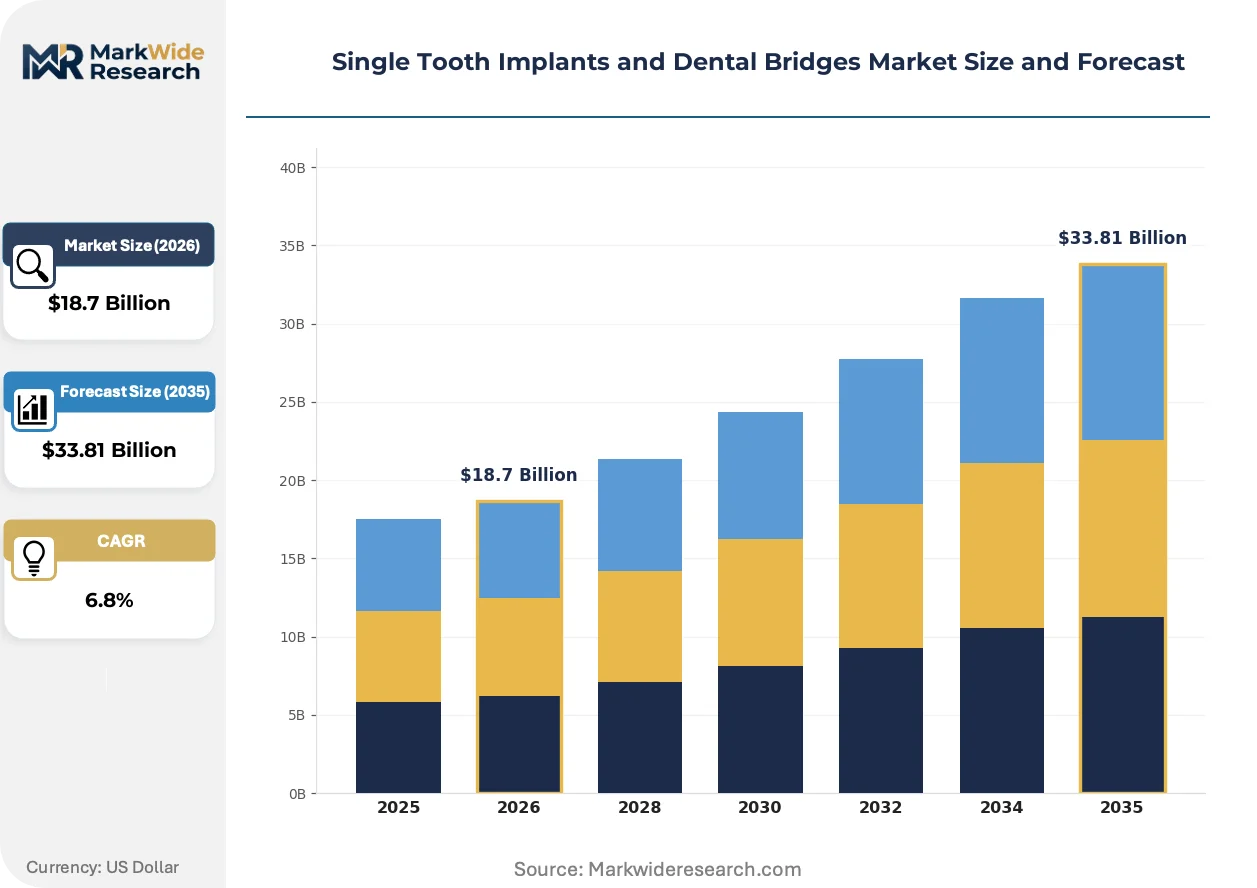
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implants, Bridges, Abutments, Prosthetics Material: Titanium, Zirconia, Stainless Steel, Ceramics End User: Dentists, Clinics, Hospitals, Laboratories Procedure Type: Implant Placement, Bridge Installation, Crown Fitting, Bone Grafting |
| Companies Covered | Institut Straumann AG, Dentsply Sirona, Zimmer Biomet, Nobel Biocare Services AG, Ivoclar Vivadent, OSSTEM IMPLANT CO., LTD., ZimVie, Danaher, Henry Schein, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single Tooth Implants and Dental Bridges Market Strategic Shifts
Digital impression capture and additive manufacturing are dissolving the geographic and temporal boundaries that once defined prosthetic dentistry, enabling distributed production models that compress patient chair time.
Monolithic zirconia crowns produced via CAD/CAM milling are rendering obsolete layered porcelain-fused-to-metal restorations in anterior aesthetic zones. US and German cosmetic dental clinics now specify full-contour zirconia for 80-plus percent of anterior single-unit cases. The shift eliminates metal substructure opacity issues while reducing laboratory technician labor hours per unit.
EU MDR Article 10 post-market surveillance mandates now require implant manufacturers to maintain active implant registries tracking adverse events across member states. Straumann and Dentsply Sirona have consolidated European adverse event reporting through centralized pharmacovigilance databases. The regulation compresses product liability exposure timelines while elevating documentation costs for smaller European dental laboratories fabricating custom abutments.
Subscription-based implant planning software is displacing perpetual-license CAD purchases among US dental service organizations. Aspen Dental and Heartland Dental negotiate enterprise seat licenses that bundle annual updates with cloud-based case collaboration tools. The model concentrates purchasing power with multi-location DSO procurement teams while marginalizing independent practitioners lacking volume leverage.
Single Tooth Implants and Dental Bridges Market Segmentation
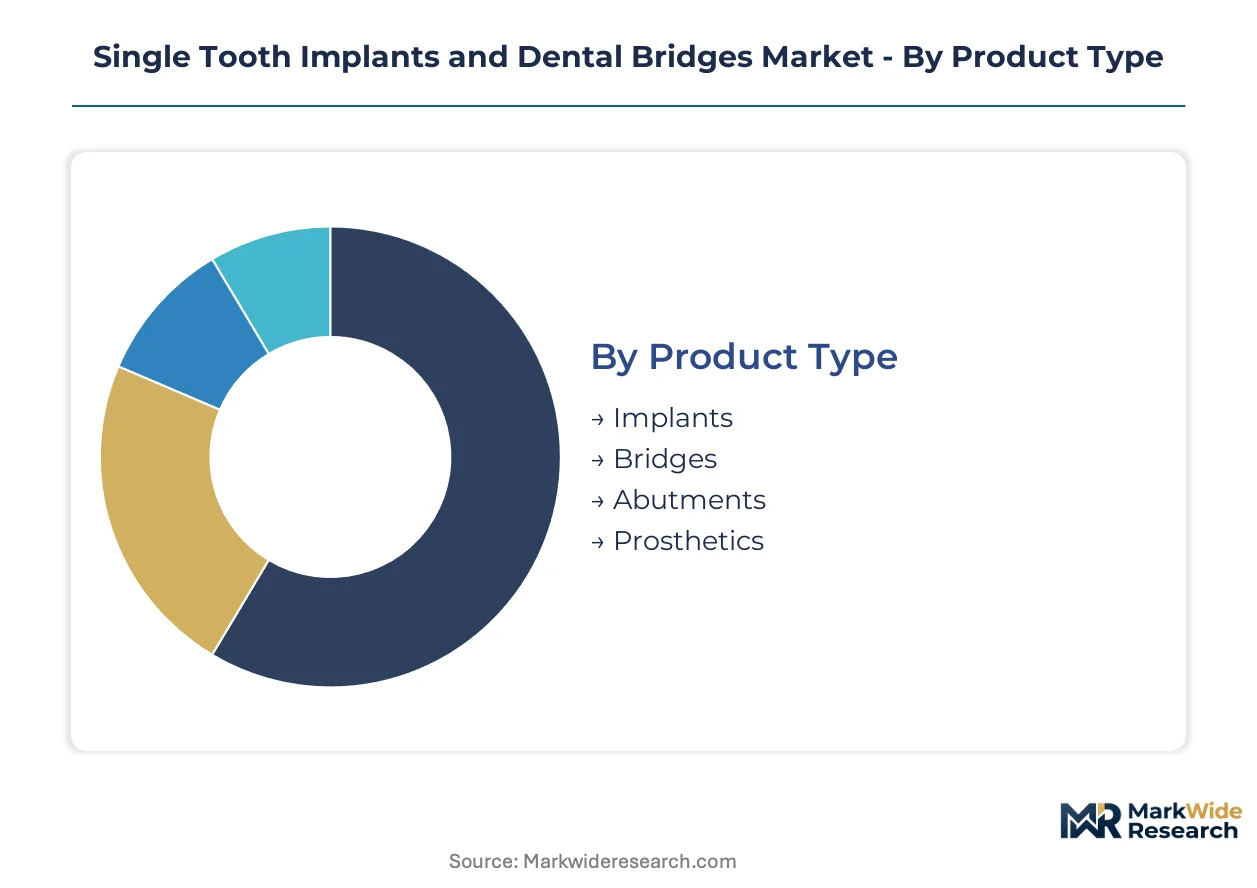
Segmentation in the single tooth implants and dental bridges market reveals how clinical priorities, material science advances, and workflow digitization reshape purchasing patterns across patient populations and provider types.
Product Type:
Cost tier stratification separates premium implant systems from conventional bridge restoration, with reimbursement parity and chairside efficiency driving volume allocation across dental service organizations.
- Implants:Titanium alloy screw-form devices achieve osseointegration through threaded surface modifications and platform-switching abutment designs. Demand concentrates in US Medicare Advantage networks and German statutory insurance panels where reimbursement parity with bridges has eliminated cost barriers for edentulous seniors.
- Bridges:Conventional three-unit fixed prostheses retain volume in Medicaid-restricted US markets and emerging economies where implant surgical infrastructure remains underdeveloped. Brazilian and Indian public health systems specify bridges as first-line tooth replacement due to lower per-procedure reimbursement ceilings.
- Abutments:Stock and custom-milled titanium components connect implant fixtures to definitive restorations, with zirconia abutments gaining preference in anterior aesthetic zones.
- Prosthetics:Crowns and superstructures fabricated from monolithic zirconia or layered ceramics complete the restorative chain, with CAD/CAM production displacing conventional casting.
Implants command the established base. The steepest expansion runs through abutments as chairside milling enables same-day delivery protocols.
Material:
Application requirements dictate material selection, with load-bearing posterior zones favoring titanium strength and anterior aesthetics demanding zirconia's optical properties.
- Titanium:Commercially pure and alloyed grades (Ti-6Al-4V ELI) dominate implant fixture manufacturing due to fatigue resistance and established osseointegration profiles. German and South Korean dental chains specify titanium for posterior multi-unit cases where mechanical loads exceed zirconia thresholds.
- Zirconia:Yttria-stabilized tetragonal zirconia polycrystal (Y-TZP) achieves flexural strengths exceeding 900 MPa while permitting light transmission mimicking natural dentition. US cosmetic dental clinics in California and Florida now specify zirconia for 80-plus percent of anterior single-unit restorations, displacing porcelain-fused-to-metal alternatives.
- Stainless Steel:Temporary crowns and provisional restorations utilize 316L grade for cost-sensitive applications in pediatric and emergency dentistry.
- Ceramics:Lithium disilicate and hybrid ceramic formulations serve specific indications requiring balance between aesthetics and machinability.
Titanium retains the volume base across posterior indications. Zirconia posts the steepest share gains as anterior aesthetic standards intensify.
End User:
Customer type fragmentation reflects workflow digitization, with capital-equipped clinics capturing margin previously retained by independent laboratories.
- Dentists:General practitioners and prosthodontists in US dental service organizations drive implant case volume through bundled surgical-restorative packages. Aspen Dental and Heartland Dental procurement teams negotiate enterprise software licenses that centralize treatment planning across multi-location networks.
- Clinics:Specialty implant centers in South Korea's Seoul-Gyeonggi corridor and India's Mumbai cluster attract medical tourism flows with cost-optimized surgical packages priced 40-60 percent below US benchmarks.
- Hospitals:Academic medical centers and oral surgery departments manage complex cases requiring general anesthesia or simultaneous bone grafting procedures.
- Laboratories:Independent dental laboratories face margin compression as chairside CAD/CAM adoption shifts crown production to dentist-operated milling systems, concentrating fabrication volume in large-scale digital production facilities.
Dentists command the established base. The steepest expansion runs through clinics as dental tourism corridors mature and same-day protocols proliferate.
Procedure Type:
Maturity gradients separate established implant placement from emerging digital workflows, with bone grafting representing the technical frontier for complex cases.
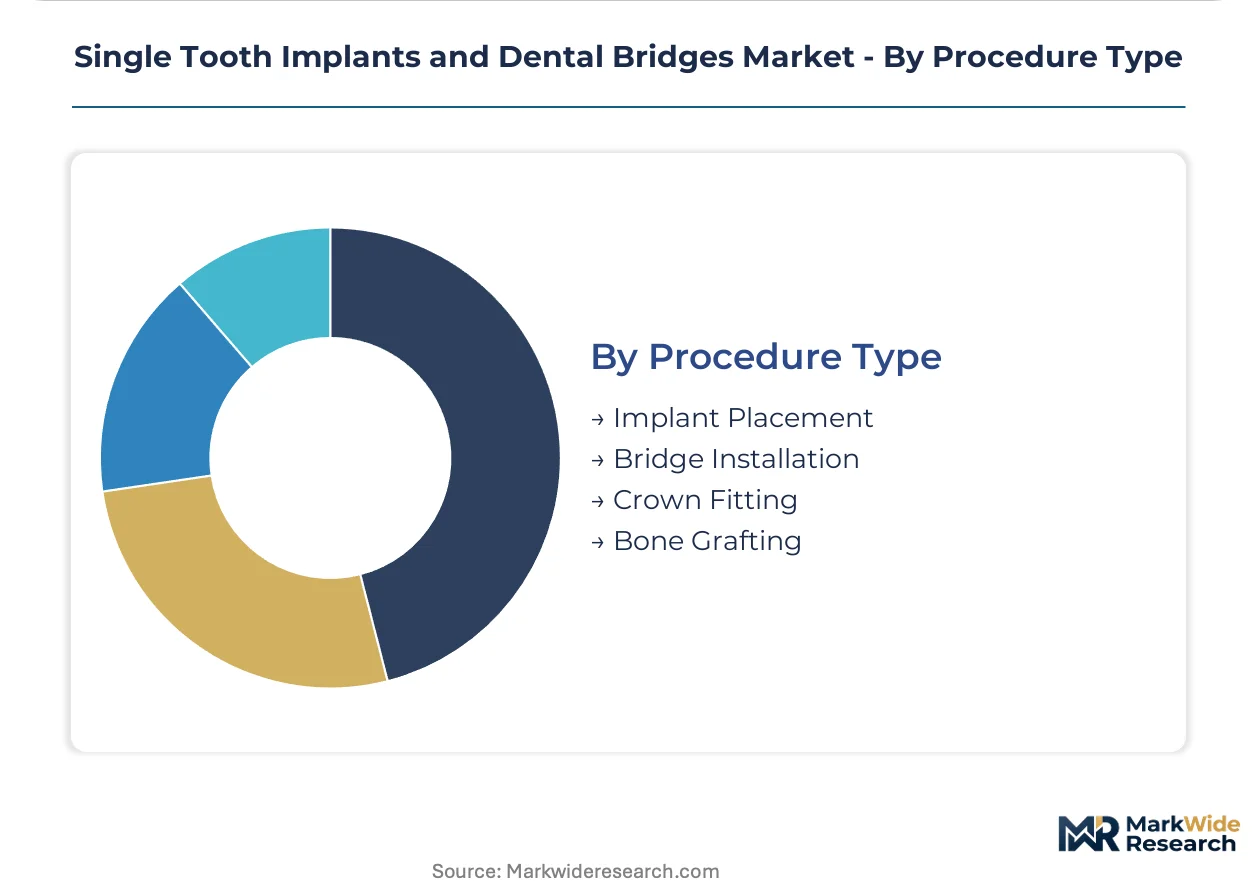
- Implant Placement:Flapped and flapless surgical protocols utilizing guided surgery templates now dominate tooth replacement in reimbursed markets. ISO 14801 fatigue testing standardization has enabled immediate-loading protocols that compress treatment timelines from months to hours.
- Bridge Installation:Conventional tooth preparation and cementation retains preference where adjacent teeth already require crown restoration, converting three-unit cases from additive implant procedures to subtractive bridge alternatives.
- Crown Fitting:Digital impression capture and same-day milling have collapsed delivery timelines, with intraoral scanner integration enabling single-appointment definitive restoration in equipped practices.
- Bone Grafting:Sinus augmentation and ridge preservation procedures expand implant candidacy in atrophic jaws, with synthetic graft substitutes and growth factor adjuncts reducing autograft morbidity.
Implant placement commands the established base. The steepest expansion runs through crown fitting as chairside CAD/CAM deployment accelerates across dental service organizations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across markets. German and South Korean patients face minimal out-of-pocket exposure under comprehensive reimbursement, while US Medicaid enrollees and Indian cash-pay segments absorb full procedure costs, driving bridge preference over implants in these pockets.
United States
Medicare Advantage dental benefit expansion is reshaping senior access patterns. The FDA's 510(k) pathway accelerates titanium device clearance timelines. Dental service organizations in Florida and Arizona are consolidating procurement through enterprise software licenses that standardize implant planning across multi-clinic networks.
Germany
Statutory health insurance reimbursement parity eliminates cost barriers for edentulous seniors in Bavaria and North Rhine-Westphalia. The EU MDR imposes enhanced clinical evidence requirements for custom abutments. Berlin-Brandenburg dental laboratories are consolidating fabrication volume as chairside CAD/CAM adoption shifts crown production to dentist-operated systems.
South Korea
Aging demographics in the Seoul-Gyeonggi corridor drive prosthetic volume through national health insurance coverage. MFDS fast-track approvals compress titanium implant registration timelines. Busan-Ulsan clinic clusters are attracting regional medical tourism flows with cost-optimized surgical packages.
India
Cash-pay dominance in tooth replacement creates sharp price sensitivity across Maharashtra and Gujarat markets. The country's central pharmaceutical regulator maintains device classification frameworks that shape import duty structures. Mumbai and Chennai dental tourism corridors are capturing Middle Eastern and African patients seeking implant packages at 40-60 percent below US benchmarks.
Brazil
Public health system reimbursement ceilings restrict implant access, preserving bridge volume in São Paulo and Minas Gerais state clinics. ANVISA medical device regulations govern import licensing for foreign-manufactured fixtures. Rio de Janeiro specialty centers are developing cost-tiered service menus that segment premium implant offerings from economy bridge alternatives.
Single Tooth Implants and Dental Bridges Market Competitive Environment
Capability concentration sits with heritage implant manufacturers possessing decades of osseointegration research; scale advantage sits with diversified dental conglomerates leveraging broad distribution networks. The market structures around three tiers: premium-positioned Swiss-German specialists, volume-optimized Korean-Taiwanese suppliers, and diversified US-based dental platforms. Consolidation pressure is intensifying through dental service organization procurement centralization and cross-border technology licensing arrangements.
Within the premium heritage tier, Institut Straumann AG and Nobel Biocare Services AG represent decades of titanium implant research accumulation and European laboratory relationships. OSSTEM IMPLANT CO., LTD. exemplifies the Asia-Pacific volume-optimized archetype through cost-engineered surgical kit configurations. Dentsply Sirona occupies a position bridging equipment and consumable domains through digital workflow integration.
| Leading Market Players |
|---|
| Institut Straumann AG |
| Dentsply Sirona |
| Zimmer Biomet |
| Nobel Biocare Services AG |
| Ivoclar Vivadent |
| OSSTEM IMPLANT CO., LTD. |
| ZimVie |
| Danaher |
| Henry Schein |
| Others |
Value Chain & Pricing Dynamics
Seoul-Gyeonggi manufacturing clusters anchor titanium implant fixture production, with capacity utilization rates at Korean forging facilities directly transmitting into pricing leverage for domestic dental chains negotiating surgical kit bundles. Aerospace-grade titanium sponge allocations from Chinese and Russian smelters feed into this hub, creating downstream cost pass-through dynamics that Korean manufacturers exploit to undercut European heritage brands in Asia-Pacific tenders.
Pricing Analysis
Long-term offtake agreements between dental service organizations and implant manufacturers dominate procurement, with enterprise seat licenses for CAD/CAM software bundled into per-unit fixture pricing. Premium-mid-economy pricing differentiation separates Straumann's research-backed heritage positioning from OSSTEM's volume-optimized surgical configurations. Cost compression in economy tiers intensifies as Indian and Brazilian clinic chains negotiate direct sourcing arrangements that bypass distributor markups. Medicaid-restricted US markets exhibit highest price sensitivity, while German statutory insurance panels show lowest sensitivity due to reimbursement parity.
Supply Chain Analysis
Contract manufacturing concentration sits with German precision forges and South Korean CNC machining specialists holding ISO 14801-certified capacity for implant-abutment connections. Raw material dependencies center on Chinese titanium sponge, Ukrainian zirconium ores, and Japanese yttria stabilizers for Y-TZP ceramics. Single-source vulnerability concentrates in aerospace-grade titanium alloy supply from Chinese state-owned smelters subject to export quota disruptions. Distribution runs through dental service organization procurement centralization in the US, independent laboratory networks in Germany, and direct clinic sales in South Korea.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dental service organization consolidation across the US and Germany has concentrated purchasing power among fewer buyers, shifting margin capture away from implant manufacturers toward clinic-operated procurement teams. This buyer-power concentration demands strategic repositioning across stakeholder archetypes.
For Market Incumbents: Pre-empt margin erosion from chairside CAD/CAM adoption by acquiring digital workflow software specialists and securing exclusive intraoral scanner partnerships. Institut Straumann AG and Dentsply Sirona must defend against Korean volume players by embedding proprietary abutment interfaces that lock in laboratory switching costs. Backward integration into zirconia blank manufacturing reduces exposure to Ukrainian raw material disruptions.
For New Entrants and Emerging Players: Establish a beachhead in India's dental tourism corridor by partnering with Mumbai and Chennai clinic clusters to offer cost-optimized implant packages at 40-60 percent below US benchmarks. Target Medicaid-restricted US markets where bridge substitution persists due to implant coverage exclusions. Deploy subscription-based planning software to bypass perpetual-license barriers facing independent practitioners.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because dental service organization procurement centralization will concentrate volume among suppliers possessing enterprise software integration capabilities. Acquisition targets should display chairside CAD/CAM compatibility and MFDS or FDA regulatory clearances. Monitor Medicare Advantage dental benefit expansion rates as the inflection signal for US senior segment acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| CAD/CAM Software Acquisition | Captures margin shifting from laboratories to dentist-operated milling systems. |
| MFDS Fast-Track Registration | Accelerates titanium implant entry into South Korea's national health insurance panels. |
| Zirconia Blank Manufacturing Integration | Reduces raw material exposure to Ukrainian ore supply disruptions. |
| Dental Service Organization Partnership | Locks in enterprise procurement volume through bundled surgical-restorative packages. |
| Immediate-Loading Protocol Certification | Expands same-day implant candidacy pools through ISO 14801 fatigue validation. |
Study Parameters
A standing panel of prosthodontists, dental laboratory technicians, GPO contracts managers, and biomedical engineers provided ongoing calibration across primary interview rounds. Secondary validation drew from FDA 510(k) clearance databases, EU MDR Article 10 post-market surveillance registries, hospital procurement contract filings, and MFDS registration timelines. Bottom-up implant shipment data from Korean and German manufacturers triangulated against top-down dental service organization spending disclosures.
Scenario-bracketing framed demand projections across the analysis window, with segmentation dimensions spanning product type, material grade, end-user workflow maturity, and procedure complexity tier. CAGRs derived from fitted growth curves applied to reimbursed versus cash-pay market splits. Forecast inputs incorporated aging demographic projections, statutory insurance reimbursement parity rulings, and chairside CAD/CAM deployment rates across dental clinic networks.
Macroeconomic conditions sit as an overlay; deviation in titanium alloy commodity indices, medical device tariff schedules, or national health insurance reimbursement ceilings would shift the trajectory. Quarterly review of MFDS registration volumes, Medicare Advantage dental benefit expansion rates, and EU MDR custom abutment certification timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
RFID-Enabled Dental Printing Market
Dental Devices
Dental Anaesthetic Market
Dental Devices
South Africa Dental Devices Market
Dental Devices
Dental Contouring Market
Dental Devices
Dental 3D Scanners Market
Dental Devices
Dental Caries Market
Dental Devices
Digital Facebow Market
Dental Devices
Americas Acrylic Teeth Market
Dental Devices
Dental Implant Motors Market
Dental Devices
Dental Autoclave Market
Dental Devices
Dental Composite Resin Filling Market
Dental Devices
North America Dental Implants and Prosthetics Market
Dental Devices
3D-Printed Dental Restoration Market
Dental Devices
Nano Dentistry Market
Dental Devices
Dental Handpieces Market
Dental Devices
Dental Splints Market