
 US Neurothrombectomy Devices Market | 2026-2036
US Neurothrombectomy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
US Neurothrombectomy Devices Market Insights
Next-generation aspiration catheter technology paired with real-time intravascular imaging is rewriting how physicians approach large-vessel occlusion procedures. Stryker leverages its integrated neurovascular portfolio to control hospital purchasing decisions across the stroke care continuum. Medtronic anchors its position through sustained R&D investment in stent retriever design iterations. Penumbra, Inc. differentiates via specialized aspiration platforms that occupy the fastest-growing procedural niche.
Neurothrombectomy devices are catheter-delivered instruments engineered from nitinol or stainless steel alloys, typically 3-6 French in diameter, designed to engage, fragment, or aspirate intracranial thrombi through transarterial access to restore cerebral perfusion. Stent retriever systems lead procedural volume due to established clinical evidence and broad physician training, while aspiration catheters represent the fastest-expanding segment as direct aspiration first-pass techniques gain adoption. Hospitals command the dominant share of end-user demand given 24/7 interventional neuroradiology staffing requirements and capital-intensive angiography suite infrastructure.
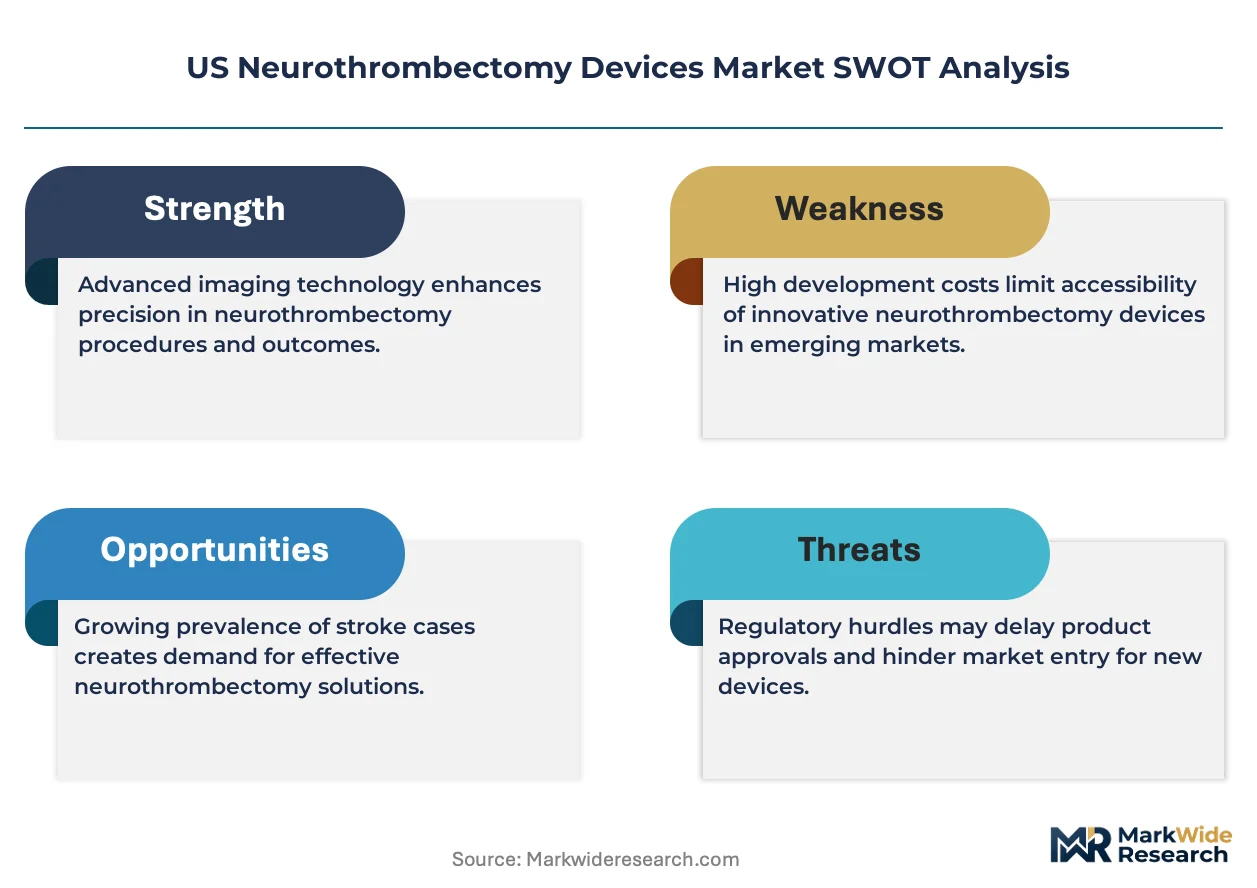
FDA premarket notification pathways and CMS inpatient prospective payment system reimbursement tiers shape product development priorities and hospital adoption economics for mechanical thrombectomy. The National Institutes of Health Stroke Scale certification requirements and Joint Commission comprehensive stroke center standards further constrain market access to facilities meeting minimum procedural volume thresholds. Stakeholders must monitor evolving AHA/ASA guideline revisions and state-level stroke system of care mandates that will determine which device categories capture incremental procedure growth.
Market Dynamics
The transition from stent retriever-first to aspiration-first procedural protocols is compressing device replacement cycles and forcing manufacturers to reconfigure catheter portfolio priorities around single-pass efficiency metrics.
Growth Catalysts
- CMS Mechanical Thrombectomy Reimbursement Tier Expansion:The inpatient prospective payment system now covers emergent large-vessel occlusion procedures at enhanced rates, accelerating hospital capital deployment into angiography suite upgrades.
- Comprehensive Stroke Center Certification Mandates:Joint Commission volume thresholds and 24/7 interventional neuroradiology staffing requirements are standardizing mechanical thrombectomy capability as a core hospital service line.
- Next-Generation Aspiration Catheter Platforms:Large-bore distal access catheter designs with improved trackability are capturing procedural share in Texas, Florida, and California stroke centers.
Market Restraints
- Nitinol Alloy Supply Concentration:Specialized shape-memory wire feedstock for stent retriever manufacturing concentrates among limited superelastic alloy suppliers, creating input cost volatility and qualification timeline risk.
- FDA Breakthrough Device Designation Bottleneck:Expedited review pathways for neurovascular devices have compressed agency bandwidth, extending premarket notification cycle times for non-breakthrough submissions.
- Intravascular Ultrasound Substitution Pressure:Real-time imaging adjuncts for thrombus characterization are displacing some diagnostic angiography runs, though not yet core retrieval procedures.
Strategic Opportunities
- Mobile Stroke Unit Prehospital Deployment:Texas and Florida are piloting ambulance-based CT angiography and teleradiology triage, creating demand for portable aspiration systems compatible with field transport.
- Artificial Intelligence-Enabled Triage Integration:FDA-cleared large-vessel occlusion detection algorithms are converging with cloud-based imaging platforms to compress door-to-puncture intervals.
- State-Level Stroke System of Care Mandates:California's emergency medical services authority routing protocols are directing patients to certified thrombectomy-capable centers, expanding addressable procedure volume.
Industry Challenges
- Interventional Neuroradiologist Training Pipeline Constraints:The Society of Vascular and Interventional Neurology fellowship positions are not scaling with comprehensive stroke center proliferation, creating procedural staffing gaps.
- Angiography Suite Capex Intensity:Biplane fluoroscopy systems with rotational cone-beam CT capability require capital outlays that strain community hospital balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Neurothrombectomy Devices Market |
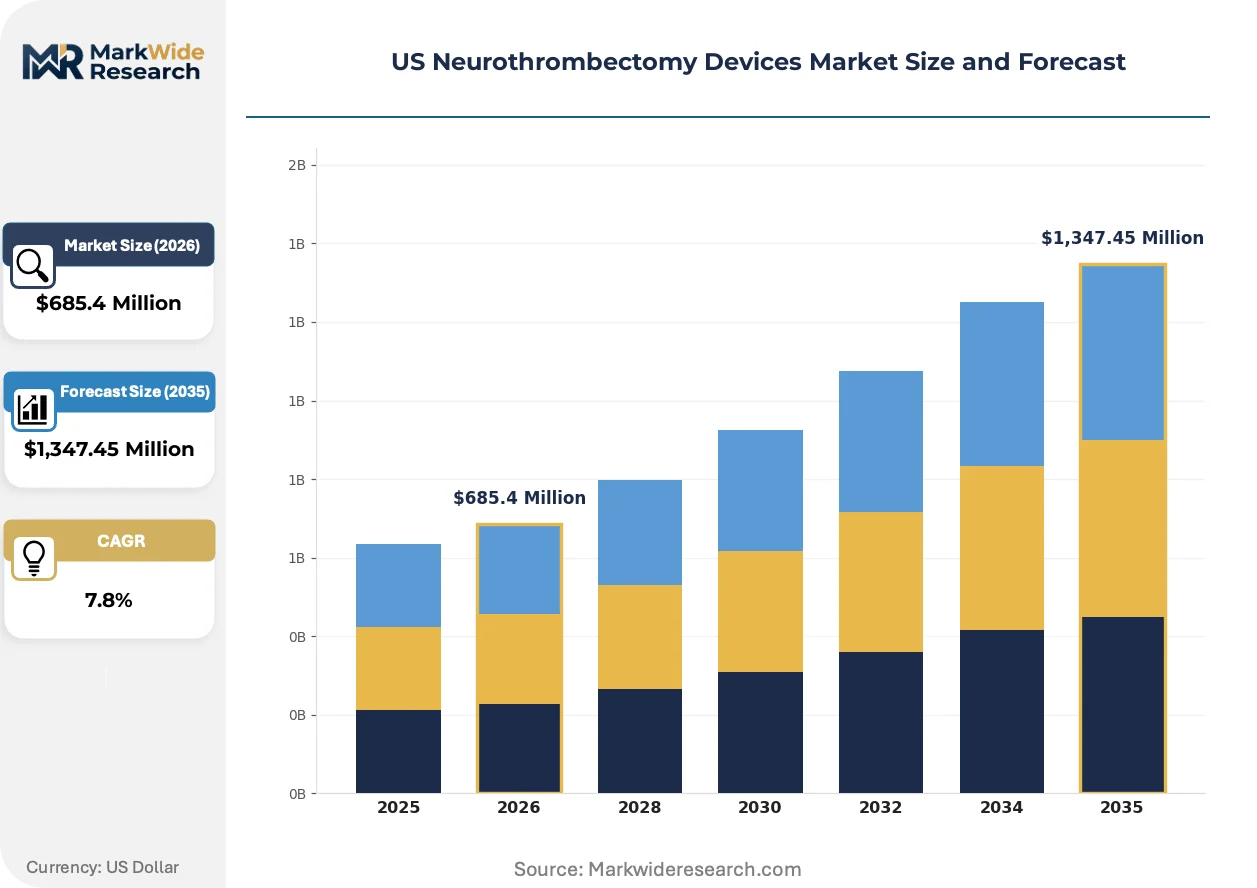
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,347.45 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Stent Retriever, Aspiration Catheter, Embolic Filter, Thrombectomy Systems End User: Hospitals, Ambulatory Surgical Centers, Neurology Clinics, Rehabilitation Centers Procedure Type: Acute Ischemic Stroke, Thromboembolic Events, Interventional Procedures, Emergency Surgeries Material: Stainless Steel, Nitinol, Polymer, Coated Materials |
| Companies Covered | Stryker, Medtronic, Penumbra, Inc., MicroVention, Inc., Boston Scientific Corporation, Johnson & Johnson Services Inc., Acandis GmbH, Phenox GmbH, Vesalio, LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Neurothrombectomy Devices Market Trends and Innovations
Device miniaturization paired with enhanced aspiration power is collapsing the distinction between diagnostic and therapeutic catheter platforms, enabling faster procedural workflows and reducing operator device exchanges.
Distal aspiration catheter technology with integrated aspiration pump compatibility is collapsing the historical trade-off between catheter deliverability and thrombus engagement surface area. Comprehensive stroke centers in high-volume states are adopting these platforms for first-pass mechanical thrombectomy, compressing the market window for intermediate-diameter legacy designs that previously dominated transitional procedural steps.
FDA breakthrough device designation pathways for neurovascular interventions have compressed the regulatory timeline for novel thrombectomy platforms while simultaneously intensifying post-market surveillance requirements. The industrial consequence is a bifurcated development pipeline where well-capitalized manufacturers accelerate PMA submissions while smaller innovators face extended 510(k) clearance delays. Aspiration catheter categories are responding with modular design architectures that accommodate iterative FDA feedback without full platform redesigns.
Hospital value analysis committees are consolidating vendor relationships around integrated stroke care portfolios, displacing the previous multi-manufacturer sourcing model. The segment experiencing this disruption most acutely is community hospitals building initial thrombectomy programs, which are replacing fragmented device procurement with single-source contracts bundling aspiration catheters, stent retrievers, and access equipment. Texas and Florida health systems are most visible in this behavioral shift, driven by Joint Commission comprehensive stroke center standardization timelines.
US Neurothrombectomy Devices Market Segmentation
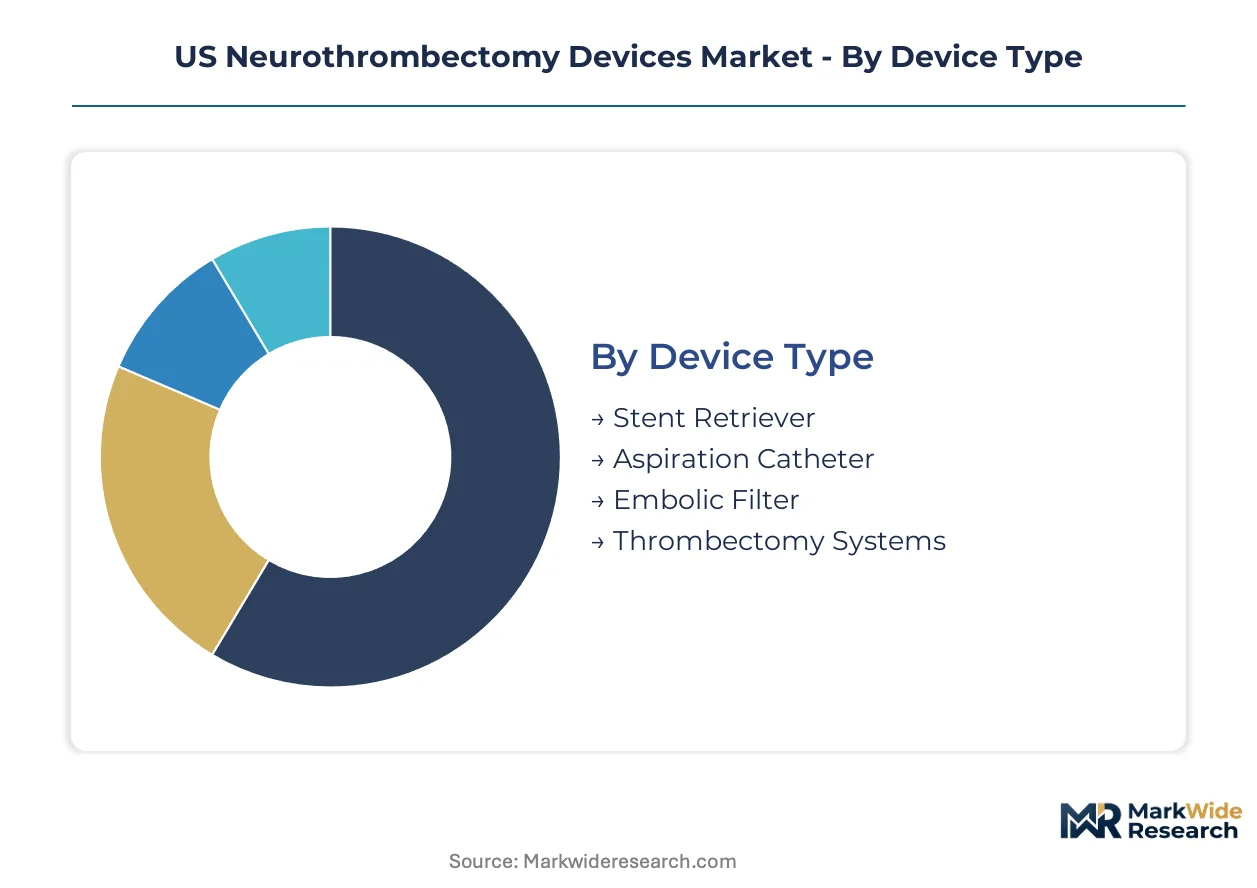
Segmentation reveals how device procurement priorities diverge across clinical settings and procedural workflows. Understanding these splits helps manufacturers align R&D investment with where purchasing authority and volume are actually concentrating.
Device Type:
After-sales-service intensity varies sharply across device categories, with aspiration platforms requiring more intensive technical support and pump integration calibration than passive stent retrievers.
- Stent Retriever:Nitinol mesh cylinders deploy across thrombus length, then collapse to ensnare clot during retrieval. Texas and Florida comprehensive stroke centers maintain highest procedural volumes, driven by established physician training pathways and Joint Commission certification timelines.
- Aspiration Catheter:Large-bore distal access designs with dedicated pump interfaces enable direct thrombus evacuation without stent deployment. California health systems are expanding catheter inventory fastest, responding to state stroke routing mandates that compress door-to-puncture intervals.
- Embolic Filter:Distal protection devices capture fragmented debris during retrieval maneuvers. Deployment concentrates in high-volume academic centers with fellowship training programs.
- Thrombectomy Systems:Integrated platforms combining aspiration and stent retriever capability in single procedure kits. Community hospitals building initial programs favor bundled procurement to reduce vendor complexity.
By volume, Stent Retriever leads. By growth pace, Aspiration Catheter is ahead.
End User:
Capital intensity and staffing requirements create distinct purchasing behaviors across facility types, with reimbursement tier eligibility shaping where device manufacturers concentrate sales resources.
- Hospitals:Comprehensive stroke centers with 24/7 interventional neuroradiology coverage command dominant device consumption. CMS inpatient prospective payment system enhanced rates for large-vessel occlusion procedures accelerate angiography suite upgrades in Texas, Florida, and California systems.
- Ambulatory Surgical Centers:Limited penetration due to emergency case nature and required imaging infrastructure. Selective outpatient thrombectomy programs are emerging in states with permissive certificate-of-need frameworks.
- Neurology Clinics:Diagnostic and post-acute monitoring functions predominate; device procurement minimal.
- Rehabilitation Centers:Post-thrombectomy care coordination without direct device utilization.
Hospitals capture the dominant revenue share. Ambulatory Surgical Centers are expanding most quickly where regulatory frameworks permit.
Procedure Type:
Clinical urgency and reimbursement classification determine device selection protocols, with emergent cases commanding premium catheter specifications and elective interventions permitting cost-conscious sourcing.
- Acute Ischemic Stroke:Time-critical large-vessel occlusion procedures drive aspiration-first protocol adoption. Door-to-puncture interval pressures in California EMS routing systems favor single-pass efficiency devices.
- Thromboembolic Events:Secondary clot migration during cardiac or peripheral interventions requires adaptable retrieval tools. Hybrid angiography suites in Florida cardiac centers see cross-specialty demand.
- Interventional Procedures:Scheduled neurovascular interventions allow device standardization and vendor contract optimization.
- Emergency Surgeries:Trauma-associated cerebrovascular compromise creates unpredictable demand spikes.
Acute Ischemic Stroke dominates procedural volume. Aspiration-first technique diffusion is climbing fastest.
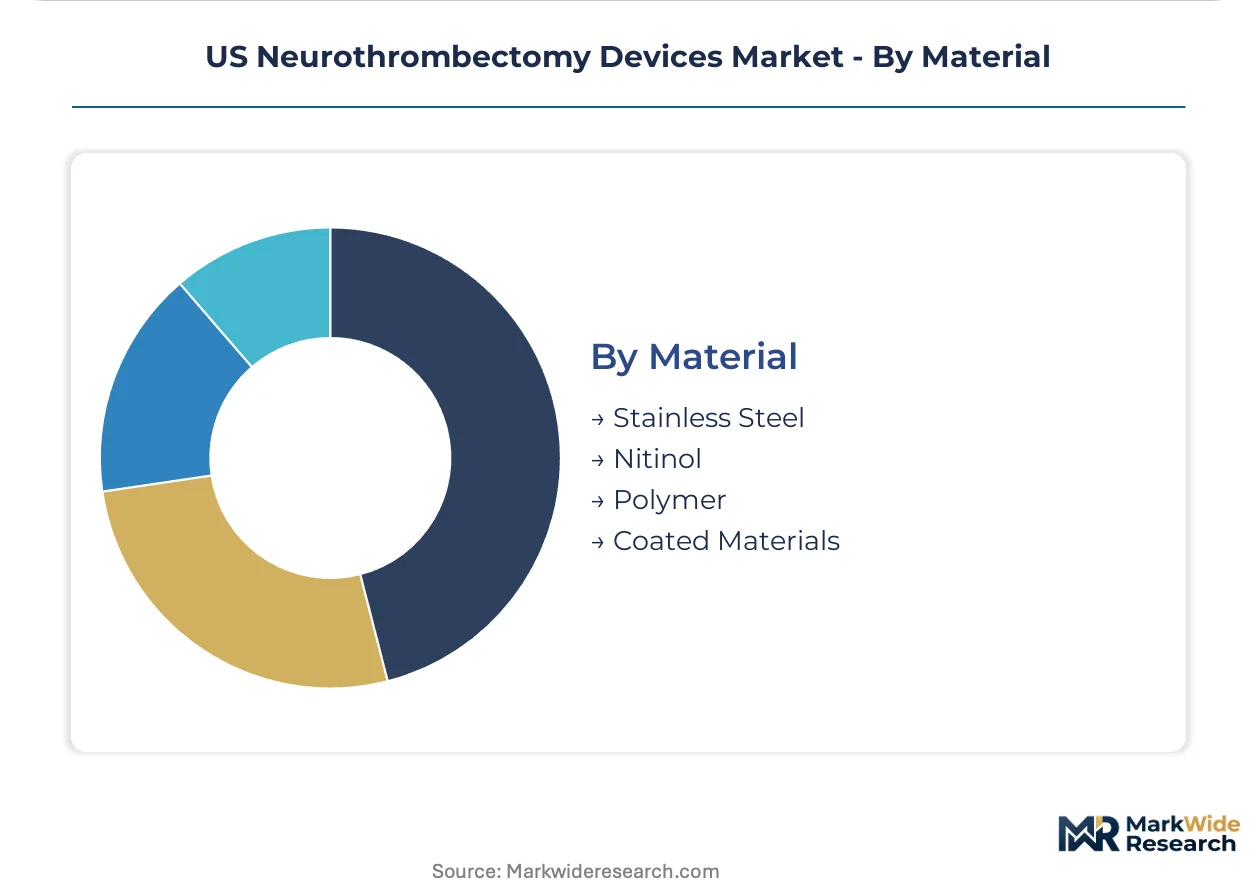
Material:
Supply chain concentration and alloy qualification timelines create divergent input cost structures across material categories, with specialized nitinol sourcing constraining stent retriever production scaling.
- Nitinol:Superelastic nickel-titanium alloy enables self-expanding stent retriever deployment and collapse. Shape-memory wire feedstock concentrates among limited qualified suppliers, creating procurement lead time risk for manufacturers.
- Stainless Steel:Lower-cost alternative for access catheter shafts and structural components. Texas device fabricators leverage regional metalworking infrastructure for cost-competitive sourcing.
- Polymer:Catheter liner and jacket materials enabling trackability and thrombus engagement surface optimization.
- Coated Materials:Hydrophilic and thromboresistant surface treatments reducing friction and platelet adhesion.
Nitinol commands premium positioning. Polymer formulations are gaining share fastest through catheter miniaturization trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US-manufactured neurothrombectomy devices flow primarily to domestic comprehensive stroke centers, with Texas, Florida, and California absorbing the dominant procurement volumes. State-level stroke system mandates and Joint Commission certification timelines concentrate demand in these corridors.
Texas
Houston and Dallas-Fort Worth health systems deploy the highest aspiration catheter volumes nationwide. The Texas Department of State Health Services enforces emergency medical services routing protocols that direct large-vessel occlusion patients to certified thrombectomy centers. Medical device distribution hubs in the Texas Medical Center coordinate just-in-time inventory for 24/7 interventional neuroradiology suites.
Florida
Tampa Bay and South Florida stroke centers lead adoption of next-generation aspiration platforms. Florida's Agency for Health Care Administration ties Medicaid reimbursement to comprehensive stroke center designation, accelerating capital deployment. Jacksonville and Miami metropolitan clusters host the densest concentration of mobile stroke unit pilot programs.
California
Los Angeles and San Francisco Bay Area facilities command premium device specifications under state EMS authority routing mandates. California's Office of Statewide Health Planning and Development requires biplane angiography capability for comprehensive stroke center certification. Sacramento and San Diego health systems are expanding catheter inventory fastest to meet door-to-puncture interval benchmarks.
New York
New York City metropolitan hospitals maintain high stent retriever procedural volumes through established fellowship training pipelines. The New York State Department of Health certificate-of-need process constrains new comprehensive stroke center entrants, protecting incumbent device demand. Buffalo and Rochester academic medical centers anchor upstate thrombectomy capability expansion.
Illinois
Chicago-area health systems balance aspiration-first protocol adoption with legacy stent retriever infrastructure. The Illinois Department of Public Health stroke system of care regulations mandate interfacility transfer agreements for thrombectomy-eligible patients. Northwestern and University of Chicago medical centers drive device specification standards across the Midwest referral basin.
US Neurothrombectomy Devices Market Competitive Landscape
Channel-controlling players compete with product-specialist players across portfolio breadth versus procedural focus. The vendor base organizes around three strategic archetypes: integrated stroke-care portfolio holders, aspiration platform specialists, and stent retriever design innovators. Consolidation pressure intensifies as hospital value analysis committees demand bundled procurement contracts. Competitive moves center on single-source contract capture and modular catheter architectures that accelerate FDA feedback integration.
Within the integrated portfolio tier, Stryker and Medtronic anchor hospital purchasing decisions through comprehensive stroke-care offerings. Penumbra, Inc. exemplifies the aspiration-specialist archetype with concentrated investment in large-bore distal access platforms. Among European-based innovators, Acandis GmbH and Phenox GmbH occupy positions emphasizing stent retriever design iteration and regional regulatory expertise.
| Leading Market Players |
|---|
| Stryker |
| Medtronic |
| Penumbra, Inc. |
| MicroVention, Inc. |
| Boston Scientific Corporation |
| Johnson & Johnson Services Inc. |
| Acandis GmbH |
| Phenox GmbH |
| Vesalio, LLC |
| Others |
Pricing and Supply Chain Analysis
Nitinol alloy supply concentration among limited superelastic wire feedstock suppliers determines both tiered pricing spreads across stent retriever generations and the geographic shape of catheter manufacturing networks. FDA qualification timelines for new alloy sources extend procurement lead times, compressing margins for manufacturers without long-term offtake agreements while rewarding integrated players with captive nitinol supply.
Pricing Analysis
Next-generation aspiration catheter platforms command substantial premiums over intermediate-diameter legacy designs and prior-generation stent retrievers. Three-tier pricing structure across premium, standard, and economy levels segments by catheter deliverability specifications and pump integration capability, with FDA breakthrough designation status anchoring the top tier. Pricing pressure stems from hospital value analysis committee consolidation around single-source stroke care portfolios. Community hospitals building initial thrombectomy programs exhibit highest price sensitivity, while comprehensive stroke centers in Texas and California prioritize single-pass efficiency metrics over unit cost.
Supply Chain Analysis
Extended payment terms from Texas and Florida health systems to device distributors are compressing working capital cycles upstream to nitinol wire fabricators and catheter extrusion houses. Superelastic alloy feedstock concentrates in the United States and Germany, with polymer liner materials sourced from Japan and specialty coating chemistries from Switzerland. Supply chain risk centers on single-source vulnerability for shape-memory wire qualification under FDA 21 CFR Part 820 quality system requirements. Distribution runs through regional medical device hubs in the Texas Medical Center and Jacksonville metropolitan clusters serving 24/7 interventional neuroradiology suites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts for aspiration pump calibration and catheter compatibility verification are expanding faster than hardware unit sales, transforming procurement economics toward recurring-revenue relationships. This service-attach dynamic favors manufacturers with field engineering density in high-volume stroke corridors.
For Market Incumbents: Build integrated stroke care portfolio moats by bundling aspiration catheters, stent retrievers, and access equipment under exclusive hospital system contracts. Anchor defensive positioning through backward integration into nitinol alloy sourcing to neutralize feedstock volatility. Expand field service headcount in Texas and Florida faster than device sales growth to capture technical support recurring revenue.
For New Entrants and Emerging Players: Mid-market community hospitals in Illinois and New York represent the most penetrable entry point, protected from incumbent saturation by certificate-of-need regulatory barriers that slow comprehensive stroke center proliferation. California's state EMS routing mandates create demand for portable aspiration systems compatible with mobile stroke unit deployment. Pursue modular catheter architectures enabling rapid FDA feedback integration without platform redesign.
For Investors and Strategic Acquirers: FDA breakthrough device designation pathway expansion reshapes the acquisition landscape toward platforms with expedited review status and established post-market surveillance infrastructure. Long-term viability across the analysis window hinges on reimbursement strategy execution under CMS inpatient prospective payment system tier evolution. Target acquisition candidates with aspiration-first protocol clinical data packages. Monitor Joint Commission comprehensive stroke center certification timelines as volume inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Designation Pursuit | Expedited review compresses time-to-revenue for novel catheter platforms against standard 510(k) pathways. |
| Hospital System Partnership | Single-source contracts with Texas and Florida health systems lock out competing vendors through bundled procurement. |
| Software Companion Development | AI-enabled large-vessel occlusion detection algorithms integrate with cloud imaging to reduce door-to-puncture intervals. |
| Reimbursement Strategy | CMS mechanical thrombectomy tier expansion determines hospital capital deployment into angiography suite upgrades. |
| CE Marking Pathway | EU MDR compliance for nitinol stent retrievers opens parallel revenue streams outside domestic CMS reimbursement. |
Research Methodology
The analysis maps aspiration catheter platforms, stent retriever systems, embolic protection devices, and integrated thrombectomy kits, each validated through interventional neuroradiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) and PMA filings, CMS Medicare reimbursement databases, Joint Commission certification records, and hospital procurement contract repositories. Bottom-up device unit demand modeling triangulated against top-down health system capital expenditure tracking.
Forecast assumptions held fixed the current CMS inpatient prospective payment system reimbursement tier structure while varying state-level stroke system mandate adoption rates across the projection horizon. Segmentation dimensions modeled include device type, end-user facility tier, procedure urgency classification, and material composition. CAGRs derived from procedure volume elasticity to comprehensive stroke center certification timelines and catheter replacement cycle compression under aspiration-first protocol diffusion. Forecast inputs incorporated interventional neuroradiologist fellowship pipeline scaling and biplane angiography suite installation rates.
Practitioners should monitor FDA breakthrough designation queue depth, nitinol alloy spot pricing volatility, and state EMS routing mandate implementation for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Plastic Surgery Devices Market
Medical Devices
Left Atrial Appendage (LAA) Closure Device Market
Medical Devices
Tracheobronchial Suction Catheters Market
Medical Devices
Brazil Aesthetic Devices Market
Medical Devices
Portable Medical Electronic Products Market
Medical Devices
Baby Thermometer Market
Medical Devices
Asia-Pacific Interventional Cardiology and Peripheral Vascular Devices Market
Medical Devices
Europe Foot Orthotic Insoles Market
Medical Devices
Heart Failure POC and LOC Devices Market
Medical Devices
Embolization Coils Market
Medical Devices
Knee Braces Market
Medical Devices
Continuous Passive Motion Devices Market
Medical Devices
In Vitro Fertilization Monitoring System Market
Medical Devices
Middle East and Africa Single-Use Medical Device Reprocessing Market
Medical Devices
Global Trauma Devices Market
Medical Devices
Blood Warmers Market