
 Critical Care Devices Market | 2026-2036
Critical Care Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Critical Care Devices Market Analysis
Intensivist staffing shortages across developed health systems is collapsing throughput capacity in tertiary ICUs and forcing hospitals toward device automation. Medtronic leverages its integrated critical care portfolio to sustain installed-base loyalty across mechanical ventilation and monitoring platforms. Baxter anchors its position through deep specialization in infusion therapy and renal replacement systems for ICU settings. Philips competes on digital monitoring density, while Hamilton Medical dominates high-performance ventilator engineering for acute respiratory failure.
Critical care devices comprise electromechanical and digital systems engineered for continuous physiological support, typically operating with precision tolerances of ±2-5% for infusion delivery and pressure-controlled ventilation algorithms. These systems serve the primary commercial purpose of sustaining organ function during acute decompensation in institutional settings. Ventilators and digital monitoring platforms capture the dominant margin pools as hospitals prioritize respiratory support infrastructure and real-time data integration. Infusion pumps represent a mature replacement-driven segment where smart device connectivity is creating differentiation. Monitors and resuscitation devices see fastest growth in emergency departments as triage protocols demand earlier hemodynamic surveillance.
FDA premarket notification requirements and EU MDR technical documentation standards impose substantial validation burdens that filter market access toward established manufacturers with regulatory infrastructure. The EPA and OSHA frameworks additionally shape device material specifications and workplace safety protocols for clinical deployment. Stakeholders must weigh reimbursement trajectory against capital equipment refresh cycles as health systems recalibrate ICU expansion plans.
Market Dynamics
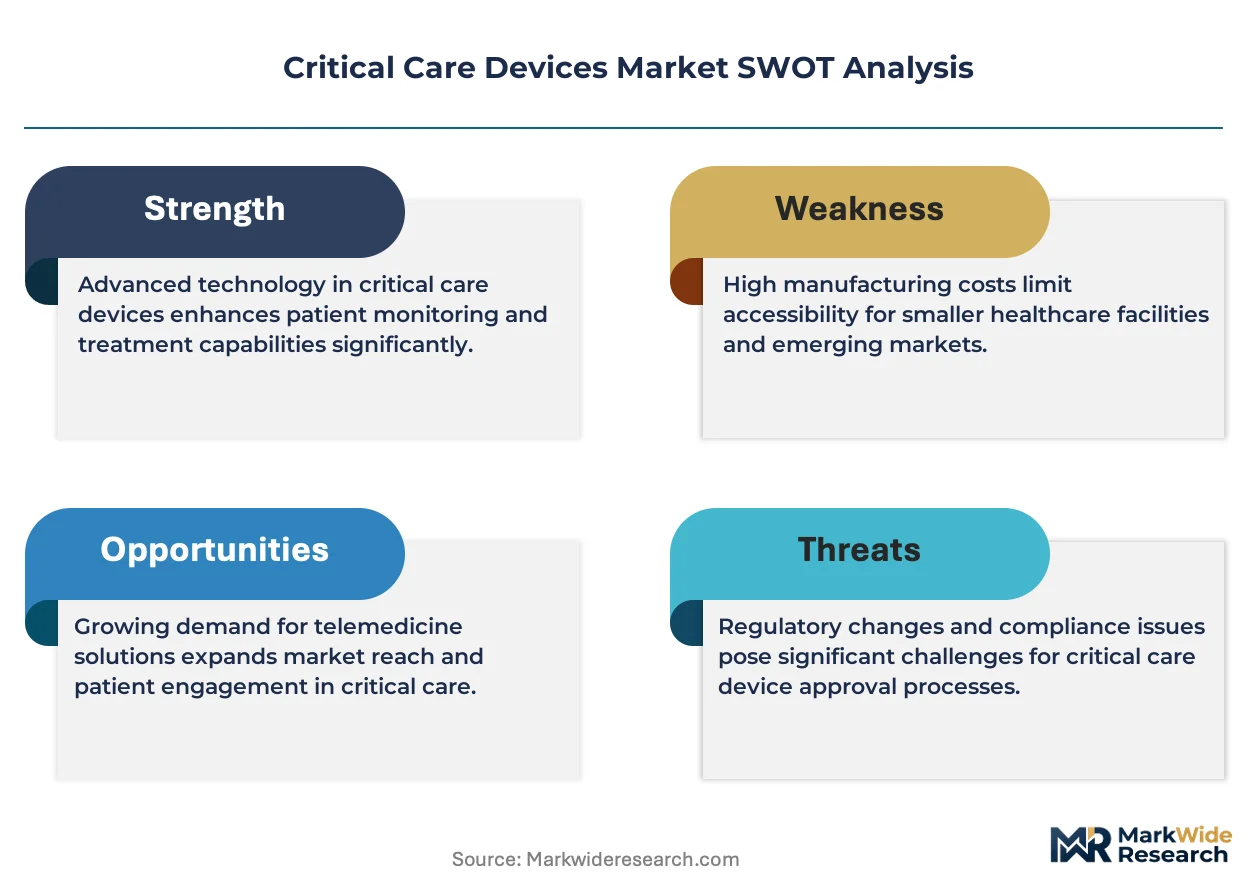
Intensivist staffing shortages across developed health systems are forcing hospitals toward device automation, compressing throughput capacity in tertiary ICUs and accelerating capital deployment into autonomous monitoring and ventilation platforms that reduce bedside labor intensity.
Growth Catalysts
- EU MDR Conformity Assessments:The Medical Device Regulation's enhanced clinical evidence requirements are filtering market access toward established manufacturers with robust quality management systems, consolidating procurement decisions around compliant suppliers.
- Mechanical Ventilation Infrastructure:Acute respiratory failure protocols in tertiary hospitals are expanding ventilator fleet sizes and upgrade cycles as pandemic-era depreciation schedules mature.
- China:Hospital infrastructure expansion in tier-one cities is concentrating demand for integrated critical care platforms as the country scales ICU bed capacity per capita toward OECD benchmarks.
Market Restraints
- Semiconductor Component Volatility:Precision sensor and processor supply concentration in East Asian foundries creates input cost instability for ventilator and monitor manufacturers.
- FDA Premarket Notification Burden:The 510(k) pathway's substantial equivalence demonstrations and clinical validation timelines extend product launch cycles by 18-36 months for novel device categories.
- Renal Replacement System Maturity:Infusion pump and CRRT device markets face replacement-driven saturation in North American and Western European installed bases.
Strategic Opportunities
- India:Underpenetrated ICU infrastructure in secondary cities creates whitespace for mid-tier monitoring and ventilation platforms as hospital accreditation standards tighten.
- Closed-Loop Anesthesia Integration:Convergence of AI-driven sedation algorithms with mechanical ventilation control is enabling autonomous critical care workflows in academic medical centers.
- OSHA Workplace Safety Mandates:Enhanced exposure limits for anesthetic gases and radiation are driving replacement demand for containment-integrated delivery systems in surgical ICUs.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Specialized expertise in ventilator algorithm development and hemodynamic signal processing concentrates at a handful of academic and corporate research centers.
- Legacy Device Interoperability:Proprietary data protocols from 1990s-era monitoring platforms resist integration with contemporary HL7 FHIR architectures, fragmenting hospital IT roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Critical Care Devices Market |
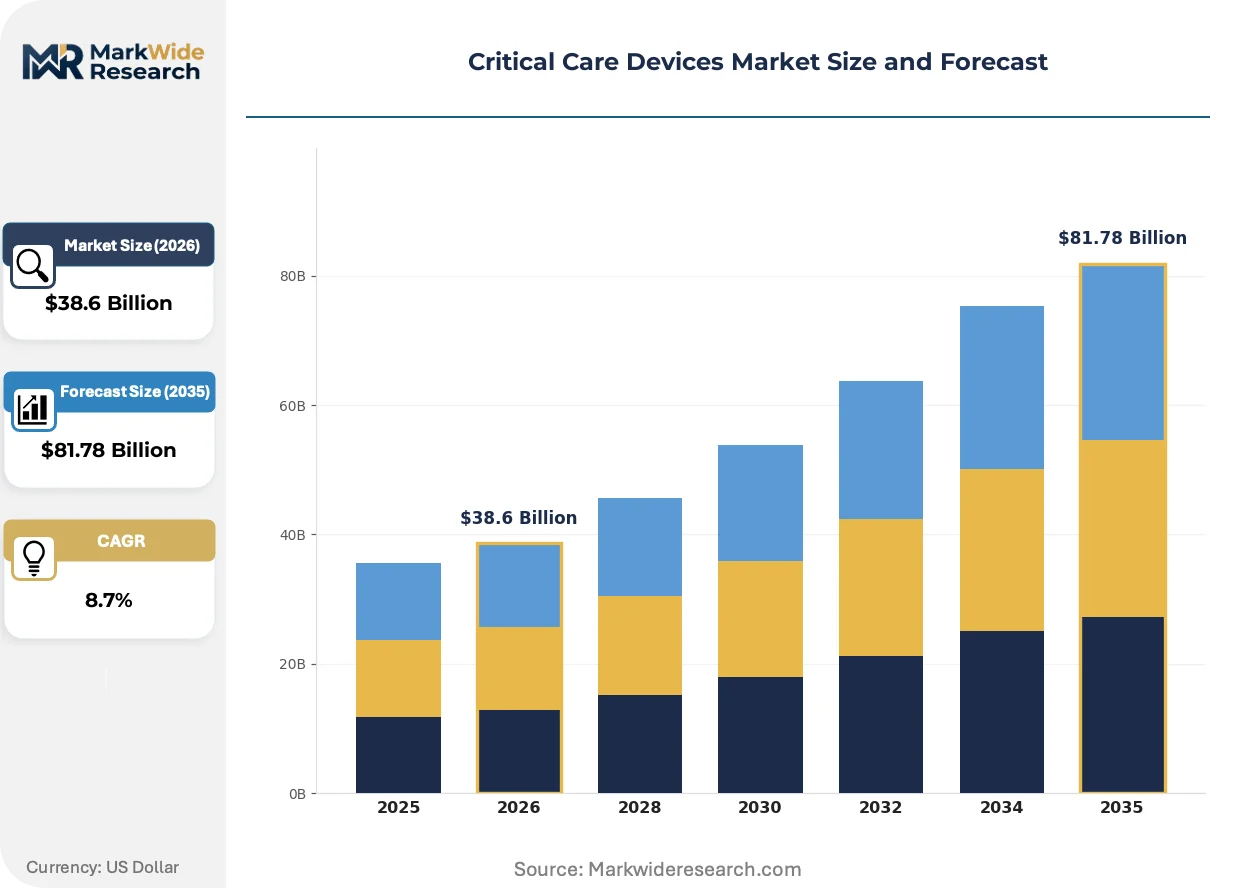
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $81.78 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ventilators, Infusion Pumps, Monitors, Resuscitation Devices End User: Hospitals, Emergency Departments, Intensive Care Units, Surgical Centers Technology: Mechanical Ventilation, Digital Monitoring, Infusion Technology, Smart Devices Application: Cardiac Care, Respiratory Support, Anesthesia, Trauma Management |
| Companies Covered | Medtronic, Baxter, GE Healthcare, Koninklijke Philips, Drägerwerk, Getinge, Fresenius Medical Care, B. Braun Melsungen, Hamilton Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Critical Care Devices Market Emerging Trajectories
Digital telemetry and edge computing architectures are reshaping how physiological data flows through critical care workflows, compressing decision latency while expanding the perimeter of surveillance beyond traditional bedside boundaries.
Edge AI inference engines embedded directly into patient monitors are fragmenting the traditional central station model. Tertiary hospitals in Germany and the United States are deploying these systems for real-time arrhythmia detection and sepsis risk scoring. The technology is fragmenting vendor lock-in by enabling modular algorithm marketplaces that decouple hardware from clinical decision support.
EU MDR technical documentation standards and post-market surveillance requirements are extending validation timelines for software-as-a-medical-device components. Manufacturers must now maintain continuous clinical evidence pipelines for algorithm updates that previously shipped as routine firmware revisions. Hemodynamic monitoring platforms with embedded AI classifiers face the steepest compliance burden as notified bodies scrutinize black-box decision logic.
Hospital procurement departments are consolidating vendor relationships through enterprise-wide critical care platform contracts that bundle ventilation, monitoring, and infusion therapy under single-source agreements. Group purchasing organizations in the United States are negotiating these arrangements to reduce service contract fragmentation. The shift is most visible in multi-hospital health systems seeking to standardize training protocols and spare parts inventories across dispersed ICU networks.
Critical Care Devices Market Segmentation
Critical care device procurement flows through distinct channel configurations that shape how manufacturers structure their go-to-market operations. Each segmentation dimension reveals different pressure points for pricing, service bundling, and technology integration strategies.
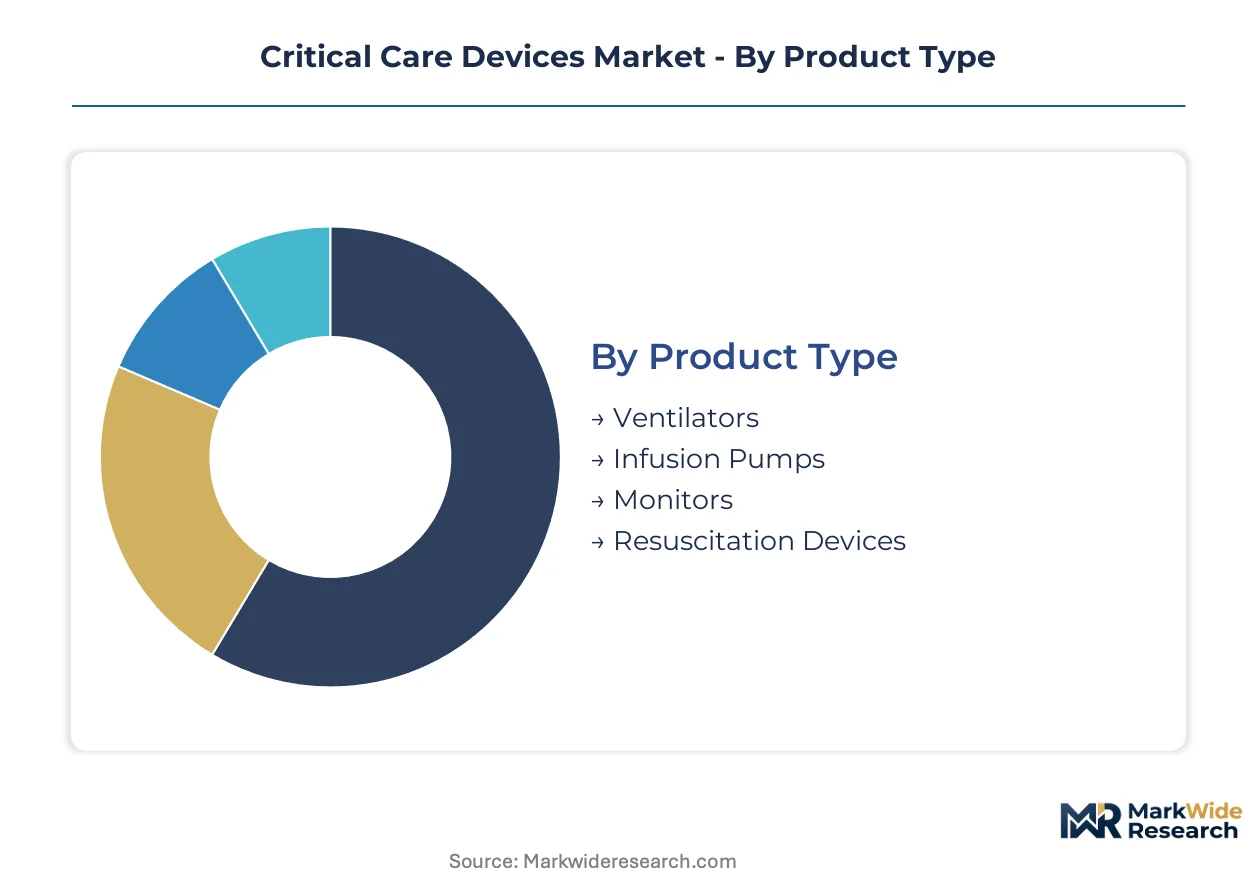
Product Type:
Channel economics vary sharply across product categories, with capital-intensive systems demanding direct sales forces while consumable-heavy segments accommodate distributor networks.
- Ventilators:Electromechanical systems delivering pressure-controlled or volume-controlled respiratory support with precision algorithms. Demand concentrates in tertiary hospital ICUs across the United States, Germany, and China as these markets expand mechanical ventilation fleet sizes to address acute respiratory failure protocols.
- Monitors:Digital telemetry platforms integrating multi-parameter physiological surveillance with edge computing architectures. Emergency departments in academic medical centers are driving replacement cycles as triage protocols demand earlier hemodynamic surveillance and real-time data integration.
- Infusion Pumps:Programmable electromechanical devices for controlled fluid and medication delivery with smart connectivity features.
- Resuscitation Devices:Emergency intervention equipment including defibrillators and airway management tools for acute decompensation scenarios.
Monitors dominate installed base. Ventilators are where expansion concentrates.
End User:
Customer scale and clinical acuity determine procurement sophistication, with large health systems negotiating enterprise-wide platform contracts against fragmented purchasing in smaller facilities.
- Intensive Care Units:High-acuity institutional settings requiring continuous multi-organ support through integrated device ecosystems. Tertiary hospitals in the United States and Germany are consolidating vendor relationships through single-source agreements bundling ventilation, monitoring, and infusion therapy to standardize training protocols across dispersed networks.
- Emergency Departments:Rapid-triage environments demanding portable surveillance and intervention capabilities with minimal setup latency. Digital monitoring platforms with embedded AI classifiers are climbing the fastest here as edge AI inference engines fragment traditional central station models.
- Hospitals:General acute care facilities with mixed acuity levels and capital budget constraints.
- Surgical Centers:Ambulatory settings with focused procedure volumes and compressed recovery timelines.
Intensive Care Units anchor revenue concentration. Emergency Departments are gaining share fastest.
Technology:
Regulatory classification complexity separates premium-priced validated systems from commoditized hardware, with software-as-a-medical-device components facing extended EU MDR validation timelines.
- Digital Monitoring:Telemetry architectures with embedded algorithmic decision support and HL7 FHIR interoperability capabilities. EU MDR post-market surveillance requirements are extending validation timelines for software updates that previously shipped as routine firmware revisions.
- Mechanical Ventilation:Precision electromechanical systems with closed-loop control algorithms for acute respiratory support. FDA premarket notification pathways impose substantial equivalence demonstrations that extend product launch cycles for novel ventilation modes.
- Smart Devices:Connectivity-enabled equipment with remote monitoring and predictive maintenance capabilities.
- Infusion Technology:Mature pump mechanics with incremental software differentiation for dose error reduction.
Mechanical Ventilation commands premium pricing. Digital Monitoring shows steepest expansion trajectory.
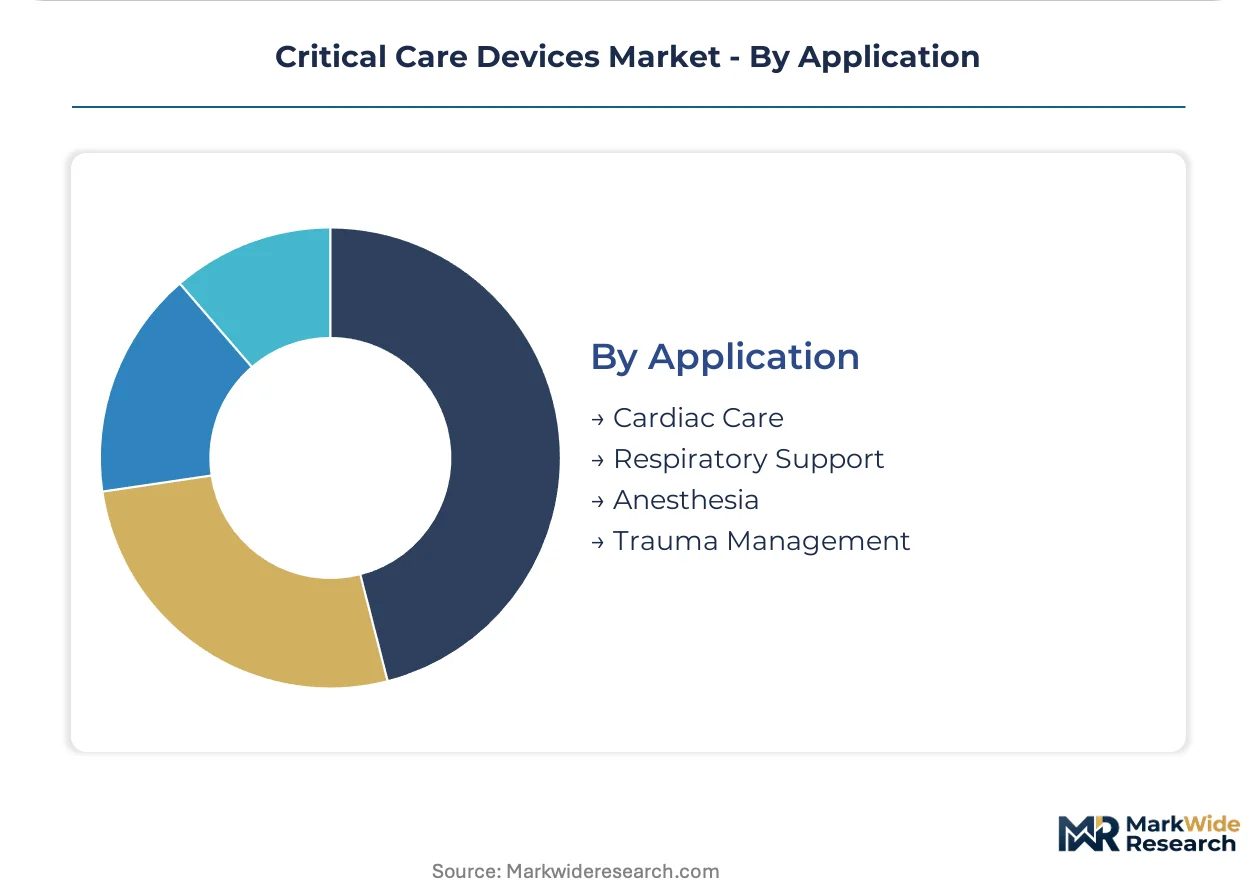
Application:
Clinical workflow integration requirements shape device specification priorities, with anesthesia and cardiac applications demanding highest precision tolerances.
- Respiratory Support:Ventilation and oxygenation management for acute and chronic respiratory failure. China is scaling ICU bed capacity per capita toward OECD benchmarks, concentrating demand for high-performance ventilator engineering in tier-one cities.
- Cardiac Care:Hemodynamic monitoring and circulatory support for acute coronary syndromes and arrhythmia management. Germany's tertiary hospitals are deploying edge AI inference engines for real-time arrhythmia detection, fragmenting vendor lock-in through modular algorithm marketplaces.
- Anesthesia:Sedation delivery and physiological maintenance during surgical procedures.
- Trauma Management:Rapid stabilization protocols for acute injury and hemorrhage control.
Respiratory Support leads capital deployment. Cardiac Care is where technology differentiation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA premarket notification pathways anchor the United States as the dominant geography for critical care device commercialization, while EU MDR conformity assessments reshape European market access. China scales ICU infrastructure toward OECD benchmarks. Germany and India concentrate specialized manufacturing and whitespace demand respectively.
United States
Tertiary hospitals expand mechanical ventilation fleet sizes as pandemic-era depreciation schedules mature. FDA 510(k) pathways impose substantial equivalence demonstrations extending product launch cycles for novel device categories. The Boston-Cambridge corridor concentrates biomedical engineering talent for ventilator algorithm development.
Germany
Academic medical centers deploy edge AI inference engines for real-time arrhythmia detection and sepsis risk scoring. EU MDR technical documentation standards filter market access toward established manufacturers with robust quality management systems. The Baden-Württemberg industrial cluster anchors precision electromechanical manufacturing for ICU platforms.
China
Hospital infrastructure expansion in tier-one cities concentrates demand for integrated critical care platforms. NMPA regulatory harmonization with international standards accelerates approval timelines for multinational manufacturers. The Yangtze River Delta region scales domestic production capacity for monitoring and ventilation systems.
India
Underpenetrated ICU infrastructure in secondary cities creates whitespace for mid-tier monitoring and ventilation platforms. CDSCO medical device rules tighten hospital accreditation standards driving procurement upgrades. Maharashtra and Karnataka concentrate private hospital chain expansion and medical device distribution networks.
Japan
Aging demographics expand chronic respiratory failure patient volumes requiring sustained ventilation support. PMDA regulatory frameworks emphasize post-market surveillance for software-as-a-medical-device components. The Kanto region around Tokyo concentrates academic medical center adoption of autonomous critical care workflows.
Critical Care Devices Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding enterprise-wide platform contracts that bundle ventilation, monitoring, and infusion therapy. The middle tier fragments across single-modality specialists and regional manufacturers with focused geographic footprints. Two strategic archetypes dominate: diversified health technology conglomerates with deep regulatory infrastructure, and precision engineering specialists with concentrated ventilator or renal replacement expertise. Competitive moves center on M&A for digital monitoring capabilities and strategic partnerships for AI algorithm marketplaces.
Among diversified health technology conglomerates, Medtronic and Koninklijke Philips exemplify the integrated platform archetype, anchoring enterprise procurement decisions through bundled service contracts. Baxter occupies a position within the precision therapy specialist tier, representing deep specialization in infusion and renal replacement systems. Hamilton Medical sits within the high-performance engineering segment, exemplifying concentrated expertise in acute respiratory support platforms.
| Leading Market Players |
|---|
| Medtronic |
| Baxter |
| GE Healthcare |
| Koninklijke Philips |
| Drägerwerk |
| Getinge |
| Fresenius Medical Care |
| B. Braun Melsungen |
| Hamilton Medical |
| Others |
Supply Flow & Price Mechanics
FDA 510(k) premarket notification pathways and EU MDR conformity assessments gate both supplier qualification and price differentiation simultaneously, filtering market access toward established manufacturers with robust regulatory infrastructure while compressing margins for non-compliant entrants. Hospitals in the United States and Germany leverage enterprise-wide platform contracts to extract volume discounts from bundled ventilation, monitoring, and infusion systems, concentrating procurement power among multi-hospital health systems.
Pricing Analysis
Geographic price spreads of 15-25% separate premium-tier German and US hospital contracts from mid-tier Indian and Chinese procurement, reflecting certification grade differentials and after-sales service bundling. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA/CE marking tier and algorithmic capability depth, with edge-AI-enabled monitors commanding substantial premiums over base telemetry units. Cost compression in the economy tier is intensifying because domestic Chinese manufacturers are scaling production capacity for export markets. Emergency departments exhibit highest price sensitivity due to capital budget constraints, while academic medical centers in Germany and the United States demonstrate lowest sensitivity when purchasing closed-loop anesthesia integration platforms.
Supply Chain Analysis
Inventory lead times for precision pressure sensors and edge-computing processors have extended from 12 weeks to 26 weeks since pandemic-era disruptions, forcing ventilator and monitor manufacturers to hold larger safety stocks. Component supply concentrates in Taiwan, South Korea, and China for semiconductor foundry output, with Germany and Switzerland anchoring precision electromechanical subassembly production. Raw material dependencies span medical-grade aluminum enclosures, silicone diaphragms for pneumatic circuits, and lithium-ion battery cells for portable resuscitation devices. Single-source vulnerability in East Asian semiconductor foundries poses structural risk for algorithm-enabled monitoring platforms. Distribution runs through direct sales forces for capital-intensive systems and authorized distributor networks for consumable-heavy infusion pump segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has shifted decisively toward consolidated hospital procurement committees and group purchasing organizations in the United States, fragmenting vendor relationships and extracting bundled pricing concessions across multi-year enterprise agreements.
For Market Incumbents: Shield installed-base loyalty by deepening algorithmic differentiation through modular AI marketplaces that decouple hardware from clinical decision support, countering emerging software-as-a-medical-device entrants. Prioritize backward integration into precision sensor supply through partnerships with Taiwanese foundries, reducing exposure to semiconductor allocation volatility. Vertical control over ventilator algorithm development talent in the Boston-Cambridge and Baden-Württemberg clusters represents a critical defensive lever against mid-tier engineering competitors. For New Entrants and Emerging Players: Lead with mid-tier monitoring platforms targeting secondary cities in India where ICU infrastructure remains underpenetrated and hospital accreditation standards are tightening procurement requirements. Position against legacy device interoperability gaps by offering native HL7 FHIR architectures that integrate seamlessly with contemporary hospital IT roadmaps. A direct-to-hospital sales model bypassing established distributor networks captures margin in price-sensitive emergency department segments. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified health technology conglomerates seeking to divest non-core critical care assets, particularly renal replacement and infusion therapy divisions facing replacement-driven saturation in Western markets. Long-term viability over the coming decade hinges on software-as-a-medical-device revenue streams with recurring validation burdens rather than pure hardware replacement cycles. Monitor FDA premarket notification backlog trends as an inflection indicator for approval timeline compression and novel device category entry feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Shortens product launch cycles for AI-enabled hemodynamic monitors competing in US academic medical centers. |
| EU MDR Technical Documentation Investment | Consolidates market access for established manufacturers against notified body scrutiny of algorithm updates. |
| Hospital System Partnership | Locks in enterprise-wide platform contracts bundling ventilation, monitoring, and infusion across dispersed ICU networks. |
| Software Companion Development | Enables modular algorithm marketplaces that fragment vendor lock-in through edge AI inference engines. |
| Reimbursement Strategy Alignment | Captures capital equipment refresh cycles as health systems recalibrate ICU expansion plans against Medicare trajectory. |
Methodological Framework
Cross-validation between primary interviews with hospital purchasing committees, biomedical engineers, and GPO contracts managers and secondary validation against FDA 510(k) filings, EU MDR notified body databases, and hospital procurement contract registries anchors the qualitative findings. Bottom-up triangulation across installed base estimates and replacement cycle assumptions integrates with top-down macroeconomic health expenditure models. Primary fieldwork captured perspective from intensive care clinicians in tertiary hospitals across the United States, Germany, China, and India, supplemented by regulatory affairs specialists and ventilator algorithm development engineers.
Sensitivity analysis across semiconductor cost volatility scenarios and intensivist staffing shortage projections tests forecast robustness throughout the projection horizon. The analytical framework segments by product type, end-user acuity tier, technology classification, and clinical application, with additional granularity on regulatory pathway cluster and geographic procurement sophistication. CAGRs derive from logistic diffusion curves fitted to historical ICU bed expansion rates and capital equipment depreciation schedules. Key inputs include pandemic-era ventilator fleet depreciation maturation timelines and China ICU bed capacity convergence toward OECD benchmarks.
The analysis sits within stated boundaries; outcomes outside sustained health system capital expenditure commitment or accelerated EU MDR implementation timelines would require recalibration. Forecasts reflect documented assumptions regarding semiconductor supply normalization and regulatory harmonization progress. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Single-Use Assemblies Market
Medical Devices
Injection Pen Market
Medical Devices
Gastric Space-Occupying Devices Market
Medical Devices
Global Medical Device Connectors Market
Medical Devices
South Africa Digital X-Ray Devices Market
Medical Devices
Asia Pacific Apheresis Market
Medical Devices
Asia-Pacific Wearable Medical Devices Market
Medical Devices
Cardiac Implants Market
Medical Devices
Water Bath Vaporizer Market
Medical Devices
India Drug Delivery Devices Market
Medical Devices
Global Foley Catheters Market
Medical Devices
Hydrogen Inhalers Market
Medical Devices
Transcutaneous Oximetry Systems Market
Medical Devices
Global Cerebral Somatic Oximeters Market
Medical Devices
Global Neurology Ultrasonic Aspirators Market
Medical Devices
Cranial Closure and Fixation Devices Market