
 Shoulder Arthroplasty Market | 2026-2036
Shoulder Arthroplasty Market Size, Share, and Industry Trends Forecast 2026-2036
Shoulder Arthroplasty Market Intelligence
Hospital purchasing consortiums is reshaping how implant manufacturers secure volume commitments across integrated delivery networks. Stryker leverages its robotics platform to anchor premium positioning in academic medical centers. Zimmer Biomet competes through broad catalog depth that spans anatomic and reverse shoulder systems. Smith & Nephew differentiates via its cementless fixation technology and sports medicine crossover expertise.
Shoulder arthroplasty encompasses the surgical replacement of damaged glenohumeral joint surfaces with prosthetic components, typically cobalt-chromium or titanium alloy humeral heads articulating against polyethylene glenoid liners, designed to restore range of motion and relieve pain in patients with end-stage osteoarthritis or rotator cuff arthropathy. Reverse shoulder replacement dominates volume among revision and cuff-deficient populations where biomechanical constraints rule out anatomic designs. Robotic-assisted surgery commands the fastest expansion trajectory as navigation accuracy reduces component malposition and early loosening. Metal-on-polyethylene pairings retain the largest installed base despite ceramic and composite alternatives gaining traction in younger, higher-demand cohorts.
FDA 510(k) clearance requirements and EU MDR conformity assessments shape product development timelines and clinical evidence burdens for manufacturers seeking market access. ISO 5832 material standards and ASTM implant testing protocols govern biocompatibility and mechanical performance specifications that differentiate supplier qualification tiers. Stakeholders must monitor how CMS bundled payment evolution and site-of-service differentials redistribute volume between hospital outpatient departments and freestanding ambulatory centers.
Market Dynamics
Robotic navigation platforms are compressing revision rates and redistributing procedural volume toward high-throughput surgical centers equipped for capital-intensive instrumentation.
Growth Catalysts
- Ambulatory site-of-service migration:CMS reimbursement differentials favoring hospital outpatient departments and freestanding ASCs accelerate same-day discharge protocols for select patient cohorts.
- EU MDR conformity pathways:Streamlined clinical evidence requirements for well-established implant designs reduce time-to-market for iterative component modifications.
- Polyethylene crosslinking advances:Vitamin E-stabilized liners extend wear resistance in anatomic designs, expanding addressable patient age downward.
Market Restraints
- Cobalt-chromium supply concentration:Primary smelter capacity clusters in specific mining jurisdictions create input cost volatility for humeral head forging operations.
- Technical limitation in glenoid fixation:Cementless glenoid component designs face higher early loosening rates in osteoporotic bone, restricting adoption to defined bone quality thresholds.
- Substitution threat from biologic resurfacing:Interpositional graft techniques for young, active patients with focal cartilage defects delay arthroplasty timing in specific demographic segments.
Strategic Opportunities
- Underpenetrated Japanese market:Aging demographics and surgeon training expansion create volume potential for reverse shoulder designs in cuff-deficient populations.
- Technology convergence of navigation and preoperative planning:CT-based templating integrated with robotic execution reduces component malposition in complex deformity cases.
- Distribution innovation through direct-to-hospital consignment:Implant manufacturers bypass distributor markups by maintaining sterile field inventory at high-volume orthopedic centers.
Industry Challenges
- Fellowship-trained shoulder specialist scarcity:Limited ACGME-accredited programs constrain surgeon supply expansion needed for procedural volume growth.
- EU MDR technical documentation burden:Legacy implant systems require costly clinical data regeneration for renewed CE marking under tightened notified body scrutiny.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shoulder Arthroplasty Market |
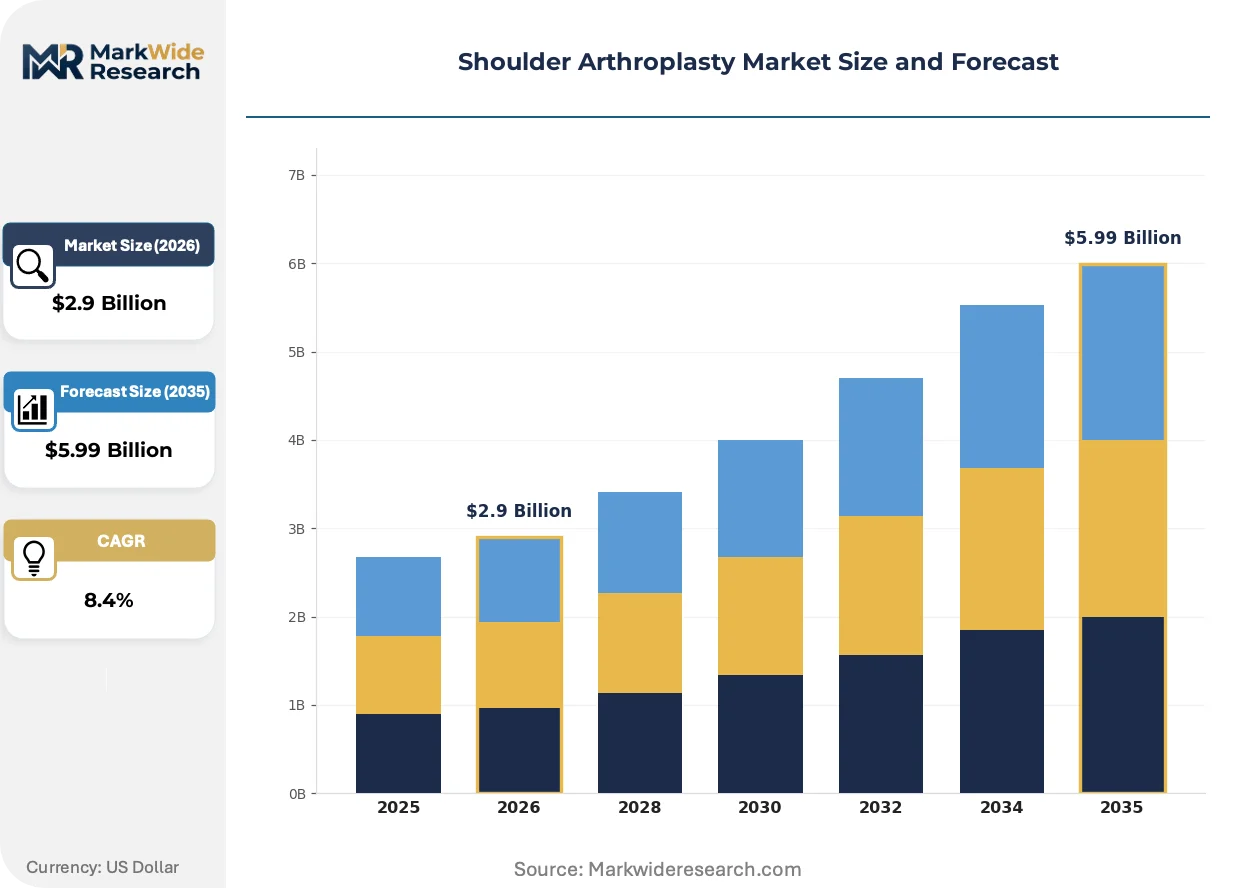
| Market Size in 2026 | $2.9 Billion |
| Market Size in 2035 | $5.99 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Total Shoulder Replacement, Partial Shoulder Replacement, Reverse Shoulder Replacement, Resurfacing Arthroplasty End User: Hospitals, Ambulatory Surgical Centers, Orthopedic Clinics, Rehabilitation Centers Technology: Robotic-Assisted Surgery, Computer-Assisted Surgery, Traditional Surgery, Minimal Invasive Surgery Material: Metal, Polyethylene, Ceramic, Composite |
| Companies Covered | Exactech, Smith & Nephew, Zimmer Biomet, Integra LifeSciences, Wright Medical Group, Stryker, Arthrex, Shoulder Innovations, DePuy Synthes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shoulder Arthroplasty Market Strategic Shifts & Innovations
Digital surgical planning tools and patient-specific instrumentation are compressing operative time variability and enabling reproducible outcomes across heterogeneous surgeon experience levels.
Patient-specific 3D-printed glenoid guides are collapsing the learning curve for complex revision cases by translating preoperative deformity correction into intraoperative drill trajectory enforcement. Community hospital systems with limited fellowship-trained specialists adopt these disposable guides to standardize component positioning. The technology is collapsing volume concentration in academic referral centers by decentralizing technical capability.
FDA 510(k) predicate pathway evolution demands enhanced biomechanical testing documentation for novel bearing surface combinations, extending review timelines for ceramic-on-polyethylene submissions. Manufacturers respond by accumulating retrieval analysis data from international joint registries to satisfy substantial equivalence challenges. Smaller design houses without established predicate portfolios face disproportionate evidence generation burdens.
After-sales service unbundling separates implant pricing from traditional instrumentation loaner programs, forcing capital-constrained facilities to evaluate per-case tray rental economics against outright system purchase. Independent ASCs negotiate à la carte instrument access to preserve margin on bundled payment cases. Texas and Florida surgical networks lead this procurement model fragmentation, pressuring manufacturers to modularize commercial terms.
Shoulder Arthroplasty Market Segmentation
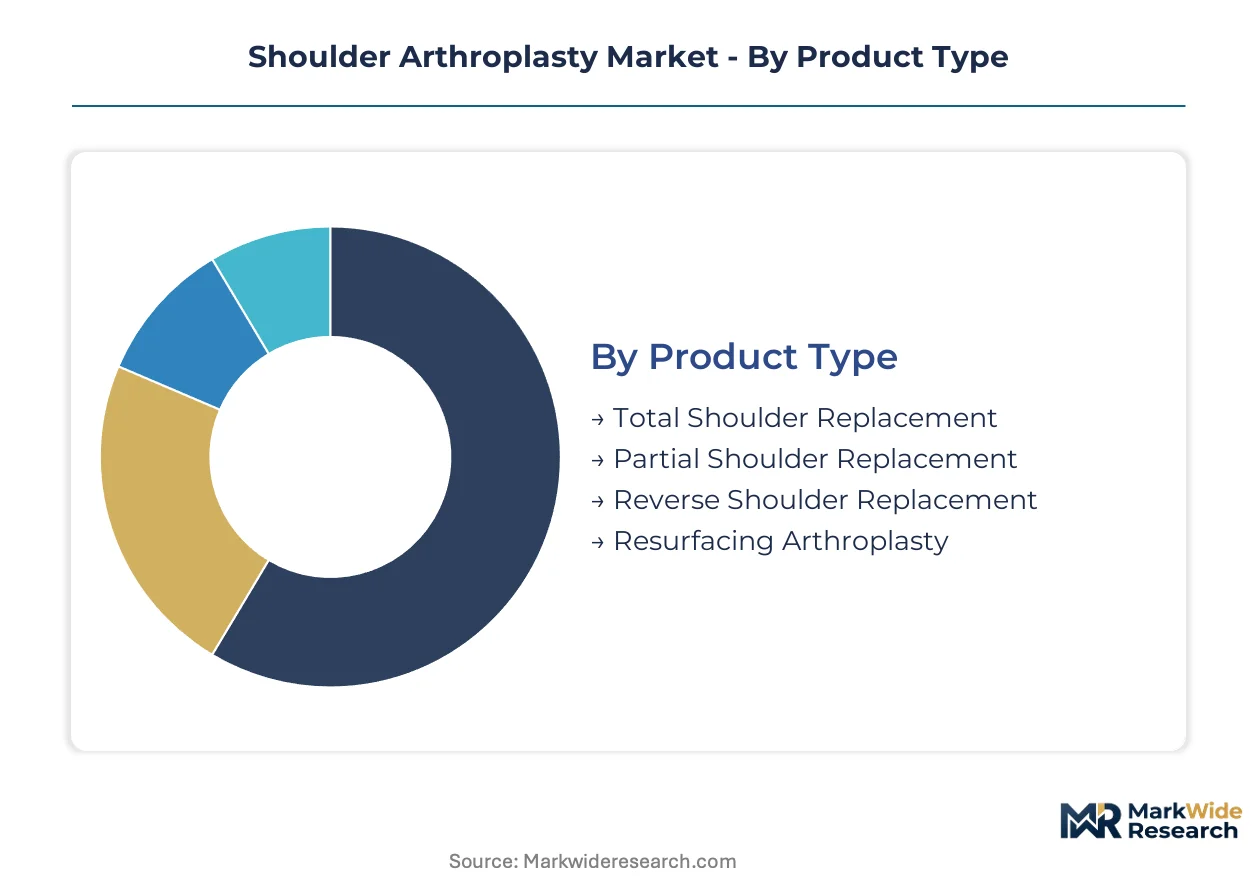
Shoulder arthroplasty segmentation reveals how procedural complexity, site-of-service economics, and bearing surface innovation create distinct commercial battlegrounds. Each dimension carries specific reimbursement, regulatory, and supply chain implications that shape manufacturer positioning.
Product Type:
Cost tier stratification across implant systems determines hospital purchasing committee priorities and surgeon training investment requirements.
- Reverse Shoulder Replacement:Glenosphere-and-socket configuration inverts native anatomy to recruit deltoid compensation for rotator cuff deficiency. Academic medical centers in the United States concentrate demand as fellowship-trained specialists manage complex revision and cuff-deficient populations.
- Total Shoulder Replacement:Anatomic humeral head and polyethylene glenoid liner restore native kinematics in osteoarthritic patients with intact cuff function. Community hospital systems favor this established design for its predictable outcomes and broader surgeon accessibility.
- Partial Shoulder Replacement:Hemiarthroplasty preserves native glenoid anatomy in younger patients with focal humeral head pathology.
- Resurfacing Arthroplasty:Bone-conserving cap implants address early-stage disease with reduced resection requirements.
Reverse designs command the established base in revision and cuff-deficient populations. The steepest expansion runs through anatomic total shoulder systems as ambulatory migration broadens addressable patient pools.
End User:
Customer type fragmentation reflects site-of-service reimbursement differentials and capital intensity thresholds.
- Hospitals:Inpatient and hospital outpatient departments manage complex deformity, revision, and medically comorbid cases requiring overnight observation. CMS bundled payment evolution at these facilities shapes implant pricing negotiations and length-of-stay protocols.
- Ambulatory Surgical Centers:Freestanding facilities exploit same-day discharge economics for select primary arthroplasty cohorts. Texas and Florida surgical networks lead volume migration as payer prior authorization frameworks mature.
- Orthopedic Clinics:Office-based settings concentrate preoperative planning and postoperative rehabilitation coordination.
- Rehabilitation Centers:Dedicated facilities manage extended recovery protocols for complex revision recoveries.
Hospitals retain the high-acuity base. ASCs are gaining share fastest where patient selection criteria standardize.
Technology:
Application sophistication divides capital-equipped academic centers from community facilities operating on conventional instrumentation.
- Robotic-Assisted Surgery:Navigation platforms enforce humeral head and glenoid component positioning through CT-based preoperative planning and intraoperative haptic feedback. Stryker's installed base concentrates in high-throughput centers where revision rate reduction justifies capital expenditure.
- Computer-Assisted Surgery:Optical tracking systems provide real-time alignment feedback without robotic execution hardware.
- Traditional Surgery:Mechanical jigs and freehand technique dominate community hospital economics where case volume cannot support capital platform amortization.
- Minimal Invasive Surgery:Subscapularis-sparing and deltoid-splitting approaches reduce soft tissue disruption for accelerated rehabilitation.
Traditional technique commands the procedural volume base. Robotic assistance is climbing the fastest as navigation accuracy data accumulates in joint registries.
Material:
Supply concentration in cobalt-chromium forging and polyethylene crosslinking chemistry governs cost structure and wear performance differentiation.
- Metal:Cobalt-chromium and titanium alloy humeral heads deliver proven fatigue resistance and biocompatibility under ISO 5832 standards. Primary smelter capacity concentration in specific mining jurisdictions creates input cost volatility for forging operations.
- Polyethylene:Crosslinked and vitamin E-stabilized glenoid liners dominate bearing surface configurations with established retrieval data.
- Ceramic:Alumina and oxidized zirconium alternatives address metal hypersensitivity and reduce ion release in younger patients.
- Composite:Carbon fiber-reinforced and polymer matrix materials target specific modulus-matching applications.
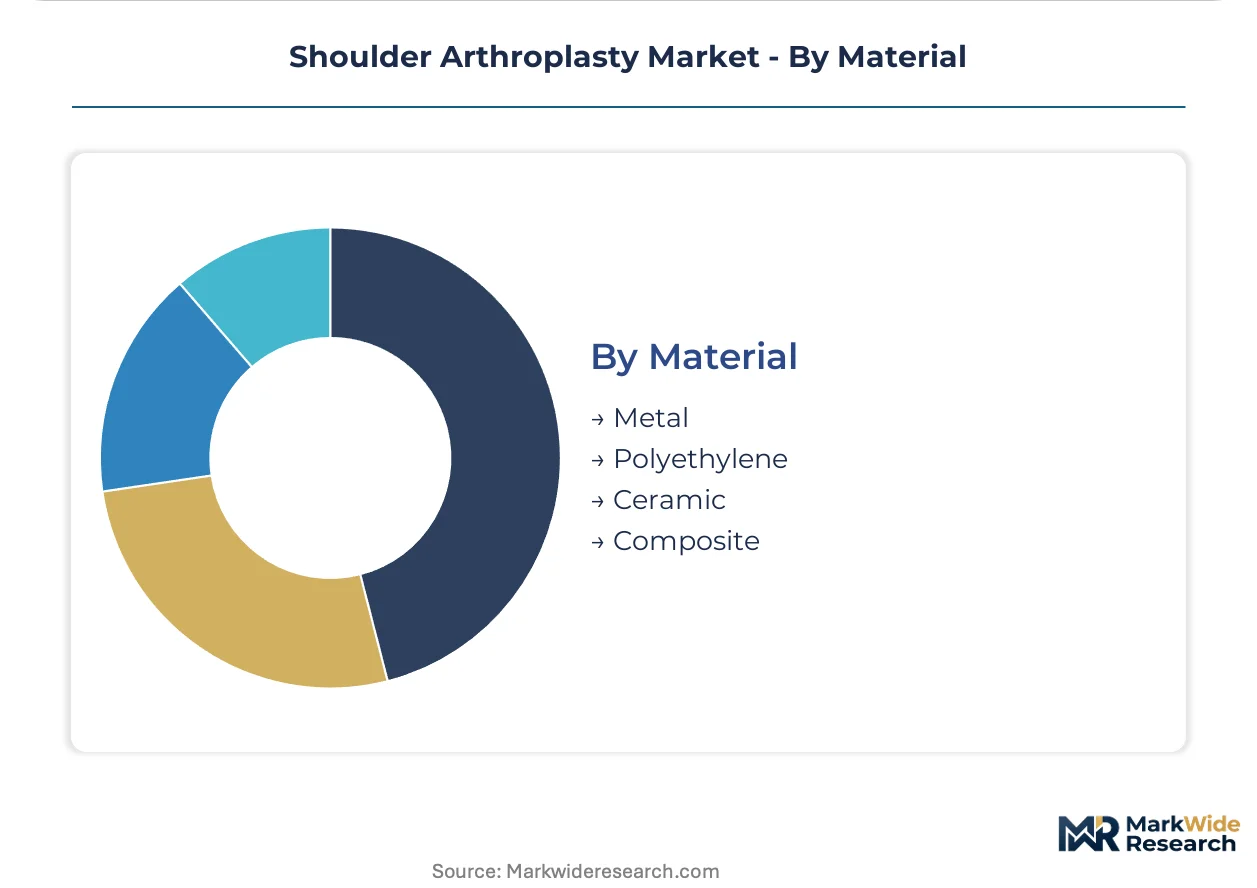
Metal-on-polyethylene pairings command the installed base. Ceramic bearings are expanding most quickly in high-demand patient segments seeking longevity extension.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain logistics corridor underwrites Europe's implant distribution efficiency, while Japan's Kansai International Airport anchors Asia-Pacific supply reliability for temperature-sensitive orthopedic inventory.
United States
The aging demographic and established ACGME-accredited fellowship programs sustain procedural volume leadership. FDA 510(k) premarket notification pathways accelerate iterative component modifications for domestic manufacturers. The Texas Medical Center in Houston concentrates reverse shoulder revision complexity, drawing cuff-deficient referrals from across the Southwest.
Germany
EU MDR conformity assessment streamlines market access for well-established implant designs with retrieval registry data. The country's statutory health insurance system maintains predictable reimbursement for anatomic and reverse procedures alike. The Rhine-Ruhr metropolitan cluster hosts high-throughput orthopedic centers equipped for robotic navigation platform amortization.
Japan
Surgeon training expansion and aging demographics create volume potential for reverse shoulder designs in cuff-deficient populations. PMDA regulatory frameworks require substantial equivalence documentation for bearing surface innovations. The Kanto region around Tokyo concentrates academic medical center volume where navigation accuracy data accumulates in national joint registries.
Australia
TGA approval pathways align with ISO 5832 material standards that govern cobalt-chromium and titanium alloy specifications. Private health insurance penetration supports premium-tier ceramic bearing adoption in younger patient cohorts. The Sydney-Melbourne corridor dominates procedural volume as ambulatory surgical center networks mature their orthopedic service lines.
Shoulder Arthroplasty Market Key Industry Players
On the supply side, the industry is consolidating around integrated orthopedic platforms with robotics and navigation capabilities. Three strategic archetypes dominate: diversified conglomerates with broad catalog depth, mid-cap specialists with cementless fixation expertise, and robotics-anchored premium-positioned players. Dominant competitive moves include strategic partnerships for CT-based templating integration and portfolio diversification into patient-specific instrumentation.
Among diversified orthopedic conglomerates, Stryker and Zimmer Biomet occupy positions that exemplify scale-driven platform strategies, while Smith & Nephew represents the mid-cap specialist archetype with differentiated fixation technology. These anchors reflect how manufacturer positioning stratifies across capital intensity thresholds and site-of-service economics.
| Leading Market Players |
|---|
| Exactech |
| Smith & Nephew |
| Zimmer Biomet |
| Integra LifeSciences |
| Wright Medical Group |
| Stryker |
| Arthrex |
| Shoulder Innovations |
| DePuy Synthes |
| Others |
Cost & Logistics Intelligence
The Port of Rotterdam's cold-chain logistics corridor anchors European implant distribution, with its specialized pharmaceutical handling capacity translating directly into manufacturer pricing power across the continent's hospital purchasing consortiums.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates robotic-navigation-enabled systems from conventional mechanical instrumentation and basic implant-only configurations. Price differentiation rests on after-sales service bundling and surgeon training program inclusion, with academic medical centers showing least sensitivity due to bundled payment economics while independent ASCs drive hardest volume-discount negotiations. Cost compression in the standard tier is intensifying as GPOs consolidate procurement across integrated delivery networks.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard as manufacturers absorb working capital pressure to secure exclusive supply agreements with high-volume orthopedic centers. Primary smelter capacity for cobalt-chromium feedstock clusters in China, South Africa, and Finland, with forging operations drawing from these concentrated sources. Single-source vulnerability in vitamin E-stabilized polyethylene resin creates exposure to specialty chemical plant outages. Distribution runs through consignment inventory models at hospital outpatient departments and direct-to-facility sterile field delivery for ambulatory surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards control over scarce assets: fellowship-trained surgeon relationships, robotic platform installed bases, and predicate-rich FDA portfolios constitute the binding constraints on competitive expansion.
For Market Incumbents: Build installed-base moats through robotic platform ecosystem lock-in and exclusive surgeon training academy partnerships. Secure backward integration into cobalt-chromium forging capacity to buffer raw material volatility. Cementless glenoid fixation expertise represents a defensible differentiation point against revision-rate competition. For New Entrants and Emerging Players: Pursue patient-specific instrumentation white space where 3D-printed surgical guides lower technical barriers for community hospital systems lacking fellowship-trained specialists. The Japanese reverse shoulder segment offers most penetrable geography given training expansion and aging demographics. Go-to-market through direct-to-hospital consignment bypassing traditional distributor markups. For Investors and Strategic Acquirers: Long-term, this sits as a procedure-volume compounding play because ambulatory site-of-service migration and robotic navigation adoption create durable recurring revenue streams through instrument tray rental and software subscription attach. Target mid-cap specialists with cementless fixation IP and predicate-rich regulatory portfolios. Watch CMS bundled payment site-of-service differentials as volume migration inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Predicate Accumulation | Rich predicate portfolios accelerate iterative component clearance timelines for bearing surface innovations. |
| Hospital System Partnership | Exclusive supply agreements with Texas and Florida surgical networks anchor ambulatory volume migration. |
| Robotic Platform Integration | CT-based templating with haptic feedback execution reduces malposition liability in complex deformity cases. |
| Reimbursement Strategy | CMS bundled payment optimization shapes site-of-service economics and length-of-stay protocol design. |
| Software Companion Development | Digital surgical planning tools standardize outcomes across heterogeneous surgeon experience levels. |
Research Approach
A spread of perspectives from orthopedic surgeons, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers converged on the working assumptions underpinning volume and value estimates. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, CMS Medicare claims data, hospital procurement databases, and national joint registry retrieval analyses. Bottom-up procedure volume builds triangulated against top-down implant manufacturer revenue assessments across the analysis window.
Demand-supply-balance framing anchored the analytical framework throughout the projection horizon. Segmentation modeling spanned product type complexity, site-of-service economics, technology sophistication, and material bearing surface innovation. CAGRs derived from regression analysis of historical procedural volume against demographic drivers and reimbursement evolution. Forecast inputs incorporated ACGME fellowship program expansion rates and ASC orthopedic service line capital investment patterns.
Macroeconomic conditions sit as an overlay; deviation in elective procedure deferral rates, cobalt-chromium commodity pricing, or EU MDR notified body capacity would shift the trajectory. Forecasts reflect documented assumptions about payer prior authorization frameworks and robotic platform adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Patients Repositioning and Offloading Device Market
Orthopedic Devices
Orthopedic Contract Manufacturing Market
Orthopedic Devices
Outsourced Orthopedic Manufacturing Market
Orthopedic Devices
Orthopedic Artificial Bone Defect Repair Materials Market
Orthopedic Devices
Vertebroplasty and Kyphoplasty Devices Market
Orthopedic Devices
India Spinal Surgery Devices Market
Orthopedic Devices
Polyethylene Orthopaedic Insert Market
Orthopedic Devices
India Orthopedic Braces and Supports Market
Orthopedic Devices
Hip Replacement Market
Orthopedic Devices
Veterinary Orthopedic Drills Market
Orthopedic Devices
Wrist Replacement Orthopedic Devices Market
Orthopedic Devices
Japan Spinal Surgery Devices Market
Orthopedic Devices
Medical Crutches Market
Orthopedic Devices
Global Joint Replacement Market
Orthopedic Devices
Global Orthopedic Splints Market
Orthopedic Devices
Global Personalized 3D Printed Orthopedic Implants Market