
 United Kingdom Contraceptive Devices Market | 2026-2036
United Kingdom Contraceptive Devices Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Contraceptive Devices Market Analytics
Silicone elastomer is realigning condom manufacturing economics as manufacturers shift from natural rubber latex to address allergy prevalence and extend product shelf stability. CooperSurgical leverages its vertically integrated supply chain to dominate the UK intrauterine device segment. Reckitt Benckiser sustains brand strength across retail pharmacy channels with sustained marketing investment. Organon & Co. specializes in hormone-releasing systems and anchors hospital formulary presence through clinician education programs.
Contraceptive devices encompass intrauterine devices, barrier methods, pharmaceutical implants, and hormonal delivery systems engineered from medical-grade polymers, copper alloys, or synthetic progestins to prevent fertilization or implantation through mechanical, chemical, or hormonal action. The product type dimension shows intrauterine devices capturing the dominant margin pool due to their multi-year efficacy and higher reimbursement rates, while implants represent the fastest-growing category as general practitioners expand clinic-based insertion capacity. Within distribution channels, pharmacies occupy the volume leadership position for condoms and emergency contraception, whereas hospitals and clinics control access to invasive methods requiring clinical administration.
The Medicines and Healthcare products Regulatory Agency sets device safety and clinical performance standards, while NHS England commissioning frameworks determine regional reimbursement eligibility and provider payment structures. MHRA post-market surveillance requirements shape manufacturer liability exposure and recall protocols, directly influencing product design documentation and adverse event reporting systems. Stakeholders must monitor how NICE technology appraisal updates redistribute funding between long-acting and short-acting methods across integrated care boards.
Market Dynamics
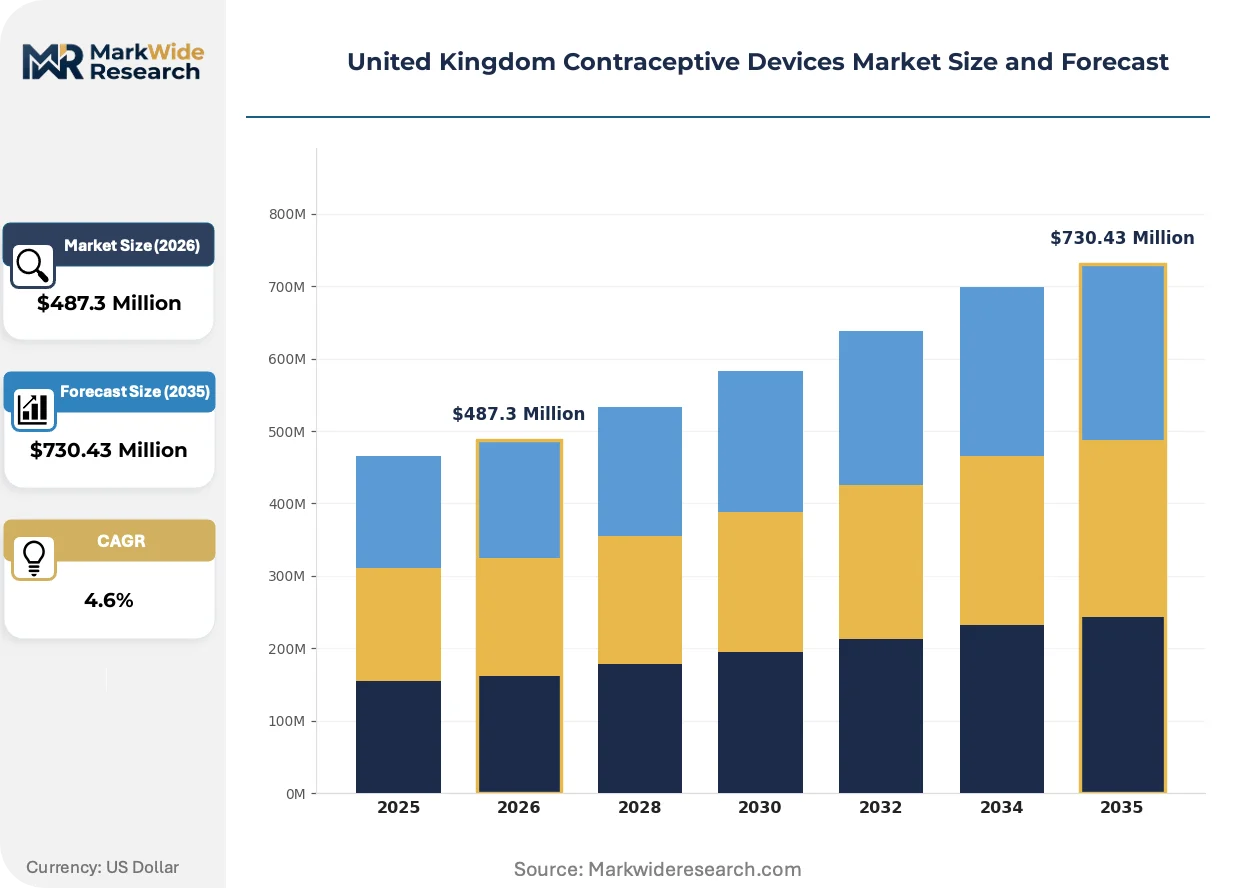
NHS England's commissioning frameworks are redistributing provider payments toward long-acting reversible contraceptives, compressing demand for short-acting methods and reshaping manufacturer revenue concentration across integrated care boards.
Growth Catalysts
- MHRA Guidance Updates:Revised hormone-releasing intrauterine system protocols from the Medicines and Healthcare products Regulatory Agency have expanded clinical eligibility criteria, pulling new patient cohorts into clinic-based insertion services.
- Silicone Elastomer Migration:Manufacturers are abandoning natural rubber latex for medical-grade silicone polymers, eliminating allergy barriers and extending shelf stability to capture pharmacy retail volume.
- Greater London Provider Density:Concentrated sexual health clinic networks in the capital generate referral spillover into surrounding integrated care boards, amplifying regional demand pull.
Market Restraints
- Copper Alloy Input Volatility:Intrauterine device manufacturers face margin pressure from fluctuating copper commodity prices, with raw material exposure concentrated in Asian smelter supply.
- Clinical Administration Bottlenecks:Invasive method insertion requires trained specialist availability, and NHS workforce gaps in rural integrated care boards create access inequities that cap category penetration.
- Generic Condom Substitution:Unbranded barrier method imports from low-cost manufacturing jurisdictions erode pharmacy margin pools for established domestic suppliers.
Strategic Opportunities
- General Practitioner Clinic Expansion:NHS funding for primary care-based long-acting reversible contraceptive insertion creates white space outside traditional hospital sexual health departments.
- Pharmacy Channel Integration:Emergency hormonal contraception and barrier method categories are consolidating into supermarket pharmacy formats, displacing independent retail chemists.
- NICE Technology Appraisal Tailwinds:Pending National Institute for Health and Care Excellence reviews of subdermal implants signal potential reimbursement expansion for clinic-administered pharmaceutical delivery systems.
Industry Challenges
- Specialist Insertion Skill Scarcity:Intrauterine device and implant administration requires certified clinician training, and NHS workforce pipelines are failing to replace retiring sexual health specialists.
- Post-Market Surveillance Documentation:MHRA adverse event reporting mandates impose heavy compliance overhead on manufacturers, particularly for hormone-releasing systems with complex pharmacovigilance obligations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Contraceptive Devices Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $730.43 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intrauterine Devices, Condoms, Birth Control Pills, Implants Distribution Channel: Pharmacies, Online Retail, Hospitals, Clinics End User: Women of Reproductive Age, Healthcare Providers, Teenagers, Couples Application: Contraception, Family Planning, Menstrual Regulation, Hormonal Therapy |
| Companies Covered | Bayer AG, CooperSurgical, Inc., Reckitt Benckiser Group plc, Organon & Co., Gedeon Richter Plc, Church & Dwight Co., Inc., Merck & Co., Inc., Pfizer Inc., Teva Pharmaceutical Industries Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Contraceptive Devices Market Evolving Landscape
Digital patient pathways and polymer material science are converging to compress the traditional clinic-to-pharmacy care continuum for contraceptive access across UK integrated care systems.
Subdermal hormonal implants are decentralizing contraceptive administration from hospital sexual health departments into general practice settings. NHS England's expanded primary care commissioning budgets are accelerating GP clinic adoption. This shift is compressing specialist referral queues while fragmenting device procurement across dispersed clinical settings.
MHRA post-market surveillance requirements for hormone-releasing intrauterine systems have tightened pharmacovigilance documentation standards. Manufacturers must now maintain real-world outcome registries spanning multi-year efficacy windows. Hospital formularies are responding by consolidating supplier relationships to reduce compliance audit complexity.
Patient-initiated digital consultation platforms are displacing traditional GP appointment booking for initial contraceptive counseling. Younger demographic cohorts in urban integrated care boards are driving adoption. This behavioral pivot is rerouting demand toward pharmacy-based emergency provision and away from scheduled clinic visits.
United Kingdom Contraceptive Devices Market Segmentation
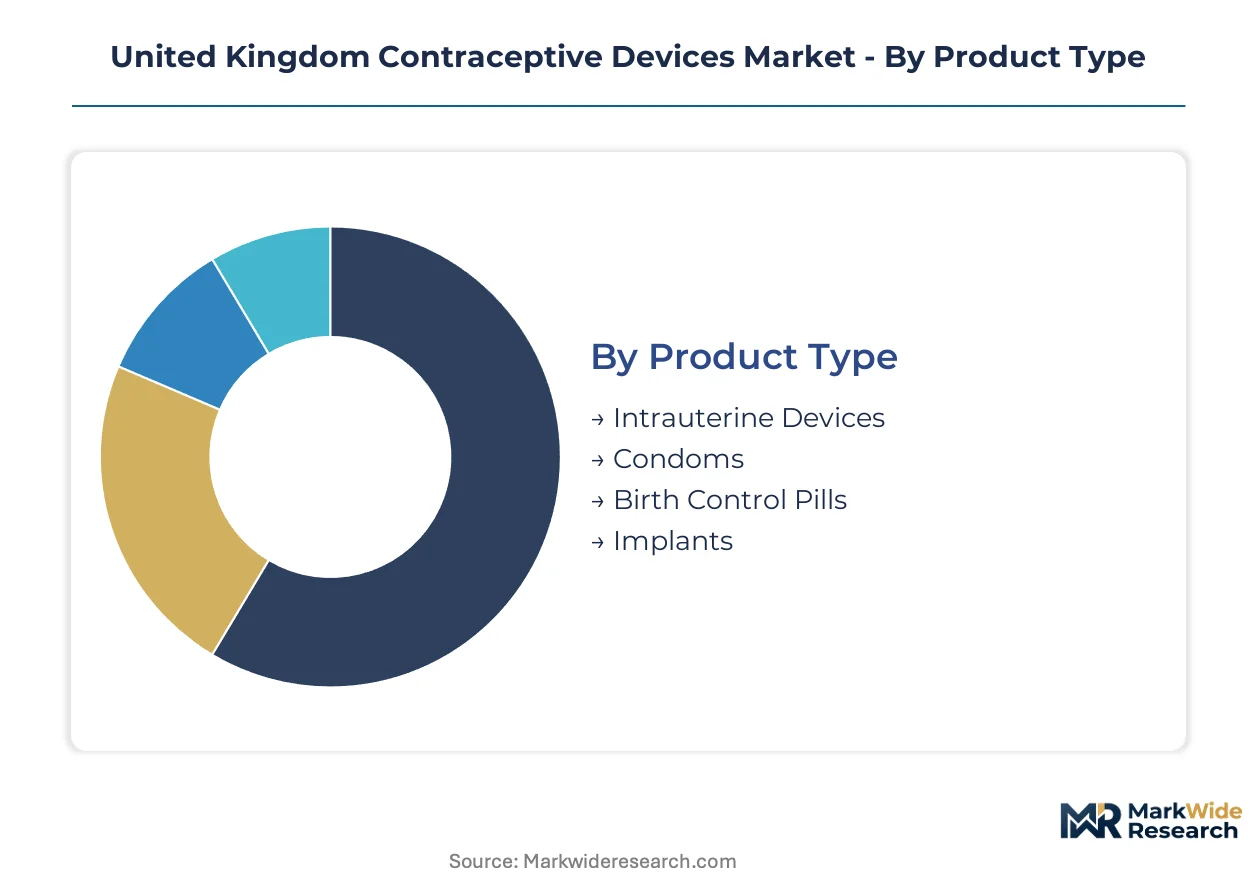
Segmentation reveals how procurement authority and patient access routes split across the United Kingdom contraceptive devices market. NHS commissioning frameworks, MHRA device classifications, and retail pharmacy economics each favor different segment combinations, creating distinct competitive arenas for manufacturers and distributors.
Product Type:
Supply concentration tilts toward manufacturers with vertically integrated polymer compounding and copper wire drawing capabilities, locking out pure-assembly competitors from the highest-margin device categories.
- Intrauterine Devices:Copper alloy and hormone-releasing systems engineered from medical-grade polymers or copper wire require precision extrusion and sterilization validation. Demand concentrates in Greater London and South East integrated care boards where sexual health clinic density supports high-volume insertion services and NHS reimbursement flows most reliably.
- Implants:Subdermal etonogestrel rods manufactured from medical-grade silicone elastomer demand advanced polymer curing and drug-elution control. General practitioner clinics across England are expanding insertion capacity under NHS primary care commissioning, pulling procurement away from hospital sexual health departments.
- Condoms:Barrier methods span natural rubber latex and silicone elastomer variants, with pharmacy retail chains dominating volume procurement.
- Birth Control Pills:Oral hormonal contraceptives fall outside device classification but intersect with emergency provision pathways in pharmacy settings.
Today's leader: Intrauterine Devices. Tomorrow's challenger: Implants.
Distribution Channel:
Channel economics split sharply between prescription-controlled invasive methods and over-the-counter barrier products, with margin structures reflecting MHRA classification tiers rather than manufacturing cost alone.
- Pharmacies:Community and supermarket pharmacy formats control condom and emergency hormonal contraception volume, with Boots and Lloyds Pharmacy capturing the majority of retail transactions through high-street presence and NHS prescription fulfillment.
- Hospitals:Acute trust sexual health departments manage complex insertion cases and device complications, maintaining formulary control over copper IUDs and hormone-releasing systems through consultant-led procurement committees.
- Clinics:NHS community sexual health clinics and general practice settings are gaining insertion capacity for long-acting reversible contraceptives.
- Online Retail:E-commerce platforms capture condom and barrier method sales through subscription models and discreet delivery, though MHRA regulations restrict prescription device sales to registered pharmacy premises.
Pharmacies dominate volume. Clinics are climbing the fastest as primary care commissioning expands.
End User:
User segmentation tracks decision-making authority, with healthcare providers controlling invasive method access while patients self-select barrier and emergency options.
- Women of Reproductive Age:The core patient population spans ages 15-49, with demand intensity varying by life stage and parity status across urban and rural integrated care boards.
- Healthcare Providers:General practitioners, sexual health specialists, and nurse practitioners control insertion service availability and device formulary selection through NHS commissioning influence.
- Teenagers:Younger cohorts access contraception through dedicated youth clinics and pharmacy emergency provision, with confidentiality protections shaping channel preference.
- Couples:Partner-influenced decision-making drives condom selection and shared responsibility for family planning outcomes.
Women of Reproductive Age anchor current demand. Healthcare Providers are expanding their gatekeeper role through GP clinic commissioning.
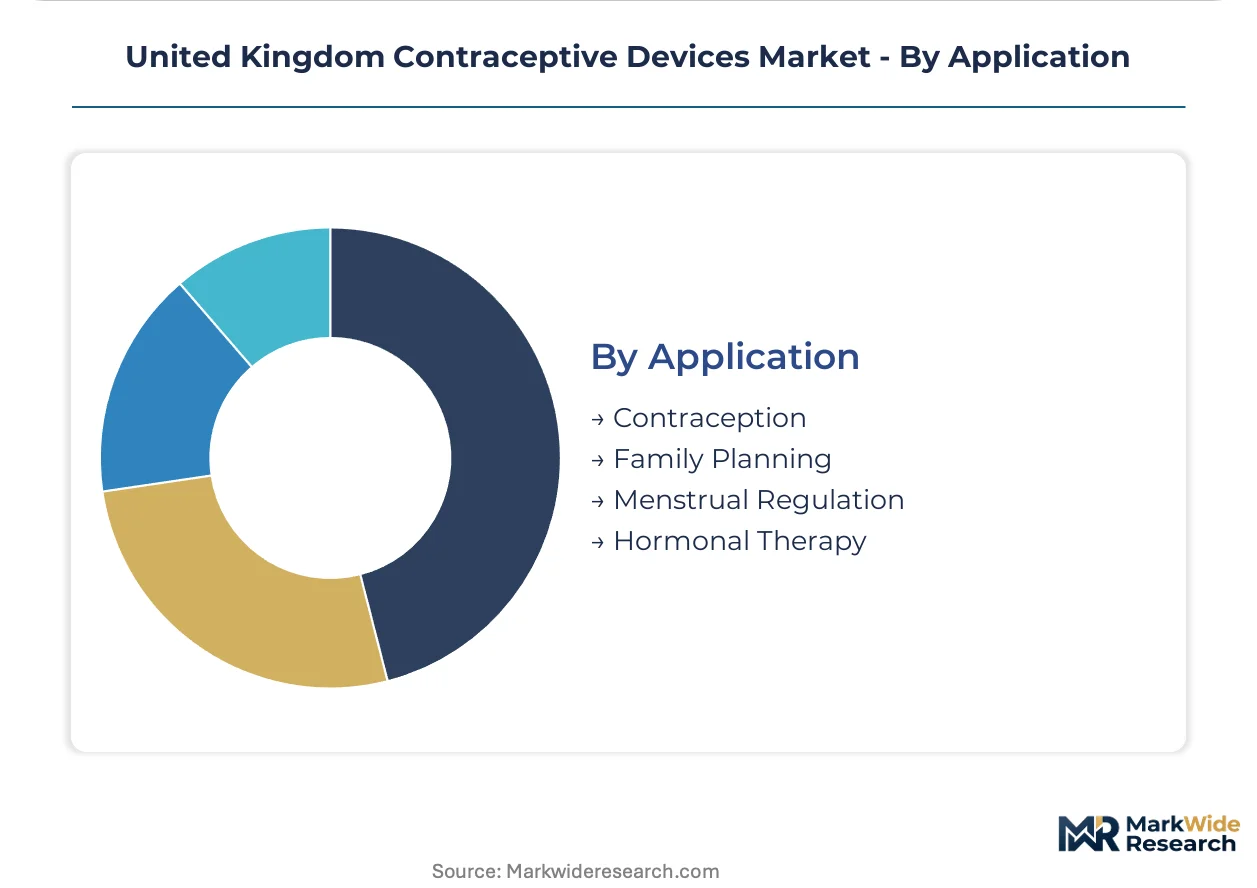
Application:
Application segmentation separates fertility prevention from therapeutic uses, with hormone-releasing systems crossing into gynecological treatment indications.
- Contraception:Pregnancy prevention remains the primary indication across all device categories, with efficacy duration and reversibility driving method selection.
- Family Planning:Spacing and limiting births aligns with NHS public health objectives, with long-acting reversible contraceptives prioritized for cost-effectiveness.
- Menstrual Regulation:Hormone-releasing IUDs and implants address heavy menstrual bleeding through progestin-induced endometrial suppression, expanding prescriber adoption beyond pure contraception.
- Hormonal Therapy:Endometriosis and dysmenorrhea management represents an emerging off-label and licensed use case for subdermal and intrauterine progestin delivery.
Contraception commands current volume. Hormonal Therapy offers the steepest expansion trajectory as gynecological indications broaden prescriber adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater London anchors UK contraceptive device procurement through its dense network of NHS sexual health clinics and integrated care boards. Regional demand patterns reflect commissioning budget allocation, provider workforce distribution, and patient access route preferences across England's administrative geography.
London and South East
Specialist sexual health clinics in Camden, Lambeth, and Brighton generate the highest intrauterine device insertion volumes nationally. NHS England's regional commissioning team prioritizes long-acting reversible contraceptive funding here, pulling manufacturer field support concentration. The concentration of teaching hospitals creates spillover training effects into surrounding integrated care boards.
Midlands
Birmingham and Manchester sexual health departments are expanding GP clinic insertion capacity under primary care network contracts. NHS Midlands regional procurement frameworks favor multi-year device supply agreements to reduce transaction overhead. Workforce recruitment challenges in rural Staffordshire and Shropshire create access inequities that cap category penetration.
North England
Leeds and Newcastle acute trusts maintain hospital-based sexual health service models with limited primary care delegation. NHS North East and Yorkshire integrated care boards face the most severe specialist nurse shortages, extending appointment wait times. Pharmacy emergency contraception volume runs proportionally higher as clinic access constrains.
Scotland
NHS Scotland's unified commissioning structure enables faster formulary adoption for new hormone-releasing systems than England's fragmented system. Edinburgh and Glasgow sexual health centers drive device procurement volume. The Scottish Medicines Consortium's parallel technology appraisal track creates regulatory complexity for manufacturers seeking rapid market entry.
Wales
Cardiff and Swansea health boards concentrate contraceptive device procurement through centralized pharmacy contracts. NHS Wales's smaller integrated care board count simplifies supplier relationship management but reduces competitive tender frequency. Rural North Wales access gaps mirror English border county patterns.
United Kingdom Contraceptive Devices Market Competitive Landscape
Global majors compete with regional champions across NHS procurement channels and retail pharmacy distribution. Market structure tilts toward consolidated supply relationships in hospital formulary segments while fragmenting across pharmacy retail. Three archetypes dominate: vertically integrated device manufacturers with polymer compounding capabilities; pharmaceutical licensees leveraging hormone delivery expertise; and consumer health multinationals with retail channel scale. Competitive moves center on NHS framework bidding concentration and silicone material substitution to capture allergy-sensitive patient segments.
Among the vertically integrated specialists, CooperSurgical, Inc. anchors the intrauterine device segment through supply chain control over critical polymer and copper components. Reckitt Benckiser Group plc occupies the retail pharmacy tier with sustained brand investment across condom and emergency contraception categories. Organon & Co. exemplifies the pharmaceutical-derived archetype, building hospital formulary presence through clinician education infrastructure. These three represent distinct competitive vectors—manufacturing depth, consumer marketing scale, and prescriber relationship intensity—that shape procurement outcomes across NHS and retail channels.
| Leading Market Players |
|---|
| Bayer AG |
| CooperSurgical, Inc. |
| Reckitt Benckiser Group plc |
| Organon & Co. |
| Gedeon Richter Plc |
| Church & Dwight Co., Inc. |
| Merck & Co., Inc. |
| Pfizer Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Others |
Value Network & Pricing Analysis
Specialist nurse availability in Greater London and the South East creates labor-cost differentials that widen pricing-tier spreads between premium hormone-releasing systems and economy copper devices. NHS England's regional commissioning budgets amplify this effect as integrated care boards with denser clinical workforces absorb higher service-delivery premiums.
Pricing Analysis
Input-cost pass-through from copper alloy and medical-grade silicone elastomer feeds into three-tier pricing structure across premium, standard, and economy levels. Price differentiation centers on MHRA device classification tier and prescriber administration setting, with hospital formulary placements commanding brand premiums over pharmacy retail. Cost compression in economy copper IUDs is intensifying because generic import substitution erodes domestic manufacturer margins. Pharmacy retail buyers exhibit highest price sensitivity, while hospital procurement committees prioritize clinical outcome reliability over unit cost.
Supply Chain Analysis
Workforce availability for polymer compounding and precision extrusion concentrates supply concentration in Germany, the United States, and select Asian manufacturing jurisdictions. Raw material dependencies center on copper wire drawing, medical-grade silicone elastomer, and synthetic progestin APIs. Single-source vulnerability runs through Asian smelter supply for copper alloy feedstock. Distribution runs through NHS regional procurement frameworks and retail pharmacy wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom contraceptive devices market reads as a late-cycle quality story as patient demand shifts toward silicone elastomer barrier methods and hormone-releasing systems with extended efficacy windows.
For Market Incumbents: Anticipate generic substitution pressure in economy condom tiers by consolidating backward integration into medical-grade polymer compounding. Secure MHRA post-market surveillance documentation capabilities to defend hospital formulary positions against emerging pharmaceutical licensees. Channel control through NHS framework bidding concentration remains the critical defensive lever. For New Entrants and Emerging Players: Digital patient consultation platforms offer a technology-first wedge into pharmacy-based emergency contraception pathways. White space concentrates in GP clinic insertion services across Midlands and North England integrated care boards where primary care commissioning expands fastest. A prescriber-education-led go-to-market angle bypasses entrenched hospital formulary gatekeepers. For Investors and Strategic Acquirers: Pharmaceutical conglomerates with hormone delivery expertise are the most active acquirer in this space, seeking clinic-administered device portfolios to complement drug pipelines. Acquisition targets with vertically integrated polymer capabilities and NHS framework contract history offer strongest long-term viability. Monitor NICE technology appraisal timelines as the signal for reimbursement expansion inflection.| Strategic Initiative | Industry Significance |
|---|---|
| GP Clinic Insertion Capacity Expansion | NHS primary care commissioning redirects procurement away from hospital sexual health departments toward dispersed clinical settings. |
| Silicone Elastomer Manufacturing Transition | Medical-grade polymer substitution eliminates natural rubber latex allergy barriers while extending product shelf stability. |
| MHRA Post-Market Surveillance Investment | Pharmacovigilance documentation capabilities determine hospital formulary eligibility for hormone-releasing systems. |
| Digital Patient Pathway Development | Younger demographic cohorts in urban integrated care boards drive adoption of app-based contraceptive counseling. |
| NHS Framework Contract Concentration | Regional procurement consolidation favors suppliers with multi-year device supply agreements and audit-ready compliance systems. |
Research Methodology
Direct dialogue with sexual health specialists, NHS procurement managers, GP clinic administrators, and pharmacy retail buyers grounded qualitative findings in operational reality. Secondary validation drew from MHRA device registration databases, NHS England commissioning framework disclosures, NICE technology appraisal documentation, and integrated care board procurement records. Bottom-up and top-down triangulation cross-checked manufacturer shipment data against regional patient access metrics.
Bottom-up modeling segmented volume and value across product type, distribution channel, and integrated care board geography throughout the forecast period. Analytical frameworks incorporated patient demographic projections, NHS workforce pipeline data, and MHRA regulatory pathway timelines. CAGRs were derived from fitted trend analysis of historical procurement volumes and forward-modeled commissioning budget allocations.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to NHS workforce recruitment shortfalls and copper commodity price volatility. Projections reflect assumptions about sustained primary care commissioning expansion and stable MHRA regulatory standards. Material deviation in NICE reimbursement decisions or specialist nurse training pipeline output warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Controlled-Release Drug Delivery Technology Market
Medical Devices
Transcutaneous Electrical Nerve Stimulation Market
Medical Devices
Epidural Anesthesia Sets Market
Medical Devices
Neurostimulation Market
Medical Devices
Keratoprosthesis (Kpro) Market
Medical Devices
Airway Management Devices Market
Medical Devices
Trocars Market
Medical Devices
Cyclotron Market
Medical Devices
Bone Densitometer Devices Market
Medical Devices
Elastomeric Infusion Pump Market
Medical Devices
Global Connected Medical Devices Market
Medical Devices
Sialendoscopes Market
Medical Devices
Respiratory Oxygen Delivery Devices Market
Medical Devices
Subcutaneous Drug Delivery Devices Market
Medical Devices
Benign Prostatic Hyperplasia (BPH) Treatment Devices Market
Medical Devices
US Contact Lenses Market