
 Rib Fracture Repair Systems Market | 2026-2036
Rib Fracture Repair Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Rib Fracture Repair Systems Market Analytics
Consolidation among Level I trauma centers is repositioning procurement power toward integrated hospital networks across the United States. Zimmer Biomet leverages its broad trauma portfolio to sustain orthopedic-surgery relationships that extend into rib fixation. Johnson & Johnson Services, Inc. anchors its position through DePuy Synthes distribution reach into emergency departments. Acumed, LLC specializes in anatomically contoured plating systems that dominate the upper-thoracic segment.
Rib fracture repair systems comprise implants and instruments designed to stabilize displaced or multiple rib fractures, typically manufactured from titanium alloys or stainless steel with plate thicknesses ranging from 1.0 mm to 1.5 mm and screw diameters of 2.0 mm to 2.7 mm, serving the primary purpose of restoring chest wall integrity and enabling pulmonary function recovery. Intramedullary nails occupy the fastest-expanding product category as surgeons pursue less invasive access routes that reduce intercostal muscle disruption. Minimally invasive technology leads volume growth among procedural approaches, though open surgery retains margin concentration in complex polytrauma cases where visualization proves critical. Robotic-assisted technology remains nascent but captures disproportionate attention from teaching institutions seeking to differentiate training programs.
FDA 510(k) premarket notification requirements govern commercial entry in the United States, while the EU Medical Device Regulation imposes stricter clinical-evidence thresholds on thoracic implant manufacturers seeking CE marking. The EU AI Act introduces additional scrutiny for robotic-assisted surgical platforms that incorporate real-time imaging analytics. Stakeholders must monitor how reimbursement coding for rib-specific procedures evolves relative to generic trauma fixation categories, as this determines whether hospital capital committees prioritize dedicated rib system purchases.
Market Dynamics
Consolidation among United States Level I trauma centers is concentrating procurement decisions into fewer integrated delivery networks, amplifying price pressure on rib fixation hardware while simultaneously expanding volume commitments for compliant suppliers.
Growth Catalysts
- FDA 510(k) Streamlining:The premarket notification pathway accelerates commercial entry for thoracic plating systems, reducing time-to-revenue for manufacturers targeting trauma center networks.
- Academic Medical Center Expansion:Teaching hospitals are building dedicated flail chest protocols that mandate surgical stabilization for select polytrauma patients, creating procedural volume anchors.
- Titanium Alloy Advances:Improved fatigue resistance in 1.0 mm to 1.5 mm plate thicknesses enables thinner constructs without sacrificing load-bearing capacity.
Market Restraints
- Input Cost Volatility:Titanium sponge prices fluctuate with aerospace demand cycles, compressing margins for implant manufacturers locked into multi-year hospital contracts.
- Supply Concentration Risk:Precision forging capacity for anatomically contoured plates clusters among specialty orthopedic subcontractors in the United States Midwest.
- Reimbursement Coding Friction:CMS has not established distinct DRG weights for rib-specific fixation, bundling procedures under generic thoracic trauma categories that undercapture device costs.
Strategic Opportunities
- Ambulatory Surgical Center Penetration:Selective rib fracture repairs are migrating to high-volume ASCs in Texas and Florida, creating channel diversification beyond traditional hospital purchasing.
- EU MDR Clinical Evidence Requirements:Stricter CE marking thresholds favor established manufacturers with robust PMCF data, potentially clearing mid-tier competitors from European trauma centers.
- Robotic-Assisted Platform Convergence:Integration of real-time fluoroscopic navigation with automated screw placement is opening training program differentiation opportunities at academic institutions.
Industry Challenges
- Thoracic Surgeon Training Gaps:Few residency programs offer dedicated chest wall reconstruction curricula, limiting the addressable surgeon base for complex plating procedures.
- Interoperability Complexity:Proprietary screw-plate interfaces across manufacturers complicate revision surgeries and create inventory management burdens for hospital sterile processing departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rib Fracture Repair Systems Market |
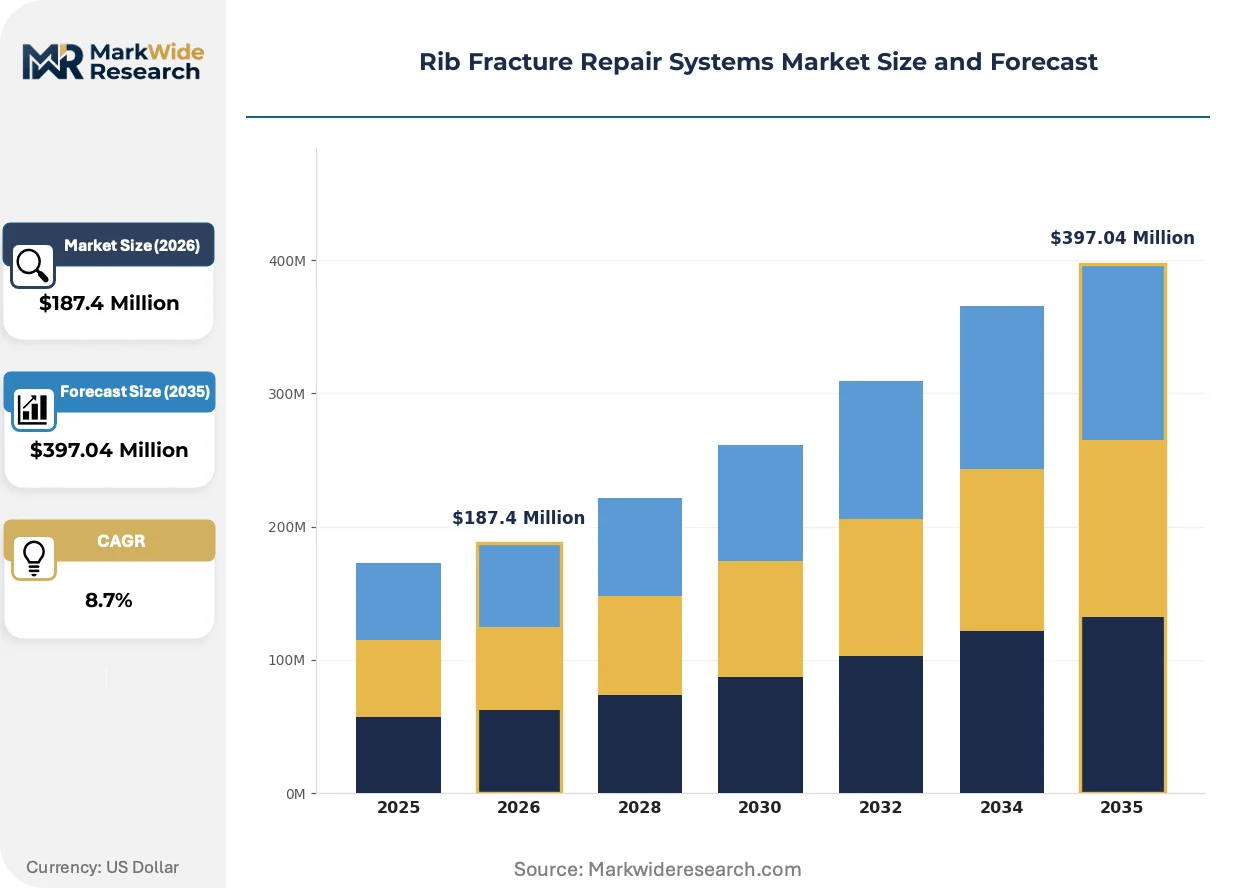
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intramedullary Nails, Plates, Screws, Mesh Technology: Minimally Invasive, Open Surgery, Biodegradable Materials, Robotic-Assisted End User: Hospitals, Surgical Centers, Clinics, Rehabilitation Centers Application: Trauma Surgery, Chest Wall Stabilization, Pain Management, Postoperative Care |
| Companies Covered | Zimmer Biomet, Johnson & Johnson Services, Inc., Acumed, LLC, Stryker Corporation, KLS Martin Group, Jeil Medical Corporation, Waston Medical Co., Ltd., NEURO FRANCE Implants, Able Medical Devices, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rib Fracture Repair Systems Market Evolving Landscape
Intramedullary fixation techniques are reshaping procedural economics by reducing operative time and intercostal muscle disruption, forcing manufacturers to rebalance R&D portfolios toward less invasive access technologies.
Intramedullary nails are decentralizing surgical site selection for rib fracture repair. These devices enable percutaneous placement through small lateral incisions, reducing ICU length-of-stay for flail chest patients. Community trauma centers without dedicated thoracic surgery programs are adopting this technology fastest, compressing the historical concentration of complex cases at academic referral hubs.
EU MDR Article 61 clinical evaluation requirements are elevating evidence burdens for thoracic implant manufacturers seeking CE marking. The regulation mandates systematic literature reviews and post-market clinical follow-up that smaller manufacturers struggle to resource. German trauma centers are responding by consolidating supplier lists toward manufacturers with established PMCF infrastructures.
Hospital value analysis committees are unbundling implant costs from bundled payment contracts for trauma episodes. This purchasing behavior shift separates device selection from procedural reimbursement, empowering materials management to negotiate rib system contracts independently of surgeon preference cards. The pattern is most visible in California and New York, where integrated delivery networks have centralized orthopedic procurement functions.
Rib Fracture Repair Systems Market Segmentation
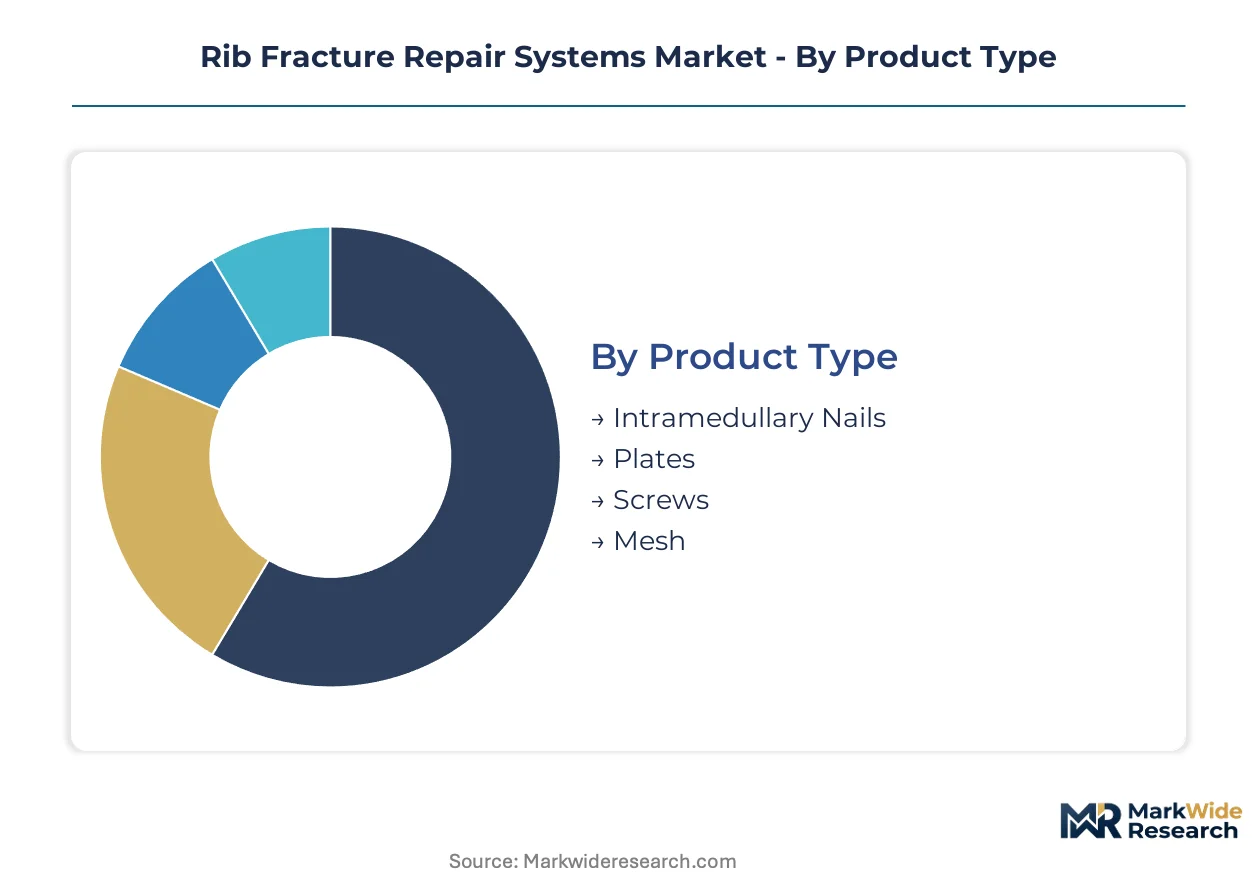
Rib fracture repair systems fragment across four distinct dimensions that determine procurement pathways and clinical adoption. Product type governs manufacturing complexity and titanium alloy specifications. Technology selection drives capital equipment requirements and surgeon training investments. End-user channel dictates pricing tolerance and inventory turnover velocity. Application focus shapes regulatory evidence requirements and reimbursement coding strategies.
Product Type:
Supply concentration for precision-forged titanium components clusters among Midwest orthopedic subcontractors, creating procurement leverage for integrated hospital networks.
- Intramedullary Nails:These devices enable percutaneous placement through small lateral incisions, minimizing intercostal muscle disruption. Community trauma centers in Texas and Florida are adopting this technology fastest, compressing case concentration at academic referral hubs while shortening ICU length-of-stay for flail chest patients.
- Plates:Anatomically contoured titanium constructs with 1.0 mm to 1.5 mm thicknesses restore chest wall integrity in polytrauma cases. Level I trauma centers at academic medical centers anchor demand, driven by dedicated flail chest protocols that mandate surgical stabilization for select patients.
- Screws:Titanium or stainless steel fixation elements with 2.0 mm to 2.7 mm diameters secure plates to rib cortices. Proprietary thread designs complicate revision surgeries and create sterile processing inventory burdens.
- Mesh:Flexible titanium or polymer constructs address comminuted fractures with inadequate bony purchase for screw fixation. Thoracic surgeons at teaching institutions deploy mesh in complex chest wall reconstructions.
Plates absorb the bulk of installed capacity; intramedullary nails are expanding most quickly.
Technology:
Cost tier separation between capital-intensive robotic platforms and conventional instrumentation is widening procurement decision pathways across hospital value analysis committees.
- Minimally Invasive:Percutaneous and limited-access techniques reduce operative time and postoperative pain. This approach leads volume growth as surgeons pursue faster patient mobilization and reduced pulmonary complications.
- Open Surgery:Direct visualization through thoracotomy or extended incisions retains margin concentration in complex polytrauma cases. Academic medical centers with dedicated thoracic surgery programs maintain open technique volume for revision reconstructions.
- Biodegradable Materials:Absorbable polymer constructs eliminate hardware removal surgeries. European trauma centers under EU MDR Article 61 scrutiny are evaluating these alternatives for reduced long-term implant burden.
- Robotic-Assisted:Real-time fluoroscopic navigation with automated screw placement captures disproportionate attention from teaching institutions. FDA 510(k) pathways and EU AI Act compliance requirements shape commercial entry timelines for these platforms.
Minimally invasive systems absorb the bulk of installed capacity; robotic-assisted platforms are climbing the fastest.
End User:
Customer type determines pricing architecture and contract structure, with hospital networks extracting volume commitments through consolidated procurement functions.
- Hospitals:Level I trauma centers and academic medical centers generate the highest procedural volumes for flail chest stabilization. Integrated delivery networks in California and New York have centralized orthopedic procurement, unbundling implant costs from bundled payment contracts.
- Surgical Centers:High-volume ambulatory facilities in Texas and Florida are absorbing selective rib fracture repairs. These sites demand streamlined instrument sets and compressed sterilization turnaround times.
- Clinics:Outpatient settings manage non-displaced fracture follow-up and hardware removal scheduling. Clinic-based demand concentrates in postoperative surveillance rather than initial fixation.
- Rehabilitation Centers:Post-acute facilities coordinate pulmonary recovery protocols after surgical stabilization. These centers influence surgeon device selection through outcome reporting feedback loops.
Hospitals absorb the bulk of installed capacity; surgical centers are gaining share fastest.
Application:
Margin structure varies sharply across application focus, with trauma surgery commanding premium pricing relative to postoperative care adjuncts.
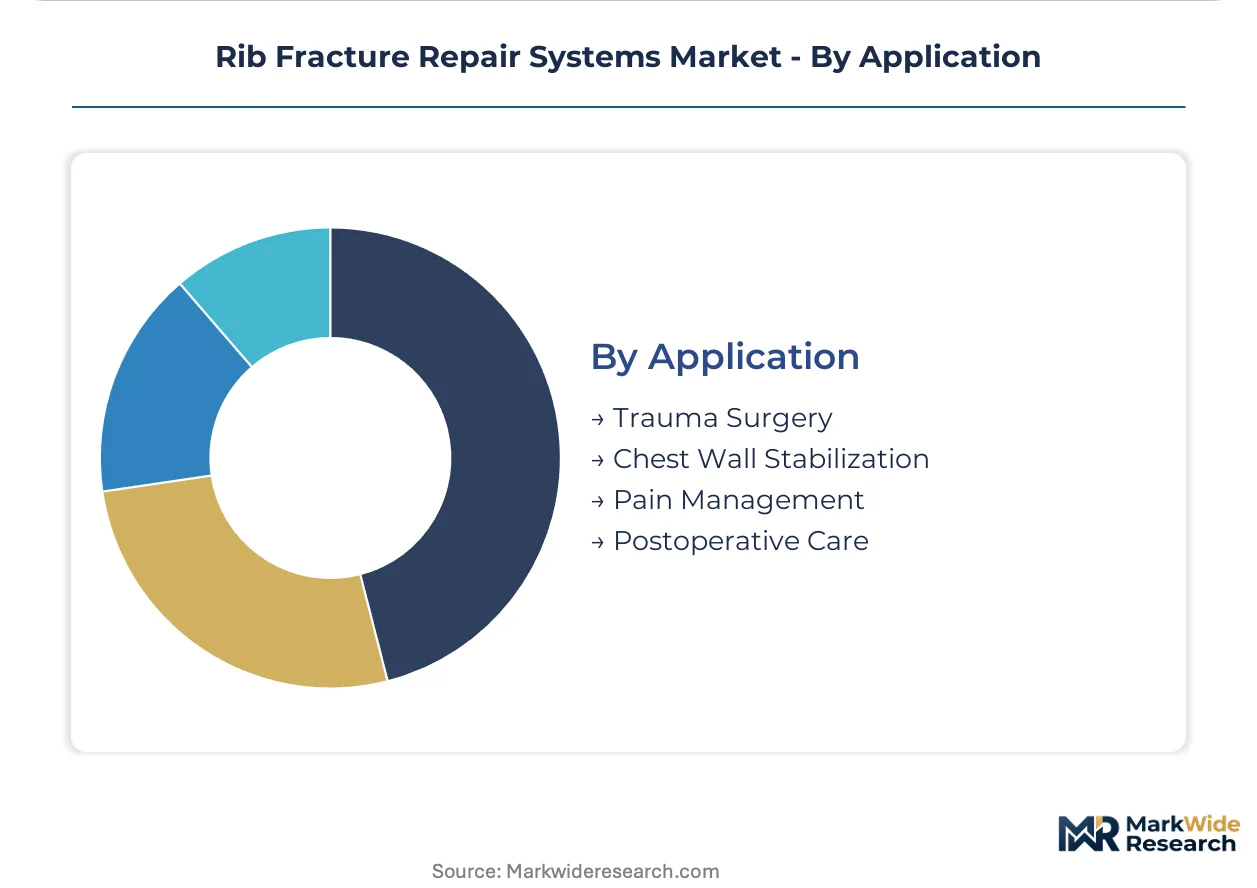
- Trauma Surgery:Emergency stabilization of displaced or multiple rib fractures in polytrauma patients. Academic medical center emergency departments anchor demand, with procedural volume tied to motor vehicle accident and fall injury patterns.
- Chest Wall Stabilization:Restoration of thoracic integrity to enable pulmonary function recovery. This application concentrates in flail chest cases where paradoxical chest wall motion threatens respiratory failure.
- Pain Management:Surgical fixation reduces narcotic requirements and accelerates ventilator weaning. Pain-driven application is expanding as enhanced recovery after surgery protocols prioritize opioid-sparing interventions.
- Postoperative Care:Hardware removal, revision surgery, and long-term surveillance follow initial fixation. Postoperative application generates recurring revenue through implant extraction and complication management.
Trauma surgery absorbs the bulk of installed capacity; pain management is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Titanium sponge processing clusters in the United States Midwest anchor precision-forging capacity for anatomically contoured rib plates. This geographic concentration shapes procurement leverage for integrated hospital networks while determining regional supply security for trauma centers.
United States
Level I trauma center networks in California and New York drive procedural volume for flail chest stabilization through dedicated protocols. FDA 510(k) premarket notification pathways streamline commercial entry for thoracic plating manufacturers. The Midwest precision-forging corridor concentrates subcontractor capacity for 1.0 mm to 1.5 mm titanium constructs.
Germany
German trauma centers under EU MDR Article 61 scrutiny consolidate supplier lists toward manufacturers with established PMCF infrastructures. The country's national pharmaceutical regulator enforces systematic literature reviews for CE marking of thoracic implants. Industrial clusters in Baden-Württemberg and Bavaria host orthopedic device subcontractors serving rib fixation system assemblers.
United Kingdom
NHS England value analysis committees unbundle implant costs from bundled payment contracts for trauma episodes. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR evidence thresholds while streamlining national approval timelines. London and Southeast England academic medical centers anchor demand for complex chest wall reconstruction hardware.
China
NMPA medical device registration requirements govern commercial entry for imported thoracic plating systems while accelerating domestic manufacturer certification. Yangtze River Delta medical device clusters produce precision-machined fixation components for regional trauma hospital networks. Shanghai and Jiangsu Province teaching hospitals pilot robotic-assisted surgical platforms for rib fracture repair.
Japan
PMDA premarket approval processes impose clinical evidence requirements on thoracic implant manufacturers comparable to FDA standards. Kanto region academic medical centers in Tokyo maintain dedicated thoracic surgery programs with chest wall reconstruction curricula. METI industrial policy supports titanium alloy processing capabilities for medical device applications.
Rib Fracture Repair Systems Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue robotic-assisted navigation platforms. The vendor base stratifies across three tiers: diversified orthopedic conglomerates with trauma portfolios, specialized thoracic fixation manufacturers, and regional device fabricators serving single-country markets. Consolidation among Level I trauma centers concentrates procurement decisions into integrated delivery networks, amplifying price pressure while expanding volume commitments. Two dominant competitive moves define current positioning: M&A activity targeting specialized plating technology, and strategic partnerships between implant manufacturers and robotic platform developers.
Within the diversified orthopedic tier, Zimmer Biomet and Johnson & Johnson Services, Inc. represent established trauma portfolio holders. Stryker Corporation occupies a position among scale-driven device manufacturers with broad emergency department distribution. Acumed, LLC exemplifies the specialized fixation archetype, anchoring the upper-thoracic plating segment through anatomically contoured system design. Jeil Medical Corporation and Waston Medical Co., Ltd. sit within the Asia-Pacific regional fabricator category, serving domestic trauma center networks under national regulator frameworks.
| Leading Market Players |
|---|
| Zimmer Biomet |
| Johnson & Johnson Services, Inc. |
| Acumed, LLC |
| Stryker Corporation |
| KLS Martin Group |
| Jeil Medical Corporation |
| Waston Medical Co., Ltd. |
| NEURO FRANCE Implants |
| Able Medical Devices |
| Others |
Value Network & Pricing Analysis
EU MDR Article 61 clinical evidence mandates gate both qualified titanium forging supply and premium-tier pricing access for thoracic implant manufacturers, compressing mid-tier competitors while rewarding established players with robust PMCF infrastructures. Hospital value analysis committees exploit this bifurcation to extract volume discounts from compliant suppliers.
Pricing Analysis
Volume concentration in minimally invasive intramedullary nails trades against margin retention in open-surgery plating systems for complex polytrauma. Three-tier pricing structure across premium robotic-assisted platforms, standard anatomically contoured plates, and economy intramedullary nails differentiates by certification grade and after-sales service bundling. Cost compression in standard-tier hardware intensifies as integrated delivery networks consolidate procurement across California and New York hospital systems. Ambulatory surgical centers in Texas and Florida exhibit highest price sensitivity; academic medical centers with dedicated thoracic surgery programs demonstrate lowest sensitivity due to protocol-mandated device specifications.
Supply Chain Analysis
Direct-to-hospital channels handle high-volume trauma center demand while specialty distributors serve community surgical centers with compressed instrument sets. Precision forging capacity for 1.0 mm to 1.5 mm titanium plates concentrates in the United States Midwest, with secondary machining clusters in Baden-Württemberg and Bavaria feeding European assemblers. Raw material supply draws from titanium sponge processors tied to aerospace demand cycles, with screw-grade stainless steel sourcing from Yangtze River Delta mills. Single-source vulnerability in anatomically contoured plate forging creates procurement leverage for integrated hospital networks. Distribution runs through orthopedic-focused GPOs and direct manufacturer contracts with Level I trauma center networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rib fracture repair market sits in a technology-transition phase as intramedullary nail systems displace traditional open-plating approaches for flail chest stabilization, compressing historical case concentration at academic referral hubs.
For Market Incumbents: Acquire specialized intramedullary nail technology portfolios to offset displacement threat from minimally invasive entrants. Backward integration into titanium sponge processing mitigates aerospace-demand price volatility. Defensive patent clustering around percutaneous access instrumentation preserves margin in the fastest-expanding procedural category.
For New Entrants and Emerging Players: Begin with ambulatory surgical center channels in Texas and Florida where procurement committees lack entrenched supplier relationships. Target community trauma centers without dedicated thoracic surgery programs as the most penetrable end-user segment. Lead with streamlined instrument sets and compressed sterilization turnaround times as the primary go-to-market wedge.
For Investors and Strategic Acquirers: FDA 510(k) clearance for robotic-assisted thoracic platforms is the leading indicator that capital equipment convergence will reshape competitive economics. Five-to-ten year viability favors manufacturers with established PMCF infrastructures under EU MDR compliance. Acquisition target archetype: specialized plating technology holders with anatomically contoured IP and Midwest forging relationships. Watch NMPA registration timelines for imported thoracic systems as the signal for Chinese market entry inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR CE Marking Pathway | Systematic literature reviews and PMCF data satisfy German trauma center supplier consolidation. |
| Hospital System Partnership | Integrated delivery network contracts in California and New York unbundle implant costs from bundled payments. |
| Software Companion Development | Real-time fluoroscopic navigation integration differentiates robotic-assisted platforms at teaching institutions. |
| Reimbursement Strategy | Distinct DRG weight advocacy for rib-specific fixation addresses CMS undercapture of device costs. |
| FDA 510(k) Streamlining | Premarket notification acceleration reduces time-to-revenue for thoracic plating manufacturers. |
Research Methodology
FDA 510(k) premarket notification databases, EU MDR Article 61 clinical evaluation submissions, and hospital procurement contract records formed the secondary backbone for this analysis. Primary interviews with thoracic surgeons, hospital value analysis committee members, biomedical engineers, and GPO contracts managers validated demand assumptions. Bottom-up procedural volume estimates triangulated against top-down manufacturer shipment data across the analysis window.
Bottom-up modeling anchored in Level I trauma center procedural volumes, ASC migration patterns, and technology adoption curves. Segmentation dimensions included product type, technology approach, end-user channel, and application focus. CAGRs derived from logistic diffusion curves fitted to historical adoption rates, with titanium alloy processing capacity and reimbursement coding evolution as industry-specific forecast inputs.
Underlying measurement precision varies by segment; intramedullary nail volumes carry tighter precision than robotic-assisted platform forecasts given nascent commercial penetration. Periodic stress-testing of base assumptions is recommended given reimbursement coding friction and EU MDR implementation variability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Airotar Handpiece Market
Medical Devices
At-Home Vaginal Ph Test Kit Market
Medical Devices
Healthcare Additive Manufacturing Market
Medical Devices
Ultrasonic Electrosurgical Devices Market
Medical Devices
Global Artificial Organ and Bionic Implants Market
Medical Devices
Sweden Minimally Invasive Surgery Devices Market
Medical Devices
Neuromodulation Devices Market
Medical Devices
Wireless Surgical Cameras Market
Medical Devices
Global Foot Orthotic Insoles Market
Medical Devices
Air Oxygen Blender Market
Medical Devices
Medical Goggle Market
Medical Devices
Drug Delivery Devices Market
Medical Devices
Cervical Dilators Market
Medical Devices
Global Aneurysm Clips Market
Medical Devices
Ankle Syndesmosis Treatment Devices Market
Medical Devices
Global Blood Clot Retrieval Devices Market