
 Preventive Medicine Market | 2026-2036
Preventive Medicine Market Size, Share, and Industry Trends Forecast 2026-2036
Preventive Medicine Market Outlook
Corporate wellness programs is rebalancing the end-use mix as employers assume larger shares of preventive care expenditure. Pfizer Inc. leverages its vaccine manufacturing scale to supply institutional prevention contracts across multiple continents. Abbott Laboratories anchors point-of-care diagnostic networks with integrated testing platforms designed for decentralized settings. GSK plc. specializes in maternal and pediatric immunization schedules that align with national childhood vaccination programs.
Preventive medicine encompasses clinical interventions, diagnostic protocols, and behavioral health strategies applied before disease onset to reduce incidence, morbidity, and downstream treatment costs. Vaccines constitute the most mature product segment with established cold-chain logistics and public procurement frameworks, while genomic testing represents the fastest-expanding technology category as polygenic risk scores gain clinical validation. Screening tools command concentrated margin pools in oncology and cardiovascular applications where early detection alters therapeutic pathways and payer economics. Telehealth integration into primary care settings is restructuring service delivery by enabling continuous monitoring outside traditional facility boundaries.
The FDA governs premarket approval for diagnostic tests and wearable devices through 510(k) and De Novo pathways that determine market access timelines. CMS reimbursement policies for preventive services under the Affordable Care Act directly influence provider adoption rates and patient utilization patterns. Stakeholders must monitor evolving regulatory frameworks for artificial intelligence-enabled diagnostics as the FDA develops software-as-a-medical-device standards that will reshape competitive positioning in algorithm-driven screening.
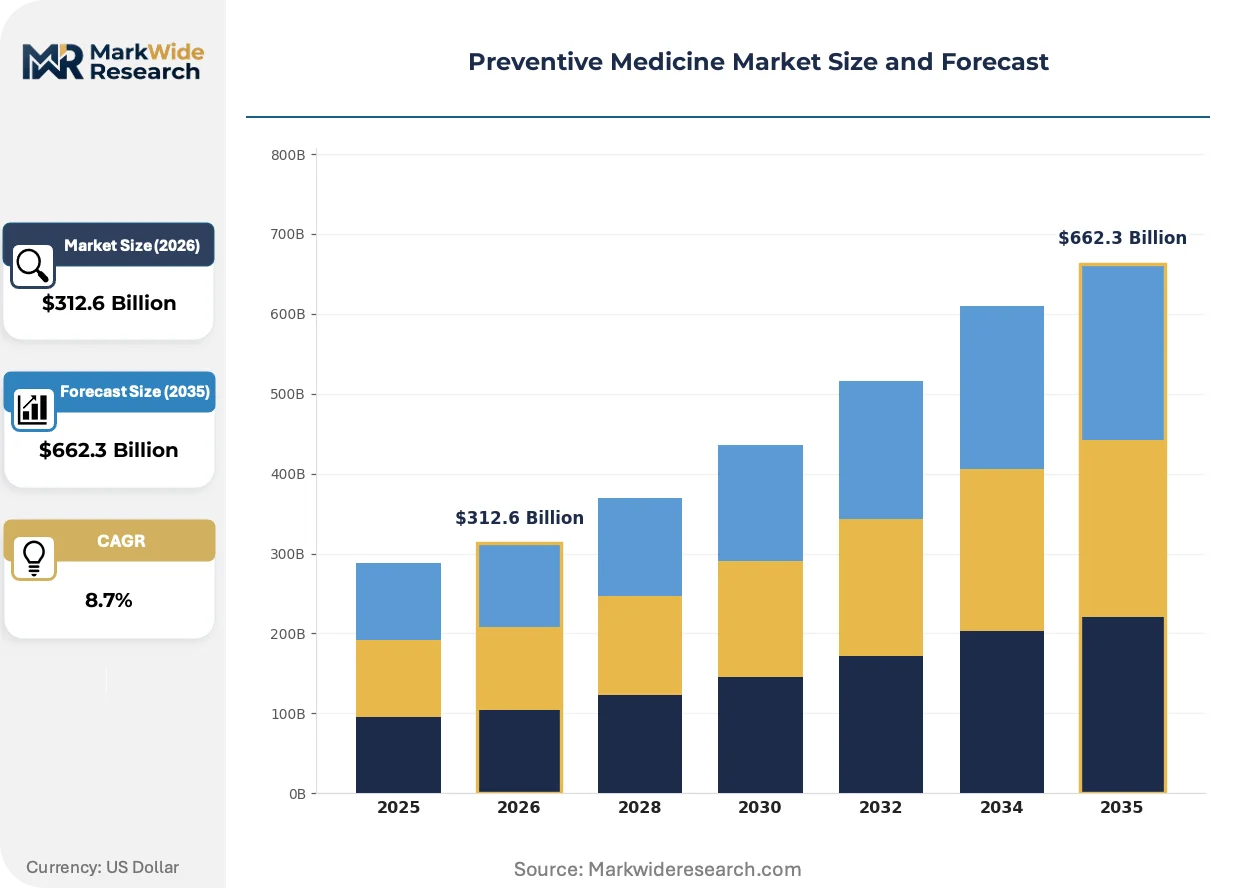
Market Dynamics
Value-based care contracts are restructuring preventive medicine economics by shifting reimbursement from procedure volume to measurable health outcomes, forcing providers and payers to reconfigure service delivery around risk-adjusted prevention metrics rather than episodic treatment.
Growth Catalysts
- CMS Preventive Services Mandate:The Affordable Care Act's elimination of cost-sharing for designated screenings expands patient access to early detection protocols across employer-sponsored plans.
- Polygenic Risk Scoring:Clinical validation of multi-gene algorithms is expanding eligible patient populations for personalized prevention programs in oncology and cardiovascular settings.
- Telehealth Infrastructure:Remote patient monitoring platforms enable continuous biometric tracking outside hospital walls, reducing barriers to adherence for chronic disease prevention.
Market Restraints
- Cold-Chain Logistics Concentration:Vaccine distribution networks remain concentrated among third-party logistics providers with specialized temperature-controlled capabilities, creating single-point vulnerability for temperature-sensitive biologics.
- Diagnostic Test Validation Costs:FDA 510(k) and De Novo pathway requirements impose capital-intensive clinical evidence generation burdens on novel screening technologies before market authorization.
- Behavioral Substitution:Direct-to-consumer wellness applications capture patient attention with lower-friction engagement models, diverting utilization from clinically validated prevention protocols.
Strategic Opportunities
- Decentralized Testing Networks:Point-of-care molecular diagnostics open pharmacy and retail clinic channels for infectious disease screening previously confined to hospital laboratories.
- AI-Enabled Imaging:Machine learning algorithms applied to radiology workflows are converging with existing imaging infrastructure to automate early-stage cancer detection in mammography and lung CT protocols.
- India Preventive Care Expansion:Ayushman Bharat health insurance expansion creates reimbursement pathways for population-scale screening programs targeting diabetes and hypertension in underserved districts.
Industry Challenges
- Interoperability Fragmentation:Electronic health record systems lack standardized data exchange protocols, complicating longitudinal tracking of preventive care outcomes across disparate provider networks.
- Genetic Counselor Workforce Gap:Expansion of genomic testing outpaces certified professional supply, creating bottlenecks in results interpretation and patient communication for hereditary risk assessments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Preventive Medicine Market |
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $662.3 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccines, Diagnostic Tests, Screening Tools, Wearable Devices Care Setting: Primary Care, Clinics, Community Health Centers, Corporate Wellness Programs Technology: Telehealth, Mobile Health Apps, Genomic Testing, Biomarkers Target Population: Children, Elderly, Pregnant Women, High-Risk Individuals |
| Companies Covered | Johnson & Johnson, Pfizer Inc., Novartis AG, Abbott Laboratories, Quest Diagnostics, AstraZeneca, GSK plc., Sanofi, Merck & Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Preventive Medicine Market Strategic Shifts
Artificial intelligence is penetrating diagnostic workflows at accelerating velocity, compressing the gap between data generation and clinical decision support while regulatory frameworks scramble to keep pace with algorithmic innovation.
Multi-omics platforms are converging with electronic health record systems to generate integrated risk profiles combining genomic, proteomic, and metabolomic biomarkers with longitudinal clinical histories. Health systems in the United States and Germany are piloting these integrations for cardiovascular risk stratification. This convergence is compressing the traditional separation between research-grade biomarker discovery and point-of-care clinical utility.
The FDA's Software as a Medical Device guidance is establishing premarket review frameworks for algorithm-driven diagnostics that learn from real-world data. Manufacturers must now submit algorithm change control protocols before deployment. Developers of AI-enabled pathology tools face the steepest compliance adaptation timelines as the agency applies lockdown requirements to continuously learning systems.
Employer purchasing coalitions are consolidating preventive service procurement through specialized benefit administrators rather than traditional insurance carriers. Large manufacturing and technology employers in the United States Midwest and Pacific Northwest have moved fastest toward this unbundled model. This channel rotation concentrates negotiating leverage with a smaller set of specialized vendors and compresses margins for generalist health plans.
Preventive Medicine Market Segmentation
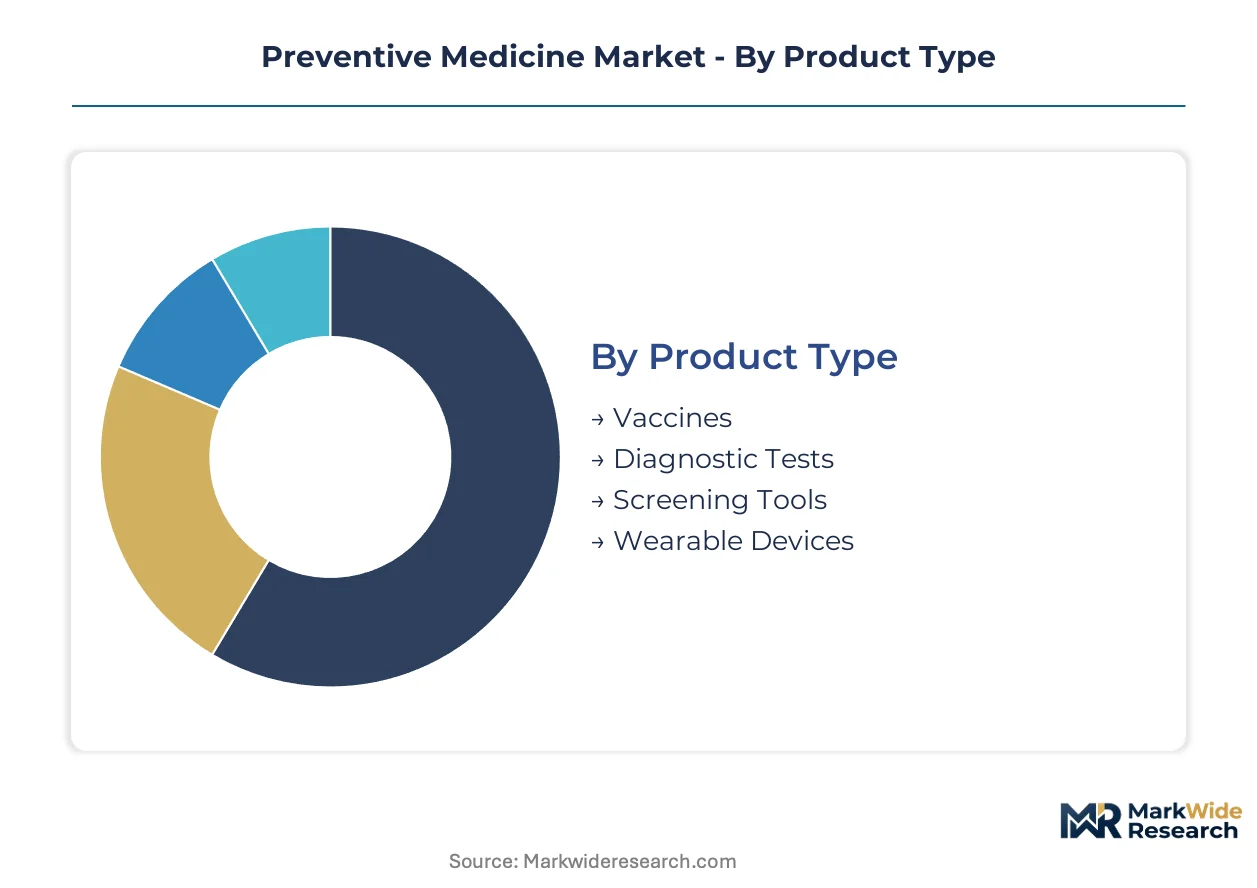
Preventive medicine segmentation reveals distinct procurement patterns across product modalities and care delivery channels. Each category carries unique regulatory pathways and reimbursement structures that determine commercial viability and market access timelines.
Product Type:
Formulation stability and cold-chain requirements differentiate manufacturing economics across biological and non-biological prevention modalities.
- Vaccines:Temperature-sensitive biologics requiring validated cold-chain distribution from manufacturing through point of administration. Demand concentrates in pediatric and elderly immunization schedules funded through public procurement programs in the United States and Germany.
- Diagnostic Tests:In vitro assays ranging from rapid antigen platforms to complex molecular panels. Point-of-care deployment in pharmacy retail channels is displacing centralized laboratory routing for infectious disease screening.
- Screening Tools:Imaging and endoscopic protocols for asymptomatic population surveillance. Colorectal and breast cancer applications command concentrated reimbursement under CMS preventive services mandates.
- Wearable Devices:Continuous biometric monitors for cardiovascular and metabolic parameter tracking. Consumer-grade hardware with clinical validation is penetrating employer-sponsored wellness contracts.
Mature deployment sits with Vaccines. Newer deployment is concentrated in Wearable Devices.
Care Setting:
Reimbursement mechanics and patient capture rates vary sharply across facility-based and distributed care models.
- Primary Care:Longitudinal patient relationships enable risk-stratified prevention protocols. Value-based care contracts in the United States are restructuring physician compensation around panel-wide screening compliance metrics.
- Clinics:Procedure-focused sites optimized for high-throughput screening and immunization delivery. Retail health clinics in CVS and Walgreens networks are expanding point-of-care diagnostic capacity.
- Community Health Centers:Federally qualified health centers serving underserved populations with sliding-scale fee structures. HRSA funding supports diabetes and hypertension prevention programs in rural counties.
- Corporate Wellness Programs:Employer-sponsored preventive services delivered through on-site clinics or third-party administrators. Self-insured employers in manufacturing and technology sectors are unbundling prevention benefits from traditional carriers.
Volume concentration remains in Primary Care. Margin expansion is fastest in Corporate Wellness Programs.
Technology:
Data infrastructure maturity and clinical validation status determine adoption velocity across digital and molecular platforms.
- Telehealth:Synchronous and asynchronous remote consultation platforms integrated with electronic health records. Medicare reimbursement parity established during the pandemic is stabilizing into permanent coverage frameworks.
- Mobile Health Apps:Smartphone-based behavioral interventions and medication adherence tools. FDA software-as-a-medical-device guidance is imposing premarket review requirements on diagnostic algorithm deployments.
- Genomic Testing:Polygenic risk scoring and hereditary disease screening using next-generation sequencing. Cardiovascular and oncology applications are gaining coverage from commercial payers following clinical utility demonstration.
- Biomarkers:Protein, metabolite, and lipid panels for subclinical disease detection. Multi-omics integration with longitudinal electronic health records is piloting in German and United States health systems.
Regulatory clarity is strongest in Telehealth. Technology leadership is concentrating in Genomic Testing.
Target Population:
Risk profile heterogeneity drives variation in intervention intensity and economic modeling across demographic cohorts.
- Children:School-entry immunization requirements and well-child screening protocols. Medicaid and CHIP programs fund preventive services with minimal cost-sharing in the United States.
- Elderly:Medicare Annual Wellness Visits and age-appropriate cancer screenings. Fall prevention and cognitive assessment are expanding under Medicare Advantage supplemental benefits.
- Pregnant Women:Prenatal screening for chromosomal abnormalities and infectious disease exposure. Medicaid maternity coverage mandates first-trimester access to genetic counseling services.
- High-Risk Individuals:Patients with family history or polygenic risk scores triggering intensive surveillance protocols. Commercial payers are piloting risk-stratified prevention benefits for prediabetic and BRCA-positive populations.
Programmatic infrastructure is most developed for Children. Personalized intensity is climbing fastest among High-Risk Individuals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in India and China's Hainan Free Trade Port concentrate preventive medicine manufacturing through tax holidays and streamlined customs protocols that reduce landed costs for temperature-sensitive biologics.
United States
Employer-sponsored wellness contracts and Medicare Advantage supplemental benefits drive preventive service procurement. The Affordable Care Act's CMS preventive services mandate eliminates patient cost-sharing for designated screenings. The Research Triangle Park in North Carolina anchors vaccine manufacturing clusters where cold-chain infrastructure expansion supports institutional distribution networks.
Germany
Statutory health insurance integration of digital prevention apps and multi-omics pilot programs accelerates adoption. The EU Medical Device Regulation (MDR) imposes clinical evidence requirements on diagnostic software deployments. The Munich-Frankfurt corridor concentrates AI-enabled imaging development where health systems test algorithm-driven cancer screening protocols.
India
Ayushman Bharat health insurance expansion creates reimbursement pathways for population-scale diabetes and hypertension screening. The Central Drugs Standard Control Organization (CDSCO) streamlines medical device registration through risk-based classification. Hyderabad's Genome Valley anchors genomic testing infrastructure where contract research organizations validate polygenic risk algorithms for cardiovascular applications.
China
National immunization program expansion and Healthy China 2030 policy targets elevate preventive care priority in health system planning. The National Medical Products Administration (NMPA) accelerates review timelines for innovative diagnostics through priority review pathways. Shanghai's Zhangjiang Hi-Tech Park concentrates molecular diagnostic manufacturing where domestic firms scale point-of-care testing platforms.
United Kingdom
NHS Long Term Plan commitments to early cancer detection expand screening program budgets and diagnostic capacity. The Medicines and Healthcare products Regulatory Agency (MHRA) applies post-Brexit frameworks for software-as-a-medical-device oversight. The Cambridge-London corridor anchors genomic medicine clusters where polygenic risk scoring integrates with primary care electronic health records.
Preventive Medicine Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with vaccine production consolidating around biological manufacturing scale while diagnostic testing fragments across point-of-care and laboratory platforms. The market structures into three archetypes: integrated pharmaceutical conglomerates with vaccine portfolios, specialized diagnostic platform developers, and decentralized testing service networks. Competitive moves concentrate on strategic partnerships for biomarker discovery and geographic licensing arrangements for regulatory market access.
Within the integrated pharmaceutical tier, Pfizer Inc. and GSK plc. exemplify scale-driven prevention portfolios, while Abbott Laboratories represents the diagnostic platform archetype with decentralized testing infrastructure. These three firms anchor distinct competitive vectors: vaccine supply contracting, maternal-pediatric immunization scheduling, and point-of-care network deployment respectively.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Pfizer Inc. |
| Novartis AG |
| Abbott Laboratories |
| Quest Diagnostics |
| AstraZeneca |
| GSK plc. |
| Sanofi |
| Merck & Co., Inc. |
| Others |
Value Chain & Pricing Dynamics
Certified genetic counselor concentrations in the United States Northeast and Germany's Munich-Frankfurt corridor create labor-cost differentials that widen pricing-tier spreads between premium genomic interpretation services and standardized screening panels.
Pricing Analysis
Short lead-time premiums for cold-chain vaccine deliveries command 15-25% markups over scheduled procurement slots, while spot inventory discounts apply to near-expiry biologics approaching temperature-threshold limits. The dominant pricing model runs contract-based long-term offtake agreements with public procurement programs, differentiated by FDA tier certification and volume scale commitments. Pricing pressure stems from employer purchasing coalitions consolidating negotiating leverage with specialized benefit administrators. Self-insured employers in manufacturing sectors show highest price sensitivity; Medicare Advantage plans demonstrate lowest sensitivity due to risk-adjusted reimbursement floors.
Supply Chain Analysis
Regional distribution centers in Belgium, Singapore, and the United States Midwest operate hub-and-spoke patterns for temperature-sensitive biologics, with spoke nodes reaching pharmacy retail channels and hospital systems. Manufacturing concentrates in the United States, Germany, and India for vaccine fill-finish operations; China and South Korea anchor wearable device component assembly. Raw material dependencies include specialized refrigerants, medical-grade glass vials, and semiconductor sensors for continuous monitors. Single-source vulnerability runs through third-party logistics providers with validated cold-chain credentials. Distribution runs through institutional procurement frameworks for vaccines and direct-to-employer channels for wellness program services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The preventive medicine market sits in a technology-transition phase where AI-enabled diagnostics replace legacy radiology workflows and polygenic risk scoring displaces single-gene hereditary screening protocols.
For Market Incumbents: Anticipate margin compression from employer purchasing coalitions by securing exclusive distribution partnerships with specialized benefit administrators. Defensive consolidation through backward integration into biomarker discovery capabilities counters emerging AI-native diagnostic developers. Prioritize FDA software-as-a-medical-device certification investments to maintain algorithm deployment privileges against regulatory lockdown requirements. For New Entrants and Emerging Players: Capture white-space opportunity in India's Ayushman Bharat reimbursement pathways for population-scale diabetes and hypertension screening programs. The most penetrable segment sits with decentralized point-of-care molecular diagnostics in pharmacy retail channels previously confined to hospital laboratories. Pursue go-to-market angles through GPO contracts managers at federally qualified health centers seeking sliding-scale fee structures for underserved counties. For Investors and Strategic Acquirers: Re-rating potential sits with AI-enabled imaging specialists given FDA algorithm change control protocol approvals as catalysts. Long-term viability favors platform developers with integrated electronic health record connectivity over standalone application vendors. Target acquisition archetypes include contract research organizations validating polygenic risk algorithms for cardiovascular applications. Watch CDSCO priority review pathway grants as inflection indicators for Indian market access acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-a-Medical-Device Submission | Algorithm change control protocols unlock Medicare reimbursement for AI pathology tools under CMS preventive services mandates. |
| Hospital System Partnership | Integrated electronic health record connectivity enables longitudinal risk stratification combining genomic and clinical biomarkers. |
| Backward Integration into Biomarker Discovery | In-house polygenic risk algorithm development reduces licensing costs and accelerates cardiovascular application validation timelines. |
| Reimbursement Strategy | Value-based care contract alignment with employer purchasing coalitions secures multi-year preventive service procurement commitments. |
| Geographic Expansion | CDSCO streamlined registration through risk-based classification opens India's Ayushman Bharat population-scale screening reimbursement pathways. |
Study Parameters
Independent corroboration across FDA 510(k) and De Novo submission databases, CMS Medicare reimbursement filings, and ClinicalTrials.gov protocols underwrites the qualitative findings. Primary interviews with regulatory affairs leads at diagnostic platform developers, formulary directors at commercial payers, hospital procurement managers, and biomedical engineers at health systems combined with secondary validation. Bottom-up triangulation across product-type shipment data and top-down reconciliation against employer-sponsored healthcare expenditure reports anchor the analysis.
Rate-of-change decomposition across the analysis window separates volume drivers from price-mix effects. Segmentation dimensions modeled include product type, care setting, technology platform, and target population risk stratum. CAGRs derive from regression against historical immunization schedule completion rates, screening compliance metrics under value-based contracts, and genomic test coverage expansion curves. Forecast inputs incorporate FDA software-as-a-medical-device guidance implementation timelines and employer wellness program adoption elasticities.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to AI diagnostic reimbursement parity decisions and genetic counselor workforce expansion rates. Outputs reflect documented assumptions around CMS preventive services mandate stability and cold-chain logistics capacity growth. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Research
AAV Contract Development and Manufacturing Organizations Market
Medical Research
Epigenetics Market
Medical Research
Global Human Liver Models Market
Medical Research
India Computer-Aided Drug Discovery Market
Medical Research
Health Economics and Outcomes Research (HEOR) Services Market
Medical Research
Forensic Medicine Market
Medical Research
US Academic Medical Centers Market
Medical Research
Global Mice Model Market
Medical Research
Malaria Vaccine Market
Medical Research
North America Biobanks Market
Medical Research
Cancer Mouse Models Market
Medical Research
Chromatin Immunoprecipitation Sequencing Market
Medical Research
Placenta Market
Medical Research
Mice Model Technologies Market
Medical Research
Asia-Pacific Computer-Aided Drug Discovery Market
Medical Research
Global Humanized Mouse Model Market