
 Eye Drop Dispenser Market | 2026-2036
Eye Drop Dispenser Market Size, Share, and Industry Trends Forecast 2026-2036
Eye Drop Dispenser Market Analytics
ISO 15378 certification for primary packaging materials is unwinding competitive access across ophthalmic supply chains. Aptar Pharma leverages advanced pump engineering to sustain leadership in preservative-free multi-dose formats. Silgan Holdings anchors North American manufacturing scale through captive blow-fill-seal capacity. Gulden Ophthalmics specializes in adaptive devices for geriatric and pediatric hand-strength limitations.
An eye drop dispenser is a metered-dose delivery system engineered to administer precise microliter volumes of ophthalmic formulations while minimizing contamination, waste, and ocular surface trauma through controlled drop formation and targeted instillation. Multi-dose pump systems with unidirectional valve architecture dominate institutional procurement due to sterility assurance and cost-per-dose efficiency. Single-use strip dispensers lead household segments where travel convenience and cross-infection prevention drive preference. Smart dispensers with dose-tracking and Bluetooth connectivity represent the fastest-expanding category as digital therapeutics integration reshapes adherence monitoring and reimbursement logic.
FDA 21 CFR Part 4 combination product rules and EU MDR Class IIa requirements for active drug-device combinations govern design validation, human factors testing, and post-market surveillance obligations. EPA resin regulations and REACH substance restrictions on phthalates and bisphenol derivatives constrain material selection for plastic and biodegradable housings. Stakeholders must monitor evolving pharmacopeial standards for extractables and leachables testing as preservative-free formulations proliferate and regulatory scrutiny intensifies on polymer-drug compatibility over shelf life.
Market Dynamics
ISO 15378 certification requirements for primary ophthalmic packaging materials are restructuring competitive access across supply chains, forcing smaller converters toward specialized contract manufacturing partnerships while favoring incumbents with captive blow-fill-seal capacity.
Growth Catalysts
- EMA MDR Class IIa mandates:Active drug-device combination rules in Europe are accelerating validation investments for preservative-free multi-dose pump systems, pulling demand toward compliant suppliers.
- Geriatric hand-strength limitations:Japan's super-aged demographic profile is driving institutional procurement of adaptive dispenser geometries with reduced actuation force requirements.
- Bluetooth-enabled adherence tracking:Digital therapeutics integration is reshaping reimbursement logic for smart dispensers in United States Medicare Advantage formularies.
Market Restraints
- Medical-grade polymer feedstock concentration:Cyclo-olefin polymer supply concentrates among three Japanese and German resin compounders, exposing converters to input cost volatility.
- REACH phthalate restrictions:ECHA substance limitations on plasticizer chemistries are constraining material selection for biodegradable housing development programs.
- Extractables testing burden:USP <661> and <1661> pharmacopeial standards for polymer-drug compatibility are extending qualification timelines for preservative-free formulations.
Strategic Opportunities
- Pediatric indication expansion:Underpenetrated demand for child-resistant yet accessible dispensers in France and Germany presents white space for ergonomic design specialists.
- Biodegradable housing convergence:PLA-PHA polymer blends combined with antimicrobial surface treatments are opening sustainable positioning in Nordic hospital procurement frameworks.
- Direct-to-patient subscription channels:Chronic dry-eye management platforms in the United States are bypassing traditional pharmacy distribution for automated refill dispenser programs.
Industry Challenges
- Human factors engineering talent scarcity:Specialized usability testing expertise for geriatric and visually impaired populations remains concentrated among three US and Swiss consultancies.
- ISO 15378 certification timeline compression:Primary packaging material audits are extending 40-60% longer as notified bodies prioritize MDR transition backlogs.
- Legacy ERP integration friction:Smart dispenser data streams require middleware development for compatibility with established hospital inventory management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eye Drop Dispenser Market |
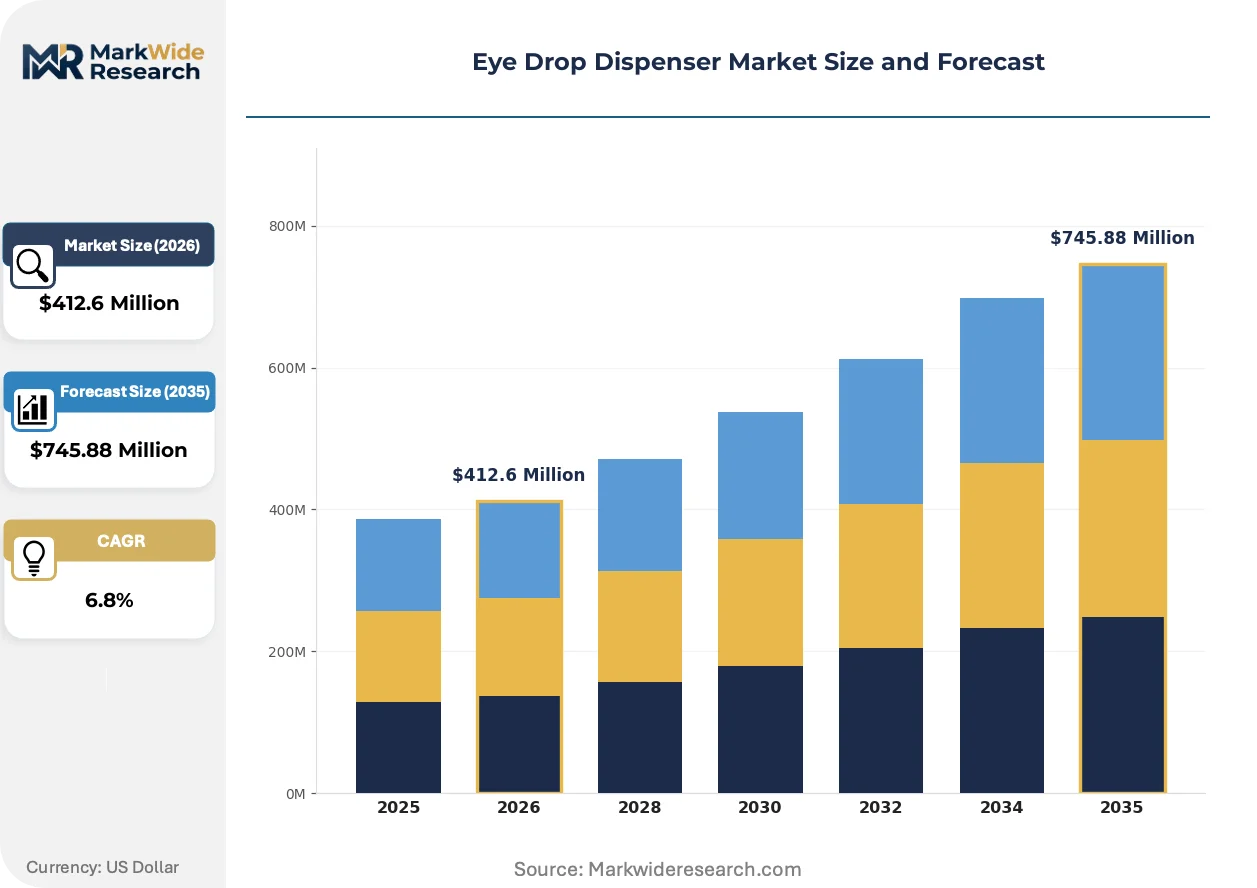
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-use, Multi-dose, Alternative Dropper, Smart Dispenser Delivery Mode: Squeeze Bottle, Pump, Spray, Rigid Delivery End User: Households, Clinics, Hospitals, Pharmacies Material: Plastic, Glass, Metal, Biodegradable |
| Companies Covered | Silgan Holdings, Spruyt Hillen, Aptar Pharma, Scope Ophthalmics, Gulden Ophthalmics, Owen Mumford, Alcon, Simovision, Opticare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eye Drop Dispenser Market Evolving Landscape
Unidirectional valve architectures with silicone-free elastomer seals are displacing conventional pump technologies as sterility assurance standards tighten across institutional procurement channels worldwide.
Electromechanical dose-counters with capacitive sensing are supplanting mechanical pawl-and-ratchet mechanisms in premium multi-dose dispensers. Glaucoma specialty clinics in Germany and Japan are adopting these systems at replacement cycle intervals compressed to 18-24 months. The shift is enabling real-world evidence generation for pharmaceutical sponsors while compressing margins for legacy mechanical component suppliers.
FDA 21 CFR Part 4 combination product rules are forcing parallel design validation pathways for drug-device submissions. The regulation requires human factors testing documentation that spans both pharmaceutical and engineering disciplines. Ophthalmology clinics in the United States are responding by consolidating vendor relationships toward full-service CDMOs with integrated regulatory affairs capabilities.
Hospital formularies are unbundling device procurement from drug purchasing agreements, creating standalone tender categories for precision dosing systems. This pattern disrupts traditional bundling arrangements between pharmaceutical manufacturers and dispenser suppliers. The Netherlands and Switzerland exhibit the most advanced unbundling, with separate technical evaluation committees for device performance metrics.
Eye Drop Dispenser Market Segmentation
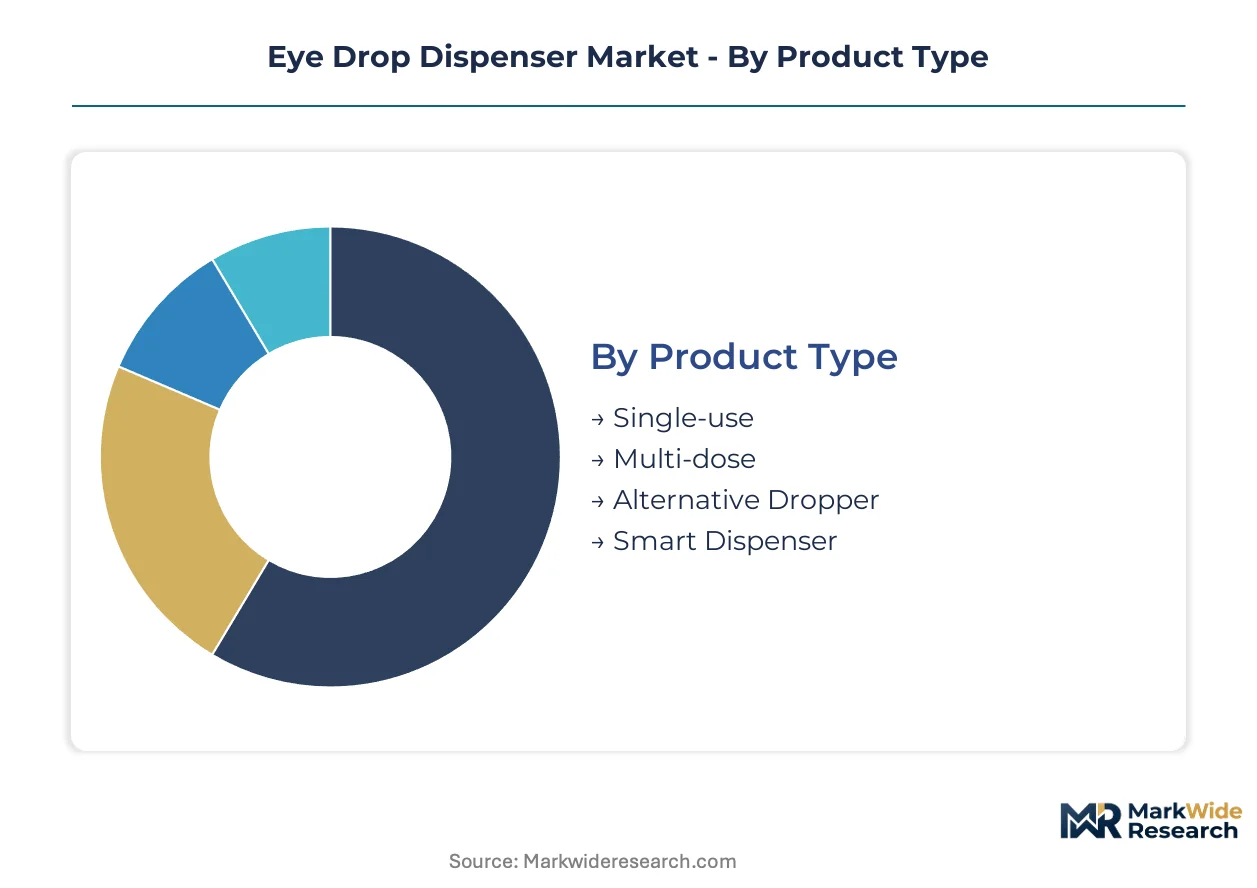
Segmentation in the eye drop dispenser market reveals divergent margin structures across precision dosing technologies and sterility assurance levels. Procurement channels fragment sharply between institutional tenders demanding validated multi-dose systems and retail segments prioritizing portability and unit economics.
Product Type:
Premium margin pools concentrate in connected devices and preservative-free multi-dose formats where regulatory validation creates pricing power.
- Multi-dose:Pump systems with unidirectional valve architecture dominate ophthalmology clinic procurement in the United States, Germany, and Japan. EMA MDR Class IIa compliance requirements and FDA 21 CFR Part 4 validation timelines favor incumbent suppliers with captive blow-fill-seal capacity and extend replacement cycles to 18-24 months in glaucoma specialty settings.
- Smart Dispenser:Bluetooth-enabled dose-counters with capacitive sensing integrate with digital therapeutics platforms and Medicare Advantage formularies. These electromechanical systems generate real-world adherence data for pharmaceutical sponsors while commanding hardware premiums that compress margins for legacy mechanical component suppliers.
- Single-use:Strip dispensers lead household segments where travel convenience and cross-infection prevention drive preference in France and Nordic markets.
- Alternative Dropper:Adaptive geometries with reduced actuation force serve geriatric and pediatric hand-strength limitations in Japan's super-aged demographic profile.
Multi-dose holds installed capacity. Smart Dispenser is rotating up the share rankings.
Delivery Mode:
Cost tier stratification separates precision pump mechanisms from commodity squeeze formats, with spray and rigid systems occupying intermediate positioning.
- Pump:Metered-dose delivery with silicone-free elastomer seals displaces conventional technologies as sterility assurance standards tighten across institutional procurement channels worldwide. Cyclo-olefin polymer feedstock concentration among Japanese and German resin compounders exposes converters to input cost volatility.
- Squeeze Bottle:Polyethylene and polypropylene formats dominate volume in retail pharmacy and direct-to-patient subscription channels for chronic dry-eye management platforms in the United States.
- Spray:Aerosolized mist delivery reduces ocular surface trauma in pediatric indications across France and Germany.
- Rigid Delivery:Fixed-geometry dispensers with antimicrobial surface treatments target Nordic hospital procurement frameworks prioritizing sustainable materials.
Pump systems command the highest unit economics. Squeeze Bottle rotates up through subscription channel expansion.
End User:
Application concentration splits between chronic disease management in outpatient settings and acute care protocols requiring single-patient assignment.
- Hospitals:Unidirectional valve architectures with extractables testing documentation per USP <661> and <1661> standards dominate formulary procurement. The Netherlands and Switzerland exhibit the most advanced unbundling patterns, with separate technical evaluation committees for device performance metrics independent of drug purchasing agreements.
- Clinics:Glaucoma and dry-eye specialty practices in Germany and Japan compress replacement cycles for electromechanical dose-counters while consolidating vendor relationships toward full-service CDMOs with integrated regulatory affairs capabilities.
- Households:Single-use strip dispensers and portable multi-dose systems prioritize travel convenience and cross-infection prevention.
- Pharmacies:Traditional distribution faces disruption from automated refill dispenser programs bypassing retail channels.
Hospitals hold validated procurement volume. Clinics are rotating up through digital therapeutics integration.
Material:
Supply concentration in medical-grade polymer feedstocks constrains biodegradable development programs facing REACH phthalate restrictions.
- Plastic:Cyclo-olefin polymers and polyethylene terephthalate glycol dominate multi-dose and squeeze bottle formats. EPA resin regulations and ECHA substance limitations on plasticizer chemistries constrain material selection as preservative-free formulations proliferate.
- Biodegradable:PLA-PHA polymer blends with antimicrobial surface treatments open sustainable positioning in Nordic hospital procurement frameworks, though extractables testing burden extends qualification timelines.
- Glass:Borosilicate formats retain niche demand for high-value preservative-free formulations requiring inert primary contact surfaces.
- Metal:Aluminum housings serve premium connected devices requiring electromagnetic shielding for Bluetooth-enabled adherence tracking systems.
Plastic holds incumbent supply scale. Biodegradable is rotating up through Nordic procurement preference shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement managers at ophthalmology clinics and hospital formularies concentrate demand in aging societies with high glaucoma and dry-eye prevalence. Buyers prioritize preservative-free multi-dose systems with validated sterility assurance and digital adherence tracking capabilities.
United States
Medicare Advantage formularies are expanding coverage for Bluetooth-enabled smart dispensers with dose-tracking functionality. FDA 21 CFR Part 4 combination product rules require parallel design validation for drug-device submissions. Glaucoma specialty practices in California and Massachusetts compress replacement cycles to 18-24 months for electromechanical systems.
Germany
Hospital formularies in Bavaria and North Rhine-Westphalia lead European unbundling of device procurement from drug purchasing agreements. EMA MDR Class IIa mandates accelerate validation investments for preservative-free pump systems. The KBA-equivalent notified body landscape extends ISO 15378 certification timelines amid MDR transition backlogs.
Japan
Super-aged demographic profiles drive institutional procurement of adaptive dispensers with reduced actuation force. METI guidelines on medical device quality management intersect with PMDA requirements for preservative-free multi-dose formats. Tokyo and Osaka ophthalmology clusters consolidate vendor relationships toward full-service CDMOs with integrated regulatory affairs.
Netherlands
Hospital procurement frameworks in the Randstad exhibit the most advanced unbundling patterns with separate technical evaluation committees for device performance metrics. REACH phthalate restrictions constrain biodegradable housing development programs. Eindhoven-region converters face cyclo-olefin polymer feedstock concentration among Japanese and German resin compounders.
Switzerland
Swissmedic requirements for active drug-device combinations govern human factors testing documentation spanning pharmaceutical and engineering disciplines. Nordic-inspired sustainable procurement preferences in Zurich and Basel favor PLA-PHA polymer blends with antimicrobial surface treatments. Extractables testing per USP standards extends qualification timelines for preservative-free formulations.
Eye Drop Dispenser Market Competitive Landscape
Player mix skews toward packaging specialists with captive blow-fill-seal capacity and pump engineering capabilities. Consolidation pressure favors incumbents with ISO 15378 certification and integrated regulatory affairs functions. Three archetypes dominate: precision dosing engineers, adaptive device specialists for geriatric populations, and connected health platform integrators. Capacity expansion and strategic partnerships with pharmaceutical sponsors represent the dominant competitive moves as formularies unbundle device procurement.
Within the precision dosing tier, Aptar Pharma and Silgan Holdings exemplify contrasting scale strategies. Aptar Pharma leverages advanced pump engineering to sustain leadership in preservative-free multi-dose formats. Silgan Holdings anchors North American manufacturing scale through captive blow-fill-seal capacity. Gulden Ophthalmics occupies a specialist position in adaptive geometries for hand-strength limitations. These three represent the archetype spectrum from premium engineering to manufacturing scale to ergonomic specialization.
| Leading Market Players |
|---|
| Silgan Holdings |
| Spruyt Hillen |
| Aptar Pharma |
| Scope Ophthalmics |
| Gulden Ophthalmics |
| Owen Mumford |
| Alcon |
| Simovision |
| Opticare |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between cyclo-olefin polymer suppliers and blow-fill-seal converters lock in both feedstock access and price visibility for multi-dose pump manufacturers serving FDA and EMA compliance markets. These contracts insulate tier-one suppliers from resin volatility while exposing spot-market buyers to margin compression.
Pricing Analysis
Cost-plus contracts with Japanese and German resin indexation govern cyclo-olefin polymer supply. Three-tier pricing structure across premium, standard, and economy levels separates ISO 15378-certified systems from uncertified alternatives and commodity squeeze bottles. Pricing pressure stems from REACH phthalate restrictions forcing material reformulation. Hospital procurement committees exhibit lowest price sensitivity; retail pharmacy channels face highest cost compression.
Supply Chain Analysis
Cyclo-olefin polymer feedstock concentration among Japanese and German resin compounders creates a chokepoint exposing converters to input cost volatility. Medical-grade polymer compounding draws from Mitsui Chemicals, Zeon Corporation, and TOPAS Advanced Polymers. Single-source vulnerability concentrates in silicone-free elastomer seals for unidirectional valve architectures. Distribution runs through pharmaceutical CDMOs and direct-to-patient subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflect as Bluetooth-enabled dispensers integrate with Medicare Advantage formularies and pharmaceutical adherence contracts, shifting value capture from hardware margins to recurring data services.
For Market Incumbents: Compound regulatory certification advantages by accelerating ISO 15378 audits ahead of MDR transition backlogs. Defend against smart dispenser entrants by acquiring electromechanical dose-counter engineering talent from Swiss and US consultancies. Prioritize backward integration into blow-fill-seal capacity to maintain cost position against Asian contract manufacturers. For New Entrants and Emerging Players: Lead with pediatric indication expansion in France and Germany where child-resistant yet accessible geometries remain underpenetrated. Target adaptive device white space for geriatric hand-strength limitations in Japan's super-aged demographic. Deploy direct-to-patient subscription channels bypassing traditional pharmacy distribution. For Investors and Strategic Acquirers: Capital is best deployed toward connected health platform integrators with FDA 21 CFR Part 4 combination product validation and pharmaceutical sponsor relationships. Long-term viability hinges on digital therapeutics ecosystem positioning rather than mechanical component manufacturing. Watch for Medicare Advantage formulary expansion signals as adherence data reimbursement logic matures.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Class IIa Compliance Investment | EMA validation timelines favor incumbents with captive regulatory affairs capacity. |
| Pharmaceutical Sponsor Partnership | Real-world adherence data contracts reshape reimbursement logic for smart dispensers. |
| Blow-Fill-Seal Capacity Expansion | Captive manufacturing insulates against cyclo-olefin polymer feedstock concentration. |
| Pediatric Indication Development | France and Germany procurement frameworks prioritize child-resistant ergonomic designs. |
| Biodegradable Housing Program | PLA-PHA polymer blends align with Nordic hospital sustainable procurement preferences. |
Research Methodology
A standing panel of ophthalmology clinic procurement managers, hospital formulary directors, pharmaceutical regulatory affairs leads, and blow-fill-seal manufacturing engineers provided ongoing calibration. Primary interviews combined with secondary validation from FDA 510(k) filings, EMA MDR submission databases, USP pharmacopeial standards, and hospital GPO contract repositories. Bottom-up unit economics and top-down category spend estimates underwent iterative triangulation.
Consistency checks validated volume and value outputs against pharmaceutical packaging industry benchmarks and regional medical device production indices. Segmentation modeling spanned product type, delivery mode, end user, and material composition across the analysis window. CAGRs derived from replacement cycle compression patterns in glaucoma specialty settings and digital therapeutics adoption curves. Forecast inputs incorporated ISO 15378 certification timeline projections and cyclo-olefin polymer supply elasticity assumptions.
Underlying assumptions cover MDR transition completion, REACH phthalate restriction enforcement, and Medicare Advantage formulary expansion, with deviation risk concentrated in notified body audit capacity and resin compounder production allocation. Practitioners should keep alternative scenarios live as digital therapeutics reimbursement logic and sustainable procurement preference shifts evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Keratometers Market
Medical Devices
Cervical Retractors Market
Medical Devices
Non- Resorbable Cranial Fixation System Market
Medical Devices
Hyperpigmentation Treatment Devices Market
Medical Devices
Bioimpedance Analyzers Market
Medical Devices
Asia-Pacific General Surgical Devices Market
Medical Devices
Education Microscope Market
Medical Devices
Saudi Arabia Ophthalmic Devices Market
Medical Devices
Middle East and Africa Vagus Nerve Stimulation Market
Medical Devices
Insulin Delivery Devices (Idd) Market
Medical Devices
Pedicle Screw Systems Market
Medical Devices
Artificial Ventilation and Anesthesia Masks Market
Medical Devices
North America Ablation Devices Market
Medical Devices
Global Dermatome Device Market
Medical Devices
Pannus Retraction Device Market
Medical Devices
Cheek Implants Market