
 Small Bone and Joint Orthopedic Devices Market | 2026-2036
Small Bone and Joint Orthopedic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Small Bone and Joint Orthopedic Devices Market Outlook
Implant maintenance and remote monitoring subscription layers is repositioning vendor-customer relationships in small bone and joint orthopedic devices. Stryker leverages its surgical navigation ecosystem to lock in recurring service revenue across hospital accounts. Arthrex, Inc. anchors its competitive stance through specialized arthroscopy instrumentation and surgeon training infrastructure. Zimmer Biomet competes on manufacturing scale, sustaining broad portfolio coverage across trauma and extremities segments.
Small bone and joint orthopedic devices comprise fixation hardware, biological grafts, and powered instrumentation engineered for skeletal structures distal to the shoulder and hip, typically fabricated from titanium alloys, PEEK polymers, or resorbable composites to achieve anatomical stabilization with modulus-matched biomechanics. These systems restore articular function and osseous union in distal radius, ankle, wrist, and shoulder reconstructions where load-bearing demands differ from large-joint arthroplasty. The fracture repair application segment leads procedural volume, while 3D printing technology captures expanding margin pools through patient-specific anatomical modeling and custom plate geometries. Minimally invasive surgery technology sustains faster growth trajectories as ambulatory settings demand reduced soft-tissue disruption and abbreviated recovery protocols.
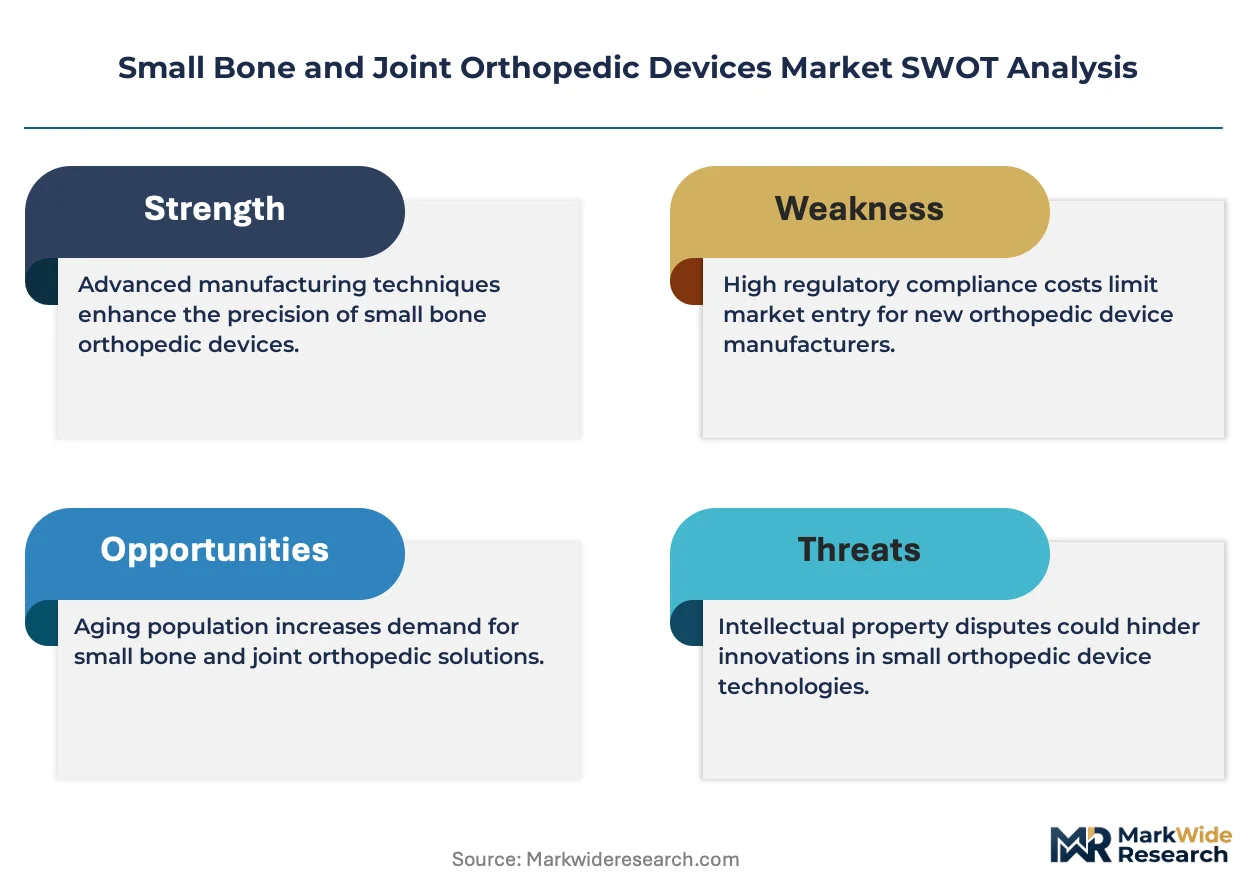
FDA 510(k) premarket notification requirements and EU MDR conformity assessment procedures govern device commercialization, with the latter extending clinical evidence obligations for medium-risk implantable hardware. The country's national pharmaceutical regulator in Japan, PMDA, imposes additional QMS inspections that filter market access for foreign manufacturers. Stakeholders must monitor evolving biodegradability standards and recycling mandates from ECHA and national environmental agencies that will reshape material selection commitments across product development pipelines.
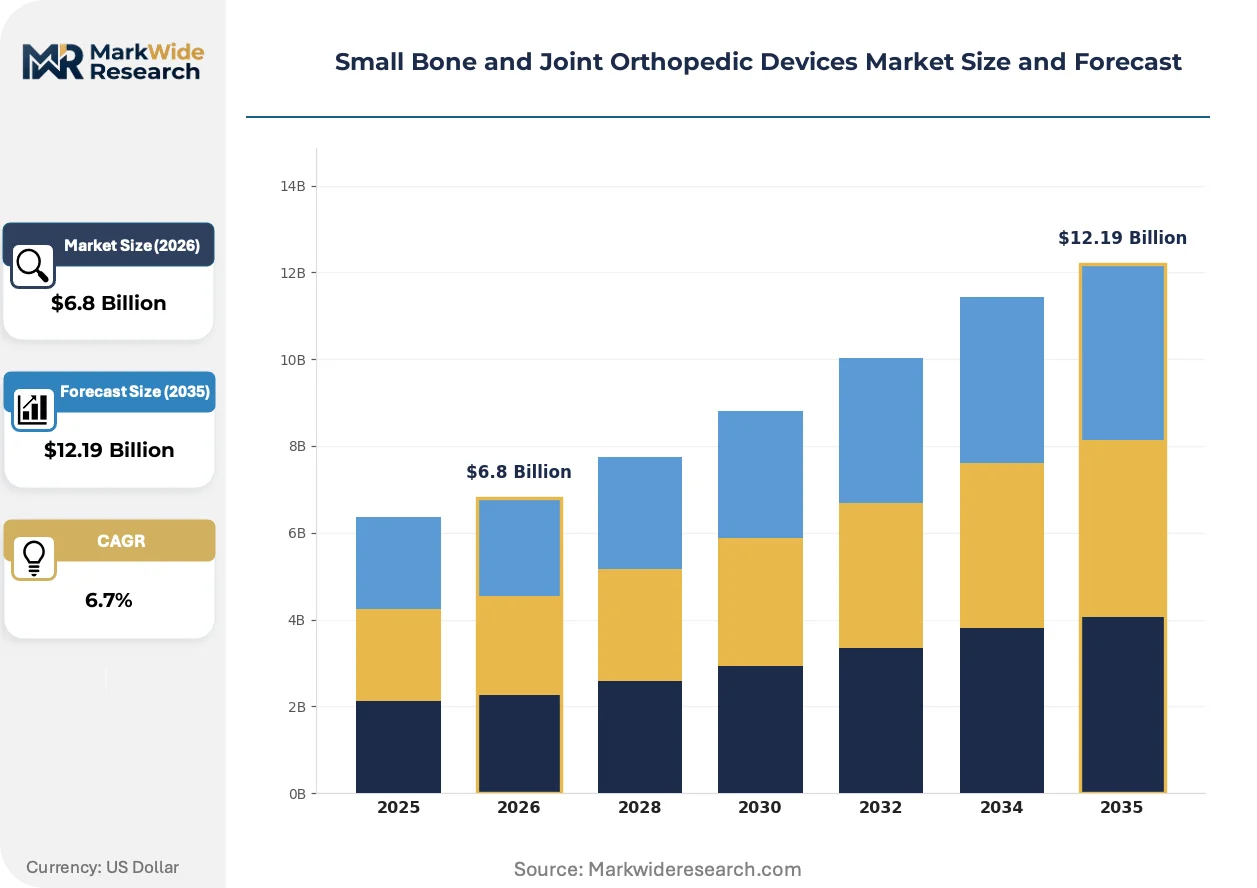
Market Dynamics
Outpatient migration from inpatient settings is compressing procedural economics and forcing device vendors to reconfigure instrumentation for ambulatory surgical centers. This structural shift demands smaller footprints, faster turnover protocols, and disposable instrument alternatives that align with same-day discharge mandates.
Growth Catalysts
- Ambulatory surgical center expansion:United States bundled payment models for joint procedures incentivize site-of-care migration, accelerating demand for compact powered instrumentation and single-use consumables.
- FDA 510(k) pathway compression:Streamlined premarket notification for 3D-printed patient-specific implants reduces time-to-market for titanium alloy fixation hardware with custom plate geometries.
- Biological graft integration:Resorbable composite scaffolds engineered for distal radius and ankle reconstructions capture procedural volume as surgeons prioritize osseous union over permanent implant retention.
Market Restraints
- Titanium alloy supply concentration:Sponge and mill product sourcing clusters in select Asian and Russian feedstock regions expose manufacturers to geopolitical input volatility and export restriction risk.
- EU MDR clinical evidence extension:Medium-risk implantable hardware now requires expanded conformity assessment documentation, lengthening commercialization timelines and inflating regulatory compliance costs.
- PEEK polymer substitution ceiling:Modulus-matched biomechanics in load-bearing small bone applications limit material substitution for titanium in high-stress fixation scenarios.
Strategic Opportunities
- Remote monitoring subscription layers:Implant maintenance telemetry services reposition vendor-hospital relationships toward recurring revenue models anchored by surgical navigation ecosystem integration.
- Japan PMDA QMS pathway optimization:Foreign manufacturers that pre-empt quality management system inspections unlock premium pricing in an underpenetrated extremities reconstruction market.
- Arthroscopy instrumentation convergence:Minimally invasive surgery platforms combining 4K visualization with powered shaver systems capture margin pools in wrist and shoulder outpatient procedures.
Industry Challenges
- Surgeon training infrastructure scaling:Cadaveric lab capacity and proctoring networks struggle to match adoption velocity for patient-specific 3D-printed implant workflows.
- Biodegradability standard uncertainty:ECHA evolving mandates on resorbable composite recycling obligations create material selection pipeline risk without clear compliance benchmarks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Small Bone and Joint Orthopedic Devices Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.19 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plates, Screws, Pins, Bone Grafts End User: Hospitals, Ambulatory Surgical Centers, Orthopedic Clinics, Outpatient Facilities Application: Fracture Repair, Joint Reconstruction, Arthroscopy, Sports Medicine Technology: Minimally Invasive Surgery, Robotics, 3D Printing, Biodegradable Implants |
| Companies Covered | Stryker, Arthrex, Inc., Zimmer Biomet, Smith+Nephew, DePuy Synthes Companies, CONMED Corporation, Acumed LLC, Wright Medical Group N.V., Flower Orthopedics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Small Bone and Joint Orthopedic Devices Market Strategic Shifts
Additive manufacturing is redrawing competitive boundaries in small bone fixation as patient-specific geometries displace standard plate inventories. This technological inflection compresses surgical planning cycles and enables anatomical matching previously unattainable with subtractive milling.
3D-printed titanium lattice structures is expanding into distal radius and ankle fracture repair applications by enabling porosity gradients that match native bone stiffness. Ambulatory surgical centers in the United States adopt these implants at accelerating velocity as bundled payment models reward reduced revision rates. The technology is expanding into custom plate geometries that eliminate contouring time in the operating room, compressing procedure duration and instrument sterilization burden.
EU MDR Article 10 clinical evaluation requirements impose expanded post-market surveillance obligations on medium-risk implantable hardware manufacturers. This regulatory friction elevates documentation costs and extends notified body review timelines for PEEK polymer and resorbable composite fixation systems. Trauma and extremities segments respond by consolidating product portfolios to focus resources on highest-volume SKUs with defensible clinical evidence packages.
After-sales service unbundling separates implant hardware from navigation system subscriptions and remote monitoring telemetry. Hospital procurement teams in Germany and France increasingly negotiate instrumentation and software maintenance as distinct line items, pressuring bundled pricing architectures. This behavioral shift concentrates in health systems with centralized value analysis committees that benchmark total cost of ownership across multi-year implant contracts.
Small Bone and Joint Orthopedic Devices Market Segmentation
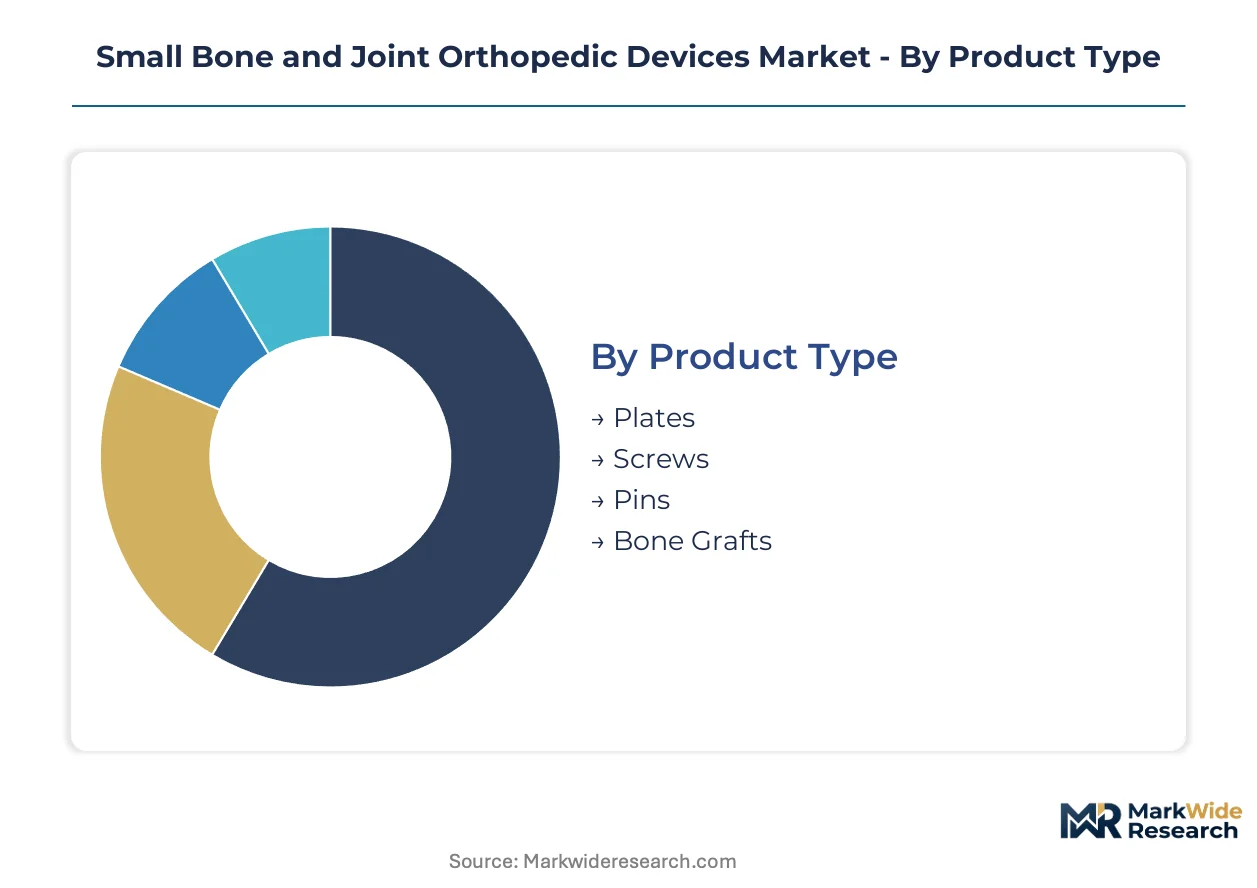
Small bone and joint orthopedic devices fragment across four intersecting dimensions that shape procurement economics. Surgeons prioritize fixation stability and anatomical fit; procurement teams weigh total cost of ownership across implant, instrumentation, and service layers.
Product Type:
Material modulus and load-bearing requirements drive selection between permanent hardware and bioresorbable alternatives.
- Plates:Titanium alloy and PEEK polymer constructs provide rigid fixation for distal radius and ankle fractures. United States ASCs favor low-profile designs that reduce soft-tissue irritation and accelerate same-day discharge protocols.
- Screws:Cortical and cancellous thread geometries achieve purchase in varying bone density. Cannulated systems dominate extremities reconstruction as surgeons demand guide-wire compatibility for percutaneous placement accuracy.
- Pins:Kirschner wires and Steinmann pins enable temporary stabilization in pediatric and geriatric trauma cases.
- Bone Grafts:Allograft and synthetic scaffolds supplement fixation in comminuted fractures with segmental bone loss.
Plates lead on scale; bone grafts lead on momentum as biological integration gains procedural preference.
End User:
Site-of-care economics reshape device form factors and sterilization protocols.
- Hospitals:Academic medical centers maintain comprehensive trauma capabilities with full instrument sets and revision hardware inventory. Bundled payment exposure concentrates orthopedic service lines around high-volume joint reconstruction procedures.
- Ambulatory Surgical Centers:Compact powered instrumentation and single-use consumables align with same-day discharge mandates. United States site-of-care migration accelerates as CMS payment differentials widen against inpatient settings.
- Orthopedic Clinics:Office-based procedures drive demand for mini-fragment fixation and local anesthesia-compatible systems.
- Outpatient Facilities:Hospital outpatient departments bridge acute trauma and scheduled reconstruction with hybrid instrumentation platforms.
Hospitals retain volume leadership; ambulatory surgical centers climb fastest as migration economics intensify.
Application:
Procedural complexity and reimbursement intensity determine hardware specification tiers.
- Fracture Repair:Trauma fixation commands highest procedural volume across distal radius, ankle, and metatarsal injuries. Titanium plate-screw constructs predominate as surgeons prioritize mechanical stability over bioresorption in load-bearing scenarios.
- Joint Reconstruction:Small joint arthroplasty in wrist and ankle demands anatomic component sizing and bearing surface durability.
- Arthroscopy:Wrist and shoulder outpatient procedures expand shaver and burr utilization in diagnostic and therapeutic interventions.
- Sports Medicine:Ligament repair and tendon reattachment procedures favor suture anchor systems with high pull-out strength.
Fracture repair dominates absolute volume; arthroscopy gains share fastest as minimally invasive techniques proliferate.
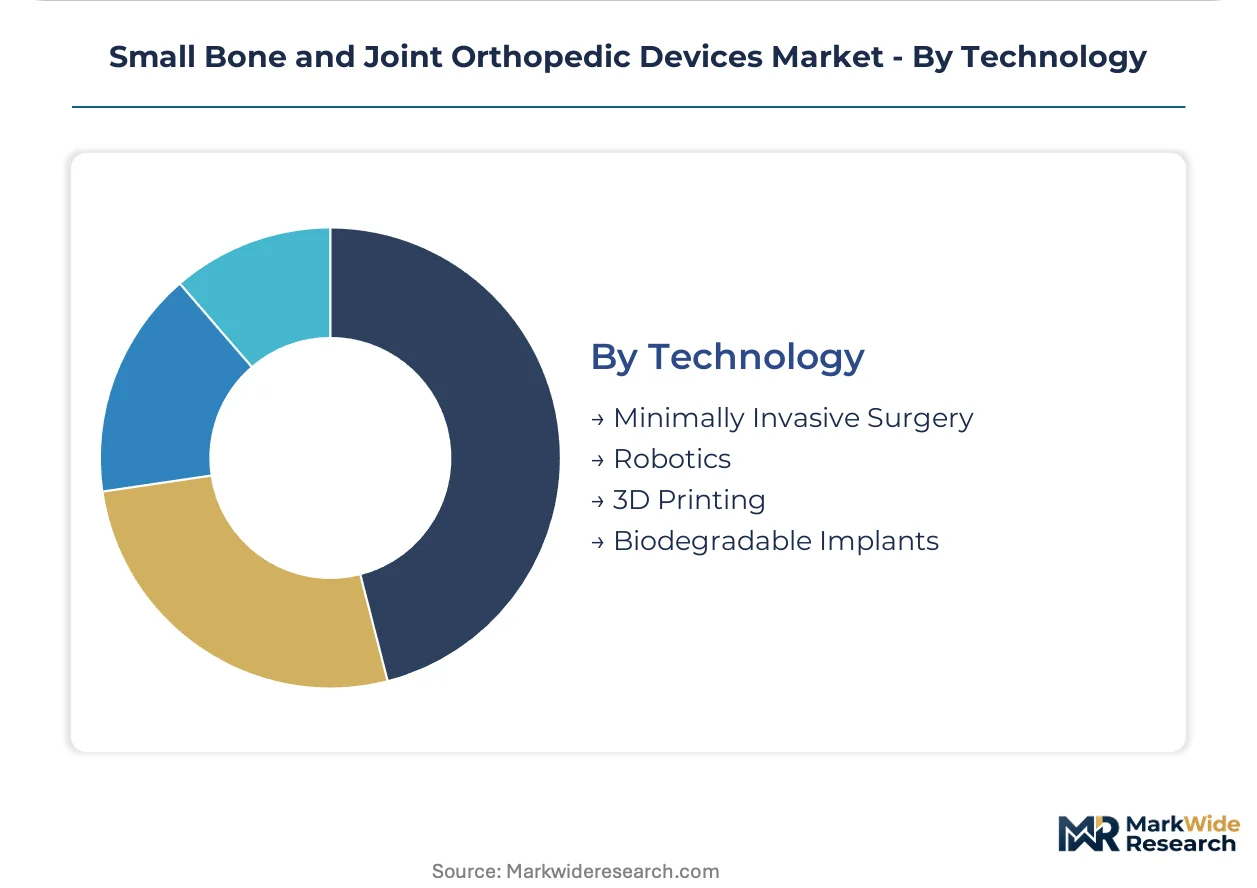
Technology:
Manufacturing modality and material science differentiate premium positioning from standard hardware.
- Minimally Invasive Surgery:Percutaneous fixation and arthroscopic approaches reduce soft-tissue disruption. Ambulatory settings demand specialized instrumentation that fits compact sterilization footprints and rapid turnover protocols.
- Robotics:Surgical navigation systems enable preoperative planning and intraoperative guidance for complex reconstructions.
- 3D Printing:Patient-specific titanium lattice structures with porosity gradients match native bone stiffness. Custom plate geometries eliminate intraoperative contouring time, compressing procedure duration.
- Biodegradable Implants:Resorbable composite scaffolds engineered from polylactic acid and polyglycolic acid copolymers eliminate secondary removal surgeries in pediatric and select adult applications.
Minimally invasive surgery anchors current revenue; 3D printing shows steepest expansion trajectory as FDA 510(k) pathways compress time-to-market for patient-specific geometries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States procurement teams negotiate implant contracts under bundled payment pressure while Germany's hospital procurement centralization accelerates price benchmarking across multi-year tenders. Japan's PMDA QMS inspections filter foreign manufacturer access, creating divergent market entry economics across these three major orthopedic device consumption centers.
United States
CMS payment differentials between inpatient and ambulatory settings accelerate site-of-care migration for wrist and ankle procedures. FDA 510(k) pathway streamlining for 3D-printed patient-specific implants compresses commercialization timelines for titanium lattice fixation systems. Warsaw, Indiana anchors domestic manufacturing concentration for trauma and extremities hardware, with regional supply chains feeding ASC networks across the Midwest and Southeast.
Germany
Hospital procurement centralization through value analysis committees benchmarks total cost of ownership across implant-instrumentation-service bundles. EU MDR Article 10 clinical evaluation requirements extend notified body review timelines for medium-risk implantable hardware. Tuttlingen in Baden-Württemberg maintains surgical instrument manufacturing density, with regional clusters specializing in arthroscopy visualization and powered shaver systems for outpatient shoulder procedures.
Japan
Aging demographics expand procedural volume for distal radius and ankle fracture fixation in geriatric trauma cases. PMDA QMS inspections impose additional compliance layers that filter market access for foreign manufacturers of titanium alloy plates and screws. Tokyo-Osaka metropolitan corridors concentrate orthopedic service line investment, with academic medical centers piloting patient-specific 3D-printed implant workflows for complex reconstructions.
Switzerland
Swissmedic conformity assessment procedures align with EU MDR standards while maintaining distinct post-market surveillance obligations for resorbable composite scaffolds. Premium pricing tolerance in private hospital segments supports adoption of biological graft integration technologies. Basel-Zurich corridor concentrates medtech R&D infrastructure, with regional innovation clusters advancing biodegradable implant material science for pediatric applications.
China
Volume-based procurement (VBP) tenders for orthopedic implants compress pricing for standard titanium plate-screw constructs in public hospital segments. NMPA regulatory harmonization efforts accelerate review timelines for domestically manufactured trauma fixation systems. Suzhou and Changzhou industrial parks concentrate contract manufacturing capacity for international OEMs, with regional supply chains scaling production of cannulated screw systems for extremities reconstruction.
Small Bone and Joint Orthopedic Devices Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated device vendors commanding premium positioning in arthroscopy and surgical navigation while component fabricators supply private-label trauma hardware. Market structure concentrates around three to five dominant integrated players with comprehensive extremities portfolios, flanked by mid-scale specialists in arthroscopy instrumentation and biological graft technologies. Two strategic archetypes define competitive positioning: ecosystem vendors bundling implants with navigation and remote monitoring subscriptions, and manufacturing-scale competitors sustaining broad SKU coverage across trauma segments. M&A activity targets arthroscopy platform consolidation and 3D-printing capability acquisition, while geographic expansion focuses on Japan QMS certification and China VBP tender participation.
Among United States-based integrated device vendors, Stryker occupies a position exemplifying the ecosystem archetype through surgical navigation and recurring service revenue models. Arthrex, Inc. represents the specialized instrumentation tier, anchoring competitive stance through arthroscopy platform concentration and surgeon training infrastructure investment. Zimmer Biomet sits within the manufacturing-scale archetype, sustaining broad portfolio coverage across trauma and extremities segments through production volume and distribution reach.
| Leading Market Players |
|---|
| Stryker |
| Arthrex, Inc. |
| Zimmer Biomet |
| Smith+Nephew |
| DePuy Synthes Companies |
| CONMED Corporation |
| Acumed LLC |
| Wright Medical Group N.V. |
| Flower Orthopedics |
| Others |
Value Chain & Pricing Dynamics
Backward integration into titanium sponge processing anchors supply position and pricing power for trauma hardware manufacturers confronting volatile Asian feedstock markets. Captive mill product capacity insulates integrated vendors from Russian export restriction exposure while enabling premium positioning for patient-specific 3D-printed constructs in United States ASC procurement cycles.
Pricing Analysis
Capacity additions in China are reshaping price floors for standard titanium plate-screw constructs as NMPA regulatory harmonization accelerates domestic manufacturing scale. Three-tier pricing structure across premium patient-specific, standard anatomical, and economy generic levels differentiates by FDA 510(k) clearance status and surgeon training bundling. Cost compression in economy tiers intensifies as volume-based procurement tenders in public hospital segments force margin contraction. ASC procurement committees exhibit highest price sensitivity; academic medical centers with bundled payment exposure prioritize total cost of ownership over per-unit implant cost.
Supply Chain Analysis
Freight cost volatility from Asian titanium sponge clusters to Warsaw, Indiana manufacturing centers compresses margin buffers for trauma hardware distributors serving Midwest ASC networks. Supply concentrates in China, Japan, and Russia for titanium mill products, with PEEK polymer resin sourcing anchored in German and Belgian chemical processing hubs. Raw material dependencies span titanium sponge, cobalt-chrome alloys, and polylactic acid copolymers for resorbable scaffolds. Single-source vulnerability in electron beam melting powder for additive manufacturing threatens 3D-printed implant production continuity. Distribution runs through GPO contracts for hospital systems and direct-to-ASC consignment inventory for outpatient migration volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU MDR Article 10 clinical evidence extensions and FDA 510(k) pathway streamlining simultaneously elevate compliance costs for incumbents and compress barriers for 3D-printing entrants, restructuring competitive returns across the forecast horizon.
For Market Incumbents: Deepen surgical navigation ecosystem lock-in through remote monitoring subscription layers that reposition hospital relationships toward recurring revenue models. Anchor defensive positioning against 3D-printing specialists by accelerating patient-specific implant portfolio expansion before FDA 510(k) pathway compression erodes first-mover advantages. Prioritize Japan PMDA QMS certification investment to capture premium pricing in geriatric trauma fixation demand. For New Entrants and Emerging Players: Ambulatory surgical center procurement committees represent the most penetrable buyer archetype as site-of-care migration outpaces incumbent reconfiguration velocity for compact instrumentation footprints. Target United States Midwest and Southeast ASC networks with disposable instrument alternatives and rapid-turnover sterilization protocols. Pursue 3D-printing capability acquisition as primary go-to-market angle, leveraging compressed FDA timelines for patient-specific geometries against legacy subtractive manufacturing incumbents. For Investors and Strategic Acquirers: Roll-up economics work for arthroscopy platform consolidation because minimally invasive surgery convergence creates defensible revenue streams through shaver-burr system recurring consumables and surgeon training infrastructure lock-in. Long-term viability centers on ecosystem vendors with navigation-implant-telemetry integration rather than standalone hardware manufacturers facing commoditization pressure. Target acquisition archetype: mid-scale 3D-printing specialists with FDA-cleared titanium lattice structures and established ASC distribution relationships. Signal to watch: PMDA QMS inspection clearance velocity for foreign manufacturers as predictor of Japan market access premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| 3D-Printing Capability Acquisition | Patient-specific titanium lattice structures capture ASC margin pools through reduced revision rates. |
| FDA 510(k) Pathway Optimization | Streamlined premarket notification compresses time-to-market for custom plate geometries. |
| Japan PMDA QMS Certification | Quality management system clearance unlocks premium pricing in underpenetrated extremities reconstruction market. |
| Remote Monitoring Subscription Launch | Implant maintenance telemetry services reposition vendor-hospital relationships toward recurring revenue models. |
| Arthroscopy Platform Integration | 4K visualization with powered shaver systems captures margin pools in wrist and shoulder outpatient procedures. |
Study Parameters
Coverage spans United States, Germany, Japan, Switzerland, and China, with primary inputs from each market cluster combining executive interviews with orthopedic device manufacturers and secondary validation through regulatory filings. Conversations engaged trauma product managers, ASC procurement directors, biomedical engineers, GPO contracts managers, and PMDA regulatory consultants. Secondary sources encompass FDA 510(k) databases, EU MDR notified body documentation, CMS Medicare payment data, hospital procurement contracts, and titanium sponge trade statistics. Bottom-up implant volume modeling triangulated against top-down market sizing from manufacturer revenue disclosures.
Rate-of-change decomposition across volume and value dimensions anchored forecast construction throughout the projection horizon. Segmentation modeling spanned product type, end user, application, and technology dimensions including 3D-printing adoption velocity and minimally invasive surgery penetration curves. CAGRs derived from procedure volume growth rates, price trajectory assumptions by tier, and mix shift toward patient-specific constructs. Industry-specific inputs incorporated ASC site-of-care migration velocity, EU MDR compliance cost pass-through estimates, and PEEK polymer substitution ceiling constraints in load-bearing applications.
Inputs from PMDA regulatory consultants and ASC procurement directors were available through the study window; gaps in real-time 3D-printing implant utilization data introduce uncertainty bands around patient-specific geometry adoption curves. Forecasts reflect assumptions regarding FDA pathway streamlining continuity and EU MDR notified body capacity expansion. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
India Orthopedic Braces and Supports Market
Orthopedic Devices
Medical Traction Devices Market
Orthopedic Devices
Global Joint Replacement Market
Orthopedic Devices
Spine Surgery Devices Market
Orthopedic Devices
Patients Repositioning and Offloading Device Market
Orthopedic Devices
Europe Knee Cartilage Repair Market
Orthopedic Devices
US Tendon Repair Market
Orthopedic Devices
Limb Salvage Systems Market
Orthopedic Devices
Hip Resurfacing Implants Market
Orthopedic Devices
Global Animal Ortho-Prosthetics Market
Orthopedic Devices
Orthopedic Devices Market
Orthopedic Devices
Veterinary Orthopedic Injectable Drug Market
Orthopedic Devices
Spinal Devices Market
Orthopedic Devices
Global Orthopedic Navigation Systems Market
Orthopedic Devices
South Korea Spinal Surgery Devices Market
Orthopedic Devices
Orthopedic Consumables Market