
 Electronic Nasal Spray Devices Market | 2026-2036
Electronic Nasal Spray Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Nasal Spray Devices Market Foresight
Asset-light leasing models for connected inhalation platforms is reconfiguring competitive entry barriers, allowing mid-tier firms to access precision dosing technology without capital-intensive manufacturing commitments. AptarGroup leverages its decades of aerosol engineering heritage to sustain leadership in metered-dose mechanisms. Johnson & Johnson Services, Inc. anchors its position through deep integration with consumer health distribution networks. Teva Pharmaceutical Industries Ltd. competes by specializing in generic-compatible device architectures that reduce patient switching costs.
Electronic nasal spray devices combine electrically actuated pump mechanisms with microprocessor-controlled dosing algorithms to deliver precise medication volumes through the nasal mucosa, typically achieving particle size distributions of 10-50 microns optimized for turbinate deposition. These systems serve primarily to improve bioavailability and reduce variability in intranasal drug delivery for chronic and acute therapies. Automatic devices command premium positioning due to their programmability and adherence-tracking capabilities, while portable formats represent the fastest-expanding segment as patients prioritize discretion and travel compatibility. The electrically actuated technology dimension attracts the most development capital, though pump-based systems still dominate installed base volumes across hospital formularies.
FDA 21 CFR Part 820 quality system requirements and EU MDR Class IIa device classifications impose substantial validation burdens on manufacturers seeking dual-market access. The EPA also regulates propellant chemistries under significant new alternatives policy frameworks, constraining formulation choices for aerosol variants. Stakeholders must monitor evolving reimbursement codes for connected drug-device combinations across Medicare, NHS England, and Japan's MHLW to anticipate which technology tiers will achieve sustainable commercial traction.
Market Dynamics
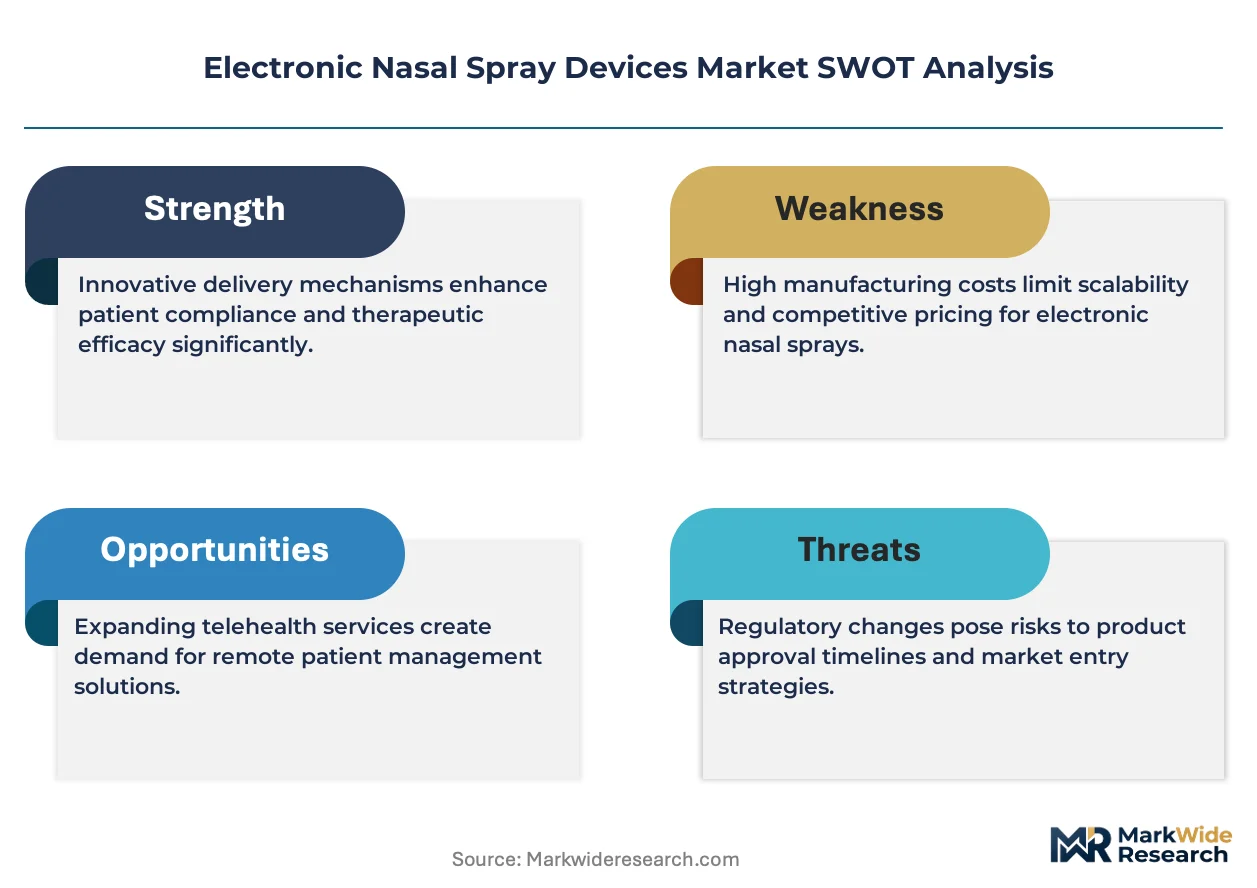
Connected drug-device combination regulations from FDA and EMA are compressing development timelines and forcing manufacturers to front-load quality validation investments before commercial launch. This regulatory ratcheting is concentrating development resources among firms with established aerosol engineering capabilities and existing predicate device portfolios.
Growth Catalysts
- Chronic rhinitis self-administration:Home care patients seek metered-dose precision without clinical supervision, expanding addressable populations beyond hospital formularies.
- EU MDR Class IIa device pathways:Harmonized conformity assessment procedures reduce redundant testing for manufacturers pursuing dual US-EU market access.
- Aging demographics in Japan and Germany:Turbinate deposition therapies attract reimbursement priority as nasal delivery avoids first-pass hepatic metabolism in polypharmacy patients.
Market Restraints
- EPA Significant New Alternatives Policy constraints:Propellant chemistry restrictions limit hydrofluoroalkane formulation options and extend reformulation cycles.
- Microprocessor and sensor supply concentration:Precision dosing algorithms depend on semiconductor inputs vulnerable to foundry capacity allocation in East Asian manufacturing clusters.
- Bioavailability ceiling for large molecules:Nasal mucosa permeability barriers prevent protein therapeutic delivery above 10-20 kDa molecular weight thresholds.
Strategic Opportunities
- Pediatric and geriatric underpenetration:Manual actuation force requirements exclude these populations from existing device architectures in the United States.
- Adherence telemetry integration:Bluetooth-enabled dose counters and smartphone connectivity create service revenue streams beyond hardware margins.
- Japan MHLW reimbursement code expansion:Connected device premium pricing pathways are under review for chronic rhinitis maintenance therapy categories.
Industry Challenges
- Cross-functional talent scarcity:Device engineers with simultaneous aerosol physics and embedded systems firmware expertise command premium compensation and extend hiring cycles.
- Predicate device 510(k) pathway erosion:FDA is narrowing substantial equivalence determinations for electronic actuation mechanisms versus mechanical pump references.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Nasal Spray Devices Market |
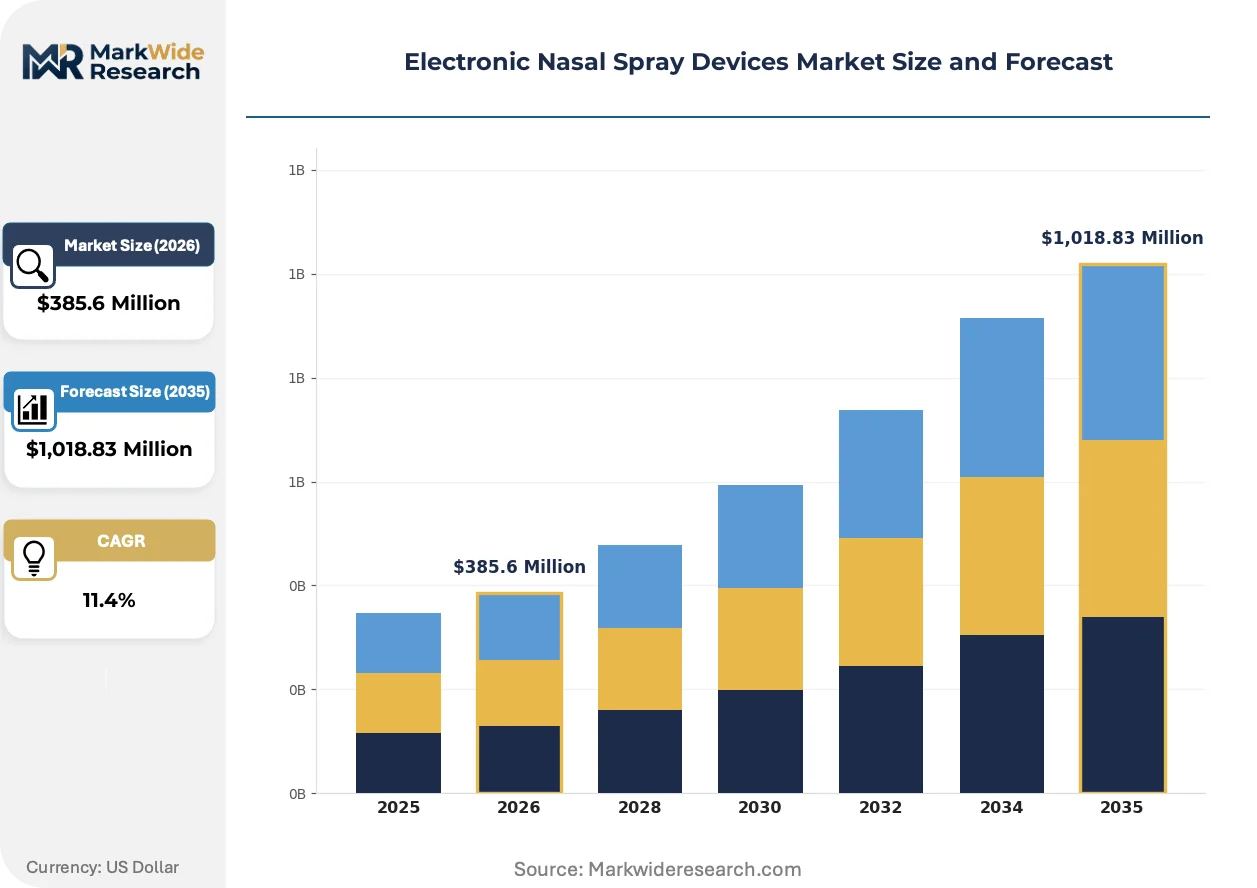
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,018.83 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Semi-Automatic, Automatic, Portable End User: Hospitals, Clinics, Home Care, Pharmacies Application: Allergic Rhinitis, Asthma, Migraine, Hormonal Therapies Technology: Aerosol, Pump, Osmotic, Electrically Actuated |
| Companies Covered | AptarGroup, Inc., GlaxoSmithKline plc, Johnson & Johnson Services, Inc., Merck & Co., Inc., AstraZeneca plc, Bayer AG, Novartis AG, Becton, Dickinson and Company, Teva Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Nasal Spray Devices Market Shifts & Advancements
Electromechanical actuation is displacing mechanical pump architectures across premium device tiers, while regulatory data requirements for connected systems are reshaping competitive moats around quality management maturity rather than patent position alone.
Soft-mist piezoelectric atomization is rendering obsolete conventional pump-based mechanical actuation in precision dosing segments. Allergic rhinitis patients with variable inspiratory flow rates are adopting these systems at accelerating rates in German and Japanese reimbursement markets. The technology is compressing dose variability coefficients from 25% to under 8%, rendering obsolete legacy mechanical systems for maintenance therapy indications.
REACH Annex XVII restrictions on persistent organic pollutants are extending substance scrutiny to device lubricants and elastomer seals. Manufacturers must reformulate wetted components or secure supply continuity exemptions, adding 12-18 months to design history file compilation. Automatic device categories with extensive polymer portfolios face the heaviest testing burden and are consolidating supplier bases to pre-validated material streams.
Patients are unbundling device acquisition from pharmaceutical procurement, seeking hardware-agnostic platforms compatible with multiple drug cartridges. Direct-to-consumer channels and specialty pharmacy networks are capturing this preference shift, displacing traditional hospital formulary gatekeepers in the United States. Chronic rhinitis patients in Medicare Part D plans exhibit the strongest channel migration toward mail-order device fulfillment with remote therapeutic monitoring integration.
Electronic Nasal Spray Devices Market Segmentation
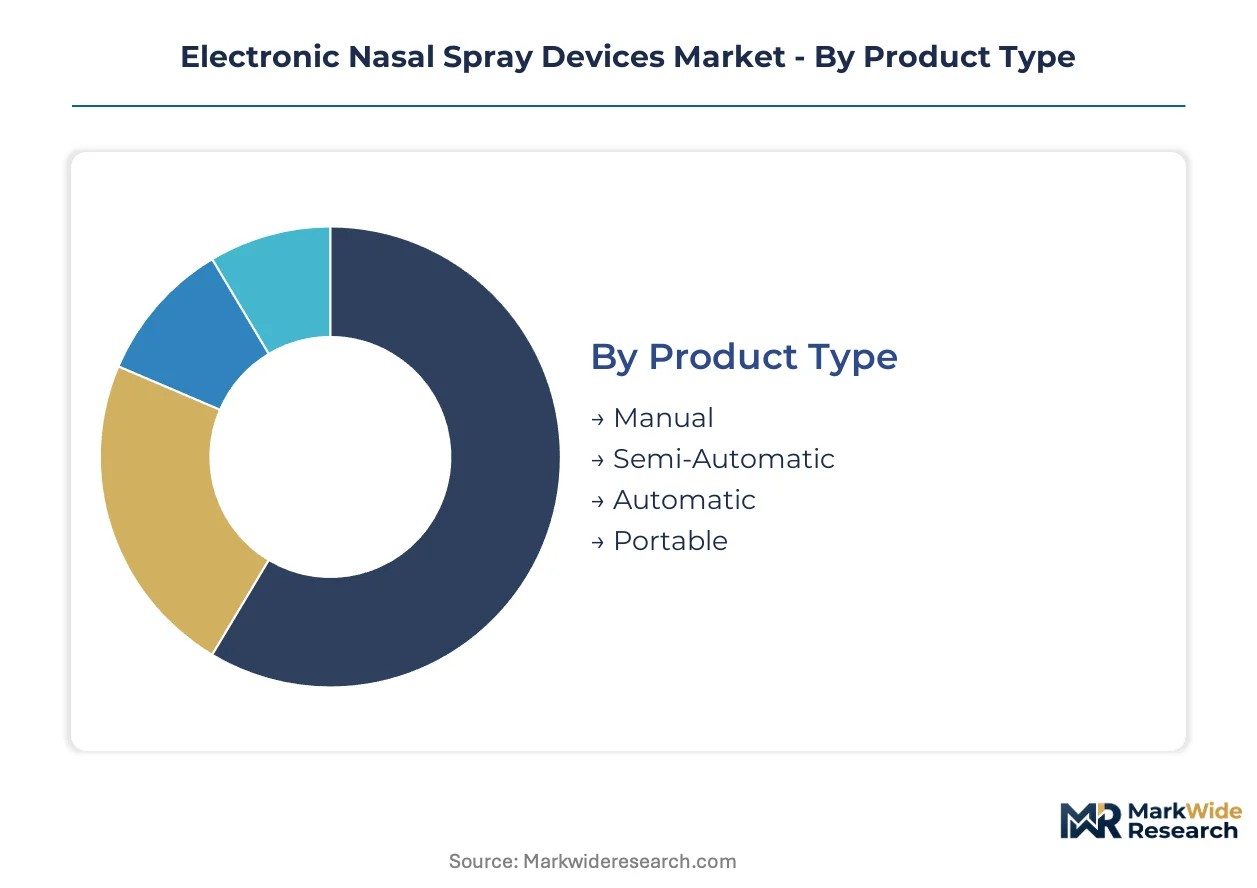
Electronic nasal spray devices fragment across four distinct category axes, each governing procurement decisions and reimbursement pathways differently. Product type and technology dimensions determine manufacturing complexity and regulatory classification, while end-user and application segments dictate channel strategy and pricing architecture.
Product Type:
Mature mechanical formats coexist with emerging electromechanical platforms, creating tiered market access points.
- Automatic:Microprocessor-controlled dosing algorithms achieve particle size distributions of 10-50 microns for turbinate deposition. Premium positioning in United States Medicare Part D plans reflects programmability and adherence-tracking capabilities that justify higher reimbursement tiers.
- Portable:Battery-optimized form factors prioritize discretion and travel compatibility. German and Japanese chronic rhinitis patients are migrating toward these formats fastest as self-administration replaces clinic-based therapy.
- Manual:Spring-actuated mechanisms dominate hospital formulary volumes due to lower per-unit acquisition costs and minimal training requirements.
- Semi-Automatic:Hybrid architectures combine mechanical priming with electronic dose verification, occupying mid-tier positioning in European pharmacy channels.
Automatic devices handle the majority of throughput; Portable is the fastest mover on share.
End User:
Channel concentration shapes margin structure, with institutional procurement favoring volume contracts and direct-to-consumer routes capturing service revenue.
- Home Care:Self-administered therapy platforms with remote monitoring integration. United States chronic rhinitis patients in Medicare Advantage plans drive fastest adoption as reimbursement codes expand for connected drug-device combinations.
- Hospitals:Acute care formularies prioritize predicate device familiarity and 510(k) clearance velocity over feature sophistication.
- Clinics:Specialist ENT practices in Germany and Japan source precision-dosing units for allergen immunotherapy protocols.
- Pharmacies:Retail dispensing networks capture hardware-agnostic platform demand as patients unbundle device acquisition from pharmaceutical procurement.
Home Care commands expanding margin pools; Pharmacies are climbing the fastest on patient channel migration.
Application:
Therapeutic indication determines particle engineering specifications and bioavailability targets.
- Allergic Rhinitis:Seasonal and perennial maintenance therapy with soft-mist piezoelectric atomization compressing dose variability coefficients below 8%. German reimbursement markets show strongest uptake as patients abandon legacy mechanical pumps.
- Asthma:Adjunctive nasal corticosteroid delivery requiring coordination with bronchodilator regimens.
- Migraine:Acute triptan formulations demanding rapid mucosal absorption profiles.
- Hormonal Therapies:Peptide and protein formulations constrained by nasal mucosa permeability barriers above 10-20 kDa molecular weight thresholds.
Allergic Rhinitis anchors installed base volumes; Hormonal Therapies face steepest expansion trajectory pending permeability breakthroughs.
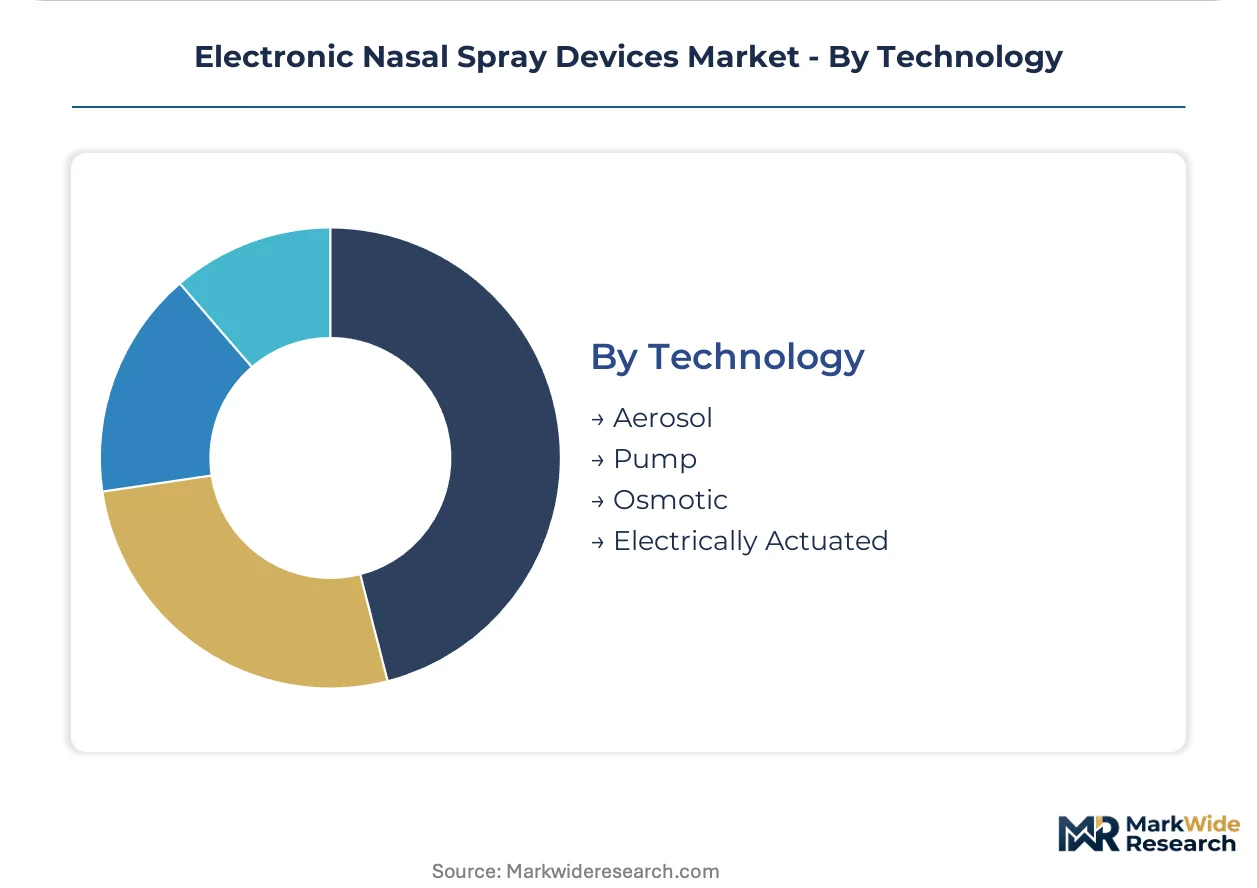
Technology:
Actuation mechanism selection determines regulatory pathway complexity and supply chain vulnerability.
- Electrically Actuated:Piezoelectric and solenoid-driven systems attracting majority of development capital despite semiconductor supply concentration risks in East Asian foundries.
- Pump:Mechanical displacement architectures still dominating hospital formulary volumes across United States, Germany, and Japan.
- Aerosol:Pressurized metered-dose systems facing EPA Significant New Alternatives Policy constraints on hydrofluoroalkane propellant chemistries.
- Osmotic:Membrane-controlled release mechanisms for sustained delivery profiles in hormonal therapy applications.
Pump technology retains majority installed base; Electrically Actuated is gaining share fastest on precision dosing premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains a substantial trade surplus in precision drug-delivery hardware, exporting electromechanical actuation systems to German and Japanese pharmaceutical assemblers while importing specialized piezoelectric components from East Asian foundries.
United States
Medicare Part D reimbursement expansion for connected drug-device combinations is accelerating home care procurement of automatic nasal spray platforms. FDA 21 CFR Part 820 quality system requirements impose validation burdens that favor established predicate device holders. The Minneapolis-St. Paul medical device corridor concentrates aerosol engineering talent and contract manufacturing capacity for metered-dose mechanisms.
Germany
Chronic rhinitis patients in statutory health insurance schemes are migrating from mechanical pumps to soft-mist piezoelectric systems at accelerating rates. EU MDR Class IIa device classifications harmonize conformity assessment with FDA pathways for dual-market manufacturers. The Baden-Württemberg precision engineering cluster around Stuttgart supplies microprocessor-controlled dosing subassemblies to European device integrators.
Japan
Aging demographics and polypharmacy prevalence position turbinate deposition therapies for MHLW reimbursement priority as hepatic metabolism avoidance gains clinical traction. PMDA consultation procedures for combination products compress pre-market review timelines for firms with QMS certification. The Kansai region around Osaka hosts specialized elastomer seal manufacturers serving osmotic release device architectures.
United Kingdom
NHS England reimbursement code evolution for remote therapeutic monitoring is creating premium pricing pathways for Bluetooth-enabled adherence trackers. MHRA post-Brexit recognition agreements with FDA and EMA preserve market access continuity for dual-registered manufacturers. The Cambridge life sciences cluster incubates firmware development for embedded dose-counting algorithms.
Switzerland
Swissmedic's streamlined Class IIa review procedures attract development-stage firms seeking rapid European market entry for electromechanical platforms. Bilateral mutual recognition agreements with EU MDR reduce redundant technical documentation for Basel-area pharmaceutical-device alliances. The Zurich precision components sector supplies piezoelectric actuators to nasal spray device assemblers.
Electronic Nasal Spray Devices Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability tiers: aerosol engineering heritage firms, pharmaceutical-device integrators, and generic-compatible platform specialists. Tier-one players command predicate device portfolios that accelerate 510(k) clearance velocity. Tier-two entrants leverage asset-light leasing models to access precision dosing technology without capital-intensive manufacturing commitments. Dominant competitive moves include strategic partnerships between semiconductor foundries and device firmware developers, plus portfolio diversification into adherence telemetry services.
Within the pharmaceutical-device integration tier, Johnson & Johnson Services, Inc. and GlaxoSmithKline plc exemplify archetypes combining consumer health distribution networks with in-house aerosol engineering capabilities. Teva Pharmaceutical Industries Ltd. occupies a position representing generic-compatible platform specialization that reduces patient switching costs. These three anchors illustrate how regulatory data requirements for connected systems are reshaping competitive moats around quality management maturity rather than manufacturing scale alone.
| Leading Market Players |
|---|
| AptarGroup, Inc. |
| GlaxoSmithKline plc |
| Johnson & Johnson Services, Inc. |
| Merck & Co., Inc. |
| AstraZeneca plc |
| Bayer AG |
| Novartis AG |
| Becton, Dickinson and Company |
| Teva Pharmaceutical Industries Ltd. |
| Others |
Supply & Pricing Matrix
East Asian semiconductor foundry concentration for piezoelectric actuators and dosing microprocessors funnels margin capture toward device assemblers with captive firmware development capabilities, while contract manufacturers without embedded systems expertise face persistent cost pass-through vulnerability.
Pricing Analysis
Hospital procurement committees anchor transactional per-unit pricing for mechanical pump devices, while home care channels command subscription-tier structures bundling hardware with adherence telemetry services. Three-tier pricing structure across premium automatic, standard semi-automatic, and economy manual levels separates FDA-cleared connected platforms from predicate device alternatives. Pricing pressure stems from Medicare Part D reimbursement compression on non-connected formats, with chronic rhinitis patients in commercial insurance plans exhibiting lowest price sensitivity due to co-pay insulation.
Supply Chain Analysis
Piezoelectric ceramic feedstock draws from Japanese and German precision materials suppliers, while semiconductor dosing controllers hinge on Taiwanese and South Korean foundry output. Elastomer seal compounds and hydrofluoroalkane propellants face EPA Significant New Alternatives Policy restriction risk extending lead times. Distribution runs through specialty pharmacy networks and hospital GPO contracts, with direct-to-consumer channels capturing fastest share expansion among Medicare Advantage enrollees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardware-agnostic platform economics are displacing closed drug-device bundles as chronic rhinitis patients unbundle procurement decisions, creating interoperability premiums for firmware-agnostic device architectures compatible with multiple pharmaceutical cartridges.
For Market Incumbents: Entrench predicate device portfolios through backward integration into piezoelectric actuator supply, securing allocation priority at East Asian foundries. Deepen QMS certification investment to accelerate FDA 510(k) clearance velocity against narrowing substantial equivalence pathways. Anchor hospital formulary position through GPO contract extensions before pharmacy channel migration accelerates. For New Entrants and Emerging Players: Pursue pediatric and geriatric actuation-force gaps in United States home care, where manual device architectures exclude these populations. Target Bluetooth-enabled adherence telemetry as a service revenue layer atop hardware margins, capturing Medicare Advantage remote monitoring reimbursement expansion. Leverage asset-light leasing models to access precision dosing technology without capital-intensive manufacturing commitments. For Investors and Strategic Acquirers: Capital is best deployed toward firmware-agnostic platform specialists with validated dosing algorithms and existing predicate device clearances, positioned for pharmaceutical partnership layering. Long-term viability favors firms bridging aerosol physics and embedded systems expertise as regulatory data requirements intensify. Watch FDA guidance evolution on connected drug-device combination validation as the inflection signal for quality management maturity premiums.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission for Connected Device | Accelerates Medicare Part D reimbursement tier access for automatic platforms with adherence tracking. |
| CE Marking Pathway under EU MDR | Harmonizes conformity assessment with FDA 21 CFR Part 820 for dual-market manufacturers. |
| Hospital System Partnership | Secures formulary placement before pharmacy channel migration displaces institutional procurement. |
| Software Companion Development | Enables Bluetooth dose counter integration and smartphone adherence telemetry revenue streams. |
| Reimbursement Strategy | Positions connected platforms for Japan MHLW premium pricing pathway expansion in chronic rhinitis categories. |
Research Methodology
Operator-level perspectives from biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists anchored the qualitative base, triangulated against FDA 510(k) filings, EMA device registration databases, CMS Medicare reimbursement code updates, and hospital procurement transaction records. Bottom-up device shipment estimates and top-down pharmaceutical partnership valuations were cross-validated.
Scenario-bracketing around semiconductor supply disruption and EPA propellant chemistry restrictions framed the analytical approach across the analysis window, with segmentation modeling across product type, technology actuation mechanism, end-user channel, and therapeutic application dimensions. CAGRs were derived from installed base replacement cycles and reimbursement code expansion trajectories, incorporating chronic rhinitis prevalence projections and polypharmacy demographic shifts as demand-side inputs.
Sensitivities concentrate around FDA substantial equivalence pathway narrowing and East Asian foundry capacity allocation volatility. Forecasts reflect assumptions on connected device reimbursement code stability and EU MDR Class IIa review timeline continuity. Cross-checking against Medicare Part D formulary placement data and Japan MHLW pricing survey releases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Hospital and Pre-Hospital External Defibrillator Market
Medical Devices
Aesthetic Devices Market
Medical Devices
Spherical IOL Market
Medical Devices
Asia-Pacific Refractive Surgery Devices Market
Medical Devices
Image-Based Cytometer Market
Medical Devices
Human Enhancement Market
Medical Devices
Capsular Tension Rings Market
Medical Devices
Blood Irradiator Device Market
Medical Devices
Capsule Endoscope Systems Market
Medical Devices
Russia Viscosupplementation Market
Medical Devices
Global Amniocentesis Needle Market
Medical Devices
Multi-Channel Infusion Pumps Market
Medical Devices
External Nasal Dilator Market
Medical Devices
India Anesthesia Devices Market
Medical Devices
Leadless Cardiac Pacemaker Market
Medical Devices
Endoscope Procedure Kits Market