
 Heel Pressure Injury Relieving Devices Market | 2026-2036
Heel Pressure Injury Relieving Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Heel Pressure Injury Relieving Devices Market Foresight
Long-term care facilities is consolidating as the dominant end-use vertical, overtaking acute hospital settings as the primary volume channel for heel pressure injury relieving devices. Stryker leverages its integrated hospital-to-home care portfolio to sustain channel dominance across both institutional and post-acute segments. EHOB specializes in air-filled suspension technology, occupying a defensible niche in bariatric and high-risk patient categories. Mölnlycke Health Care anchors European procurement flows through its established wound care distribution infrastructure.
Heel pressure injury relieving devices are engineered support surfaces designed to redistribute plantar pressure, maintain neutral ankle positioning, and eliminate friction-shear forces at the calcaneal prominence through materials such as viscoelastic foam, silicone elastomers, or alternating air-cell matrices. Their primary commercial purpose is to prevent Stage I-IV pressure ulcers in immobilized patients, thereby reducing costly hospital-acquired condition penalties and litigation exposure. Foam-based heel protectors dominate current volume due to cost accessibility, while dynamic support systems incorporating pressure mapping sensors command the fastest expansion trajectory as facilities pursue real-time skin integrity monitoring. Gel pad configurations sit at the premium tier, capturing concentrated margin pools in operating room and intensive care applications where thermoregulation and biocompatibility standards are most stringent.
The US FDA classifies heel offloading devices as Class I or II medical devices depending on therapeutic claims, while CMS hospital-acquired condition reduction programs directly tie reimbursement to pressure ulcer incidence metrics. The EU Medical Device Regulation imposes strengthened clinical evidence requirements and post-market surveillance obligations that filter lower-capability suppliers from European distribution channels. Japan's PMDA maintains distinct material biocompatibility testing protocols that create incremental compliance costs for foreign entrants. Stakeholders must monitor how evolving digital health integration requirements reshape competitive positioning between passive cushioning and sensor-enabled responsive systems.
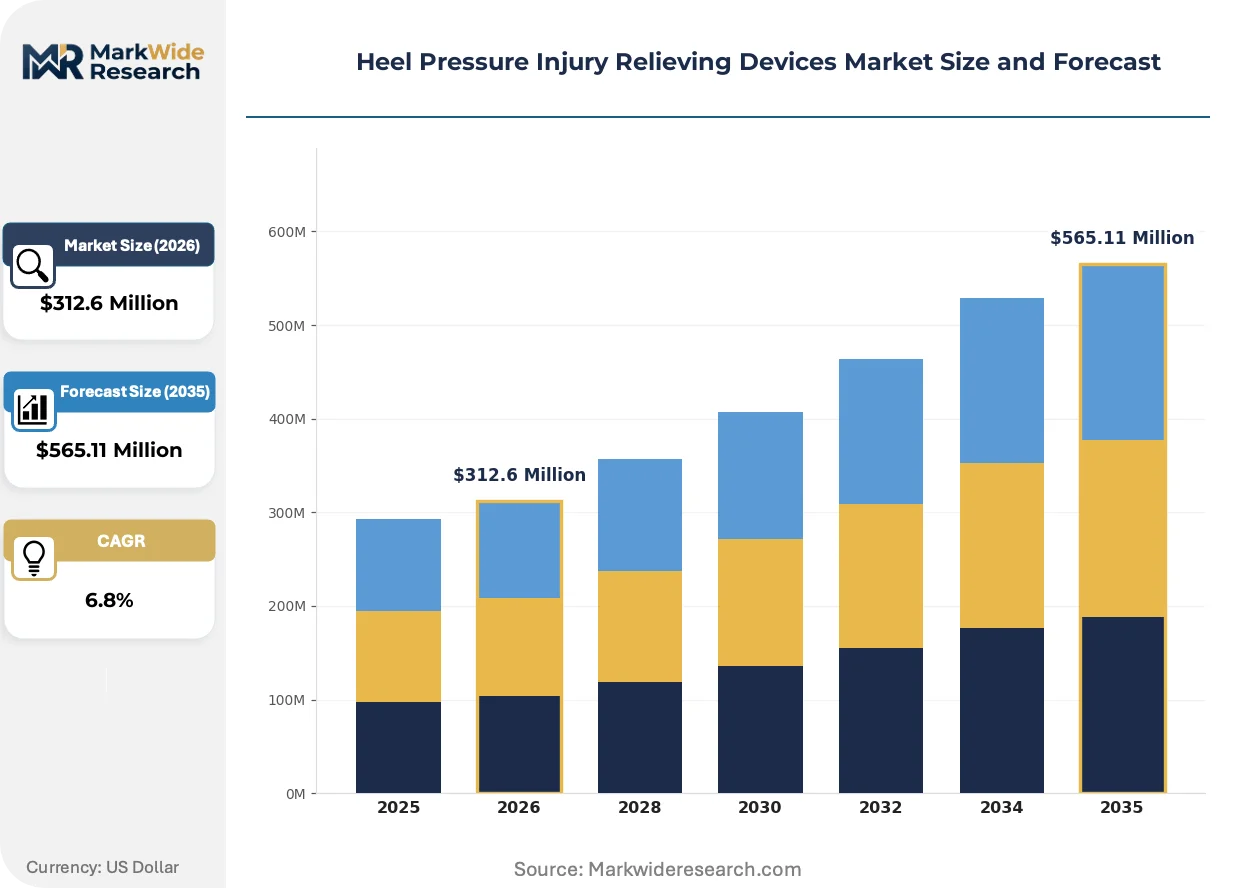
Market Dynamics
CMS hospital-acquired condition penalties are compressing reimbursement margins for pressure ulcer incidents, forcing acute-care networks to standardize heel offloading protocols across every admission pathway and post-acute handoff.
Growth Catalysts
- MDR clinical evidence mandates:The EU Medical Device Regulation is filtering marginal suppliers from European distribution, concentrating procurement among validated manufacturers with post-market surveillance infrastructure.
- Long-term care consolidation:Skilled nursing facilities are centralizing purchasing decisions under corporate infection prevention protocols that mandate heel suspension devices for immobility-risk patients.
- Silicone elastomer advances:Thermoregulating gel formulations are expanding device applicability into operating room environments where tissue perfusion monitoring intersects with offloading requirements.
Market Restraints
- Medical-grade foam input volatility:Petrochemical feedstock fluctuations compress margin stability for viscoelastic foam manufacturers serving cost-sensitive procurement tiers.
- Single-source sensor component concentration:Pressure-mapping microelectronics production concentrates in East Asian foundries, exposing device assemblers to geopolitical supply disruption.
- Static cushioning substitution ceiling:Low-cost foam wedges retain share in budget-constrained home care settings despite inferior pressure redistribution performance.
Strategic Opportunities
- Japan's PMDA biocompatibility pathway:Foreign entrants mastering distinct material testing protocols capture premium positioning in an aging acute-care market with limited domestic competition.
- Home health agency channel expansion:Post-acute discharge planners are embedding heel protectors into durable medical equipment bundles, creating recurring revenue streams outside institutional procurement.
- FDA digital health integration guidance:Real-time skin integrity monitoring systems qualify for streamlined premarket review, accelerating sensor-enabled responsive device commercialization.
Industry Challenges
- Clinical evidence generation timelines:Pressure ulcer prevention trials require extended patient monitoring periods that delay regulatory submissions and compress competitive windows.
- Legacy EHR interoperability friction:Sensor-enabled devices face integration complexity with entrenched electronic health record architectures that resist real-time biophysical data ingestion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heel Pressure Injury Relieving Devices Market |
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $565.11 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heel Cushions, Heel Protectors, Wedge Cushions, Gel Pads End User: Hospitals, Home Care Settings, Rehabilitation Centers, Long-Term Care Facilities Material: Foam, Silicone, Gel, Air-filled Technology: Pressure Mapping, Dynamic Support, Responsive Materials, Adjustable Systems |
| Companies Covered | Stryker, EHOB, DeRoyal Industries, Hill-Rom Services, Arjo, Mölnlycke Health Care, Medline, Skil-Care Corporation, Posey Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heel Pressure Injury Relieving Devices Market Shifts & Advancements
Real-time monitoring capabilities are redistributing competitive advantage from passive material science toward responsive system architectures that integrate clinical workflow automation.
Alternating air-cell suspension technology is decentralizing pressure management from centralized nursing observation to autonomous patient-level responsiveness. Long-term care networks in Germany are deploying these systems at scale for bariatric and high-acuity populations. The technology is decentralizing clinical labor by embedding algorithmic pressure redistribution that eliminates manual repositioning protocols.
The EU Medical Device Regulation's post-market surveillance obligations are compressing supplier margins while elevating documentation standards for wound care device manufacturers. European procurement committees now require clinical evidence packages that exceed legacy CE-marking thresholds. German hospital networks are consolidating supplier lists around MDR-compliant manufacturers with established vigilance systems.
Acute-care networks are unbundling device procurement from wound care service contracts, shifting purchasing authority from materials management to infection prevention specialists. This reconfiguration concentrates buying power within quality metrics rather than unit cost optimization. The United States exhibits the most pronounced channel transformation as CMS penalties align procurement incentives with clinical outcome accountability.
Heel Pressure Injury Relieving Devices Market Segmentation
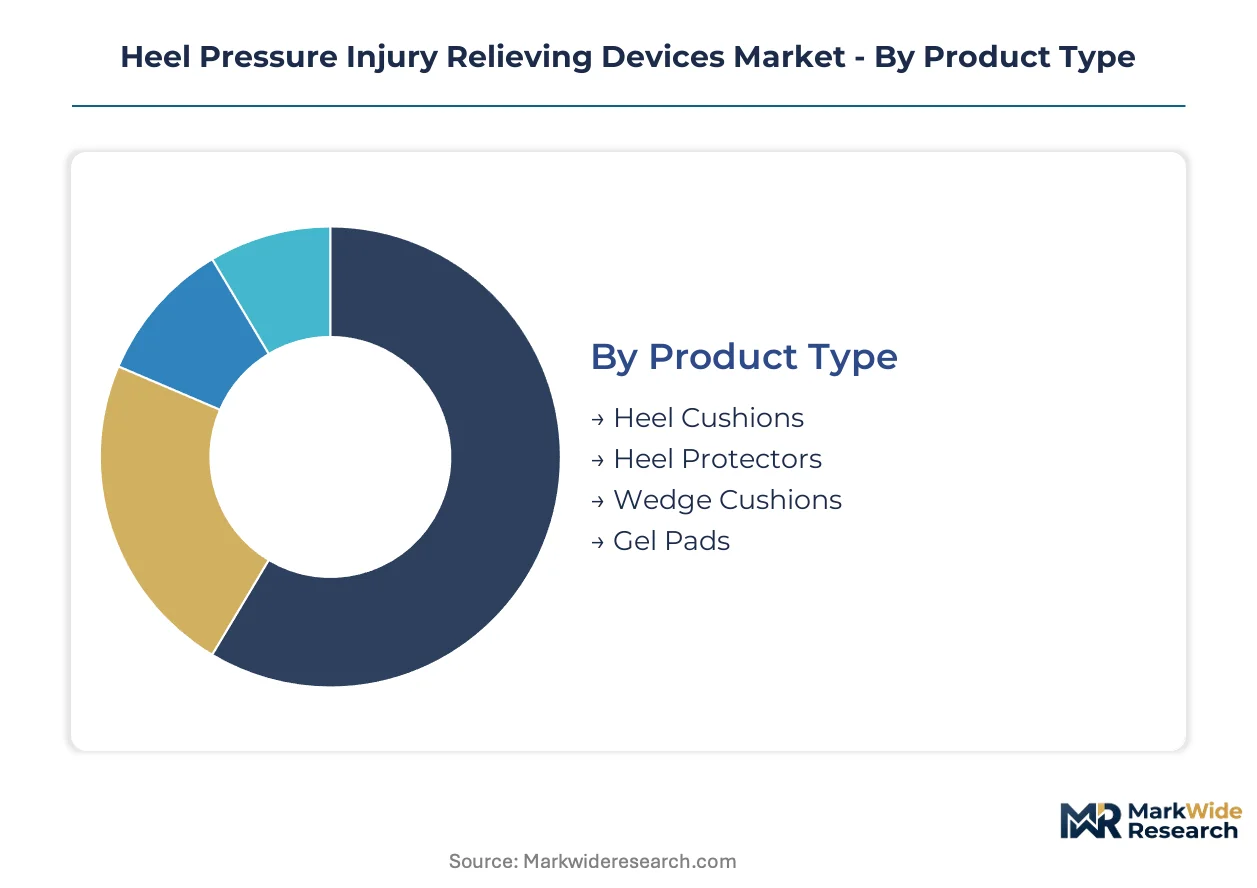
Device segmentation in this market maps directly to clinical workflow intensity and reimbursement exposure. Procurement committees weigh material durability against sensor integration capabilities when standardizing across admission pathways.
Product Type:
Upgrade cycles accelerate when facilities face CMS penalty thresholds, driving replacement of basic cushioning with sensor-enabled alternatives.
- Heel Protectors:Suspension boots and offloading boots engineered from viscoelastic foam or fabric-backed laminates eliminate ground contact for high-acuity immobilized patients. Demand concentrates in US acute-care networks where hospital-acquired condition penalties force universal admission protocols for immobility-risk patients.
- Gel Pads:Thermoregulating silicone elastomer matrices maintain tissue perfusion in operating room environments where anesthesia-induced hypoperfusion intersects with prolonged supine positioning. German surgical suites are standardizing these configurations for procedures exceeding four hours.
- Heel Cushions:Passive foam inserts redistribute pressure for ambulatory patients with limited mobility.
- Wedge Cushions:Angled foam constructs elevate the lower extremity for edema management in post-acute settings.
Heel protectors sit at the top of the volume ranking, with gel pads climbing the fastest.
End User:
Cost tier stratification separates capital-intensive acute-care deployments from consumable-heavy post-acute channels.
- Long-Term Care Facilities:Skilled nursing facilities and assisted living communities operate under corporate infection prevention mandates that embed heel suspension into standard care bundles. Japan's aging bed density sustains device utilization as facilities absorb PMDA-compliant imports for bariatric populations.
- Hospitals:Acute-care networks face direct CMS reimbursement compression for pressure ulcer incidence, forcing systematic offloading protocol implementation across every admission pathway from emergency department through discharge planning.
- Home Care Settings:Durable medical equipment distributors bundle basic foam wedges into post-discharge prescriptions.
- Rehabilitation Centers:Physical therapy protocols incorporate adjustable positioning devices for mobility restoration.
Long-term care facilities command the highest procurement volume, with home care settings expanding most quickly as discharge planners extend monitoring into community settings.
Material:
Supply concentration in petrochemical feedstocks and medical-grade elastomer foundries shapes margin stability across material tiers.
- Foam:Viscoelastic polyurethane formulations dominate cost-sensitive procurement tiers through manufacturing scale and established sterilization compatibility. Budget-constrained home care channels retain foam wedges despite inferior pressure redistribution metrics.
- Silicone:Medical-grade elastomers enable thermoregulating gel formulations that expand applicability into operating room environments. PMDA biocompatibility testing protocols in Japan create compliance barriers that filter marginal suppliers from premium positioning.
- Gel:Hydrogel composites offer intermediate pressure redistribution for mid-acuity patients.
- Air-filled:Alternating air-cell matrices enable autonomous pressure redistribution without manual repositioning.
Foam materials anchor volume leadership, with silicone gaining share fastest as surgical suite standards tighten.
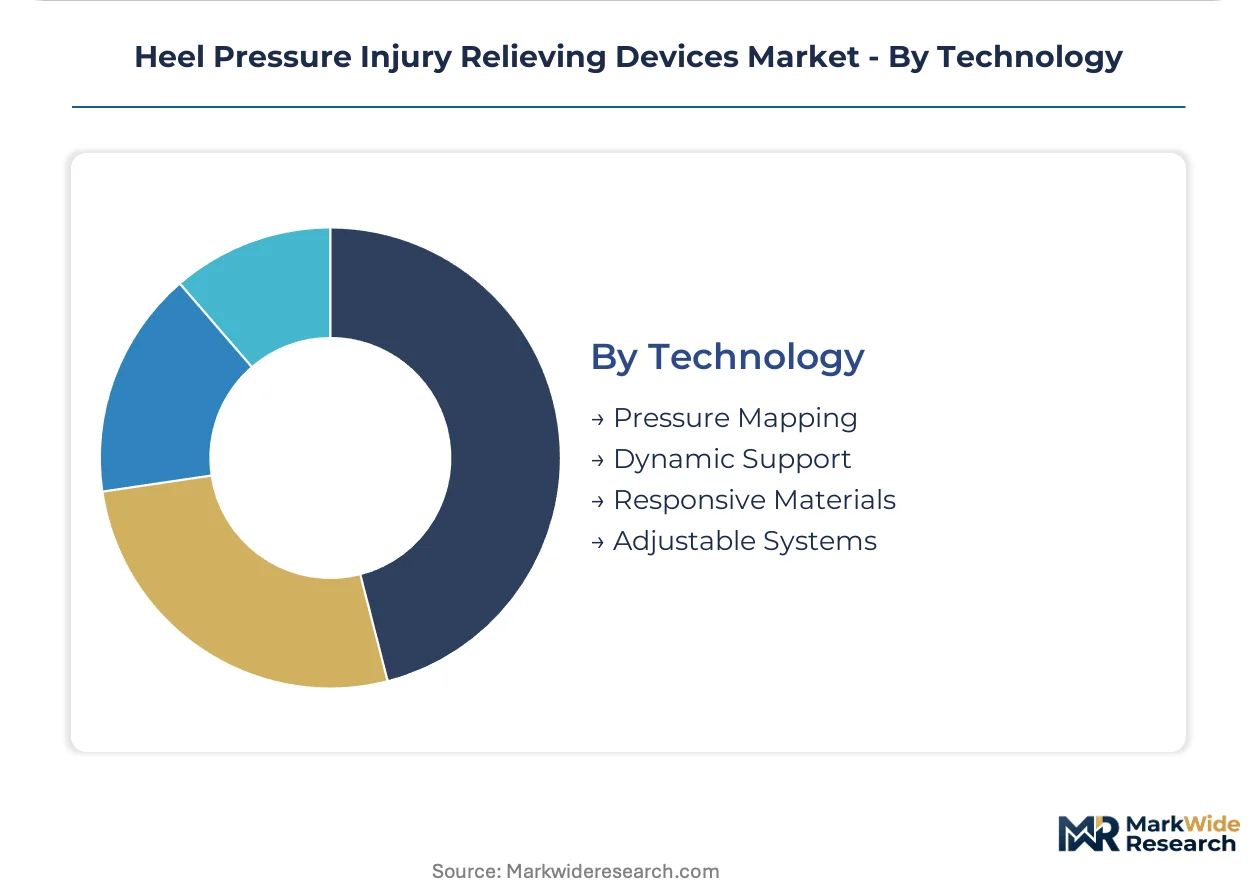
Technology:
Application intensity separates passive cushioning from responsive systems that embed clinical labor automation.
- Dynamic Support:Alternating air-cell suspension systems algorithmically redistribute pressure without nursing intervention, decentralizing care from centralized observation to patient-level autonomy. German long-term care networks deploy these at scale for bariatric populations.
- Pressure Mapping:Real-time sensor arrays track tissue perfusion and interface pressure, integrating with electronic health record architectures for automated documentation. FDA digital health guidance streamlines premarket review for these configurations.
- Responsive Materials:Phase-change and shear-reducing substrates adapt to patient movement.
- Adjustable Systems:Mechanical positioning mechanisms accommodate varying limb dimensions.
Dynamic support systems lead current volume deployment, with pressure mapping representing the steepest expansion trajectory as facilities pursue real-time skin integrity monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German long-term care networks anchor procurement volume for heel pressure injury relieving devices, with acute-care facilities across multiple geographies tightening offloading protocols under reimbursement-linked quality metrics.
United States
CMS hospital-acquired condition penalties compress reimbursement margins for pressure ulcer incidents, forcing acute-care networks to standardize heel offloading across every admission pathway. The FDA classifies these devices as Class I or II medical devices depending on therapeutic claims. Boston-based hospital networks are consolidating supplier lists around manufacturers with established post-market surveillance infrastructure.
Germany
Skilled nursing facilities operate under corporate infection prevention mandates that embed heel suspension into standard care bundles. The EU Medical Device Regulation imposes strengthened clinical evidence requirements and post-market surveillance obligations that filter lower-capability suppliers. Bavarian long-term care networks deploy alternating air-cell suspension systems at scale for bariatric populations.
Japan
Aging bed density sustains device utilization as facilities absorb PMDA-compliant imports for bariatric populations. The PMDA maintains distinct material biocompatibility testing protocols that create incremental compliance costs for foreign entrants. Tokyo acute-care markets exhibit concentrated demand for thermoregulating gel configurations in surgical suites.
United Kingdom
NHS procurement frameworks emphasize pressure ulcer prevention within quality outcome metrics, channeling demand toward validated manufacturers. The Medicines and Healthcare products Regulatory Agency enforces post-market surveillance aligned with EU MDR transition timelines. London hospital networks are unbundling device procurement from wound care service contracts, shifting purchasing authority to infection prevention specialists.
Heel Pressure Injury Relieving Devices Market Competitive Landscape
Portfolio diversification dominates the current landscape as established wound care manufacturers extend into adjacent pressure injury prevention categories. The vendor base concentrates around three tiers: integrated hospital-to-home care conglomerates, specialized suspension technology developers, and regional foam fabrication specialists. Two strategic archetypes define competitive positioning: full-spectrum wound care portfolio owners leveraging distribution infrastructure, and niche technology specialists defending premium positioning through material differentiation. M&A activity and technology licensing agreements represent the dominant competitive moves as participants seek sensor-enabled responsive system capabilities.
Within the integrated care portfolio tier, Stryker leverages its hospital-to-home infrastructure to sustain channel dominance across institutional and post-acute segments. EHOB occupies a defensible position in air-filled suspension technology, representing the specialized niche archetype. Mölnlycke Health Care anchors European procurement flows through established wound care distribution networks, exemplifying the regional infrastructure-dependent competitive model.
| Leading Market Players |
|---|
| Stryker |
| EHOB |
| DeRoyal Industries |
| Hill-Rom Services |
| Arjo |
| Mölnlycke Health Care |
| Medline |
| Skil-Care Corporation |
| Posey Products |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between MDR-validated European manufacturers and commodity foam fabricators manifests in parallel supply chain stratification, with premium-tier vendors capturing pricing power through post-market surveillance infrastructure while budget channels absorb petrochemical feedstock volatility.
Pricing Analysis
Petrochemical feedstock pass-through dynamics compress margin stability for viscoelastic foam manufacturers serving cost-sensitive procurement tiers. Three-tier pricing structure across premium, standard, and economy levels separates sensor-enabled responsive systems from passive cushioning and basic foam wedges. Cost compression in the economy tier is intensifying because home care distributors prioritize unit economics over pressure redistribution performance. Long-term care facilities exhibit the least price sensitivity due to corporate infection prevention mandates, while home care settings remain most responsive to per-unit cost.
Supply Chain Analysis
Domestic-content mandates in Japan's PMDA biocompatibility pathway are reshaping sourcing patterns for foreign entrants seeking premium positioning. Medical-grade silicone elastomer production concentrates in Germany, Japan, and the United States, with pressure-mapping microelectronics sourcing from East Asian foundries. Single-source sensor component concentration exposes device assemblers to geopolitical supply disruption. Distribution runs through wound care distribution networks and durable medical equipment bundlers into institutional and post-acute channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where CMS penalty thresholds and MDR clinical evidence mandates are shifting procurement authority toward validated manufacturers with outcome-accountable specifications.
For Market Incumbents: Cement channel dominance by deepening post-market surveillance infrastructure to meet EU MDR vigilance obligations and extending software companion development for EHR-integrated pressure mapping systems. Threat substitution from low-cost foam wedges in home care channels demands defensive certification investment to maintain hospital system preferred vendor status. For New Entrants and Emerging Players: Capture white-space opportunity in Japan's acute-care surgical suite segment where PMDA biocompatibility protocols filter marginal competition and thermoregulating gel configurations command premium positioning. Home health agency channel expansion offers the most penetrable entry vector through durable medical equipment bundle partnerships. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized suspension technology developers possessing algorithmic pressure redistribution IP and established GPO contracts manager relationships. Long-term viability over the extended care cycle favors acquisition targets with sensor-enabled responsive system capabilities and FDA digital health premarket review experience. Watch for inflection when CMS expands hospital-acquired condition penalties into post-acute reimbursement frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Post-Market Surveillance Buildout | European procurement committees now require vigilance documentation that filters lower-capability suppliers from distribution channels. |
| FDA Digital Health Premarket Submission | Real-time skin integrity monitoring systems qualify for streamlined review pathways that accelerate sensor-enabled device commercialization. |
| Hospital System Partnership | Acute-care networks are consolidating supplier lists around manufacturers with established infection prevention specialist relationships. |
| Software Companion Development | EHR interoperability capabilities differentiate responsive systems from passive cushioning in procurement evaluations. |
| Reimbursement Strategy | Alignment with CMS quality metrics and Medicare Advantage outcome-based contracts shapes channel access and pricing power. |
Research Methodology
Multiple input streams — clinical workflow observations, procurement database analysis, and regulatory filing review — were reconciled through primary interviews with wound care clinicians, hospital purchasing committee members, biomedical engineers, and GPO contracts managers, validated against secondary sources including FDA 510(k) filings, EU MDR technical documentation, CMS Medicare cost report data, and hospital procurement system records, with bottom-up device shipment estimates triangulated against top-down reimbursement exposure calculations.
Data-stream reconciliation across product type, end-user facility category, material grade tier, and technology intensity dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from facility admission pathway modeling and replacement cycle analysis for sensor-enabled versus passive device categories, with forecast inputs incorporating CMS penalty threshold evolution and EU MDR transition timeline compliance costs.
Regulatory enforcement variance, petrochemical feedstock disruption, and EHR interoperability adoption delays are the dominant revision risks that could alter trajectory assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Human Enhancement Market
Medical Devices
Human Anatomy Model Market
Medical Devices
Hybrid Grafts Market
Medical Devices
Global Venous Blood Collection Devices Market
Medical Devices
Urinary Flow Meters Market
Medical Devices
Portable OT Light Market
Medical Devices
Artificial Implants Market
Medical Devices
Surgical Helmet Systems Market
Medical Devices
Infrared Heating Pad Market
Medical Devices
Left Atrial Appendage (LAA) Closure Device Market
Medical Devices
Global Microdermabrasion Devices Market
Medical Devices
Pediatric Home-Use Medical Devices Market
Medical Devices
Electric Massage Equipment Market
Medical Devices
North America Surgical Microscopes Market
Medical Devices
Liposuction Devices Market
Medical Devices
Australia Ultrasound Devices Market