
 Vaginal Pessary Market | 2026-2036
Vaginal Pessary Market Size, Share, and Industry Trends Forecast 2026-2036
Vaginal Pessary Market Intelligence
Urogynecology fellowship training is rotating toward conservative management protocols, expanding the clinical workforce qualified for pessary fitting and follow-up care. CooperSurgical Inc. leverages its broad women's health portfolio to sustain channel presence across gynecology clinics. Dr. Arabin GmbH & Co. KG anchors European supply through specialized silicone pessary craftsmanship. Integra LifeSciences competes in adjacent pelvic floor segments, extending its clinical reach into pessary-adjacent procedures.
A vaginal pessary is a removable medical device inserted into the vagina to provide structural support to pelvic organs compromised by prolapse or incontinence, typically fabricated from medical-grade silicone or thermoplastic elastomer through injection molding or compression forming processes. Ring pessaries dominate ambulatory fittings due to straightforward insertion protocols and broad clinician familiarity, while Gellhorn pessaries occupy advanced cases requiring significant apical support in patients with stage III-IV prolapse. Silicone formulations lead material preference for biocompatibility and odor resistance, though thermoplastic elastomer alternatives are gaining traction in cost-sensitive procurement environments across women's health clinics.
FDA 510(k) premarket notification requirements shape product development timelines and clinical evidence thresholds for US market entry, while EU MDR conformity assessment procedures extend certification burdens for silicone and latex devices distributed in Europe. ISO 13485 quality management standards govern manufacturing consistency across multinational supply chains serving gynecology clinics and ambulatory surgical centers. Stakeholders must monitor evolving reimbursement codes for pessary fitting services, as coverage expansion or contraction will directly alter provider economics and patient access trajectories.
Market Dynamics
Silicone supply concentration in German manufacturing clusters is compressing procurement timelines for North American distributors while FDA 510(k) pathway efficiencies accelerate product commercialization velocity.
Growth Catalysts
- FDA 510(k) Streamlining:The FDA's premarket notification pathway for silicone-based devices reduces clinical evidence burdens and shortens time-to-market for manufacturers targeting ambulatory surgical centers.
- Urogynecology Fellowship Expansion:Conservative management protocols are proliferating through accredited training programs, expanding the clinical workforce qualified for pessary fitting across women's health clinics.
- Silicone Biocompatibility Standards:ISO 13485 quality management certification is becoming baseline for supply chain qualification, driving manufacturing consistency across multinational distribution networks.
Market Restraints
- Medical-Grade Silicone Price Volatility:Petrochemical feedstock fluctuations and specialized polymer purification requirements create input cost instability for compression-forming manufacturers.
- EU MDR Certification Burden:Extended conformity assessment procedures for silicone and latex devices are lengthening market entry timelines for European distribution.
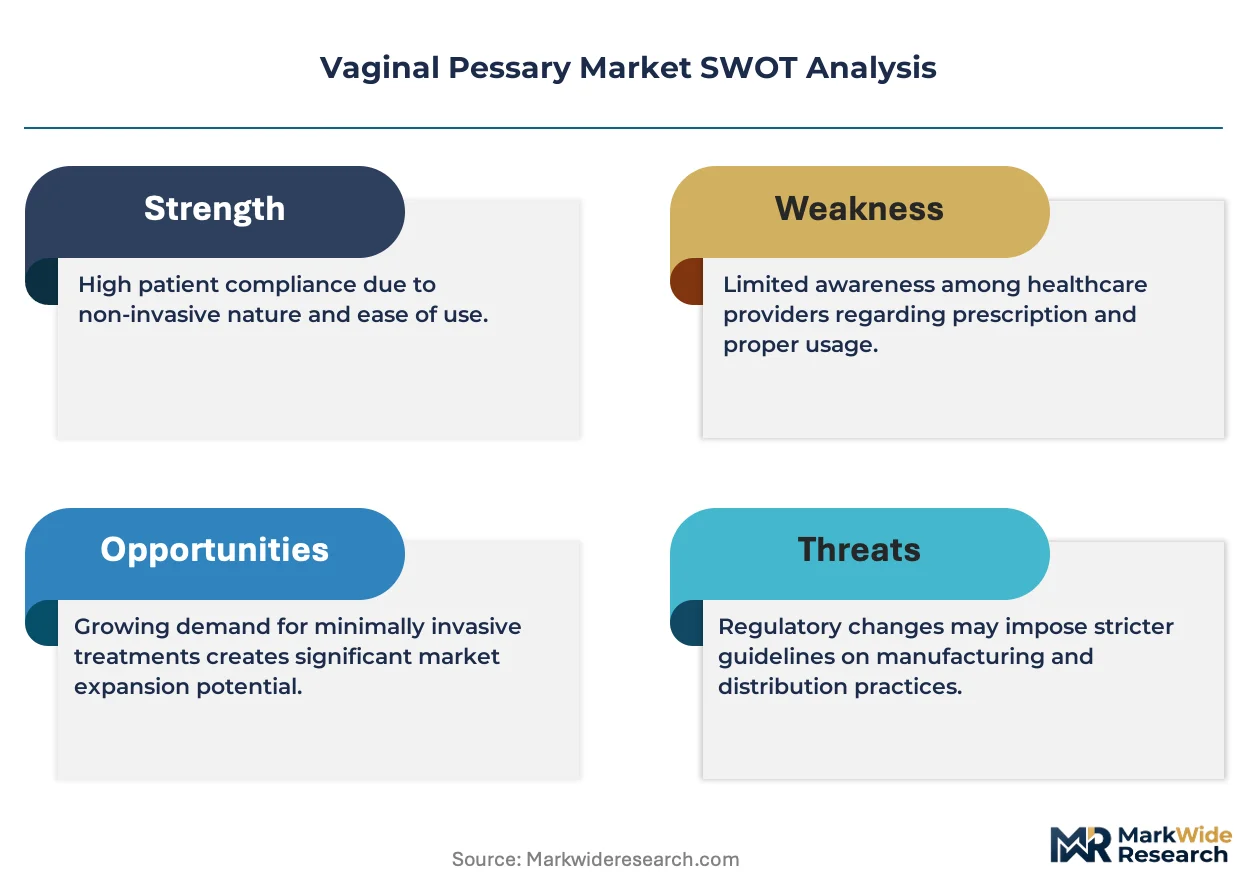
- Surgical Mesh Substitution:Transvaginal mesh procedures retain preference among certain urogynecology specialists for advanced prolapse cases, limiting conservative management penetration.
Strategic Opportunities
- Telehealth Fitting Protocols:Remote consultation platforms are emerging as viable channels for initial pessary sizing and patient education, reducing geographic access barriers in rural markets.
- Thermoplastic Elastomer Formulations:Cost-sensitive procurement environments in community health centers are creating demand for alternative materials that maintain biocompatibility at lower unit economics.
- Reimbursement Code Expansion:CMS coverage modifications for pessary fitting services present direct revenue pathway improvements for gynecology clinic operators.
Industry Challenges
- Pelvic Floor Specialist Shortage:The limited pipeline of fellowship-trained urogynecologists constrains fitting capacity expansion despite rising patient referrals from primary care.
- Legacy Inventory Integration:Clinics maintaining latex-based pessary stocks face sterilization protocol conflicts and patient allergy documentation complexities during silicone transition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vaginal Pessary Market |
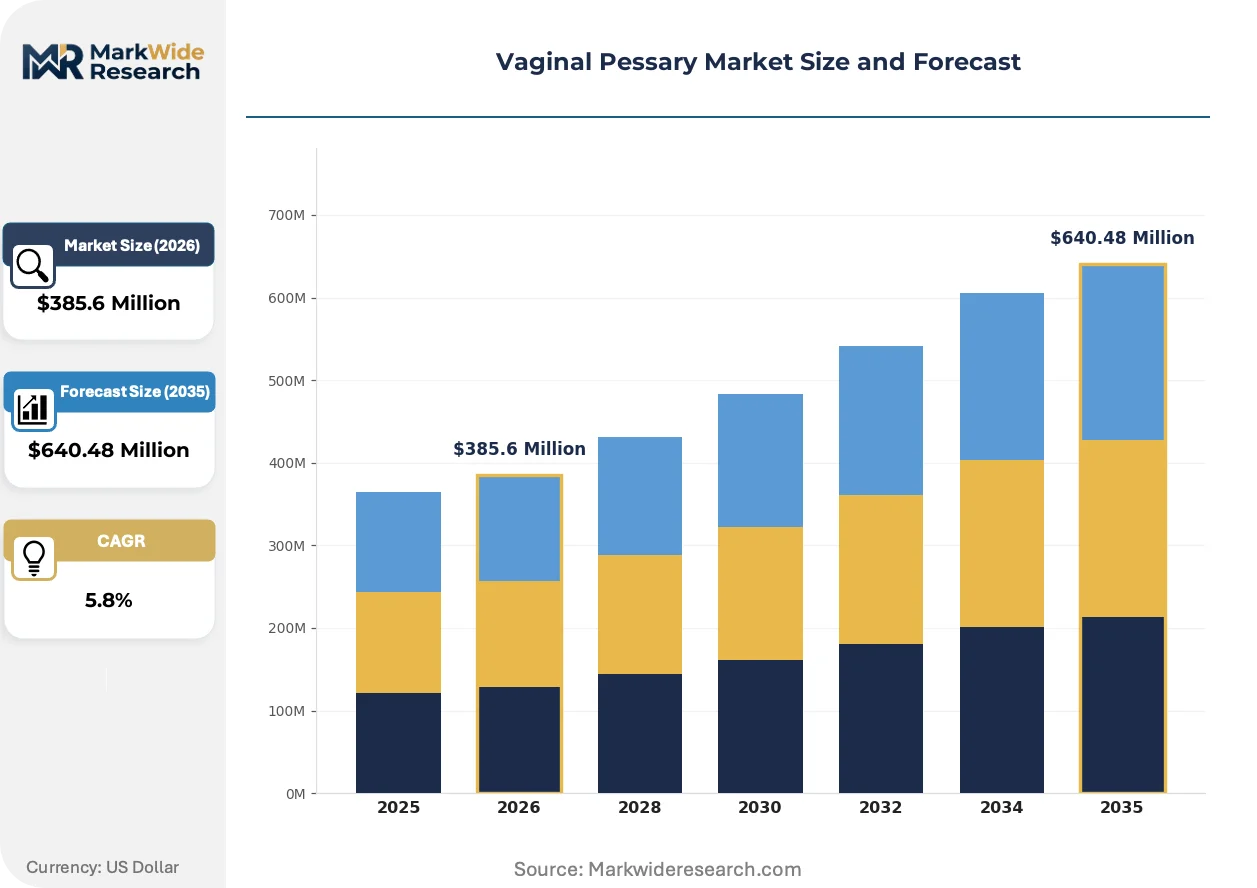
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $640.48 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ring Pessary, Cube Pessary, Gellhorn Pessary, Dish Pessary, Donut Pessary Application: Pelvic Organ Prolapse, Urinary Incontinence, Cystocele Repair, Rectocele Management, Vaginal Support End User: Gynecology Clinics, Urology Centers, Ambulatory Surgical Centers, Rehabilitation Centers, Women’s Health Clinics Material Type: Silicone, Latex, Thermoplastic Elastomer, Medical-Grade PVC, Polyurethane |
| Companies Covered | Panpac Medical Corp., Integra LifeSciences, CooperSurgical Inc., Milex Products Inc., Personal Medical Corp., MedGyn Products Inc., Bioteque America Inc., Dr. Arabin GmbH & Co. KG, Bliss GVS Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vaginal Pessary Market Strategic Shifts & Innovations
Digital measurement tools and material science advances are compressing fitting cycles while regulatory harmonization efforts reshape quality assurance protocols across manufacturing geographies.
Custom-fit silicone pessary fabrication using 3D scanning and additive manufacturing workflows is miniaturizing production batch sizes. Women's health clinics in metropolitan clusters are adopting point-of-care measurement systems that reduce fitting appointment duration from three sessions to one. This compression is enabling inventory-light distribution models that shift working capital burden from clinics to specialized manufacturers.
EU MDR Article 117 requirements for notified body involvement in silicone device conformity assessment are elevating documentation standards for European market entry. Manufacturers are restructuring quality management systems to accommodate unannounced audits and post-market surveillance obligations. The German notified body ecosystem is experiencing capacity constraints that extend certification timelines for new product variants.
Patients are initiating care journeys through direct-to-consumer educational platforms before clinical contact, altering traditional referral patterns. Gynecology clinics are responding by unbundling consultation and fitting services into discrete billable events. This disintermediation is most pronounced in US metropolitan markets where health system consolidation has centralized pelvic floor specialty access.
Vaginal Pessary Market Segmentation
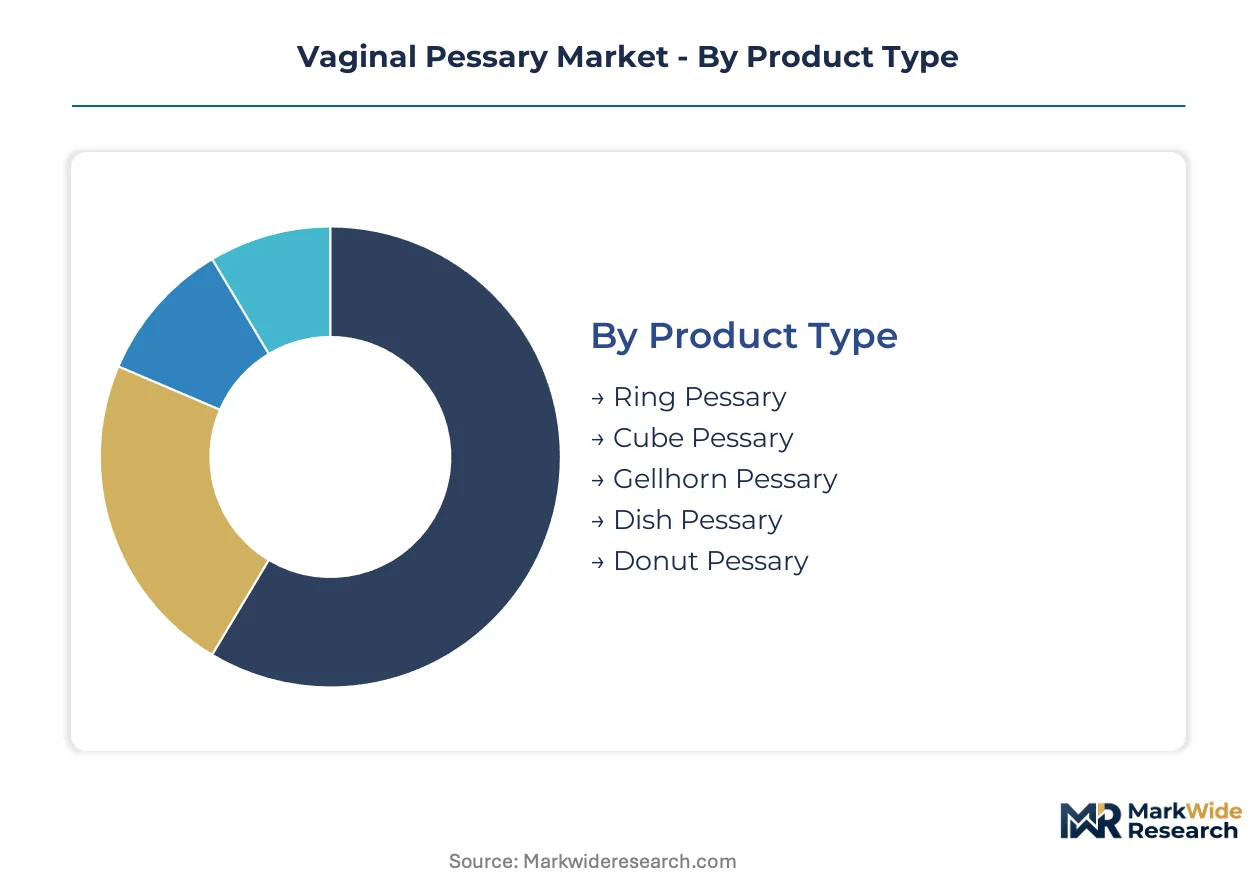
Segmentation in the vaginal pessary market reveals distinct procurement and fitting workflows across product geometries, clinical indications, and care settings. Channel economics vary sharply between ambulatory fittings and surgical center protocols.
Product Type:
Ring and Gellhorn pessaries flow through high-volume gynecology clinic channels, while specialized geometries target urology center referral networks.
- Ring Pessary:The circular silicone device with central support membrane dominates first-line conservative management. Demand concentrates in US metropolitan women's health clinics where single-visit fitting protocols compress appointment duration and inventory turnover accelerates.
- Gellhorn Pessary:This stemmed configuration provides apical support for advanced prolapse stages. German urogynecology centers anchor European procurement volumes, driven by stage III-IV patient referrals from primary care networks seeking alternatives to mesh surgery.
- Cube Pessary:Suction-based retention suits patients with compromised perineal support. UK NHS community clinics favor this geometry for home self-management programs.
- Dish Pessary:Broad platform design distributes pressure across vaginal vault. Australian pelvic floor physiotherapy practices specify this variant for rectocele-dominant presentations.
- Donut Pessary:Toroidal silicone construction suits severe cystocele with intact perineal body. Japanese obstetrics-gynecology departments maintain dedicated fitting protocols for this geometry.
By volume, Ring Pessary leads. By growth pace, Gellhorn Pessary is expanding most quickly.
Application:
Cost tiering separates reimbursement pathways, with prolapse indications commanding higher professional fees than incontinence management in US Medicare schedules.
- Pelvic Organ Prolapse:Structural support for descensus of uterus or vaginal apex represents the primary clinical indication. French public hospital procurement concentrates here, with ANSM quality surveillance driving silicone material specifications.
- Urinary Incontinence:Bladder neck support without prolapse correction targets stress incontinence dominant cases. Canadian urology center expansion into pessary fitting is accelerating demand for this application segment.
- Cystocele Repair:Anterior compartment support addresses bladder herniation. Italian regional health authorities reimburse this indication under distinct tariff codes separate from comprehensive prolapse management.
- Rectocele Management:Posterior compartment support for rectal herniation. Spanish public health system waiting list pressures are shifting rectocele cases toward conservative pessary trials.
- Vaginal Support:General vault suspension without compartment-specific correction. Brazilian SUS system primary care gatekeepers increasingly initiate this conservative pathway before specialty referral.
By patient volume, Pelvic Organ Prolapse dominates. By referral velocity, Urinary Incontinence is climbing the fastest.
End User:
Customer type determines fitting complexity and follow-up cadence, with surgical centers requiring sterile field protocols absent in clinic-based care.
- Gynecology Clinics:Office-based fitting with speculum examination and digital sizing constitutes the standard care model. US private practice consolidation is concentrating procurement volume through multi-site women's health platforms.
- Urology Centers:Male-dominated specialty settings are expanding female pelvic floor services. German Klinikum networks are cross-training urologists in pessary fitting to capture prolapse referrals.
- Ambulatory Surgical Centers:Same-day surgical facilities incorporate pessary fitting as preoperative staging or post-mesh explant bridge therapy. Indian corporate hospital chains are adding this service line to ASC satellites.
- Rehabilitation Centers:Pelvic floor physiotherapy integration supports pessary self-management training. Australian private rehabilitation networks bundle fitting with biofeedback protocols.
- Women's Health Clinics:Dedicated female care settings optimize patient experience and continuity. UK community sexual and reproductive health clinics are expanding pessary capacity under integrated care contracts.
By procedure count, Gynecology Clinics lead. By service line expansion, Urology Centers are gaining share fastest.
Material Type:
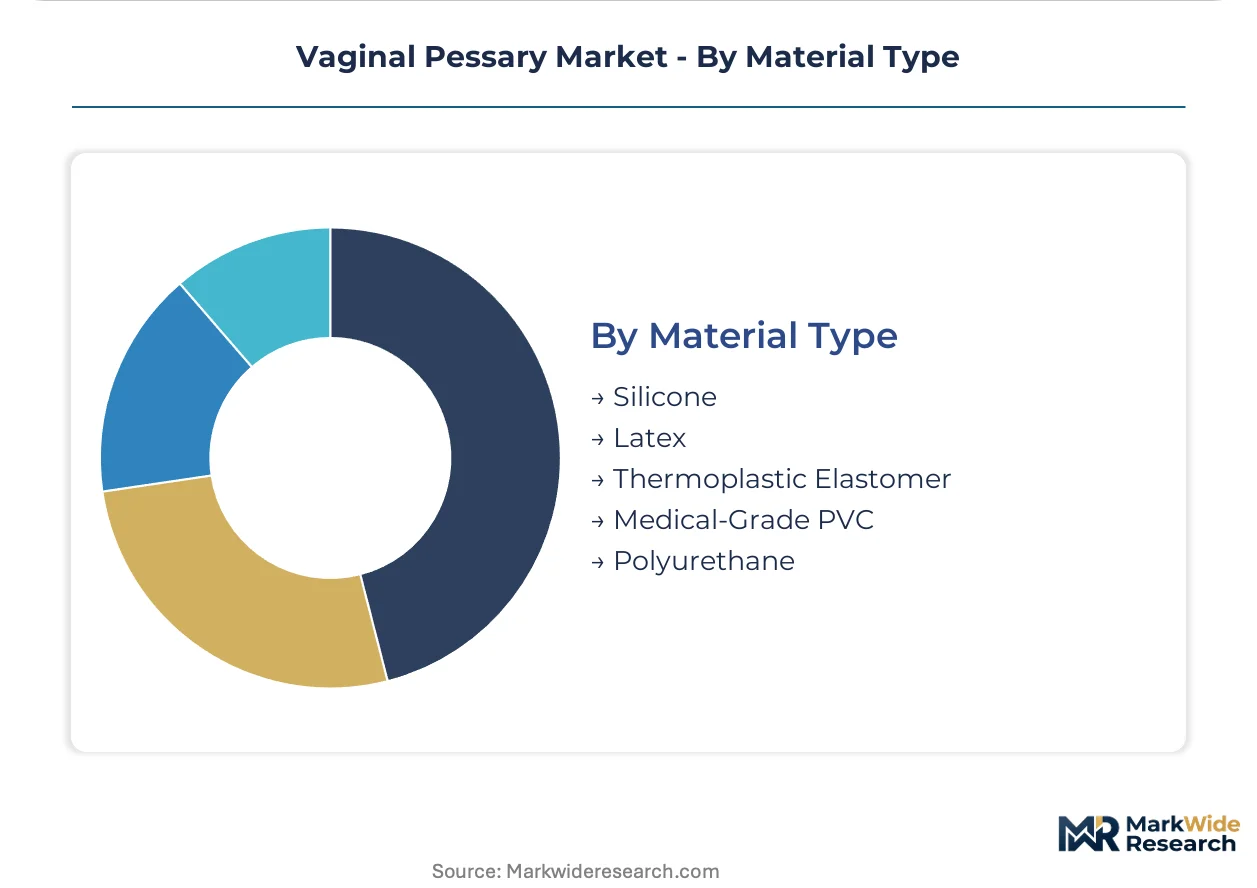
Supply concentration in German silicone manufacturing clusters compresses procurement timelines for premium formulations while thermoplastic alternatives penetrate cost-sensitive channels.
- Silicone:Medical-grade platinum-cured polymer delivers biocompatibility, odor resistance, and extended wear duration. Dr. Arabin GmbH & Co. KG's specialized craftsmanship anchors European supply.
- Thermoplastic Elastomer:Injection-moldable alternatives reduce unit costs for high-turnover clinic inventories. Indian domestic manufacturers are scaling TPE production for price-sensitive institutional procurement.
- Latex:Natural rubber formulations persist in legacy inventory despite allergy documentation burdens. Brazilian public health system warehouses maintain latex stocks amid silicone transition delays.
- Medical-Grade PVC:Rigid support structures suit specific geometric applications. Chinese domestic market producers supply PVC pessaries for basic prolapse support.
- Polyurethane:Alternative elastomer with distinct hardness profiles for specialized fitting requirements. Japanese medical device specialists explore polyurethane for custom-fit applications.
By installed base, Silicone leads. By procurement momentum, Thermoplastic Elastomer shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German urogynecology centers fit pessaries for stage III-IV prolapse at triple the rate of US ambulatory clinics, while Japanese obstetrics-gynecology departments maintain dedicated protocols for toroidal geometries absent elsewhere.
United States
Private practice consolidation drives procurement through multi-site women's health platforms. FDA 510(k) premarket notification requirements shape product development timelines for silicone devices. Metropolitan clusters in Texas and California are adopting point-of-care measurement systems that compress fitting from three sessions to one.
Germany
ANSM quality surveillance drives silicone material specifications for public hospital procurement. EU MDR Article 117 elevates documentation standards for notified body involvement. The Bavarian manufacturing cluster around Dr. Arabin GmbH & Co. KG anchors European supply through specialized craftsmanship.
Japan
PMDA medical device regulations govern silicone biocompatibility certification for domestic distribution. METI industrial standards support precision manufacturing of custom-fit geometries. Tokyo and Osaka obstetrics-gynecology departments maintain dedicated fitting protocols for donut pessaries in severe cystocele cases.
United Kingdom
NHS community sexual and reproductive health clinics are expanding pessary capacity under integrated care contracts. MHRA post-market surveillance requirements align with EU MDR transition timelines. London and Manchester pelvic floor physiotherapy practices specify dish pessaries for rectocele-dominant presentations.
Brazil
SUS system primary care gatekeepers increasingly initiate conservative pessary pathways before specialty referral. ANVISA medical device registration creates compliance thresholds for imported silicone formulations. São Paulo public health warehouses maintain latex stocks amid silicone transition delays.
Vaginal Pessary Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with women's health conglomerates leveraging portfolio breadth against focused pessary craftsmen. Consolidation pressures favor multi-site distribution networks that can absorb EU MDR certification costs. Three archetypes dominate: integrated women's health platforms, specialized silicone fabricators, and regional contract manufacturers serving cost-sensitive procurement. Competitive moves center on backward integration into medical-grade silicone supply and geographic expansion through urology center partnerships.
Among German fabricators, Dr. Arabin GmbH & Co. KG exemplifies the specialized craftsmanship archetype, while CooperSurgical Inc. and Integra LifeSciences represent integrated platforms with women's health portfolio breadth. These three occupy distinct competitive positions: the German specialist anchors European premium supply, the US conglomerate sustains channel presence across gynecology clinics, and the life sciences platform extends clinical reach into adjacent pelvic floor segments.
| Leading Market Players |
|---|
| Panpac Medical Corp. |
| Integra LifeSciences |
| CooperSurgical Inc. |
| Milex Products Inc. |
| Personal Medical Corp. |
| MedGyn Products Inc. |
| Bioteque America Inc. |
| Dr. Arabin GmbH & Co. KG |
| Bliss GVS Pharma |
| Others |
Cost & Logistics Intelligence
FDA 510(k) premarket notification requirements and EU MDR Article 117 conformity assessments simultaneously gate supplier qualification and stratify price tiers across the vaginal pessary market. German silicone fabricators command premium positioning through specialized craftsmanship certification, while thermoplastic elastomer alternatives penetrate cost-sensitive procurement channels in community health centers.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between multi-site women's health platforms and specialized manufacturers, insulating volume purchasers from medical-grade silicone price volatility. Price differentiation separates platinum-cured silicone formulations with extended wear guarantees from injection-molded thermoplastic alternatives targeting high-turnover clinic inventories. Pricing pressure stems from petrochemical feedstock fluctuations compressing margins for compression-forming manufacturers. Community health centers exhibit the highest price sensitivity, while metropolitan urogynecology clinics prioritize biocompatibility certification over unit cost.
Supply Chain Analysis
Strategic stockpiling of medical-grade silicone resin characterizes procurement strategies among North American distributors facing German manufacturing cluster concentration. Supply concentrates in Germany, the United States, and India, with Bavarian fabricators anchoring European premium production and Indian manufacturers scaling thermoplastic elastomer output. Raw material dependencies center on platinum-cured silicone polymer, thermoplastic elastomer compounds, and specialized molding equipment. Single-source vulnerability in German notified body certification capacity extends lead times for EU market entry. Distribution runs through specialized medical device distributors serving gynecology clinic networks and hospital procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vaginal pessary market is entering a cyclical recovery phase as urogynecology fellowship expansion rebuilds clinical fitting capacity depleted during conservative management protocol transitions. Patient referral volumes from primary care networks are rebounding across metropolitan women's health clusters.
For Market Incumbents: Shield market position by deepening backward integration into medical-grade silicone supply chains and accelerating FDA 510(k) portfolio expansion ahead of EU MDR certification bottlenecks. Surgical mesh substitution for advanced prolapse cases threatens conservative management penetration; counter this through urology center partnership programs that embed pessary fitting into preoperative staging protocols.
For New Entrants and Emerging Players: Differentiate on telehealth-enabled fitting protocols that reduce geographic access barriers in rural markets underserved by fellowship-trained specialists. White-space opportunities concentrate in thermoplastic elastomer formulations for cost-sensitive community health center procurement and point-of-care 3D scanning systems that compress fitting cycles. Target Canadian urology center expansion as the most penetrable geography, leveraging remote consultation platforms for initial patient education and sizing.
For Investors and Strategic Acquirers: EU MDR Article 117 implementation reshapes the acquisition landscape by elevating capital requirements for notified body compliance and post-market surveillance infrastructure. Long-term viability favors specialized silicone fabricators with captive German manufacturing assets and established quality management systems. Acquisition target archetype: mid-cap manufacturers with ISO 13485 certification and existing European distribution networks. Watch CMS reimbursement code expansion for pessary fitting services as the signal indicating provider economics inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Shortens time-to-market for silicone-based devices targeting ambulatory surgical center expansion. |
| EU MDR Certification Investment | Notified body engagement satisfies Article 117 requirements for German and French hospital procurement. |
| Urology Center Partnership Program | Cross-training protocols capture prolapse referrals from male-dominated specialty settings. |
| Telehealth Fitting Platform Development | Remote consultation infrastructure penetrates rural markets with limited pelvic floor specialist access. |
| Thermoplastic Elastomer Formulation Scale-Up | Injection-moldable alternatives address price-sensitive procurement in community health centers. |
Research Approach
Cross-validation between primary interviews with urogynecologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers anchors the qualitative findings against secondary validation from FDA 510(k) filings, EU MDR notified body documentation, CMS Medicare reimbursement databases, and hospital procurement contract records. Bottom-up triangulation across product geometry demand estimates and top-down validation through women's health clinic service line expansion data ensures segmentation integrity.
Sensitivity analysis frameworks test forecast robustness across alternative scenarios for urogynecology fellowship graduation rates and silicone raw material price trajectories. The analytical framework models demand across product type, application indication, end-user setting, material formulation, and regional regulatory cluster throughout the projection horizon. CAGRs derive from fitted trend extrapolation moderated by specialist capacity constraints and reimbursement policy assumptions. Industry-specific inputs include pessary fitting protocol adoption curves and telehealth consultation penetration rates.
Forecasts assume regulatory continuity in FDA 510(k) clearance pathways and EU MDR conformity assessment procedures; material policy shifts would require re-modeling. Revision becomes warranted when urogynecology specialist shortage severity crosses thresholds that constrain fitting capacity expansion despite patient referral growth.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Blood Warmer Devices Market
Medical Devices
Global Intrauterine Contraceptive Devices (IUD) Market
Medical Devices
Global Electrotherapy Devices Market
Medical Devices
Microdebrider Market
Medical Devices
Global Urethral Dilator Market
Medical Devices
Healthcare Additive Manufacturing Market
Medical Devices
Pedicle Screw Systems Market
Medical Devices
Heating Pads Market
Medical Devices
Global Medical Injection Molding Market
Medical Devices
US Digital Pregnancy Test Kits Market
Medical Devices
Medical Devices Clinical Trials Market
Medical Devices
Asia-Pacific Manual Resuscitators Market
Medical Devices
Animal Ultrasound Market
Medical Devices
Uterine Fibroid Embolization Devices Market
Medical Devices
Knotless Suture Anchors Market
Medical Devices
Global Insufflation Devices Market