
 Bronchial Thermoplasty Catheter Market | 2026-2036
Bronchial Thermoplasty Catheter Market Size, Share, and Industry Trends Forecast 2026-2036
Bronchial Thermoplasty Catheter Market Analysis
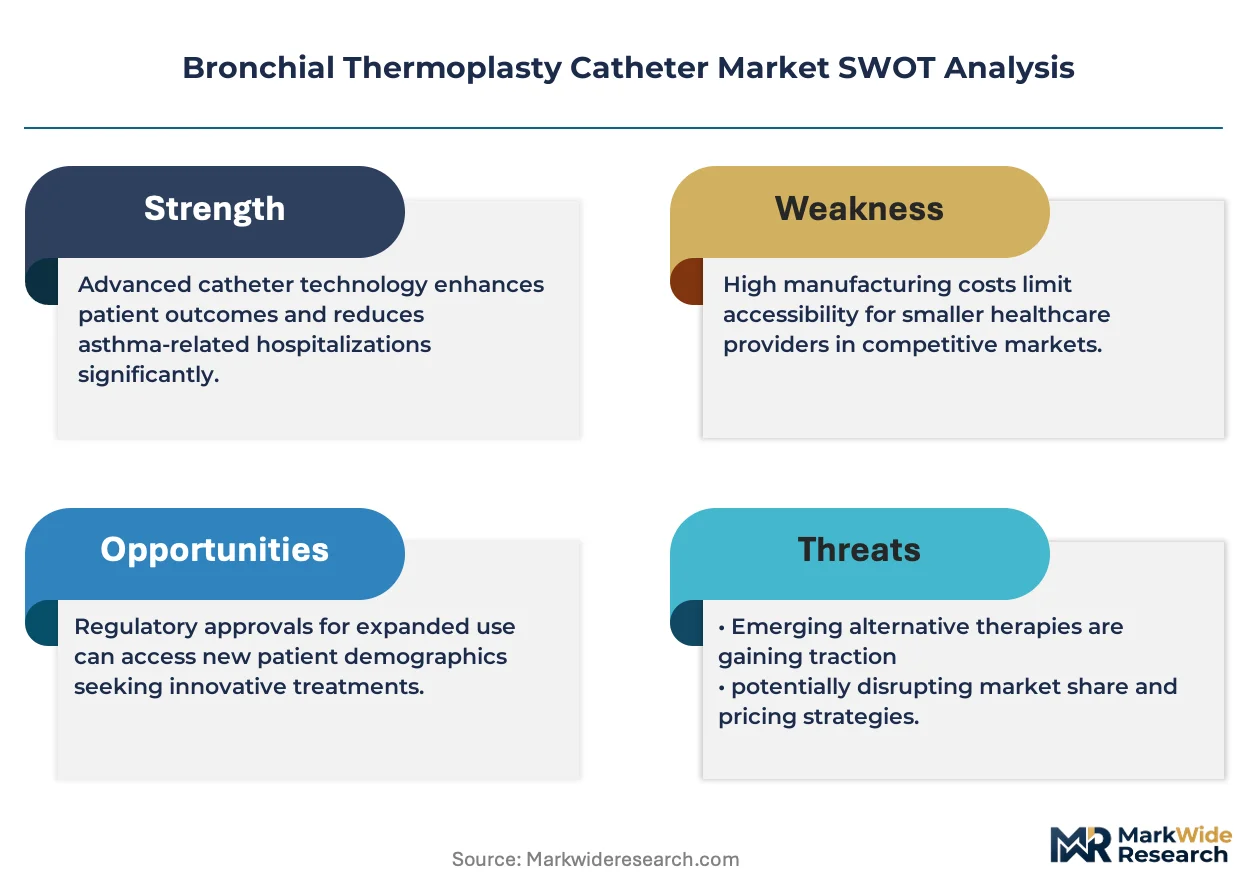
The divergence between premium radiofrequency-enabled catheters and commodity surgical tools is hardening as reimbursement policies favor demonstrated clinical outcomes. Boston Scientific Corporation leverages its interventional pulmonology portfolio to sustain technology leadership in radiofrequency energy delivery systems. Medtronic plc anchors its position through deep integration with hospital purchasing networks across North America and Europe.
Bronchial thermoplasty catheters are electrosurgical devices that deliver controlled radiofrequency energy to airway smooth muscle via a flexible bronchoscope-compatible design, typically operating at 65°C for targeted thermal ablation to reduce bronchoconstriction in severe asthma patients. The single-use segment dominates current revenue as infection control protocols and device traceability requirements eliminate reusable options in most regulated markets. Radiofrequency energy technology leads the technology landscape while hybrid techniques represent the fastest-growing category as manufacturers combine thermal ablation with real-time imaging feedback to improve procedure precision and safety profiles.
FDA premarket approval pathways and EMA Medical Device Regulation conformity assessments govern market access, with both agencies demanding extensive clinical evidence for class III devices that contact airway tissue under energy delivery. Japan's PMDA adds a distinct regulatory layer through its foreign manufacturer registration and quality management system inspection requirements. Stakeholders must monitor evolving reimbursement decisions by CMS and national health technology assessment bodies, as coverage determinations will dictate whether the installed base of interventional pulmonology suites expands sufficiently to absorb forecasted catheter production volumes.
Market Dynamics
Radiofrequency catheter manufacturers face intensifying pressure from FDA premarket approval timelines and EMA Medical Device Regulation conformity assessments, which compress commercialization windows while demanding expanded clinical evidence packages for class III airway devices.
Growth Catalysts
- Severe asthma prevalence in hospital settings:Pulmonology departments across the United States, Germany, and Japan are expanding interventional suites to accommodate bronchial thermoplasty procedures as standard-of-care protocols mature.
- EMA MDR quality management mandates:Stricter traceability and post-market surveillance requirements are accelerating replacement cycles for legacy catheter inventories in European markets.
- Hybrid imaging-thermal systems:Real-time feedback integration is improving procedure safety profiles and expanding addressable patient populations beyond conventional candidate criteria.
Market Restraints
- Single-use material cost volatility:Polymer and electrode supply chains concentrated in East Asian manufacturing clusters expose margins to input price swings.
- Reimbursement coverage gaps:CMS national coverage determinations and German G-BA assessments impose procedural volume ceilings that constrain hospital purchasing commitments.
- Biologic therapy substitution:Monoclonal antibody treatments for severe eosinophilic asthma compete directly for the same refractory patient population.
Strategic Opportunities
- Underpenetrated Japanese outpatient channels:METI healthcare efficiency directives are creating procedural volume incentives in ambulatory settings previously reserved for inpatient bronchoscopy.
- CE marking fast-track pathways:EMA breakthrough device designations for asthma innovations with demonstrated clinical superiority are compressing time-to-revenue for qualified submissions.
- Artificial intelligence-guided ablation:Machine learning integration with radiofrequency delivery is expanding into predictive tissue response modeling.
Industry Challenges
- Interventional pulmonologist training pipelines:Specialized bronchoscopy certification programs face capacity constraints that limit qualified operator supply.
- ISO 13485 quality system audits:Foreign manufacturer registration requirements in Japan and the European Union demand sustained compliance investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bronchial Thermoplasty Catheter Market |
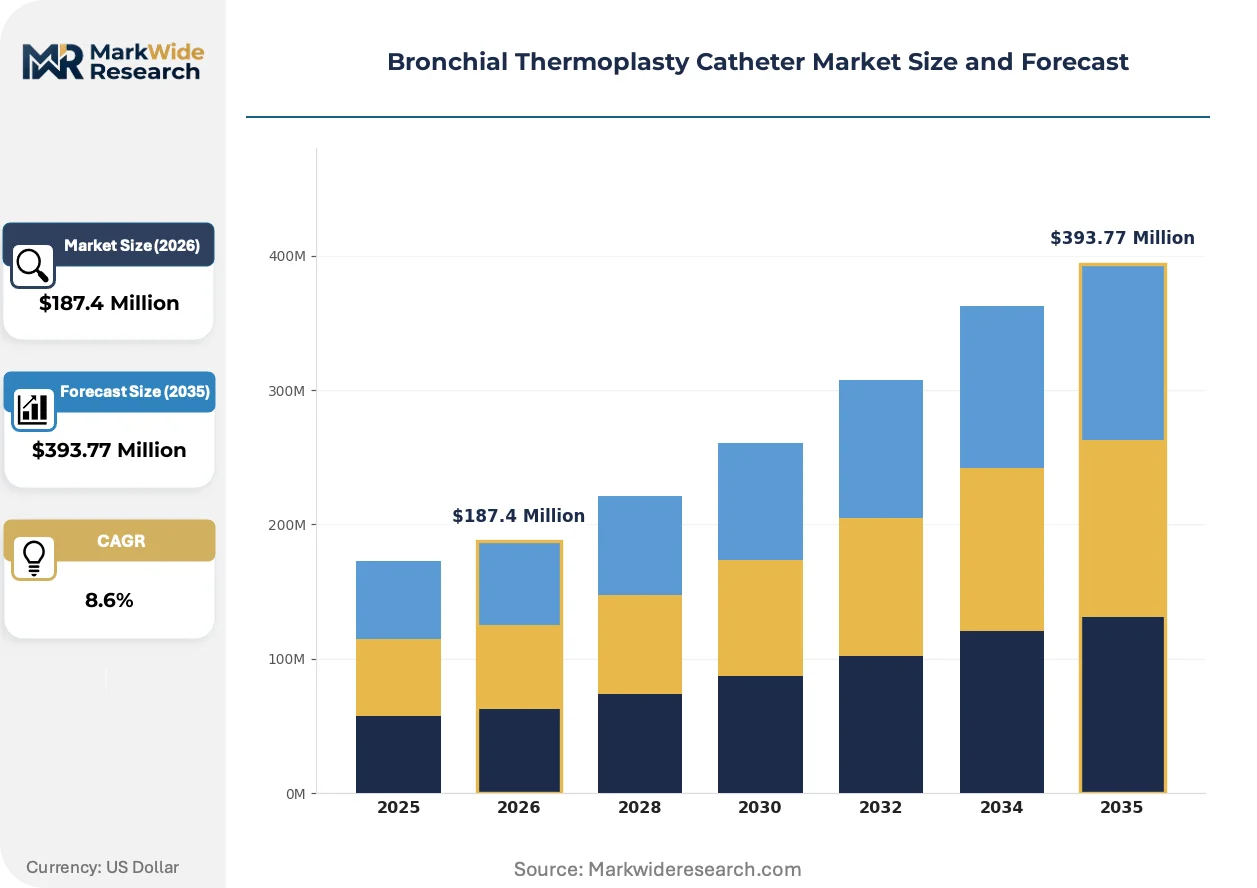
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Use, Reusable, Custom Designed, Standardized End User: Hospitals, Outpatient Clinics, Specialty Care Centers, Academic Institutions Application: Severe Asthma, Chronic Obstructive Pulmonary Disease, Other Respiratory Disorders, Clinical Research Technology: Radiofrequency Energy, Laser-Based, Conventional Surgery, Hybrid Techniques |
| Companies Covered | Teleflex Incorporated, Johnson & Johnson, Boston Scientific Corporation, Smith & Nephew plc, Abbott Laboratories, Medtronic plc, Cook Medical LLC, Merit Medical Systems, Inc., Olympus Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bronchial Thermoplasty Catheter Market Emerging Trajectories
Device architecture is converging with digital health infrastructure, creating new performance benchmarks that favor integrated systems over standalone catheter platforms. This shift is redefining procurement criteria and vendor selection frameworks.
Hybrid thermal-imaging catheters combine radiofrequency energy delivery with real-time optical coherence tomography feedback, enabling precise airway wall thickness measurement during ablation. Academic medical centers in the United States and Germany are piloting these systems to reduce procedure time and complication rates. The technology is expanding into outpatient bronchoscopy suites previously limited to diagnostic procedures.
EMA Medical Device Regulation Article 117 conformity assessments now require notified body involvement for all class III airway devices, extending pre-market timelines by 12-18 months. Manufacturers are responding by front-loading clinical evidence generation and establishing European authorized representative offices. German and French hospital purchasing networks are prioritizing suppliers with established MDR technical documentation.
Hospital procurement departments are consolidating bronchial thermoplasty catheter sourcing through integrated delivery networks and group purchasing organizations. This concentration is displacing direct manufacturer relationships at individual pulmonary departments. The United States exhibits the most pronounced consolidation, with three national GPOs controlling the majority of interventional pulmonology device contracts.
Bronchial Thermoplasty Catheter Market Segmentation
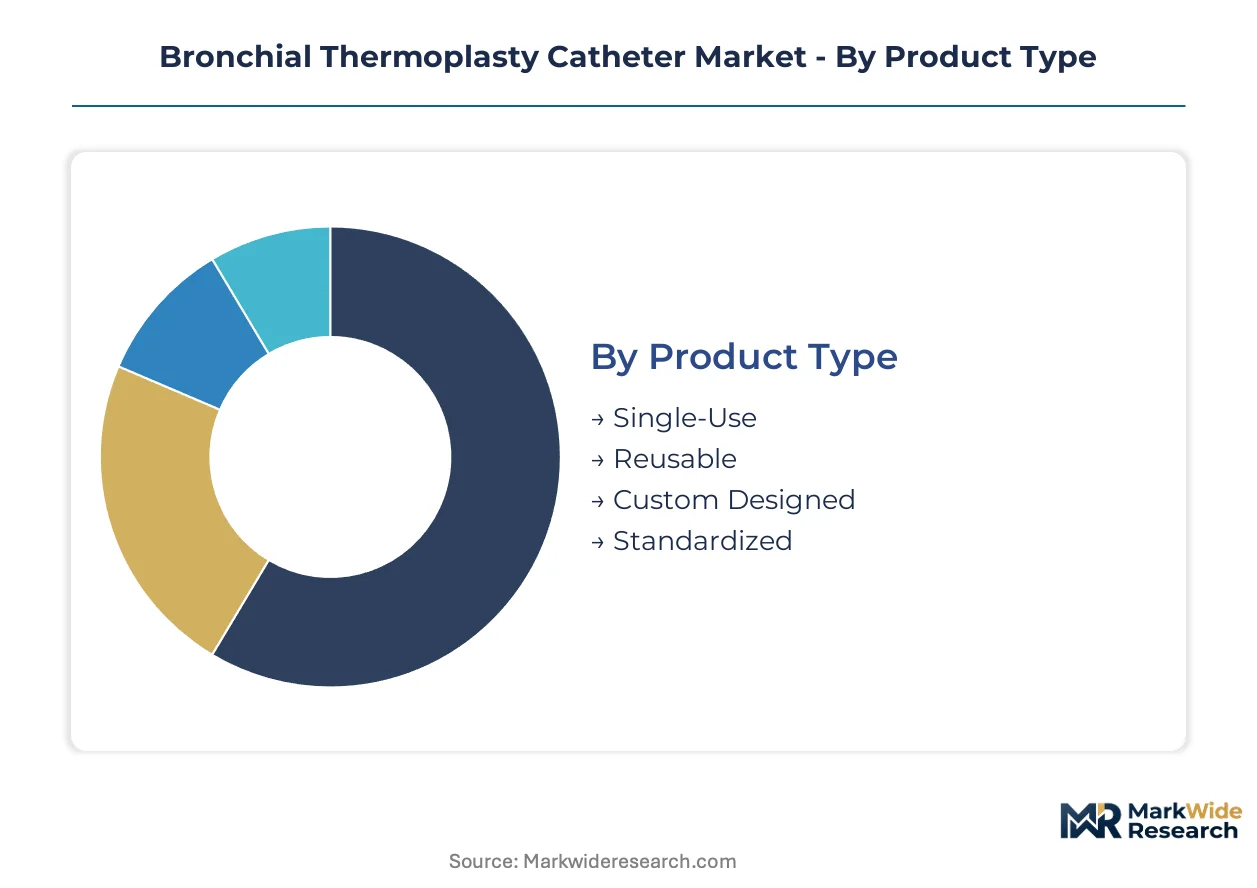
Segmentation in the bronchial thermoplasty catheter market reveals how regulatory pathways, clinical settings, and energy delivery mechanisms partition commercial opportunity. Each dimension carries distinct certification burdens and reimbursement implications that shape manufacturer prioritization and hospital procurement decisions.
Product Type:
FDA premarket approval and EMA MDR Article 117 conformity assessments apply differentially across reusability tiers, with single-use designs facing heightened traceability mandates under post-market surveillance rules.
- Single-Use:Polymer-based disposable catheters with embedded radiofrequency electrodes dominate hospital procurement in the United States and Germany. Infection control protocols and device-level UDI requirements under EMA MDR eliminate reusable alternatives in most European tertiary centers.
- Reusable:Sterilizable catheter platforms with detachable electrode arrays persist in limited Japanese academic settings where METI efficiency directives emphasize capital equipment longevity. PMDA quality management system inspections impose compliance costs that constrain commercial viability.
- Custom Designed:Patient-specific geometries for complex airway anatomies serve niche research applications at select academic medical centers.
- Standardized:Uniform catheter specifications enable volume manufacturing scale and streamlined regulatory dossiers for broad commercial distribution.
Single-Use sits at the top of the volume ranking, with Custom Designed climbing the fastest as personalized medicine protocols expand.
End User:
Cost tier stratification separates capital-intensive interventional suites from outpatient channels, with reimbursement differentials determining addressable patient volumes across facility types.
- Hospitals:Tertiary pulmonary departments with dedicated bronchoscopy suites generate the majority of procedure volumes in the United States, Germany, and Japan. CMS national coverage determinations and German G-BA assessments directly constrain catheter purchasing commitments through procedural reimbursement ceilings.
- Outpatient Clinics:Ambulatory bronchoscopy centers in Japan are expanding under METI healthcare efficiency directives that incentivize same-day procedures previously reserved for inpatient settings.
- Specialty Care Centers:Focused respiratory disease facilities concentrate severe asthma expertise and interventional pulmonology training pipelines.
- Academic Institutions:University-affiliated medical centers pilot hybrid thermal-imaging systems and train certified operators for next-generation catheter platforms.
Hospitals anchor revenue concentration, though Outpatient Clinics are gaining share fastest as procedural migration accelerates.
Application:
Clinical indication breadth determines regulatory evidence requirements, with severe asthma commanding the most extensive PMA and MDR technical documentation packages.
- Severe Asthma:Radiofrequency ablation of airway smooth muscle in refractory patients constitutes the primary approved indication. FDA PMA supplements and EMA post-authorization study commitments demand sustained clinical evidence generation for label maintenance.
- Chronic Obstructive Pulmonary Disease:Investigational applications in COPD bronchospasm management are expanding addressable populations beyond conventional asthma candidate criteria.
- Other Respiratory Disorders:Bronchiectasis and chronic cough syndromes represent exploratory targets with limited reimbursement coverage.
- Clinical Research:Academic-sponsored trials for novel energy delivery parameters and imaging integration protocols drive early-stage catheter consumption.
Severe Asthma dominates procedure volumes, with Clinical Research showing the steepest expansion trajectory as hybrid system validation intensifies.
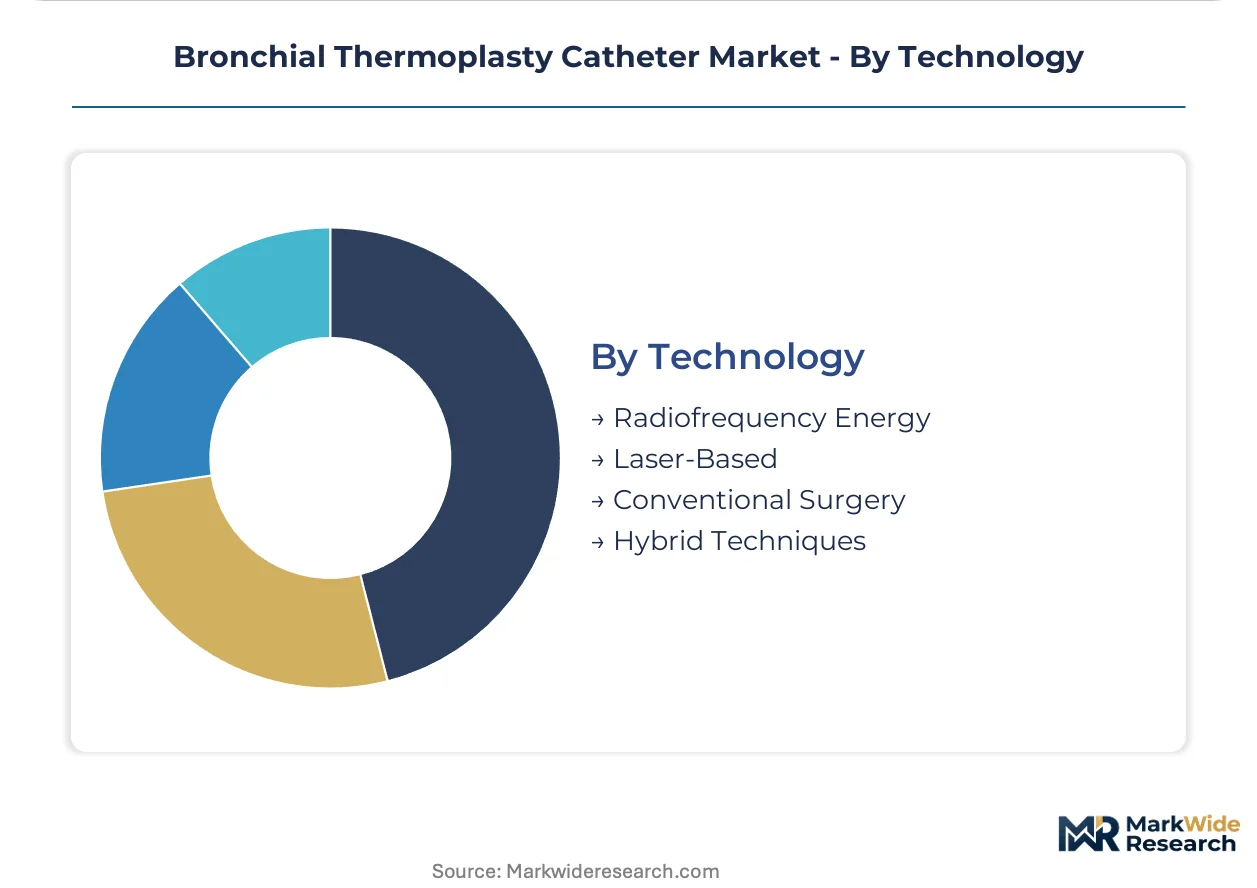
Technology:
Margin profiles diverge sharply between established radiofrequency platforms and emerging hybrid architectures that combine thermal delivery with real-time feedback systems.
- Radiofrequency Energy:Controlled 65°C thermal ablation via flexible bronchoscope-compatible electrodes represents the commercial standard. Boston Scientific and Medtronic anchor their interventional pulmonology portfolios on proprietary energy delivery algorithms and electrode geometries.
- Hybrid Techniques:Integrated radiofrequency-optical coherence tomography systems enable real-time airway wall thickness measurement during ablation. German and United States academic centers pilot these platforms to reduce procedure time and complication rates.
- Laser-Based:Photothermal ablation alternatives face technical challenges in controlled tissue penetration depth for airway applications.
- Conventional Surgery:Non-energy surgical bronchoplasty retains minimal relevance as catheter-based interventions displace open approaches.
Radiofrequency Energy maintains volume leadership, while Hybrid Techniques are climbing fastest as precision safety profiles expand qualified operator pools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Japan present contrasting procurement environments, with German hospital networks emphasizing EMA MDR compliance while Japanese facilities prioritize METI efficiency metrics. The United States anchors procedure volume through CMS reimbursement structures, though coverage determinations vary by Medicare Administrative Contractor jurisdiction.
United States
Tertiary pulmonary departments in Cleveland Clinic and Mayo Clinic networks drive catheter consumption through dedicated interventional bronchoscopy suites. FDA premarket approval pathways for class III airway devices demand extensive clinical evidence packages that extend commercialization timelines. The Boston-Cambridge corridor concentrates medical device R&D activity, with academic medical centers piloting hybrid thermal-imaging integration protocols.
Germany
University hospitals in Munich and Heidelberg generate substantial procedure volumes under G-BA reimbursement assessments that cap per-procedure compensation. EMA Medical Device Regulation Article 117 conformity assessments now require notified body involvement for all class III devices, extending pre-market timelines. The Baden-Württemberg region hosts specialized interventional pulmonology training programs that feed qualified operators into hospital networks across Bavaria and North Rhine-Westphalia.
Japan
Academic medical centers in Tokyo and Osaka maintain the highest concentration of certified bronchial thermoplasty operators in Asia-Pacific. PMDA foreign manufacturer registration requirements impose quality management system inspection obligations that filter market entrants. METI healthcare efficiency directives are shifting procedural volume toward ambulatory settings in Kansai region clinics previously restricted to inpatient bronchoscopy.
United Kingdom
NHS England specialized commissioning frameworks determine access to bronchial thermoplasty through designated respiratory centers in London, Manchester, and Birmingham. MHRA post-Brexit regulatory alignment with EMA MDR standards maintains conformity assessment requirements for class III airway devices. The Oxford-Cambridge-London golden triangle concentrates clinical research activity evaluating next-generation catheter platforms.
France
HAS health technology assessment procedures evaluate bronchial thermoplasty coverage through academic hospital networks in Paris, Lyon, and Marseille. ANSM market surveillance requirements align with EMA MDR post-market vigilance obligations for energy-delivering airway devices. The Île-de-France region maintains the densest concentration of interventional pulmonology suites outside Germany, with procedural volumes concentrated at AP-HP institutions.
Bronchial Thermoplasty Catheter Market Vendor Landscape
Top-tier vendors anchor technology leadership through proprietary radiofrequency energy delivery systems, while mid-tier specialists compete on regional regulatory expertise and catheter customization capabilities. The vendor base stratifies across three archetypes: diversified medical technology conglomerates with interventional pulmonology portfolios, specialized electrosurgical device manufacturers, and academic spin-outs commercializing hybrid imaging-thermal platforms. Competitive dynamics center on M&A activity targeting complementary energy delivery patents and strategic partnerships with academic medical centers for clinical evidence generation.
Among diversified medical technology conglomerates, Boston Scientific Corporation and Medtronic plc occupy positions exemplifying scale-driven competitive strategy, while Johnson & Johnson represents the integrated healthcare holding company archetype. These entities anchor market structure through established FDA PMA dossiers and EMA MDR technical documentation portfolios. Olympus Corporation, originating from precision optical instrumentation, exemplifies the imaging-technology crossover archetype pursuing hybrid catheter platform development. The competitive terrain rewards manufacturers with sustained compliance investment capacity across FDA, EMA, and PMDA jurisdictions.
| Leading Market Players |
|---|
| Teleflex Incorporated |
| Johnson & Johnson |
| Boston Scientific Corporation |
| Smith & Nephew plc |
| Abbott Laboratories |
| Medtronic plc |
| Cook Medical LLC |
| Merit Medical Systems, Inc. |
| Olympus Corporation |
| Others |
Supply Flow & Price Mechanics
Polymer resin indices and precious metal electrode benchmarks cascade through East Asian manufacturing clusters into finished catheter pricing tiers, with single-use disposable premiums widening as infection control mandates harden across FDA and EMA jurisdictions.
Pricing Analysis
Capacity additions in South Korean and Chinese polymer compounding facilities are reshaping price floors for catheter substrates while RF electrode coatings remain concentrated in Japanese and German metallurgy shops. Three-tier pricing structure across premium hybrid-imaging systems, standard radiofrequency platforms, and economy single-use disposables reflects certification grade differentiation and after-sales service bundling. Cost compression in the economy tier is intensifying because GPO consolidation in the United States extracts volume discounts from manufacturers. Outpatient clinics in Japan exhibit the highest price sensitivity as METI efficiency directives cap procedural reimbursements, while academic medical centers in Germany and the United States prioritize clinical performance over unit economics.
Supply Chain Analysis
Domestic-content mandates in Japan's METI medical device procurement guidelines and emerging Buy American preferences in CMS-covered hospital purchasing are reshaping sourcing patterns for catheter assembly. Manufacturing concentrates in China, South Korea, and Malaysia for polymer extrusion and electrode subassembly, with final sterilization and packaging anchored in Germany and the United States. Raw material dependencies center on medical-grade polyether block amides, platinum-iridium electrode alloys, and ethylene oxide sterilization gases. Single-source vulnerability in East Asian polymer feedstock exposes margins to logistics chokepoint risk. Distribution runs through integrated delivery networks and group purchasing organizations that displace direct manufacturer relationships at individual pulmonary departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bronchial thermoplasty catheter demand compounds steadily as severe asthma prevalence in hospital settings drives procedural volume expansion across interventional pulmonology suites in the United States, Germany, and Japan.
For Market Incumbents: Cement technology leadership by deepening backward integration into RF energy delivery algorithm development and capturing hybrid imaging-thermal system patents before competitors. Biologic therapy substitution for severe eosinophilic asthma poses the most immediate threat to addressable patient populations. Channel control through exclusive GPO contracting represents the critical defensive lever. For New Entrants and Emerging Players: Ambulatory surgery centers in Japan's Kansai region offer the most penetrable white-space target as METI directives shift procedural volume away from inpatient settings. Academic medical centers piloting next-generation catheter platforms present a secondary entry vector through research supply agreements. A reimbursement strategy anchored to outpatient procedure economics enables faster hospital purchasing committee adoption than premium positioning. For Investors and Strategic Acquirers: Consolidation pressure builds where EMA MDR compliance costs filter subscale manufacturers from European markets. The five-to-ten year viability window favors platforms with established FDA PMA dossiers and hybrid technology roadmaps. Acquisition targets should demonstrate proprietary RF electrode geometries or OCT integration capabilities. The signal to watch is CMS national coverage determination expansion for outpatient bronchial thermoplasty procedures, which would trigger hospital capital commitment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | Extensive clinical evidence packages for class III airway devices secure commercialization timelines and reimbursement eligibility. |
| CE Marking Fast-Track Pathway | EMA breakthrough device designations compress time-to-revenue for qualified asthma innovations with demonstrated clinical superiority. |
| Hospital System Partnership | GPO contracts at Cleveland Clinic and Mayo Clinic networks anchor volume commitments and displace competitor relationships. |
| Software Companion Development | AI-guided ablation algorithms with predictive tissue response modeling differentiate hybrid platforms from standalone catheters. |
| Reimbursement Strategy | CMS coverage determination alignment and German G-BA assessment navigation dictate hospital purchasing committee approval. |
Methodological Framework
Bottom-up hospital procurement modeling reconciled against top-down catheter production tracking forms the analytical core of this study. Primary interviews with interventional pulmonologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers combined with secondary validation from FDA PMA filings, EMA MDR technical documentation databases, CMS national coverage determination records, and hospital procurement databases. Triangulation between demand-side procedure volume estimates and supply-side manufacturing capacity assessments ensures analytical coherence.
Input-output matrices map catheter consumption across reusability tiers, end-user facility types, clinical applications, and energy delivery technologies throughout the projection horizon. Segmentation dimensions include product architecture, procedural setting, indication breadth, and technology platform, with CAGRs derived from installed base expansion rates and replacement cycle dynamics. Forecast inputs incorporate interventional pulmonologist training pipeline capacity, regulatory approval timeline assumptions, and reimbursement coverage evolution patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to biologic therapy substitution rates, CMS coverage determination revisions, and EMA MDR post-market surveillance enforcement intensity. Forecasts reflect documented assumptions regarding procedural migration to outpatient settings and hybrid imaging-thermal system adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Smart Medical Loupes Market
Medical Devices
Canada Digital X-Ray Devices Market
Medical Devices
Tissue Sectioning Market
Medical Devices
Global Over-The-Wire Micro-Guide Catheter Market
Medical Devices
Global Medical Cannula Market
Medical Devices
Global Brain Monitoring Devices Market
Medical Devices
3D Printing in Healthcare Market
Medical Devices
Global Cardiac Holter Monitor Market
Medical Devices
Global Extremities Market
Medical Devices
Anesthesia Circuits Market
Medical Devices
Sweden Minimally Invasive Surgery Devices Market
Medical Devices
Micro Balloon Catheter Market
Medical Devices
Radiofrequency Skin Rejuvenation Devices Market
Medical Devices
Phakic Intraocular Lenses (IOL) Market
Medical Devices
Chordal Suture Systems Market
Medical Devices
Thoracolumbar Spine Devices Market