
 Ankle Mobile Bearing System Market | 2026-2036
Ankle Mobile Bearing System Market Size, Share, and Industry Trends Forecast 2026-2036
Ankle Mobile Bearing System Market Intelligence
A transition from single-source to multi-source component procurement is expanding supply chain resilience for original equipment manufacturers. Stryker Corporation leverages its extensive distribution network to maintain a significant market presence. Enovis Corporation differentiates through its focus on clinical outcomes and surgeon education programs. Meanwhile, Zimmer Biomet Holdings Inc. competes with a broad portfolio of orthopedic solutions, including both mobile and fixed-bearing ankle systems.
An ankle mobile bearing system is a total ankle arthroplasty device designed to restore joint function. It features a polyethylene insert that moves freely between the metal tibial and talar components, aiming to replicate natural ankle kinematics. The Mobile Bearing technology segment dominates due to its perceived benefits in range of motion. Within applications, treatment for Osteoarthritis represents a primary volume driver, with procedures increasingly performed in Specialized Hospitals and Ambulatory Surgery Centers.
Regulatory frameworks from bodies like the U.S. FDA and the European Medicines Agency under the MDR are critical. These agencies mandate rigorous pre-market approval processes, including clinical trials demonstrating safety and efficacy, and enforce post-market surveillance. For manufacturers, successfully navigating evolving reimbursement policies and demonstrating long-term implant survivorship will determine future market position.
Market Dynamics
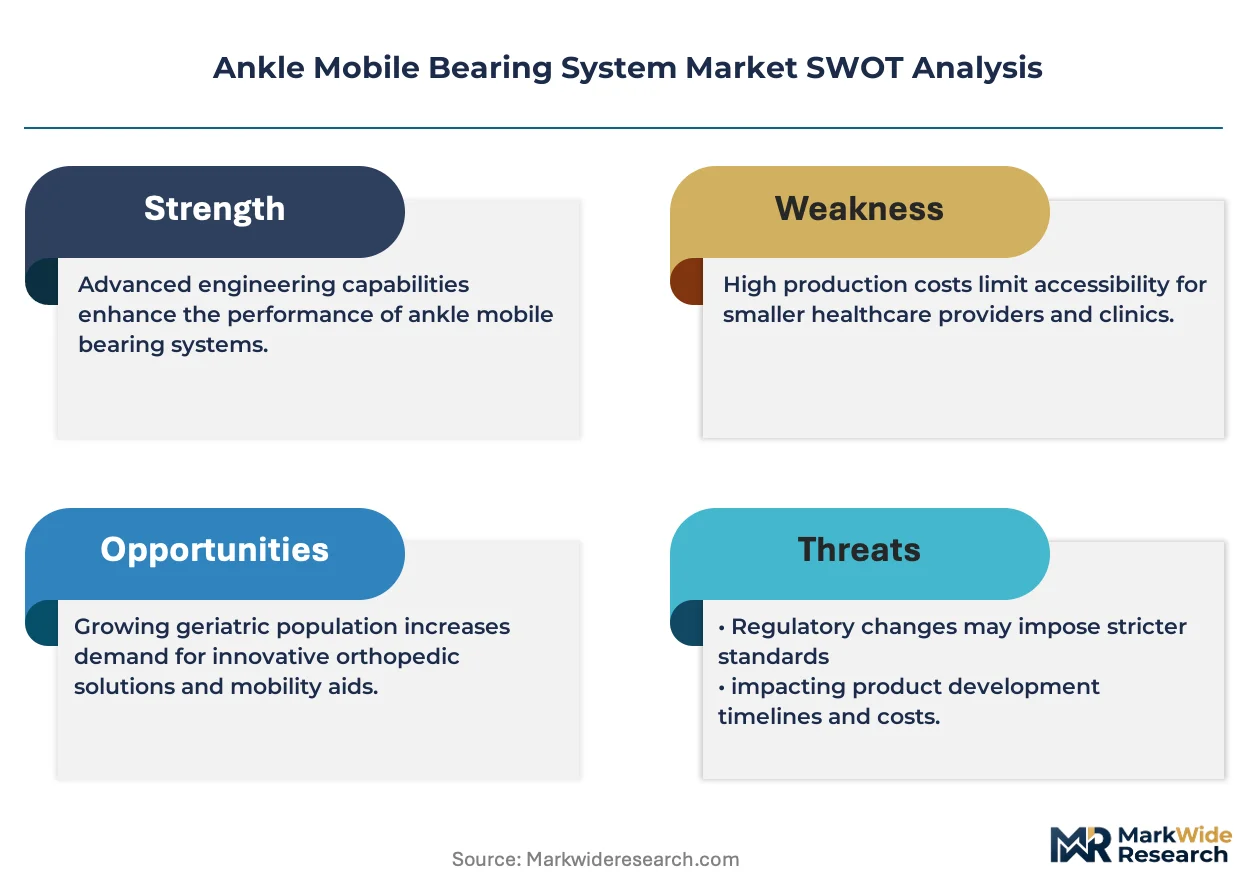
The central dynamic in the ankle mobile bearing system market is the intensified regulatory demand for long-term implant survivorship data. Agencies like the U.S. FDA and European bodies under the MDR are compelling manufacturers to prove device longevity, shifting competitive focus from initial surgical outcomes to documented, multi-year performance.
Growth Catalysts
- Advances in Polyethylene:Innovations in ultra-high-molecular-weight polyethylene (UHMWPE), specifically through antioxidant stabilization and enhanced cross-linking, are reducing wear debris and improving the long-term durability of the bearing surface.
- Procedure Shift to ASCs:The migration of total ankle arthroplasty procedures to ambulatory surgery centers (ASCs) in the United States creates demand for systems with efficient, streamlined instrumentation and proven reproducible outcomes.
- Aging Global Population:Increasing rates of osteoarthritis and post-traumatic arthritis in aging populations, particularly in developed nations like Germany and Japan, provide a consistent patient volume for ankle replacement procedures.
Market Restraints
- High Procedure and Implant Cost:The significant cost associated with total ankle arthroplasty, including the implant itself and requisite hospital services, acts as a barrier to patient access in healthcare systems with limited reimbursement coverage.
- Risk of Aseptic Loosening:Despite material improvements, aseptic loosening of the talar or tibial components remains a primary failure mechanism, representing a key technical limitation that can necessitate complex revision surgery.
- Stringent Regulatory Pathways:The Premarket Approval (PMA) process required by the U.S. FDA for Class III devices is exceptionally rigorous and costly, which can deter smaller innovators from entering the market.
Strategic Opportunities
- Patient-Specific Instrumentation:Leveraging 3D printing to create patient-specific cutting guides and instruments offers an opportunity to improve surgical accuracy, reduce operative time, and potentially improve implant alignment and long-term outcomes.
- Expansion in Asia-Pacific:Markets such as South Korea and Australia, with their sophisticated healthcare infrastructure and growing elderly populations, represent underpenetrated geographies for mobile bearing ankle system manufacturers.
- Revision-Specific Systems:Developing dedicated mobile bearing systems designed to address the unique challenges of revision arthroplasty, such as significant bone loss and ligamentous instability, opens a specialized clinical market segment.
Industry Challenges
- Specialized Surgeon Training Curve:Achieving optimal patient outcomes with total ankle arthroplasty is highly dependent on surgeon experience, creating a significant challenge related to training, proctoring, and ensuring consistent results across a broad user base.
- Long-Term Clinical Data Collection:Fulfilling post-market surveillance mandates from regulators like the EMA requires manufacturers to establish and maintain costly, long-term patient registries to track implant performance and adverse events.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ankle Mobile Bearing System Market |
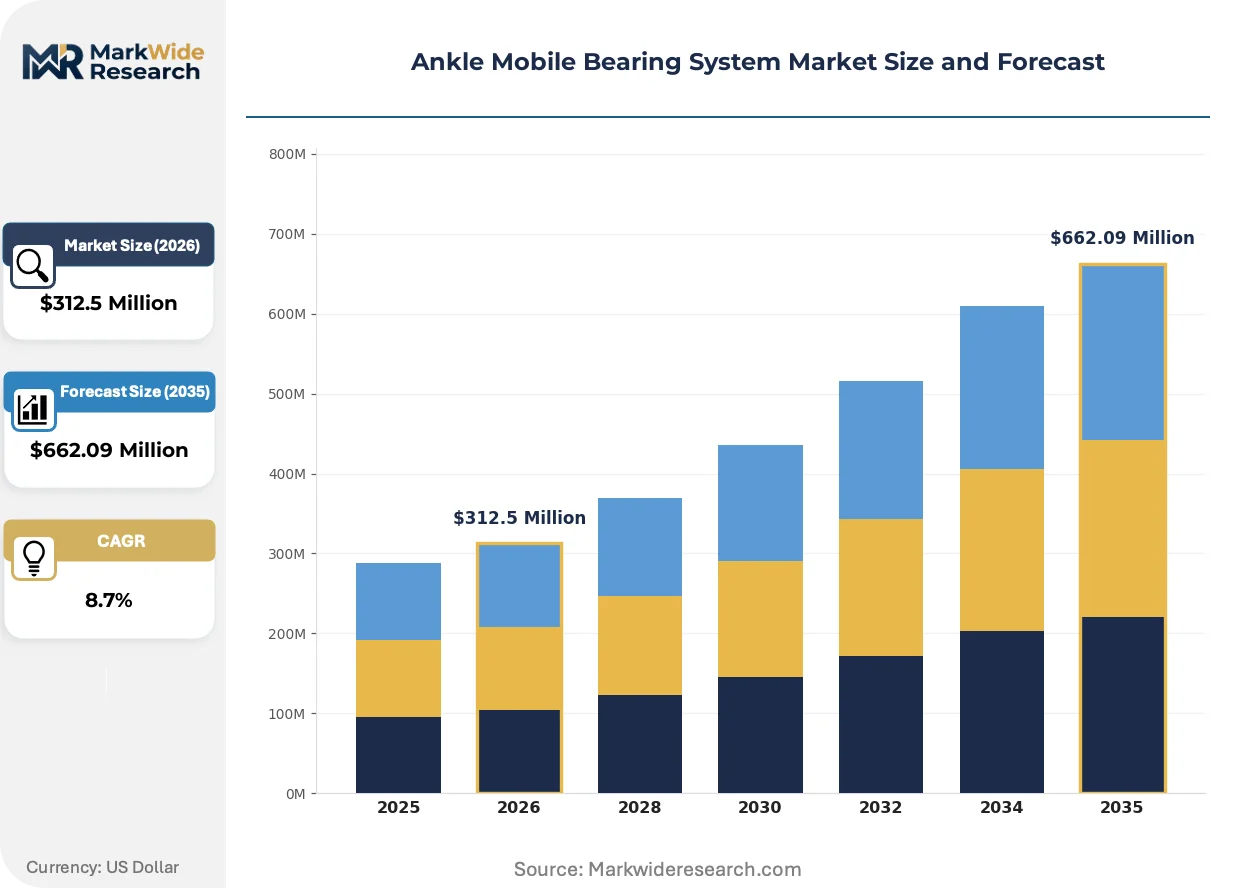
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $662.09 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Uncemented Prosthesis, Cemented Prosthesis, Cementless Prosthesis, Hybrid Prosthesis Technology: Mobile Bearing, Fixed Bearing, Semi-mobile Bearing, Dual Mobility Application: Post-Traumatic Arthritis, Rheumatoid Arthritis, Osteoarthritis, Avascular Necrosis End User: Orthopedic Clinics, Rehabilitation Centers, Specialized Hospitals, Ambulatory Surgery Centers |
| Companies Covered | Enovis Corporation, Paragon 28 Inc, Stryker Corporation, MatOrtho Limited, FH Orthopedics, Zimmer Biomet Holdings Inc, Exactech Inc, Corin Group PLC, Smith And Nephew plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ankle Mobile Bearing System Market Strategic Shifts & Innovations
The market is moving toward a model of evidence-based personalization, where device selection and surgical technique are increasingly informed by patient-specific anatomy and objective performance data. This shift prioritizes technologies that enhance implant-to-bone integration and provide measurable post-operative feedback on joint function.
Additive manufacturing enables the production of metal tibial and talar components with porous, lattice-like structures designed to mimic cancellous bone and promote biological fixation. Specialized orthopedic centers and academic hospitals are adopting these 3D-printed implants for complex cases requiring enhanced stability. This technology is expanding into the development of patient-specific surgical guides, which aim to increase the precision of bone cuts and implant positioning.
The European Union's Medical Device Regulation (MDR) has substantially increased the requirements for clinical evidence and lifecycle management of medical devices. This regulatory shift is forcing manufacturers to invest heavily in prospective clinical studies and robust post-market surveillance systems to maintain CE marking for their ankle systems. The implant segment most affected is new devices, which now face a much higher bar for market entry compared to implants with legacy data from national registries.
A transition toward value-based healthcare models is altering how hospitals select and purchase orthopedic implants. This change disrupts traditional purchasing based purely on price, instead favoring systems that can demonstrate superior long-term survivorship and lower overall episode-of-care costs. This procurement behavior is most prominent within large, integrated health networks in the United States and public healthcare systems in the United Kingdom.
Ankle Mobile Bearing System Market Segmentation
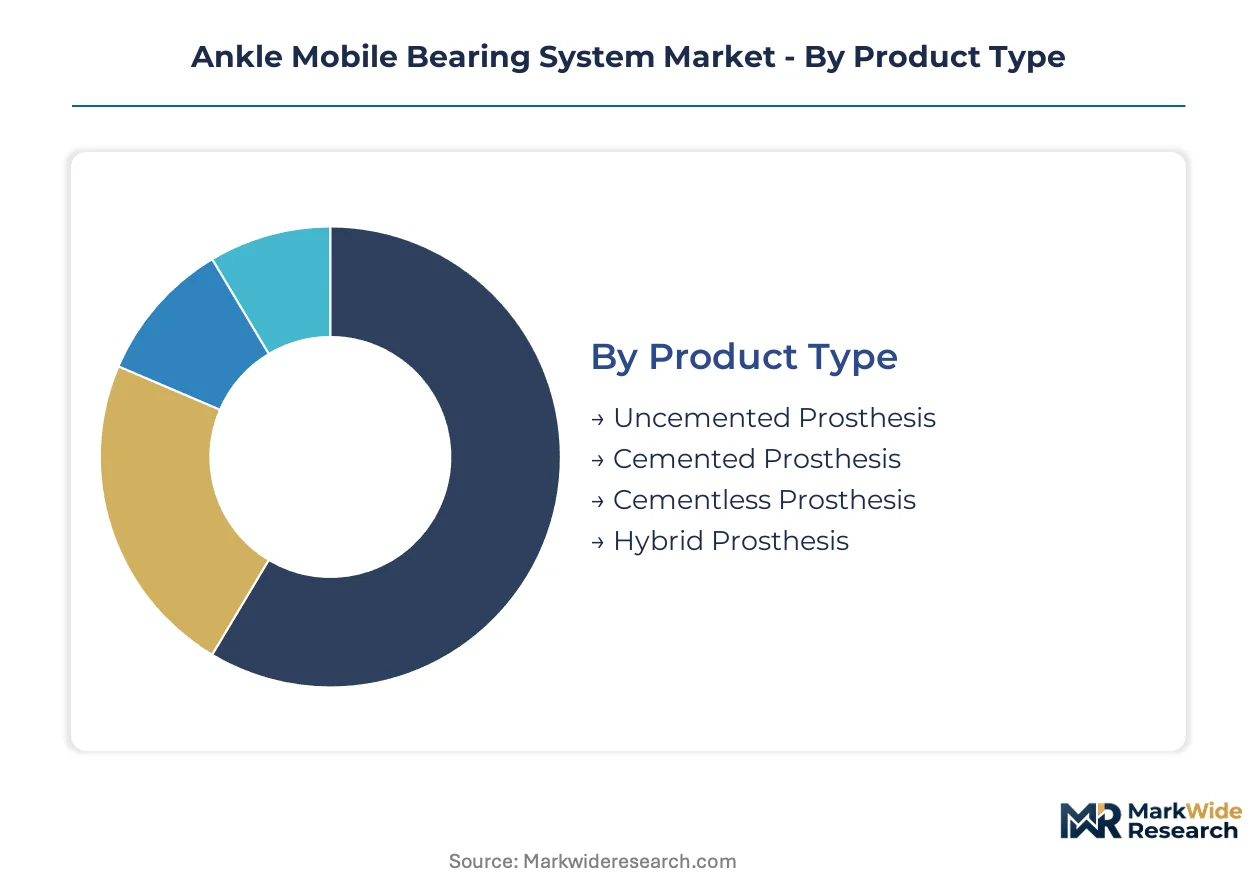
Market segmentation provides a granular view of the ankle mobile bearing system landscape, delineating distinct product characteristics, technological approaches, clinical applications, and end-user settings. This detailed breakdown highlights areas of concentrated demand and evolving preference across different healthcare environments.
Product Type:
The product type segmentation reveals how material composition and fixation methods influence adoption, splitting demand between high-volume standard solutions and premium, patient-specific implants.
- Uncemented Prosthesis:These implants rely on bone ingrowth for fixation, often featuring porous coatings to encourage biological integration directly with the patient's bone. Demand for uncemented systems is strong in developed markets like the United States, where long-term fixation and reduced revision rates are prioritized.
- Cementless Prosthesis:Cementless designs utilize surface treatments and specific implant geometries to achieve immediate mechanical stability and promote secondary biological fixation without bone cement. These systems are gaining traction for patient-specific applications and in younger, active patient populations aiming for durable outcomes.
- Cemented Prosthesis:Traditional cemented implants use bone cement for immediate and secure fixation, providing stability for patients with compromised bone quality or specific anatomical challenges.
- Hybrid Prosthesis:Hybrid systems combine cemented and uncemented components, typically cementing one component (e.g., tibial) and allowing bone ingrowth for the other (e.g., talar) to optimize fixation based on bone stock.
Mature deployment sits with Cemented Prosthesis. Newer deployment is concentrated in Cementless Prosthesis.
Technology:
Technological differentiation within ankle mobile bearing systems centers on the articulation mechanism, impacting joint kinematics and long-term implant performance.
- Mobile Bearing:This technology features a polyethylene insert that moves freely between metal tibial and talar components, designed to replicate natural ankle motion and reduce stress on fixation interfaces. Demand for mobile bearing systems dominates due to perceived advantages in range of motion and reduced wear debris.
- Fixed Bearing:Fixed bearing systems employ a rigid articulation where the polyethylene insert is secured to one of the metal components, providing inherent stability but with potentially less kinematic freedom. These systems are often chosen for their simplicity and established clinical track record in specific patient cohorts.
- Semi-mobile Bearing:Semi-mobile designs offer a compromise between fixed and mobile systems, allowing limited movement of the polyethylene insert to balance stability with some degree of kinematic flexibility.
- Dual Mobility:Dual mobility systems incorporate two articulation surfaces to enhance stability and range of motion, often featuring a small polyethylene head articulating within a larger polyethylene liner, which then articulates with a metal shell.
The Mobile Bearing segment represents the fastest-growing trajectory. Fixed Bearing technology maintains a stable market presence.
Application:
The application segment details the specific etiologies driving demand for total ankle arthroplasty, reflecting the diverse patient populations served by these devices.
- Osteoarthritis:This degenerative joint disease is a primary volume driver for ankle replacement procedures, particularly prevalent in aging populations across developed nations such as Germany and Japan. The increasing incidence of osteoarthritis consistently fuels demand for mobile bearing systems.
- Post-Traumatic Arthritis:Arthritis resulting from previous ankle injuries represents a significant application segment, often requiring complex surgical solutions due to altered anatomy and bone defects. The adoption of mobile bearing systems in ambulatory surgery centers for these cases is a key growth catalyst.
- Rheumatoid Arthritis:This autoimmune inflammatory condition can severely damage ankle joints, necessitating arthroplasty to alleviate pain and restore function in affected individuals.
- Avascular Necrosis:Avascular necrosis of the talus, characterized by bone death due to interrupted blood supply, creates demand for ankle replacement when conservative treatments fail to preserve joint integrity.
Osteoarthritis procedures drive the largest volume. Post-Traumatic Arthritis is expanding most quickly.
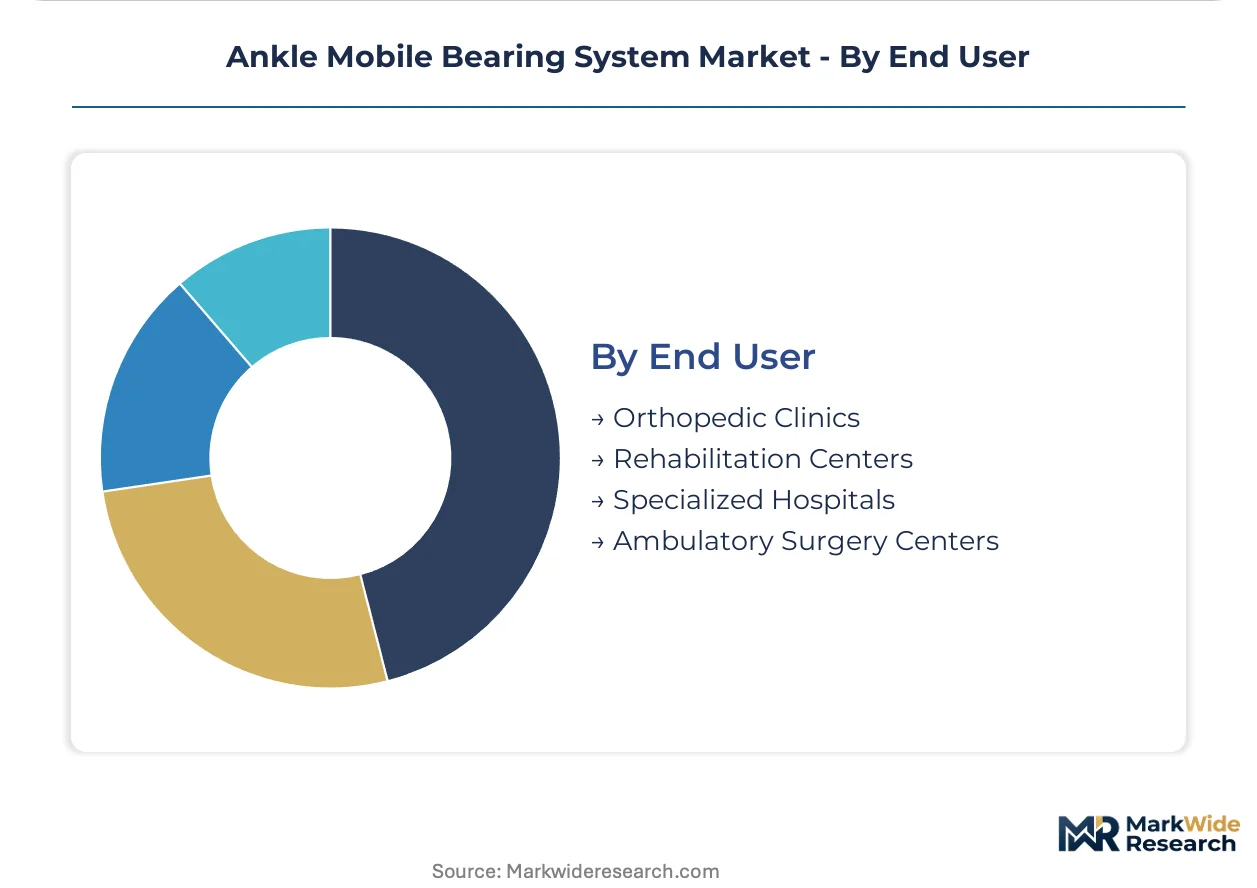
End User:
The end-user segmentation highlights the diverse healthcare settings where ankle mobile bearing systems are deployed, reflecting differing operational models and patient care pathways.
- Specialized Hospitals:These facilities handle complex orthopedic cases, often serving as referral centers for challenging ankle pathologies and revision surgeries requiring extensive resources and specialized surgical teams. Specialized hospitals frequently adopt advanced mobile bearing systems and patient-specific instrumentation.
- Ambulatory Surgery Centers:The migration of total ankle arthroplasty procedures to ASCs in the United States creates demand for streamlined systems with efficient instrumentation and reproducible outcomes. ASCs offer a cost-effective setting for suitable outpatient procedures, driving system design towards efficiency.
- Orthopedic Clinics:Orthopedic clinics primarily focus on diagnosis, non-surgical management, and pre-operative and post-operative care, often referring patients to specialized centers for surgical intervention.
- Rehabilitation Centers:Rehabilitation centers play a crucial role in post-surgical recovery, providing physical therapy and occupational therapy to optimize patient outcomes and restore ankle function following arthroplasty.
Ambulatory Surgery Centers are gaining share fastest. Specialized Hospitals maintain a dominant position for complex cases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States, with its advanced healthcare infrastructure and significant investment in medical device innovation, anchors demand for ankle mobile bearing systems. Developed economies consistently drive patient volume due to high rates of osteoarthritis and post-traumatic arthritis. Regulatory environments and reimbursement policies significantly influence market access and adoption across these regions.
United States
Rising incidence of post-traumatic arthritis and an aging population requiring joint replacement procedures stimulate demand for ankle arthroplasty. The U.S. FDA's rigorous Premarket Approval (PMA) process ensures device safety and efficacy, shaping product development. Major orthopedic centers in cities like Minneapolis-St. Paul and Warsaw, Indiana, concentrate research and manufacturing for advanced implant technologies.
Germany
A high prevalence of osteoarthritis in Germany's elderly population drives consistent demand for ankle mobile bearing systems. The European Medical Device Regulation (MDR) mandates extensive clinical evidence for device approval, influencing manufacturer investment in long-term studies. Munich and Berlin serve as key hubs for orthopedic surgery and medical technology innovation.
Japan
Japan's rapidly aging demographic and increasing awareness of advanced joint replacement options contribute to market expansion. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees stringent approval processes for medical devices, emphasizing clinical performance data. Tokyo and Osaka are significant centers for medical device distribution and specialized orthopedic treatment.
South Korea
Growing healthcare expenditure and a sophisticated medical technology sector underpin the expanding demand for ankle mobile bearing systems in South Korea. The Ministry of Food and Drug Safety (MFDS) regulates device market entry, requiring robust clinical documentation. Seoul's medical districts and university hospitals actively adopt new orthopedic surgical techniques.
Australia
Australia's well-developed healthcare system and increasing rates of sports-related ankle injuries sustain demand for advanced arthroplasty solutions. The Therapeutic Goods Administration (TGA) ensures high standards for medical device quality and safety. Melbourne and Sydney feature prominent orthopedic clinics and research facilities driving clinical adoption.
Ankle Mobile Bearing System Market Key Industry Players
Portfolio diversification dominates the current landscape, as manufacturers seek to offer comprehensive solutions across the orthopedic spectrum. The market exhibits a tiered structure, with large multinational corporations competing alongside specialized orthopedic device developers. Strategic partnerships and technology licensing agreements represent common competitive moves, alongside continuous product innovation.
Large, established players like Stryker Corporation and Zimmer Biomet Holdings Inc. exemplify the diversified orthopedic solution provider archetype, leveraging extensive product portfolios and global distribution networks. Enovis Corporation represents a firm focused on clinical outcomes and surgeon education, differentiating its offerings through specialized programs. These companies navigate complex regulatory pathways and invest in long-term clinical data collection to maintain their market positions.
| Leading Market Players |
|---|
| Enovis Corporation |
| Paragon 28 Inc |
| Stryker Corporation |
| MatOrtho Limited |
| FH Orthopedics |
| Zimmer Biomet Holdings Inc |
| Exactech Inc |
| Corin Group PLC |
| Smith And Nephew plc |
| Others |
Cost & Logistics Intelligence
Highly specialized orthopedic surgeons, particularly in developed markets, drive labor-cost differentials that contribute to pricing-tier spreads for ankle mobile bearing systems.
Pricing Analysis
Warranty and service bundling significantly influence pricing for ankle mobile bearing systems. The dominant pricing model leans towards value-based and contract-based long-term agreements, especially with large hospital networks. Price differentiation arises from demonstrated long-term implant survivorship, brand premium, and comprehensive surgeon education programs. Pricing softness stems from evolving reimbursement policies and the shift to cost-conscious ambulatory surgery centers, which are highly price sensitive compared to specialized hospitals prioritizing advanced solutions.
Supply Chain Analysis
Certification and qualification gating critically influence the supply chain for ankle mobile bearing systems. Supply concentration centers in developed healthcare markets like the United States, Germany, and Japan, leveraging robust R&D and manufacturing capabilities, while relying on specialized raw materials like ultra-high-molecular-weight polyethylene and medical-grade metal alloys. Stringent regulatory pathways, such as the U.S. FDA's PMA process and the EU MDR, create a significant structural risk. Distribution runs through extensive global networks, often leveraging direct sales forces and specialized orthopedic distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ankle mobile bearing system market is currently in a technology-transition phase, with advanced 3D-printed implants displacing legacy designs for enhanced bone integration.
For Market Incumbents: To counter the threat of stringent regulatory pathways and rising cost pressures, incumbents must deepen their commitment to long-term clinical data collection. Companies like Stryker Corporation should leverage their extensive distribution networks to expand surgeon education programs, ensuring consistent outcomes. Investing in next-generation ultra-high-molecular-weight polyethylene (UHMWPE) innovations will reduce aseptic loosening, a primary failure mechanism. Portfolio diversification across mobile and fixed-bearing systems also mitigates market shifts.
For New Entrants and Emerging Players: Begin with a focus on niche, high-value segments currently underserved by large players. Patient-specific instrumentation, leveraging 3D printing for surgical guides, offers a strong entry point by improving surgical accuracy. Target underpenetrated geographies like South Korea and Australia, emphasizing superior long-term outcomes for post-traumatic arthritis cases. A direct-to-surgeon go-to-market strategy, coupled with robust clinical evidence, can build early adoption and brand loyalty.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized orthopedic device developers given the sustained patient volume from aging populations and technological advancements. The long-term viability of the market is anchored by continuous innovation in implant materials and surgical techniques. Target acquisition archetypes include firms with strong intellectual property in patient-specific instrumentation or revision-specific systems. The signal to watch is the increasing adoption rates of 3D-printed components and patient-specific guides in ambulatory surgery centers.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in UHMWPE Innovations | Reduces wear debris and aseptic loosening, improving long-term durability for mobile bearing systems. |
| Develop Patient-Specific Instrumentation | Enhances surgical accuracy and implant alignment, critical for long-term outcomes in total ankle arthroplasty. |
| Expand Surgeon Education Programs | Improves consistent outcomes across a broad user base, addressing the specialized surgeon training curve. |
| Pursue Asia-Pacific Market Entry | Taps into underpenetrated geographies like South Korea with growing elderly populations and sophisticated healthcare. |
| Establish Long-Term Patient Registries | Fulfills post-market surveillance mandates from regulators like the EMA, demonstrating implant survivorship. |
Research Approach
Independent corroboration across U.S. FDA filings, EMA reports, and national orthopedic registries underwrites the qualitative findings. This approach combined primary interviews with orthopedic surgeons, hospital purchasing committees, and medical device engineers, with extensive secondary validation. Academic clinical trial databases also informed the analysis. Bottom-up data aggregation and top-down market sizing provided comprehensive triangulation.
Historical reference periods provided the foundation for projecting market dynamics across the analysis window. The analytical framework modeled segmentation dimensions including product type, technology, application, end user, and regional regulatory environments. Compound annual growth rates were calculated from historical trends and projected market drivers. Key forecast inputs included the increasing incidence rates of osteoarthritis and the growing adoption of total ankle arthroplasty in ambulatory surgery centers.
Underlying measurement precision varies by segment; mobile bearing technology and osteoarthritis applications carry tighter precision than others. Forecasts reflect assumptions regarding evolving reimbursement policies and new regulatory mandates. A model refresh is warranted upon material changes in implant survivorship data or healthcare infrastructure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Neurotech Devices Market
Medical Devices
Ultrasonic Electrosurgical Devices Market
Medical Devices
Europe Smart Bed Market
Medical Devices
Wearable Medical Robots Market
Medical Devices
Australia Respiratory Devices Market
Medical Devices
GCC and UAE Diabetes Devices Market
Medical Devices
Latin America Biomedical Sensors Market
Medical Devices
Medical Laser Cutting Device Market
Medical Devices
Blood Warmers Market
Medical Devices
Passive Prosthetics Market
Medical Devices
Breast Localization System Market
Medical Devices
Life Science Microscopy Devices Market
Medical Devices
Drainage Catheters Market
Medical Devices
Global Surgical Visualization Systems Market
Medical Devices
Postpartum Hemorrhage (PPH) Devices Market
Medical Devices
Global Surgical Navigation System Market