
 Electroencephalogram (EEG) Caps Market | 2026-2036
Electroencephalogram (EEG) Caps Market Size, Share, and Industry Trends Forecast 2026-2036
Electroencephalogram (EEG) Caps Market Foresight
High-density electrode arrays is bifurcating the competitive landscape into precision-oriented and cost-optimized tiers. Brain Products leverages German engineering standards to dominate research-grade instrumentation. ANT Neuro specializes in modular cap architectures for multimodal neuroimaging workflows. Natus Medical anchors North American hospital procurement through established clinical distribution channels.
An electroencephalogram cap is a wearable electrode array, typically constructed from elastic fabrics with embedded silver-silver chloride or conductive polymer sensors, designed to capture scalp electrical potentials with spatial resolutions ranging from 8 to 256 channels. Its primary commercial purpose is to enable non-invasive brain activity recording for clinical diagnostics, neuroscientific research, and emerging brain-computer interface applications. Reusable caps with wet electrode technology still occupy the largest installed base in hospital neurology departments, though disposable caps are gaining share in infection-sensitive settings. Wireless technology segments are expanding fastest in research facilities and home care environments where tethered setups limit experimental design or patient mobility.
FDA 510(k) clearance requirements and the EU MDR framework govern electrode biocompatibility, electrical safety, and clinical performance claims for EEG caps sold in the United States and European markets. ISO 13485 quality management certification has become a de facto threshold for supplier qualification in institutional procurement. The central bank and national health technology assessment bodies in Japan and South Korea are tightening reimbursement criteria for diagnostic EEG procedures. Stakeholders must monitor evolving regulatory convergence between FDA digital health guidance and EU AI Act implications for smart EEG algorithms before committing to multi-year product roadmaps.
Market Dynamics
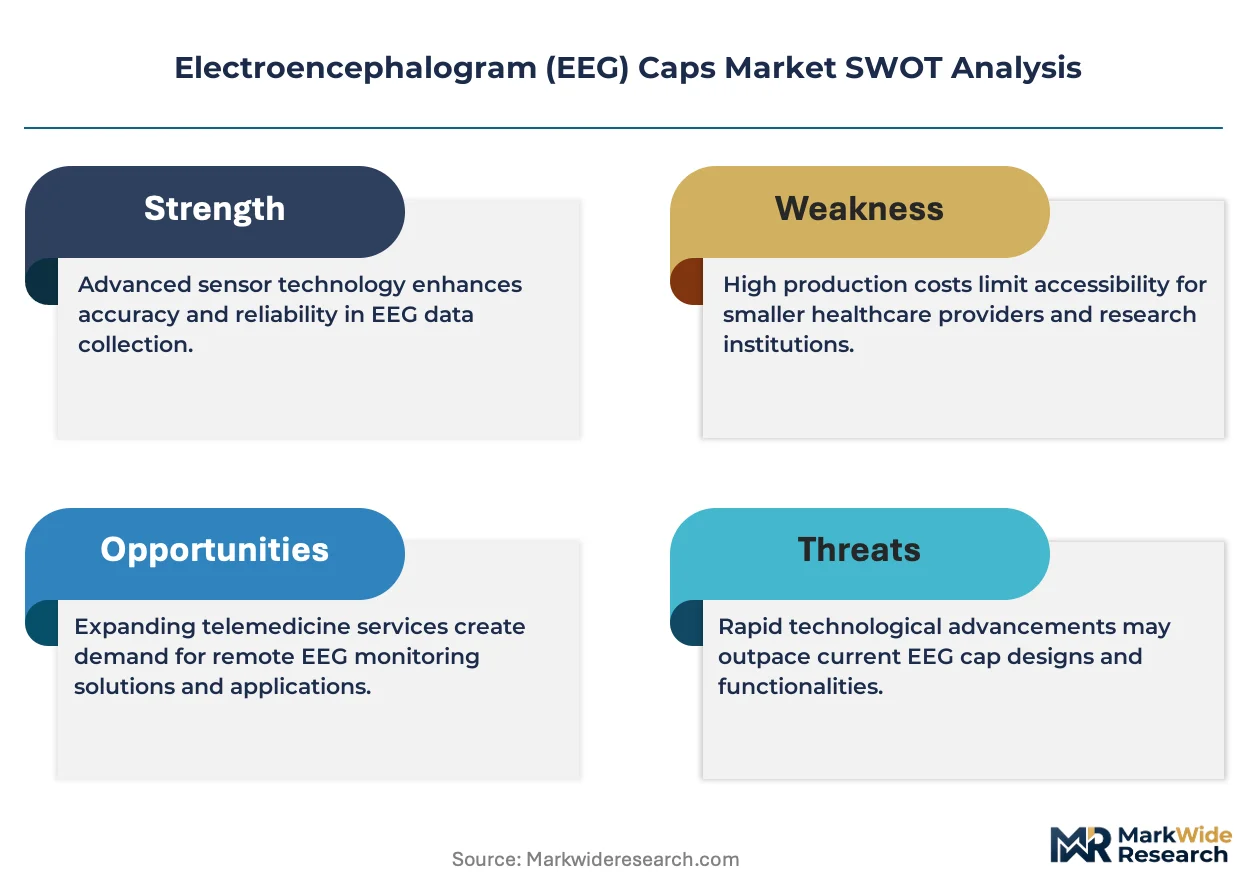
The EEG caps market is undergoing a bifurcation driven by high-density electrode arrays, which are splitting demand between precision-oriented research instrumentation and cost-optimized clinical screening tools. This technical divergence is reshaping supplier positioning across hospital systems and academic neuroscience departments.
Growth Catalysts
- Wet-to-dry electrode transition:Conductive polymer sensors eliminate gel application time, accelerating adoption in emergency neurology departments across United States hospital networks.
- EU MDR biocompatibility mandates:Stricter electrode material testing requirements under the Medical Device Regulation are filtering out non-compliant suppliers and consolidating procurement toward certified manufacturers.
- Home-based neurofeedback:Wireless Bluetooth-enabled caps are penetrating direct-to-consumer channels for ADHD and sleep disorder management in Japan.
Market Restraints
- Silver price volatility:Ag-AgCl electrode production remains exposed to precious metal commodity swings, compressing margins for reusable cap manufacturers.
- German supplier concentration:Precision electrode array fabrication clusters heavily in Baden-Württemberg, creating single-region supply vulnerability for high-channel-count systems.
- fMRI substitution in research:Functional magnetic resonance imaging captures deeper brain structures with superior spatial resolution, limiting EEG cap penetration in funded neuroscience grants.
Strategic Opportunities
- Pediatric epilepsy monitoring in India:Underpenetrated neurology infrastructure and rising diagnostic awareness create whitespace for disposable, infection-controlled cap formats.
- Brain-computer interface development:Convergence of EEG signal processing with machine learning algorithms is opening hardware supply contracts for consumer neurotechnology startups.
- South Korean reimbursement expansion:National Health Insurance Service coverage revisions for ambulatory EEG are stimulating procurement in Seoul metropolitan hospital chains.
Industry Challenges
- ISO 13485 certification timelines:Quality management system audits for new cap designs extend 14-18 months, delaying product launches and freezing R&D roadmaps.
- Electrode-site registration standardization:Inconsistent 10-20 system modifications across research institutions complicate multi-site data pooling and meta-analysis protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electroencephalogram (EEG) Caps Market |
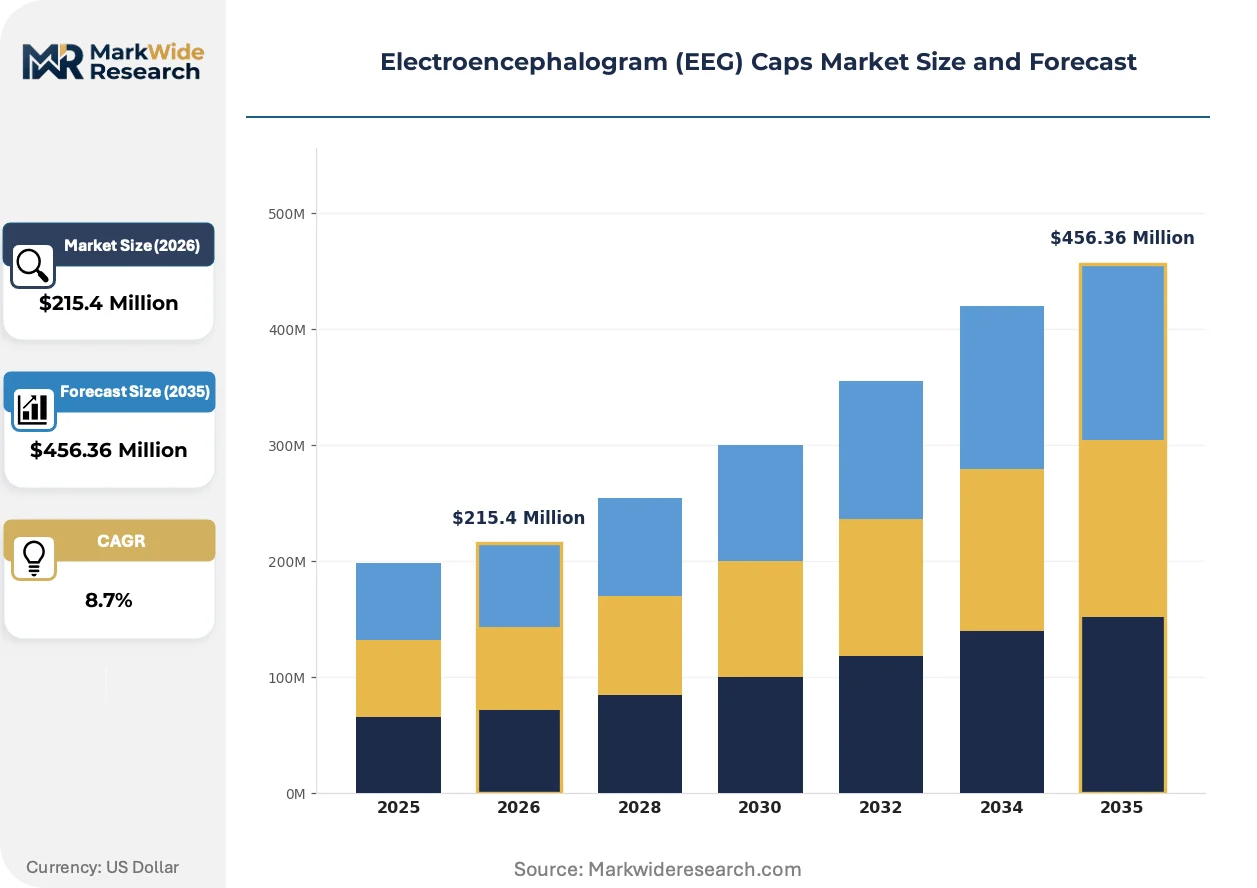
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $456.36 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable Caps, Reusable Caps, Standard Caps, High-Density Caps End User: Hospitals, Research Facilities, Neurology Clinics, Home Care Technology: Dry Electrode Technology, Wet Electrode Technology, Wireless Technology, Smart EEG Technology Application: Sleep Studies, Epilepsy Monitoring, Brain-Computer Interface, Cognitive Research |
| Companies Covered | Brain Products, ANT Neuro, Compumedics Neuroscan, BIOPAC Systems, Electro Cap, Natus Medical, Nihon Kohden, g.tec medical engineering, BioSemi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electroencephalogram (EEG) Caps Market Shifts & Advancements
Dry electrode architectures and embedded signal processing are converging to eliminate traditional laboratory constraints, enabling mobile brain monitoring across clinical and consumer contexts. These technical advances are compressing the boundary between medical-grade diagnostics and wellness applications.
Printed flexible electrode arrays are supplanting rigid disc sensors in next-generation cap designs. Research institutions in Germany and the Netherlands are piloting these conformal interfaces for extended-duration recordings. The shift is compressing setup times from 45 minutes to under 10 minutes while improving patient comfort during sleep studies.
EU AI Act algorithmic transparency requirements are forcing EEG software vendors to document training data provenance and decision logic for diagnostic support tools. Manufacturers selling into European hospital systems must now maintain technical documentation files covering bias testing and performance validation across demographic subgroups. Clinical-grade platforms are responding by segregating research and regulated software branches to isolate compliance costs.
Hospital procurement departments are unbundling cap hardware from software licenses and maintenance contracts, treating each as separate line items in competitive tenders. This disaggregation is pressuring bundled pricing models and favoring modular suppliers in United States group purchasing organization negotiations. Academic medical centers in Boston and San Francisco are leading this contractual decomposition, citing flexibility to swap analytics platforms without hardware replacement.
Electroencephalogram (EEG) Caps Market Segmentation
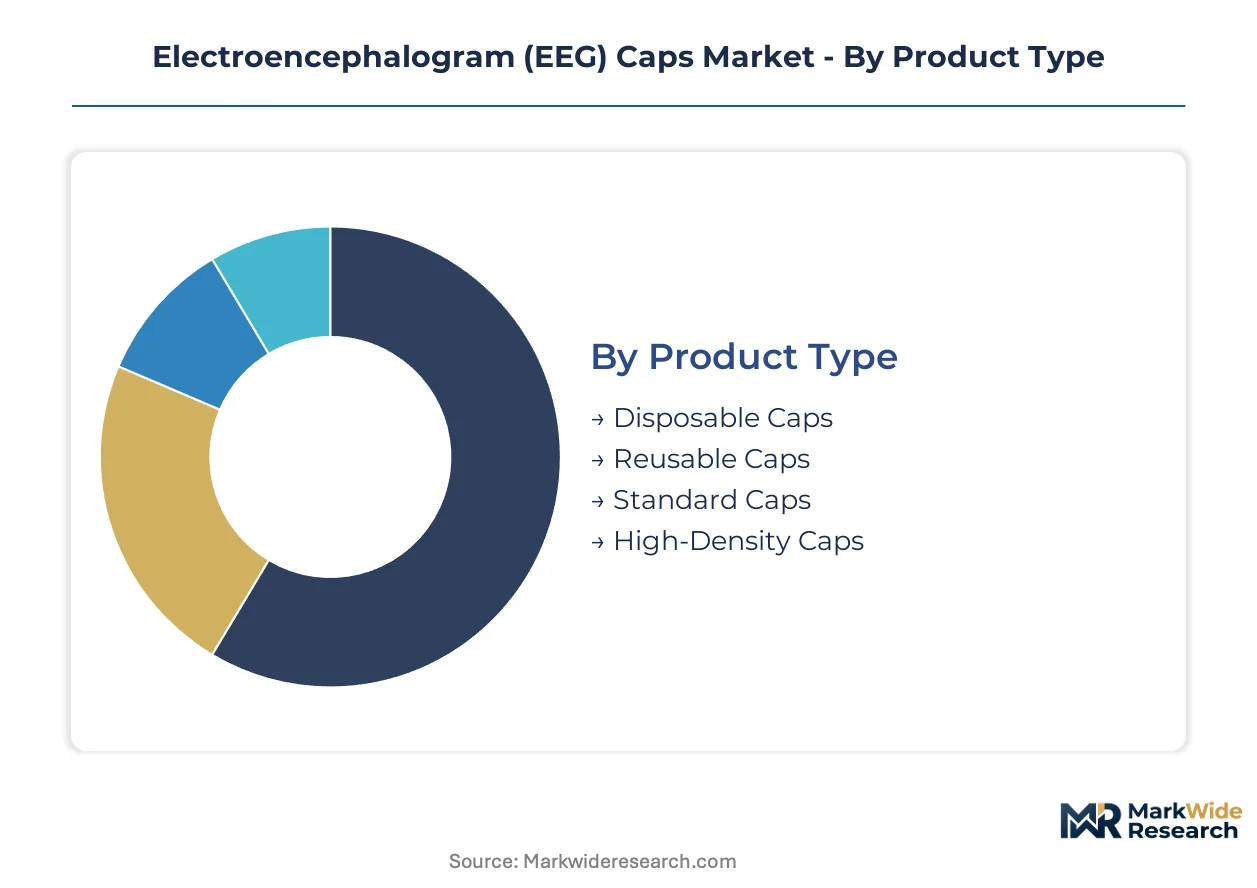
Segmentation in the EEG caps market reveals distinct procurement patterns across clinical and research channels. Each dimension—product format, end-user environment, electrode technology, and clinical application—carries unique regulatory requirements and margin structures that shape supplier positioning.
Product Type:
Channel mix varies sharply by reusability and electrode density, with hospital procurement favoring standardized formats while research facilities drive high-channel-count adoption.
- Reusable Caps:Constructed from elastic fabrics with embedded silver-silver chloride sensors, these caps withstand hundreds of cleaning cycles under hospital sterilization protocols. Demand concentrates in United States neurology departments where capital equipment budgets favor multi-year depreciation over per-use disposables.
- Disposable Caps:Single-use polymer assemblies with pre-gelled electrodes eliminate cross-contamination risk in infection-sensitive settings. German hospital networks are expanding procurement of these formats for emergency epilepsy monitoring where rapid turnaround between patients is critical.
- Standard Caps:8-32 channel configurations serve routine clinical screening with cost-optimized sensor placement.
- High-Density Caps:64-256 electrode arrays enable sub-centimeter spatial resolution for research applications requiring precise source localization.
By volume, standard caps lead in hospital procurement. By growth pace, high-density configurations are climbing the fastest as brain-computer interface development accelerates.
End User:
Cost tier stratification separates institutional buyers with centralized purchasing from direct-to-consumer channels where price sensitivity dominates.
- Hospitals:Integrated delivery networks in Japan and Germany negotiate multi-year supply agreements with ISO 13485-certified manufacturers. These contracts bundle cap hardware with maintenance and electrode replenishment.
- Research Facilities:Academic neuroscience departments prioritize signal fidelity and customization flexibility over unit cost. German Max Planck Institutes and United States National Institutes of Health-funded centers drive demand for modular architectures supporting multimodal imaging fusion.
- Neurology Clinics:Outpatient settings favor rapid-setup disposable formats for ambulatory EEG services.
- Home Care:Wireless-enabled consumer devices for sleep and attention management are penetrating Japanese direct-to-consumer channels.
By installed base, hospitals dominate. By expansion trajectory, home care is gaining share fastest as wearable neurotechnology matures.
Technology:
Application requirements dictate electrode chemistry selection, with clinical throughput favoring dry sensors while research precision maintains wet electrode standards.
- Wet Electrode Technology:Conductive gel interfaces between silver-silver chloride sensors and scalp tissue deliver impedance levels below 5 kilo-ohms for artifact-resistant recordings. Research protocols at Stanford University and Amsterdam UMC continue to mandate these formats for publication-grade data quality.
- Dry Electrode Technology:Conductive polymer or micro-needle arrays eliminate gel application, compressing setup time from 45 minutes to under 10 minutes. United States emergency departments are piloting these for rapid seizure assessment.
- Wireless Technology:Bluetooth-enabled amplifiers untether patients from bedside equipment, enabling ambulatory monitoring during daily activities.
- Smart EEG Technology:Embedded signal processing with machine learning classification runs artifact rejection and event detection at the edge.
By current deployment, wet electrodes retain the largest installed base. By adoption velocity, dry architectures are expanding most quickly in clinical environments.
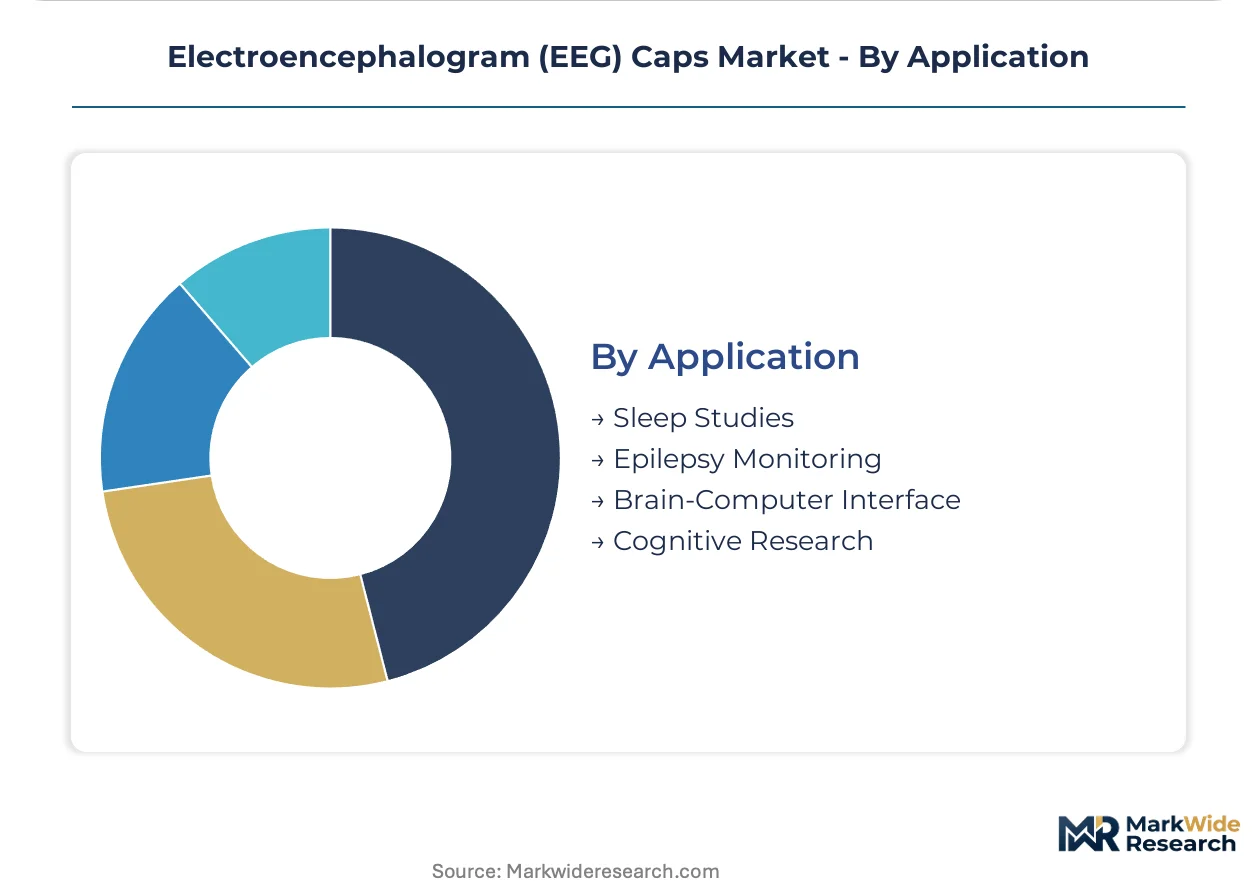
Application:
Maturity curves separate established diagnostic categories from emerging consumer-facing use cases with divergent reimbursement and regulatory pathways.
- Epilepsy Monitoring:Long-duration video-EEG telemetry in hospital epilepsy monitoring units represents the largest clinical volume. FDA 510(k) clearance requirements govern electrode biocompatibility and electrical safety for these indications.
- Sleep Studies:Polysomnography labs utilize standardized 10-20 montage caps for apnea and narcolepsy diagnosis. German sleep medicine centers are transitioning to disposable formats to streamline overnight study logistics.
- Cognitive Research:Academic laboratories employ high-density arrays for attention, memory, and perception studies with strict protocol standardization requirements.
- Brain-Computer Interface:Consumer neurotechnology startups and defense research programs are driving hardware supply contracts for thought-controlled device interfaces.
By procedure volume, epilepsy monitoring leads. By development intensity, brain-computer interface represents the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in EEG caps tilt toward German precision manufacturing and Japanese component sourcing, with the United States absorbing the largest share of high-channel-count research instrumentation. Net trade positions reflect concentrated electrode array fabrication in Central Europe against distributed clinical procurement across North American hospital networks.
United States
Hospital epilepsy monitoring units in Boston and San Francisco drive procurement of reusable high-density arrays. FDA 510(k) clearance pathways govern electrode biocompatibility claims for clinical-grade caps. The National Institutes of Health-funded research corridor between Maryland and Massachusetts anchors demand for modular instrumentation supporting multimodal neuroimaging.
Germany
Max Planck Institutes and university medical centers in Berlin and Munich sustain premium-tier research-grade orders. EU MDR biocompatibility mandates filter supplier qualification toward ISO 13485-certified manufacturers. The Baden-Württemberg precision engineering cluster concentrates electrode array fabrication for 64-256 channel systems.
Japan
Metropolitan hospital chains in Tokyo and Osaka are expanding ambulatory EEG services under revised National Health Insurance Service coverage. METI standards govern wireless medical device transmission protocols for home-care neurofeedback applications. The Kansai medical device manufacturing base supplies dry-electrode components for consumer-facing sleep monitoring devices.
India
Pediatric neurology departments in Maharashtra and Karnataka are piloting disposable cap formats for infection-controlled epilepsy screening. The country's national pharmaceutical regulator evaluates clinical performance claims for imported electrode systems. Hyderabad's medical technology corridor hosts assembly operations for cost-optimized 8-32 channel configurations.
South Korea
Seoul metropolitan hospital chains are scaling procurement following National Health Insurance Service reimbursement expansion for diagnostic EEG. MFDS regulates electrical safety and software validation for smart EEG algorithms. The Pangyo Techno Valley cluster incubates brain-computer interface startups sourcing hardware from domestic electrode suppliers.
Electroencephalogram (EEG) Caps Market Competitive Landscape
Concentration sits with German engineering specialists and North American clinical distributors, yielding a tiered structure that separates precision-research instrumentation from cost-optimized hospital screening tools. The competitive landscape fragments across three strategic archetypes: precision electrode array fabricators anchored in Central Europe, clinical distribution platforms with established hospital procurement relationships, and modular architecture specialists serving multimodal neuroimaging workflows. Dominant competitive moves include geographic expansion into Asia-Pacific reimbursement-expansion markets and technology licensing partnerships with consumer neurotechnology startups.
Within the precision-research tier, Brain Products and ANT Neuro exemplify German-engineered instrumentation standards, while Natus Medical occupies a position within North American clinical distribution channels. Brain Products represents the high-channel-count fabrication archetype concentrated in Baden-Württemberg. ANT Neuro sits within the modular architecture specialist category serving academic neuroscience departments. Natus Medical anchors the hospital procurement integration archetype through established United States group purchasing organization relationships.
| Leading Market Players |
|---|
| Brain Products |
| ANT Neuro |
| Compumedics Neuroscan |
| BIOPAC Systems |
| Electro Cap |
| Natus Medical |
| Nihon Kohden |
| g.tec medical engineering |
| BioSemi |
| Others |
Supply & Pricing Matrix
Conductive polymer sensors displacing silver-silver chloride electrodes are redrawing procurement economics across the EEG caps market, compressing material costs while shifting supplier advantage toward polymer chemistry specialists in Japan and South Korea away from traditional precious-metal fabricators in Germany.
Pricing Analysis
Hospital procurement committees anchor pricing negotiations through multi-year group purchasing organization contracts that bundle cap hardware with electrode replenishment and software maintenance. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified research instrumentation from CE-marked clinical screening tools and unbranded disposable formats. Cost compression in the standard tier is intensifying because German manufacturers are absorbing EU MDR compliance overhead while competing with Asian assemblers. Neurology clinics exhibit the highest price sensitivity due to constrained capital budgets, whereas academic neuroscience departments prioritize signal fidelity over unit economics.
Supply Chain Analysis
Container availability fluctuations on the Hamburg-Singapore trade lane are extending lead times for electrode array components sourced from Central European precision engineering clusters. Fabrication concentrates in Germany for high-density arrays, Japan for dry-electrode polymers, and South Korea for wireless amplification modules. Silver supply draws from Mexican and Peruvian mining operations, conductive polymer feedstock rests on petrochemical complexes in East Asia, and elastic textile substrates hinge on Taiwanese weaving operations. Single-source vulnerability sits with Baden-Württemberg electrode lithography for 128+ channel systems. Distribution runs through hospital group purchasing organizations in the United States, university procurement consortia in Europe, and medical device distributors in Asia-Pacific.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent EEG cap manufacturers face substitution defense imperatives as functional magnetic resonance imaging captures deeper brain structures with superior spatial resolution in funded neuroscience research, threatening high-channel-count hardware demand.
For Market Incumbents: Secure backward integration into conductive polymer supply chains to offset silver price volatility exposure and lock in dry-electrode cost advantages. Fortify ISO 13485 certification moats against emerging Asian competitors pursuing EU MDR compliance, while expanding hospital system partnerships in Seoul and Tokyo where reimbursement expansion is stimulating procurement. For New Entrants and Emerging Players: Differentiate on rapid-setup disposable formats targeting pediatric epilepsy monitoring in Indian hospital networks where infection control protocols favor single-use architectures. Penetrate the brain-computer interface developer segment through modular cap designs compatible with machine learning signal processing workflows, leveraging direct hardware supply contracts with Pangyo Techno Valley startups. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed clinical distribution platforms holding entrenched United States group purchasing organization relationships. Five-to-ten year viability hinges on software companion development capabilities and smart EEG algorithm regulatory clearance trajectories. Monitor FDA digital health guidance convergence with EU AI Act algorithmic transparency requirements as the critical inflection signal for hardware-software bundled valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Investment | ISO 13485 quality management audits filter supplier qualification toward certified manufacturers in institutional procurement. |
| Dry Electrode Technology Migration | Conductive polymer sensors eliminate gel application time, accelerating adoption in United States emergency neurology departments. |
| Software Companion Development | Embedded machine learning classification for artifact rejection runs at the edge, enabling smart EEG platform differentiation. |
| Hospital System Partnership Expansion | Bundled multi-year supply agreements with Japanese metropolitan chains capture National Health Insurance Service reimbursement expansion. |
| Brain-Computer Interface Hardware Supply | Modular cap architectures compatible with consumer neurotechnology startups open defense and wellness application channels. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with hospital biomedical engineers, neurology department heads, academic neuroscience researchers, group purchasing organization contract managers, and medical device regulatory affairs specialists; and secondary validation against FDA 510(k) clearance databases, EU MDR technical documentation filings, Japanese METI wireless device standards, hospital procurement contract registries, and ISO 13485 certification records. Bottom-up demand modeling from channel shipment data triangulated against top-down market sizing from manufacturer revenue disclosures.
Across the analysis window, the forecasting framework modeled volume and value trajectories through segmentation across product format, electrode technology, end-user environment, and clinical application dimensions. CAGRs were derived from trend extrapolation of procurement patterns, reimbursement expansion timelines, and technology substitution curves. Forecast inputs incorporated silver commodity price volatility indices, EU MDR compliance cost burdens, and brain-computer interface startup funding velocity as industry-specific demand drivers.
The analysis sits within stated boundaries; outcomes outside sustained reimbursement expansion in Asia-Pacific hospital systems, stable precious metal commodity pricing, and regulatory convergence between FDA digital health guidance and EU AI Act requirements would require recalibration. Forecasts reflect documented assumptions regarding electrode technology transition rates and hospital capital equipment replacement cycles. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
US Nurse Call Systems Market
Medical Devices
Medical Devices Vigilance Market
Medical Devices
Global Canes and Crutches Market
Medical Devices
Needle-Free Drug Delivery Devices Market
Medical Devices
Flow Cytometry Products Market
Medical Devices
Injectable Bulking Agents Market
Medical Devices
Low Vision Aids Market
Medical Devices
Rib Fracture Repair Systems Market
Medical Devices
Minimally Invasive Neurosurgery Devices Market
Medical Devices
Europe Breast Implant Market
Medical Devices
Global Artificial Skin Market
Medical Devices
Biological Microscope Market
Medical Devices
Global Limb Prosthetics Market
Medical Devices
Medical Bionic Implant Market
Medical Devices
Middle East and Africa Medical Devices Market
Medical Devices
Coronary Guidewires Market