
 Modified Starch Market | 2026-2036
Modified Starch Market Size, Share, and Industry Trends Forecast 2026-2036
Modified Starch Market Intelligence
The substitution of chemically modified starches with physically or enzymatically treated alternatives is realigning product formulation costs in the food industry. This shift is reshaping the competitive positioning of ingredient suppliers. Cargill leverages its vast agricultural sourcing network to ensure feedstock security for its global operations. Ingredion differentiates through its extensive portfolio of functional solutions, while Roquette Frères specializes in plant-based ingredients for food and pharmaceutical end-uses.
Modified starch is a carbohydrate polymer, derived from sources like corn or potato, whose chemical structure is altered to improve functional properties. This process enhances attributes such as viscosity, freeze-thaw stability, and resistance to shear for industrial use. Pregelatinized and enzymatically modified starches are gaining share due to their superior performance in convenience foods. The mature paper coating and adhesives applications continue to represent a significant volume base for cross-linked starches.
Regulatory bodies like the U.S. FDA, through its GRAS notifications, and the European Food Safety Authority (EFSA), via its E-number system, define permissible modification types. These standards directly influence R&D investment toward approved processing methods and clean-label claims. Navigating the evolving consumer preference for 'natural' ingredients while maintaining cost-effectiveness and functional performance remains the central challenge for producers.
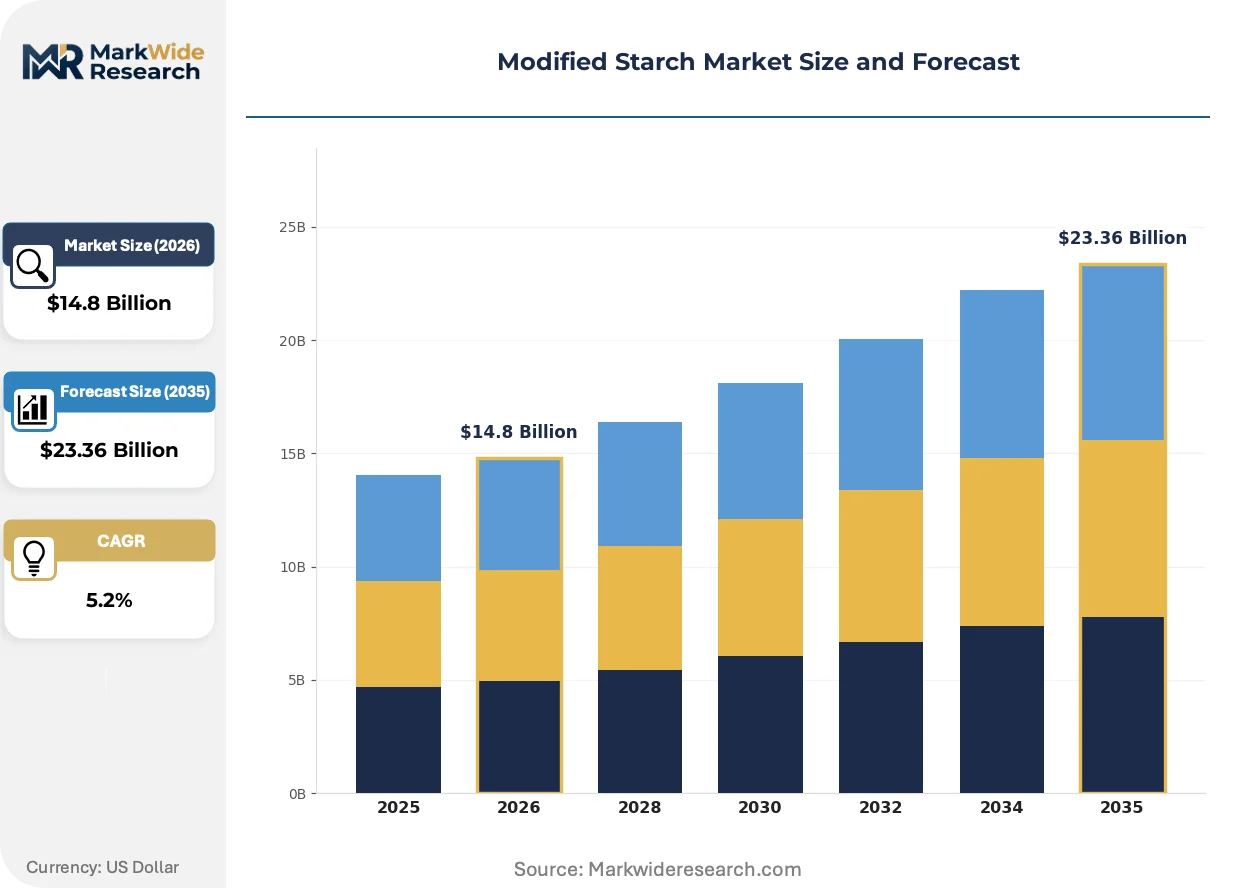
Market Dynamics
The push for clean-label ingredients is the central force shaping the market, compelling a shift from chemical modification towards enzymatic and physical processing methods. This transition alters cost structures and demands greater investment in novel food science technologies to meet consumer expectations.
Growth Catalysts
- Advanced Enzymatic Modification:New enzyme cocktails create starches with superior freeze-thaw stability and texture, meeting demand from the frozen and convenience food sectors.
- Food Industry Expansion in Asia:Rapid growth in China's processed food and beverage manufacturing provides a large-volume demand base for functional starches in noodles, sauces, and dairy products.
- Regulatory Harmonization:The U.S. FDA's GRAS notification process provides a transparent pathway for introducing innovative, non-chemically modified starches, encouraging R&D investment.
Market Restraints
- Feedstock Price Volatility:Fluctuations in the global prices of key raw materials like corn, wheat, and tapioca directly impact production costs and create margin pressure for manufacturers.
- Substitution from Hydrocolloids:Guar gum, xanthan gum, and carrageenan present viable alternatives in many applications, competing directly on both functionality and price points.
- Slow Regulatory Approvals:The lengthy evaluation process for new food additives under bodies like the European Food Safety Authority (EFSA) can delay the commercialization of novel starches.
Strategic Opportunities
- Plant-Based Formulations:The growing plant-based meat and dairy alternative market requires sophisticated texturizers and binders, creating a high-value application space for specialized modified starches.
- Pharmaceutical Excipients:Developing high-purity starches for use as binders and disintegrants in oral solid dosage forms offers a pathway into the less price-sensitive pharmaceutical industry.
- Emerging Economies:Rising disposable incomes and urbanization in Southeast Asian nations are increasing consumption of processed foods, opening new geographic markets for starch suppliers.
Industry Challenges
- Supply Chain Traceability:Ensuring consistent quality and non-GMO status from a fragmented global agricultural supply base requires complex and costly identity preservation programs.
- Navigating Global Labeling Laws:Adhering to disparate international regulations for what constitutes a 'natural' or 'clean-label' ingredient complicates product formulation and export strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Modified Starch Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $23.36 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acid-Modified, Oxidized, Cross-linked, Pregelatinized, Enzymatically Modified Application: Textile Processing, Paper Coating, Oil Drilling, Adhesives, Pharmaceuticals, Food & Beverages End Use Industry: Personal Care, Detergents, Construction, Animal Feed, Packaging Packaging Type: Powder Bags, Bulk Bags, Fiber Drums, Plastic Containers |
| Companies Covered | Roquette Frères, Avebe U.A., ADM, Emsland, Grain Processing Corporation, Cargill, Tate & Lyle, AGRANA, Ingredion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Modified Starch Market Strategic Shifts & Innovations
Innovation is centered on resolving the conflict between consumer demand for simple, recognizable ingredients and the food industry's need for high-performance texturizers. This drives advancements in non-chemical modification and formulation science to achieve functionality without compromising clean-label status.
Advanced process control systems integrate sensors and machine learning to monitor enzymatic reactions in real-time. Food and beverage manufacturers are adopting these platforms to achieve precise, repeatable functional properties in their starch ingredients. This technology is automating the creation of customized textures, reducing batch variability and the need for extensive operator intervention.
European Food Safety Authority's ongoing re-evaluation of food additives is increasing scrutiny on chemically modified starches and their corresponding E-numbers. This regulatory pressure forces ingredient suppliers to prioritize physically modified and functional native starches that can be listed as "corn starch" or "potato starch". The dairy and prepared sauces segments are most affected, reformulating products to maintain clean-label declarations.
Ingredient procurement is evolving from purchasing discrete components to sourcing complete, co-developed functional systems. This shift challenges standalone starch suppliers but benefits those who can offer customized blends combining starches with proteins and fibers to solve specific texture or stability problems. This integrated approach is most visible in the North American sports nutrition and beverage markets.
Modified Starch Market Segmentation
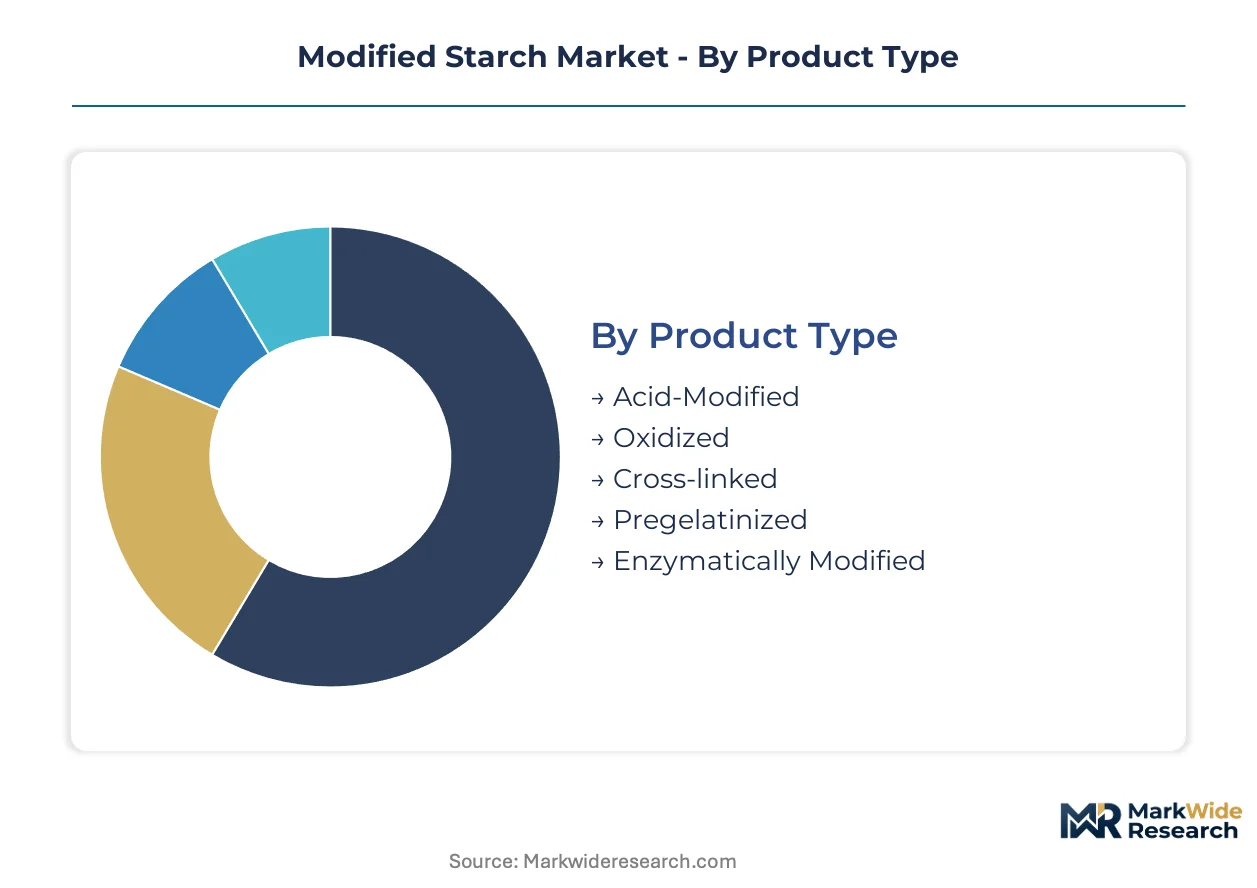
The modified starch market fragments across diverse product types, applications, and end-use industries, each catering to specific functional requirements. Understanding these segments is crucial for identifying areas of concentrated demand and technological innovation within the food and industrial sectors. This detailed segmentation highlights where value creation is highest and where competitive differentiation occurs.
Product Type:
Supply concentration for modified starches often dictates the prevalence of certain product types, with established chemical modification processes holding significant volume. However, newer enzymatic methods are gaining traction due to evolving regulatory and consumer preferences.
- Enzymatically Modified:These starches are treated with enzymes to alter their molecular structure, enhancing properties like freeze-thaw stability and texture. Demand from the frozen food and convenience meal sectors, particularly in China's expanding processed food industry, drives their adoption.
- Pregelatinized:These starches are pre-cooked and dried, allowing them to thicken instantly in cold water without heating, making them ideal for convenience foods. Their superior performance in instant soups, sauces, and dairy products fuels their market expansion across North America.
- Acid-Modified:Produced by treating starch with acid, these starches have reduced viscosity and improved film-forming properties, finding use in confectionery and paper applications.
- Oxidized:Created through oxidation, these starches offer enhanced whiteness, clarity, and binding characteristics, commonly applied in paper sizing and textile finishing.
- Cross-linked:These starches exhibit high stability under heat, acid, and shear, making them suitable for demanding industrial applications like paper coating and adhesives.
Cross-linked starches absorb the bulk of installed capacity; Enzymatically Modified starches are expanding most quickly.
Application:
Market volume distribution across applications reflects both mature industrial uses and high-growth segments driven by consumer trends and regulatory shifts.
- Food & Beverages:Modified starches serve as thickeners, stabilizers, and texturizers in a vast array of products, from baked goods and dairy to processed meats and beverages. The push for clean-label ingredients in Europe and the US compels reformulation efforts towards physically and enzymatically modified options.
- Paper Coating:These applications utilize modified starches for their binding and film-forming properties, improving paper strength, printability, and surface finish. This segment represents a significant, mature volume base for cross-linked starches across global paper manufacturing hubs.
- Textile Processing:Starches are used for sizing, printing, and finishing fabrics, improving their strength, stiffness, and appearance.
- Oil Drilling:Modified starches function as fluid loss control agents and rheology modifiers in drilling muds, particularly in offshore operations.
- Adhesives:Starches provide tack and binding strength in various adhesive formulations, including corrugated board and packaging.
- Pharmaceuticals:High-purity starches act as excipients, binders, and disintegrants in oral solid dosage forms, offering functional benefits in drug delivery.
Food & Beverages applications are gaining share fastest as consumer demand for processed foods rises globally.
End Use Industry:
The type of customer driving demand often dictates the specific functional requirements and purity standards for modified starches, influencing product development and market focus.
- Animal Feed:Modified starches act as binders, palatability enhancers, and energy sources in animal nutrition formulations. Demand for high-performance feed in developing economies, such as Brazil and India, supports growth in this sector.
- Packaging:Starches are integral to bio-based and sustainable packaging solutions, including biodegradable films and coatings, driven by environmental regulations in the European Union.
- Personal Care:Modified starches are used as thickeners, emulsifiers, and texture modifiers in cosmetics, lotions, and other personal hygiene products.
- Detergents:Starches serve as binders and rheology modifiers in laundry detergents and cleaning agents.
- Construction:Modified starches improve the workability, adhesion, and water retention of building materials like mortars and plasters.
The Animal Feed industry presents a significant market opportunity, while the Packaging industry is experiencing the steepest expansion trajectory.
Packaging Type:
The volume of procurement and logistical requirements primarily determine the preferred packaging types for modified starches, impacting handling costs and supply chain efficiency.
- Bulk Bags:These large flexible containers, typically holding 500-1500 kg, are favored for high-volume industrial customers due to their cost-effectiveness and efficient handling. Major food processing plants and paper mills in North America heavily rely on bulk bag deliveries.
- Powder Bags:Typically 20-50 kg sacks, these are common for smaller industrial users or specific ingredients requiring easier manual handling. Food service distributors and smaller manufacturers in Southeast Asia frequently purchase starches in powder bags.
- Fiber Drums:These cylindrical containers offer protection for specialized or higher-value starches, often used for pharmaceutical-grade products.
- Plastic Containers:Ranging from pails to larger totes, these are used for liquid or paste-form modified starches, providing moisture barrier and stability.
Bulk Bags dominate the overall volume of modified starch shipments; Plastic Containers are climbing fastest in specialized applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's expansive food processing industry, often concentrated in special economic zones like the Yangtze River Delta, drives significant demand for modified starches. This concentration facilitates efficient supply chains and fosters innovation in functional food ingredients. Local and international manufacturers benefit from these established industrial hubs.
China
Demand for advanced enzymatic starches and pregelatinized options is high due to rapid growth in processed foods and convenience meals. The NMPA's food additive standards guide product development for local manufacturers. Food industrial parks in Shanghai and Guangzhou are centers for starch application innovation.
United States
Consumer preference for clean-label texturizers and the expansion of plant-based food alternatives fuel demand for modified starches. The U.S. FDA's GRAS notification process provides a clear path for novel starch ingredients. Corn Belt states like Iowa and Illinois are major production and application hubs.
Germany
The European food industry, particularly in dairy and prepared sauces, seeks physically and enzymatically modified starches for reformulation. EFSA's E-number system influences ingredient choices, prioritizing approved processing methods. Food ingredient clusters in North Rhine-Westphalia and Bavaria advance starch technology.
India
Rising disposable incomes and urbanization increase consumption of processed foods, driving demand for functional starches in snacks and beverages. The FSSAI regulates food additives, shaping the types of modified starches permissible. Food processing hubs in Maharashtra and Gujarat are key consumption centers.
Brazil
Growth in animal feed and convenience food sectors creates substantial demand for binders and texturizers. ANVISA guidelines for food additives ensure safety and quality for starch formulations. Agricultural processing zones in São Paulo and Paraná drive both feedstock supply and end-use manufacturing.
Modified Starch Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with larger firms dominating high-volume industrial applications while niche players target specialized food formulations. The market exhibits a tiered structure, from global agricultural processors to regional ingredient suppliers. Strategic archetypes include integrated starch producers, functional ingredient innovators, and localized solution providers. Companies often engage in capacity expansion and strategic partnerships to secure feedstock and broaden their product portfolios.
Within the integrated starch producer archetype, Cargill and Ingredion exemplify global reach and broad product offerings, leveraging vast agricultural networks to ensure feedstock security. These companies offer extensive portfolios of functional solutions, serving diverse industries from food and beverage to industrial applications. Roquette Frères, conversely, anchors the specialized plant-based ingredient segment, focusing on high-value food and pharmaceutical end-uses. Their differentiation stems from targeted innovation in specific application areas.
| Leading Market Players |
|---|
| Roquette Frères |
| Avebe U.A. |
| ADM |
| Emsland |
| Grain Processing Corporation |
| Cargill |
| Tate & Lyle |
| AGRANA |
| Ingredion |
| Others |
Cost & Logistics Intelligence
Feedstock price volatility across corn, wheat, and tapioca directly impacts modified starch production costs, which then influence pricing tiers for industrial and food-grade applications downstream. This dynamic necessitates robust hedging strategies for manufacturers and affects procurement decisions for large-volume buyers.
Pricing Analysis
Premium pricing for short lead times often applies to specialized modified starches needed quickly by food manufacturers for urgent reformulations. The dominant pricing structure involves contract-based long-term offtake agreements for high-volume industrial users. Price differentiation stems from the quality grade, particularly for pharmaceutical excipients, and the volume scale of procurement. Pricing pressure stems from hydrocolloid substitution and raw material price fluctuations. Industrial applications, such as paper coating, exhibit higher price sensitivity compared to the less price-sensitive pharmaceutical excipients segment.
Supply Chain Analysis
Reverse logistics for modified starches are minimal, as the product is typically consumed entirely without returns or refurbishment flows. Geographic supply concentration for raw materials centers on agricultural hubs in the United States (Corn Belt) and China. Key raw material dependencies include corn, wheat, and tapioca. Supply chain risk arises from commodity price volatility and the complex identity preservation programs required for non-GMO status. Distribution primarily runs through direct sales channels for large food and industrial customers, supplemented by regional distributors for smaller manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
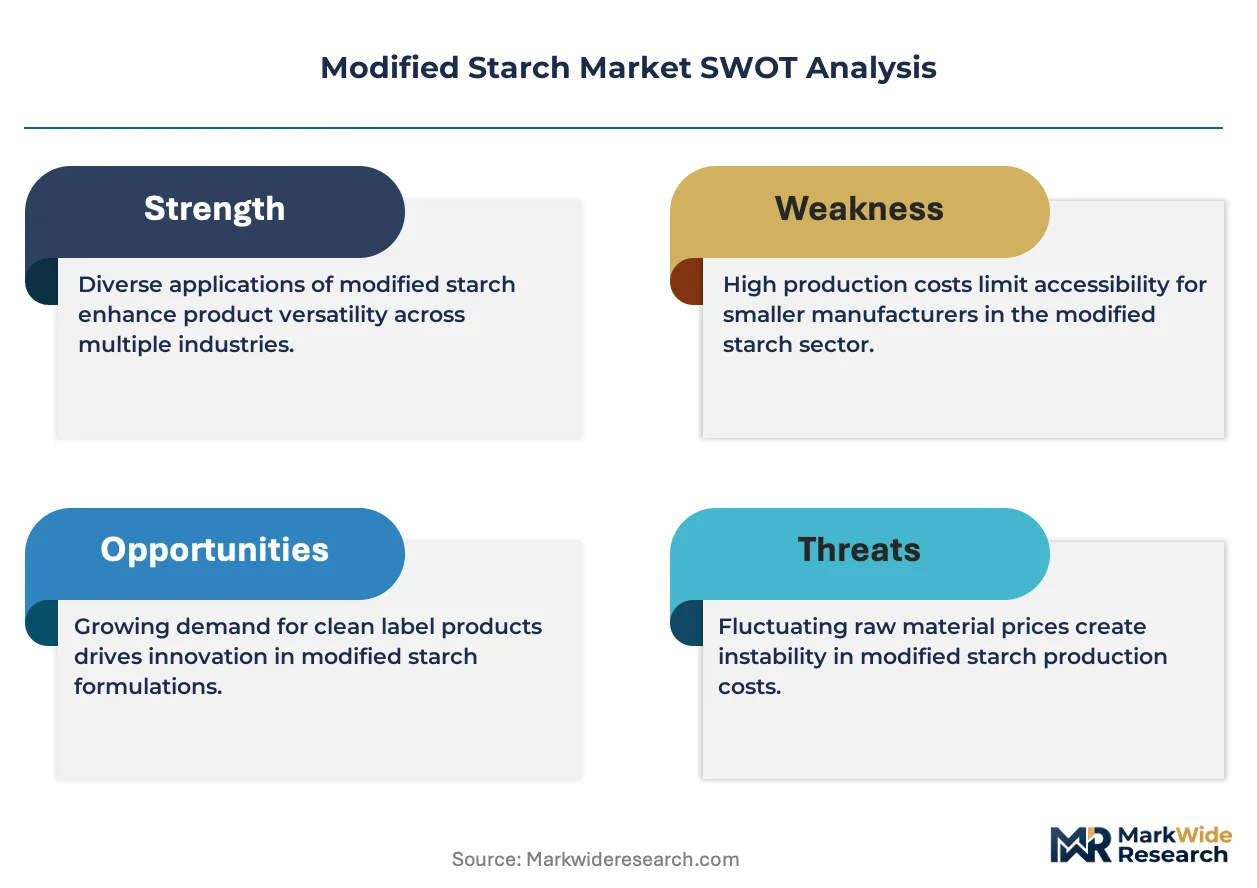
This market is a cost-of-compliance story, where the European Food Safety Authority's (EFSA) E-number system creates a barrier-to-entry moat for compliant players developing novel clean-label ingredients.
For Market Incumbents: Deploy advanced enzymatic technology to innovate new clean-label starch alternatives. Incumbents should invest in R&D to develop starches with superior performance characteristics, mitigating the threat of hydrocolloid substitution. Secure long-term feedstock contracts to buffer against commodity price volatility, ensuring supply stability for global operations. Consolidate market share through strategic partnerships that expand geographic reach into fast-growing Asian markets.
For New Entrants and Emerging Players: Begin with targeting high-value niche applications like plant-based formulations and pharmaceutical excipients. The Southeast Asian processed food market, driven by rising disposable incomes, offers a penetrable geographic segment. Go-to-market strategies should emphasize offering customized, co-developed functional systems that combine starches with proteins and fibers, addressing specific texture challenges for clean-label products.
For Investors and Strategic Acquirers: Increased venture capital funding in food tech start-ups developing novel starch alternatives is the leading indicator that innovation is accelerating. The long-term viability of this market is anchored by sustained global demand for processed foods and the persistent clean-label trend. Acquisition targets should be niche players with proprietary enzymatic modification technologies or specialized plant-based ingredient portfolios. Watch for regulatory approvals of new processing methods as a key inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced Enzymatic R&D | Develops novel starches meeting clean-label demands and superior functional properties. |
| Secure Long-Term Feedstock Contracts | Mitigates raw material price volatility, ensuring stable production costs for manufacturers. |
| Expand Plant-Based Ingredient Portfolio | Captures high-value opportunities in the rapidly growing plant-based food sector. |
| Target Emerging Economies in Asia | Accesses new geographic markets with increasing consumption of processed food products. |
| Develop Integrated Functional Systems | Offers comprehensive texture and stability solutions, differentiating from standalone ingredient suppliers. |
Research Approach
Independent corroboration across industry experts, regulatory bodies, and academic literature underwrites the qualitative findings of this market analysis. Primary interviews were conducted with food scientists, procurement managers, R&D directors, and regulatory specialists to gather firsthand insights. Secondary validation involved reviewing company annual reports, government food safety databases, and trade association publications. This approach utilized both bottom-up and top-down triangulation to ensure data accuracy.
Comparable historical reference periods anchored the forecast window, integrating historical data analysis with identified market drivers and restraints. The analytical framework modeled segmentation dimensions including product type, application, end-use industry, and geographic region. Compound annual growth rates were derived through regression analysis and expert consensus, incorporating key industry-specific forecast inputs like raw material price trends and processed food consumption growth across the analysis window.
Unforeseen regulatory changes, sudden shifts in consumer preferences, and significant feedstock supply disruptions are the dominant revision risks for these forecasts. The projections reflect current assumptions about market dynamics and technological advancements. Practitioners should monitor regulatory updates, food innovation trends, and agricultural commodity markets for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Italy Food Hydrocolloids Market
Food Components and Additives
South America Food Hydrocolloids Market
Food Components and Additives
Edible Films and Coating Market
Food Components and Additives
Europe Food Hydrocolloids Market
Food Components and Additives
Blackcurrant Powder Market
Food Components and Additives
Spain Food Hydrocolloids Market
Food Components and Additives
Modified Wheat Starch Market
Food Components and Additives
Food Grade Iron Powder Market
Food Components and Additives
Food Grade Antifoams Market
Food Components and Additives
Europe Food Preservatives Market
Food Components and Additives
France Food Hydrocolloids Market
Food Components and Additives
Flavonoids Market
Food Components and Additives
Asia Pacific Food Grade Carbon Dioxide Market
Food Components and Additives
Germany Food Hydrocolloids Market
Food Components and Additives
Horseradish Peroxidase Market
Food Components and Additives
Food Grade Xanthan Gum Market