
 Europe Food Stabilizers Market | 2026-2036
Europe Food Stabilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Food Stabilizers Market Foresight
Consolidation among dairy processors is realigning ingredient procurement across Northern Europe. Cargill leverages its integrated pectin supply chain to secure long-term contracts with yogurt manufacturers. Palsgaard sustains its emulsifier leadership through specialized bakery applications in Scandinavia. Kerry Group anchors its position with clean-label stabilization systems for ready-to-drink beverages.
Food stabilizers are hydrocolloid and emulsifier compounds—typically pectin, carrageenan, or modified starches at 0.1–2.0% inclusion rates—that control water mobility, texture retention, and shelf stability in processed foods. These functional ingredients prevent syneresis in dairy, maintain viscosity in heat-processed sauces, and extend freeze-thaw tolerance in bakery fillings. Thickening agents occupy the largest volume share as manufacturers reformulate toward reduced-fat dairy without texture loss. Emulsifiers represent the fastest-growing category, driven by plant-based beverage expansion requiring oil-water interface stability. Gelling agents command premium positioning in confectionery and dessert applications where thermal reversibility defines product performance.
EFSA maintains additive safety evaluations that directly determine Acceptable Daily Intake levels and renewal timelines for hydrocolloid approvals. REACH compliance governs chemical purity thresholds for imported stabilizer raw materials entering EU formulation facilities. The EU Green Deal's packaging waste directives are pressuring stabilizer suppliers to demonstrate biodegradability credentials alongside functional performance. Stakeholders must monitor EFSA's ongoing re-evaluation of carrageenan and modified cellulose classifications, as regulatory reclassification would force immediate reformulation across multiple application segments.
Market Dynamics
Clean-label reformulation mandates from EFSA are compressing formulation windows for hydrocolloid suppliers, forcing simultaneous purity upgrades and cost containment across dairy and beverage value chains.
Growth Catalysts
- EFSA Additive Re-evaluation Schedules:Accelerated safety reviews for carrageenan and modified cellulose are compelling manufacturers to secure early-mover positions with compliant alternative stabilizers.
- Plant-Based Beverage Expansion:Oat and pea protein drink manufacturers require sophisticated emulsifier systems to maintain suspension stability without dairy-derived ingredients.
- Germany's Processed Food Corridor:Concentrated bakery and beverage production in Bavaria and North Rhine-Westphalia generates sustained volume demand for texture-modifying hydrocolloids.
Market Restraints
- Seaweed Supply Concentration:Carrageenan raw material sourcing depends on Philippine and Indonesian harvest regions vulnerable to climate variability and export restrictions.
- REACH Compliance Burden:Chemical purity documentation requirements for imported modified starches extend qualification timelines by 8-14 months for non-EU suppliers.
- Clean-Label Cost Premium:Pectin and natural gum alternatives command 40-60% higher unit costs versus synthetic hydrocolloids, compressing margin recovery in private-label dairy.
Strategic Opportunities
- Poland and Romania Food Processing:Underdeveloped stabilizer formulation capabilities in Central European dairy plants create technical service partnerships for Western suppliers.
- EU Green Deal Packaging Mandates:Biodegradability credentials for stabilizer systems unlock preferred supplier status with sustainability-committing retail chains.
- Fermentation-Derived Hydrocolloids:Precision fermentation platforms producing xanthan gum alternatives bypass agricultural supply constraints and geographic concentration risks.
Industry Challenges
- Formulation Chemist Scarcity:Specialized expertise in hydrocolloid synergy mapping and texture optimization remains concentrated among retiring technical specialists in Netherlands and Denmark.
- Multi-Site Certification Complexity:BRC and IFS food safety audits across dispersed European production facilities demand coordinated quality management system investments.
- Legacy Equipment Retrofit Requirements:Existing spray-drying and blending infrastructure requires capital modification to handle heat-sensitive clean-label stabilizer inputs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Food Stabilizers Market |
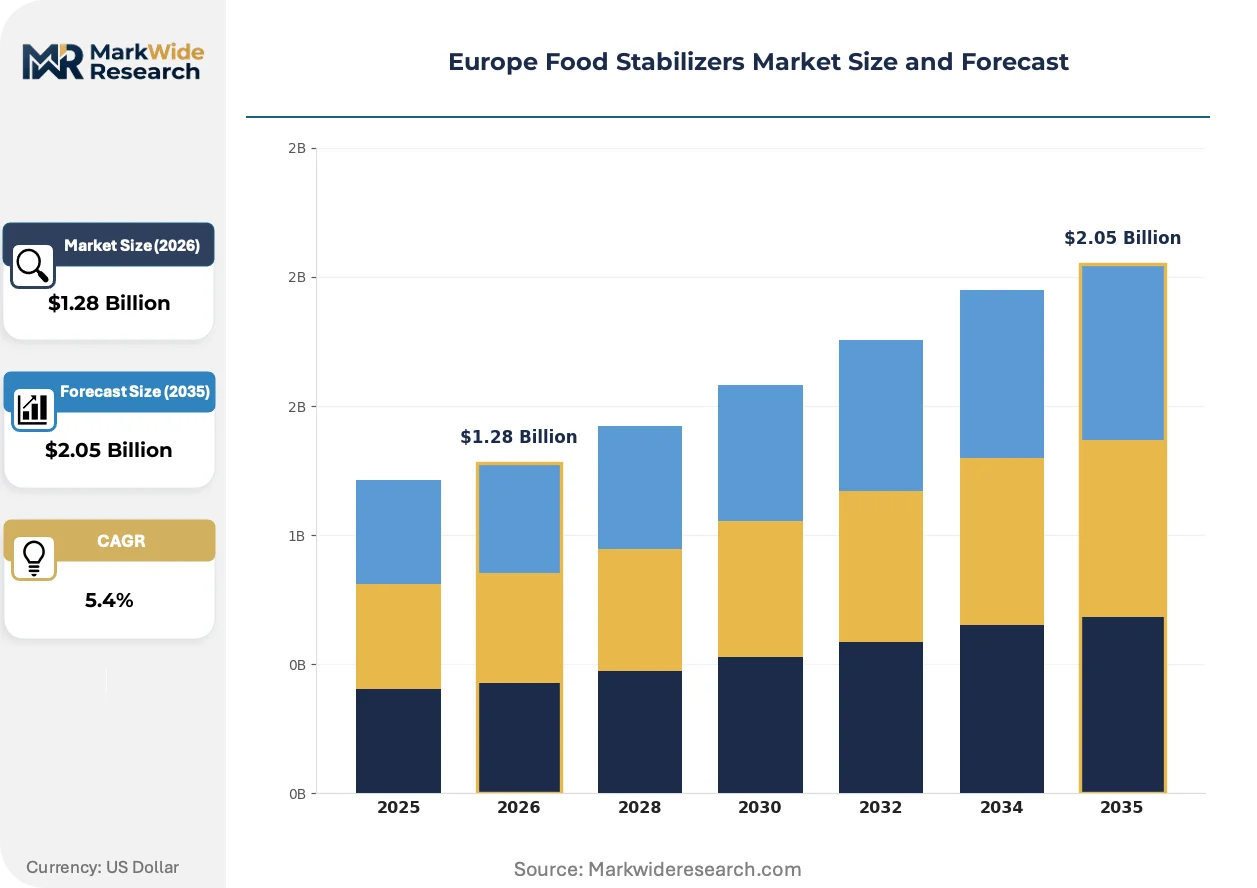
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $2.05 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsifiers, Gelling Agents, Thickening Agents, Binders Application: Dairy Products, Bakery, Beverages, Sauces Form: Powder, Liquid, Granules, Gel End User: Food Manufacturers, Retailers, Food Service Operators, Catering Services |
| Companies Covered | Kerry Group, Ingredion, Cargill, CP Kelco, Ashland, DuPont de Nemours, Archer Daniels Midland, Palsgaard, Tate & Lyle, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Food Stabilizers Market Shifts & Advancements
Stabilizer technology trajectories center on biological production methods, regulatory-driven ingredient substitution, and procurement model compression that rewards technical partnership over transactional supply.
Fermentation-derived hydrocolloids are overtaking agricultural extraction as the dominant production paradigm for premium stabilizer grades. Specialty dairy processors in France and Italy are adopting these biomanufactured alternatives at 18-month replacement cycles. This shift is compressing traditional seaweed and plant-extraction supply chains while enabling batch-to-batch consistency unattainable with climate-dependent raw materials.
EFSA's ongoing re-evaluation of carrageenan safety classifications is tightening purity thresholds for hydrocolloid suppliers seeking renewal approvals. Industrial consequence includes mandatory heavy metal and poligeenan contamination testing at sub-ppm detection limits. Dairy dessert and infant formula segments in Germany and Netherlands are responding with accelerated reformulation timelines and dual-sourcing qualification programs.
Technical service integration into ingredient supply contracts is displacing spot purchasing across mid-sized European food manufacturers. Bakery and sauce producers in Scandinavia now expect on-site texture optimization support and rapid prototype development as standard commercial terms. This behavioral shift is most visible in Denmark's cooperative dairy sector, where procurement committees prioritize formulation partnership capabilities over unit price in supplier selection.
Europe Food Stabilizers Market Segmentation
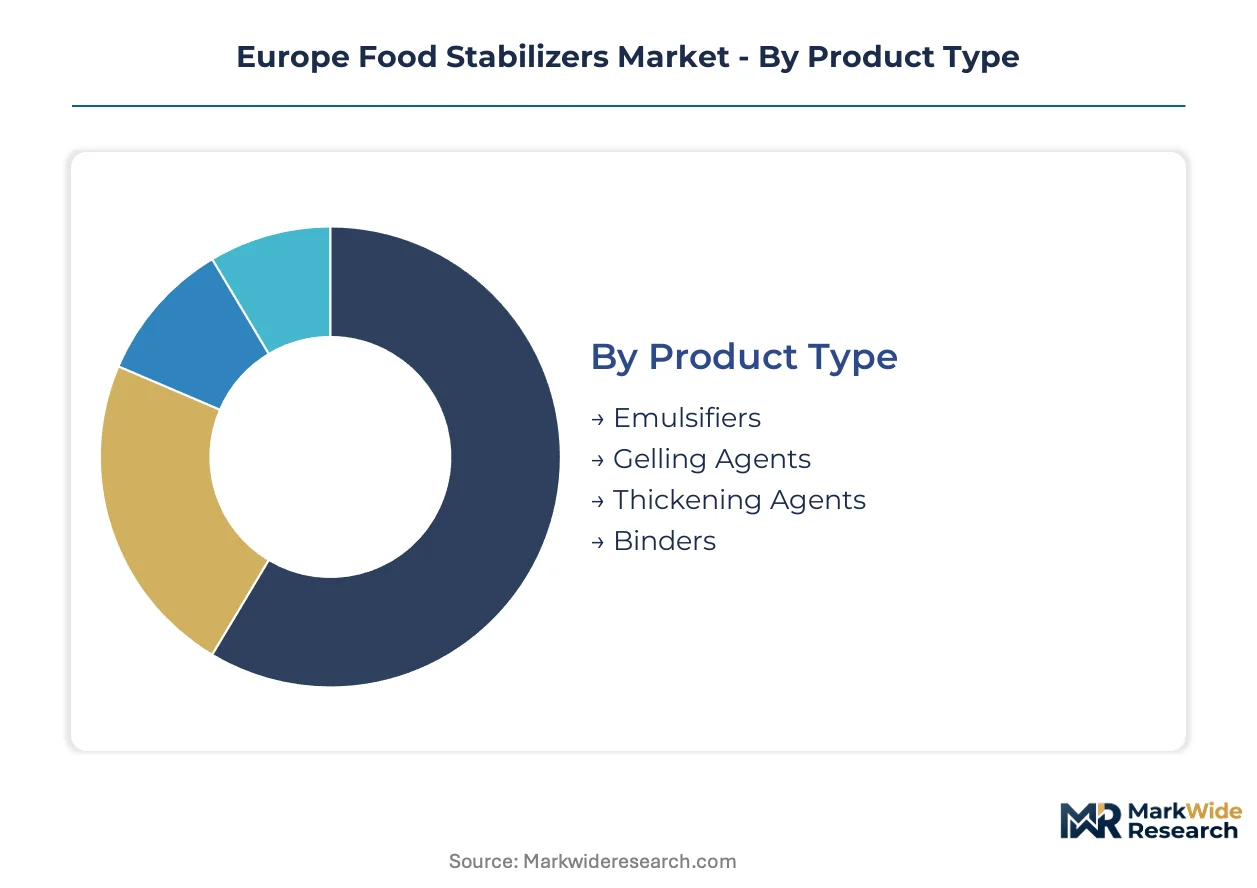
Food stabilizer procurement patterns diverge sharply across product chemistry, application requirements, and customer operational scale. Manufacturers must align formulation capabilities with specific segment demands to capture value in this technically fragmented market.
Product Type:
Cost tier differentiation separates commodity hydrocolloid buyers from premium emulsifier purchasers seeking specialized performance guarantees.
- Thickening Agents:Modified starches and cellulose derivatives dominate dairy reformulation as manufacturers reduce fat content without viscosity loss. German yogurt processors anchor European volume offtake for clean-label alternatives to traditional hydrocolloids.
- Emulsifiers:Lecithin and mono-diglyceride systems stabilize oil-water interfaces in plant-based oat and pea protein beverages. Scandinavian beverage manufacturers drive fastest category expansion as dairy alternatives capture refrigerated case space.
- Gelling Agents:Pectin and carrageenan provide thermal reversibility for confectionery and dessert applications. French and Italian premium dessert producers command premium positioning through specialized gelling performance.
- Binders:Hydrocolloid blends maintain structural integrity in reduced-meat and reformed protein products. Central European meat processors increasingly specify binder systems for cost-optimized formulations.
Thickening agents lead volumes today; emulsifiers are gaining share fastest.
Application:
Volume concentration varies by processing intensity and reformulation frequency across food manufacturing segments.
- Dairy Products:Stabilizer systems prevent syneresis in yogurt, control melt in processed cheese, and extend shelf stability in UHT milk. Bavaria and North Rhine-Westphalia processing corridors generate sustained demand for texture-modifying hydrocolloids.
- Bakery:Freeze-thaw tolerant hydrocolloids maintain filling viscosity through distribution cold chains. Scandinavian industrial bakeries specify stabilizer performance for extended retail shelf life requirements.
- Beverages:Suspension stability for pulp and protein particles demands sophisticated emulsifier and hydrocolloid synergy. Ready-to-drink smoothie manufacturers in Netherlands and Belgium prioritize clean-label stabilization systems.
- Sauces:Heat-processed condiments require viscosity retention through sterilization and hot-fill operations. Italian pasta sauce producers anchor Mediterranean demand for modified starch and xanthan gum systems.
Dairy applications command the largest installed base; beverage applications show steepest expansion trajectory.
Form:
Customer infrastructure and handling economics determine format preference across manufacturing scales.
- Powder:Spray-dried hydrocolloids offer extended shelf stability and flexible dosing precision for large-scale dry blend operations. Major dairy processors in Germany and France standardize on powder formats for automated ingredient handling systems.
- Liquid:Pre-hydrated emulsifier dispersions eliminate dust exposure and accelerate batch cycle times. Mid-sized sauce manufacturers in Poland and Romania favor liquid concentrates for reduced technical labor requirements.
- Granules:Low-dust agglomerated particles improve flowability for manual addition scenarios. Smaller bakery operations in Southern Europe specify granule formats for weighing accuracy without specialized equipment.
- Gel:Pre-solubilized hydrocolloid pastes enable cold-process incorporation for heat-sensitive formulations. Premium dessert producers in Italy utilize gel formats for precise texture control in delicate applications.
Powder dominates manufacturing economics; liquid formats are expanding most quickly among mid-tier processors.
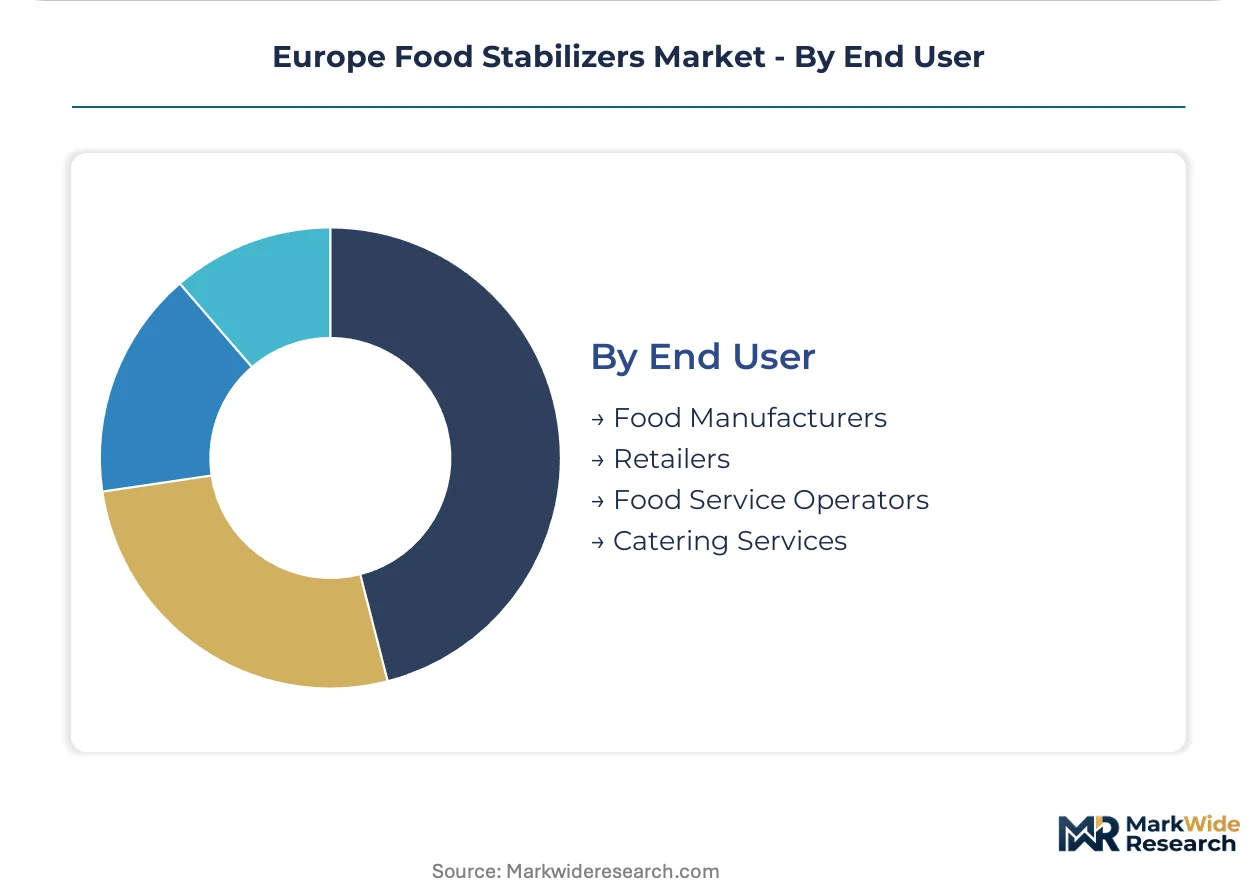
End User:
Procurement sophistication and technical service requirements stratify sharply across customer categories.
- Food Manufacturers:Integrated stabilizer specification into NPD workflows demands on-site formulation partnership and rapid prototype support. Denmark's cooperative dairy sector prioritizes technical collaboration capabilities over unit pricing in supplier selection.
- Food Service Operators:Consistency and holding stability requirements drive specification of robust hydrocolloid systems for prepared sauces and desserts. Contract catering chains across Germany specify stabilizer performance for extended hot-hold applications.
- Retailers:Private-label development teams seek cost-optimized stabilizer solutions meeting clean-label positioning requirements. Scandinavian retail chains audit supplier biodegradability credentials against EU Green Deal packaging mandates.
- Catering Services:Event and institutional caterers prioritize shelf-stable prepared components with minimal preparation labor. Central European institutional foodservice contracts specify stabilizer performance for ambient distribution logistics.
Food manufacturers anchor absolute demand; food service operators represent the fastest-climbing customer segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's processed food corridor generates heavier stabilizer offtake than France's dairy heartland, though both markets pivot on EFSA regulatory timelines. Southern European markets lag in clean-label adoption but accelerate retrofit investments. Central European expansion corridors attract technical service partnerships from Western suppliers.
Germany
Bavaria and North Rhine-Westphalia anchor European demand for texture-modifying hydrocolloids in yogurt and processed cheese applications. EFSA's additive re-evaluation schedules compel manufacturers to secure compliant alternative stabilizers ahead of renewal deadlines. Munich-based dairy processors anchor reformulation activity for reduced-fat products without viscosity loss.
France
Premium dessert producers in Île-de-France and Auvergne-Rhône-Alpes command premium positioning through specialized gelling performance requirements. REACH compliance documentation for imported modified starches extends qualification timelines for non-EU suppliers accessing formulation facilities. Lyon and Paris industrial zones concentrate pectin-intensive confectionery manufacturing.
Italy
Pasta sauce producers in Emilia-Romagna and Lombardy anchor Mediterranean demand for modified starch and xanthan gum systems in heat-processed condiments. EU Green Deal packaging waste directives pressure stabilizer suppliers to demonstrate biodegradability credentials alongside functional performance. Bologna's food technology cluster drives rapid prototype development for clean-label reformulation.
Netherlands
Ready-to-drink smoothie manufacturers in Randstad prioritize clean-label stabilization systems for pulp and protein particle suspension. EFSA's ongoing carrageenan safety re-evaluation tightens purity thresholds for hydrocolloid suppliers seeking renewal approvals. Wageningen's food innovation ecosystem accelerates fermentation-derived hydrocolloid adoption at compressed replacement cycles.
Poland
Underdeveloped stabilizer formulation capabilities in Central European dairy plants create technical service partnerships for Western suppliers. BRC and IFS food safety audits across dispersed production facilities demand coordinated quality management system investments. Warsaw and Łódź processing corridors attract mid-tier sauce manufacturers favoring liquid concentrate formats for reduced technical labor requirements.
Europe Food Stabilizers Market Competitive Landscape
Danish and Dutch producers anchor the premium formulation tier; American agricultural conglomerates hold commodity hydrocolloid scale. The vendor base stratifies across integrated multinationals with captive raw material sourcing and specialized European emulsifier houses. Three archetypes dominate: fermentation technology pioneers, seaweed extraction specialists, and dairy-centric technical service providers. Competitive intensity centers on backward integration into agricultural supply chains and geographic expansion into Central European formulation partnerships.
Within the integrated multinational tier, Cargill, Kerry Group, and Palsgaard occupy positions defined by supply chain control and application specialization. Cargill represents agricultural-originated hydrocolloid scale with integrated pectin supply chain capabilities. Kerry Group exemplifies technical service-anchored positioning through formulation partnership models with cooperative dairy sectors. Palsgaard sits within the Scandinavian emulsifier specialist archetype, leveraging regional dairy processing density for application development proximity.
| Leading Market Players |
|---|
| Kerry Group |
| Ingredion |
| Cargill |
| CP Kelco |
| Ashland |
| DuPont de Nemours |
| Archer Daniels Midland |
| Palsgaard |
| Tate & Lyle |
| Others |
Supply & Pricing Matrix
Seaweed harvest volatility in Philippine and Indonesian waters cascades through carrageenan pricing tiers, pushing German dairy processors toward pectin alternatives at 40-60% unit cost premiums while compressing margin recovery in private-label segments.
Pricing Analysis
Capacity additions in fermentation-derived hydrocolloid platforms are reshaping price floors for premium stabilizer grades, displacing agricultural extraction cost structures. Three-tier pricing structure across premium fermentation-derived, standard plant-extracted, and economy modified starch levels stratifies buyer segments. Pricing pressure stems from EFSA-mandated purity upgrades requiring sub-ppm heavy metal testing. Private-label dairy processors exhibit highest price sensitivity; premium dessert manufacturers in France and Italy show lowest.
Supply Chain Analysis
Reverse logistics for stabilizer returns and reformulation waste streams remain underdeveloped across European formulation facilities, creating disposal cost burdens for mid-tier processors. Raw material sourcing draws from Philippine seaweed farms, Danish fermentation bioreactors, and French citrus peel pectin extraction. Carrageenan supply hinges on climate-vulnerable Southeast Asian harvest regions. Distribution runs through Rotterdam and Hamburg port hubs into Bavarian and North Rhine-Westphalia processing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's food stabilizer market represents a late-cycle quality story as clean-label mandates shift procurement toward fermentation-derived hydrocolloids with batch-to-batch consistency guarantees.
For Market Incumbents: Cement backward integration into fermentation platforms to secure captive xanthan gum alternatives bypassing agricultural supply constraints. Prioritize technical service partnership capabilities over unit pricing in supplier selection to defend against emerging precision fermentation specialists capturing Scandinavian dairy accounts. For New Entrants and Emerging Players: Precision fermentation technology platforms offer a technology-first wedge into premium pectin and carrageenan substitution markets. Target underdeveloped Central European dairy formulation capabilities in Poland and Romania through technical service partnerships. Lead with on-site texture optimization support as standard commercial terms. For Investors and Strategic Acquirers: Consolidation pressure builds where formulation chemist scarcity concentrates among retiring technical specialists in Netherlands and Denmark. Five-to-ten year viability favors acquisition of fermentation technology pioneers with EFSA pre-qualification status. Monitor EFSA carrageenan re-evaluation timelines as inflection indicator for accelerated reformulation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Platform Scale-Up | Precision fermentation bypasses Philippine seaweed supply concentration risks for German dairy processors. |
| Technical Service Partnership | On-site formulation support secures long-term contracts with Denmark's cooperative dairy procurement committees. |
| EFSA Pre-Qualification Investment | Early-mover positioning on carrageenan alternatives captures Bavarian yogurt reformulation timelines. |
| Central European Expansion | Poland and Romania dairy plants create technical service partnerships for Western suppliers. |
| Biodegradability Certification | EU Green Deal packaging credentials unlock preferred supplier status with Scandinavian retail chains. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hydrocolloid procurement managers, dairy formulation chemists, EFSA regulatory affairs specialists, and bakery R&D directors with secondary validation through EFSA additive safety evaluations, REACH compliance documentation, EU Green Deal packaging directives, and customs trade data for hydrocolloid imports. Bottom-up segment sizing triangulated against top-down market envelope checks.
Segment-weighting approaches modeled product type, application, form, and end-user dimensions across the projection horizon. CAGRs derived from trend extrapolation of clean-label reformulation cycles, plant-based beverage expansion trajectories, and EFSA regulatory timeline impacts. Industry-specific inputs included fermentation technology adoption curves and seaweed harvest variability indices.
The model holds under stable EFSA regulatory schedules; deviation in carrageenan re-classification timelines or Philippine export restrictions would shift volume trajectories. Practitioners should monitor EFSA additive safety announcements and Southeast Asian climate patterns for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Food Grade Magnesium Carbonate Market
Food Components and Additives
Asia Pacific Food Grade Carbon Dioxide Market
Food Components and Additives
Food Grade Silica Market
Food Components and Additives
Clean Label Pectin Market
Food Components and Additives
Fractionated Fatty Acid Market
Food Components and Additives
Germany Food Preservatives Market
Food Components and Additives
Inulin and Fructooligosaccharide Market
Food Components and Additives
Isoflavones Market
Food Components and Additives
Mexico Food Hydrocolloids Market
Food Components and Additives
Food Hydrocolloids Market
Food Components and Additives
Polyunsaturated Fatty Acids Market
Food Components and Additives
Food Grade Calcium Carbonate Market
Food Components and Additives
Australia Food Hydrocolloids Market
Food Components and Additives
Polyphenol Antioxidant Market
Food Components and Additives
North America Food Hydrocolloids Market
Food Components and Additives
India Food Hydrocolloids Market