
 Blackcurrant Powder Market | 2026-2036
Blackcurrant Powder Market Size, Share, and Industry Trends Forecast 2026-2036
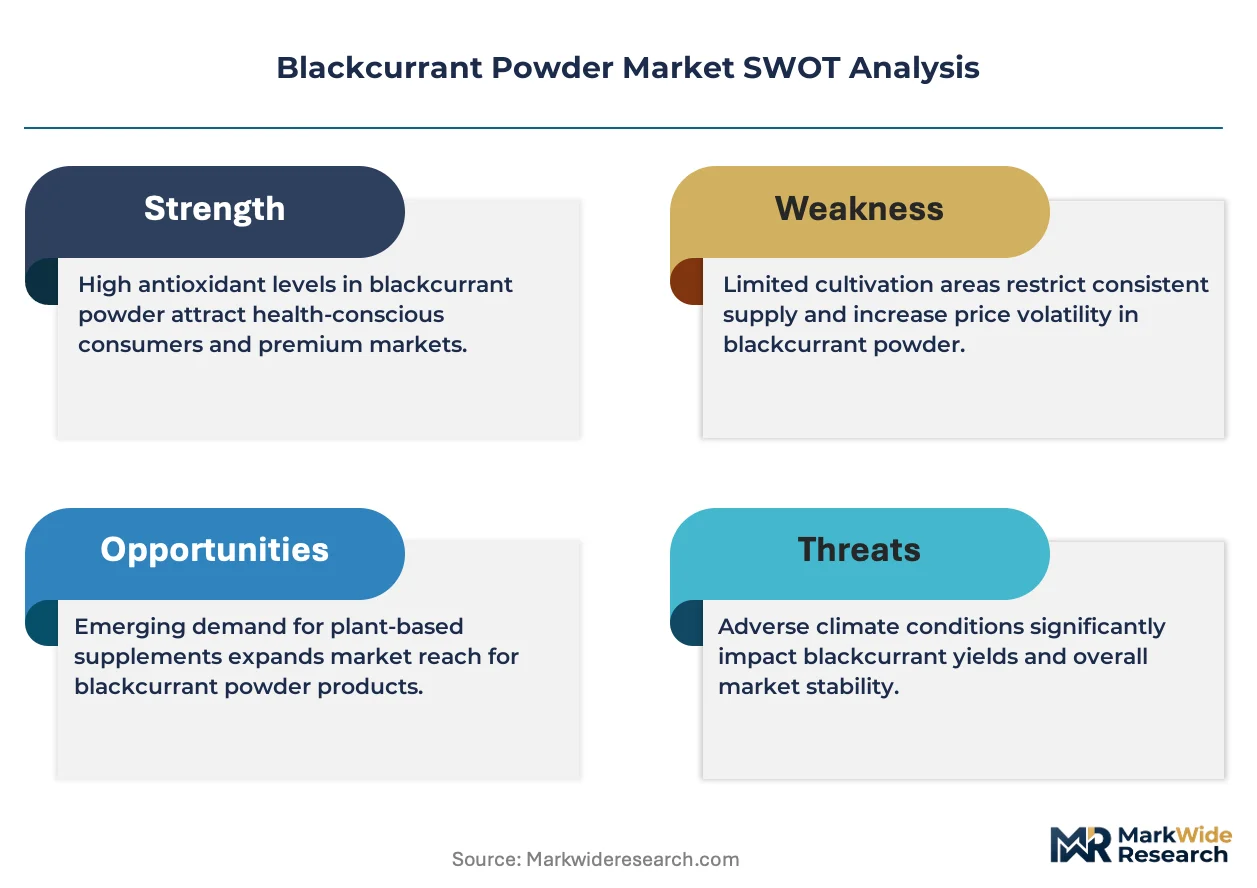
Blackcurrant Powder Market Analysis
Skilled freeze-drying technicians are reorganizing production capacity across Eastern European and Nordic processing facilities as demand for premium-grade powders intensifies. FutureCeuticals leverages its botanical extraction infrastructure to supply standardized anthocyanin concentrates to North American supplement brands. Waitaki Bio anchors its competitive position through New Zealand-sourced organic raw material streams and controlled-atmosphere drying protocols. Arctic Power Berries differentiates via direct-to-consumer packaging formats that bypass conventional wholesale channels.
Blackcurrant powder consists of dehydrated fruit tissue processed to retain anthocyanin content typically exceeding 25% by weight in premium grades, serving as a colorant, flavoring agent, and functional ingredient across food and nutraceutical applications. Spray-dried variants dominate volume throughput due to lower unit economics and broader compatibility with mass-market beverage formulations, while freeze-dried segments command margin concentration from specialty dietary supplement and cosmetic buyers. The organic product type category sustains price premiums through certified supply chains, though conventional powder retains volume leadership in industrial bakery and sauce applications where cost sensitivity shapes procurement.
EU EFSA novel food assessments and REACH-compliant extraction solvent standards govern market access for European-bound blackcurrant powder, while FDA GRAS self-affirmation pathways structure US commercialization timelines for new suppliers. New Zealand's MPI organic certification and parallel EU equivalency agreements enable Waitaki Bio and comparable processors to serve dual-market demand without redundant audit cycles. Stakeholders must monitor evolving EU Green Deal agricultural input restrictions and corresponding reformulation requirements in downstream cosmetic and pharmaceutical applications.
Market Dynamics
Clean-label formulation mandates from EU EFSA and FDA GRAS pathways are restructuring procurement priorities, forcing ingredient buyers to validate anthocyanin retention rates through certified extraction protocols rather than accepting supplier claims.
Growth Catalysts
- EFSA Novel Food assessments:Standardized safety evaluations accelerate ingredient approvals for functional food brands seeking EU market entry, reducing regulatory uncertainty that previously delayed product launches.
- Freeze-drying infrastructure expansion:Processing facilities in Poland and Finland deploy controlled-atmosphere protocols that preserve 25%+ anthocyanin content, enabling premium-grade supply for dietary supplement manufacturers.
- German functional food prioritization:Domestic brands mandate domestically processed blackcurrant derivatives, creating pull-through demand for transparent supply chain documentation.
Market Restraints
- Organic raw material concentration:New Zealand MPI-certified supply chains dominate premium-grade feedstock, creating geographic dependency risk for processors lacking bilateral equivalency agreements.
- REACH-compliant solvent costs:ECHA-mandated extraction standards elevate processing expenses versus conventional solvent systems, compressing margins for mid-tier suppliers.
- Spray-dried powder substitution:Lower-unit-cost variants satisfy mass-market beverage formulations, limiting price realization for freeze-dried alternatives in cost-sensitive industrial bakery segments.
Strategic Opportunities
- Direct-to-consumer channel development:Single-serve packaging formats bypass conventional wholesale intermediaries, capturing margin that previously accrued to distributors.
- EU Green Deal agricultural input alignment:Reformulation requirements in downstream cosmetic applications create demand for certified organic powder that meets evolving input restrictions.
- Dual-market certification leverage:New Zealand processors with parallel EU equivalency agreements serve both markets without redundant audit cycles, accelerating geographic expansion.
Industry Challenges
- Freeze-drying technician scarcity:Skilled operators capable of optimizing controlled-atmosphere parameters remain concentrated in Nordic and Eastern European facilities, constraining production scale-up.
- Anthocyanin standardization complexity:Batch-to-batch variation in natural fruit composition complicates consistent concentrate delivery for supplement brands requiring precise dosing claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blackcurrant Powder Market |
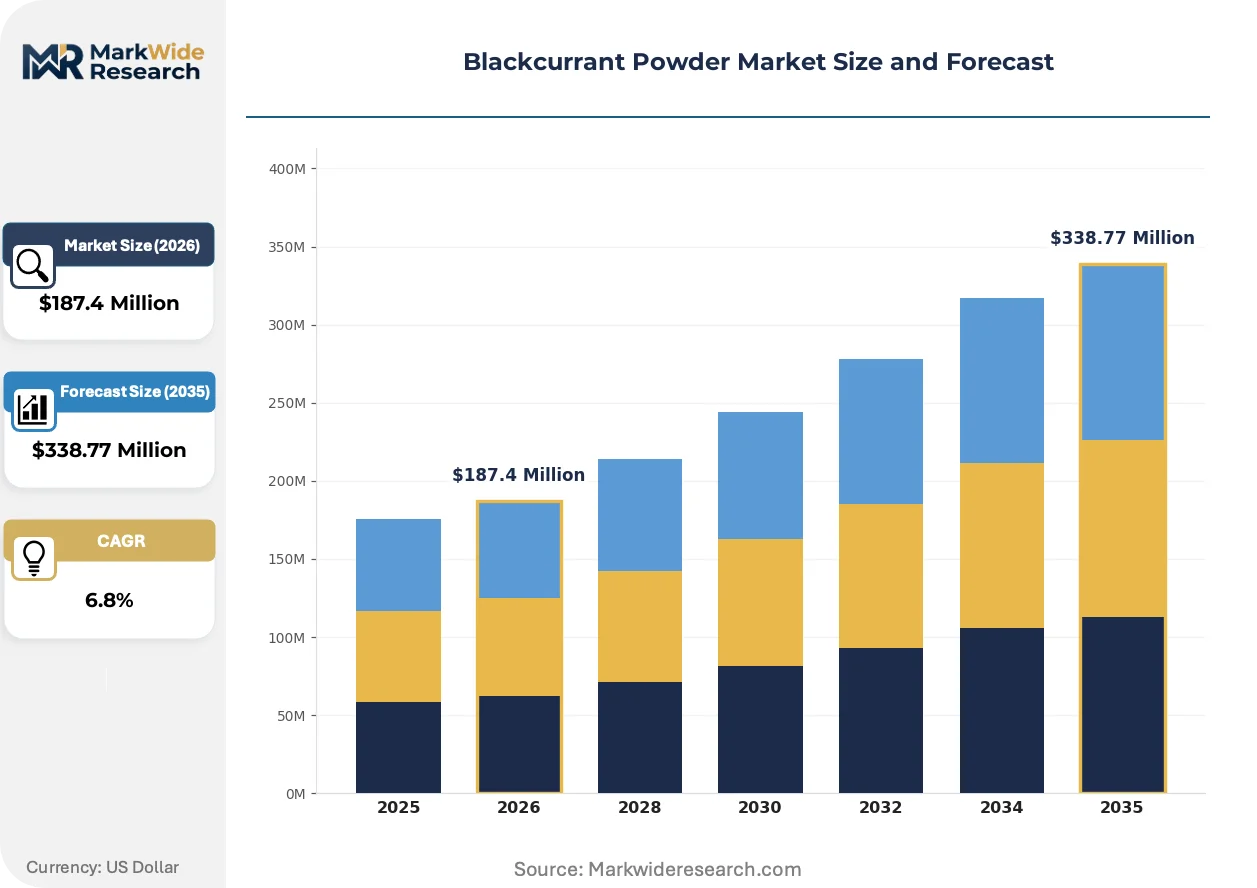
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Conventional, Freeze-Dried, Spray-Dried Distribution Channel: Online, Retail, Wholesale, Direct Sales End User: Food & Beverage, Dietary Supplements, Cosmetics, Pharmaceuticals Application: Beverages, Bakery Products, Sauces, Nutritional Bars |
| Companies Covered | FutureCeuticals, Waitaki Bio, Arctic Power Berries, Active Micro Technologies LLC, Z Natural Foods LLC, LOOV Organic LLC, CurrantC LLC, ConnOils LLC, LYO FOOD Sp. z o.o, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blackcurrant Powder Market Emerging Trajectories
Processing technology divergence and regulatory fragmentation are splitting competitive advantages between mass-market cost efficiency and premium-grade functional credentialing.
Controlled-atmosphere freeze-drying is bifurcating the supply base. This technology preserves heat-sensitive anthocyanin compounds at rates exceeding 25% by weight. Dietary supplement and cosmetic buyers absorb 40-60% price premiums for certified retention documentation. Mass-market beverage formulators remain anchored to spray-dried alternatives, compressing mid-tier processors into undifferentiated commodity positioning.
EU Green Deal agricultural input restrictions are reshaping cosmetic and pharmaceutical sourcing protocols. Downstream formulators face mandated reformulation timelines for plant-derived ingredients. German and French cosmetic brands accelerate procurement of MPI-certified organic powder to preempt compliance gaps. New Zealand processors with existing EU equivalency agreements capture preferential allocation.
Clean-label verification requirements are altering buyer-supplier contracting structures. Functional food brands now mandate third-party anthocyanin assay documentation rather than accepting certificates of analysis. German retailers lead enforcement, rejecting batches lacking EFSA-aligned novel food dossiers. Direct-to-consumer supplement channels follow, with subscription brands publishing retention rates as primary marketing claims.
Blackcurrant Powder Market Segmentation
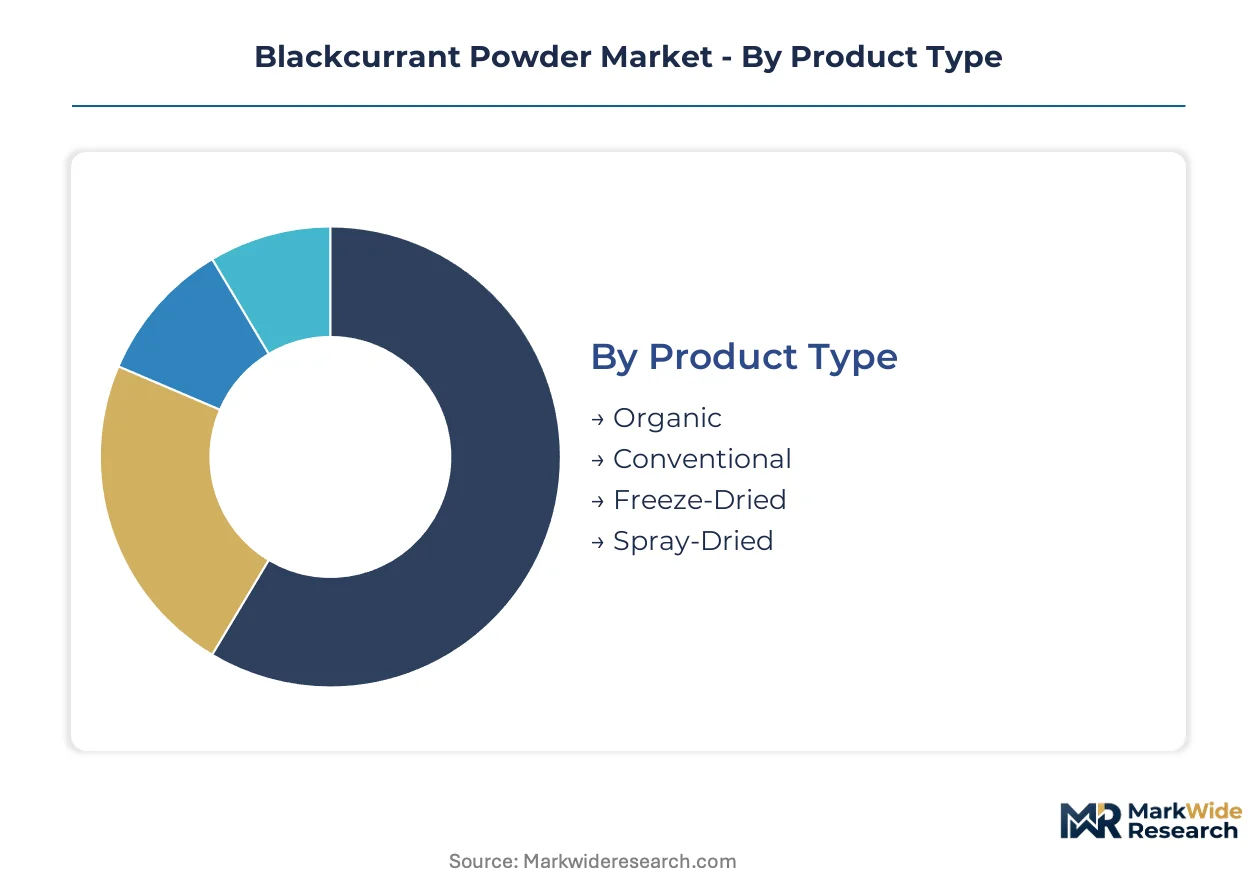
Segmentation in blackcurrant powder reveals divergent margin structures between commodity-grade industrial supply and certified functional ingredients. Procurement patterns bifurcate sharply across extraction protocols, with freeze-dried variants commanding substantial premiums for anthocyanin retention documentation.
Product Type:
Margin pools concentrate in certified organic and freeze-dried segments where supply scarcity and processing complexity create pricing power.
- Organic:Certified supply chains under New Zealand MPI and EU organic equivalency protocols sustain price premiums through audit-validated agricultural inputs. German functional food brands and French cosmetic formulators prioritize this grade to meet EU Green Deal agricultural input restrictions.
- Freeze-Dried:Controlled-atmosphere protocols preserve anthocyanin content exceeding 25% by weight, serving dietary supplement manufacturers requiring precise dosing claims. Polish and Finnish processing facilities deploy skilled technicians to optimize retention parameters for premium-grade output.
- Conventional:Industrial bakery and sauce applications drive volume throughput where cost sensitivity dominates procurement decisions.
- Spray-Dried:Mass-market beverage formulators absorb lower unit economics for broader compatibility with high-volume production lines.
Freeze-dried holds installed capacity. Organic is rotating up the share rankings.
Distribution Channel:
Channel economics favor direct relationships that capture margin previously allocated to wholesale intermediaries.
- Direct Sales:Supplement subscription brands and cosmetic formulators contract directly with New Zealand processors to secure MPI-certified supply with full traceability documentation.
- Online:Single-serve packaging formats from Arctic Power Berries and comparable operators bypass conventional retail, capturing end-consumer price realization.
- Wholesale:Industrial buyers in bakery and beverage manufacturing consolidate procurement through established ingredient distributors.
- Retail:Health food stores and specialty grocers stock premium-grade powders for home-use consumers seeking functional food ingredients.
Wholesale maintains volume throughput. Direct sales is climbing the fastest.
End User:
End-use concentration tracks regulatory validation requirements, with segments demanding EFSA novel food dossiers absorbing supply priority.
- Dietary Supplements:North American brands source standardized anthocyanin concentrates from FutureCeuticals and comparable extraction specialists for capsule and tablet formulations.
- Cosmetics:German and French brands accelerate procurement ahead of EU Green Deal reformulation mandates for plant-derived colorants and actives.
- Food & Beverage:Functional food brands in Germany mandate domestically processed derivatives for supply chain transparency compliance.
- Pharmaceuticals:Clinical-grade applications require REACH-compliant extraction solvents and batch-to-batch standardization protocols.
Food & Beverage anchors current demand. Cosmetics is gaining share fastest.
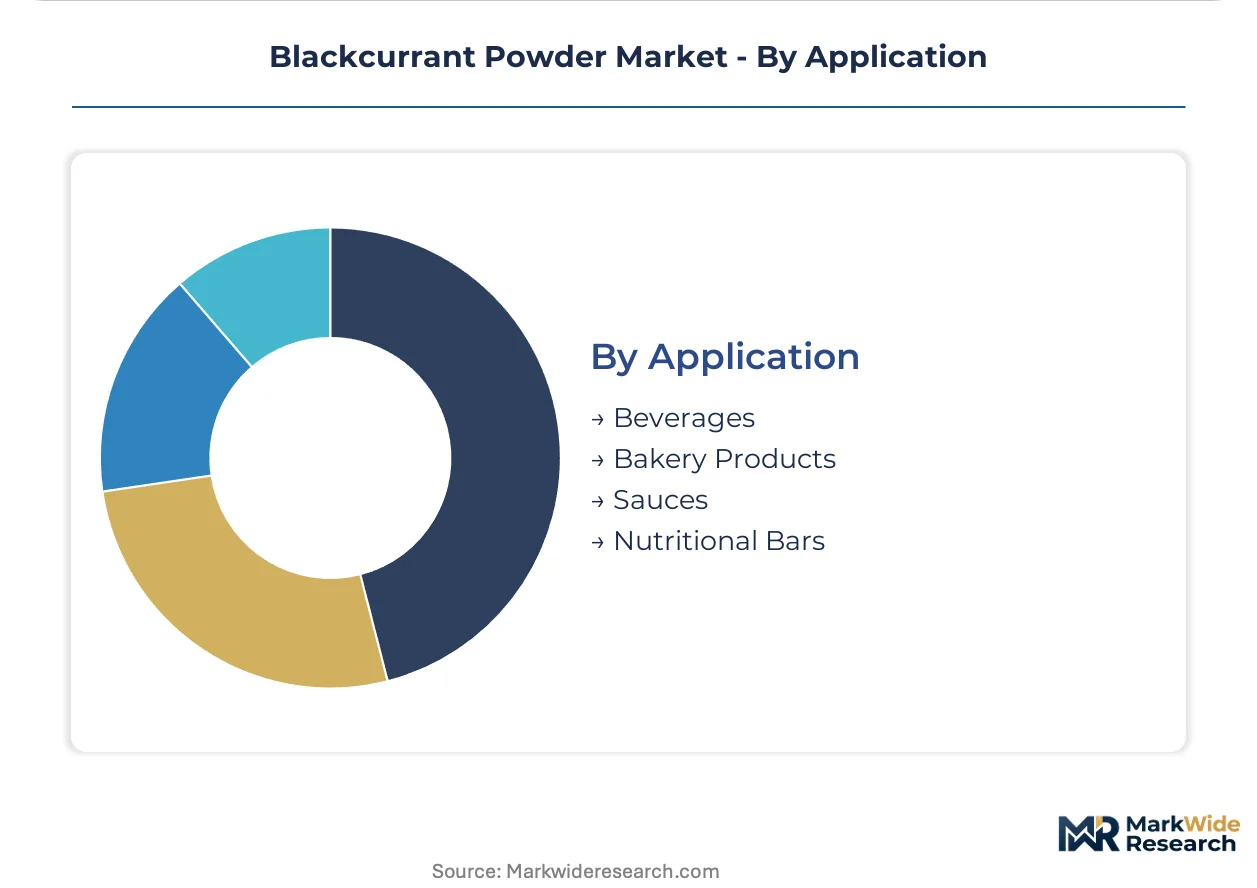
Application:
Application mix reflects divergent technical requirements between heat-stable industrial uses and cold-process functional formulations.
- Nutritional Bars:Cold-pressed manufacturing preserves anthocyanin activity, attracting premium powder grades from supplement-focused brands.
- Beverages:Mass-market smoothie and juice applications favor spray-dried powders for solubility and cost efficiency.
- Bakery Products:Heat exposure during baking degrades anthocyanin content, limiting functional claims and compressing input grade specifications.
- Sauces:pH-stable formulations in condiments accommodate conventional powder grades where color contribution outweighs bioactive retention.
Beverages holds volume leadership. Nutritional bars is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German functional food brands consume blackcurrant powder primarily for anthocyanin retention documentation, whereas US buyers prioritize GRAS-affirmed supply chains for supplement formulations. New Zealand processors anchor premium-grade output through MPI-certified organic streams. Polish and Finnish facilities concentrate freeze-drying capacity for controlled-atmosphere protocols.
Germany
Domestic brands mandate domestically processed blackcurrant derivatives to satisfy supply chain transparency requirements. EFSA Novel Food assessments structure procurement contracts, with retailers rejecting batches lacking standardized dossiers. Processing clusters in Bavaria and Baden-Württemberg deploy technicians optimizing anthocyanin retention parameters for supplement-grade output.
United States
North American supplement brands source standardized anthocyanin concentrates for capsule and tablet formulations. FDA GRAS self-affirmation pathways govern commercialization timelines for new suppliers entering the market. FutureCeuticals anchors botanical extraction supply through established infrastructure serving domestic dietary supplement manufacturers.
New Zealand
MPI-certified organic supply chains dominate premium-grade feedstock for cosmetic and pharmaceutical applications. EU equivalency agreements enable dual-market service without redundant audit cycles. Waitaki Bio controls raw material streams through bilateral certification protocols serving German and French cosmetic formulators.
Poland
Eastern European processing facilities expand freeze-drying capacity as skilled technician availability constrains production scale-up elsewhere. REACH-compliant extraction solvent standards elevate processing expenses versus conventional systems. LYO FOOD Sp. z o.o occupies a position within the regional specialist tier deploying controlled-atmosphere protocols.
Finland
Nordic facilities preserve heat-sensitive anthocyanin compounds at rates exceeding 25% by weight through advanced drying infrastructure. Arctic Power Berries exemplifies direct-to-consumer channel development through single-serve packaging formats bypassing wholesale intermediaries. Finnish processors capture margin concentration from specialty dietary supplement buyers seeking certified retention documentation.
Blackcurrant Powder Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding premium positioning through certified organic supply chains and controlled-atmosphere processing capabilities. The middle tier fragments across spray-dried commodity supply and regional freeze-drying operations. Three archetypes define competitive positioning: MPI-certified New Zealand processors with dual-market equivalency, North American extraction specialists serving supplement brands, and Nordic direct-to-consumer operators with packaging format differentiation. Capacity expansion and channel bypass strategies dominate competitive moves as firms seek to capture margin from wholesale intermediaries.
Within the New Zealand-certified tier, Waitaki Bio represents integrated upstream control over organic raw material streams. FutureCeuticals anchors the North American extraction specialist position. Arctic Power Berries exemplifies direct-to-consumer channel innovation. These three companies illustrate how geographic certification advantages and format differentiation create defendable positioning against commodity-grade competitors.
| Leading Market Players |
|---|
| FutureCeuticals |
| Waitaki Bio |
| Arctic Power Berries |
| Active Micro Technologies LLC |
| Z Natural Foods LLC |
| LOOV Organic LLC |
| CurrantC LLC |
| ConnOils LLC |
| LYO FOOD Sp. z o.o |
| Others |
Supply Flow & Price Mechanics
EU Green Deal agricultural input restrictions gate both supply qualification and price differentiation simultaneously, forcing cosmetic formulators to pay premiums for MPI-certified organic powder while conventional grades face cost compression from REACH-compliant solvent mandates. This regulatory architecture splits procurement economics between certified retention documentation commanding substantial markups and undifferentiated spray-dried supply serving cost-sensitive industrial buyers.
Pricing Analysis
Long-term offtake contracts dominate premium-grade procurement as German functional food brands and French cosmetic formulators secure multi-year allocations from New Zealand processors. Price differentiation rests on anthocyanin retention certification and MPI organic equivalency status, with freeze-dried variants absorbing 40-60% premiums over spray-dried alternatives. Cost compression runs through conventional grades as industrial bakery buyers substitute lower-unit-cost powders without functional claims. Mass-market beverage formulators exhibit highest price sensitivity, while dietary supplement manufacturers absorb premiums for standardized concentrate documentation.
Supply Chain Analysis
Strategic stockpiling of MPI-certified organic feedstock characterizes premium-tier procurement as buyers anticipate EU Green Deal reformulation deadlines. Raw material sourcing concentrates in New Zealand, Poland, and Finland, drawing from controlled-atmosphere drying infrastructure and bilateral equivalency agreements. Supply chain risk centers on single-source dependency for skilled freeze-drying technicians concentrated in Nordic and Eastern European facilities. Distribution runs through direct sales channels for certified grades and wholesale intermediaries for industrial volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spray-dried berry powders and synthetic anthocyanin substitutes threaten incumbent positioning as cost-sensitive formulators reformulate around lower input costs. Incumbents must defend premium-tier credentialing against this substitution pressure.
For Market Incumbents: Shield anthocyanin retention leadership by deepening controlled-atmosphere technician training programs in Poland and Finland. Secure backward integration into MPI-certified organic cultivation through long-term grower contracts in New Zealand. This defensive posture counters spray-dried substitution threats while locking in supply scarcity premiums.
For New Entrants and Emerging Players: Direct-to-consumer subscription fulfillment represents the most penetrable service-layer gap as incumbents under-serve home-use consumers seeking traceable functional ingredients. Target single-serve packaging formats with full MPI documentation published as primary marketing claims. Bypass wholesale intermediaries entirely to capture end-consumer price realization.
For Investors and Strategic Acquirers: EU Green Deal agricultural input restrictions reshape the acquisition landscape toward processors with existing dual-market certification infrastructure. Five-to-ten-year viability favors New Zealand-based operators with parallel EU equivalency agreements and captive organic supply. Monitor EFSA novel food dossier approval velocity as the inflection signal for premium-grade demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Cultivation | Captive MPI-certified supply secures preferential allocation from German cosmetic formulators facing reformulation mandates. |
| Controlled-Atmosphere Capacity Expansion | Polish and Finnish facility upgrades address technician scarcity constraining premium-grade output scale. |
| Direct-to-Consumer Channel Launch | Single-serve formats bypass wholesale margin extraction and publish retention rates as primary claims. |
| Dual-Market Certification Investment | Parallel EU equivalency agreements enable New Zealand processors to serve both markets without redundant audits. |
| Long-Term Supply Agreement with Supplement Brands | Contracted offtake volumes de-risk batch-to-batch standardization investments for North American capsule manufacturers. |
Methodological Framework
Operator-level perspectives from freeze-drying technicians, MPI certification auditors, cosmetic formulators, and dietary supplement procurement managers anchored the qualitative base. These primary interviews combined with secondary validation from EFSA novel food dossiers, MPI organic certification records, REACH-compliant solvent disclosure filings, and customs trade data for berry powder imports. Bottom-up capacity assessments across Polish and Finnish processing facilities triangulated against top-down demand estimates from German functional food brands.
Sensitivity analysis tested forecast robustness across anthocyanin retention rate assumptions, EU Green Deal implementation timelines, and freeze-drying technician availability scenarios. The analytical framework modeled volume and value outputs across product type, distribution channel, end user, and application dimensions throughout the projection horizon. CAGRs derived from segment-level growth trajectories incorporating EFSA approval velocity, MPI certification expansion rates, and direct-to-consumer channel penetration curves.
Underlying assumptions cover sustained EU Green Deal enforcement, stable MPI-EU equivalency agreements, and continued technician concentration in Nordic and Eastern European facilities, with deviation risk concentrated in regulatory timeline acceleration or certification protocol fragmentation. Revision becomes warranted when EFSA novel food approval rates or EU agricultural input restriction scopes cross thresholds that materially alter premium-grade demand elasticity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Food Grade Titanium Dioxide Market
Food Components and Additives
Food-Grade Monopotassium Phosphate Market
Food Components and Additives
Citrus Pectin from Mediterranean Juice Side Streams Market
Food Components and Additives
North America Food Antimicrobial and Antioxidants Market
Food Components and Additives
Modified Wheat Starch Market
Food Components and Additives
Food Grade Calcium Carbonate Market
Food Components and Additives
Europe Food Preservatives Market
Food Components and Additives
Germany Food Hydrocolloids Market
Food Components and Additives
Food Texture Market
Food Components and Additives
Linoleic Acid Market
Food Components and Additives
Asia-Pacific Food Hydrocolloids Market
Food Components and Additives
United Kingdom Food Hydrocolloids Market
Food Components and Additives
Food Grade Sodium Carbonate Market
Food Components and Additives
Food Grade Iron Powder Market
Food Components and Additives
Europe Food Hydrocolloids Market
Food Components and Additives
Polyphenol Antioxidant Market